
 Implantable Cardiac Rhythm Management Device Market | 2026-2036
Implantable Cardiac Rhythm Management Device Market Size, Share, and Industry Trends Forecast 2026-2036
Implantable Cardiac Rhythm Management Device Market Intelligence
Hospital procurement channels for implantable cardiac rhythm management devices is narrowing toward integrated delivery networks with centralized contracting authority. Medtronic leverages its cath lab partnerships to sustain implant volume across major academic medical centers. Abbott competes through leadless pacemaker specialization that differentiates its portfolio in minimally invasive procedures. Boston Scientific Corporation anchors its position with subcutaneous ICD technology that occupies a distinct risk-stratified segment.
Implantable cardiac rhythm management devices are battery-powered therapeutic systems implanted subcutaneously or transvenously to monitor cardiac electrical activity and deliver pacing, defibrillation, or resynchronization therapy; contemporary units incorporate lithium-iodine cells with typical longevity of seven to twelve years and wireless telemetry for remote surveillance. Their primary purpose is to reduce sudden cardiac death and manage chronic arrhythmias in patients with conduction disorders or heart failure. Pacemakers remain the mature volume base with stable replacement cycles, while leadless technology represents the fastest-growing structural segment as extraction risk concerns reshape physician preference. Cardiac resynchronization therapy devices command premium positioning due to heart failure indication complexity and specialized implant training requirements.
FDA premarket approval pathways and ISO 14155 clinical investigation standards govern device safety validation and post-market surveillance obligations in the United States, while the EU Medical Device Regulation imposes strengthened notified body oversight and unique device identification mandates across European markets. These frameworks elevate compliance costs and extend development timelines, effectively filtering market access toward established manufacturers with dedicated regulatory infrastructure. Stakeholders must monitor evolving cybersecurity guidance for connected cardiac devices and assess alignment with outcome-based reimbursement pilots before committing capital to next-generation platform development.
Market Dynamics
Leadless pacemaker architectures are compressing replacement cycle economics while redefining cath lab workflow requirements across integrated delivery networks.
Growth Catalysts
- EU MDR Unique Device Identification:Strengthened traceability mandates accelerate hospital consolidation around wireless-enabled platforms with embedded compliance architecture.
- Medicare reimbursement tightening:Elevated qualification thresholds in the United States favor devices with demonstrated remote monitoring outcomes.
- Germany's electrophysiology hub cities:Cath lab consolidation in Berlin, Munich, and Heidelberg creates concentrated demand for integrated CRM platforms.
Market Restraints
- Lithium-iodine cell supply concentration:Battery chemistry dependency on specialized Japanese and South Korean suppliers creates input cost volatility and single-source risk.
- Lead extraction complexity:Transvenous device legacy installed base generates procedural morbidity concerns that slow physician conversion to newer platforms.
- FDA premarket approval timelines:Extended validation cycles for novel sensing algorithms delay commercialization by 18-36 months versus predicate pathways.
Strategic Opportunities
- India's underpenetrated cardiac resynchronization therapy:Heart failure device implant rates lag Western benchmarks by 80%, creating white space for training-intensive platform deployment.
- AI-enabled arrhythmia prediction:Convergence of machine learning with implantable sensing is digitizing preventive intervention protocols before decompensation events.
- Remote patient monitoring reimbursement codes:New CMS billing categories incentivize health systems to prioritize wireless telemetry capability in procurement specifications.
Industry Challenges
- Electrophysiologist training pipeline:Fellowship program capacity constraints limit qualified implanter availability for complex cardiac resynchronization therapy procedures.
- Cybersecurity validation burden:FDA guidance on connected device threat modeling requires dedicated engineering teams and extends development schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Implantable Cardiac Rhythm Management Device Market |
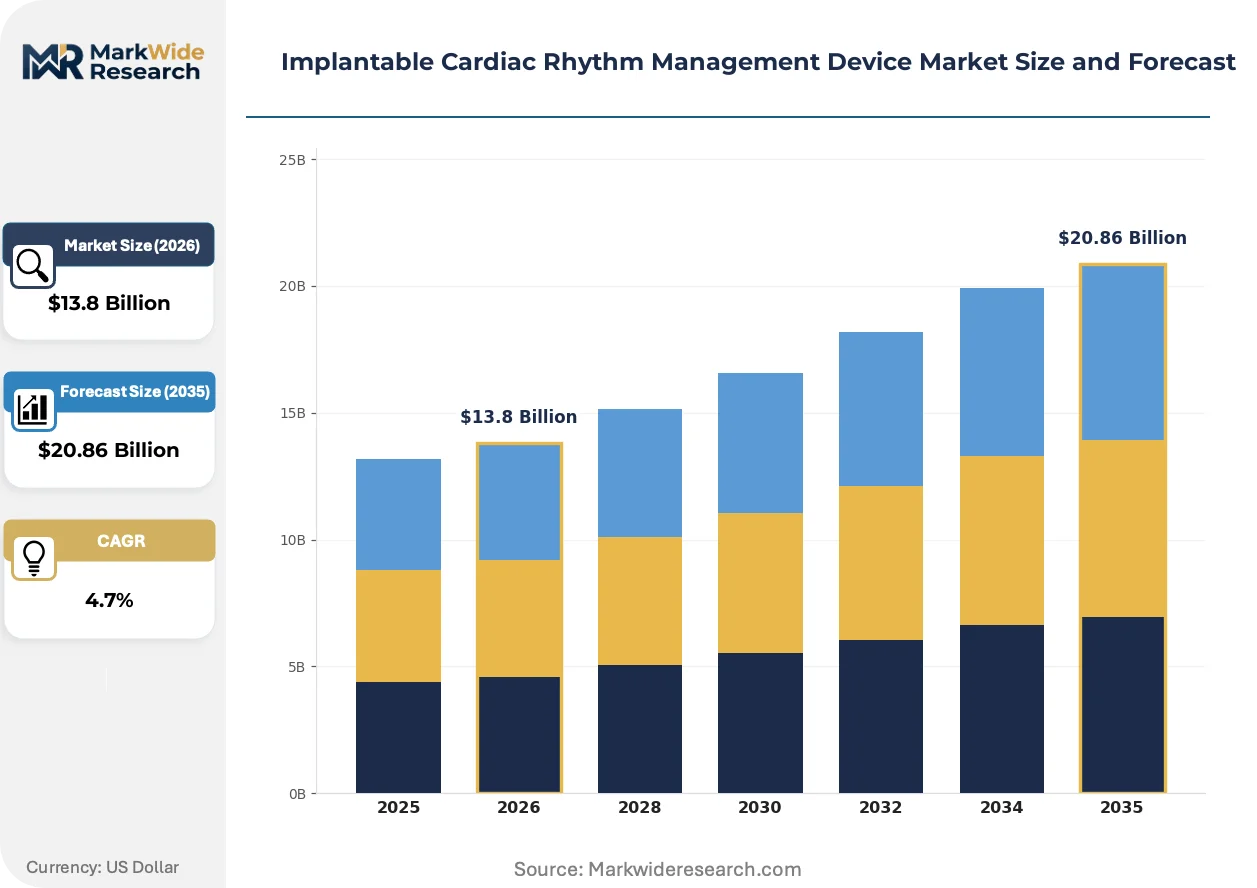
| Market Size in 2026 | $13.8 Billion |
| Market Size in 2035 | $20.86 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Pacemakers, Implantable Cardioverter Defibrillators, Cardiac Resynchronization Therapy Devices, Loop Recorders End User: Hospitals, Cardiology Clinics, Surgical Centers, Home Care Technology: Wireless Monitoring, Remote Programming, Leadless Technology, Biometric Sensors Application: Atrial Fibrillation, Heart Failure, Bradycardia, Syncope |
| Companies Covered | Medtronic, Abbott, Boston Scientific Corporation, Biotronik, Koninklijke Philips, LivaNova, Zoll Medical Corporation, Microport Scientific Corporation, Nihon Kohden Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Implantable Cardiac Rhythm Management Device Market Strategic Shifts & Innovations
Wireless telemetry architectures are restructuring post-implant surveillance economics while enabling population-scale arrhythmia management outside traditional clinic footprints.
Leadless pacemaker miniaturization is digitizing the structural boundary between diagnostic monitoring and therapeutic intervention. Academic medical centers in the United States and Germany are adopting these devices for anticoagulation-ineligible patients at triple-digit annual growth rates. The technology is compressing extraction-risk liability while expanding eligible patient pools beyond traditional transvenous candidates.
EU Medical Device Regulation post-market surveillance requirements are elevating clinical evidence burdens for legacy device families. Manufacturers must now maintain active implant registries with 15-year follow-up obligations for defibrillator platforms. Cardiac resynchronization therapy devices face the steepest compliance cost escalation due to heart failure outcome complexity and multi-center data collection mandates.
Hospital procurement centralization through integrated delivery networks is consolidating contracting authority into fewer decision-makers. Cardiovascular service line administrators now override individual electrophysiologist preferences based on total cost-of-ownership metrics. This behavioral shift is most pronounced in United States metropolitan markets where health system mergers have reduced independent hospital counts by half over the past decade.
Implantable Cardiac Rhythm Management Device Market Segmentation
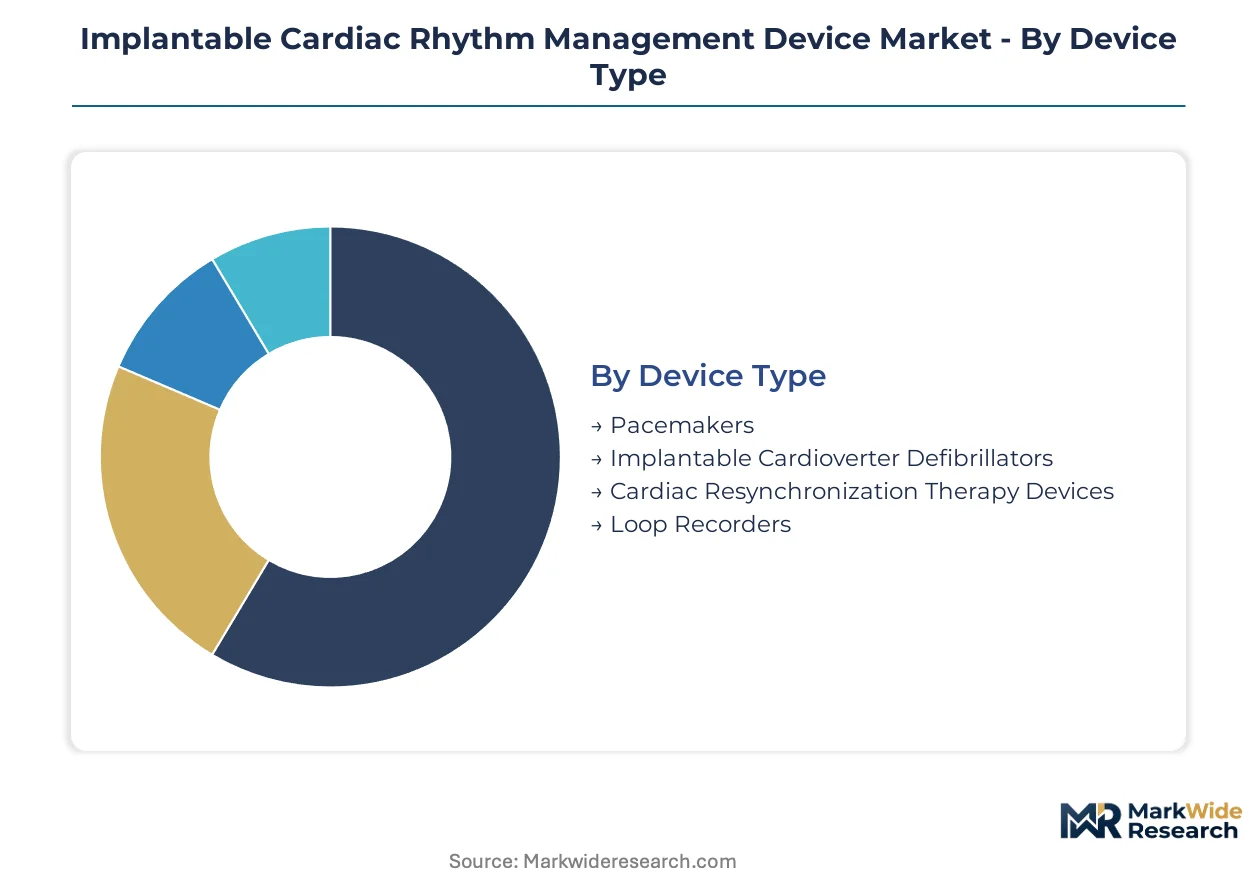
Segmentation in the implantable cardiac rhythm management device market reveals how technology maturity, care setting economics, and clinical indication complexity create distinct commercial battlegrounds. Manufacturers must align platform development with the specific workflow, reimbursement, and outcome requirements of each slice.
Device Type:
The maturity spectrum spans legacy transvenous systems to emerging leadless architectures that eliminate extraction risk.
- Pacemakers:Conventional dual-chamber units with transvenous leads remain the volume foundation across replacement cycles and de novo implants. Demand concentrates in United States integrated delivery networks where Medicare reimbursement protocols favor established remote monitoring outcomes.
- Implantable Cardioverter Defibrillators:These devices deliver high-voltage therapy for ventricular arrhythmias with lithium-iodine power cells lasting seven to twelve years. Germany's electrophysiology hub cities in Berlin, Munich, and Heidelberg drive concentrated procurement of ICD platforms with embedded wireless telemetry.
- Cardiac Resynchronization Therapy Devices:Biventricular pacing systems for heart failure with reduced ejection fraction.
- Loop Recorders:Subcutaneous diagnostic monitors for cryptogenic stroke and unexplained syncope evaluation.
Pacemakers handle the majority of throughput; leadless-enabled pacemaker platforms are gaining share fastest as extraction-risk liability reshapes physician preference.
End User:
Cost tier stratification separates capital-intensive hospital installations from ambulatory settings with lower fixed-cost thresholds.
- Hospitals:Academic medical centers and community hospitals with cath lab infrastructure perform the bulk of complex implants and device replacements. Procurement authority has centralized into integrated delivery network contracting offices that prioritize total cost-of-ownership metrics over individual physician preference.
- Cardiology Clinics:Specialized electrophysiology practices handle device interrogation, programming adjustments, and longitudinal arrhythmia management. These settings concentrate in United States metropolitan markets where health system mergers have halved independent hospital counts over the past decade.
- Surgical Centers:Ambulatory facilities focused on low-acuity pacemaker implants with same-day discharge protocols.
- Home Care:Remote monitoring infrastructure enabling surveillance outside traditional clinic footprints.
Hospitals absorb the dominant share of implant volume; home care infrastructure is expanding most quickly on the back of new CMS reimbursement codes for remote patient monitoring.
Technology:
Application focus distinguishes diagnostic surveillance capabilities from therapeutic intervention systems.
- Wireless Monitoring:Radiofrequency telemetry enabling automated data transmission to cloud-based surveillance platforms. United States hospital procurement specifications now mandate wireless capability as Medicare reimbursement tightening elevates remote monitoring outcomes.
- Leadless Technology:Miniaturized pacemakers implanted directly into the right ventricle without transvenous leads. Academic medical centers in Germany and the United States are adopting these devices for anticoagulation-ineligible patients at accelerated rates.
- Remote Programming:Bidirectional communication allowing parameter adjustments without clinic visits.
- Biometric Sensors:Integrated accelerometers and impedance measurements tracking heart failure decompensation markers.
Wireless monitoring underpins the majority of installed base connectivity; leadless technology is climbing the fastest as cath lab workflows adapt to catheter-delivered implant techniques.
Application:
Volume concentration varies by indication prevalence and device complexity requirements.
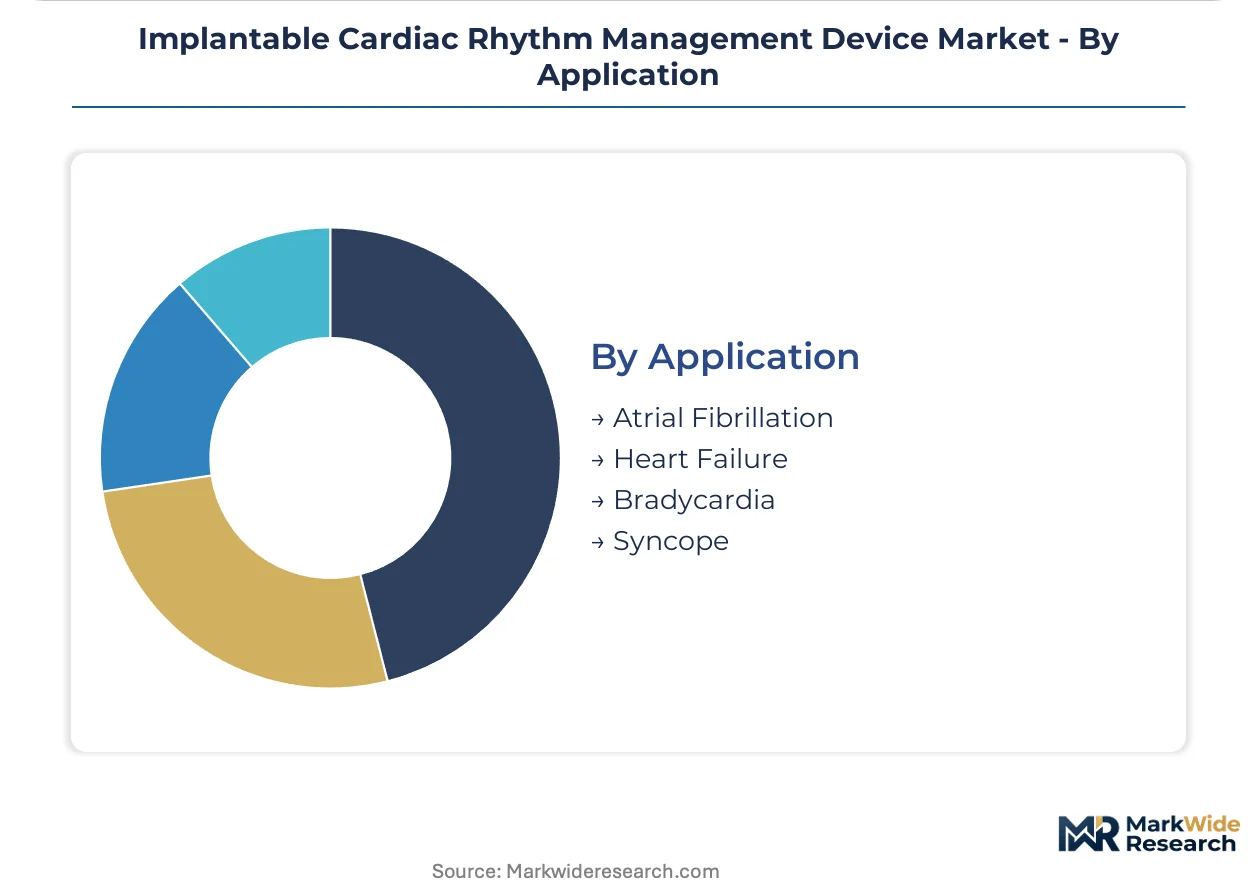
- Atrial Fibrillation:The most common sustained arrhythmia drives demand for stroke prevention devices and rhythm control systems. United States electrophysiology practices concentrate ablation and device implant volume for AF patients with concomitant bradycardia indications.
- Heart Failure:Cardiac resynchronization therapy and diagnostic monitoring for reduced ejection fraction. Germany's specialized heart failure centers in Heidelberg and Munich anchor European adoption of CRT platforms with comprehensive multi-center outcome registries.
- Bradycardia:Sinus node dysfunction and atrioventricular block indications for pacemaker dependency.
- Syncope:Recurrent unexplained loss of consciousness requiring diagnostic loop recorder implantation.
Bradycardia generates the highest absolute implant counts; heart failure applications are expanding most steeply as resynchronization therapy penetrates underdiagnosed populations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The transatlantic data cable infrastructure connecting Frankfurt to New York underwrites Germany's role as a cardiac rhythm management data relay hub, while the Port of Rotterdam's medical device distribution network anchors European supply chain throughput for implantable systems.
United States
Academic medical centers in Boston, Cleveland, and Minneapolis drive concentrated demand for leadless pacemaker platforms. FDA premarket approval pathways govern device safety validation with extended timelines for novel sensing algorithms. The Cleveland Clinic and Mayo Clinic anchor implant volume for complex cardiac resynchronization therapy procedures.
Germany
Electrophysiology hub cities in Berlin, Munich, and Heidelberg generate concentrated procurement of integrated CRM platforms with wireless telemetry. EU Medical Device Regulation imposes strengthened notified body oversight and unique device identification mandates. The Heidelberg University Hospital anchors multi-center outcome registries for heart failure device platforms.
Japan
Aging demographics and coronary disease prevalence sustain replacement cycle volume for lithium-iodine powered devices. PMDA regulatory frameworks align with ISO 14155 clinical investigation standards for post-market surveillance obligations. Tokyo and Osaka metropolitan clusters concentrate cath lab infrastructure for minimally invasive leadless implants.
India
Heart failure device implant rates lag Western benchmarks, creating white space for training-intensive cardiac resynchronization therapy deployment. CDSCO governs medical device registration with evolving framework alignment to global standards. Metro clusters in Mumbai, Delhi-NCR, and Bangalore concentrate private hospital infrastructure for premium device adoption.
China
Domestic manufacturing scale and hospital procurement centralization reshape competitive access for international manufacturers. NMPA governs Class III medical device registration with strengthened clinical evidence requirements. The Yangtze River Delta and Beijing-Tianjin-Hebei corridors concentrate tertiary hospital capacity for complex electrophysiology procedures.
Implantable Cardiac Rhythm Management Device Market Key Industry Players
On the supply side, the industry is consolidating around integrated platform manufacturers with dedicated regulatory infrastructure and cath lab partnership networks. Three strategic archetypes dominate: diversified medtech conglomerates with full CRM portfolios, cardiac rhythm specialists with leadless technology differentiation, and emerging Asia-Pacific manufacturers with cost-optimized production. Competitive moves concentrate on M&A for technology access and strategic partnerships with integrated delivery networks for procurement lock-in.
Among diversified medtech conglomerates, Medtronic and Abbott exemplify the integrated platform archetype with cath lab partnerships sustaining implant volume across major academic medical centers. Boston Scientific Corporation occupies a distinct position within the risk-stratified technology tier, representing specialists who anchor market presence through subcutaneous ICD differentiation. These three entities collectively illustrate how regulatory infrastructure scale and clinical training network depth determine competitive access in tightening reimbursement environments.
| Leading Market Players |
|---|
| Medtronic |
| Abbott |
| Boston Scientific Corporation |
| Biotronik |
| Koninklijke Philips |
| LivaNova |
| Zoll Medical Corporation |
| Microport Scientific Corporation |
| Nihon Kohden Corporation |
| Others |
Cost & Logistics Intelligence
Overcapacity in South Korean lithium-iodine cell production is compressing battery input costs while elevating pricing leverage for device manufacturers with long-term offtake agreements. This utilization dynamic tightens margins for specialized Japanese suppliers and rewards integrated CRM platform vendors with captive sourcing arrangements.
Pricing Analysis
Volume-discount tiering structures separate premium cardiac resynchronization therapy platforms from standard dual-chamber pacemakers and economy single-chamber units. Price differentiation rests on FDA premarket approval tier, wireless telemetry capability, and cath lab training bundling. Cost compression in the economy tier is intensifying because Indian and Chinese manufacturers are expanding into CE-marked device exports. Integrated delivery networks in the United States demonstrate lowest price sensitivity due to total cost-of-ownership procurement mandates, while independent cardiology clinics in India exhibit highest sensitivity to upfront device costs.
Supply Chain Analysis
Upstream feedstock concentration for lithium-iodine cells centers on South Korea, Japan, and select Chinese chemical processors. Device assembly draws from Malaysian and Costa Rican FDA-registered facilities for United States market access, with German and Swiss plants serving EU MDR compliance. Single-source vulnerability concentrates in specialized tantalum capacitor supply for defibrillator energy storage. Distribution runs through integrated delivery network central contracting offices in the United States and hospital procurement consortiums in Germany.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Remote monitoring service revenue is expanding faster than hardware implant volume as CMS reimbursement codes for wireless telemetry create recurring revenue attachment opportunities. This service-attach dynamic repositions device vendors toward longitudinal patient relationship economics.
For Market Incumbents: Insulate implant volume through exclusive cath lab partnerships with academic medical centers in Boston and Heidelberg. Deepen backward integration into lithium-iodine cell supply through joint ventures with South Korean chemical processors. Lock in integrated delivery network procurement contracts before EU MDR unique device identification mandates consolidate contracting authority further.
For New Entrants and Emerging Players: Pursue India's underpenetrated cardiac resynchronization therapy segment where implant rates lag Western benchmarks. Target leadless pacemaker miniaturization for anticoagulation-ineligible patient pools. Deploy training-intensive platform deployment through partnerships with Mumbai and Delhi-NCR private hospital chains.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across AI-enabled arrhythmia prediction sub-segments as FDA cybersecurity validation requirements expand engineering headcount needs. Long-term viability favors manufacturers with dedicated regulatory infrastructure and active implant registry capabilities. Acquisition target archetype: leadless technology specialists with CE marking pathway progress. Signal to watch: CMS remote patient monitoring reimbursement code expansion frequency.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Submission | Extended premarket approval timelines for novel sensing algorithms delay commercialization versus predicate pathways. |
| CE Marking Pathway | EU MDR strengthened notified body oversight elevates clinical evidence burdens for legacy device families. |
| Hospital System Partnership | Cath lab consolidation in Berlin, Munich, and Heidelberg concentrates procurement authority for integrated CRM platforms. |
| Software Companion Development | AI-enabled arrhythmia prediction converges machine learning with implantable sensing for preventive intervention protocols. |
| Reimbursement Strategy | Medicare tightening elevates qualification thresholds favoring devices with demonstrated remote monitoring outcomes. |
Research Approach
Findings reconcile primary fieldwork against secondary review of FDA 510(k) and PMA filings, CMS Medicare reimbursement databases, and EU MDR notified body guidance documents. Electrophysiologists, hospital purchasing committee chairs, biomedical engineers, and GPO contracts managers provided qualitative input on procurement specification evolution. SEC 10-K disclosures from listed manufacturers and ISO 14155 clinical investigation standards supplied quantitative anchors. Bottom-up implant volume modeling and top-down market sizing triangulated demand estimates.
Forecast inputs incorporate device type segmentation, end-user channel stratification, technology capability tiers, and application indication complexity across the projection horizon. Modeled dimensions span pacemaker, ICD, CRT, and loop recorder categories with wireless telemetry and leadless technology penetration rates. CAGRs derive from replacement cycle economics, cath lab capacity expansion, and reimbursement code evolution. Heart failure prevalence trajectories and electrophysiologist fellowship pipeline constraints inform demand elasticity assumptions.
Sensitivities concentrate around FDA premarket approval timeline extensions, EU MDR post-market surveillance cost escalation, and lithium-iodine cell supply disruption. Forecasts reflect assumptions on Medicare reimbursement stability and integrated delivery network consolidation velocity. Cross-checking against CMS remote patient monitoring billing code utilization data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Wrist Fixator Procedure Kit Market
Medical Devices
South America C-Arms Market
Medical Devices
Wearable Blood Pressure Monitor Market
Medical Devices
Global Interventional Neurology Devices Market
Medical Devices
Digital Body Thermometer Market
Medical Devices
Fluidics for Preclinical Market
Medical Devices
Nano Healthcare Technology Market
Medical Devices
Global Pupillometer Market
Medical Devices
Global Medical Composite Market
Medical Devices
North America Neurostimulation Devices Market
Medical Devices
Brazil Respiratory Devices Market
Medical Devices
Ultrasound Skin Tightening Devices Market
Medical Devices
Global Wearable Pregnancy Devices Market
Medical Devices
Pediatric Home-Use Medical Devices Market
Medical Devices
Veno-Venous Extracorporeal Life Support (VV ECLS) Devices Market
Medical Devices
Cyclotron Market