
 Occlusion Balloon Catheter Market | 2026-2036
Occlusion Balloon Catheter Market Size, Share, and Industry Trends Forecast 2026-2036
Occlusion Balloon Catheter Market Outlook
End-use demand is shifting toward ambulatory surgical centers as outpatient cardiovascular procedures expand and hospitals face capacity constraints. Boston Scientific Corporation leverages its integrated electrophysiology and interventional cardiology portfolio to maintain catheter supply chain continuity across multiple continents. Cook Medical anchors its competitive stance through in-house manufacturing of specialty balloons with proprietary polymer formulations. Medtronic competes by extending its structural heart and peripheral interventions footprint into occlusion balloon adjacencies.
An occlusion balloon catheter is a minimally invasive device comprising a compliant or semi-compliant balloon membrane bonded to a steerable shaft, designed to temporarily block or isolate blood flow during diagnostic or therapeutic interventions. The balloon inflates via hydraulic pressure to a specified diameter and burst pressure rating, enabling controlled vascular occlusion for procedures such as angioplasty, embolization, or temporary flow arrest. PTCA balloons occupy the mature volume core of the market, while temporary occlusion balloons capture expanding margin pools in complex structural heart cases. Hydraulic technologies dominate current installed procedural bases, though pneumatic systems are gaining traction in neurovascular applications requiring rapid deflation profiles.
FDA 510(k) clearance pathways and EU MDR technical documentation requirements shape product development timelines and market access costs for manufacturers serving Western markets. Japan's PMDA and China's NMPA impose additional clinical validation standards that filter entrants without localized regulatory infrastructure. Stakeholders must monitor reimbursement coding dynamics for outpatient catheterization procedures, as site-of-service payment differentials between hospitals and ambulatory centers directly influence purchasing concentration and device selection criteria.
Market Dynamics
The migration of cardiovascular procedures from inpatient to ambulatory settings is compressing purchasing cycles and forcing manufacturers to reconfigure catheter sizing and packaging for same-day discharge protocols.
Growth Catalysts
- Medicare site-of-service differentials:Reimbursement advantages for outpatient catheterization procedures accelerate capital deployment into ambulatory surgical centers across the United States.
- Structural heart complexity:Transcatheter valve replacements and left atrial appendage closures generate demand for temporary occlusion balloons with rapid inflation-deflation profiles.
- Polymer formulation advances:Proprietary compliant membrane chemistries extend burst pressure ratings while reducing wall thickness for navigational flexibility.
Market Restraints
- Specialty polymer supply concentration:North American and European resin suppliers control high-purity thermoplastic elastomer feedstocks for balloon membranes.
- EU MDR technical documentation burden:Extended conformity assessment timelines delay product launches and strain regulatory affairs staffing.
- PTCA balloon commoditization:Mature angioplasty segments face pricing pressure from Asian contract manufacturers with automated production lines.
Strategic Opportunities
- Neurovascular occlusion adjacencies:Pneumatic balloon systems with sub-second deflation capture share in stroke thrombectomy and aneurysm embolization workflows.
- Japan PMDA streamlined review:Sakigake designation pathways for breakthrough devices reduce time-to-market for novel catheter designs.
- Integrated lab network procurement:Multi-hospital catheterization lab consortiums create volume aggregation channels bypassing traditional distributor markups.
Industry Challenges
- Polymer processing talent scarcity:Thin-wall extrusion and balloon blow-molding expertise concentrates among aging technician cohorts in Minnesota and Ireland manufacturing clusters.
- Dual regulatory file maintenance:Parallel FDA 510(k) and EU MDR technical documentation requirements consume quality assurance bandwidth without revenue recognition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Occlusion Balloon Catheter Market |
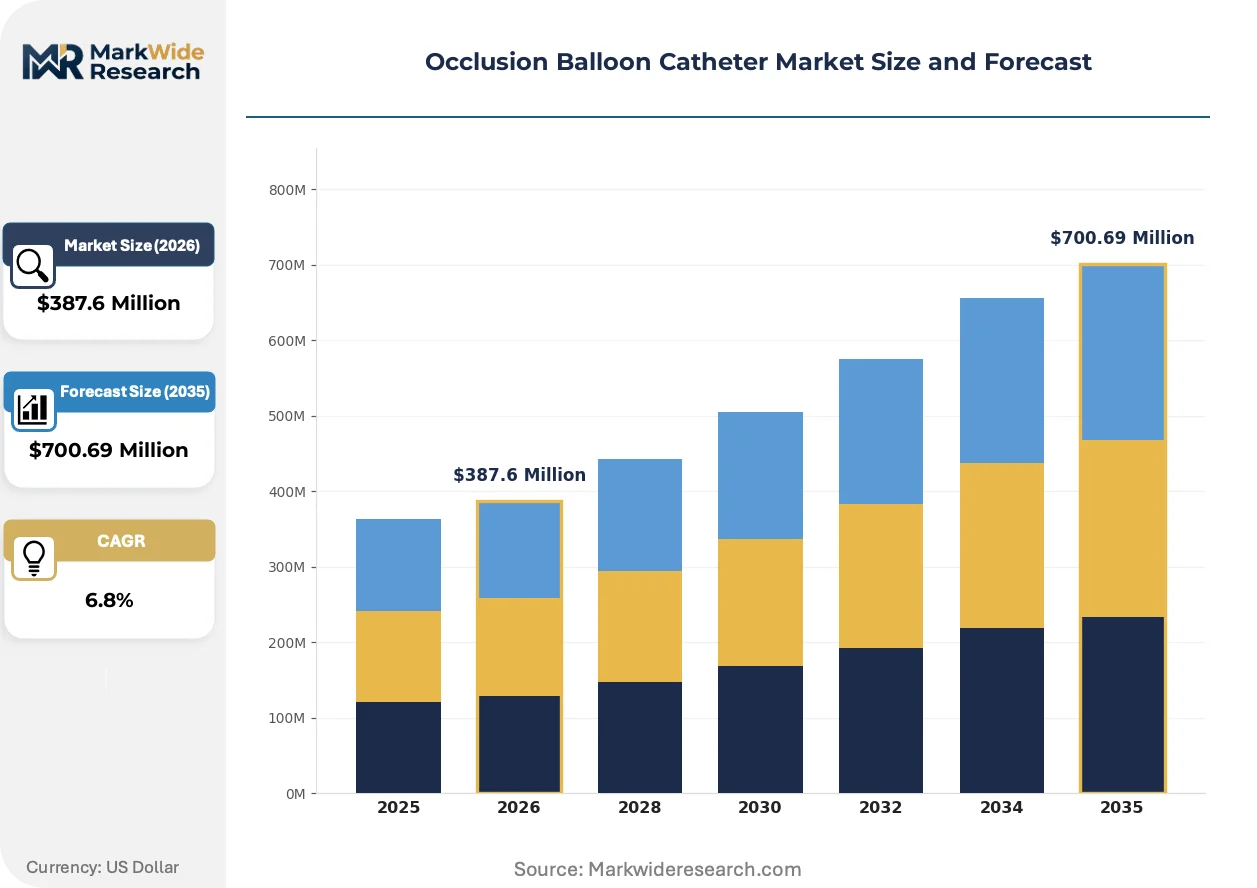
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $700.69 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PTCA Balloons, Focal Occlusion Balloons, Temporary Occlusion Balloons, Others End User: Hospitals, Ambulatory Surgical Centers, Diagnostic Imaging Centers, Specialty Clinics Application: Cardiovascular Procedures, Neurological Procedures, Gastroenterological Procedures, Urological Procedures Technology: Hydraulic Technologies, Pneumatic Technologies, Mechanical Technologies, Electrical Technologies |
| Companies Covered | Boston Scientific Corporation, Cook Medical, Stryker Corporation, W. L. Gore & Associates, Oscor Inc., Medtronic, Terumo Corporation, Merit Medical Systems, Front Line Medical Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Occlusion Balloon Catheter Market Strategic Shifts
Catheter architecture is fragmenting into component-optimized subsystems as manufacturers decouple balloon membrane chemistry from shaft steerability to accelerate iteration cycles.
Compliant balloon membranes with gradient-density polymer layering are modularizing the interface between vascular access and therapeutic delivery. Interventional cardiologists in high-volume United States catheterization labs specify these platforms for complex chronic total occlusion cases. The technology is modularizing procurement decisions, allowing hospitals to mix membrane formulations from one supplier with shaft geometries from another.
EU MDR post-market surveillance requirements mandate systematic clinical follow-up data collection for class III devices. Manufacturers must maintain electronic systems for vigilance reporting and periodic safety updates across notified body jurisdictions. Temporary occlusion balloons with novel materials face disproportionate scrutiny, compressing development timelines for European launches relative to FDA-cleared equivalents.
Catheter procurement is consolidating through integrated delivery network formulary committees that standardize device selection across multiple facilities. Ambulatory surgical centers within these networks gain purchasing parity with flagship hospitals, eroding traditional site-of-service price discrimination. The United States exhibits the most advanced concentration, with multi-state cardiology groups negotiating direct manufacturer contracts.
Occlusion Balloon Catheter Market Segmentation
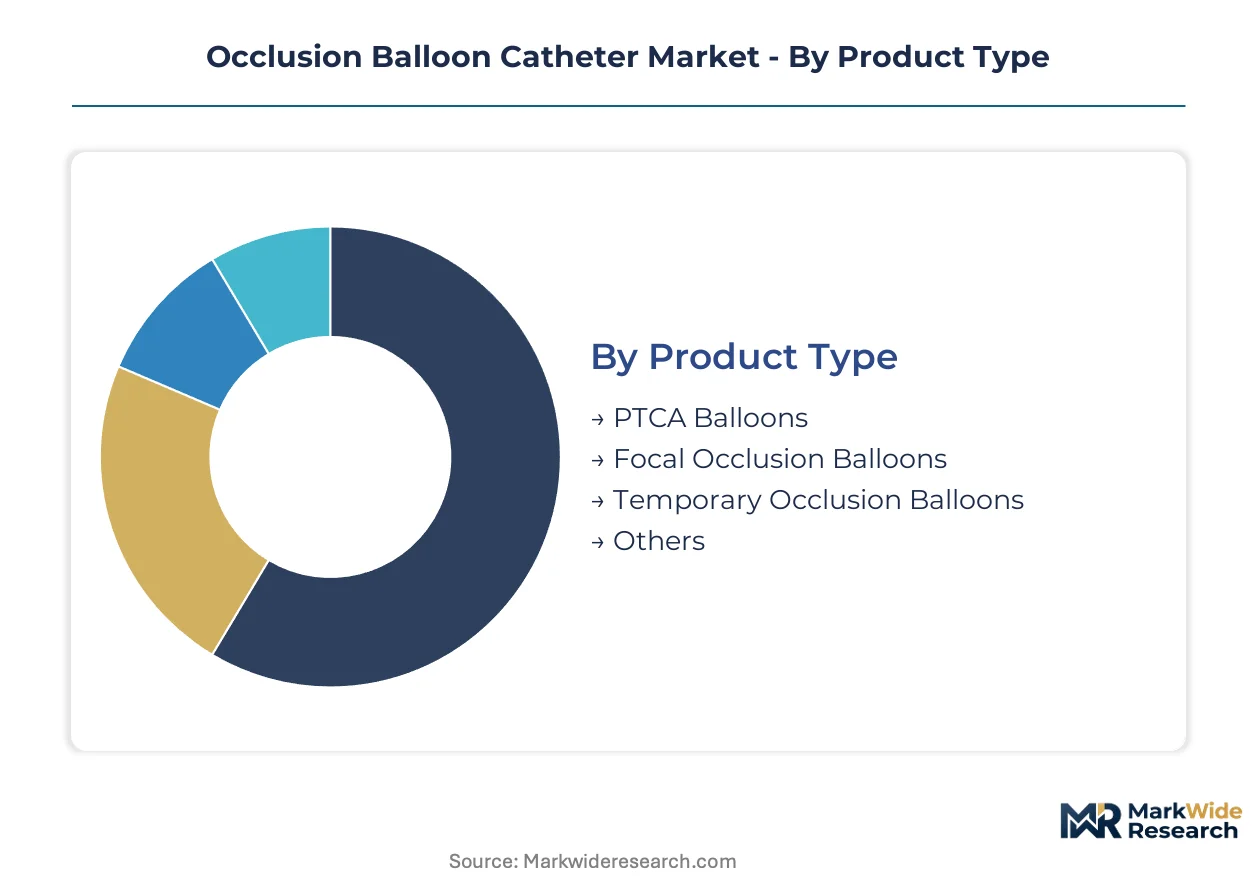
Device procurement decisions in the occlusion balloon catheter market fragment across clinical workflow requirements, site-of-service economics, and procedural complexity tiers. Manufacturers must align balloon membrane specifications with the upgrade cycles of catheterization lab equipment and the evolving reimbursement profiles of each care setting.
Product Type:
Replacement cycles for occlusion balloon platforms accelerate as catheterization labs refresh imaging systems and pressure-monitoring consoles, forcing compatibility upgrades across balloon inflation interfaces.
- PTCA Balloons:Semi-compliant polyethylene terephthalate membranes dominate this mature segment, with burst pressure ratings calibrated for coronary artery dilation. Demand concentrates in United States hospital catheterization labs where Medicare reimbursement for percutaneous coronary intervention sustains high procedural throughput despite pricing compression.
- Temporary Occlusion Balloons:Ultra-compliant thermoplastic elastomer formulations enable rapid inflation-deflation cycles essential for transcatheter valve replacement procedures. Adoption is climbing fastest in ambulatory surgical centers within integrated delivery networks that have secured site-of-service payment differentials for structural heart interventions.
- Focal Occlusion Balloons:Short-segment designs target embolization procedures requiring precise flow arrest.
- Others:Specialty configurations including cutting balloons and drug-coated variants serve niche revascularization protocols.
Volume placements concentrate in PTCA Balloons; the faster expansion belongs to Temporary Occlusion Balloons.
End User:
Capital deployment patterns across care settings reflect divergent reimbursement economics and patient throughput requirements.
- Ambulatory Surgical Centers:Same-day discharge protocols drive demand for pre-sterilized, single-use catheter kits with streamlined packaging. United States multi-state cardiology groups negotiate direct manufacturer contracts, bypassing traditional distributor markups and compressing procurement cycles.
- Hospitals:High-acuity catheterization labs maintain inventory breadth for emergency PCI and complex chronic total occlusion cases. Capacity constraints are pushing stable elective procedures toward outpatient settings, eroding historical volume concentration.
- Diagnostic Imaging Centers:Limited therapeutic scope restricts occlusion balloon utilization to pre-procedural planning.
- Specialty Clinics:Peripheral vascular practices in suburban United States markets source mid-tier compliant balloons for office-based lab procedures.
Procurement authority is shifting toward Ambulatory Surgical Centers; Hospitals retain the highest absolute consumption.
Application:
Procedural migration patterns determine which balloon specifications gain priority in manufacturer development pipelines.
- Cardiovascular Procedures:Coronary and peripheral interventions consume the majority of compliant and semi-compliant balloon inventory. United States integrated delivery network formulary committees standardize device selection across flagship hospitals and affiliated ambulatory centers.
- Neurological Procedures:Stroke thrombectomy and aneurysm embolization require pneumatic balloon systems with sub-second deflation profiles. PMDA Sakigake designation pathways in Japan accelerate regulatory clearance for novel neurovascular catheter designs.
- Gastroenterological Procedures:Transarterial chemoembolization utilizes occlusion balloons for hepatic flow control.
- Urological Procedures:Benign prostatic hyperplasia interventions represent an emerging adjacency for temporary occlusion platforms.
Revenue concentration sits with Cardiovascular Procedures; Neurological Procedures are gaining share fastest.
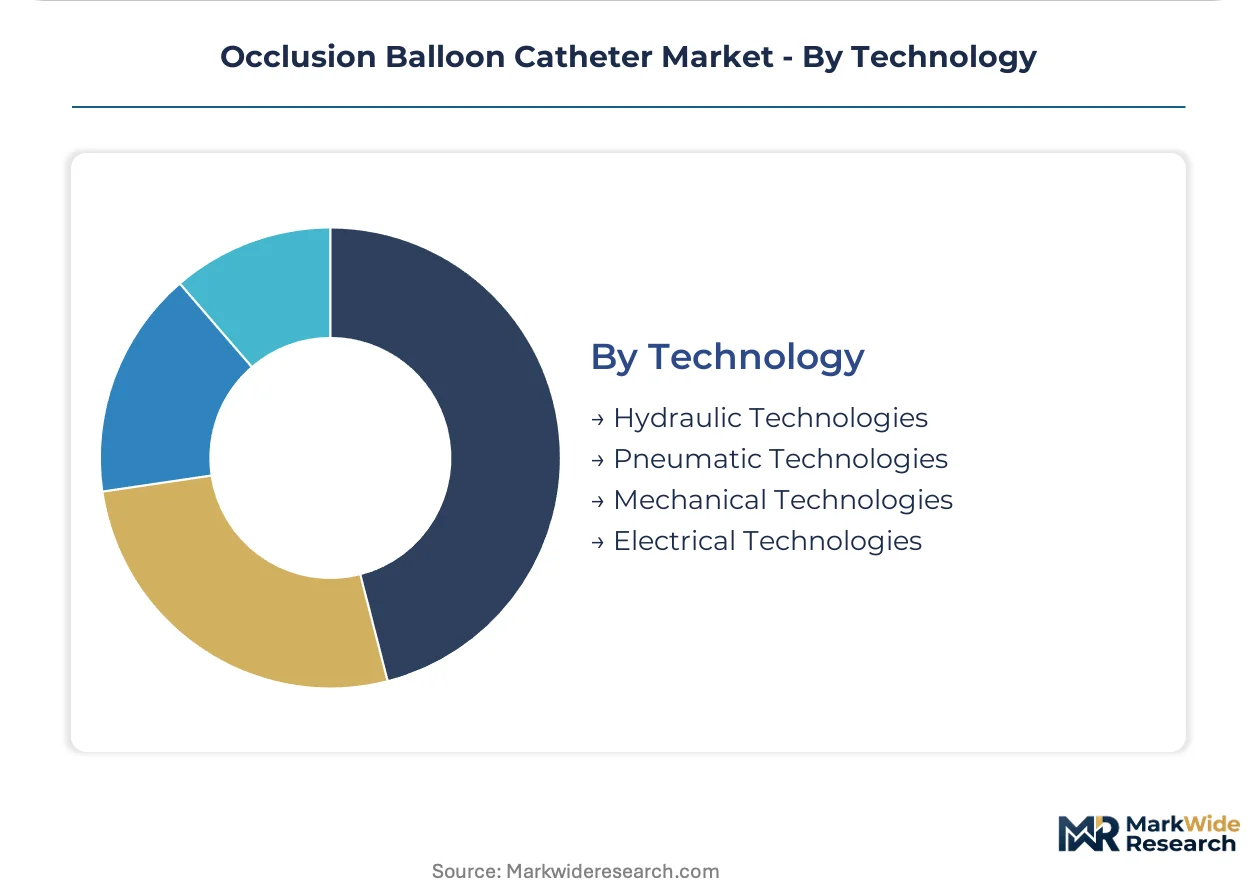
Technology:
Inflation mechanism selection trades off precision control against deflation speed requirements.
- Hydraulic Technologies:Pressure-monitored saline inflation dominates installed procedural bases across United States catheterization labs. FDA 510(k) clearance pathways for hydraulic systems are well-established, reducing regulatory uncertainty for incremental product iterations.
- Pneumatic Technologies:Compressed gas systems enable rapid balloon collapse critical for neurovascular applications. EU MDR technical documentation requirements impose extended conformity assessment timelines for pneumatic platforms with novel materials.
- Mechanical Technologies:Screw-driven inflation mechanisms serve resource-constrained settings lacking pressurized gas infrastructure.
- Electrical Technologies:Electromechanical pressure control remains experimental, with limited commercial penetration.
Installed base dominance belongs to Hydraulic Technologies; Pneumatic Technologies show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Free-trade zones in Shenzhen and Shanghai accelerate catheter component manufacturing concentration for Asia-Pacific supply chains. Tax incentives for medical device production in Minnesota and Ireland anchor Western hemisphere balloon membrane fabrication. Site-of-service reimbursement differentials in the United States concentrate procedural demand within integrated catheterization lab networks.
United States
Medicare outpatient payment differentials drive capital deployment into ambulatory surgical centers across multi-state cardiology networks. FDA 510(k) clearance pathways establish well-trodden regulatory routes for hydraulic occlusion balloon iterations. Minneapolis-St. Paul hosts concentrated thin-wall extrusion expertise among aging technician cohorts supplying membrane feedstocks.
Germany
EU MDR technical documentation requirements extend conformity assessment timelines for pneumatic balloon platforms entering European markets. REACH compliance for specialty thermoplastic elastomers filters non-European resin suppliers from high-purity feedstock channels. Baden-Württemberg industrial clusters maintain precision polymer processing infrastructure for compliant membrane production.
Japan
PMDA Sakigake designation pathways compress regulatory review periods for breakthrough neurovascular catheter designs. METI medical device reimbursement frameworks differentiate payment rates between hospital and outpatient stroke thrombectomy settings. Kansai manufacturing corridors concentrate pneumatic system assembly for sub-second deflation applications.
China
NMPA clinical validation standards for class III cardiovascular devices require localized regulatory infrastructure for market entry. Dual carbon goals in manufacturing zones pressure polymer processing facilities toward energy-efficient blow-molding operations. Yangtze River Delta medical device parks attract catheter assembly investments from multinational contract manufacturers.
Switzerland
Swissmedic streamlined review procedures for innovative temporary occlusion balloons attract EU-parallel filing strategies from device developers. Precision polymer formulation R&D tax credits sustain proprietary membrane chemistry investments in Lake Geneva biotech corridors. Basel-area industrial clusters integrate balloon membrane prototyping with pharmaceutical delivery system development.
Occlusion Balloon Catheter Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with integrated electrophysiology portfolios commanding premium positioning in United States catheterization labs while Asian automated production lines capture commoditized PTCA balloon volume. The vendor base organizes around three archetypes: diversified cardiovascular conglomerates with structural heart adjacencies, specialty balloon fabricators with captive polymer supply, and neurovascular-focused innovators exploiting pneumatic deflation speed. M&A activity concentrates on neurovascular occlusion capabilities, while strategic partnerships between membrane chemists and shaft geometry specialists accelerate modular subsystem development.
Among diversified cardiovascular conglomerates, Boston Scientific Corporation and Medtronic occupy positions spanning electrophysiology through structural heart interventions, with their scale enabling integrated catheterization lab procurement negotiations. Cook Medical exemplifies the specialty fabricator archetype through in-house polymer formulation capabilities. Terumo Corporation represents Asia-Pacific manufacturing scale advantages in automated balloon production lines.
| Leading Market Players |
|---|
| Boston Scientific Corporation |
| Cook Medical |
| Stryker Corporation |
| W. L. Gore & Associates |
| Oscor Inc. |
| Medtronic |
| Terumo Corporation |
| Merit Medical Systems |
| Front Line Medical Technologies |
| Others |
Value Chain & Pricing Dynamics
PTCA balloon commoditization against temporary occlusion premium tiers bifurcates the market into margin-compressed volume segments and defensible high-performance niches, with FDA 510(k) clearance tiers and EU MDR conformity assessment burdens determining which suppliers capture pricing power versus facing procurement consolidation.
Pricing Analysis
Short lead-time premiums for compliant membrane formulations reward manufacturers with Minnesota and Ireland extrusion capabilities, while spot inventory discounts erode margins for Asian contract producers. Three-tier pricing structure across premium, standard, and economy levels separates proprietary thermoplastic elastomer platforms from semi-compliant polyethylene terephthalate variants and commodity angioplasty balloons. Cost compression in PTCA segments is intensifying because automated production lines in Asia-Pacific manufacturing parks undercut Western fabrication costs. Ambulatory surgical centers within United States integrated delivery networks exhibit the sharpest price sensitivity through direct manufacturer contract negotiations, whereas hospital catheterization labs maintain lower sensitivity for emergency PCI inventory.
Supply Chain Analysis
ISO 13485 and FDA QSR certification gating filters resin suppliers and contract manufacturers from high-purity thermoplastic elastomer feedstock channels. Geographic concentration centers on the United States for thin-wall extrusion expertise, Ireland for balloon blow-molding operations, and China for automated assembly lines. Raw material dependencies draw from North American and European specialty polymer suppliers, Japanese precision catheter components, and Chinese packaging materials. Single-source vulnerability concentrates in aging technician cohorts mastering proprietary polymer formulations. Distribution runs through integrated delivery network formulary committees and GPO contracts bypassing traditional distributor markups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
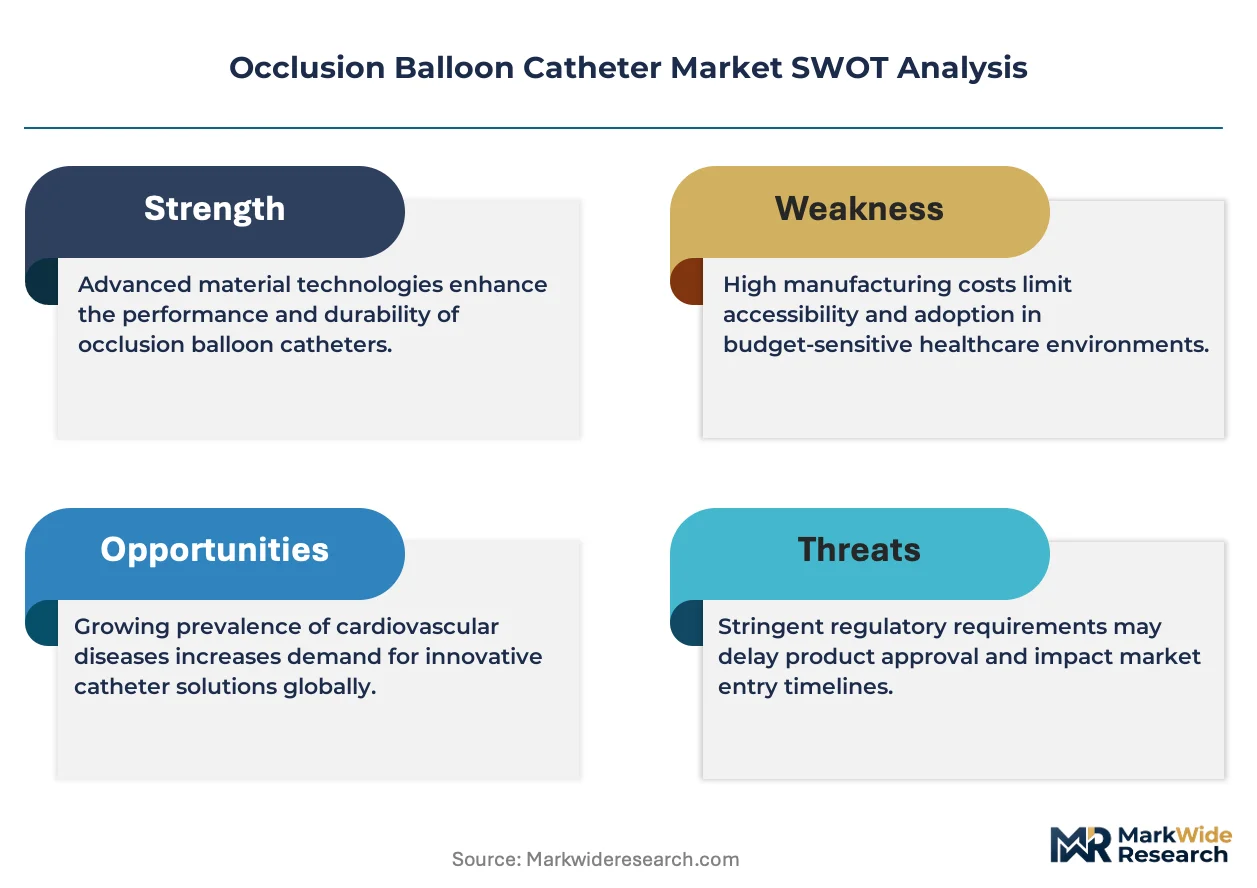
This market operates as a cost-of-compliance story where EU MDR technical documentation requirements and FDA 510(k) pathway investments erect barrier-to-entry moats favoring incumbent manufacturers with established regulatory affairs infrastructure.
For Market Incumbents: Anticipate margin compression in PTCA balloons by accelerating proprietary polymer formulation R&D in Minnesota and Ireland clusters, while defending structural heart adjacencies through captive supply of rapid-inflation thermoplastic elastomer membranes. Site-of-service reimbursement differentials threaten hospital volume concentration; counter by securing direct contracts with multi-state ambulatory surgical center networks.
For New Entrants and Emerging Players: Neurovascular stroke thrombectomy programs represent the most penetrable buyer archetype, as pneumatic balloon demand with sub-second deflation profiles outpaces established supply. Target Japan's PMDA Sakigake designation pathway for breakthrough device status, then leverage streamlined regulatory clearance into United States catheterization lab procurement trials through niche performance specifications.
For Investors and Strategic Acquirers: Exit pathways concentrate in neurovascular occlusion capability acquisitions, with pneumatic system expertise and PMDA-cleared product portfolios commanding strategic premiums. Long-term viability favors manufacturers with backward integration into specialty polymer supply and dual FDA-EU MDR filing capacity. Monitor Medicare site-of-service reimbursement rulemaking as the critical inflection signal for ambulatory surgical center capital deployment velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Premarket Notification | Establishes clearance pathway for hydraulic occlusion balloon iterations in United States catheterization labs. |
| EU MDR Technical Documentation | Extends conformity assessment timelines but creates regulatory moat against non-compliant Asian competitors. |
| Hospital System Partnership | Integrated delivery network formulary committees consolidate procurement across flagship and ambulatory facilities. |
| Backward Integration into Polymers | In-house thermoplastic elastomer formulation secures burst pressure rating advantages and supply continuity. |
| Reimbursement Strategy | Medicare outpatient payment differential positioning determines ambulatory surgical center purchasing concentration. |
Study Parameters
Independent corroboration across interventional cardiologists, hospital purchasing committee members, biomedical engineers, and GPO contracts managers underwrites the qualitative findings, validated against FDA 510(k) clearance databases, EU MDR notified body documentation, CMS Medicare reimbursement schedules, and hospital procurement contract records. Bottom-up segmentation modeling triangulates with top-down macroeconomic drivers.
Rate-of-change decomposition separates volume growth in PTCA balloons from value expansion in temporary occlusion platforms across the analysis window, with segmentation dimensions spanning product type, end-user setting, procedural application, and inflation technology. CAGRs derive from installed base replacement cycles, catheterization lab equipment refresh timelines, and site-of-service migration patterns. Forecast inputs incorporate polymer formulation advancement trajectories and regulatory pathway timeline assumptions.
Revisions become necessary when Medicare site-of-service reimbursement rules shift materially, EU MDR notified body capacity constraints extend conformity assessments, or specialty polymer supply disruptions alter membrane fabrication economics. A model refresh is warranted upon material change in ambulatory surgical center capital deployment velocity or breakthrough device designation pathway utilization rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Smart Lenses Market
Medical Devices
Australia and New Zealand Diabetes Devices Market
Medical Devices
Global Cardiac Reader System Market
Medical Devices
Cerebral Thrombectomy Devices Market
Medical Devices
Biomedical Temperature Sensors Market
Medical Devices
Laparoscopic Electrodes Market
Medical Devices
Life Science Microscopy Devices Market
Medical Devices
United Kingdom Spinal Surgery Devices Market
Medical Devices
Implant-Borne Prosthetics Market
Medical Devices
Global Soft Tissue Allografts Market
Medical Devices
Self-Destructing Syringe Market
Medical Devices
North America Organ-On-Chip Market
Medical Devices
Spinal Trauma Devices Market
Medical Devices
Nasal Implant Market
Medical Devices
Global Optical Biometry Devices Market
Medical Devices
Epilepsy Devices Market