
 Nerve Monitoring Devices Market | 2026-2036
Nerve Monitoring Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Nerve Monitoring Devices Market Analysis
Specialized neurophysiology technologist shortages across North American and European surgical centers is redrawing how hospitals procure and deploy intraoperative monitoring systems. Medtronic leverages its integrated surgical ecosystem to bundle nerve monitoring with navigation and imaging platforms. NuVasive, Inc. anchors its competitive stance through dedicated spine surgery applications where real-time EMG feedback reduces neural complication rates.
Nerve monitoring devices encompass electromyography systems, nerve stimulators, and portable monitors that detect bioelectrical signals from neural tissue during surgical or diagnostic procedures, typically operating within microvolt sensitivity ranges and millisecond latency windows to preserve functional integrity. Intraoperative monitoring dominates current hospital procurement budgets as reimbursement frameworks tie neural outcome metrics to procedure economics. AI integration represents the fastest-expanding technology segment, though digital signal processing still commands the largest installed base due to proven reliability in high-stakes surgical environments.
FDA 510(k) clearance pathways and EU MDR technical documentation requirements impose rigorous clinical validation standards on electromyography and stimulation device manufacturers. ISO 13485 quality management systems and IEC 60601 electrical safety standards further constrain design architectures and supply chain qualifications. Stakeholders must weigh regulatory compliance timelines against AI-enabled feature development to capture preference shifts in academic medical center purchasing committees.
Market Dynamics
The convergence of AI-enabled signal processing with traditional electromyography platforms is compressing equipment refresh cycles at tertiary surgical centers. This technological displacement forces incumbent vendors to recertify legacy architectures under tightened FDA 510(k) and EU MDR validation protocols.
Growth Catalysts
- EU MDR conformity assessments:Tighter technical documentation requirements for electromyography devices are filtering out marginal suppliers and consolidating procurement decisions around validated platforms.
- Spine surgery volume concentration:United States academic medical centers are mandating real-time neural integrity monitoring for complex deformity corrections, embedding nerve monitoring into standard-of-care protocols.
- Microvolt sensitivity advances:Improved bioelectrical signal detection thresholds are expanding monitoring applicability from motor nerves to mixed and sensory pathways.
Market Restraints
- Specialized technologist shortages:North American and European surgical centers face persistent gaps in certified neurophysiology personnel, capping utilization rates of installed monitoring systems.
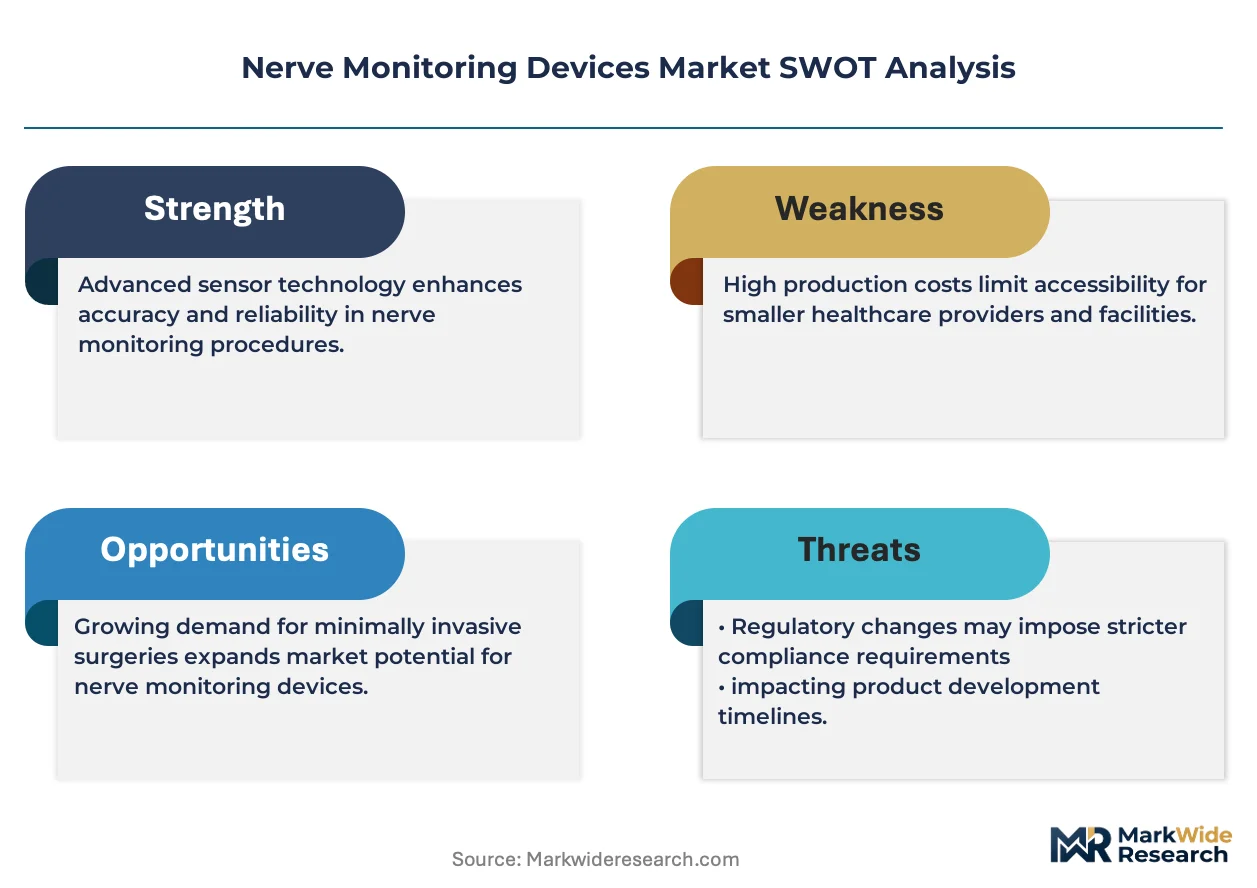
- Capital equipment intensity:Multi-channel EMG platforms require substantial upfront investment, constraining adoption at mid-tier community hospitals with constrained capital budgets.
- Regulatory timeline friction:FDA 510(k) clearance pathways for AI-integrated features impose 12-18 month validation cycles that lag behind software development velocities.
Strategic Opportunities
- Portable monitor penetration:Ambulatory surgical centers in Germany and Japan represent underdeployed settings where compact, battery-operated nerve stimulators can displace rental-dependent service models.
- ISO 13485 certification arbitrage:Contract manufacturers with established quality management systems can capture outsourced production from OEMs facing EU MDR technical documentation burdens.
- Machine learning convergence:Integration of predictive artifact rejection algorithms with existing digital signal processing architectures creates upgrade revenue without full platform replacement.
Industry Challenges
- Cross-functional training deficits:Operating room staff require simultaneous competence in surgical workflow, neurophysiological interpretation, and equipment troubleshooting.
- Legacy system integration complexity:Newer AI-enabled monitors must interface with installed surgical navigation and imaging platforms through proprietary data protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nerve Monitoring Devices Market |
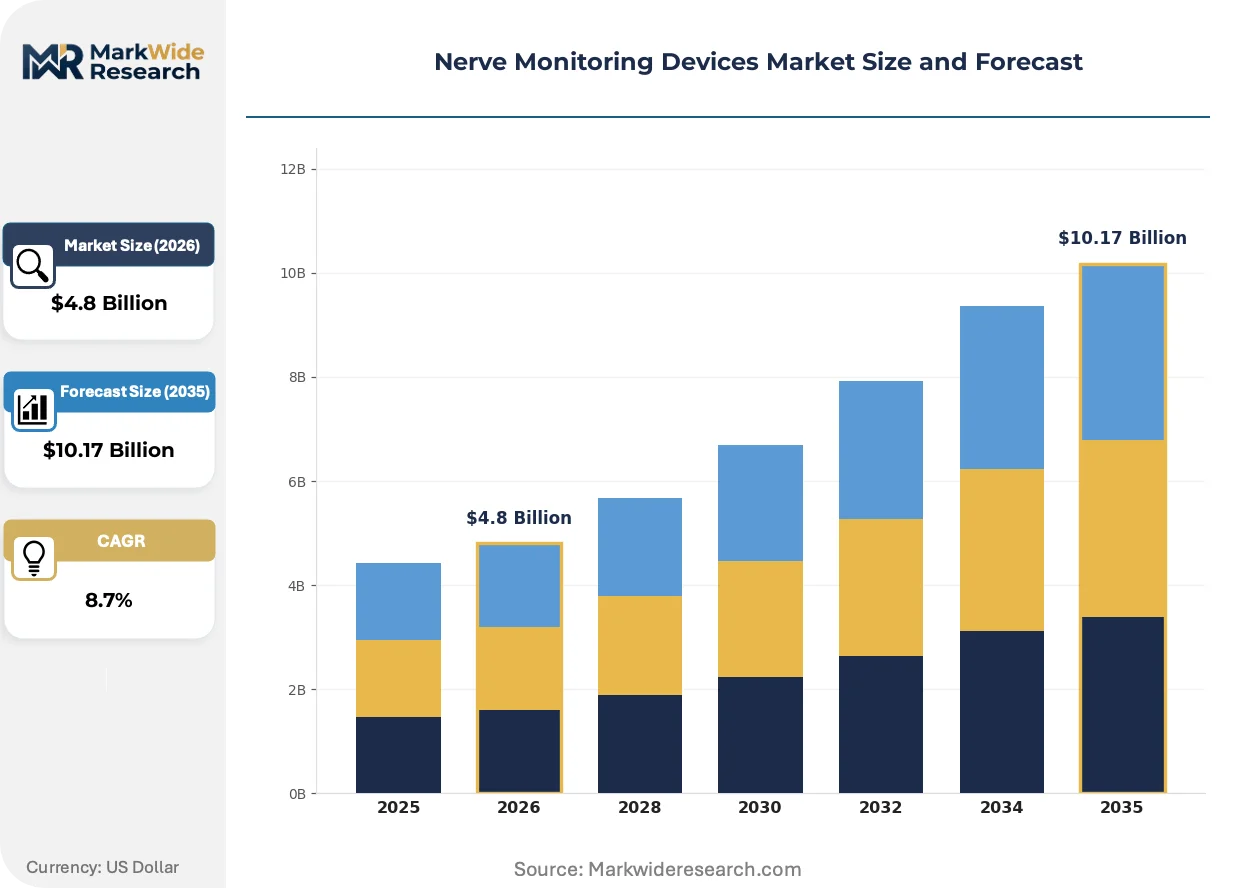
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Electromyography, Nerve Stimulation, Intraoperative Monitoring, Portable Monitors Application: Pain Management, Surgical Procedures, Neurological Disorders, Rehabilitation End User: Hospitals, Clinics, Research Institutions, Rehabilitation Centers Technology: Wireless Monitoring, Digital Signal Processing, Real-Time Analysis, AI Integration |
| Companies Covered | Medtronic, NuVasive, Inc., Natus Medical, Nihon Kohden, Cadwell Laboratories, Checkpoint Surgical, Inomed, Langer Medical GmbH, Neurosign, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nerve Monitoring Devices Market Emerging Trajectories
Signal processing architectures are fragmenting as computational demands outpace hardware refresh budgets. This divergence is forcing surgical centers to evaluate cloud-augmented monitoring against edge-computing alternatives.
Artificial intelligence-based artifact detection is decomposing traditional threshold-based alarm systems into probabilistic risk scoring. Academic medical centers in the United States are piloting these platforms for complex spinal deformity cases. The technology is decomposing the role of human technologists from real-time interpretation to supervisory validation.
FDA 510(k) premarket notification pathways are tightening clinical validation requirements for algorithm-driven EMG interpretation. Manufacturers must now submit prospective clinical data rather than predicate-device equivalence. Spine surgery device portfolios face the highest compliance burden as neural outcome metrics become tied to reimbursement frameworks.
Hospital purchasing committees are unbundling intraoperative monitoring service contracts from capital equipment sales. Third-party neurophysiology staffing firms are capturing recurring revenue streams previously retained by device OEMs. This disintermediation is most visible in United States metropolitan markets where surgical volume concentration supports dedicated outsourced monitoring teams.
Nerve Monitoring Devices Market Segmentation
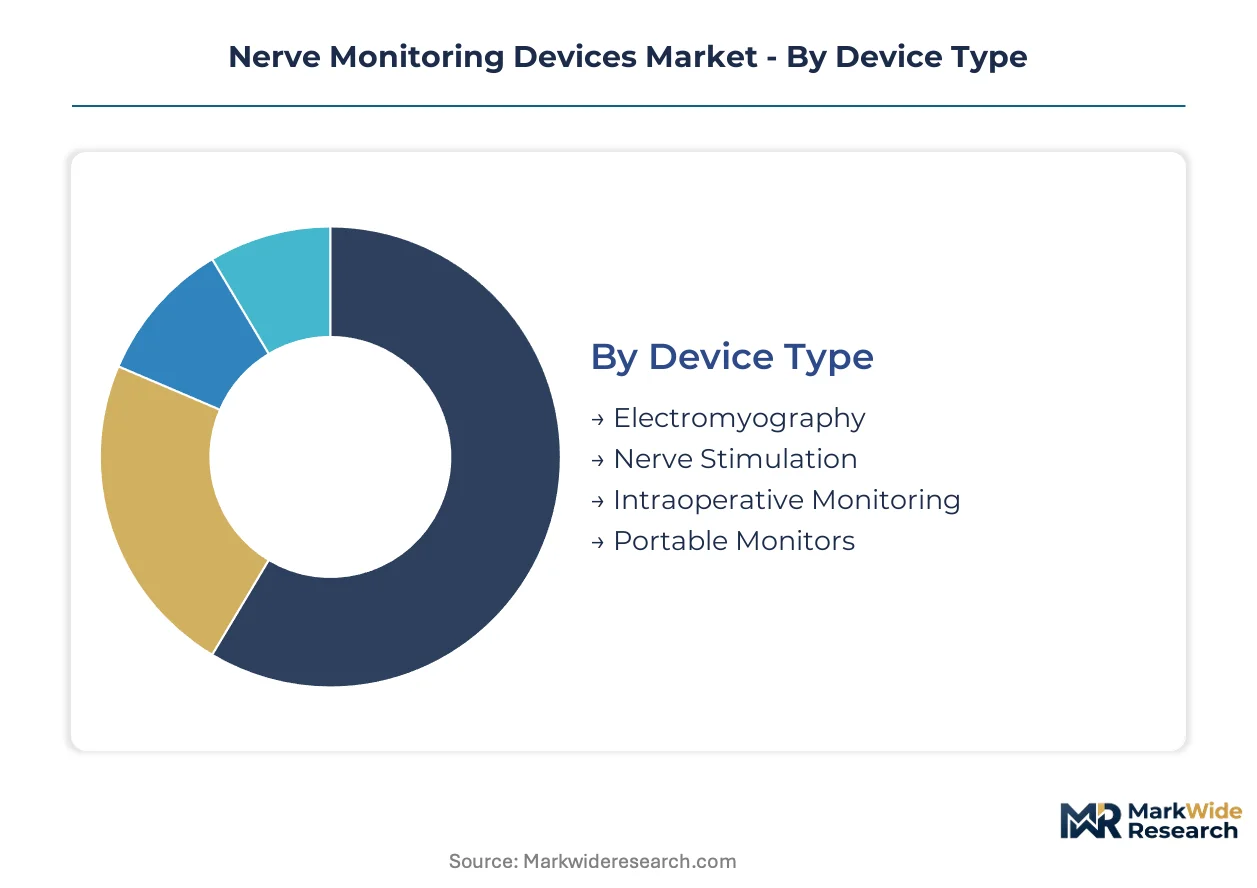
Surgical centers configure procurement around procedure-specific neural monitoring requirements, not generic device categories. Equipment refresh decisions hinge on whether installed platforms support AI-augmented signal interpretation or require complete replacement.
Device Type:
Portable monitors and wireless-enabled stimulators face intensifying substitution pressure from smartphone-integrated bioelectric sensors in diagnostic settings, though regulatory validation gaps protect the surgical core.
- Electromyography:Multi-channel surface and needle electrode systems detect microvolt-level motor unit potentials with millisecond temporal resolution. United States academic medical centers anchor demand for high-channel-count platforms during complex spinal deformity corrections, constrained by FDA 510(k) recertification timelines for algorithm-enhanced variants.
- Intraoperative Monitoring:Integrated EMG, SSEP, and MEP acquisition systems with real-time alarm thresholds preserve neural integrity during high-risk procedures. Germany's tertiary surgical centers mandate these platforms for deformity corrections, embedding them into standard-of-care protocols through reimbursement-linked outcome metrics.
- Nerve Stimulation:Constant-current and constant-voltage stimulators with programmable pulse width and frequency parameters map neural pathways.
- Portable Monitors:Battery-operated, compact devices enable ambulatory and point-of-care neural assessment outside traditional surgical suites.
Intraoperative monitoring retains volume leadership; portable monitors hold the steepest expansion curve.
Application:
Cost tier stratification separates capital-intensive surgical applications from reimbursable diagnostic and therapeutic categories.
- Surgical Procedures:Real-time neural integrity monitoring during spine, cranial, and peripheral nerve operations demands sub-millisecond latency and artifact-resistant signal processing. Japan's neurosurgical volume concentrates at university hospitals where EMG feedback reduces iatrogenic nerve injury rates, driving preference for integrated navigation-monitoring platforms.
- Neurological Disorders:Diagnostic EMG and nerve conduction studies for peripheral neuropathy, myopathy, and motor neuron disease require precise amplitude and conduction velocity quantification. Outpatient neurology clinics in the United States deploy these systems under bundled payment models that reward diagnostic throughput.
- Pain Management:Nerve blocks and radiofrequency ablation guidance using electrical stimulation.
- Rehabilitation:Biofeedback-driven neuromuscular retraining and functional electrical stimulation protocols.
Surgical procedures command the highest equipment expenditure per site; neurological disorders deliver the most consistent utilization rates.
End User:
Customer type determines capital allocation flexibility and service contract structures.
- Hospitals:Tertiary and community surgical centers with dedicated operating room infrastructure deploy integrated monitoring ecosystems. United States hospital systems negotiate enterprise-wide service agreements that bundle equipment, disposables, and technologist staffing, consolidating vendor relationships around platforms with proven EMG reliability.
- Clinics:Outpatient surgical and neurology practices favor portable, lower-channel-count devices with simplified workflows. Ambulatory surgical centers in Germany represent underpenetrated demand for compact nerve stimulators that displace rental-dependent outsourced monitoring models.
- Research Institutions:Academic medical centers and neuroscience institutes piloting novel stimulation paradigms and signal processing algorithms.
- Rehabilitation Centers:Post-acute facilities deploying functional electrical stimulation and biofeedback systems for motor recovery.
Hospitals absorb the majority of capital equipment shipments; clinics are gaining share fastest as ambulatory migration accelerates.
Technology:
Maturity gradients separate proven digital architectures from emerging AI-enabled platforms facing validation bottlenecks.
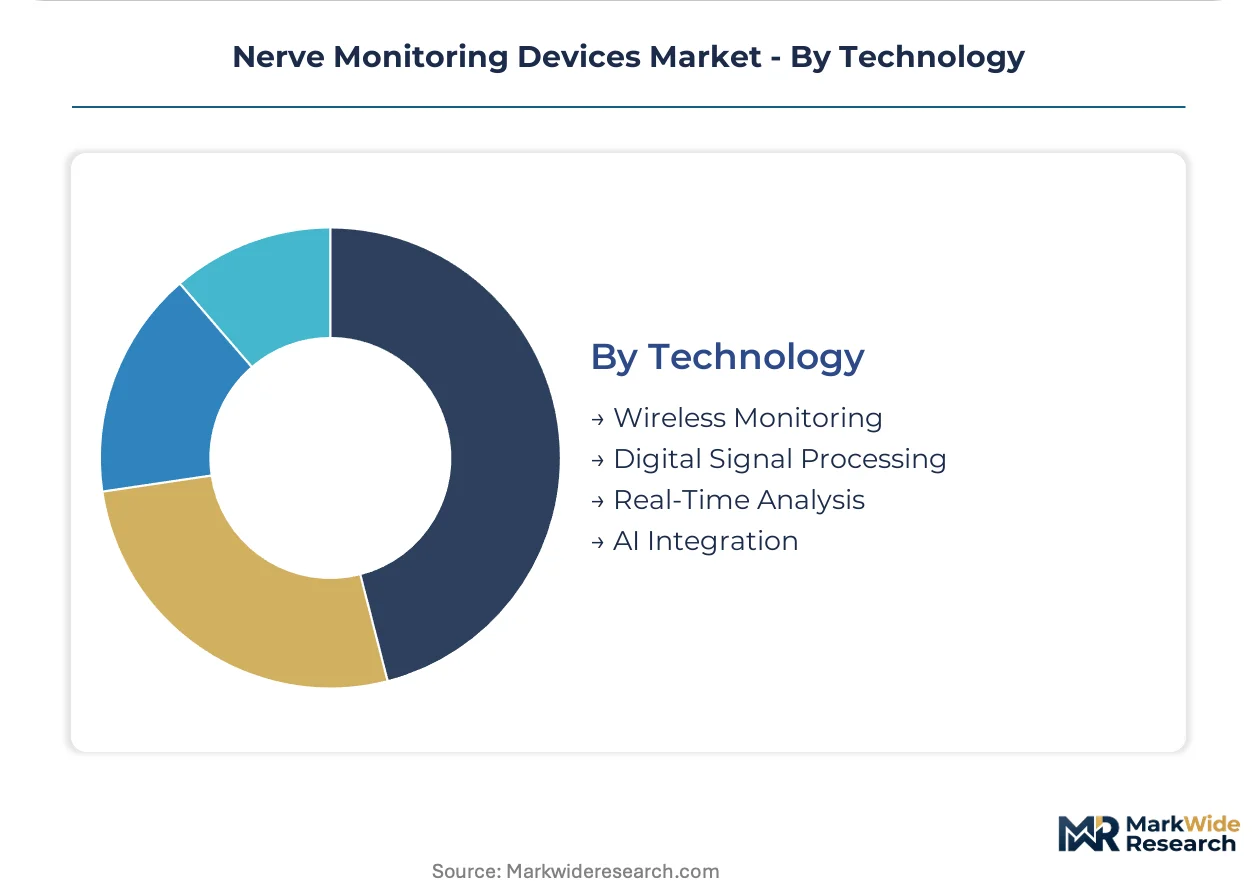
- Digital Signal Processing:Established filter banks, artifact rejection algorithms, and time-frequency decomposition methods constitute the installed base majority. IEC 60601 electrical safety compliance and ISO 13485 quality management certification constrain design architectures, favoring incremental over disruptive innovation.
- AI Integration:Machine learning models for predictive artifact detection and probabilistic risk scoring decompose traditional threshold alarms. FDA 510(k) clearance pathways now require prospective clinical data rather than predicate equivalence, extending validation cycles and compressing software development velocity.
- Wireless Monitoring:Bluetooth and proprietary RF protocols enabling untethered electrode arrays and remote display.
- Real-Time Analysis:Edge-computing architectures processing neural signals with minimal latency for intraoperative decision support.
Digital signal processing dominates current installed value; AI integration is climbing the fastest despite regulatory friction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across major markets. United States hospitals prioritize integrated surgical ecosystems while German centers emphasize standalone certification rigor. Japanese procurement favors compact, high-reliability platforms for space-constrained university hospitals.
United States
Academic medical centers in Boston and the Midwest anchor demand for multi-channel EMG platforms during complex spinal deformity corrections. FDA 510(k) clearance pathways now mandate prospective clinical data for algorithm-enhanced devices, extending validation timelines. Tertiary surgical centers in Texas and California negotiate enterprise-wide service agreements bundling equipment, disposables, and technologist staffing.
Germany
Tertiary surgical centers in Bavaria and North Rhine-Westphalia mandate real-time neural integrity monitoring for deformity corrections through reimbursement-linked outcome metrics. EU MDR conformity assessments impose rigorous technical documentation burdens on electromyography device manufacturers. Stuttgart and Munich host specialized neurophysiology training programs addressing persistent technologist shortages.
Japan
University hospitals in Tokyo and Osaka concentrate neurosurgical volume where EMG feedback reduces iatrogenic nerve injury rates. PMDA regulatory frameworks align with international electrical safety standards while maintaining distinct clinical validation requirements. Compact, battery-operated nerve stimulators penetrate ambulatory settings in Kansai region where rental-dependent service models dominate.
United Kingdom
NHS England procurement frameworks emphasize cost-per-procedure metrics over capital equipment ownership for intraoperative monitoring systems. MHRA post-Brexit regulatory pathways diverge from EU MDR timelines, creating parallel validation requirements. London and Manchester academic medical centers pilot AI-augmented signal interpretation platforms under innovation procurement schemes.
India
Corporate hospital chains in Delhi-NCR and Maharashtra expand intraoperative monitoring capacity for medical tourism spine surgery segments. CDSCO medical device regulations tighten import licensing requirements for electromyography systems. Bangalore and Hyderabad host emerging contract manufacturing operations serving OEMs seeking ISO 13485-certified production alternatives.
Nerve Monitoring Devices Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier in the nerve monitoring devices market. Medtronic leverages its surgical ecosystem breadth to bundle nerve monitoring with navigation platforms, while NuVasive anchors spine-specific applications. The vendor base fragments across dedicated EMG manufacturers, intraoperative monitoring service providers, and portable diagnostic device specialists. Strategic moves concentrate on regulatory recertification acceleration and AI feature integration to compress equipment refresh cycles.
Within the integrated surgical technology tier, Medtronic and NuVasive occupy positions exemplifying divergent ecosystem strategies. Medtronic represents the diversified platform archetype spanning multiple surgical specialties, while NuVasive exemplifies focused vertical integration within spine surgery workflows. Among European specialists, Langer Medical GmbH and Inomed sit within the precision instrumentation segment serving neurosurgical centers with established regulatory track records. Natus Medical and Nihon Kohden anchor distinct geographic strongholds, with the former representing North American diagnostic neurology equipment traditions and the latter exemplifying Japanese reliability-focused manufacturing approaches. Cadwell Laboratories occupies a position within the neurophysiology diagnostic equipment segment, while Checkpoint Surgical and Neurosign represent narrower surgical application specialists.
| Leading Market Players |
|---|
| Medtronic |
| NuVasive, Inc. |
| Natus Medical |
| Nihon Kohden |
| Cadwell Laboratories |
| Checkpoint Surgical |
| Inomed |
| Langer Medical GmbH |
| Neurosign |
| Others |
Supply Flow & Price Mechanics
Capacity utilization at ISO 13485-certified contract manufacturers in Germany and the United States determines price floors for multi-channel EMG platforms, concentrating procurement leverage among hospital systems with enterprise-scale purchasing power while squeezing mid-tier suppliers on margin.
Pricing Analysis
Long-term service contracts bundling equipment, disposables, and technologist staffing dominate United States hospital procurement, displacing capital-only transactions. Price differentiation hinges on FDA 510(k) certification tier and after-sales service depth, with algorithm-enhanced platforms commanding premium positioning. Cost compression in standard-tier systems intensifies as third-party neurophysiology staffing firms disintermediate OEM service revenue. Ambulatory surgical centers in Germany exhibit highest price sensitivity; academic medical centers in Boston and the Midwest show lowest.
Supply Chain Analysis
Malaysia and Mexico anchor printed circuit board assembly and precision electrode manufacturing for portable nerve stimulators, while Germany and Japan concentrate high-channel-count EMG system final assembly. Component sourcing draws from Taiwanese semiconductor foundries for signal processing chips and Swiss sensor specialists for microvolt-accurate acquisition hardware. Single-source vulnerability in FDA 510(k) predicate-device dependencies creates regulatory recertification risk. Distribution runs through specialized surgical device distributors with GPO contracts in the United States and direct hospital sales teams in Germany and Japan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The nerve monitoring devices market sits in early-cycle recovery as hospital capital expenditure normalization follows pandemic-deferred equipment refresh programs, with AI-augmented platform upgrades driving replacement demand.
For Market Incumbents: Fortify installed base retention by accelerating FDA 510(k) recertification for algorithm-enhanced EMG platforms ahead of competitive displacement. Deepen backward integration into disposable electrode manufacturing to capture recurring revenue streams threatened by third-party neurophysiology staffing firms. Prioritize ISO 13485-certified production capacity in Germany to hedge EU MDR technical documentation bottlenecks. For New Entrants and Emerging Players: FDA 510(k) pre-submission pathways for AI-integrated portable monitors unlock fastest regulatory clearance velocity for capital-constrained entrants. Ambulatory surgical centers in Germany and Japan represent most penetrable demand pockets where compact, battery-operated nerve stimulators displace rental-dependent service models. Pursue hospital system pilot programs with outcome-based performance guarantees to bypass entrenched vendor relationships. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors contract manufacturers with established ISO 13485 quality management systems and EU MDR technical documentation capabilities. Long-term viability centers on platforms bridging digital signal processing reliability with AI-augmented feature roadmaps. Watch FDA 510(k) clearance timelines for algorithm-driven EMG interpretation as inflection signal for competitive repositioning velocity.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Recertification Acceleration | Compresses validation timelines for AI-enhanced EMG platforms against tightening predicate-device equivalence standards. |
| EU MDR Technical Documentation Investment | Establishes conformity assessment capabilities that filter marginal suppliers and consolidate procurement decisions. |
| Third-Party Neurophysiology Staffing Partnership | Captures recurring service revenue streams disintermediated from traditional OEM equipment-disposable bundles. |
| Portable Monitor Platform Launch | Penetrates ambulatory surgical center demand in Germany and Japan with battery-operated, compact form factors. |
| Algorithm-Driven Artifact Detection Development | Decomposes threshold-based alarm systems into probabilistic risk scoring that reduces technologist interpretation burden. |
Methodological Framework
Cross-validation between primary interviews with hospital purchasing committee members, biomedical engineers, and neurophysiology technologists and secondary sources including FDA 510(k) clearance databases, EU MDR technical documentation registries, and hospital procurement contract disclosures anchors the qualitative findings. Bottom-up triangulation against top-down spending estimates from GPO contract values and capital equipment depreciation schedules validates volume assumptions. Stakeholder consultations spanned academic medical centers in Boston, Texas, and California; tertiary surgical centers in Bavaria and North Rhine-Westphalia; and university hospitals in Tokyo and Osaka.
Sensitivity analysis around equipment refresh cycle timing, AI feature adoption curves, and regulatory validation duration informs the analytical framework across the projection horizon. Segmentation dimensions modeled include device type, application category, end-user tier, and technology maturity gradient. CAGRs derive from procedure volume growth rates, reimbursement framework evolution, and replacement demand elasticity. Industry-specific inputs incorporate neurosurgical and spinal deformity correction volume forecasts, neurophysiology technologist supply constraints, and EU MDR transition timeline uncertainty.
Decision-makers should treat outputs as directional under assumptions of steady hospital capital expenditure recovery and stable FDA 510(k) predicate-device pathway availability; material deviation in reimbursement-linked outcome metrics or regulatory validation requirements would warrant model refresh. Specific risk factors include persistent technologist shortages capping utilization, AI algorithm clinical validation failures, and EU MDR notified body capacity constraints. Recalibration cycles align with material shifts in hospital procurement committee composition, regulatory pathway modifications, and AI feature commercialization velocity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Vein Illuminator Market
Medical Devices
Digital Stethoscope Market
Medical Devices
Global Prosthetics Market
Medical Devices
Global Bone Cement Delivery System Market
Medical Devices
Global Digital Pathology Systems Market
Medical Devices
Prosthetic Liners Market
Medical Devices
Cough Assist Devices Market
Medical Devices
Spine Surgery Robots Market
Medical Devices
Tissue Sectioning Market
Medical Devices
Biodegradable Stents Market
Medical Devices
US Pulse Oximeters Market
Medical Devices
Posture Correction Market
Medical Devices
China Aesthetic Devices Market
Medical Devices
Interatrial Shunt Devices Market
Medical Devices
France Contraceptive Devices Market
Medical Devices
Electrical Stimulation Devices (Esds) Market