
 Global Smart Contact Lenses Market | 2026-2036
Global Smart Contact Lenses Market Size, Share, and Industry Trends Forecast 2026-2036
Global Smart Contact Lenses Market Foresight
The EU Medical Device Regulation is decoupling market access from legacy CE certifications for smart contact lenses, forcing manufacturers to rebuild clinical evidence packages. Mojo Vision anchors its position through extreme miniaturization of microLED displays for augmented reality applications. Johnson & Johnson leverages its established optometry distribution channels to sustain reach across professional fitting networks. Samsung Electronics competes by integrating wireless communication protocols from its broader consumer electronics ecosystem.
Smart contact lenses are wearable ocular devices incorporating microelectronics, biocompatible polymers, and wireless communication systems directly onto or within a hydrogel or silicone hydrogel substrate, designed to provide real-time physiological monitoring, vision enhancement, or digital information overlay. These devices typically measure 14–16 millimeters in diameter with center thickness below 0.1 millimeter to maintain oxygen permeability and corneal health during extended wear. Sensor embedded lenses command the highest R&D investment intensity due to their regulatory complexity and clinical validation requirements for continuous biomarker detection. Augmented reality integration represents the fastest-growing product category as microdisplay efficiency improves and power consumption thresholds decline.
The FDA maintains stringent premarket approval pathways for smart contact lenses under its ophthalmic device framework, while the EU MDR mandates notified body oversight and post-market surveillance for all active implantable variants. ISO 10993 biocompatibility standards and IEC 60601 electrical safety requirements shape material selection and wireless power transmission architectures across all commercial development programs. Stakeholders must monitor how regulatory divergence between the FDA and EMA on software-as-a-medical-device classification affects cross-border commercialization timelines and clinical trial design.
Market Dynamics
MicroLED display miniaturization is compressing power budgets below 1 milliwatt per square millimeter, enabling all-day augmented reality wear without external battery packs tethered to spectacle frames.
Growth Catalysts
- FDA Breakthrough Device Designation:The FDA ophthalmic device framework accelerates clinical validation timelines for continuous glucose monitoring lenses, compressing premarket approval cycles for sensor-embedded variants targeting diabetic populations.
- Continuous Biomarker Detection:Electrochemical sensors fabricated onto silicone hydrogel substrates enable real-time tear fluid analysis for lactate, cortisol, and glucose, opening chronic disease management applications beyond ophthalmology.
- South Korea:The MFDS fast-track pathway for wearable medical devices attracts R&D investment into wireless power transmission architectures, with Seoul-based clusters specializing in RF harvesting circuits for ocular electronics.
Market Restraints
- Indium Gallium Arsenide Shortages:MicroLED epitaxy relies on constrained III-V semiconductor supply chains concentrated in Taiwan and China, creating input cost volatility for display-integrated lens programs.
- EU MDR Recertification Burden:The Medical Device Regulation's stricter biocompatibility evidence requirements for active implantable devices force manufacturers to rebuild clinical packages, extending notified body review timelines.
- Corneal Oxygen Deprivation Limits:Center thickness constraints below 0.1 millimeter restrict sensor density and battery integration, capping functionality for extended-wear continuous monitoring applications.
Strategic Opportunities
- India:The CDSCO's emerging framework for software-as-a-medical-device classification creates first-mover advantage for glucose monitoring lenses targeting 77 million diabetic patients with limited access to finger-prick diagnostics.
- AR-Assisted Surgical Navigation:Convergence of microLED overlays with intraoperative imaging systems enables real-time anatomical guidance for cataract and refractive procedures, displacing head-mounted surgical loupes.
- Teleoptometry Distribution:Remote fitting platforms bypass traditional optometry chains, reaching rural populations through smartphone-connected lens calibration and prescription verification protocols.
Industry Challenges
- Biomedical MEMS Fabrication Talent:Cleanroom process engineering for 14-millimeter diameter flexible substrates requires rare cross-training in semiconductor lithography and ocular polymer science, constraining manufacturing scale-up.
- IEC 60601-1-2 Electromagnetic Compatibility:Wireless power transmission at 13.56 MHz must demonstrate immunity to MRI fields and cellular interference, extending certification timelines for multi-market submissions.
- Legacy Electronic Health Record Integration:Continuous biomarker data streams lack standardized APIs for Epic and Cerner systems, forcing custom middleware development for hospital system adoption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Smart Contact Lenses Market |
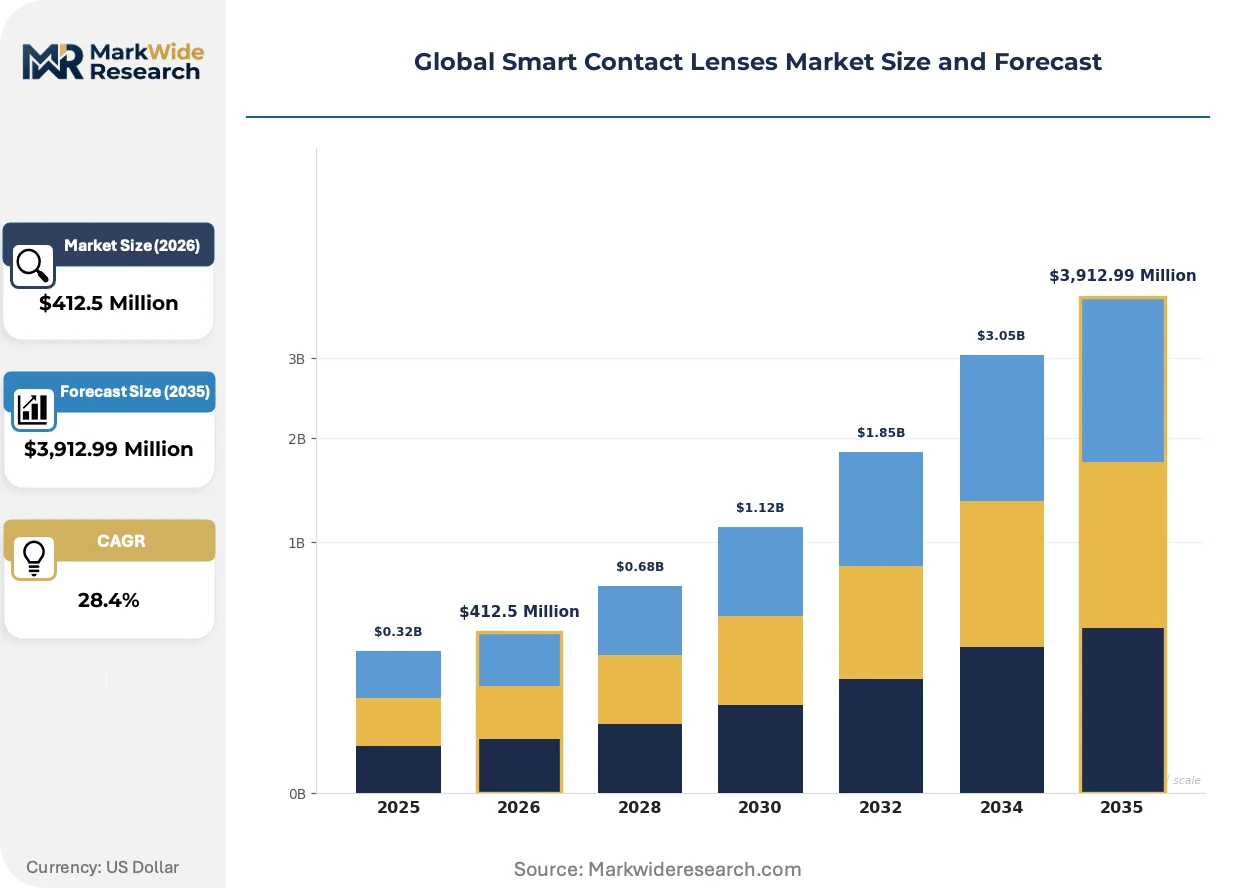
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $3,912.99 Million |
| CAGR (2026 – 2036) | 28.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Display Enabled, Sensor Embedded, Drug Delivery, Vision Enhancement, Augmented Reality Integration Technology: Microelectronics, Wireless Communication, Biocompatible Polymers, Nanotechnology, Energy Harvesting Use Case: Health Monitoring, Glucose Tracking, Eye Disease Detection, Sports Performance, Virtual Assistance End User: Optometrists, Medical Researchers, Consumer Electronics, Sports Professionals, Academic Institutions |
| Companies Covered | Mojo Vision, Johnson & Johnson, Sensimed, Innovega Inc., Alcon, Samsung Electronics, Sony Corporation, Google, InWith Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Smart Contact Lenses Market Shifts & Advancements
Power harvesting architectures and display efficiency curves are converging to enable standalone ocular computing platforms without tethered battery packs or smartphone dependencies.
MicroLED arrays with sub-micron pixel pitch are consolidating augmented reality functionality into standalone contact lens form factors. Medical device manufacturers adopting these displays for surgical navigation overlays are compressing product development cycles from five years to eighteen months. The technology is consolidating previously separate spectacle-mounted and head-worn AR systems into invisible, prescription-compatible platforms.
The EU MDR's post-market surveillance requirements for active implantable devices mandate annual safety reporting and biocompatibility reassessment. Manufacturers must maintain notified body relationships across multiple member states, increasing regulatory affairs headcount by forty percent for CE-marked lens programs. Sensor-embedded therapeutic lenses face the steepest compliance burden, with Germany's BfArM interpreting software updates as design changes requiring resubmission.
Hospital procurement departments are unbundling device acquisition from fitting service contracts, driving price transparency for lens hardware versus professional fees. Academic medical centers in Massachusetts and California now source sensor-embedded lenses through group purchasing organizations, displacing direct manufacturer relationships with optometry networks. This shift concentrates volume with distributors capable of inventory management across multiple FDA product codes.
Global Smart Contact Lenses Market Segmentation
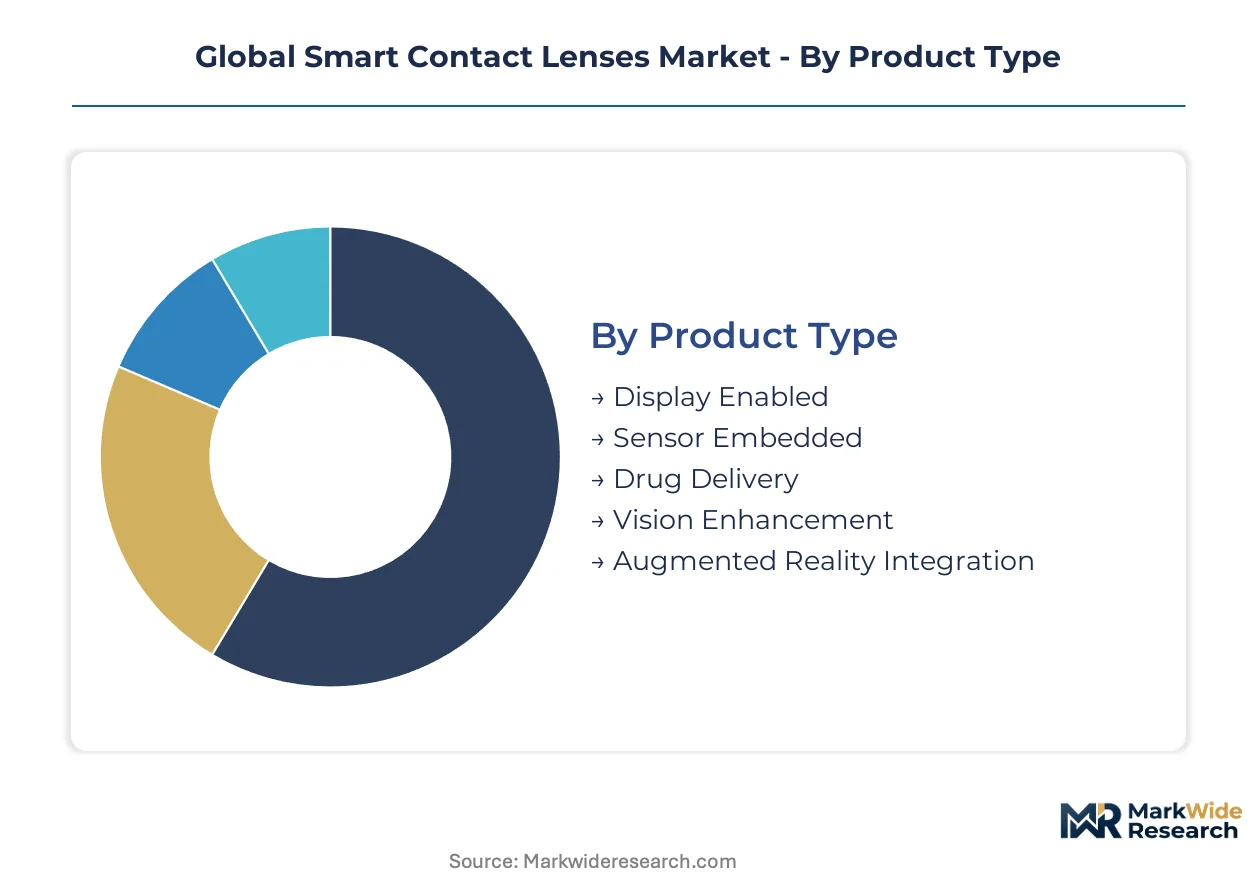
Smart contact lenses fragment across functional architectures that trade off clinical validation burden against consumer electronics scalability. Product type and technology choices determine regulatory pathway, manufacturing complexity, and margin structure. Understanding where volume concentrates versus where premium pricing holds reveals strategic positioning opportunities.
Product Type:
Display-enabled variants dominate premium positioning while sensor-embedded lenses capture chronic disease management volume.
- Display Enabled:MicroLED arrays with sub-micron pixel pitch project digital overlays directly onto the retina without external optics. Demand clusters among Massachusetts and California academic medical centers piloting surgical navigation applications where hands-free anatomical guidance displaces head-mounted loupes.
- Sensor Embedded:Electrochemical sensors fabricated onto silicone hydrogel substrates enable continuous tear fluid biomarker detection. Glucose monitoring applications in India target 77 million diabetic patients with limited finger-prick diagnostic access, driving the steepest volume expansion trajectory.
- Drug Delivery:Hydrogel matrices incorporate therapeutic compounds for timed ocular surface release. Glaucoma management programs in Germany's BfArM jurisdiction emphasize post-market surveillance for active implantable variants with resubmission requirements for formulation updates.
- Vision Enhancement:Tunable liquid crystal layers correct refractive errors dynamically. Seoul-based R&D clusters specialize in RF harvesting circuits supporting prescription-compatible platforms without tethered power.
- Augmented Reality Integration:Converged microdisplay and sensor architectures enable contextual information overlay. South Korea's MFDS fast-track pathway accelerates wearable medical device commercialization timelines.
Today's leader: Sensor Embedded. Tomorrow's challenger: Augmented Reality Integration.
Technology:
Wireless power transmission and biocompatible material science separate clinically viable platforms from prototype-stage concepts.
- Microelectronics:Biomedical MEMS fabrication at 14-millimeter diameter requires rare cross-training in semiconductor lithography and ocular polymer science. Cleanroom process engineering constraints limit manufacturing scale-up for flexible substrate production.
- Wireless Communication:Protocols operating at 13.56 MHz must demonstrate IEC 60601-1-2 electromagnetic compatibility immunity to MRI fields and cellular interference. Samsung Electronics leverages its consumer electronics ecosystem for integrated RF architectures.
- Biocompatible Polymers:Hydrogel and silicone hydrogel substrates must maintain center thickness below 0.1 millimeter to preserve corneal oxygen permeability. ISO 10993 standards shape material selection across all FDA and EU MDR development programs.
- Nanotechnology:Sub-micron feature fabrication enables sensor density improvements within oxygen deprivation constraints. Taiwan and China concentrate III-V semiconductor supply chains for microLED epitaxy.
- Energy Harvesting:RF harvesting circuits and photovoltaic integration aim to eliminate external battery packs. Seoul-based clusters lead development of standalone ocular computing platforms.
Wireless Communication anchors current revenue. Energy Harvesting unlocks standalone form factors.
Use Case:
Chronic disease management applications command regulatory investment while consumer-facing functions scale faster through electronics channels.
- Health Monitoring:Continuous biomarker streams for lactate, cortisol, and glucose require custom middleware for Epic and Cerner electronic health record integration. Hospital procurement departments unbundle device acquisition from fitting service contracts.
- Glucose Tracking:Electrochemical tear fluid analysis targets diabetic populations with FDA breakthrough device designation accelerating premarket approval cycles. The CDSCO's emerging software-as-a-medical-device framework in India creates first-mover positioning.
- Eye Disease Detection:Intraocular pressure and biomarker sensing for glaucoma progression monitoring. Germany's BfArM interprets software updates as design changes requiring notified body resubmission.
- Sports Performance:Real-time physiological feedback for hydration and exertion metrics. Consumer electronics distribution channels bypass traditional optometry fitting networks.
- Virtual Assistance:Contextual information overlay for navigation and communication. MicroLED efficiency improvements compress power budgets below 1 milliwatt per square millimeter.
Glucose Tracking commands R&D investment intensity. Sports Performance scales through consumer channels.
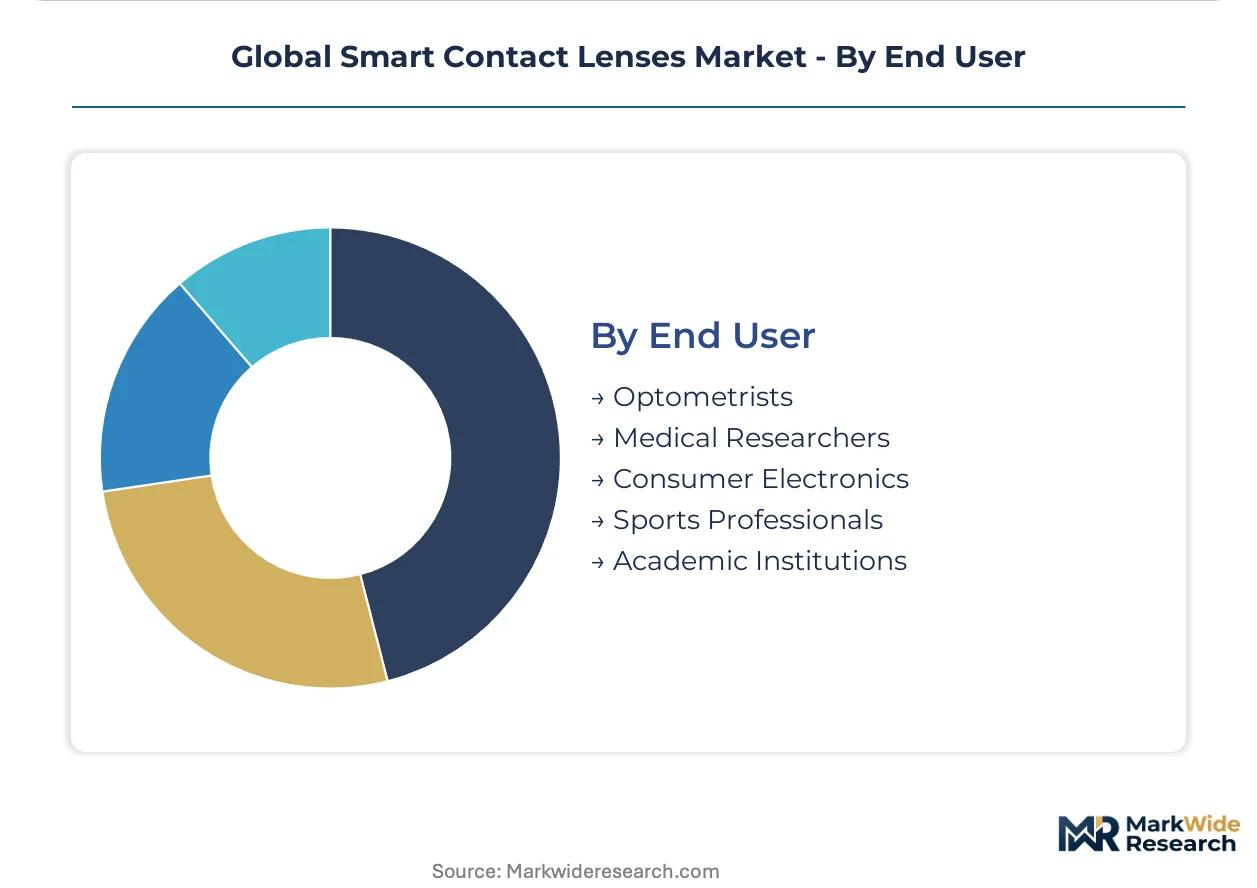
End User:
Professional fitting networks retain clinical applications while direct-to-consumer platforms emerge for wellness and performance segments.
- Optometrists:Traditional prescription verification and lens fitting services face displacement from smartphone-connected remote calibration platforms. Johnson & Johnson sustains reach through established professional distribution channels.
- Medical Researchers:Clinical validation studies for continuous glucose monitoring drive FDA breakthrough device pipeline volume. Massachusetts and California academic medical centers source through group purchasing organizations.
- Consumer Electronics:Wellness and performance applications bypass medical device regulatory pathways. Teleoptometry platforms reach rural populations through prescription verification protocols.
- Sports Professionals:Real-time biometric feedback for training optimization. Mojo Vision anchors positioning through extreme microLED miniaturization for invisible AR platforms.
- Academic Institutions:Surgical navigation pilot programs in cataract and refractive procedures. AR-assisted overlays displace head-mounted surgical loupes in teaching hospitals.
Medical Researchers validate clinical claims. Consumer Electronics capture scale economics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The smart contact lens industry traces its commercial origins to Swiss and Californian research clusters that pioneered electrochemical sensing on hydrogel substrates. Early FDA breakthrough designations in Massachusetts established the regulatory template now replicated worldwide.
United States
Massachusetts and California academic medical centers drive surgical navigation pilots for microLED-enabled lenses. The FDA's ophthalmic device framework accelerates premarket approval cycles for continuous glucose monitoring variants. Greater Boston hosts the densest concentration of biomedical MEMS fabrication facilities for flexible substrate production.
Germany
Germany's BfArM interprets software updates as design changes requiring notified body resubmission for active implantable lenses. The EU MDR's post-market surveillance mandates annual safety reporting and biocompatibility reassessment. Berlin-Brandenburg clusters specialize in cleanroom process engineering for 14-millimeter diameter ocular electronics.
South Korea
Seoul-based R&D clusters lead RF harvesting circuit development for standalone ocular computing platforms. The MFDS fast-track pathway for wearable medical devices attracts investment into wireless power transmission architectures. The capital region concentrates III-V semiconductor supply chain integration for microLED epitaxy.
India
India's 77 million diabetic patients drive demand for glucose monitoring lenses with limited finger-prick diagnostic access. The CDSCO's emerging software-as-a-medical-device framework creates first-mover positioning for sensor-embedded variants. Maharashtra and Karnataka host teleoptometry platforms reaching rural populations through smartphone-connected calibration.
Switzerland
Swissmedic maintains stringent oversight of ocular implantable devices alongside EU MDR alignment for CE-marked products. Geneva and Basel clusters pioneered electrochemical tear fluid analysis for continuous biomarker detection. The country's pharmaceutical heritage supports specialized polymer science for oxygen-permeable hydrogel matrices.
Global Smart Contact Lenses Market Competitive Landscape
Premium-margin players sit above commodity-margin players across regulatory validation intensity and clinical evidence depth. The vendor base stratifies between medical device incumbents with established optometry distribution and consumer electronics entrants with wireless communication expertise. Three archetypes dominate: sensor-embedded therapeutic specialists, augmented reality microdisplay pioneers, and diversified healthcare conglomerates leveraging professional fitting networks. Competitive moves concentrate on strategic partnerships for cleanroom fabrication capacity and technology licensing for biocompatible polymer IP.
Within the diversified healthcare tier, Johnson & Johnson and Alcon occupy positions anchored by established professional distribution channels. Samsung Electronics exemplifies the consumer electronics archetype with integrated RF architecture capabilities. Mojo Vision represents the microLED miniaturization specialist segment focused on augmented reality applications.
| Leading Market Players |
|---|
| Mojo Vision |
| Johnson & Johnson |
| Sensimed |
| Innovega Inc. |
| Alcon |
| Samsung Electronics |
| Sony Corporation |
| InWith Corporation |
| Others |
Supply & Pricing Matrix
Backward integration into III-V semiconductor epitaxy anchors supply position for microLED-integrated lens programs while compressing input cost volatility. Captive control over Taiwan and South Korea-based foundry relationships simultaneously insulates margin structures from indium gallium arsenide spot market fluctuations and enables premium-tier pricing for augmented reality variants.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates FDA breakthrough-designated glucose monitoring lenses from CE-marked wellness variants and unregulated consumer AR prototypes. Price differentiation hinges on ISO 10993 biocompatibility certification grade and clinical validation depth, with hospital procurement via group purchasing organizations driving cost compression in the sensor-embedded therapeutic tier. Academic medical centers in Massachusetts exhibit lowest price sensitivity due to reimbursement capture, while Indian teleoptometry platforms face acute margin pressure from smartphone-connected calibration commoditization.
Supply Chain Analysis
Direct-to-hospital channels handle FDA-cleared therapeutic demand, while consumer electronics distributors manage wellness and performance SKUs. Manufacturing concentrates in Taiwan for microLED epitaxy, South Korea for RF harvesting circuit fabrication, and Switzerland for hydrogel polymer science. Raw material dependencies include indium phosphide substrates, silicone hydrogel monomers, and biomedical-grade parylene coatings. Single-source vulnerability in III-V semiconductor supply chains concentrated across East Asian foundries creates tariff exposure and geopolitical disruption risk.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in this market rests on microLED efficiency curves compressing power budgets below 1 milliwatt per square millimeter, enabling standalone form factors that command premium positioning without tethered battery costs.
For Market Incumbents: Deploy certification stacking across FDA breakthrough device and EU MDR active implantable pathways to erect regulatory moats against consumer electronics entrants. Deepen captive supply of biomedical MEMS fabrication capacity in Greater Boston clusters to defend against Samsung Electronics' RF architecture integration threat. Channel control through professional optometry networks remains the critical lever for sensor-embedded therapeutic segments. For New Entrants and Emerging Players: CDSCO's emerging software-as-a-medical-device framework in India opens a window for glucose monitoring lenses targeting 77 million diabetic patients with limited finger-prick access. White-space concentration exists in rural teleoptometry distribution and sports performance biometric feedback. A direct-to-consumer go-to-market angle through smartphone-connected calibration bypasses entrenched professional fitting networks. For Investors and Strategic Acquirers: Roll-up economics work for biomedical MEMS fabrication specialists because cleanroom process engineering for 14-millimeter diameter flexible substrates requires rare cross-training that constrains manufacturing scale-up. Long-term viability favors platform consolidation around standalone ocular computing architectures with energy harvesting integration. Watch MFDS fast-track pathway utilization rates as inflection signal for South Korean R&D cluster maturity.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Designation | Accelerates premarket approval cycles for glucose monitoring variants targeting diabetic populations. |
| EU MDR Active Implantable Recertification | Forces clinical evidence package rebuilds that concentrate volume with notified body relationship holders. |
| MicroLED Display Miniaturization | Compresses power budgets below 1 milliwatt per square millimeter for standalone AR form factors. |
| Teleoptometry Platform Development | Bypasses traditional optometry chains to reach rural populations through smartphone-connected calibration. |
| RF Harvesting Circuit Integration | Enables wireless power transmission architectures without external battery packs tethered to spectacle frames. |
Research Methodology
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region's regulatory cluster and manufacturing hub. The analysis combines interviews with biomedical MEMS process engineers, FDA regulatory affairs leads, hospital GPO contracts managers, and teleoptometry platform developers with secondary validation from FDA 510(k) filings, EU MDR notified body documentation, MFDS fast-track pathway records, and ISO 10993 biocompatibility test reports. Bottom-up demand modeling and top-down supply capacity estimates undergo triangulation across multiple data streams.
Rate-of-change decomposition separates volume expansion from value-per-unit shifts across the projection horizon. The analytical framework models product type segmentation across sensor-embedded, display-enabled, and augmented reality integration variants; technology segmentation spanning microelectronics, wireless communication, and energy harvesting architectures; and use case segmentation across glucose tracking, surgical navigation, and sports performance applications. CAGRs derive from installed base penetration curves and replacement cycle assumptions for ocular electronics.
Revisions become necessary when EU MDR software-as-design-change interpretations harden, III-V semiconductor supply chain disruptions materialize, or corneal oxygen deprivation limits tighten below current 0.1 millimeter center thickness thresholds. Forecasts reflect assumptions about regulatory pathway stability, microLED efficiency improvement trajectories, and wireless power transmission safety clearance timelines. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Bowel Irrigation System Market
Medical Devices
Microdebrider Market
Medical Devices
Bioimpedance Spectroscopy Market
Medical Devices
Global Stabilometric Platform Market
Medical Devices
Global Implantable Drug Delivery Market
Medical Devices
Implantable Drug Eluting Devices Market
Medical Devices
Medical Device Technologies Market
Medical Devices
Ultrasonic Skin Care Devices Market
Medical Devices
Brazil Medical Devices Market
Medical Devices
Liposuction Devices Market
Medical Devices
Needle Destroyer Market
Medical Devices
Global Insufflation Devices Market
Medical Devices
Robotic Catheterization Systems Market
Medical Devices
Global Esophageal Catheters Market
Medical Devices
Anesthesia Face Masks Market
Medical Devices
IOL Delivery Systems Market