
 Smart Pills Drug Delivery Market | 2026-2036
Smart Pills Drug Delivery Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Pills Drug Delivery Market Outlook
Class IIb and Class III device certification tiers is collapsing the competitive field toward firms with validated quality management systems. Medtronic leverages its end-to-end gastrointestinal platform to anchor hospital procurement decisions. CapsoVision specializes in capsule endoscopy visualization while Proteus Digital Health competes through sensor-enabled medication adherence programs.
Smart pills drug delivery encompasses ingestible electronic devices combining pharmaceutical payloads with biosensors, telemetry modules, and polymeric encapsulation systems engineered for targeted GI tract release. These systems enable real-time pharmacokinetic monitoring and automated dose modulation for chronic disease management. Capsule-based platforms with wireless monitoring capabilities currently dominate installed bases while sensor integration segments capture expanding margin pools from remote patient monitoring contracts. Biologics-compatible microchip architectures represent the fastest-growing product category as peptide and nucleotide therapies require precision release kinetics.
FDA 510(k) and PMA pathways govern US market access while EMA Medical Device Regulation frameworks enforce clinical evidence standards across European member states. Japan's PMDA pharmaceutical affairs law creates additional conformance requirements for combination drug-device filings. Stakeholders must monitor evolving reimbursement codes for digital therapeutics and decide whether to pursue parallel regulatory submissions or sequential geographic rollouts.
Market Dynamics
Biologics-compatible microchip architectures are compressing development timelines for peptide and nucleotide therapies while FDA breakthrough device designations accelerate regulatory clearance pathways for ingestible sensor platforms.
Growth Catalysts
- EMA Adaptive Pathways:The European Medicines Agency's accelerated assessment framework compresses review timelines for combination drug-device products, enabling faster commercialization of sensor-enabled capsules across EU member states.
- Gastroenterology Department Expansion:Academic medical centers in the United States, Germany, and Japan are institutionalizing smart pill protocols for inflammatory bowel disease monitoring, creating dedicated reimbursement codes for digital therapeutics.
- Polymeric Encapsulation Advances:Targeted GI tract release systems now achieve precision pharmacokinetic profiles previously unattainable with conventional oral formulations, expanding addressable therapeutic categories.
Market Restraints
- Class IIb and III Certification Concentration:Quality management system validation requirements collapse the competitive field toward established medical device manufacturers with multi-year clinical evidence portfolios.
- Reimbursement Framework Immaturity:Outside the United States, Germany, and Japan, national health technology assessment bodies lack established valuation methodologies for ingestible digital therapeutics.
- Biologics Stability Constraints:Temperature-sensitive peptide payloads degrade during manufacturing and storage, limiting viable therapeutic classes for microchip-based delivery systems.
Strategic Opportunities
- India's CDSCO Combination Product Pathway:The Central Drugs Standard Control Organization's emerging regulatory framework for drug-device combinations creates first-mover positioning in a large underserved chronic disease market.
- Remote Patient Monitoring Contracts:Telemetry-enabled capsules capture expanding margin pools through value-based care arrangements with integrated delivery networks seeking hospital-at-home alternatives.
- Wireless Power Harvesting Convergence:Integration of near-field communication with biosensor arrays enables real-time dose modulation without battery-dependent architectures, reducing device footprint constraints.
Industry Challenges
- ISO 13485 Quality Management Talent Scarcity:Medical device software validation expertise concentrates in established hubs, constraining scaling for emerging platform developers.
- PMA Supplement Timeline Uncertainty:FDA premarket approval pathway modifications for sensor firmware updates create unpredictable certification cycles that disrupt product roadmap planning.
- Legacy EHR Integration Complexity:Ingestible device data streams require custom API development for integration with hospital information systems, extending implementation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Pills Drug Delivery Market |
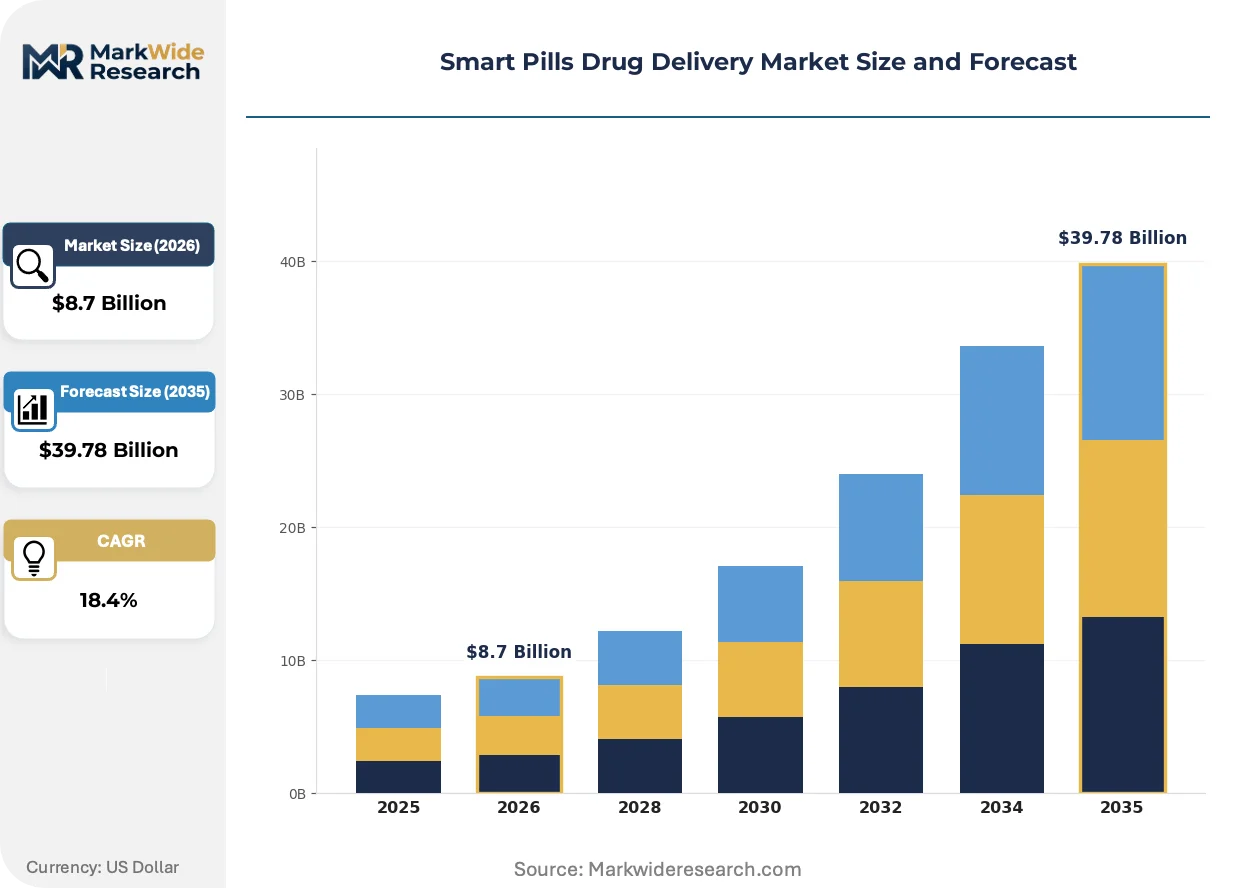
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $39.78 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Capsules, Tablets, Biologics, Microchips Delivery Mode: Oral, Rectal, Sublingual, Transdermal End User: Hospitals, Homecare, Clinics, Research Institutions Technology: Wireless Monitoring, Sensor Integration, Drug Implants, IoT Connectivity |
| Companies Covered | Medtronic, Jinshan Science and Technology, CapsoVision, Proteus Digital Health, etectRx, Philips, Olympus, IntroMedic, Otsuka Pharmaceutical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Pills Drug Delivery Market Strategic Shifts
Wireless telemetry modules are fragmenting traditional gastrointestinal diagnostic workflows while polymeric encapsulation systems enable therapeutic categories previously confined to parenteral administration.
Biologics-compatible microchip architectures are fragmenting the chronic disease management landscape. These systems combine pharmaceutical payloads with real-time biosensing capabilities for automated dose modulation. Gastroenterology departments at academic medical centers are adopting these platforms for inflammatory bowel disease monitoring at accelerating pace. The technology is fragmenting conventional endoscopy referral patterns and creating new remote therapeutic monitoring revenue streams.
EMA Medical Device Regulation frameworks enforce clinical evidence standards across European member states while FDA 510(k) and PMA pathways govern US market access. Japan's PMDA pharmaceutical affairs law creates additional conformance requirements for combination drug-device filings. Stakeholders must monitor evolving reimbursement codes for digital therapeutics and decide whether to pursue parallel regulatory submissions or sequential geographic rollouts. The sensor integration segment faces the steepest compliance burden.
Hospital procurement committees now require end-to-end platform compatibility before committing to smart pill protocols. Integrated delivery networks are displacing standalone device vendors in favor of comprehensive gastrointestinal platform providers with validated quality management systems. This concentration is most visible in the United States where reimbursement frameworks for digital therapeutics are maturing fastest and procurement authority centralizes within value-based care organizations.
Smart Pills Drug Delivery Market Segmentation
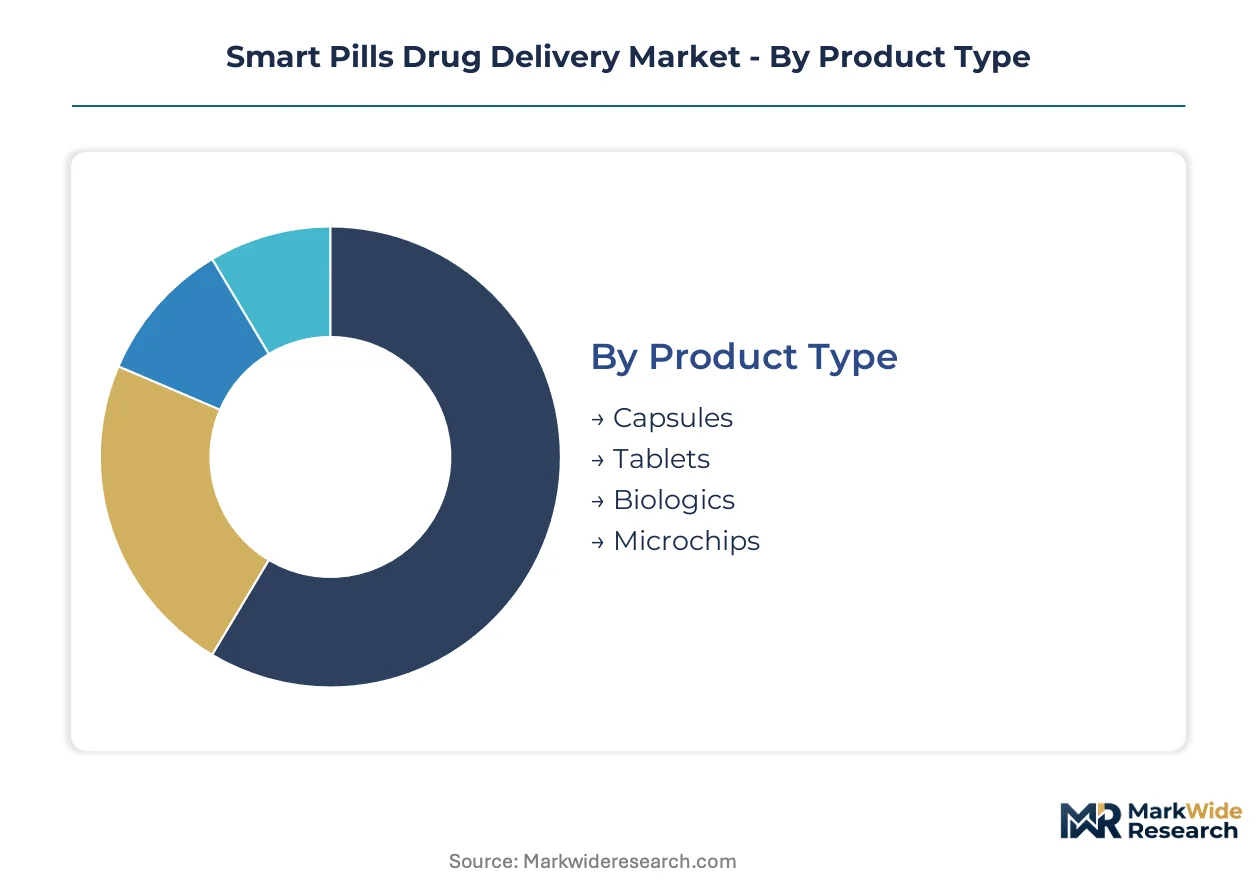
Smart pills drug delivery segmentation reveals distinct procurement patterns across product architectures, administration routes, and care settings. Each dimension carries specific regulatory pathways and reimbursement implications that reshape vendor competitive positioning.
Product Type:
Capsule-based platforms dominate domestic hospital procurement in the United States and Japan, while tablet and microchip formats see stronger export-led demand into European and emerging markets.
- Capsules:Polymeric encapsulation systems enable targeted GI tract release with integrated biosensor arrays. United States academic medical centers anchor procurement volumes through dedicated inflammatory bowel disease monitoring protocols.
- Tablets:Conventional oral form factors incorporate telemetry modules for real-time pharmacokinetic tracking. German hospital networks concentrate demand through value-based care arrangements requiring EHR-compatible data streams.
- Biologics:Peptide and nucleotide payloads require precision release kinetics from temperature-stabilized architectures.
- Microchips:Biologics-compatible architectures fragment chronic disease management with automated dose modulation capabilities.
Capsules hold the largest share; momentum sits with microchips as peptide therapy pipelines expand.
Delivery Mode:
Oral administration captures premium pricing tiers through FDA PMA pathway investments, while rectal and sublingual routes serve cost-sensitive segments with faster 510(k) clearance cycles.
- Oral:Ingestible electronic devices combine pharmaceutical payloads with wireless telemetry for hospital-at-home alternatives. United States integrated delivery networks concentrate procurement through remote patient monitoring contracts.
- Rectal:Targeted colonic release systems address inflammatory bowel disease flares with localized therapeutic action. Japanese gastroenterology departments anchor regional demand through PMDA combination product approvals.
- Sublingual:Rapid absorption profiles bypass first-pass metabolism for emergency therapeutic categories.
- Transdermal:Patch-based alternatives compete for patient adherence in chronic disease management.
Oral delivery commands the installed base; sublingual formats are climbing the fastest as emergency medicine protocols expand.
End User:
Hospital procurement centralizes within value-based care organizations in mature reimbursement markets, while homecare segments fragment across direct-to-consumer channels and remote monitoring service providers.
- Hospitals:Academic medical centers institutionalize smart pill protocols with dedicated digital therapeutics reimbursement codes. Germany's EMA adaptive pathway beneficiaries anchor European procurement concentration.
- Homecare:Telemetry-enabled capsules capture margin pools through hospital-at-home alternatives. United States Medicare Advantage plans drive demand concentration for aging-in-place therapeutic monitoring.
- Clinics:Outpatient gastroenterology practices adopt capsule endoscopy for diagnostic workflow fragmentation.
- Research Institutions:Clinical trial sponsors leverage real-time biosensing for adaptive study designs.
Hospitals retain the dominant procurement volume; homecare is gaining share fastest as reimbursement frameworks for digital therapeutics mature.
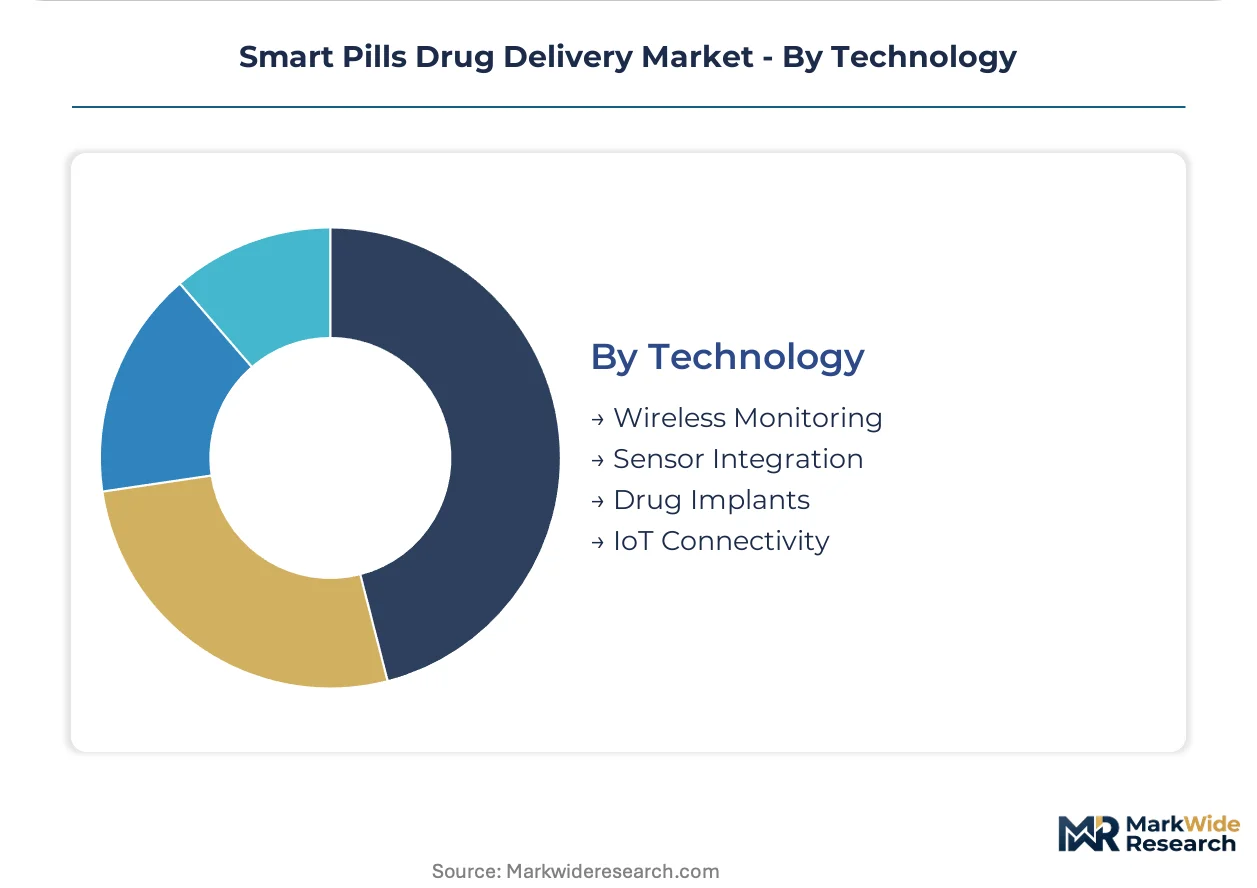
Technology:
Wireless monitoring and sensor integration segments concentrate in Class IIb and III certification tiers, while IoT connectivity platforms fragment across software-as-a-service revenue models.
- Wireless Monitoring:Near-field communication modules enable real-time dose modulation without battery-dependent architectures. Japanese PMDA pharmaceutical affairs law creates conformance requirements for telemetry-enabled combination products.
- Sensor Integration:Biosensor arrays with automated pharmacokinetic feedback compress development timelines for chronic disease management. FDA breakthrough device designations accelerate clearance pathways for ingestible sensor platforms.
- Drug Implants:Long-acting depot formulations compete for adherence-critical therapeutic categories.
- IoT Connectivity:Cloud-based data streams require custom API development for legacy EHR integration.
Wireless monitoring dominates current installed bases; sensor integration shows the steepest expansion trajectory as value-based care contracts proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing capacity for ingestible sensor platforms clusters around established medical device hubs with validated quality management systems. FDA, EMA, and PMDA regulatory frameworks create divergent certification requirements that reshape geographic expansion strategies. Demand concentrates where reimbursement codes for digital therapeutics have achieved institutional recognition.
United States
Academic medical centers in Boston, Cleveland, and Rochester anchor hospital procurement for inflammatory bowel disease monitoring protocols. FDA breakthrough device designations and PMA pathway investments compress clearance timelines for sensor-enabled capsules. Medicare Advantage plans in Florida and Arizona drive homecare segment expansion through hospital-at-home reimbursement structures.
Germany
University hospital networks in Munich, Heidelberg, and Berlin institutionalize smart pill protocols through EMA adaptive pathway beneficiaries. The national health technology assessment body evaluates ingestible digital therapeutics under accelerated assessment frameworks. Baden-Württemberg's medical technology corridor concentrates capsule endoscopy manufacturing and quality system validation expertise.
Japan
Gastroenterology departments at Tokyo and Osaka academic medical centers expand PMDA combination product approvals for telemetry-enabled therapeutics. The pharmaceutical affairs law creates conformance requirements for biologics-compatible microchip architectures. Nagoya's precision manufacturing cluster supplies polymeric encapsulation systems for temperature-stabilized peptide payloads.
India
CDSCO's emerging combination product pathway attracts contract manufacturing investment for export-oriented capsule production. Maharashtra's pharmaceutical corridor near Mumbai develops quality management capabilities for Class IIb device certification. Telangana's medical device park in Hyderabad targets first-mover positioning in chronic disease monitoring for underserved populations.
Switzerland
Swissmedic's streamlined device certification attracts R&D headquarters for biologics delivery platforms. Basel's pharmaceutical cluster integrates ingestible sensor development with peptide therapy pipelines. Geneva's health technology assessment expertise shapes European valuation methodologies for remote patient monitoring contracts.
Smart Pills Drug Delivery Market Competitive Environment
Concentration sits with diversified medical technology conglomerates possessing end-to-end gastrointestinal platforms and validated ISO 13485 quality systems. The competitive field collapses toward firms with multi-year clinical evidence portfolios as Class IIb and III certification requirements intensify. Two strategic archetypes dominate: integrated platform providers leveraging hospital procurement relationships, and specialized sensor developers capturing remote monitoring margin pools. Dominant competitive moves include strategic partnerships with integrated delivery networks and technology licensing arrangements for wireless telemetry modules.
Within the integrated platform tier, Medtronic anchors hospital procurement decisions through comprehensive gastrointestinal portfolios. CapsoVision occupies a specialist position in capsule endoscopy visualization systems. Proteus Digital Health exemplifies the sensor-enabled medication adherence archetype through its digital therapeutics positioning. These three firms represent distinct competitive vectors: end-to-end platform dominance, diagnostic visualization specialization, and pharmaceutical adherence integration.
| Leading Market Players |
|---|
| Medtronic |
| Jinshan Science and Technology |
| CapsoVision |
| Proteus Digital Health |
| etectRx |
| Philips |
| Olympus |
| IntroMedic |
| Otsuka Pharmaceutical |
| Others |
Value Chain & Pricing Dynamics
Minimum viable scale for FDA PMA pathway investments sits at 50,000-unit annual throughput, concentrating supply among firms with validated ISO 13485 quality systems and compressing price floors for emerging entrants lacking clinical evidence portfolios.
Pricing Analysis
FDA 510(k) and PMA pathway certification tiers dictate the pricing tier structure across the Smart Pills Drug Delivery Market. Three-tier pricing structure across premium, standard, and economy levels separates Class III PMA-validated platforms from Class IIb 510(k) devices and unvalidated developmental systems. Price differentiation rests on quality management system maturity and EHR integration depth, with United States academic medical centers showing lowest price sensitivity due to dedicated digital therapeutics reimbursement codes. Cost compression in the standard tier is intensifying because CDSCO pathway entrants from India are flooding export markets with lower-cost capsule platforms.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes are elevating inbound logistics costs for polymeric encapsulation raw materials sourced from Japanese and German specialty chemical suppliers. Manufacturing capacity concentrates in the United States, Japan, and Germany, with Nagoya's precision cluster feeding temperature-stabilized peptide payload architectures and Baden-Württemberg supplying biosensor arrays. Raw material dependencies include medical-grade polymers, telemetry microchips, and biologics-compatible coatings. Single-source vulnerability sits with FDA-certified polymer suppliers in Massachusetts. Distribution runs through integrated delivery network procurement committees rather than open market channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics are shifting toward interoperability mandates as hospital procurement committees require end-to-end EHR compatibility, collapsing standalone device vendor viability in favor of comprehensive gastrointestinal platform providers.
For Market Incumbents: Secure hospital procurement relationships through backward integration into telemetry module manufacturing, eliminating third-party chip supplier dependencies. Deepen quality management system validation investments to maintain Class III PMA certification moats against CDSCO pathway entrants from India. Consolidate position by acquiring specialized sensor developers with FDA breakthrough device designations.
For New Entrants and Emerging Players: Anchor in India's CDSCO combination product pathway for first-mover positioning in chronic disease monitoring for underserved populations. Target homecare segments through direct-to-consumer remote patient monitoring contracts with Medicare Advantage plans. Pursue strategic licensing arrangements for wireless power harvesting architectures to bypass battery-dependent design constraints.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among sensor-enabled medication adherence platforms with integrated pharmacy benefit manager contracts. Long-term viability over the projection horizon favors firms with validated biologics-compatible microchip architectures and peptide therapy pipeline partnerships. Target acquisition archetype: specialized capsule endoscopy developers with EMA adaptive pathway approvals. Watch FDA PMA supplement timeline clarity as the inflection signal for platform consolidation velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Designation | Accelerates PMA pathway timelines for ingestible sensor platforms targeting inflammatory bowel disease monitoring. |
| Hospital System Partnership | Locks in procurement volume through value-based care arrangements with integrated delivery networks. |
| Software Companion Development | Enables EHR integration for real-time pharmacokinetic data streams demanded by German hospital networks. |
| Reimbursement Strategy | Secures dedicated digital therapeutics codes from Medicare Advantage plans for hospital-at-home alternatives. |
| CE Marking Pathway | Opens EU market access through EMA adaptive pathways for combination drug-device filings. |
Study Parameters
A standing panel of biomedical engineers, hospital procurement managers, GPO contracts specialists, and regulatory affairs leads provided ongoing calibration across the study period. Primary interviews with these stakeholders combined with secondary validation from FDA 510(k) and PMA filings, EMA adaptive pathway submissions, ClinicalTrials.gov records, and hospital procurement databases. Bottom-up unit economics triangulated against top-down reimbursement code expansion trajectories.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation dimensions modeled include product architecture, delivery mode, end-user setting, and regional regulatory cluster. CAGRs derived from patent filing trajectories, clinical trial enrollment velocities, and reimbursement code adoption curves. Forecast inputs incorporated biologics pipeline expansion rates and wireless telemetry module cost decline curves.
Underlying assumptions cover stable FDA PMA review timelines and sustained Medicare Advantage reimbursement expansion, with deviation risk concentrated in EMA MDR framework enforcement intensity and CDSCO pathway acceleration. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Deep Brain Stimulator Market
Medical Devices
Gastric Bands Market
Medical Devices
Soft Tissue Market
Medical Devices
Mobile Operating Rooms Market
Medical Devices
Spinal Access Systems Market
Medical Devices
Brazil Aesthetic Devices Market
Medical Devices
Electric Heated Eye Mask Market
Medical Devices
Point of Care Ultrasound Systems Market
Medical Devices
Carotid Stents Market
Medical Devices
Europe Intraocular Lens Market
Medical Devices
Medical Bionic Implant/Artificial Organs Market
Medical Devices
Saudi Arabia Minimally Invasive Surgery Devices Market
Medical Devices
Digital Pregnancy Test Kits Market
Medical Devices
Netherlands Aesthetic Devices Market
Medical Devices
Peripheral Guidewires Market
Medical Devices
Continuous Bladder Irrigation Devices Market