
 Mandibular Advancement Devices Market | 2026-2036
Mandibular Advancement Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Mandibular Advancement Devices Market Intelligence
European thermoplastic molding capacity is pivoting toward medical-grade polymer fabrication for mandibular advancement platforms. SomnoMed leverages vertically integrated digital workflows across Australia and Denmark to sustain its position in custom-fitted oral appliances. ProSomnus anchors its competitiveness through proprietary nylon-based 3D printing technology that reduces device profile thickness. ResMed competes through sleep-clinic partnerships that bundle diagnostic services with oral appliance prescriptions.
Mandibular advancement devices are intraoral prostheses that mechanically protrude the mandible to maintain pharyngeal airway patency during sleep, typically fabricated from biocompatible nylon or copolymer resins with titration mechanisms allowing 0.5–1.0 mm incremental adjustments. Custom-fitted devices fabricated from medical-grade nylon command premium positioning due to superior compliance rates and reduced bulk compared to thermoplastic boil-and-bite alternatives. The home care distribution channel exhibits the fastest structural expansion as telehealth-integrated direct-to-consumer models bypass traditional dental gatekeepers. Plastic and silicone materials still occupy the largest volume share, though thermoplastic variants face margin compression from commoditized over-the-counter competition.
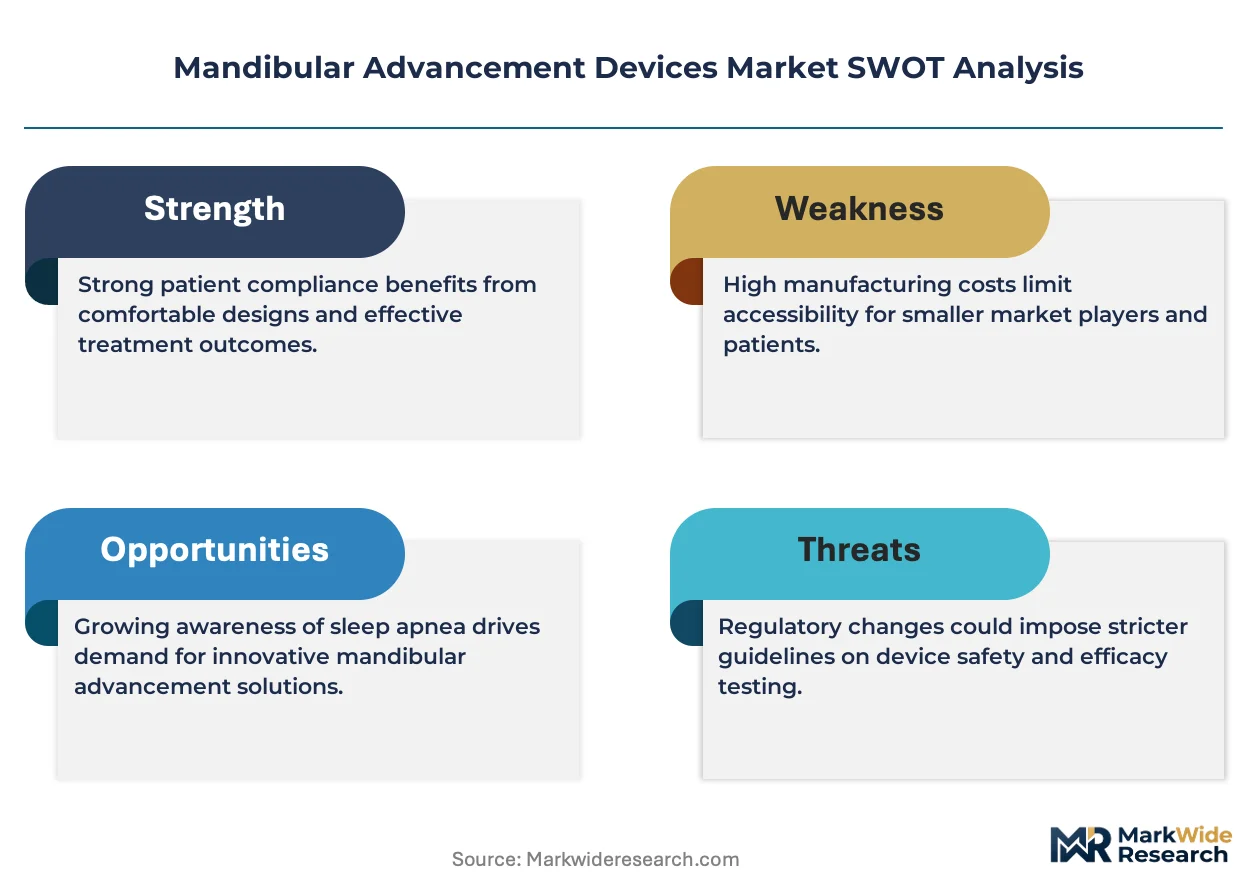
FDA 510(k) premarket notification requirements govern device safety and efficacy claims in the United States, while the EU Medical Device Regulation mandates notified body certification and clinical evidence portfolios for CE-marked products in Europe. Health Canada and TGA Australia impose comparable quality management system standards that filter market entry for non-compliant manufacturers. Stakeholders must monitor reimbursement parity debates between oral appliances and continuous positive airway pressure therapy across public and private payor systems.
Market Dynamics
The mandibular advancement devices market pivots on CMS reimbursement parity debates that determine whether oral appliance therapy achieves cost equivalence with continuous positive airway pressure therapy in obstructive sleep apnea treatment pathways.
Growth Catalysts
- FDA 510(k) pathway streamlining:The premarket notification framework for Class II medical devices accelerates commercialization timelines for novel titration mechanisms and biocompatible materials in the United States.
- Telehealth-integrated direct-to-consumer distribution:Remote dental impression kits and virtual sleep medicine consultations bypass traditional gatekeeper friction, expanding patient access beyond metropolitan sleep-dental networks.
- Home sleep apnea testing proliferation:Diagnostic decentralization from in-lab polysomnography to portable monitoring devices creates downstream prescription volume for oral appliance therapy.
Market Restraints
- Medical-grade nylon supply concentration:Polymer fabrication capacity for thin-profile, biocompatible devices clusters among European thermoplastic molders, exposing manufacturers to input cost volatility and lead time extensions.
- CPAP therapy substitution threat:ResMed and Philips Respironics maintain entrenched sleep-clinic relationships and established insurance reimbursement codes that oral appliances struggle to displace in severe apnea segments.
- EU MDR clinical evidence requirements:The Medical Device Regulation mandates expanded notified body certification portfolios and post-market surveillance systems that compress margins for mid-tier manufacturers.
Strategic Opportunities
- Pediatric and adolescent sleep apnea expansion:Craniofacial growth modification protocols in orthodontic practices represent an underpenetrated indication beyond adult obstructive sleep apnea.
- 3D printing convergence with AI-driven design:Machine learning algorithms optimizing mandibular protrusion vectors and nylon lattice structures enable mass customization at unit economics approaching thermoplastic boil-and-bite alternatives.
- Integrated sleep-dental network consolidation:Vertical acquisition of diagnostic service providers by oral appliance manufacturers captures patient flow from home sleep testing through device fabrication.
Industry Challenges
- Dental sleep medicine certification scarcity:The American Academy of Dental Sleep Medicine credentialing pipeline produces insufficient qualified practitioners to match telehealth-driven patient demand, creating treatment bottlenecks.
- Cross-border reimbursement complexity:Private payor prior authorization requirements and public health system formularies vary substantially across state and provincial boundaries, fragmenting commercial execution.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mandibular Advancement Devices Market |
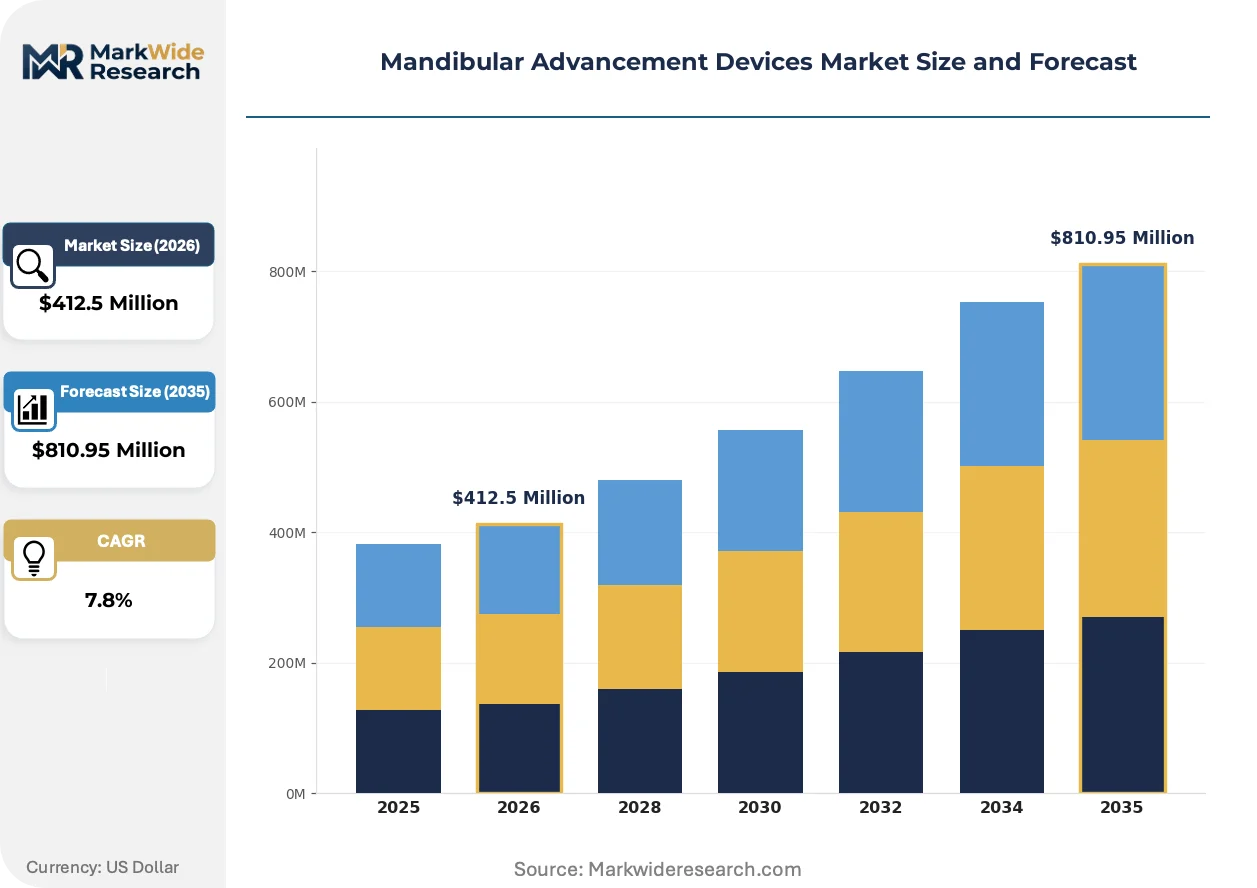
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $810.95 Million |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Custom-Fitted, Adjustable, Tongue Retaining, Dual Action Material: Plastic, Silicone, Thermoplastic, Metal End User: Private Practice, Dental Clinics, Hospitals, Home Care Distribution Channel: Online, Distributors, Retail Pharmacies, Direct Sales |
| Companies Covered | Glidewell, VitalSleep, SomnoMed, ZQuiet, SnoreRx, ProSomnus, ResMed, Thornton Adjustable Positioner, Vivos Therapeutics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mandibular Advancement Devices Market Strategic Shifts & Innovations
Digital dentistry workflows and polymer science advances are compressing fabrication timelines while regulatory frameworks on both sides of the Atlantic recalibrate safety and efficacy thresholds for intraoral prostheses.
Selective laser sintering of medical-grade nylon is electrifying custom device production by eliminating thermoplastic molding tooling costs and enabling sub-millimeter titration mechanism precision. Dental sleep medicine practices and direct-to-consumer platforms are adopting this additive manufacturing approach at accelerating velocity, collapsing the traditional four-to-six-week fabrication window to under seventy-two hours in optimized workflows.
The EU Medical Device Regulation's clinical evidence requirements are forcing European manufacturers to construct post-market surveillance systems and notified body relationships that exceed legacy Medical Device Directive obligations. Small-to-mid-tier fabricators without captive regulatory affairs capabilities face market exit pressure, concentrating CE-marked supply among vertically integrated specialists with dedicated quality management infrastructure.
Patient acquisition through direct-to-consumer channels is displacing traditional dentist-referral pathways as telehealth platforms bundle home sleep testing, virtual consultations, and mail-order impression kits. This channel shift compresses customer acquisition costs while raising compliance risks around adequate airway evaluation and titration supervision, with regulatory scrutiny concentrating on United States direct-to-consumer models where state dental board jurisdictions create enforcement fragmentation.
Mandibular Advancement Devices Market Segmentation
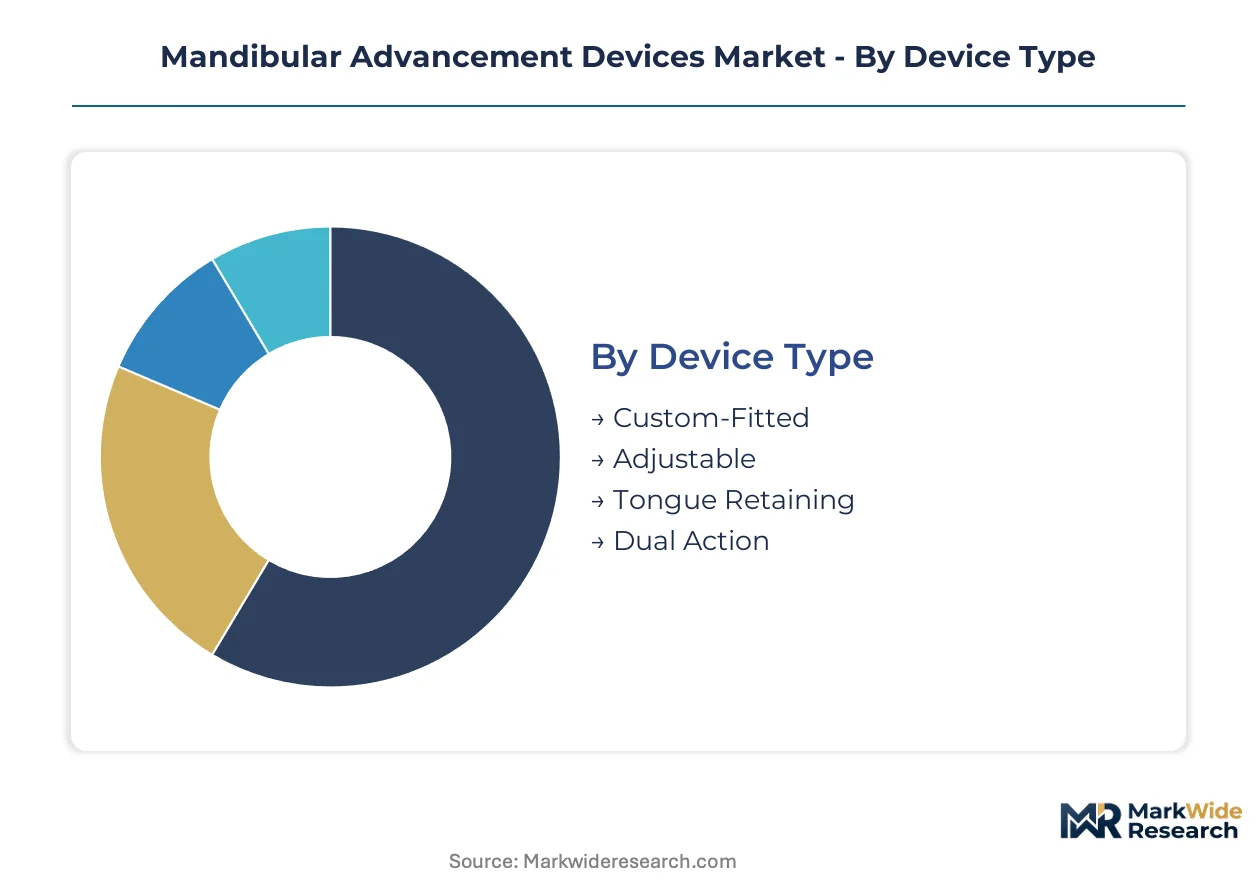
Mandibular advancement devices fragment across fabrication methods, material science, care settings, and patient access pathways. Each segmentation axis reveals distinct margin profiles, regulatory burdens, and competitive intensity that manufacturers must navigate.
Device Type:
Customization depth versus clinical adjustability defines competitive positioning across this category, with titration capability separating premium prescription platforms from commoditized alternatives.
- Custom-Fitted:Medical-grade nylon or copolymer resins are digitally milled or 3D-printed to patient-specific dental impressions. Sleep-dental networks in the United States concentrate demand here, driven by superior compliance rates and reduced bulk versus thermoplastic alternatives.
- Adjustable:Titratable mechanisms permit 0.5–1.0 mm mandibular protrusion increments without device replacement. European thermoplastic molders anchor supply for this segment, though FDA 510(k) clearance requirements filter market entry for novel adjustment architectures.
- Tongue Retaining:Suction-based anterior tongue stabilization bypasses mandibular protrusion entirely. Edentulous patients and those with temporomandibular joint constraints drive niche demand.
- Dual Action:Combined mandibular advancement and tongue stabilization mechanisms address complex airway collapse patterns. Higher fabrication complexity limits manufacturer participation.
Most installed capacity flows through Custom-Fitted. Expansion is steepest in Adjustable.
Material:
Biocompatibility certifications and polymer processing economics stratify margin capture, with medical-grade synthetics commanding premium positioning against commoditized thermoplastics.
- Plastic:Acrylic and copolymer resins dominate volume production through conventional thermoplastic molding. Boil-and-bite direct-to-consumer platforms in the United States exploit this material's low unit cost, though margin compression from over-the-counter competition intensifies.
- Silicone:Soft, flexible intraoral interfaces reduce mucosal irritation and improve overnight retention. Pediatric and geriatric applications favor this material for compliance tolerance.
- Thermoplastic:Heat-moldable polymers enable chairside fitting without laboratory fabrication. Dental clinics leverage this segment for same-day patient delivery.
- Metal:Cobalt-chromium or titanium frameworks provide structural rigidity for severe protrusion requirements. Orthodontic sleep medicine protocols in academic medical centers generate concentrated demand.
Plastic absorbs the highest absolute volume. Silicone gains share fastest in pediatric expansion.
End User:
Credentialing requirements and reimbursement pathways determine channel economics, with integrated sleep-dental networks capturing margin that fragmented private practice cannot access.
- Private Practice:Individual dental sleep medicine practitioners prescribe custom-fitted devices through traditional impression-and-laboratory workflows. American Academy of Dental Sleep Medicine certification scarcity constrains capacity expansion.
- Dental Clinics:Multi-provider practices with in-house digital scanning and 3D printing compress fabrication timelines. United States metropolitan clusters concentrate this segment's installed base.
- Hospitals:Academic medical centers and integrated delivery networks manage complex comorbid apnea cases. CPAP intolerance referrals from pulmonary sleep labs drive prescription volume.
- Home Care:Telehealth-integrated platforms bypass traditional dental gatekeepers through mail-order impression kits and remote titration supervision. CMS reimbursement parity debates shape commercial viability.
Dental Clinics process the highest prescription volume. Home Care expands most quickly.
Distribution Channel:
Patient acquisition cost structures and regulatory compliance burdens diverge sharply between direct-to-consumer models and traditional intermediary networks.
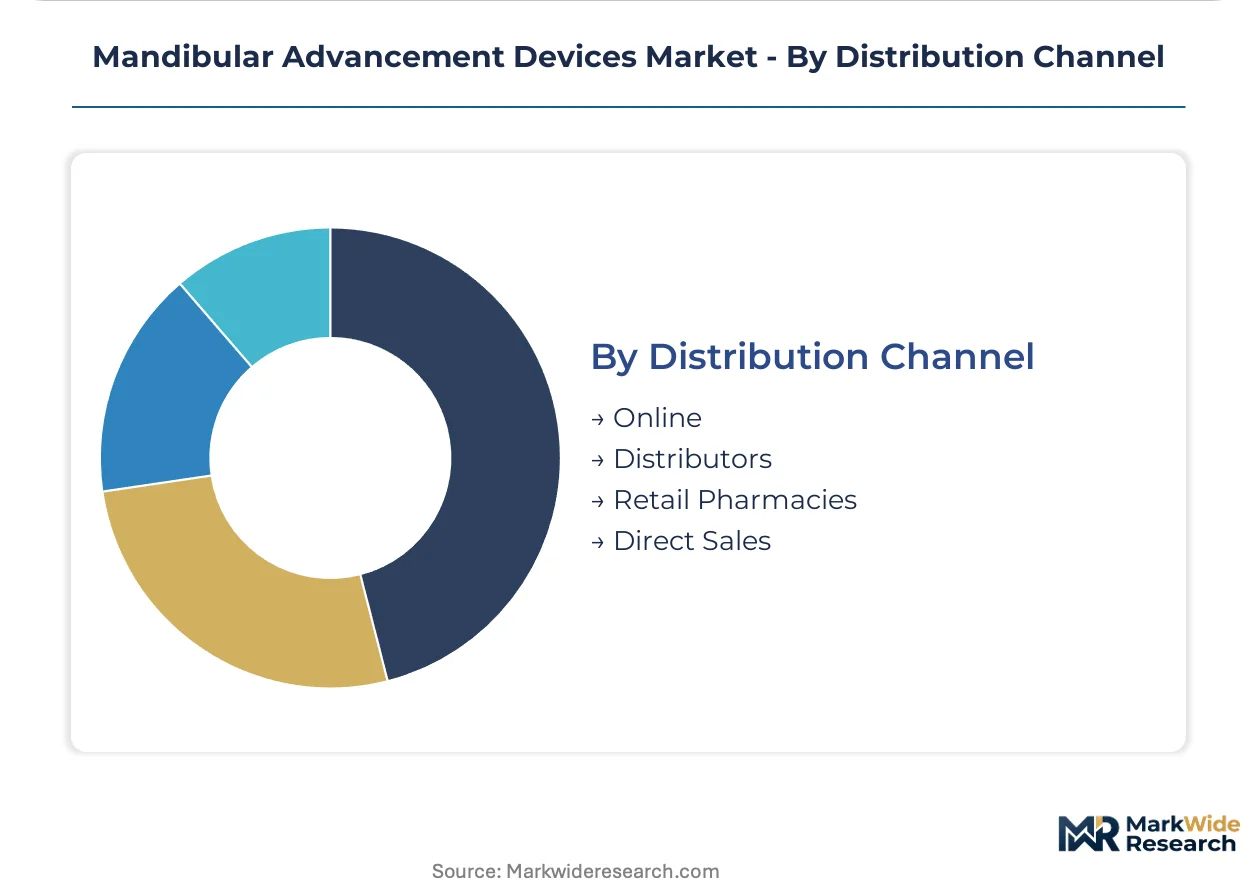
- Online:Direct-to-consumer telehealth platforms bundle home sleep testing, virtual consultations, and device fulfillment. State dental board jurisdictional fragmentation creates enforcement uncertainty in the United States.
- Distributors:Specialized dental sleep medicine supply intermediaries inventory devices for same-day chairside delivery. Relationships with dental service organizations concentrate purchasing power.
- Retail Pharmacies:Limited participation due to prescription requirements and fitting complexity. Over-the-counter boil-and-bite alternatives occupy shelf space instead.
- Direct Sales:Manufacturer-employed field representatives target high-volume sleep-dental practices. SomnoMed and ProSomnus deploy this channel for premium custom-fitted portfolios.
Distributors maintain the deepest penetration. Online channels climb the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping manufacturing footprints as fabricators migrate toward jurisdictions with streamlined medical device approval pathways. Cost-of-compliance gaps between the FDA 510(k) framework and the EU MDR are concentrating new capacity in North American and Asia-Pacific territories.
United States
CMS reimbursement parity debates and telehealth-integrated direct-to-consumer models drive prescription volume expansion. The FDA 510(k) premarket notification pathway accelerates commercialization timelines for novel titration mechanisms. Sleep-dental networks cluster in metropolitan corridors across California, Texas, and the Northeast Corridor.
Germany
Notified body certification under the EU MDR filters market entry and compresses margins for mid-tier fabricators. REACH compliance for medical-grade polymers shapes raw material sourcing decisions. Thermoplastic molding capacity concentrates in Baden-Württemberg and North Rhine-Westphalia, pivoting toward nylon fabrication for thin-profile devices.
Australia
TGA quality management system standards govern domestic market access while enabling export credibility into Asia-Pacific territories. Vertically integrated digital workflows span Sydney and Melbourne manufacturing nodes. SomnoMed leverages captive regulatory affairs capabilities to sustain CE-marked and FDA-cleared product portfolios.
Denmark
EU MDR clinical evidence requirements force construction of post-market surveillance systems that exceed legacy Medical Device Directive obligations. Copenhagen-Aarhus corridor hosts specialized polymer science R&D clusters. European manufacturers without dedicated quality management infrastructure face market exit pressure.
Japan
PMDA medical device registration creates a high-barrier entry environment favoring established multinational portfolios. METI industrial policy supports precision manufacturing capabilities for dental prosthetics. Osaka-Kobe manufacturing belt concentrates thermoplastic processing expertise for intraoral appliances.
Mandibular Advancement Devices Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue direct-to-consumer and telehealth-integrated distribution models. The vendor base stratifies across vertically integrated specialists with captive regulatory capabilities, regional thermoplastic molders serving dental sleep medicine networks, and direct-to-consumer platforms leveraging remote impression technologies. Three archetypes dominate: premium custom-fitted fabricators, commoditized boil-and-bite manufacturers, and diagnostic-integrated sleep medicine platforms. Competitive moves concentrate on M&A capture of sleep-dental networks and capacity expansion into medical-grade nylon additive manufacturing.
Within the vertically integrated tier, SomnoMed and ProSomnus exemplify archetypes combining captive regulatory affairs with digital fabrication workflows. ResMed occupies a position bridging diagnostic services and oral appliance prescription bundling. Among direct-to-consumer specialists, ZQuiet and SnoreRx represent the telehealth-integrated model bypassing traditional dental gatekeepers.
| Leading Market Players |
|---|
| Glidewell |
| VitalSleep |
| SomnoMed |
| ZQuiet |
| SnoreRx |
| ProSomnus |
| ResMed |
| Thornton Adjustable Positioner |
| Vivos Therapeutics |
| Others |
Cost & Logistics Intelligence
Medical-grade nylon resin costs cascade through fabrication tiers, with European thermoplastic molders capturing margin at the polymer conversion stage before devices reach dental sleep medicine networks or direct-to-consumer platforms in the United States.
Pricing Analysis
Distributor markups separate three-tier pricing structure across premium, standard, and economy levels in mandibular advancement devices. FDA 510(k) certification tier and customization depth drive price differentiation, with medical-grade nylon devices commanding premiums over thermoplastic boil-and-bite alternatives. Cost compression in the economy tier is intensifying because over-the-counter commoditization erodes brand premiums. Direct-to-consumer platforms exhibit highest price sensitivity; hospital sleep clinics demonstrate lowest sensitivity due to bundled reimbursement pathways.
Supply Chain Analysis
Medical-grade polymer supply rests on German and Danish specialty chemical producers, with downstream fabrication clustering in Baden-Württemberg thermoplastic molding facilities and Copenhagen-Aarhus digital manufacturing nodes. Key inputs span biocompatible nylon powders, cobalt-chromium frameworks, and copolymer resins. Single-source vulnerability concentrates in EU MDR-certified polymer grades. Distribution runs through specialized dental sleep medicine intermediaries and telehealth-integrated direct fulfillment networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Selective laser sintering automation and AI-driven design optimization compress unit economics toward premium-tier margin expansion in mandibular advancement devices.
For Market Incumbents: Anticipate telehealth-integrated direct-to-consumer platforms eroding traditional dental gatekeeper channels by building captive regulatory affairs capabilities and securing CMS reimbursement parity lobbying positions. Deepen backward integration into medical-grade nylon additive manufacturing to defend fabrication margins against commoditized thermoplastic competition. For New Entrants and Emerging Players: Launch via telehealth-integrated distribution models targeting pediatric and adolescent craniofacial sleep apnea indications, the most penetrable white-space segment beyond adult obstructive sleep apnea. Exploit American Academy of Dental Sleep Medicine certification scarcity by deploying remote titration supervision technology to bypass practitioner bottlenecks. For Investors and Strategic Acquirers: Roll-up economics work for vertically integrated digital workflow specialists because EU MDR clinical evidence requirements force market exit among mid-tier fabricators lacking dedicated quality management infrastructure. Target acquisition candidates with captive FDA 510(k) and CE marking portfolios. Watch CMS reimbursement parity decisions as the inflection signal for oral appliance therapy commercial viability.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Pathway Streamlining | Accelerates commercialization timelines for novel titration mechanisms in the United States. |
| CE Marking Compliance Investment | EU MDR mandates expand notified body certification portfolios filtering mid-tier manufacturer participation. |
| Hospital System Partnership | Academic medical center sleep labs generate CPAP intolerance referrals driving prescription volume. |
| Software Companion Development | Machine learning algorithms optimize mandibular protrusion vectors enabling mass customization at scale. |
| Reimbursement Strategy | CMS parity debates determine cost equivalence with continuous positive airway pressure therapy pathways. |
Research Approach
Coverage spans the United States, Germany, Australia, Denmark, and Japan, with primary inputs from each market combining structured interviews with dental sleep medicine practitioners, biomedical engineers at academic medical centers, GPO contracts managers, and regulatory affairs specialists at notified bodies, validated against FDA 510(k) filings, TGA registration databases, EU MDR certificates, CMS reimbursement bulletins, and customs trade records, with bottom-up prescription volume modeling triangulated against top-down market sizing.
Rate-of-change decomposition separates volume growth from price-mix effects across the projection horizon. Segmentation dimensions span device type, material science tier, end-user setting, and distribution channel, with regional regulatory cluster overlays. CAGRs derive from patient flow modeling through home sleep testing penetration curves, dental sleep medicine practitioner supply constraints, and reimbursement pathway evolution, incorporating polymer processing cost curves and additive manufacturing adoption rates as industry-specific forecast inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under EU MDR enforcement intensity shifts and CMS reimbursement parity reversal scenarios. Forecasts reflect documented assumptions regarding telehealth regulatory permissiveness, polymer supply lead times, and practitioner certification pipeline throughput. A small set of named triggers—CMS coverage determinations, EU MDR notified body capacity constraints, and medical-grade nylon supply disruptions—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Orthodontic Retainers Market
Medical Devices
Spine Positioning Devices Market
Medical Devices
Global Gamma Probe Device Market
Medical Devices
Autorefractor Keratometer Market
Medical Devices
Computer Assisted Surgical (CAS) Systems Market
Medical Devices
Europe Renal Denervation Devices Market
Medical Devices
Subcutaneous Drug Delivery Devices Market
Medical Devices
Laser Therapy Devices Market
Medical Devices
South Africa General Surgical Devices Market
Medical Devices
Nano Healthcare Technology for Medical Equipment Market
Medical Devices
Global Electrotherapy Devices Market
Medical Devices
Ophthalmic Ultrasound Devices Market
Medical Devices
Global Microkeratome Market
Medical Devices
Smart Lenses Market
Medical Devices
Asia-Pacific Ultrasound Devices Market
Medical Devices
North America Ambulatory Infusion Pumps Market