
 Interventional Spine Devices Market | 2026-2036
Interventional Spine Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Interventional Spine Devices Market Foresight
Polyetheretherketone is decoupling from titanium alloy in interbody cage construction as manufacturers seek radiolucency and modulus-matching to bone. NuVasive leverages its proprietary porous PEEK architecture to differentiate in cervical and lumbar fusion segments. Globus Medical sustains manufacturing scale through vertical control from implant machining to sterile packaging in its Pennsylvania facilities.
Interventional spine devices comprise implantable hardware, energy-based instruments, and navigation systems designed to decompress neural elements, restore segmental alignment, or modulate pain signals through percutaneous or minimally open approaches; typical cervical interbody cages measure 12-18mm in footprint with 4-10mm heights and integrate titanium plasma-spray coatings to enhance osseointegration. Spinal implants dominate current revenue pools due to recurring revision cycles and premium pricing on 3D-printed titanium constructs. Minimally invasive surgery technology leads procedural growth as navigation platforms and expandable retractors reduce approach-related morbidity and enable same-day discharge protocols.
The FDA's 510(k) program governs market entry for novel interventional spine systems, while the EU MDR imposes heightened clinical evidence requirements on legacy implant families seeking CE mark renewal. OSHA bloodborne pathogen standards and state-level CON regulations further shape capital deployment for hybrid operating suites and ambulatory spine centers. Stakeholders must monitor CMS procedural code valuations and site-of-service differentials as these directly determine whether hospital outpatient departments or freestanding ASCs capture the next wave of lumbar fusion and motion-preservation volume.
Market Dynamics
Ambulatory surgical centers are capturing lumbar fusion volume as CMS site-of-service differentials widen the reimbursement gap against hospital outpatient departments, forcing manufacturers to reconfigure distribution and sterile packaging workflows for lower-acuity settings.
Growth Catalysts
- CMS site-of-service differentials:Reimbursement spreads between freestanding ASCs and hospital outpatient departments steer cervical and lumbar fusion procedures toward lower-cost settings, expanding addressable volume for device makers with ASC-compatible sterile packaging and consignment inventory systems.
- Expandable retractor platforms:Minimally invasive surgery technology reduces approach-related morbidity and enables same-day discharge protocols, with navigation-integrated retractor systems shortening operative time and accelerating adoption among spine surgeons transitioning from open techniques.
- Aging demographics in the United States:Degenerative disc disease prevalence climbs with population aging, sustaining procedural demand for interbody fusion cages and posterior fixation systems in the 65-plus cohort where commercial reimbursement frameworks support elective spine surgery access.
Market Restraints
- Titanium powder supply concentration:Additive manufacturing of porous titanium interbody cages depends on gas-atomized Ti-6Al-4V powder sourced primarily from North American and European specialty metallurgy suppliers, exposing device makers to input cost volatility and lot-to-lot consistency risks.
- EU MDR clinical evidence requirements:Legacy implant families seeking CE mark renewal face heightened clinical data demands and extended notified body review timelines, compressing revenue recognition from European product lines and forcing portfolio rationalization decisions.
- Motion-preservation substitution:Cervical and lumbar artificial disc replacements compete with fusion constructs for younger patient segments, with some payors imposing age and prior conservative-care requirements that segment addressable fusion volume.
Strategic Opportunities
- Untapped ASC penetration in Texas and Florida:Certificate-of-need deregulation in these states enables freestanding spine center development, creating first-mover advantages for device vendors with direct-to-ASC sales forces and procedure-specific implant kits.
- Navigation-robotics convergence:Integration of intraoperative navigation with robotic guidance platforms enables percutaneous pedicle screw placement accuracy beyond fluoroscopic limits, opening procedural expansion into deformity correction and revision cases previously excluded from minimally invasive approaches.
- IRA hospital price transparency mandates:New disclosure requirements on payer-negotiated rates illuminate site-of-service cost differentials, accelerating patient steering toward ASCs and amplifying demand for lower-cost implant configurations compatible with ambulatory reimbursement ceilings.
Industry Challenges
- Biomedical engineer scarcity:Design and validation of 3D-printed titanium lattice structures requires specialized expertise in topology optimization and fatigue testing, with talent concentrated among a handful of orthopedic-focused engineering programs and contract research organizations.
- FDA 510(k) predicate drift:Substantial equivalence determinations for novel PEEK cage geometries face heightened scrutiny as the agency narrows acceptable predicate families, extending submission preparation timelines and increasing regulatory consulting expenditure.
- Legacy EHR integration:Navigation and robotics platforms require seamless connectivity with hospital information systems and imaging archives, with interoperability gaps forcing costly custom interface development for each institutional deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Interventional Spine Devices Market |
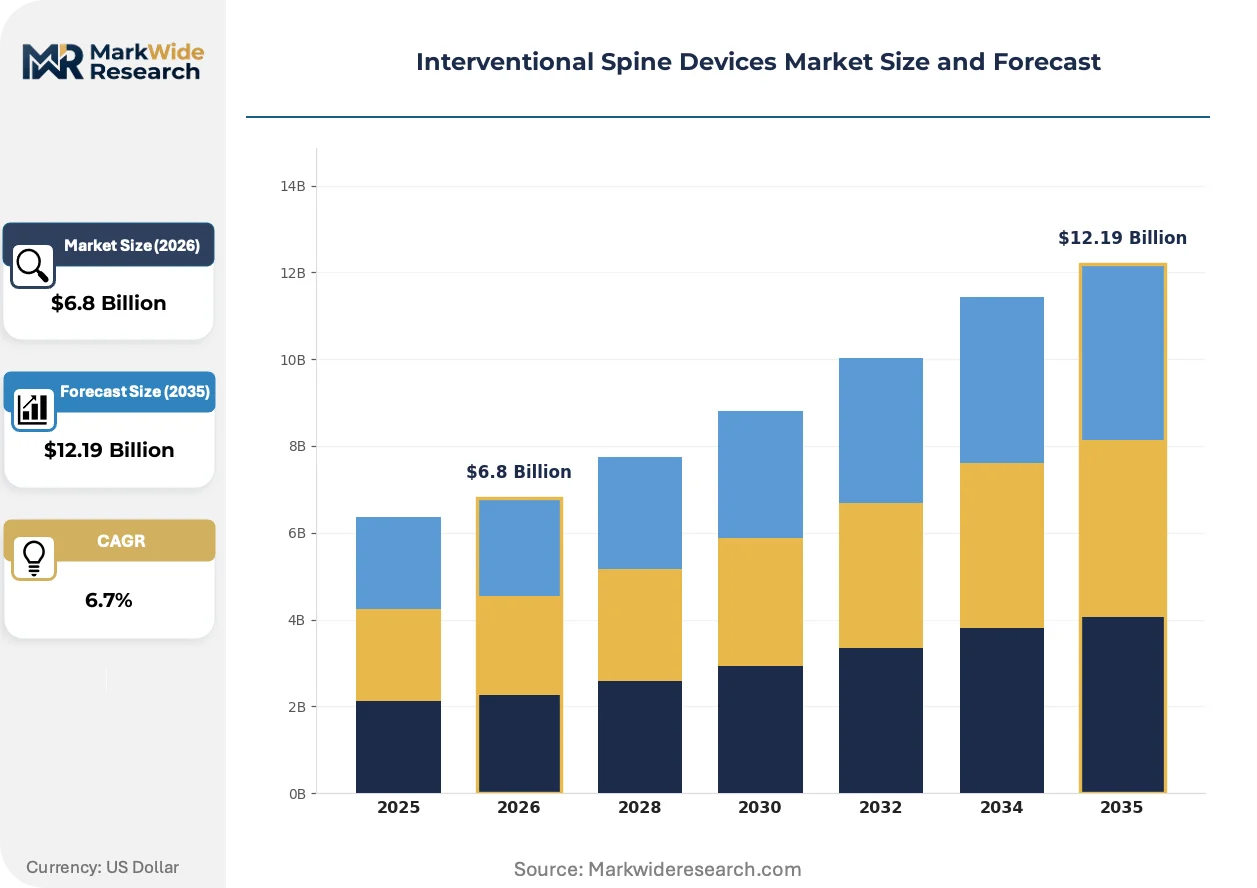
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $12.19 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
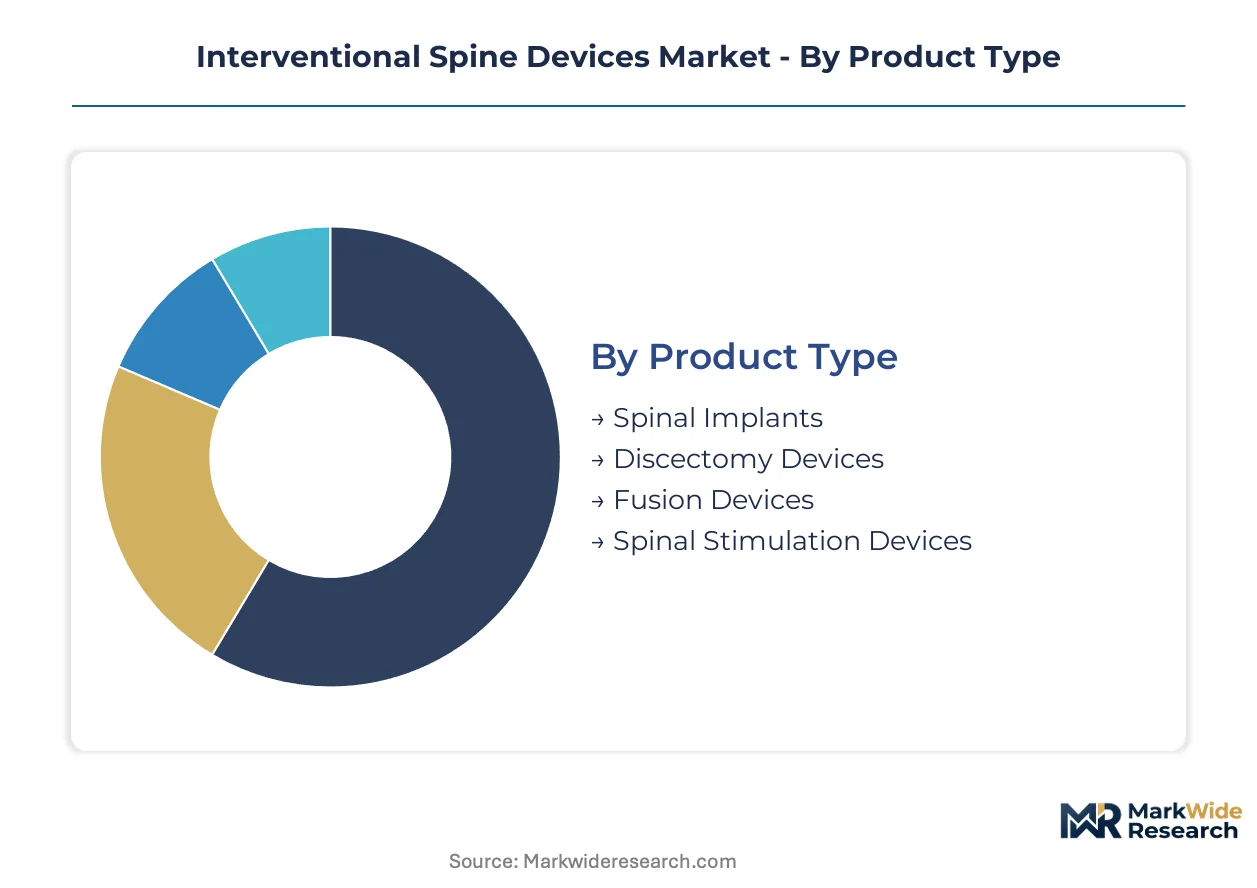
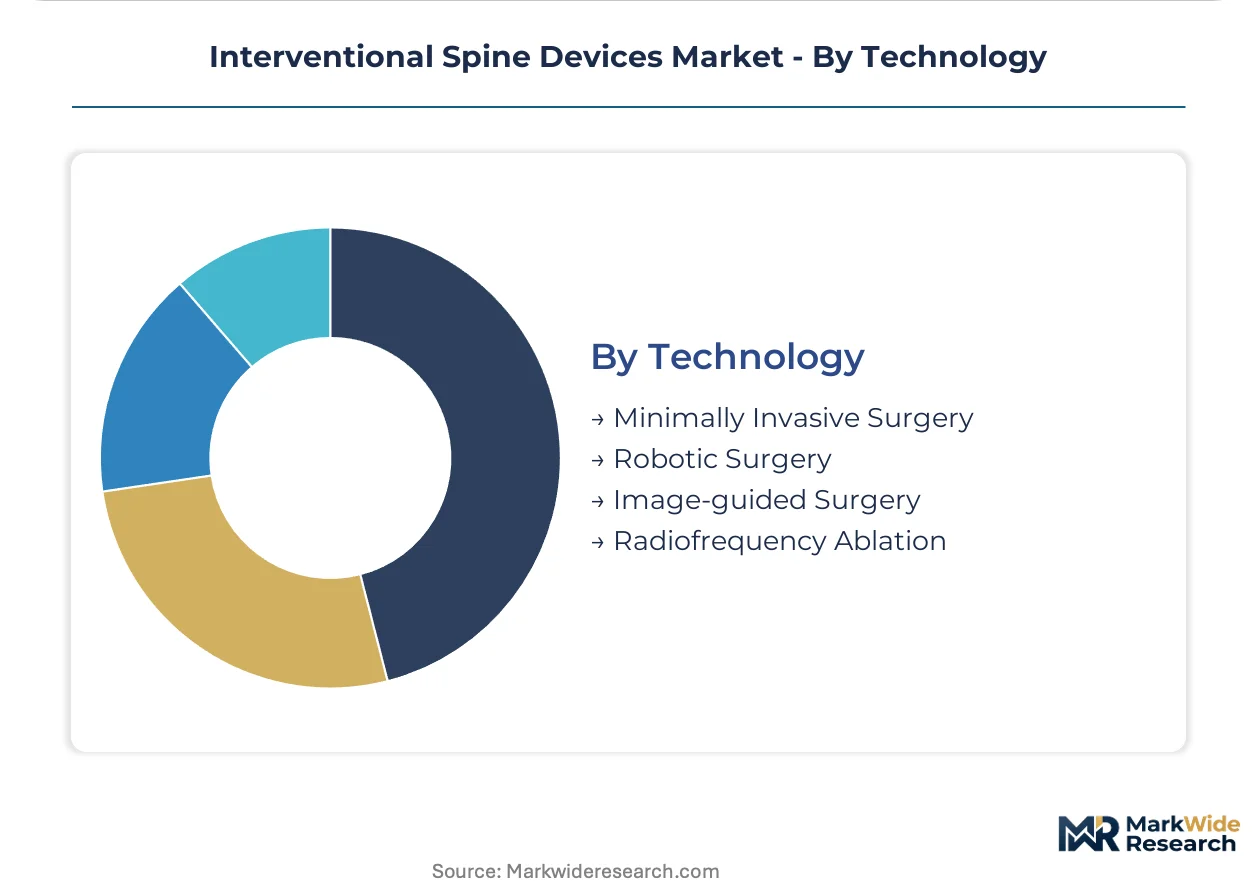
| Segmentation | Product Type: Spinal Implants, Discectomy Devices, Fusion Devices, Spinal Stimulation Devices Application: Chronic Pain Management, Spinal Stabilization, Herniated Disc Treatment, Vertebral Compression Fracture Treatment End User: Hospitals, Ambulatory Surgical Centers, Specialty Clinics, Rehabilitation Centers Technology: Minimally Invasive Surgery, Robotic Surgery, Image-guided Surgery, Radiofrequency Ablation |
| Companies Covered | NuVasive, Globus Medical, Medtronic, DePuy Synthes, Orthofix, Stryker, Zimmer Biomet, RTI Surgical, Johnson & Johnson, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Interventional Spine Devices Market Shifts & Advancements
Interventional spine technology is bifurcating between high-acuity navigation-robotic platforms for complex deformity and streamlined disposable kits for ambulatory fusion, with material science and reimbursement mechanics driving divergent innovation paths.
Patient-specific 3D-printed titanium interbody cages with optimized pore architectures and integrated fixation features are rewriting competitive positioning in lumbar fusion. ASCs and hospital outpatient departments are adopting these constructs for one- and two-level procedures where bone quality and load-bearing requirements favor modulus-matched implants over conventional PEEK. The technology is compressing revision rates and enabling premium pricing tiers tied to radiographic fusion outcomes.
The EU MDR's enhanced clinical evidence requirements for Class III implantable devices are reshaping European market access strategy. Manufacturers must generate prospective data or systematic literature reviews for legacy cage families seeking CE mark renewal, forcing portfolio prioritization and withdrawal of marginal SKUs. Cervical interbody devices with limited clinical publication history face the steepest compliance burden and highest probability of market exit.
Hospital supply chains are consolidating spine implant procurement through value-analysis committees that bundle vendor selection across trauma, joint reconstruction, and spine categories. Integrated delivery networks in California and Pennsylvania are replacing individual surgeon preference cards with standardized construct menus, compressing available supplier slots and favoring vendors with broad orthopedic portfolios and consignment inventory infrastructure. This concentration is most visible in multi-hospital systems pursuing category management centralization.
Interventional Spine Devices Market Segmentation
Interventional spine device purchasing decisions hinge on site-of-service economics, procedural acuity, and regulatory clearance pathways. Manufacturers must align product configurations with distinct reimbursement ceilings and sterility requirements across hospital, ambulatory, and specialty care settings.
Product Type:
FDA 510(k) clearances concentrate on fusion cages and posterior fixation systems, while spinal stimulators face PMA or de novo pathways with steeper clinical evidence demands. CE mark renewal under EU MDR imposes proportionate burdens across implantable hardware categories.
- Spinal Implants:Comprising interbody cages, pedicle screw systems, and interspinous spacers, these devices dominate procurement budgets through recurring revision cycles. Demand clusters in the United States where commercial payors support elective fusion access for degenerative conditions.
- Discectomy Devices:Mechanical and thermal tools for nucleus pulposus removal, including manual rongeurs and radiofrequency probes. Adoption accelerates in ambulatory settings where same-day discharge protocols favor tissue-sparing approaches over open discectomy.
- Fusion Devices:Interbody spacers, plates, and biologics promoting osseointegration. Bone morphogenetic protein carriers and demineralized bone matrices face CMS coding scrutiny that segments addressable volume.
- Spinal Stimulation Devices:Implantable pulse generators and leads for neuromodulation of chronic back and limb pain. Rechargeable systems command premium pricing tiers tied to battery longevity and programming flexibility.
Leading the category by volume: Spinal Implants. Growing fastest: Spinal Stimulation Devices.
Application:
Procedural volume distributes across degenerative, traumatic, and neoplastic indications with divergent acuity profiles and reimbursement mechanics. Site-of-service differentials steer lower-acuity applications toward freestanding centers.
- Chronic Pain Management:Dorsal column stimulation and intrathecal drug delivery systems for failed back surgery syndrome. Demand concentrates in pain management clinics where physician ownership of ambulatory surgery centers aligns economic incentives with device selection.
- Spinal Stabilization:Fusion and motion-preservation constructs for spondylolisthesis and degenerative instability. Volume growth tracks aging demographics in Florida and Texas where certificate-of-need deregulation enables dedicated spine center development.
- Herniated Disc Treatment:Microdiscectomy and percutaneous decompression procedures. Minimally invasive approaches displace open laminectomy in hospital outpatient departments seeking reduced length-of-stay metrics.
- Vertebral Compression Fracture Treatment:Balloon kyphoplasty and vertebroplasty cements for osteoporotic collapse. Reimbursement compression under CMS physician fee schedules constrains addressable volume in Medicare-dominant geographies.
Spinal Stabilization commands the largest procedure count. Herniated Disc Treatment is climbing the fastest as same-day protocols expand.
End User:
Capital deployment and inventory models diverge sharply across facility types, with sterile packaging workflows and consignment infrastructure determining vendor competitiveness.
- Hospitals:Academic medical centers and community hospitals with hybrid operating suites and 24/7 emergency spine coverage. Value-analysis committees consolidate procurement across trauma, joint, and spine categories, compressing supplier slots.
- Ambulatory Surgical Centers:Freestanding facilities capturing cervical and lumbar fusion volume as site-of-service differentials widen. Device makers reconfigure kit configurations and sterile packaging for lower-acuity workflows.
- Specialty Clinics:Orthopedic and neurosurgical practices with in-office procedure suites. Pain management-focused clinics drive spinal cord stimulator trial-to-permanent conversion rates.
- Rehabilitation Centers:Post-acute facilities managing non-surgical candidates and recovery protocols. Device exposure limited to external orthotics and patient selection for surgical referral.
Hospitals retain the dominant share. Ambulatory Surgical Centers are gaining share fastest on CMS reimbursement mechanics.
Technology:
Platform selection determines capital intensity, surgeon learning curves, and compatibility with existing imaging infrastructure.
- Minimally Invasive Surgery:Expandable retractors and percutaneous access systems reducing approach-related morbidity. Navigation-integrated platforms shorten operative time and accelerate adoption among surgeons transitioning from open techniques.
- Robotic Surgery:Guidance platforms enabling percutaneous pedicle screw placement accuracy beyond fluoroscopic limits. Procedural expansion targets deformity correction and revision cases previously excluded from minimally invasive approaches.
- Image-guided Surgery:Intraoperative CT and 3D fluoroscopy systems for real-time navigation. Interoperability gaps with legacy EHR systems force costly custom interface development.
- Radiofrequency Ablation:Thermal lesioning of medial branch nerves for facet-mediated pain. Outpatient clinic adoption driven by favorable reimbursement under CPT codes and minimal capital requirements.
Minimally Invasive Surgery leads procedural volume. Robotic Surgery shows the steepest expansion trajectory on navigation convergence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for interventional spine devices concentrates in the United States, where aging demographics and commercial reimbursement frameworks sustain procedural volume. The analysis covers five countries where regulatory pathways, site-of-service economics, and manufacturing infrastructure shape competitive positioning.
United States
Medicare site-of-service differentials and commercial payor frameworks drive cervical and lumbar fusion volume toward ambulatory surgical centers. FDA 510(k) clearances govern market entry for minimally invasive spine systems, compressing product development timelines for domestic manufacturers. Pennsylvania hosts concentrated implant machining and sterile packaging operations serving the Northeast corridor.
Germany
EU MDR clinical evidence requirements for Class III implantable devices reshape CE mark renewal strategies for legacy cage families. The country's notified bodies impose extended review timelines on porous titanium interbody constructs lacking prospective data. Baden-Württemberg maintains precision machining clusters supplying orthopedic component fabrication across European markets.
Japan
PMDA regulatory pathways for spinal implants emphasize biocompatibility testing and fatigue validation for titanium alloy constructs. METI industrial policy supports domestic production of medical devices through subsidized R&D consortia. The Kanto region around Tokyo concentrates hospital procurement networks and distributor infrastructure for imported and locally manufactured systems.
China
NMPA registration requirements for imported spinal implants mandate domestic clinical trials and extended review cycles for foreign manufacturers. Provincial health procurement platforms consolidate purchasing volume for public hospitals, compressing available supplier slots. The Yangtze River Delta region clusters contract manufacturers producing PEEK and titanium components for both domestic and export markets.
Switzerland
Swissmedic maintains stringent quality system inspections for orthopedic implant manufacturers seeking market authorization. The country's bilateral agreements with the EU enable streamlined CE mark recognition while preserving independent regulatory oversight. The Lake Geneva region hosts specialized metallurgy suppliers producing gas-atomized titanium powder for additive manufacturing applications.
Interventional Spine Devices Market Competitive Landscape
Strategic acquisitions dominate the current landscape as larger orthopedic portfolios absorb specialized spine technology platforms. The vendor base organizes around three tiers: diversified multinational conglomerates with broad trauma and joint reconstruction franchises, mid-cap spine-focused specialists with navigation and robotics capabilities, and regional contract manufacturers supplying private-label implant components. Two competitive vectors define positioning: backward integration into titanium powder supply and captive sterile packaging infrastructure for ASC-compatible workflows.
Within the diversified multinational tier, Medtronic and Johnson & Johnson exemplify scale-driven positioning through expansive distribution networks and cross-category hospital procurement relationships. NuVasive and Globus Medical occupy specialist archetypes, representing focused investment in minimally invasive platforms and patient-specific implant architectures. Stryker and Zimmer Biomet anchor the orthopedic conglomerate segment, leveraging existing trauma and joint reconstruction infrastructure to capture bundled spine procurement contracts.
| Leading Market Players |
|---|
| NuVasive |
| Globus Medical |
| Medtronic |
| DePuy Synthes |
| Orthofix |
| Stryker |
| Zimmer Biomet |
| RTI Surgical |
| Johnson & Johnson |
| Others |
Supply & Pricing Matrix
Additive manufacturing adoption in porous titanium interbody cages simultaneously compresses per-unit production costs and concentrates supply leverage among gas-atomized powder specialists in Pennsylvania and the Lake Geneva region.
Pricing Analysis
Volume-margin splits bifurcate sharply between hospital procurement contracts and ambulatory surgical center workflows. Three-tier pricing structure across premium patient-specific constructs, standard PEEK cages, and economy-grade titanium spacers reflects FDA clearance tier and osseointegration performance data. Pricing pressure stems from CMS site-of-service reimbursement compression forcing ASC-compatible configurations. Hospital value-analysis committees exhibit lowest price sensitivity due to bundled orthopedic procurement budgets, while freestanding ASCs demand aggressive cost concessions.
Supply Chain Analysis
FDA 510(k) and EU MDR certification requirements gate upstream supply relationships, privileging established machining operations with validated quality systems. Gas-atomized Ti-6Al-4V powder production concentrates in Switzerland, Pennsylvania, and North Carolina specialty metallurgy facilities. Raw material dependencies span titanium sponge feedstock, medical-grade PEEK resin, and sterile barrier packaging films. Single-source vulnerability runs through European notified body capacity constraints for CE mark renewals. Distribution runs through consignment inventory models at integrated delivery networks and direct-to-ASC sales forces.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical integration is accelerating into captive titanium powder supply and sterile packaging infrastructure as manufacturers defend margin position against reimbursement compression.
For Market Incumbents: Hedge titanium input volatility through long-term offtake agreements with gas-atomized powder suppliers in the Lake Geneva cluster. Consolidate sterile packaging workflows in Pennsylvania facilities to capture ASC volume migration driven by CMS site-of-service differentials.
For New Entrants and Emerging Players: Launch via direct-to-ASC distribution models in Texas and Florida where certificate-of-need deregulation enables freestanding spine center development. Target pain management clinic spinal cord stimulator trials with rechargeable system platforms.
For Investors and Strategic Acquirers: Exit pathways concentrate in mid-cap spine specialists with navigation-robotics convergence capabilities and established FDA predicate families. Five-to-ten-year viability hinges on EU MDR compliance completion rates. Watch notified body review timeline extensions as inflection signal for European revenue compression.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance Pathway | Accelerates market entry for minimally invasive cage geometries against narrowing predicate families. |
| CE Marking Pathway | Determines European revenue continuity as MDR clinical evidence demands reshape legacy implant portfolios. |
| Hospital System Partnership | Secures value-analysis committee placement amid procurement consolidation across orthopedic categories. |
| Reimbursement Strategy | Aligns product configuration with CMS site-of-service differentials steering volume toward ASCs. |
| Software Companion Development | Enables navigation platform interoperability with legacy EHR systems in academic medical centers. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with spine surgeons, biomedical engineers, hospital purchasing committee members, and GPO contracts managers combined with FDA 510(k) databases, CMS Medicare claims data, hospital procurement platforms, and EU MDR notified body filings. Bottom-up implant volume modeling and top-down market sizing triangulated across data streams.
Data-stream reconciliation across procedural volume registries, implant utilization surveys, and manufacturer revenue disclosures shaped the analytical framework. Segmentation dimensions modeled include product type, application acuity, end-user facility class, and technology platform complexity across the projection horizon. CAGRs derived from slope-intercept analysis of historical procedural growth and reimbursement trajectory assumptions. Forecast inputs incorporated aging demographic projections and site-of-service differential evolution.
EU MDR implementation delays, titanium powder supply disruptions, and CMS coding valuation revisions are the dominant revision risks to modeled outputs. Forecasts reflect documented assumptions on predicate family availability and notified body capacity. A model refresh is warranted upon material change in ambulatory surgical center reimbursement ceilings.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Neuroprosthetics Market
Medical Devices
Stent Delivery Systems Market
Medical Devices
Medical Connector Market
Medical Devices
Global Doppler Ultrasound Systems Market
Medical Devices
3D Printed Implants Market
Medical Devices
Artificial Vital Organs and Medical Bionics Market
Medical Devices
Global Digital Dentistry Devices Market
Medical Devices
Medical Device and Accessories Market
Medical Devices
Cryosurgery Devices Market
Medical Devices
North America Surgical Microscopes Market
Medical Devices
Image-Based Cytometer Market
Medical Devices
Global Wearable Injectors Market
Medical Devices
Next Generation Optical Biometry Devices Market
Medical Devices
Global Motion Preservation Devices Market
Medical Devices
Trial Prostheses Market
Medical Devices
Chile Ultrasound Devices Market