
 Arthroscopy Devices Market | 2026-2036
Arthroscopy Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Arthroscopy Devices Market Intelligence
Ambulatory surgical centers is bifurcating demand away from traditional hospital inpatient settings as payer preference and patient throughput economics favor same-day joint procedures. Arthrex leverages its vertically integrated implant and instrument portfolio to dominate the sports medicine channel. Stryker sustains competitive pressure through its broad operating room equipment ecosystem that locks in arthroscopy system placement. Smith & Nephew anchors its position in wound and joint repair adjacencies that feed recurring shaver and fluid management consumable demand.
Arthroscopy devices encompass rigid endoscopes, motorized shaver handpieces, irrigation pumps, and camera control units engineered to optical resolutions exceeding 1080p with LED cold-light illumination for minimally invasive joint inspection and intervention. Visualization systems command premium positioning as 4K and 3D imaging modalities displace standard-definition platforms in high-volume orthopedic service lines. Fluid management systems represent a mature consumable revenue stream where disposable tubing and pump sets generate recurring pull-through tied to case volume rather than capital replacement cycles. Robot-assisted surgery is gaining fastest within the technology dimension as platforms integrate haptic feedback and preoperative planning into arthroscopic workflows.
FDA 510(k) premarket notification governs device clearance timelines and clinical evidence requirements for arthroscope and shaver system introductions, while EU MDR technical documentation and post-market surveillance obligations are extending certification cycles for European market access. ISO 13485 quality management standards shape supplier qualification and OEM outsourcing decisions across the instrument supply base. Stakeholders must monitor reimbursement parity shifts between ASC and hospital settings as site-of-service differentials determine capital deployment priorities for arthroscopy suite expansion.
Market Dynamics
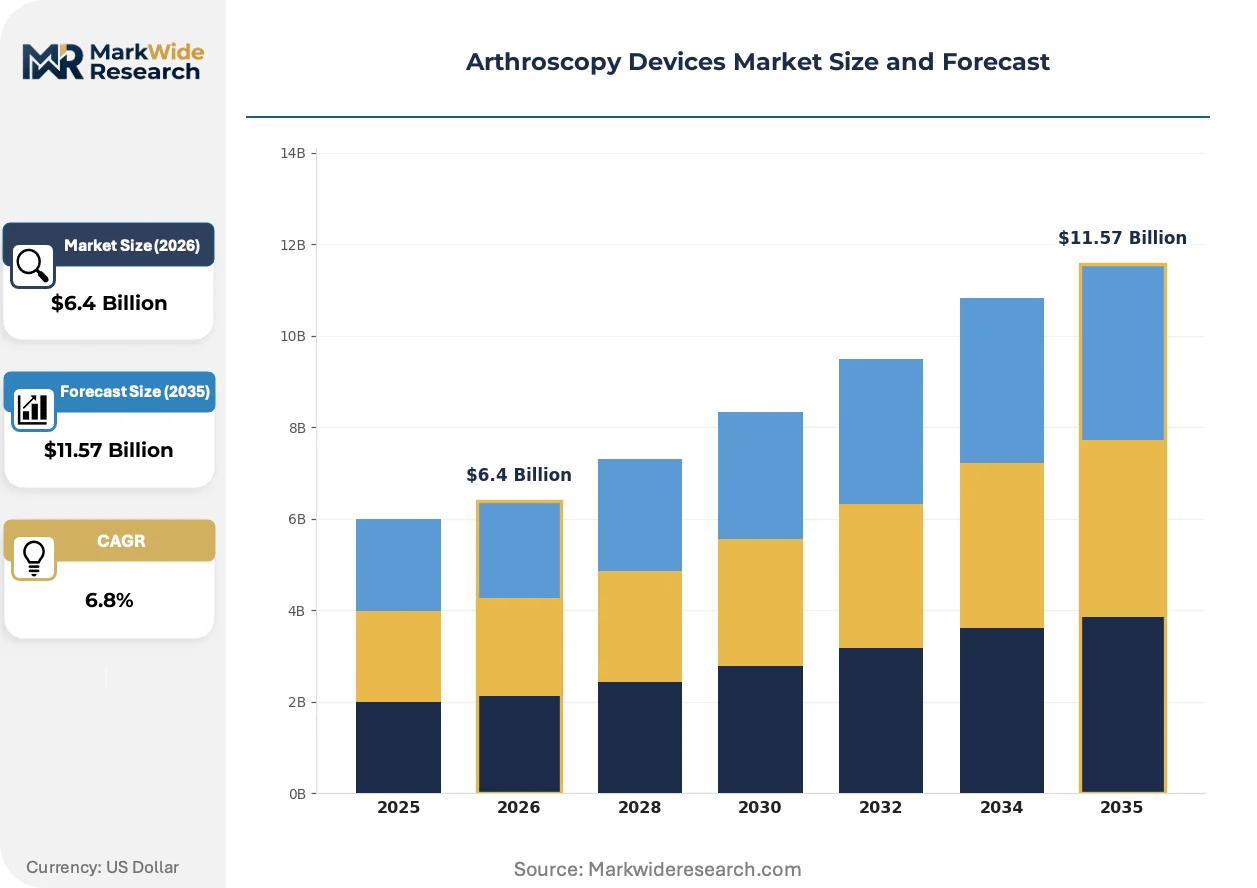
Migration toward ambulatory surgical centers is compressing capital equipment replacement cycles while simultaneously expanding consumable pull-through volumes, fundamentally restructuring how arthroscopy device vendors capture lifetime customer value.
Growth Catalysts
- CMS site-of-service payment differentials:Medicare reimbursement parity for outpatient joint procedures accelerates ASC infrastructure investment across the United States.
- 4K visualization platforms:Resolution upgrades drive replacement demand in high-volume orthopedic service lines seeking surgical precision advantages.
- Sports medicine volume expansion:Youth and professional athletic injury treatment protocols standardize arthroscopic intervention as first-line therapy.
Market Restraints
- Optical component supply concentration:German and Japanese lens manufacturers control critical endoscope glass supply, creating single-source vulnerability.
- EU MDR technical documentation burdens:Extended certification timelines delay product launches and freeze European market expansion capital.
- Reusable instrument reprocessing economics:Hospital sterilization departments face labor cost inflation that erodes the business case for multi-use shaver systems.
Strategic Opportunities
- India ASC infrastructure buildout:Private hospital chains deploy arthroscopy suites in tier-2 cities where joint procedure penetration remains below metropolitan benchmarks.
- Robot-assisted platform integration:Haptic feedback systems converge with preoperative planning software to create differentiated workflow offerings.
- Disposable fluid management tubing:Single-use pump sets eliminate reprocessing liability while securing recurring revenue streams independent of capital cycles.
Industry Challenges
- ISO 13485 supplier qualification complexity:OEM outsourcing decisions require 12-18 month validation timelines that constrain manufacturing flexibility.
- Legacy camera control unit integration:New visualization systems must maintain backward compatibility with installed base infrastructure, limiting architectural innovation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Arthroscopy Devices Market |
| Market Size in 2026 | $6.4 Billion |
| Market Size in 2035 | $11.57 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Arthroscopes, Shaver Systems, Fluid Management Systems, Visualization Systems End User: Hospitals, Ambulatory Surgical Centers, Orthopedic Clinics, Rehabilitation Centers Technology: Robot-Assisted Surgery, Wireless Monitoring, 3D Imaging, High-Definition Video Application: Sports Medicine, Pain Management, Cartilage Repair, Joint Reconstruction |
| Companies Covered | Arthrex, Stryker, Smith & Nephew, Johnson & Johnson, Zimmer Biomet, Conmed, Medtronic, Karl Storz, Olympus, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Arthroscopy Devices Market Strategic Shifts & Innovations
Digital imaging pipelines and disposable instrumentation are converging to redefine value capture models, shifting competitive advantage from capital equipment durability to consumable throughput economics and software-enabled workflow integration.
4K camera heads with integrated image processing is decomposing the traditional separation between arthroscope optics and control unit functionality. High-volume orthopedic groups in the United States are adopting these consolidated platforms within 24-month replacement windows. This consolidation is decomposing vendor margins on standalone camera controllers while elevating software licensing and sensor module revenue.
EU MDR post-market surveillance obligations are extending certification cycles for European market access. Device manufacturers now face annual clinical data submission requirements that compress product development timelines. Visualization system OEMs with legacy CE mark portfolios under the Medical Device Directive face the steepest compliance re-engineering costs.
Direct-to-ASC equipment financing is displacing traditional hospital capital committee procurement channels. Independent surgery centers in Texas and Florida are leasing arthroscopy suites through vendor-managed service agreements that bundle maintenance and consumable supply. This channel shift concentrates purchasing authority with clinical directors rather than supply chain executives.
Arthroscopy Devices Market Segmentation
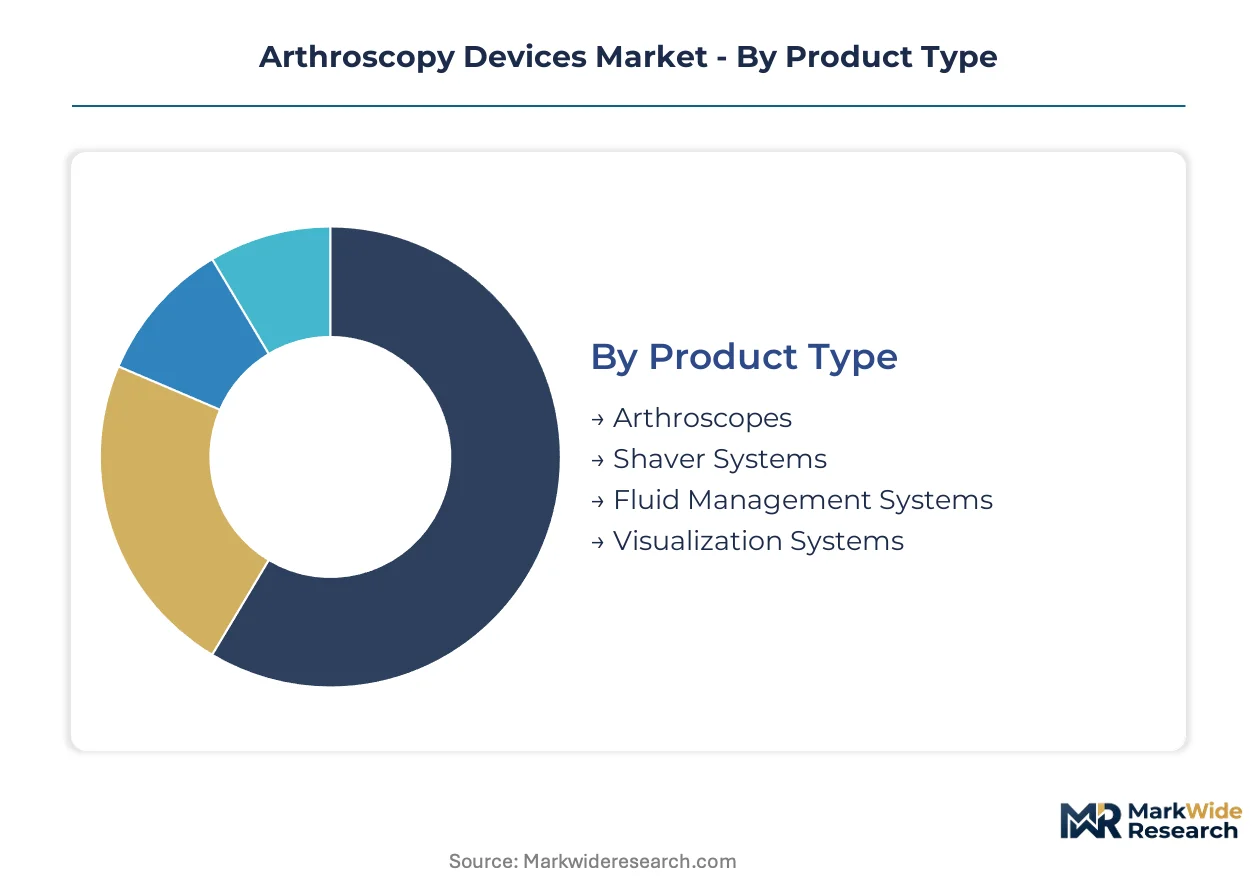
Arthroscopy device segmentation reveals how capital equipment, consumables, and software-enabled platforms compete for different margin pools across surgical settings. Understanding these splits guides vendor resource allocation between replacement cycles and recurring revenue streams.
Product Type:
Margin pools concentrate in visualization platforms commanding premium pricing through resolution upgrades, while fluid management systems deliver steady consumable pull-through independent of capital replacement timing.
- Visualization Systems:4K and 3D camera heads with integrated image processing consolidate optical and control functionality into single units. Demand clusters in high-volume United States orthopedic groups replacing standard-definition platforms within compressed 24-month windows to capture surgical precision advantages.
- Shaver Systems:Motorized handpieces with disposable blade attachments enable tissue debridement and synovectomy procedures. United States sports medicine volumes and ASC joint venture structures are pulling capital into shaver infrastructure as outpatient migration accelerates.
- Fluid Management Systems:Irrigation pumps and disposable tubing sets maintain joint distension during procedures.
- Arthroscopes:Rigid endoscopes with LED cold-light illumination provide optical access exceeding 1080p resolution.
Visualization Systems hold installed capacity. Shaver Systems is rotating up the share rankings.
End User:
Customer economics diverge sharply between capital-constrained independent centers and integrated health systems with centralized procurement authority.
- Ambulatory Surgical Centers:Independent surgery centers in Texas and Florida are leasing arthroscopy suites through vendor-managed service agreements that bundle maintenance and consumable supply. CMS site-of-service payment differentials accelerate ASC infrastructure investment across the United States.
- Hospitals:Integrated delivery networks maintain centralized capital committees with extended replacement cycles and sterilization department overhead. Hospital sterilization departments face labor cost inflation that erodes the business case for multi-use shaver systems.
- Orthopedic Clinics:Specialist practices perform diagnostic arthroscopy and minor interventions outside full surgical facilities.
- Rehabilitation Centers:Post-operative facilities utilize arthroscopy for secondary assessments and injection guidance.
Ambulatory Surgical Centers are expanding most quickly. Hospitals retain the deepest existing installed base.
Technology:
Technology segmentation tracks the shift from standalone hardware to software-integrated platforms with recurring licensing revenue.
- Robot-Assisted Surgery:Platforms integrate haptic feedback and preoperative planning into arthroscopic workflows. United States orthopedic groups are adopting these systems as first-line therapy for complex joint reconstruction expands.
- 3D Imaging:Stereoscopic visualization provides depth perception for instrument navigation in confined joint spaces.
- High-Definition Video:1080p and 4K resolution standards have become baseline requirements for new system purchases.
- Wireless Monitoring:Bluetooth-enabled pump sensors and camera heads reduce cable clutter in sterile fields.
Robot-Assisted Surgery is climbing the fastest. High-Definition Video holds baseline standard position.
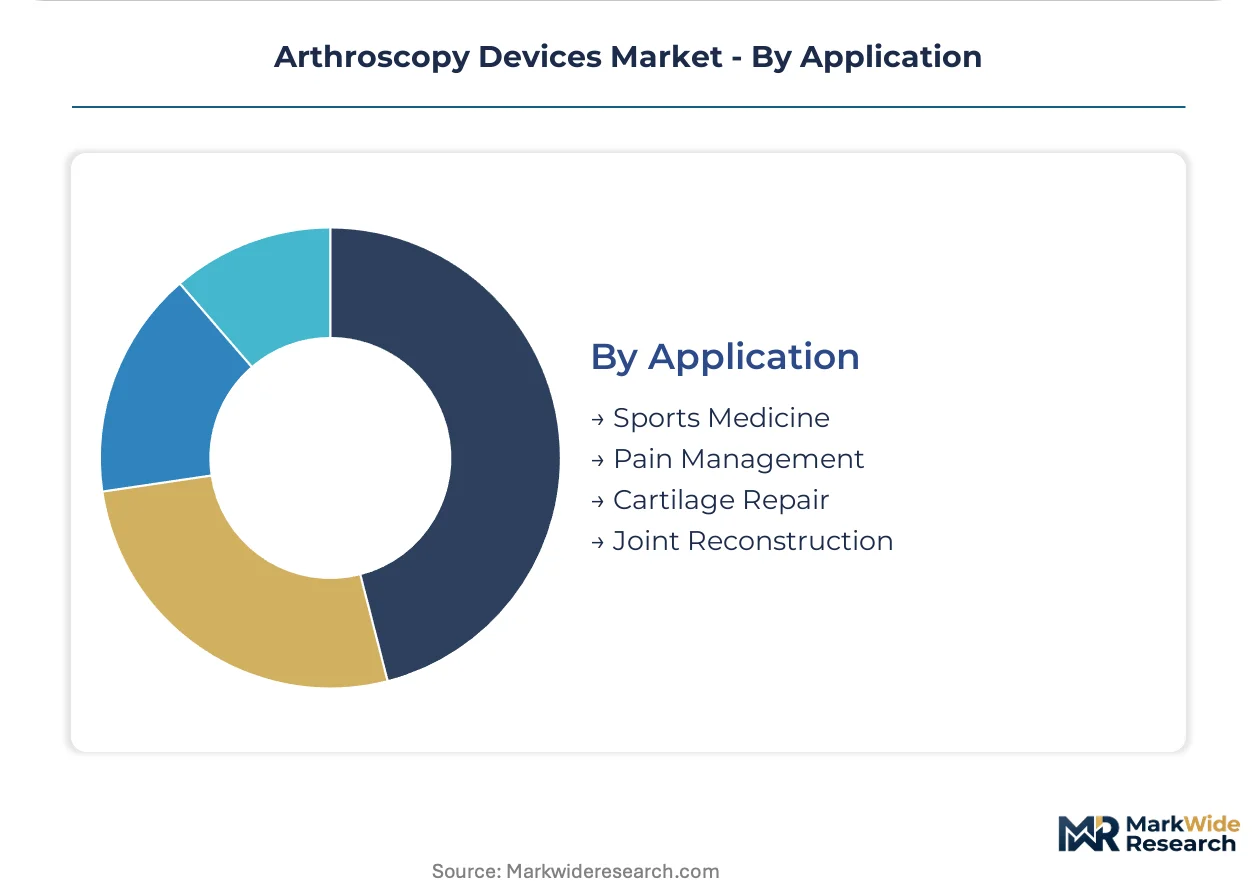
Application:
Application demand correlates with procedure reimbursement rates and patient demographic expansion.
- Sports Medicine:Youth and professional athletic injury treatment protocols standardize arthroscopic intervention as first-line therapy. United States sports medicine volumes drive shaver and visualization system placement through dedicated orthopedic service lines.
- Joint Reconstruction:Ligament repair and meniscal procedures require advanced visualization for anatomic restoration.
- Cartilage Repair:Microfracture and autologous chondrocyte implantation procedures utilize specialized instrumentation sets.
- Pain Management:Diagnostic arthroscopy and injection procedures address osteoarthritis progression in aging populations.
Sports Medicine commands premium equipment allocation. Joint Reconstruction is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German and Japanese optical component manufacturers supply precision lens assemblies to United States arthroscopy system integrators, creating a trans-Pacific trade corridor that concentrates high-value visualization technology flows.
United States
CMS site-of-service payment differentials accelerate ASC infrastructure investment across Texas and Florida, where independent surgery centers lease bundled arthroscopy suites. FDA 510(k) premarket notification governs device clearance timelines for visualization system introductions. The Dallas-Fort Worth metroplex anchors orthopedic service line expansion as hospital-ASC joint ventures concentrate capital deployment.
Germany
EU MDR technical documentation and post-market surveillance obligations extend certification cycles for European market access, compressing product development timelines for visualization OEMs. ISO 13485 quality management standards shape supplier qualification across the instrument supply base. The Baden-Württemberg region hosts precision optical manufacturers supplying critical endoscope glass to global arthroscopy device producers.
Japan
PMDA regulatory pathways govern medical device approvals while METI industrial policy supports domestic manufacturing of high-resolution imaging components. Japanese lens manufacturers control critical supply positions for arthroscope optics. The Kanto region around Tokyo concentrates medical device R&D clusters developing next-generation visualization platforms.
India
Private hospital chains deploy arthroscopy suites in tier-2 cities where joint procedure penetration remains below metropolitan benchmarks. CDSCO regulates medical device imports and domestic manufacturing under evolving notification requirements. Maharashtra's Mumbai-Pune corridor anchors orthopedic infrastructure buildout as domestic and multinational device vendors establish distribution networks.
China
NMPA medical device registration requirements structure market entry pathways for foreign arthroscopy system manufacturers seeking domestic sales authorization. The Yangtze River Delta region concentrates medical device manufacturing clusters producing components for both domestic consumption and export assembly. Shanghai-based distributors manage import channels for premium visualization equipment serving tier-1 hospital orthopedic departments.
Arthroscopy Devices Market Key Industry Players
Listed leaders compete with private specialists across visualization platform development, creating a tiered competitive structure where capital access and R&D scale separate strategic positions. The vendor base organizes around three archetypes: diversified medtech conglomerates with broad operating room ecosystems, pure-play orthopedic specialists with vertically integrated sports medicine portfolios, and optical technology firms leveraging imaging expertise into surgical applications. M&A activity concentrates on consumable revenue stream acquisition, while strategic partnerships between device manufacturers and ASC management companies reshape distribution channel control.
Within the pure-play orthopedic tier, Arthrex and Smith & Nephew exemplify positioning built around sports medicine channel dominance and wound repair adjacencies respectively. Stryker represents the diversified conglomerate archetype with ecosystem lock-in strategies spanning capital equipment and consumable pull-through. These three anchors illustrate how competitive advantage in arthroscopy devices flows from either specialized vertical focus or horizontal operating room integration rather than intermediate positioning.
| Leading Market Players |
|---|
| Arthrex |
| Stryker |
| Smith & Nephew |
| Johnson & Johnson |
| Zimmer Biomet |
| Conmed |
| Medtronic |
| Karl Storz |
| Olympus |
| Others |
Cost & Logistics Intelligence
LED cold-light illumination modules displacing xenon arc lamp assemblies simultaneously shift procurement geography toward Japanese and German optical component clusters while compressing visualization system price points across premium tiers. This substitution dynamic restructures supplier qualification timelines as ISO 13485 validation requirements extend for solid-state illumination subsystems.
Pricing Analysis
4K visualization platforms command substantial premiums over standard-definition installed base systems, while emerging 3D modalities price at further elevation above 4K tiers. Pricing stratifies across premium, standard, and economy tiers where resolution specifications, FDA 510(k) clearance status, and bundled service agreements drive differentiation. Cost compression in standard-definition tiers is intensifying because ASC lease structures prioritize monthly payment minimization over capital durability. Independent surgery centers exhibit highest price sensitivity, whereas integrated delivery networks prioritize ecosystem compatibility.
Supply Chain Analysis
Strategic stockpile preferences dominate arthroscope lens inventory management as German and Japanese optical manufacturers maintain 12-18 month order backlogs for precision glass assemblies. Supply concentrates in Baden-Württemberg for endoscope optics and Kanto region for sensor modules, with raw material dependencies spanning rare-earth phosphors, sapphire lens substrates, and surgical-grade stainless steel. Single-source vulnerability around German lens manufacturers creates structural risk exposure. Distribution runs through vendor-managed service agreements that bundle equipment leasing with consumable replenishment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The arthroscopy device market sits within a cyclical recovery phase as deferred visualization system replacements from hospital capital budget freezes now release through ASC infrastructure buildout.
For Market Incumbents: Compound installed base lock-in through backward integration into disposable shaver blade manufacturing and software companion development for preoperative planning. Threat exposure from robot-assisted surgery platforms demands defensive patent portfolio expansion around haptic feedback interfaces. Capacity addition in Texas and Florida ASC corridors secures channel control against emerging pure-play competitors.
For New Entrants and Emerging Players: Lead with India tier-2 city private hospital chains where arthroscopy suite penetration remains below metropolitan benchmarks and multinational vendor presence thins. Disposable fluid management tubing offers the most penetrable consumable entry point given reprocessing liability elimination. Direct-to-ASC equipment financing partnerships bypass traditional hospital procurement committee gatekeeping.
For Investors and Strategic Acquirers: Capital is best deployed toward optical technology specialists with captive lens grinding capabilities and established FDA 510(k) submission track records. Long-term viability across the analysis window favors vendors controlling both visualization hardware and procedure-specific software workflows. Watch CMS site-of-service reimbursement parity adjustments as the critical inflection signal for ASC capital deployment velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR technical documentation investments determine European market access timelines for visualization OEMs. |
| Hospital System Partnership | Joint venture structures with Texas and Florida ASC networks concentrate purchasing authority with clinical directors. |
| Software Companion Development | Preoperative planning modules differentiate robot-assisted platforms from standalone capital equipment offerings. |
| Reimbursement Strategy | CMS site-of-service parity alignment determines capital deployment priority between hospital and ASC settings. |
| FDA Submission | 510(k) premarket notification pathways compress time-to-market for 4K camera head introductions. |
Research Approach
Operator-level perspectives from orthopedic surgeons, ASC clinical directors, biomedical engineers, and GPO contracts managers anchored the qualitative base. Primary interviews combined with secondary validation against FDA 510(k) filings, CMS Medicare reimbursement databases, hospital procurement records, and EU MDR notified body documentation. Bottom-up procedure volume modeling and top-down equipment shipment analysis provided triangulation across the analysis window.
Sensitivity analysis tested forecast outputs against variations in ASC migration velocity, EU MDR certification timeline extensions, and optical component supply disruptions. Segmentation dimensions spanned product type, end-user setting, technology generation, and application area throughout the forecast period. CAGRs derived from equipment replacement cycle compression rates and consumable pull-through coefficients tied to sports medicine procedure expansion.
The analysis sits within stated boundaries; outcomes outside sustained CMS reimbursement parity, stable German-Japanese optical supply corridors, or FDA 510(k) pathway consistency would require recalibration. Revision becomes warranted when EU MDR post-market surveillance obligations trigger portfolio-wide compliance re-engineering costs.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Surgical Microscopes Market
Medical Devices
Brazil Drug Delivery Devices Market
Medical Devices
Biological Microscope Market
Medical Devices
Kirschner Wires Market
Medical Devices
Europe Ambulatory Infusion Pumps Market
Medical Devices
Global Cardiac Pacemakers Market
Medical Devices
Intravenous Line Connectors Market
Medical Devices
United Kingdom Drug Delivery Devices Market
Medical Devices
Italy Medical Device Regulatory Affairs Market
Medical Devices
Germanium-68/Gallium-68 Generators Market
Medical Devices
Asia-Pacific Smart Medical Devices Market
Medical Devices
Veterinary Radiography Flat Panel Detectors Market
Medical Devices
Pen Injectors Market
Medical Devices
Pelvic Reconstruction Market
Medical Devices
Wearable Medical Robots Market
Medical Devices
Sinus Dilation Devices Market