
 Hip Replacement Market | 2026-2036
Hip Replacement Market Size, Share, and Industry Trends Forecast 2026-2036
Hip Replacement Market Analysis
3D-printed acetabular cups and patient-specific instrumentation is rewriting surgical workflows across the hip replacement landscape. Zimmer Biomet leverages additive manufacturing capabilities to produce porous titanium structures that improve osseointegration. Stryker anchors its position through proprietary robotic-arm assisted platforms that integrate preoperative planning with intraoperative navigation. Smith & Nephew competes in the resurfacing niche with metal-on-metal bearings designed for younger, active patient cohorts.
Hip replacement denotes the surgical implantation of a prosthetic ball-and-socket joint, typically comprising a cobalt-chromium femoral head articulating against a ultra-high molecular weight polyethylene acetabular liner, to restore mobility in degenerated or fractured hip joints. Cemented implants retain dominant share among seniors with compromised bone quality, while uncemented implants command premium positioning for younger patients seeking longer wear life. Ambulatory surgical centers represent the fastest-growing end user channel as payors and patients gravitate toward lower-cost, shorter-stay alternatives to inpatient hospital admissions.
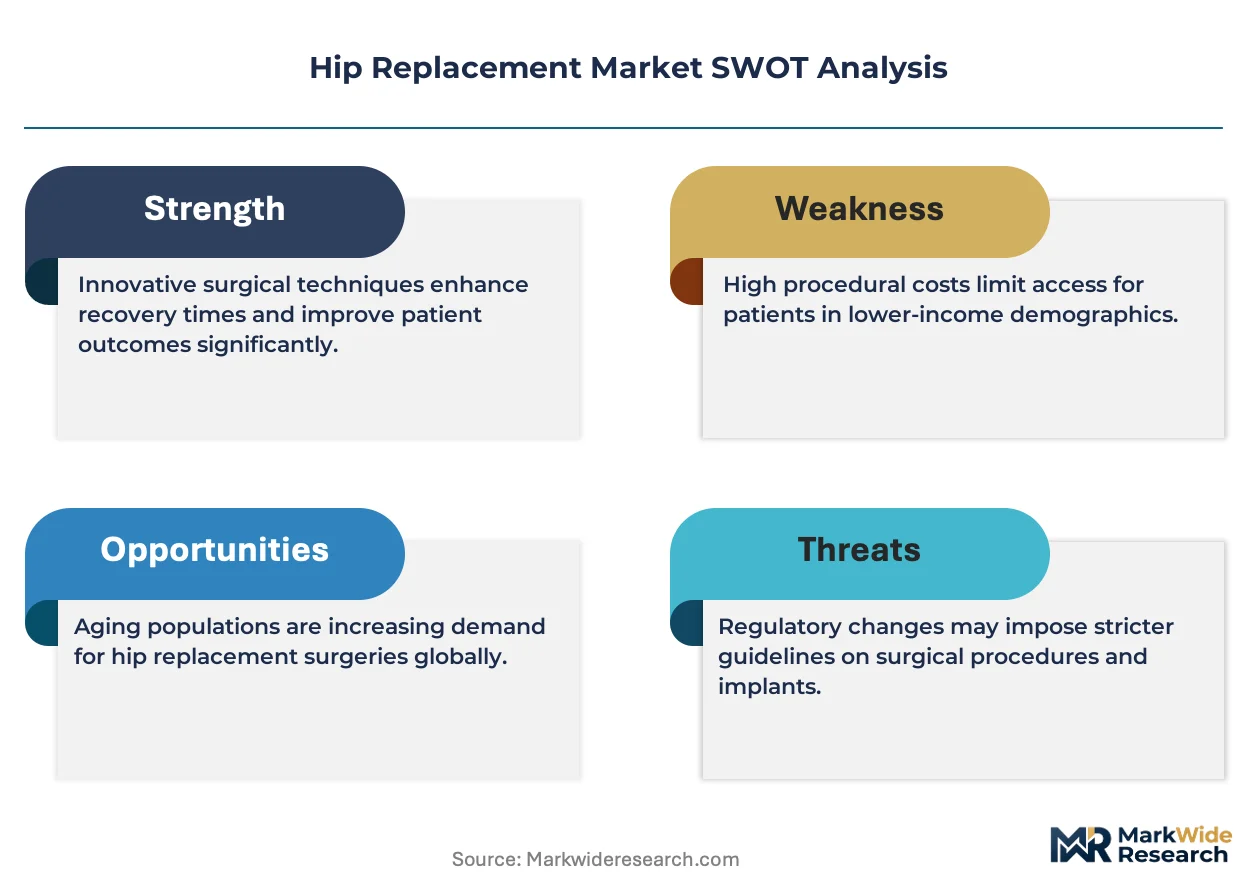
FDA 510(k) premarket notification and EU MDR conformity assessment govern device safety and clinical evidence requirements, while ISO 5832 materials standards dictate metallurgical purity thresholds for implantable alloys. These frameworks elevate barriers for new entrants and compel incumbents to maintain exhaustive design history files and post-market surveillance registries. Stakeholders must monitor evolving CMS reimbursement rules for outpatient total joint procedures and the trajectory of value-based care bundles that shift financial risk toward providers.
Market Dynamics
Same-day discharge protocols are compressing surgical workflows and forcing implant manufacturers to redesign instrumentation for ambulatory settings rather than traditional operating rooms. This structural shift is redistributing purchasing power from hospital systems to independent surgical centers.
Growth Catalysts
- FDA 510(k) Clearance Pathway:Streamlined premarket notification for substantially equivalent devices accelerates commercialization timelines for iterative implant designs. Orthopedic manufacturers leverage this route to introduce enhanced bearing surfaces without prolonged clinical trials.
- Ambulatory Surgical Centers:CMS reimbursement expansion for outpatient total hip arthroplasty pulls procedures away from inpatient facilities. These centers now account for the fastest-growing implant procurement channel in the United States.
- Patient-Specific Instrumentation:Preoperative CT-derived cutting guides reduce operative time and improve component alignment. Adoption concentrates among high-volume orthopedic groups seeking operational efficiency gains.
Market Restraints
- Cobalt-Chromium Alloy Supply Concentration:Metallurgical-grade cobalt sourcing depends on a limited supplier base concentrated in Central African mining operations. Price volatility in this input stream compresses margin predictability for femoral head manufacturers.
- EU MDR Conformity Assessment:Stricter clinical evidence requirements for Class III implantable devices extend certification timelines. Notified body capacity constraints create multi-year backlogs for hip replacement system approvals.
- Metal-on-Metal Bearing Retreat:Adverse local tissue reactions and revision surgery clusters have eroded surgeon confidence. This substitute technology now occupies a marginal niche despite earlier promise for younger patients.
Strategic Opportunities
- Japan's Super-Aged Society:The world's highest elderly dependency ratio creates sustained demand for revision implants and fracture-management stems. Domestic reimbursement policies favor cemented fixation systems for this demographic profile.
- Digital Surgery Ecosystems:Convergence of preoperative planning software with intraoperative navigation platforms enables subscription-based revenue models. Hardware vendors capture recurring service fees alongside capital equipment sales.
- Germany's Outpatient Care Reform:Federal legislation expanding same-day surgery eligibility for joint replacement creates procurement opportunities for streamlined instrument sets designed for non-hospital settings.
Industry Challenges
- Biocompatibility Testing Backlogs:ISO 5832 materials standard compliance requires extensive cytotoxicity and sensitization assays. Contract laboratory capacity constraints delay product launch schedules.
- Robotic-Assisted Surgery Integration:Capital-intensive platform adoption demands substantial training investments and workflow redesign. Smaller orthopedic practices struggle to justify per-procedure disposable costs against case volume.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hip Replacement Market |
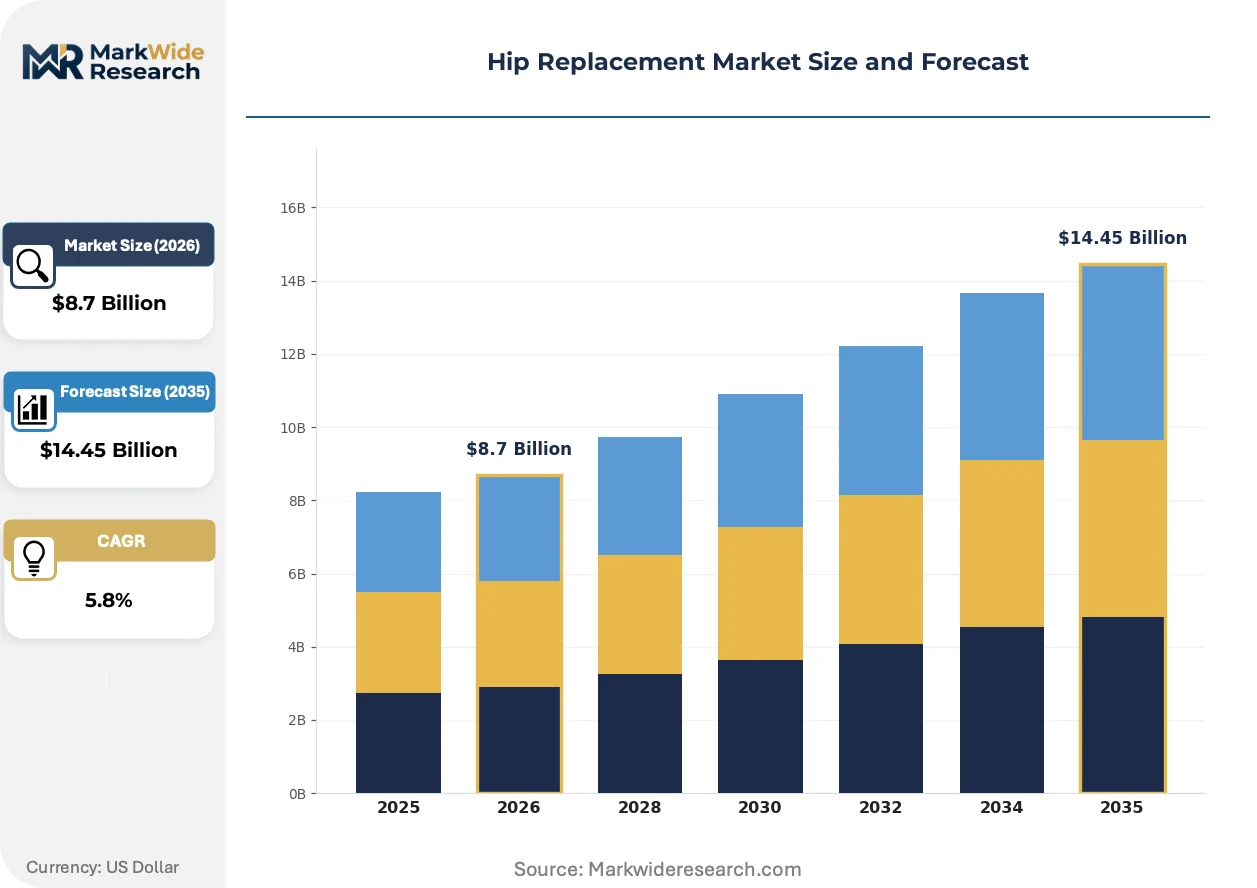
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cemented Implants, Uncemented Implants, Hybrid Implants, Resurfacing Implants End User: Hospitals, Ambulatory Surgical Centers, Orthopedic Clinics, Rehabilitation Centers Material: Titanium, Stainless Steel, Cobalt-Chromium, Polyethylene Age Group: Adults, Seniors, Middle-Aged, Pediatric |
| Companies Covered | Zimmer Biomet, DePuy Synthes, Stryker, Smith & Nephew, Johnson & Johnson, MicroPort Scientific Corporation, B. Braun Melsungen AG, Exactech, Conformis, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hip Replacement Market Emerging Trajectories
Additive manufacturing and intelligent instrumentation are converging to personalize hip replacement workflows. These developments compress operative variability while elevating biocompatibility standards for implantable alloys.
3D-printed porous titanium acetabular shells are migrating from research applications to standard-of-care adoption in academic medical centers. These structures facilitate direct bone ingrowth without cement fixation. High-volume orthopedic service lines in Germany and the United States now specify additive-manufactured components for complex revision cases. The technology is migrating from niche applications toward mainstream primary arthroplasty as printing economics improve and regulatory dossiers mature.
EU MDR post-market surveillance requirements mandate systematic implant registry participation and periodic safety update reports. Device manufacturers must maintain exhaustive design history files and clinical follow-up data. Hip replacement systems with longer commercial track records face lower compliance burdens than novel bearing couples, advantaging established product portfolios over experimental materials.
Surgeon ownership in ambulatory surgery facilities is reshaping implant procurement authority. Physician-investors prioritize instrument standardization and vendor consolidation to minimize sterilization costs and implant inventory. This concentration is most visible in the United States, where the Stark Law self-referral framework permits ownership stakes in same-day surgical centers performing joint replacement procedures.
Hip Replacement Market Segmentation
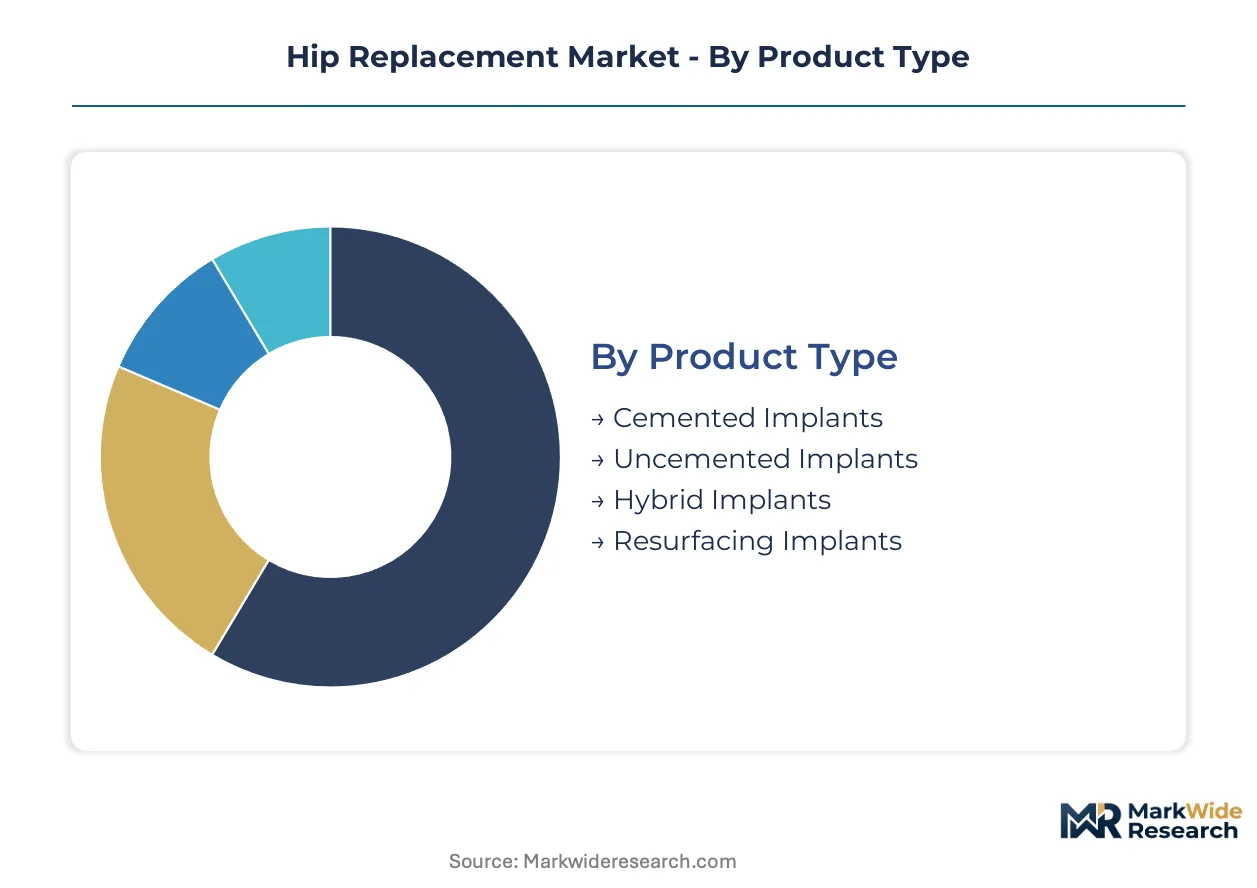
Hip replacement segmentation reveals distinct procurement patterns across fixation philosophies, care settings, metallurgical specifications, and patient demographics. Manufacturers calibrate product portfolios to match reimbursement pathways and surgical workflow requirements in each category.
Product Type:
Use-case spectrum spans elderly patients with compromised bone stock requiring immediate mechanical stability to younger cohorts prioritizing long-term osseointegration and revision flexibility.
- Cemented Implants:Polymethylmethacrylate bone cement provides immediate fixation for femoral stems in osteoporotic bone. Demand concentrates in Japan's super-aged population where domestic reimbursement favors cemented systems for seniors with compromised bone quality.
- Uncemented Implants:Porous-coated titanium or cobalt-chromium surfaces enable biological bone ingrowth without cement. Germany's high-volume orthopedic centers specify these for middle-aged patients seeking extended implant longevity and future revision options.
- Hybrid Implants:Combines cemented femoral stem with uncemented acetabular component.
- Resurfacing Implants:Conservative bone-preserving option for younger, active patients; metal-on-metal bearing retreat has constrained adoption.
Established volume favors cemented fixation; emerging adoption favors uncemented porous-coated designs.
End User:
Cost tier stratification separates capital-intensive hospital systems from lean ambulatory operators seeking instrument standardization.
- Hospitals:Comprehensive inpatient facilities manage complex revision cases and comorbid patients requiring extended monitoring. United States hospital systems retain purchasing power for premium robotic-assisted platforms and specialized revision instrumentation.
- Ambulatory Surgical Centers:Same-day discharge protocols compress surgical workflows and force implant manufacturers to redesign instrument sets for non-hospital settings. CMS reimbursement expansion for outpatient total hip arthroplasty is climbing the fastest in procurement volume among United States channels.
- Orthopedic Clinics:Physician-owned specialty practices concentrate preoperative planning and postoperative rehabilitation.
- Rehabilitation Centers:Post-acute facilities manage recovery protocols and functional outcome monitoring.
Procurement authority is migrating from hospital materials management to surgeon-investors in ambulatory facilities.
Material:
Application requirements dictate metallurgical selection based on wear characteristics, biocompatibility profiles, and imaging compatibility.
- Titanium:Excellent biocompatibility and modulus of elasticity matching cortical bone reduces stress shielding. Additive manufacturing adoption in Germany and United States academic centers specifies porous titanium for complex acetabular revisions.
- Cobalt-Chromium:Superior wear resistance for femoral heads articulating against polyethylene liners. Supply concentration in Central African mining operations creates margin pressure for manufacturers dependent on metallurgical-grade feedstock.
- Stainless Steel:Cost-effective option for temporary fracture fixation components and provisional implants.
- Polyethylene:Ultra-high molecular weight formulations dominate acetabular bearing surfaces; cross-linked variants reduce wear debris generation.
Volume leadership sits with cobalt-chromium alloys; technology investment flows toward additive-manufactured titanium architectures.
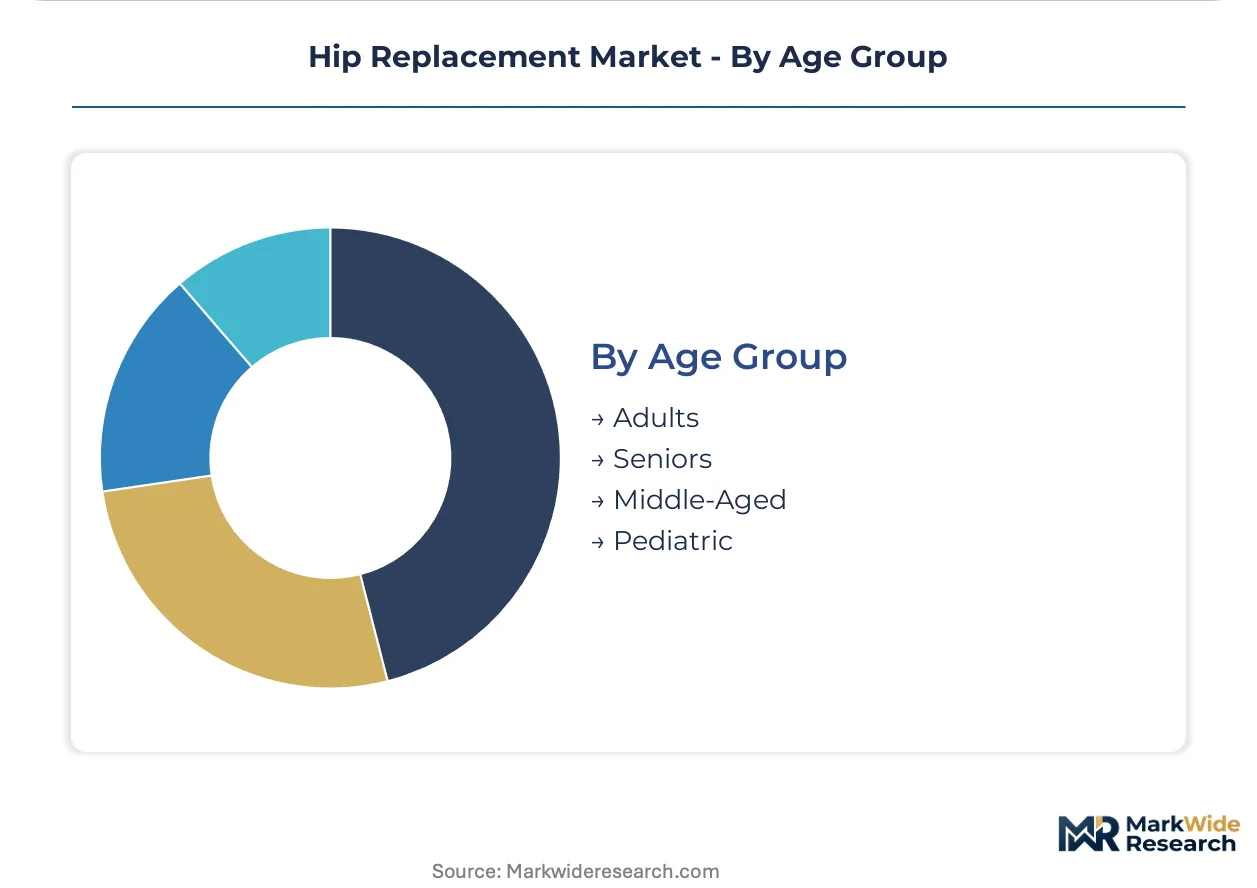
Age Group:
Customer type segmentation aligns implant selection with bone quality, activity demands, and revision probability over remaining lifespan.
- Seniors:Patients over 75 years with osteoporotic bone and limited activity requirements prioritize immediate stability. Japan's demographic profile generates sustained demand for cemented stems and fracture-management implants in this cohort.
- Middle-Aged:Patients 45-65 years with degenerative joint disease seek balance between durability and bone preservation. United States and German markets show expanding adoption of uncemented fixation and ceramic-bearing couples in this segment.
- Adults:Younger patients under 45 with traumatic or congenital indications.
- Pediatric:Rare applications for developmental dysplasia and juvenile arthritis requiring specialized small-geometry implants.
Procedure volume concentrates in seniors; technology innovation targets middle-aged candidates for long-term implant survival.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement departments in Germany and surgeon-investors in United States ambulatory centers represent the dominant buyer archetypes. Japan's super-aged demographic generates sustained revision implant demand. China's domestic manufacturers are capturing share in tier-two cities.
United States
CMS reimbursement expansion for outpatient total hip arthroplasty is accelerating same-day discharge protocols. FDA 510(k) clearance pathways streamline commercialization for iterative bearing surface designs. High-volume orthopedic groups in Florida and Texas are consolidating implant procurement authority through physician-owned ambulatory surgery centers.
Germany
Federal legislation expanding same-day surgery eligibility is creating procurement opportunities for streamlined instrument sets. EU MDR conformity assessment requirements mandate systematic implant registry participation. Academic medical centers in Bavaria and North Rhine-Westphalia specify additive-manufactured porous titanium for complex revision cases.
Japan
The world's highest elderly dependency ratio sustains demand for cemented fixation systems and fracture-management stems. PMDA regulatory frameworks govern biocompatibility testing standards for implantable alloys. Domestic reimbursement policies favor cemented stems for seniors with compromised bone quality in Tokyo and Osaka metropolitan clusters.
China
NMPA regulatory pathways are maturing for domestically manufactured joint replacement systems. Volume-based procurement reforms in provincial healthcare systems are compressing implant pricing tiers. Domestic manufacturers in Beijing-Tianjin-Hebei and Yangtze River Delta regions are expanding production capacity for standard primary arthroplasty components.
United Kingdom
NHS England value-based care bundles are shifting financial risk toward orthopedic providers and implant suppliers. MHRA post-Brexit regulatory frameworks maintain alignment with EU MDR clinical evidence standards. Teaching hospitals in London and the Midlands are piloting robotic-assisted surgery platforms with subscription-based service models.
Hip Replacement Market Vendor Landscape
Channel-controlling players compete with product-specialist players across fragmented procurement authority. The vendor base organizes around three strategic archetypes: diversified orthopedic conglomerates with full portfolio coverage, mid-scale specialists in bearing surface innovation, and regional challengers serving price-sensitive markets. M&A activity concentrates on robotic navigation platform acquisitions and additive manufacturing capability builds. Geographic expansion into China's provincial procurement systems represents a second competitive vector.
Among diversified orthopedic conglomerates, Zimmer Biomet and Stryker occupy positions exemplifying scale-driven portfolio breadth, while Smith & Nephew represents specialization in niche bearing configurations. DePuy Synthes anchors the Johnson & Johnson medical device segment with integrated trauma and joint reconstruction capabilities. MicroPort Scientific Corporation exemplifies the regional challenger archetype with China-centric manufacturing and domestic regulatory expertise. B. Braun Melsungen AG represents European-rooted diversification across anesthesia, surgery, and orthopedics with integrated hospital supply chain relationships.
| Leading Market Players |
|---|
| Zimmer Biomet |
| DePuy Synthes |
| Stryker |
| Smith & Nephew |
| Johnson & Johnson |
| MicroPort Scientific Corporation |
| B. Braun Melsungen AG |
| Exactech |
| Conformis |
| Others |
Supply Flow & Price Mechanics
Undercapacity in Central African cobalt refining is forcing femoral head manufacturers to absorb metallurgical-grade feedstock volatility while hospital procurement committees exploit fragmented supplier leverage. This utilization squeeze simultaneously elevates long-term contract premiums for implantable alloys and compresses margin buffers for mid-tier bearing surface producers.
Pricing Analysis
Cost-plus contracts with London Metal Exchange indexation dominate cobalt-chromium alloy procurement, locking manufacturers into pass-through arrangements that transfer commodity risk to device makers. Price differentiation hinges on ISO 5832 certification tier and surgical center volume scale, with premium robotic-compatible implants commanding substantial markups over standard primary arthroplasty systems. Pricing pressure stems from CMS reimbursement compression for outpatient procedures, eroding implant budget allocations. Ambulatory surgical centers exhibit highest price sensitivity, while academic medical centers prioritize bearing longevity over unit cost.
Supply Chain Analysis
Tariff exposure between Democratic Republic of Congo and Chinese processing facilities dominates metallurgical cobalt supply security, disrupting just-in-time alloy deliveries to European and North American forging operations. Supply concentrates in DRC extraction, Chinese refining, and German precision machining for final femoral head production. Raw material dependencies encompass cobalt ore, titanium sponge, and ultra-high molecular weight polyethylene resin. Single-source vulnerability pervades Central African mining concessions. Distribution runs through orthopedic GPOs and direct hospital contracting in the United States, with tender-based procurement prevailing in Germany and Japan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FDA 510(k) clearance acceleration for patient-specific instrumentation constitutes a regulatory inflection that is compressing commercialization timelines and elevating competitive velocity beyond traditional orthopedic innovation cycles.
For Market Incumbents: Insulate market position through backward integration into additive manufacturing feedstocks and captive cobalt-chromium forging capacity in Germany. Prioritize EU MDR design history file completeness to exploit notified body backlogs disadvantaging novel entrants. Cemented fixation system dominance in Japan represents a defensible revenue base against uncemented technology substitution. For New Entrants and Emerging Players: Mid-volume orthopedic service lines in United States ambulatory surgery centers represent the most penetrable entry point, as surgeon-investors seek instrument standardization alternatives to conglomerate bundling. China's provincial volume-based procurement systems offer second-mover advantages for domestically manufactured primary arthroplasty components. Go-to-market execution should emphasize disposable instrument set economics over capital platform sales. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among robotic navigation platform vendors with subscription-based service attachments. Long-term viability favors acquisition targets possessing additive manufacturing capabilities and mature regulatory dossiers under EU MDR or FDA 510(k) pathways. The signal to watch is CMS reimbursement expansion for outpatient total joint procedures, which would accelerate ambulatory center procurement authority migration.| Strategic Initiative | Industry Significance |
|---|---|
| Robotic Navigation Platform Acquisition | Stryker's MAKO integration demonstrates hardware-software convergence capturing recurring service fees. |
| Additive Manufacturing Capability Build | Zimmer Biomet's porous titanium shells reduce revision surgery rates through enhanced osseointegration. |
| EU MDR Certification Fast-Track | Expedited notified body engagement exploits multi-year approval backlogs constraining rival launches. |
| Ambulatory Surgery Center Partnership | Physician-investor instrument standardization demands favor consolidated vendor relationships. |
| Patient-Specific Instrumentation Development | CT-derived cutting guides reduce operative time and align with CMS outpatient reimbursement expansion. |
Methodological Framework
Initial hypotheses were tested against primary input from orthopedic surgeons, hospital purchasing committee directors, biomedical engineers, and GPO contracts managers and refined through secondary validation against FDA 510(k) filings, EU MDR notified body registers, CMS Medicare reimbursement databases, and orthopedic implant registry data. Bottom-up demand modeling across fixation types, end-user channels, and metallurgical specifications was cross-checked against top-down market sizing from manufacturer revenue disclosures and trade flow analysis.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, with segmentation dimensions spanning cemented versus uncemented fixation philosophies, hospital versus ambulatory surgical center procurement channels, and cobalt-chromium versus titanium material specifications. CAGRs were derived from procedure volume growth trajectories, implant price elasticity assumptions, and technology substitution curves for robotic-assisted and patient-specific workflows. Forecast inputs incorporated aging demographic projections, reimbursement policy trajectories, and regulatory approval pipeline visibility.
Practitioners should monitor EU MDR notified body capacity expansion, CMS outpatient procedure reimbursement rulings, and Central African cobalt supply disruptions for early signals of forecast deviation. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Orthopedic Devices
India Spinal Surgery Devices Market
Orthopedic Devices
Spine Devices Market
Orthopedic Devices
Prosthetics and Orthotics Market
Orthopedic Devices
Middle East and Africa Knee Cartilage Repair Market
Orthopedic Devices
South Korea Spinal Surgery Devices Market
Orthopedic Devices
Spinal Pumps Market
Orthopedic Devices
Knee Cartilage Repair Market
Orthopedic Devices
Global Total Ankle Replacement Market
Orthopedic Devices
Veterinary Prosthetics and Orthotics Market
Orthopedic Devices
Orthopedic Pedicle Screw Market
Orthopedic Devices
Shoulder Arthroplasty Market
Orthopedic Devices
Global Total Knee Replacement Market
Orthopedic Devices
Closed Heel Nursing Shoes Market
Orthopedic Devices
Adult Orthopedic Insole Market
Orthopedic Devices
Orthopedic Prosthetic Devices Market
Orthopedic Devices
Distal Compression Plates Market