
 Global Neurovascular Guidewires Market | 2026-2036
Global Neurovascular Guidewires Market Size, Share, and Industry Trends Forecast 2026-2036
Global Neurovascular Guidewires Market Foresight
Hospital procurement consortiums in the United States and Germany are reconfiguring vendor qualification criteria around single-use sterility assurance and real-time supply chain visibility. Medtronic leverages its integrated neurovascular portfolio to secure multi-year cath-lab contracts. Boston Scientific Corporation anchors its position through R&D intensity in steerable-tip architectures. Terumo Corporation competes on manufacturing scale across its Japanese and European production nodes.
Neurovascular guidewires are slender, torque-responsive instruments typically 0.010–0.035 inches in diameter, constructed from nitinol or stainless-steel cores with polymer jackets and hydrophilic coatings, designed to navigate cerebral vasculature and deliver microcatheters or implants to aneurysm and stroke sites. Torqueable guidewires dominate procedural volume due to their indispensability in tortuous intracranial anatomy, while specialty guidewires command premium positioning in flow-diversion and thrombectomy workflows. Nitinol-based platforms represent the fastest-growing material category, displacing stainless steel in centers prioritizing shape memory and kink resistance during submillimeter vessel traversal.
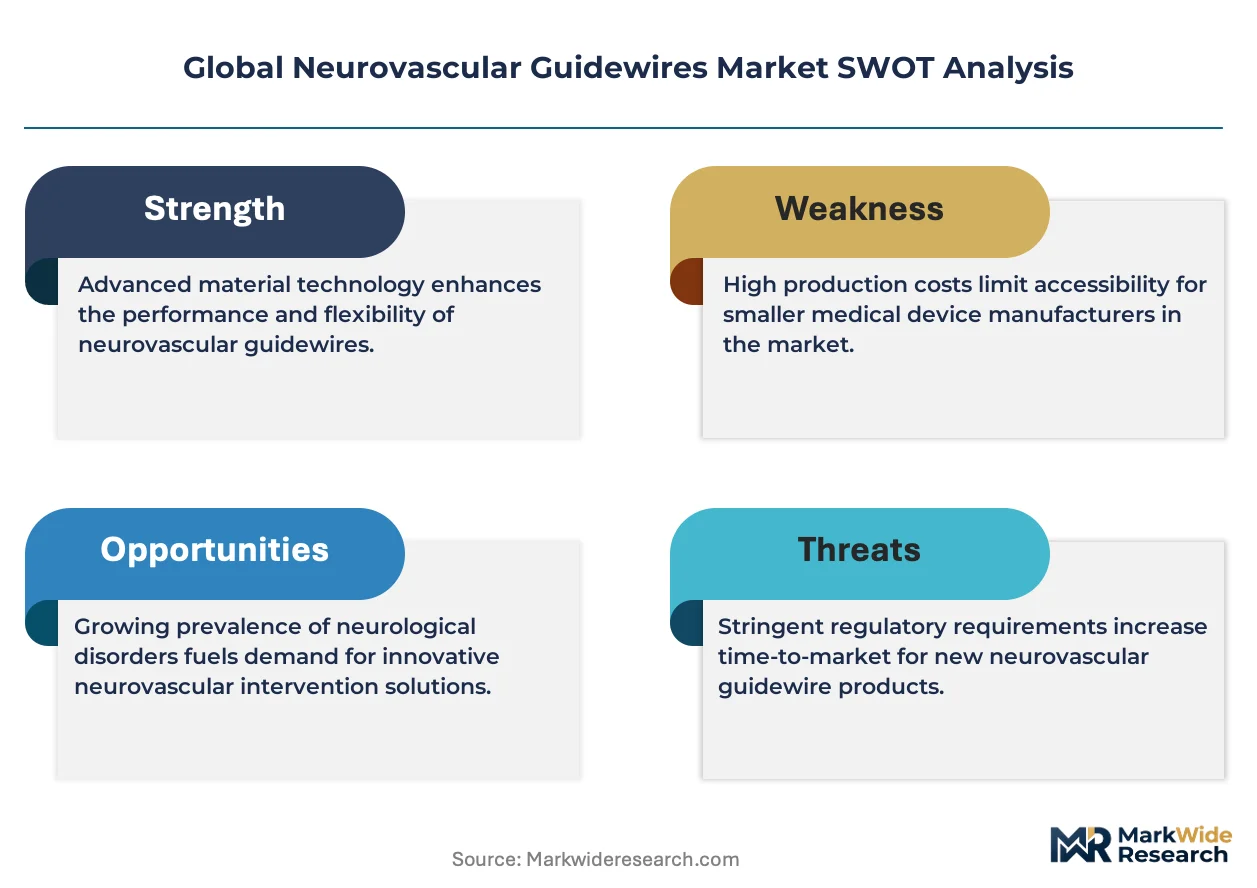
FDA 510(k) clearance pathways and EU MDR conformity requirements shape product development timelines and clinical evidence burdens for manufacturers seeking market access in the United States and European Union. Japan's PMDA and China's NMPA enforce distinct biocompatibility and labeling standards that fragment regulatory strategy across East Asian commercialization efforts. Stakeholders must monitor evolving notified-body capacity under EU MDR and FDA digital-health integration guidance as robotic-assisted neurointervention platforms begin demanding guidewire-electronics compatibility specifications.
Market Dynamics
Hospital procurement consortiums in the United States and Germany are consolidating vendor panels around single-use sterility assurance and real-time supply chain visibility, compressing the number of qualified guidewire suppliers while elevating technical specification requirements for nitinol-core torqueability and hydrophilic polymer coatings.
Growth Catalysts
- EU MDR conformity requirements:Stricter biocompatibility and clinical evidence standards under the Medical Device Regulation are accelerating replacement cycles for legacy stainless-steel platforms across German and French stroke centers.
- Robotic-assisted neurointervention:Integration demands for guidewire-electronics compatibility specifications are pulling advanced nitinol platforms into tertiary hospitals with dedicated cath labs in Japan and the United States.
- Thrombectomy workflow standardization:American Heart Association stroke guidelines emphasizing rapid mechanical thrombectomy are expanding catheter-based intervention volumes at certified comprehensive stroke centers nationwide.
Market Restraints
- Nitinol raw material concentration:Superelastic nickel-titanium alloy supply concentrates among a limited set of specialized metallurgical processors, exposing manufacturers to input cost volatility and geopolitical supply disruption.
- FDA 510(k) clinical evidence burdens:Substantial equivalence demonstrations for novel hydrophilic coatings or core geometries extend product development timelines and elevate regulatory compliance costs for market entrants.
- Reprocessed single-use alternatives:Emerging third-party reprocessing services for peripheral guidewires present potential substitution pressure as hospital cost-containment intensifies, though neurovascular applications remain restricted by sterility risk tolerance.
Strategic Opportunities
- India's underserved stroke infrastructure:Underpenetrated neurointervention capacity outside metropolitan tertiary centers creates white space for simplified guidewire platforms adapted to emerging cath-lab environments.
- Flow-diversion procedure expansion:Growing adoption of pipeline embolization devices for complex aneurysms is generating demand for specialty guidewires with enhanced distal flexibility and torque transmission.
- Japan PMDA fast-track pathways:Sakigake designation and conditional early approval frameworks for breakthrough medical devices offer regulatory tailwinds for manufacturers prioritizing Japanese commercialization timelines.
Industry Challenges
- Neurointerventionalist training pipelines:Procedural complexity and extended fellowship requirements constrain the supply of qualified operators capable of maximizing advanced guidewire capabilities in tortuous intracranial anatomy.
- EU MDR notified-body capacity constraints:Bottlenecks in conformity assessment organization availability are extending certification timelines and compressing product launch windows for European market access.
- Legacy cath-lab equipment integration:Compatibility verification with installed-base angiography systems and robotic platforms demands additional engineering resources and delays adoption at cost-constrained facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Neurovascular Guidewires Market |
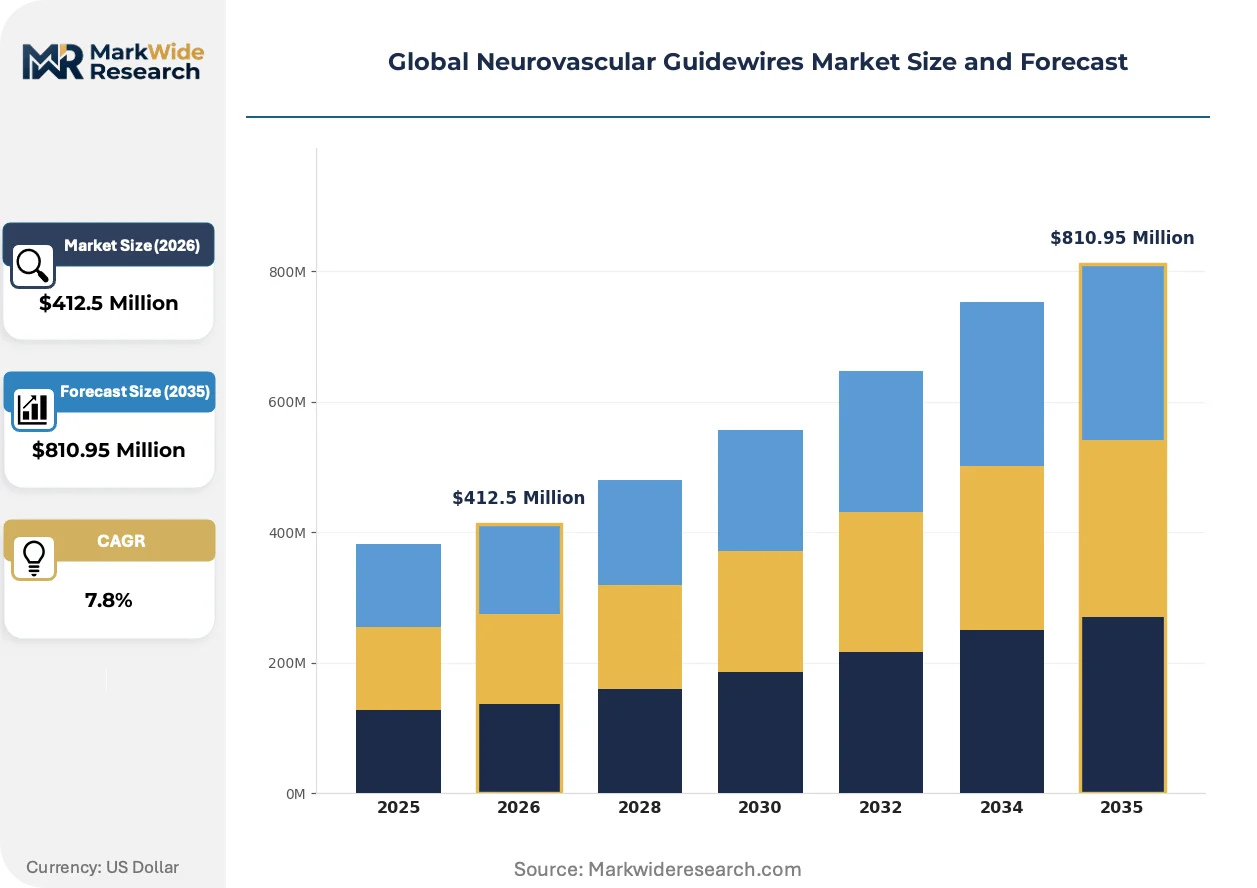
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $810.95 Million |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Torqueable Guidewires, Non-Torqueable Guidewires, Microcatheters, Specialty Guidewires Application: Neurosurgery, Interventional Radiology, Peripheral Vascular Intervention, Cardiovascular Procedures End User: Hospitals, Clinics, Ambulatory Surgical Centers, Specialized Healthcare Facilities Material: Stainless Steel, Nitinol, Polymer, PTFE |
| Companies Covered | Medtronic, Boston Scientific Corporation, Stryker Corporation, Terumo Corporation, Asahi Intecc, Johnson & Johnson, Penumbra, Cook Medical, Cardinal Health, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Neurovascular Guidewires Market Shifts & Advancements
Sensor-integrated guidewire architectures and AI-assisted navigation algorithms are converging to reshape procedural workflows, while regulatory frameworks on both sides of the Atlantic accelerate evidence-generation requirements for next-generation platforms.
Shape-memory nitinol cores with embedded fiber-optic pressure sensors are digitizing real-time vessel-wall feedback during submillimeter navigation, enabling operators to map tortuous cerebral anatomy without contrast injection. Academic medical centers in Germany and Japan are piloting these platforms for complex aneurysm approaches. The structural consequence is compressing reliance on traditional fluoroscopic guidance and reducing radiation exposure per procedure.
EU MDR Annex XIV post-market surveillance requirements are mandating systematic clinical follow-up data collection for implantable neurovascular devices, extending evidence obligations to accessory guidewires used in delivery workflows. Manufacturers must now maintain proactive vigilance systems and periodic safety update reporting across their entire neurovascular portfolios. High-volume stroke centers in France and the Netherlands are experiencing the most pronounced documentation burden as they integrate these systems.
Consolidated purchasing through regional health system alliances is displacing traditional distributor relationships in the United States, with IDNs negotiating directly for multi-year cath-lab supply commitments. Specialty guidewire vendors face margin compression as procurement teams centralize vendor qualification and demand volume-based pricing transparency. This behavioral shift is most visible across the southeastern and midwestern hospital networks where stroke center certification expansions are concentrating buying power.
Global Neurovascular Guidewires Market Segmentation
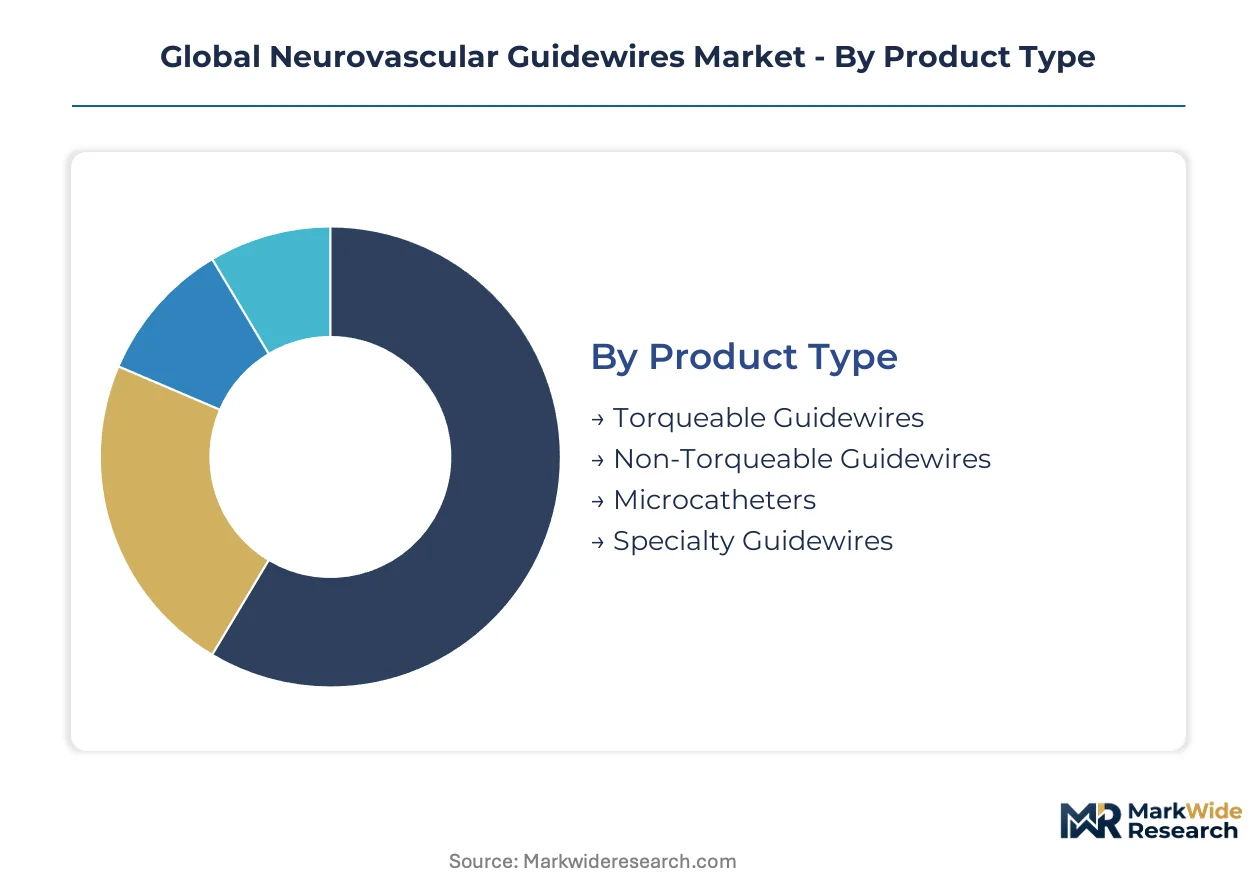
Neurovascular guidewire procurement cycles vary sharply across product tiers and clinical settings. Understanding these velocity differentials helps manufacturers align inventory positioning with replacement demand and margin capture.
Product Type:
Torqueable platforms turn over fastest in high-volume stroke centers, while specialty configurations persist longest in low-utilization settings.
- Torqueable Guidewires:Nitinol-core construction with hydrophilic polymer jackets delivers the torque response required for submillimeter cerebral navigation. Demand concentrates at certified comprehensive stroke centers in the United States and Germany where mechanical thrombectomy volumes strain instrument durability.
- Specialty Guidewires:Architectures optimized for flow-diversion delivery and aneurysm neck crossing command extended sterilization cycles and premium unit economics. Japanese tertiary hospitals with dedicated neurovascular labs anchor procurement for these platforms.
- Non-Torqueable Guidewires:Legacy stainless-steel designs retain position in cost-constrained emerging markets with simpler lesion morphologies.
- Microcatheters:Delivery systems for coil embolization and stent deployment, typically procured alongside matched guidewire platforms.
Torqueable guidewires anchor the volume base while specialty guidewires gain share at the steepest rate.
Application:
Procedure reimbursement intensity and clinical outcome accountability create divergent specification requirements across surgical and interventional domains.
- Neurosurgery:Open surgical approaches demand robust proximal torque transmission for macrovascular access, with procurement concentrated at academic medical centers in France and the United States.
- Interventional Radiology:Minimally invasive workflows prioritize distal flexibility and radiopacity for fluoroscopic visualization.
- Peripheral Vascular Intervention:Crossover utilization for carotid and vertebral access drives demand for longer-length configurations.
- Cardiovascular Procedures:Limited neurovascular crossover applications in hybrid cath-lab environments.
Interventional radiology applications generate the highest unit velocity while neurosurgery maintains the most stable procurement cadence.
End User:
Capital equipment availability and case-mix complexity stratify purchasing authority and technical specification demands.
- Hospitals:Comprehensive stroke centers with biplane angiography suites in Germany and Japan drive specification-setting for advanced nitinol platforms.
- Ambulatory Surgical Centers:Emerging site-of-care shift for diagnostic cerebral angiography creates demand for simplified, single-use instrument sets.
- Clinics:Limited penetration due to procedure complexity and emergency backup requirements.
- Specialized Healthcare Facilities:Dedicated neurovascular institutes with fellowship training programs anchor adoption of sensor-integrated platforms.
Hospitals dominate absolute procurement volume while ambulatory surgical centers expand most quickly as reimbursement shifts enable site migration.
Material:
Raw material processing capabilities and biocompatibility certification burdens concentrate supply among qualified metallurgical suppliers.
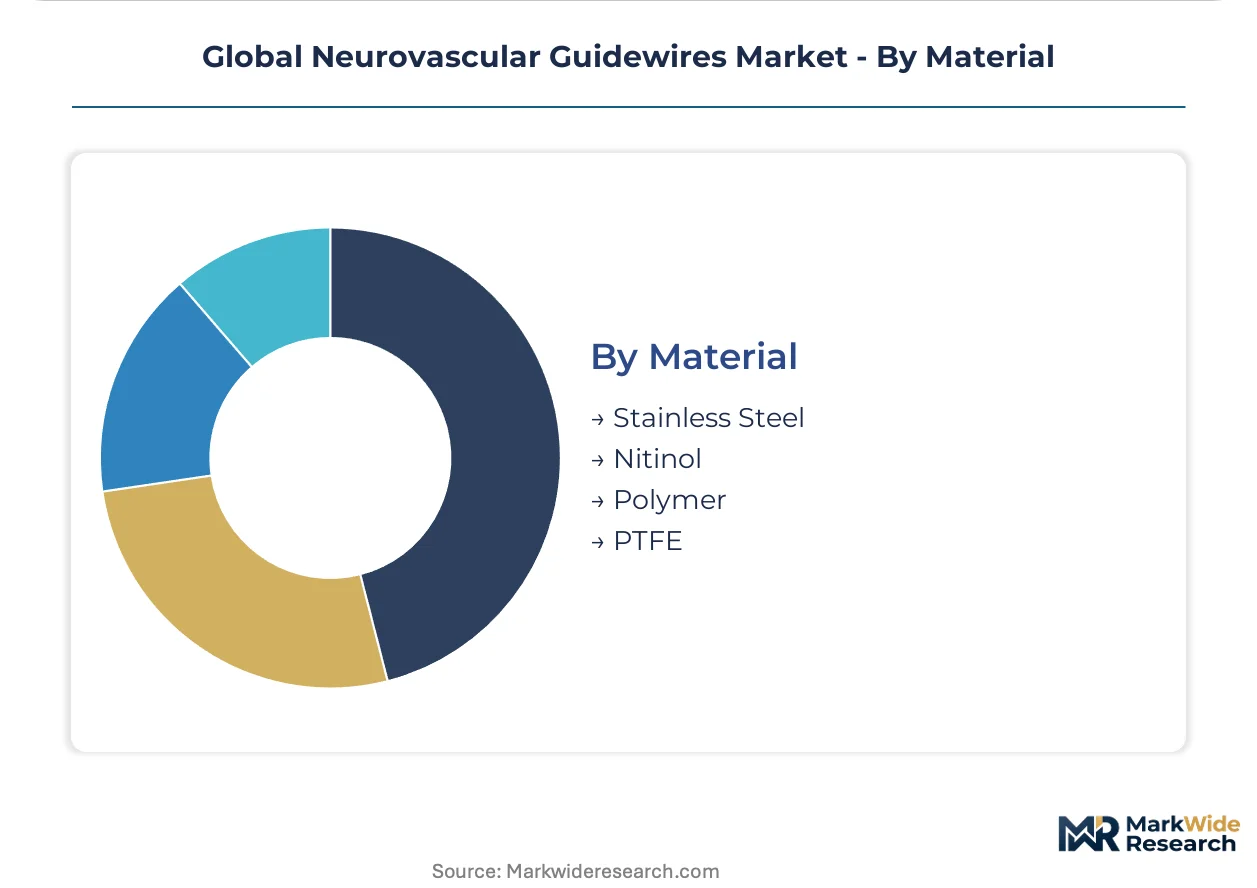
- Nitinol:Superelastic nickel-titanium alloys with shape-memory properties enable kink-resistant navigation through tortuous intracranial anatomy. German and Japanese stroke centers prioritize these platforms for complex aneurysm approaches.
- Stainless Steel:Legacy cores retain cost advantage in standardized thrombectomy workflows with predictable vessel trajectories.
- Polymer:Hydrophilic and hydrophobic jacket materials determine lubricity profiles and thrombogenicity characteristics.
- PTFE:Low-friction coatings applied to distal segments for microcatheter advancement.
Stainless steel maintains installed-base presence while nitinol climbs fastest as centers prioritize shape-memory performance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium pricing power concentrates in German and Japanese tertiary stroke centers, while cost-sensitive procurement in India and Brazil compresses margins for standard-tier platforms. This asymmetry shapes regional product mix and vendor qualification strategies.
United States
Mechanical thrombectomy volumes at certified comprehensive stroke centers drive specification-setting for nitinol-core torqueability. FDA 510(k) clearance pathways enforce substantial equivalence standards that extend development timelines for novel hydrophilic coatings. The southeastern and midwestern hospital networks concentrate procurement authority through integrated delivery network alliances.
Germany
Academic medical centers in Munich and Heidelberg pilot sensor-integrated guidewire architectures for complex aneurysm navigation. EU MDR Annex XIV post-market surveillance requirements mandate systematic clinical follow-up data collection across neurovascular portfolios. The Baden-Württemberg and Bavaria clusters anchor European demand for premium nitinol platforms.
Japan
Tertiary hospitals in Tokyo and Osaka prioritize shape-memory performance for submillimeter vessel traversal in aging patient populations. PMDA Sakigake designation offers fast-track pathways for breakthrough medical devices with embedded electronics. The Kanto and Kansai metropolitan areas concentrate robotic-assisted neurointervention adoption.
India
Underpenetrated neurointervention capacity outside metropolitan centers creates demand for simplified guidewire platforms adapted to emerging cath-lab environments. CDSCO import licensing requirements and biocompatibility standards fragment regulatory strategy for multinational manufacturers. Maharashtra and Karnataka host the primary clusters of private hospital infrastructure expansion.
Brazil
Cost-containment pressures at public university hospitals sustain demand for legacy stainless-steel configurations in standardized workflows. ANVISA registration pathways for Class III medical devices require local clinical evidence generation that extends market entry timelines. São Paulo and Rio de Janeiro anchor the private-sector adoption of advanced nitinol platforms.
Global Neurovascular Guidewires Market Competitive Landscape
Diversified medical technology conglomerates and specialized interventional device manufacturers split the market along portfolio breadth versus technical depth lines. Tier-one suppliers leverage integrated neurovascular portfolios to secure multi-year cath-lab contracts with consolidated purchasing organizations. Mid-scale specialists compete on manufacturing scale and regional regulatory expertise. Dominant competitive moves include strategic partnerships with robotic platform developers and geographic expansion through distributor acquisitions in underserved Asia-Pacific markets.
Among diversified conglomerates, Medtronic and Boston Scientific Corporation exemplify the integrated-portfolio archetype, while Terumo Corporation occupies a position within the Asia-Pacific manufacturing-specialist tier. Stryker Corporation represents the orthopedic-neurovascular crossover segment with cath-lab equipment integration capabilities. These anchors illustrate how scale, regional production nodes, and regulatory pathway expertise stratify competitive positioning across premium and standard product tiers.
| Leading Market Players |
|---|
| Medtronic |
| Boston Scientific Corporation |
| Stryker Corporation |
| Terumo Corporation |
| Asahi Intecc |
| Johnson & Johnson |
| Penumbra |
| Cook Medical |
| Cardinal Health |
| Others |
Supply & Pricing Matrix
Nitinol alloy supply concentrates among Japanese and German metallurgical processors, anchoring margin capture in specialty guidewire tiers where superelastic core specifications command configured-to-order premiums from Tokyo and Munich stroke centers.
Pricing Analysis
Configured-to-order specialty guidewires for flow-diversion workflows carry 40-60% premiums over standard thrombectomy platforms. Three-tier pricing structure across premium nitinol, standard hybrid-core, and economy stainless-steel levels reflects FDA 510(k) certification grade and torque-response customization depth. Cost compression in standard-tier segments is intensifying because hospital procurement consortiums demand volume-based transparency from integrated delivery networks. Ambulatory surgical centers exhibit highest price sensitivity; Japanese tertiary hospitals with robotic cath labs show least.
Supply Chain Analysis
Export-control restrictions on superelastic nickel-titanium processing technology limit alloy flows from German and Japanese specialist foundries to qualified medical-device manufacturers. Raw material dependencies center on nickel-titanium billet, hydrophilic polymer feedstock, and precision-drawn hypotube. Single-source vulnerability concentrates in nitinol melt capacity. Distribution runs through regional health system alliances consolidating vendor panels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Robotic-assisted neurointervention platforms are reconfiguring guidewire procurement around electronics-compatibility specifications, creating platform-economics inflection as cath-lab equipment vendors bundle instrument supply.
For Market Incumbents: Pre-empt sensor-integrated guidewire commoditization by securing exclusive cath-lab equipment partnerships with robotics developers. Deepen backward integration into nitinol melt capacity to defend against raw material volatility. Prioritize EU MDR notified-body relationship investment to compress certification timelines. For New Entrants and Emerging Players: Establish a beachhead in India's emerging stroke center infrastructure with simplified nitinol platforms adapted to biplane angiography suites outside metropolitan clusters. Target Maharashtra and Karnataka private hospital expansions with distributor partnerships bypassing consolidated GPO channels. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed European interventional device specialists holding EU MDR certificates but lacking robotics integration capabilities. Five-to-ten-year viability hinges on platform interoperability positioning. Signal to watch: PMDA Sakigake designations for sensor-integrated platforms accelerating Japanese commercialization timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Robotics Partnership Development | Bundled cath-lab supply contracts with integrated guidewire-electronics specifications lock in multi-year hospital commitments. |
| EU MDR Certification Acceleration | Notified-body capacity scarcity in Germany and France extends launch windows for unprepared manufacturers. |
| Nitinol Melt Capacity Expansion | Captive superelastic alloy supply insulates margin structures from geopolitical nickel-titanium disruption. |
| India Distribution Acquisition | Direct channel control in Maharashtra and Karnataka bypasses fragmented import licensing bottlenecks. |
| Sensor-Integrated Platform Launch | Fiber-optic pressure feedback architectures digitize vessel-wall mapping for complex aneurysm approaches. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA 510(k) filings, EU MDR technical documentation, and hospital procurement databases. Interviews with neurointerventionalists, biomedical engineers, GPO contracts managers, and cath-lab equipment specialists informed demand-side dynamics. Customs records, nitinol alloy trade flows, and PMDA approval registries provided supply-side validation. Bottom-up procedure volume estimates and top-down neurovascular device market triangulation anchored value projections.
Forecast inputs include mechanical thrombectomy adoption curves, flow-diversion procedure expansion, and robotic platform penetration across certified stroke centers. Segmentation dimensions span material tier, product type, application setting, and regional regulatory cluster. CAGRs derive from modeled replacement cycles for torqueable versus specialty platforms, calibrated against nitinol raw material cost trajectories and hospital capital expenditure patterns.
Stress conditions across EU MDR notified-body capacity, nitinol supply concentration, and thrombectomy reimbursement policy were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding procedure volume elasticity and robotics adoption timing. Material shifts in FDA digital-health integration guidance or PMDA electronics-compatibility standards would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Eye Massage Device Market
Medical Devices
US Anti-Blue Ray Myopia Lenses Market
Medical Devices
Cranial Orthoses Market
Medical Devices
Intracranial Pressure Monitors Market
Medical Devices
Implantable Port Market
Medical Devices
Organ Preservation Market
Medical Devices
Automatic Clotting Timer Systems Market
Medical Devices
Global IVF Devices Market
Medical Devices
EMEA Surgical Microscopes Market
Medical Devices
Photomedicine Technology Market
Medical Devices
Arthroscopy Devices Market
Medical Devices
Electrosurgical Generators Market
Medical Devices
Electroencephalography (EEG) Systems Market
Medical Devices
US Electrosurgical Generators Market
Medical Devices
At-Home Laser Hair Removal Devices Market
Medical Devices
Asia-Pacific Viscosupplementation Market