
 Heated Humidifiers Market | 2026-2036
Heated Humidifiers Market Size, Share, and Industry Trends Forecast 2026-2036
Heated Humidifiers Market Foresight
Modular integration of heated humidifiers with CPAP and ventilator systems is restructuring buyer choice across the respiratory care supply chain. ResMed Inc. leverages its sleep therapy platform dominance to bundle humidification modules with flow generators. Fisher & Paykel Healthcare anchors its position through specialized humidification circuits for acute and chronic ventilation. Koninklijke Philips N.V. competes across both home and hospital channels with integrated respiratory platforms.
Heated humidifiers are electromechanical devices that add temperature-controlled moisture to breathing gases, typically maintaining output between 31°C and 37°C with relative humidity at or near 100% to prevent mucosal drying and airway injury. Their primary purpose spans therapeutic respiratory support, industrial process humidity control, and environmental conditioning in sensitive applications. Steam vaporizers and ultrasonic humidifiers occupy distinct margin pools, with the former dominating clinical settings where sterilization-grade output matters and the latter expanding fastest in residential environments where noise reduction and energy efficiency drive replacement cycles. Healthcare facilities represent the most concentrated end-user segment for premium-capacity units, while home use applications pull medium-capacity systems through durable medical equipment channels.
FDA 510(k) clearance requirements and EU MDR technical documentation obligations shape product development timelines and market access costs for manufacturers targeting regulated jurisdictions. ISO 80601-2-74 standards for humidification equipment establish performance benchmarks that differentiate clinical-grade from consumer-grade offerings. Stakeholders must monitor reimbursement code revisions and home healthcare policy shifts that determine whether humidification stays bundled with therapy devices or unbundles into separate procurement categories.
Market Dynamics
Integration of heated humidifiers with ventilator and CPAP platforms is compressing standalone procurement, forcing manufacturers to bundle humidification modules or risk exclusion from hospital purchasing contracts.
Growth Catalysts
- EU MDR compliance deadlines:Stricter technical documentation requirements for Class IIa medical devices are filtering out low-capability suppliers and consolidating procurement toward certified clinical-grade systems in German and French healthcare networks.
- Home healthcare expansion:Chronic obstructive pulmonary disease patient management is shifting from acute facilities to residential settings, pulling medium-capacity humidifiers through durable medical equipment channels.
- Japan's super-aging trajectory:METI reimbursement policies for home respiratory therapy are expanding eligible patient pools, creating sustained demand for integrated humidification in Tokyo and Osaka metropolitan clusters.
Market Restraints
- Semiconductor input volatility:Microcontroller and sensor chip supply concentration in East Asian foundries creates production scheduling uncertainty for precision temperature-control units.
- Steam sterilization infrastructure:Clinical-grade vaporizer output requires hospital-grade autoclave compatibility, limiting addressable market to facilities with capital-intensive central sterile supply departments.
- Ultrasonic humidifier substitution:Energy-efficient residential alternatives capture price-sensitive home segments where clinical output standards are not mandated.
Strategic Opportunities
- India's respiratory device localization:PLI scheme incentives for medical electronics manufacturing invite joint ventures with CDSCO-registered domestic assemblers to bypass import duty structures.
- Transport ventilator integration:Emergency medical services and air ambulance operators require compact heated humidification for portable life-support platforms.
- Cloud-connected maintenance models:IoT-enabled predictive filter replacement and calibration scheduling create recurring revenue streams separate from device hardware sales.
Industry Challenges
- Biocompatibility testing timelines:ISO 10993 material characterization for heated breathing circuits extends FDA 510(k) review cycles and delays product launches.
- Legacy ventilator interoperability:Proprietary connector standards across installed hospital equipment bases force redundant SKU development for humidifier manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Heated Humidifiers Market |
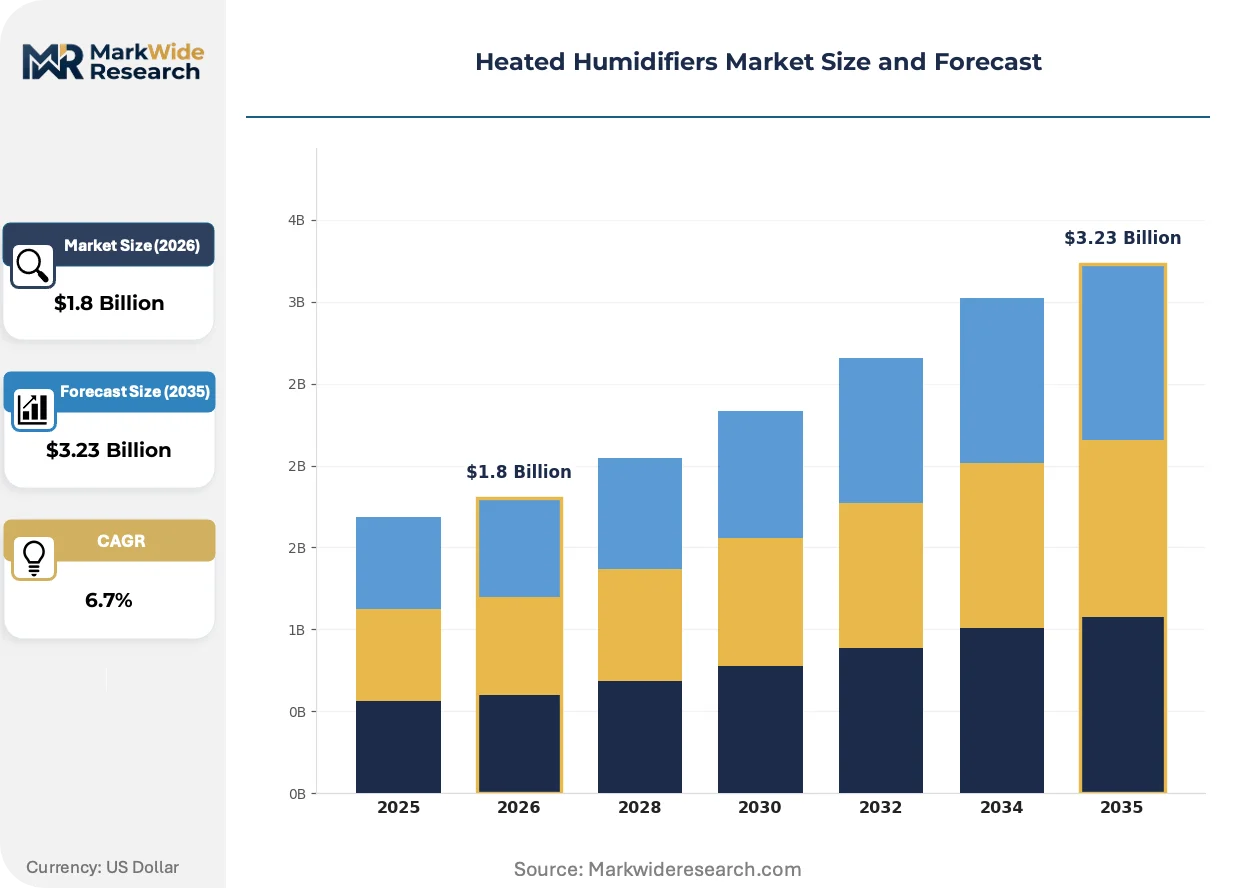
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Steam Vaporizers, Ultrasonic Humidifiers, Impeller Humidifiers, Hydronic Humidifiers End User: Residential, Commercial, Industrial, Healthcare Facilities Capacity: Small, Medium, Large, Extra Large Application: Home Use, Office Use, Laboratory Use, Greenhouse |
| Companies Covered | Koninklijke Philips N.V., ResMed Inc., Fisher & Paykel Healthcare, Teleflex Incorporated, Honeywell International Inc., Drägerwerk AG & Co. KGaA, Armstrong Medical Ltd, Dyson, Sharp, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Heated Humidifiers Market Shifts & Advancements
Advances in sensor miniaturization and materials science are enabling humidification platforms that adapt in real time to patient breathing patterns, collapsing the distinction between acute and home-care device architectures.
Adaptive humidity control algorithms using flow-sensor feedback are rewriting how respiratory support devices manage mucosal protection. Intensive care units in tertiary hospitals are adopting these systems to reduce ventilator-associated pneumonia incidence. The technology is compressing the performance gap between premium and mid-tier product lines.
EU MDR Article 10 technical documentation requirements are extending conformity assessment timelines for humidification equipment. Notified body capacity constraints in Germany and the Netherlands are creating queue bottlenecks that favor larger manufacturers with dedicated regulatory affairs functions. Smaller competitors are retreating from European market entry or pursuing UKCA certification as an alternative pathway.
Hospital procurement committees are consolidating respiratory device purchasing under value-analysis programs that evaluate total cost of ownership rather than acquisition price. Group purchasing organizations are displacing individual facility negotiations in the United States, compressing vendor margins while extending contract durations. This behavioral shift is most pronounced in integrated delivery networks spanning multiple states.
Heated Humidifiers Market Segmentation
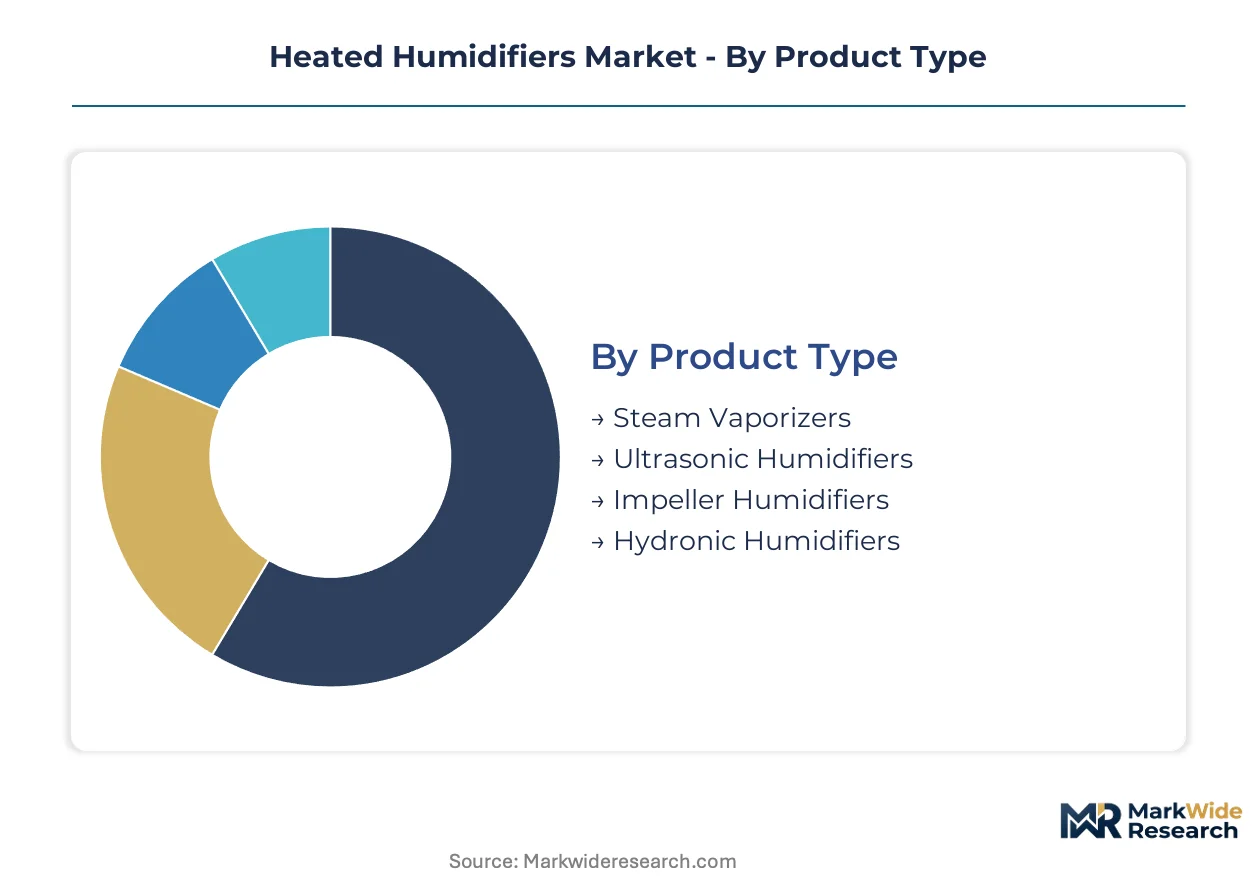
Heated humidifier procurement decisions diverge sharply across settings, with clinical-grade vaporizers commanding premium pricing against consumer alternatives while capacity requirements scale with facility infrastructure. Manufacturers must architect distinct SKU portfolios for each segment intersection to avoid margin erosion from misaligned feature sets.
Product Type:
Buyers prioritize output purity against energy efficiency tradeoffs when selecting heating mechanisms.
- Steam Vaporizers:Boiling-element systems deliver sterilization-grade moisture output at 100% relative humidity. Hospital central sterile supply departments in the United States and Germany specify these units for ventilator circuits where bacterial contamination risks dominate procurement criteria.
- Ultrasonic Humidifiers:Piezoelectric transducers generate cool mist through high-frequency vibration, reducing power draw by 40-60% versus thermal methods. Residential demand concentrates in Tokyo apartments and California suburbs where noise thresholds and electricity costs shape replacement cycles.
- Impeller Humidifiers:Rotating disk systems fling water against diffuser plates to create aerosol without heating elements.
- Hydronic Humidifiers:Boiler-fed steam injection integrates with HVAC ductwork for whole-building humidity control.
Steam vaporizers lead on scale; ultrasonic humidifiers lead on momentum.
End User:
Facility capital budgets and reimbursement pathways determine whether procurement flows through durable medical equipment channels or construction contractors.
- Healthcare Facilities:Acute care hospitals and long-term respiratory clinics purchase FDA 510(k)-cleared systems with ISO 80601-2-74 certification. German hospital networks under EU MDR Article 10 requirements are consolidating procurement toward notified body-certified suppliers, filtering out consumer-grade alternatives.
- Residential:Individual consumers acquire standalone units through pharmacy retail and e-commerce platforms. Japan's METI reimbursement expansion for home respiratory therapy is pulling clinical-grade humidifiers into domestic settings previously served by consumer appliances.
- Commercial:Office buildings and hospitality properties install duct-integrated systems for occupant comfort and material preservation.
- Industrial:Manufacturing plants deploy heavy-capacity units for process humidity control in electronics assembly and pharmaceutical production.
Healthcare facilities command the steepest price premiums; residential applications show the broadest volume base.
Capacity:
Water reservoir volume and heating element wattage scale with continuous operation requirements and available floor space.
- Large:4-6 liter reservoirs with 300W+ heating elements sustain 24-hour operation in ICU ventilator suites. Demand clusters in tertiary hospitals across the United States, Germany, and Japan where patient acuity mandates uninterrupted humidification.
- Medium:2-4 liter systems balance runtime with footprint for home healthcare and subacute facilities. COPD patient discharge programs in France and the United Kingdom are standardizing on this tier for residential oxygen therapy bundling.
- Small:Under-2-liter portable units serve travel and bedside applications.
- Extra Large:10+ liter industrial systems integrate with central plant infrastructure.
Large-capacity systems dominate hospital procurement value; medium-capacity configurations are gaining share fastest in home healthcare transitions.
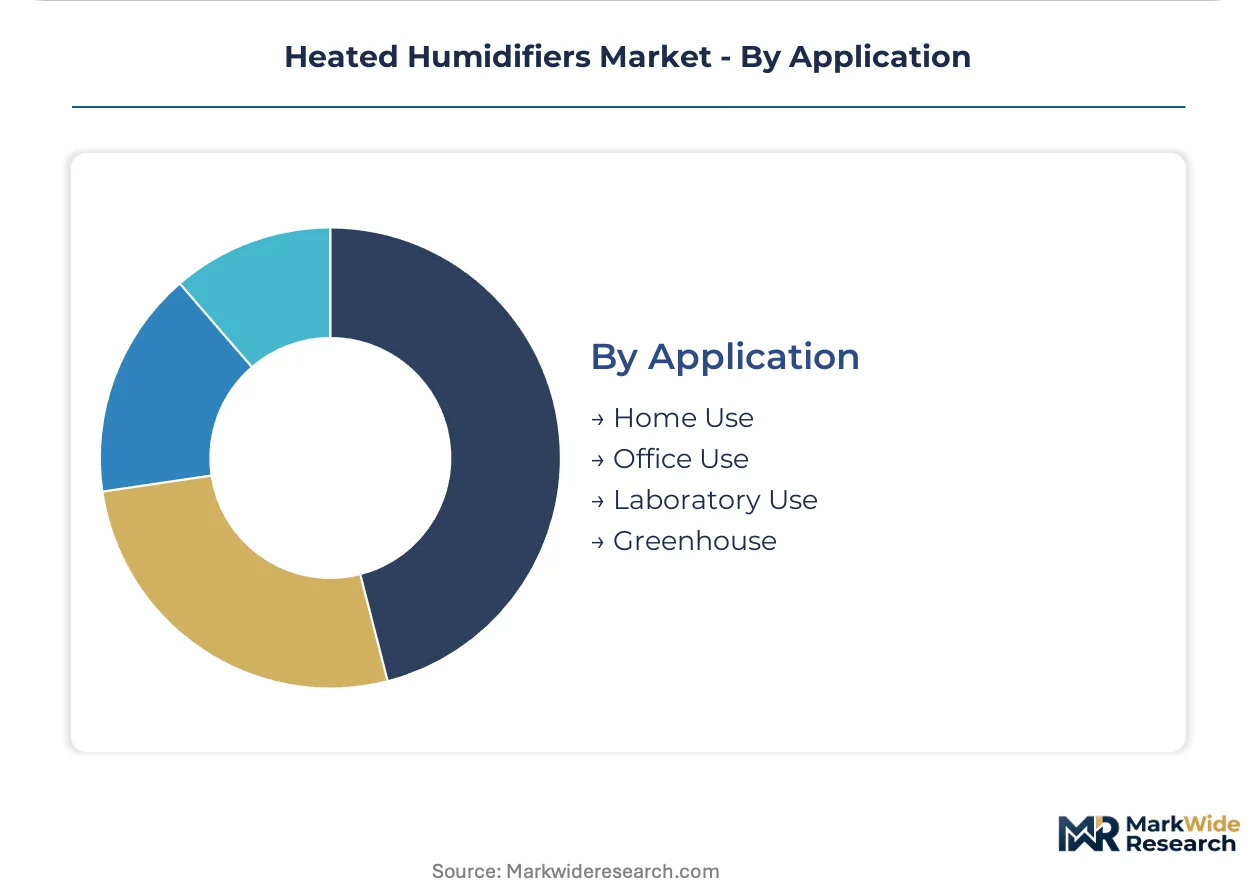
Application:
Environmental control precision requirements separate laboratory specifications from comfort-oriented installations.
- Laboratory Use:Research facilities demand ±2% RH accuracy with HEPA filtration for cell culture and analytical instrument protection. German Max Planck institutes and NIH-funded facilities in Maryland specify calibrated systems with data logging capabilities.
- Home Use:Sleep therapy and respiratory symptom relief drive consumer purchases. CPAP integration requirements in the United States are pushing humidifier bundling with flow generators, collapsing standalone procurement for this segment.
- Office Use:Workplace wellness programs install comfort-grade systems for dry climate compensation.
- Greenhouse:Agricultural operations deploy high-output units for crop propagation climate control.
Home use anchors unit shipment volume; laboratory use commands the highest specification premiums.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Heated humidifier manufacturing first scaled in post-war Germany and the United States as mechanical ventilation spread through university hospitals. Japanese electronics firms later integrated precision temperature controls for compact home units. Today's demand geography reflects this tripartite origin plus emerging production in India and China.
United States
Medicare reimbursement for home respiratory therapy pulls clinical-grade humidifiers through durable medical equipment channels. FDA 510(k) clearance requirements filter out uncertified imports. Hospital procurement concentrates in Cleveland Clinic and Mayo Clinic networks where value-analysis committees bundle humidification with ventilator platforms.
Germany
EU MDR Article 10 technical documentation obligations extend conformity assessment timelines for Class IIa devices. Notified body capacity constraints in TÜV SÜD and DEKRA create certification bottlenecks. Industrial demand clusters in Baden-Württemberg medical device manufacturing corridors serving French and Benelux hospital networks.
Japan
METI reimbursement expansion for home oxygen therapy creates patient eligibility growth in Tokyo and Osaka metropolitan areas. PMDA quality management system inspections enforce ISO 13485 standards. Aging demographics in Kansai region sustain replacement demand for integrated CPAP-humidifier systems.
India
CDSCO medical device rules and PLI scheme incentives for electronics manufacturing attract joint venture assembly. Import duty structures favor domestic production for hospital procurement. Respiratory device demand concentrates in Maharashtra pharmaceutical corridors and Karnataka medical technology parks.
China
NMPA Class II medical device registration requirements extend market access timelines for foreign manufacturers. Domestic production scales in Jiangsu and Zhejiang provinces for cost-competitive export. Hospital procurement in Beijing and Shanghai tertiary centers specifies ISO 80601-2-74 certified systems.
Heated Humidifiers Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification-grade segmentation, with clinical-grade vaporizers commanding 3-4x price multiples over residential ultrasonic alternatives. The vendor base concentrates among respiratory therapy platform owners, specialized humidification circuit manufacturers, and diversified industrial conglomerates with medical divisions. Two strategic archetypes dominate: integrated platform bundlers and standalone component specialists. Competitive moves center on regulatory certification stacking and hospital purchasing contract consolidation.
Within the integrated platform tier, Koninklijke Philips N.V. and ResMed Inc. occupy positions spanning home and hospital channels. Fisher & Paykel Healthcare exemplifies the specialized circuit archetype with focused humidification technology. These three anchors represent contrasting approaches to market access—diversified respiratory portfolios versus concentrated therapeutic expertise.
| Leading Market Players |
|---|
| Koninklijke Philips N.V. |
| ResMed Inc. |
| Fisher & Paykel Healthcare |
| Teleflex Incorporated |
| Honeywell International Inc. |
| Drägerwerk AG & Co. KGaA |
| Armstrong Medical Ltd |
| Dyson |
| Sharp |
| Others |
Supply & Pricing Matrix
Hospital procurement consolidation under value-analysis programs is compressing vendor margins and forcing supply chain reconfiguration toward regional fulfillment centers capable of rapid response to bundled contract demands.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates FDA 510(k)-cleared clinical systems from ISO-certified mid-tier units and uncertified consumer alternatives. Price differentiation rests on certification grade and after-sales service bundling, with clinical-grade vaporizers commanding substantial premiums over residential ultrasonic units. Cost compression in the mid-tier is intensifying because GPO contract consolidation favors volume discounts. Residential consumers exhibit highest price sensitivity; tertiary hospital networks demonstrate lowest sensitivity due to total-cost-of-ownership evaluation frameworks.
Supply Chain Analysis
Regional distribution centers in Germany, the United States, and Japan anchor hub-and-spoke patterns serving hospital networks and durable medical equipment channels. Manufacturing concentrates in China, Malaysia, and Mexico for cost-competitive component assembly, while precision temperature-control subsystems draw from Taiwanese and South Korean semiconductor foundries. Single-source vulnerability in microcontroller supply creates scheduling uncertainty for adaptive humidity platforms. Distribution runs through medical device distributors and direct hospital contracts, with e-commerce platforms gaining share in residential segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where EU MDR Article 10 compliance deadlines are accelerating demand migration toward certified clinical-grade suppliers.
For Market Incumbents: Lock in hospital purchasing committee relationships through extended service contracts and predictive maintenance subscriptions before ultrasonic alternatives erode home-care margins. Backward integration into sensor manufacturing reduces exposure to East Asian chip supply volatility. Prioritize UKCA certification as European notified body queues lengthen. For New Entrants and Emerging Players: Durable medical equipment distributors represent the most accessible channel for bypassing incumbent GPO lock-in. India's CDSCO-registered domestic assembly partnerships under PLI scheme incentives offer the most penetrable geographic entry point. Target transport ventilator integration for emergency medical services where portability requirements favor compact system architectures. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized humidification circuit manufacturers possessing ISO 10993 biocompatibility testing capabilities and established notified body relationships. Long-term viability hinges on regulatory certification stacking rather than hardware volume scaling. Watch FDA 510(k) review cycle durations as the signal indicating whether consolidation pressure is intensifying or easing.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Article 10 Compliance Pathway | Notified body certification unlocks German and French hospital procurement networks. |
| Hospital System Partnership | Value-analysis committee inclusion secures multi-year bundled contract visibility. |
| Software Companion Development | IoT-enabled filter monitoring creates recurring revenue separate from hardware sales. |
| Reimbursement Strategy | METI and Medicare code alignment pulls clinical-grade systems into home settings. |
| Backward Integration into Sensors | In-house temperature-control component production insulates margins from chip volatility. |
Research Methodology
Bottom-up end-use modeling reconciled against top-down supply-side tracking forms the analytical core of this study. Primary interviews with respiratory therapists, hospital purchasing committee members, biomedical engineers, and GPO contracts managers combined with secondary validation against FDA 510(k) filings, EU MDR technical documentation databases, CMS Medicare reimbursement schedules, and hospital procurement records. Triangulation across these sources ensures segmentation integrity.
Input-output matrices map humidifier unit shipments to ventilator and CPAP platform installations across the projection horizon. Segmentation dimensions include product type, end-user facility class, capacity tier, and application setting. CAGRs derive from patient population growth trajectories, reimbursement policy shifts, and replacement cycle analysis. Forecast inputs incorporate EU MDR compliance timelines and semiconductor supply lead time variability.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to reimbursement code revisions and home healthcare policy shifts. Outputs reflect documented assumptions regarding patient demographic trends and regulatory enforcement intensity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Left Atrial Appendage (LAA) Closure Device Market
Medical Devices
ECG Patch and Holter Monitor Market
Medical Devices
Upper Limb Prosthetics Market
Medical Devices
Neurointerventional Devices Market
Medical Devices
Urology Guidewires Market
Medical Devices
3D Printed Implants Market
Medical Devices
Transseptal Access Systems Market
Medical Devices
Medical Device and Accessories Market
Medical Devices
Anorectal Manometry Systems Market
Medical Devices
India Artificial Organs and Bionics Market
Medical Devices
Global Microscopy Device Market
Medical Devices
Leadless Pacing Systems Market
Medical Devices
Ocular Implants Market
Medical Devices
North America Refractive Surgery Devices Market
Medical Devices
Global Wearable Pregnancy Devices Market
Medical Devices
Global Cerebral Somatic Oximeters Market