
 Global Joint Replacement Market | 2026-2036
Global Joint Replacement Market Size, Share, and Industry Trends Forecast 2026-2036
Global Joint Replacement Market Foresight
Ambulatory surgery centers is reorganizing procurement patterns across the joint replacement landscape, pulling volume away from traditional inpatient settings. Zimmer Biomet Holdings leverages its scale in hip and knee reconstruction to dominate hospital system contracts. Stryker Corporation anchors its position through robotics-integrated surgical platforms that command premium placement. Johnson & Johnson MedTech differentiates via its DePuy Synthes portfolio across cemented and cementless fixation technologies.
Joint replacement encompasses the surgical implantation of prosthetic devices designed to restore mobility and alleviate pain in damaged articulating joints, typically manufactured from cobalt-chrome alloys, titanium, ultra-high molecular weight polyethylene, or ceramic composites through precision forging, machining, and sterilization processes. Knee implants generate the largest revenue pool due to high procedural volume and established reimbursement pathways, while shoulder implants represent the fastest-expanding category as reverse shoulder arthroplasty gains surgical acceptance. Ceramic-on-polyethylene bearings command margin premiums over metal-on-metal configurations amid biocompatibility and wear-rate advantages.
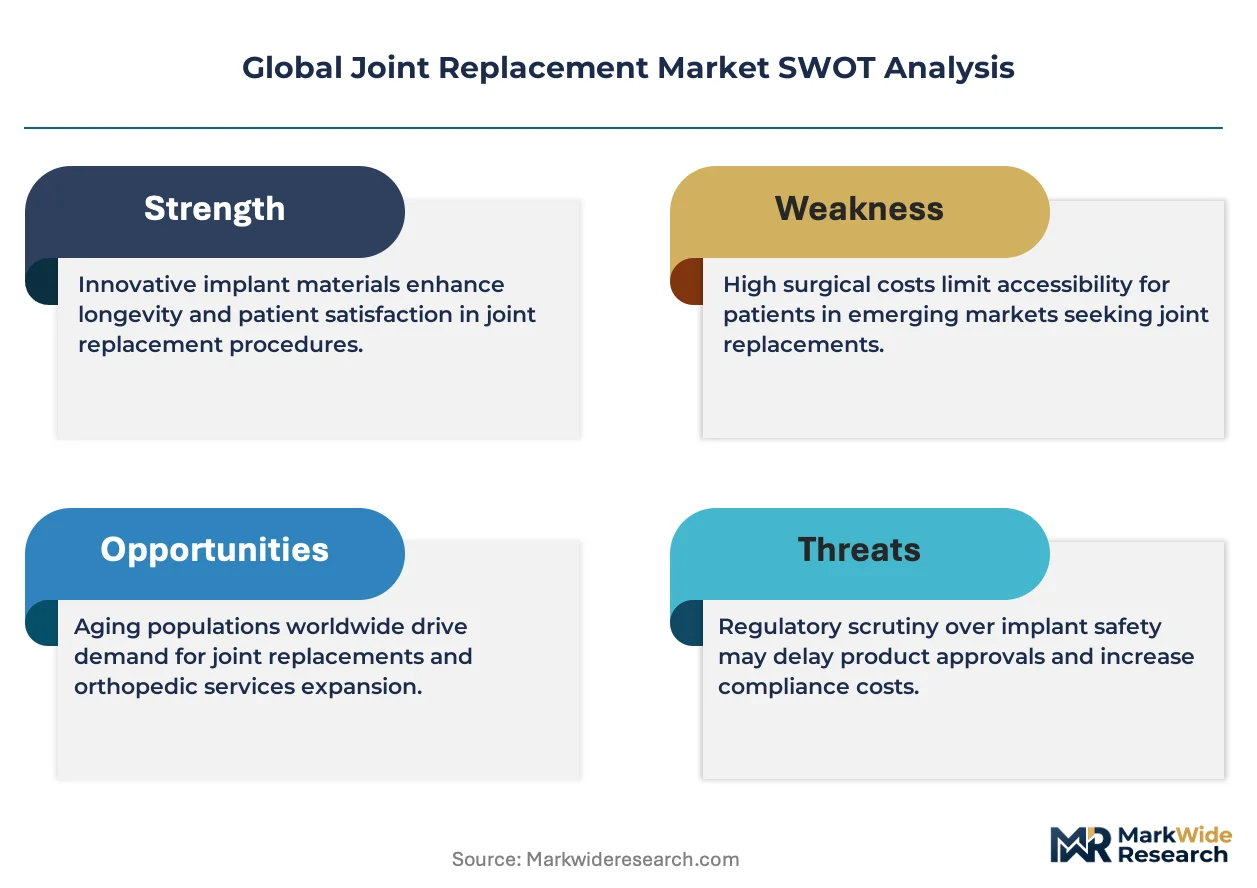
FDA 510(k) clearance pathways and EU MDR conformity assessment procedures govern device commercialization, with the latter extending certification timelines and elevating clinical evidence requirements for manufacturers. ISO 5832 material standards and ASTM F2077 test methods define mechanical performance benchmarks that products must satisfy prior to regulatory submission. Stakeholders must monitor evolving CMS reimbursement rules for outpatient joint replacement bundled payments and the trajectory of same-day discharge protocols.
Market Dynamics
Ambulatory surgery centers are capturing procedural volume from traditional hospital settings, forcing manufacturers to reconfigure distribution networks and service models around outpatient workflows and same-day discharge protocols.
Growth Catalysts
- EU MDR compliance deadlines:Manufacturers accelerating clinical evidence generation for legacy devices, creating temporary demand surges for upgraded implant portfolios ahead of certificate expiration dates.
- Reverse shoulder arthroplasty:Surgical technique refinements expanding treatable patient populations beyond rotator cuff deficiencies into primary osteoarthritis cases.
- China's tier-two hospital expansion:Provincial health commissions channeling joint replacement capacity into municipal medical centers, decentralizing procedural access from Beijing and Shanghai corridors.
Market Restraints
- Cobalt-chrome alloy supply concentration:Specialty foundry capacity clustering in Germany and Japan creates input vulnerability for bearing surface production.
- FDA 510(k) predicate device limitations:Novel material combinations lacking substantial equivalence pathways face extended premarket approval timelines.
- Polyethylene wear debris litigation:Historical metal-on-metal failure modes continue depressing surgeon confidence in alternative bearing configurations despite material improvements.
Strategic Opportunities
- Brazil's SUS reimbursement expansion:Federal health ministry protocols adding hip and knee arthroplasty to mandatory coverage lists, unlocking procedural volume in Southeast state networks.
- Robotics-integrated preoperative planning:Convergence of CT-based templating software with haptic guidance systems enabling personalized implant positioning.
- Direct-to-ambulatory distribution:Bypassing traditional hospital purchasing committees through specialty distributor relationships with ASC management companies.
Industry Challenges
- Biomedical engineer talent scarcity:Orthopedic device design expertise concentrates among aging specialists in Warsaw and Warsaw-adjacent research clusters.
- EU MDR notified body capacity:Certificate renewal queues extending 18-24 months, freezing product line extensions for mid-tier manufacturers.
- Legacy hospital EHR integration:Implant tracking systems requiring custom middleware development for automated supply chain visibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Joint Replacement Market |
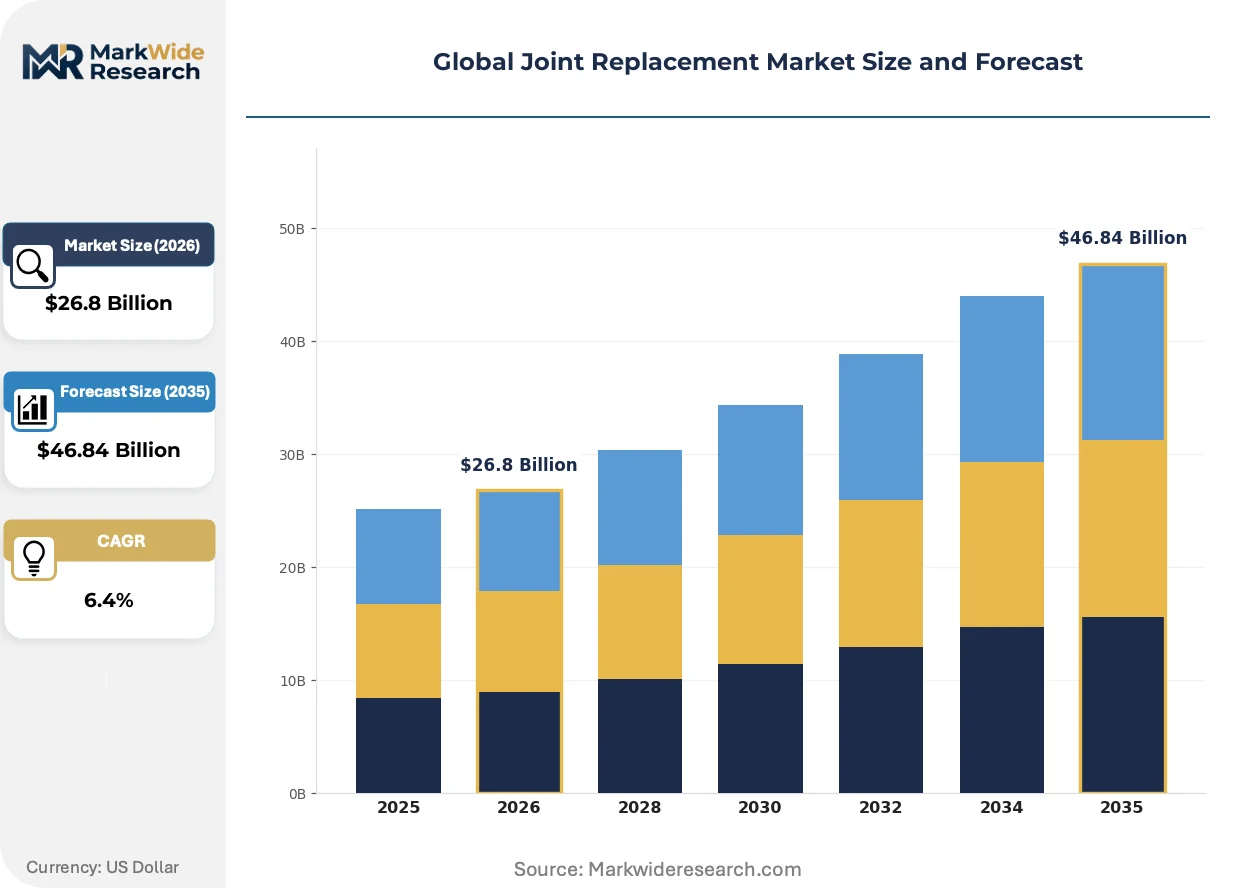
| Market Size in 2026 | $26.8 Billion |
| Market Size in 2035 | $46.84 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
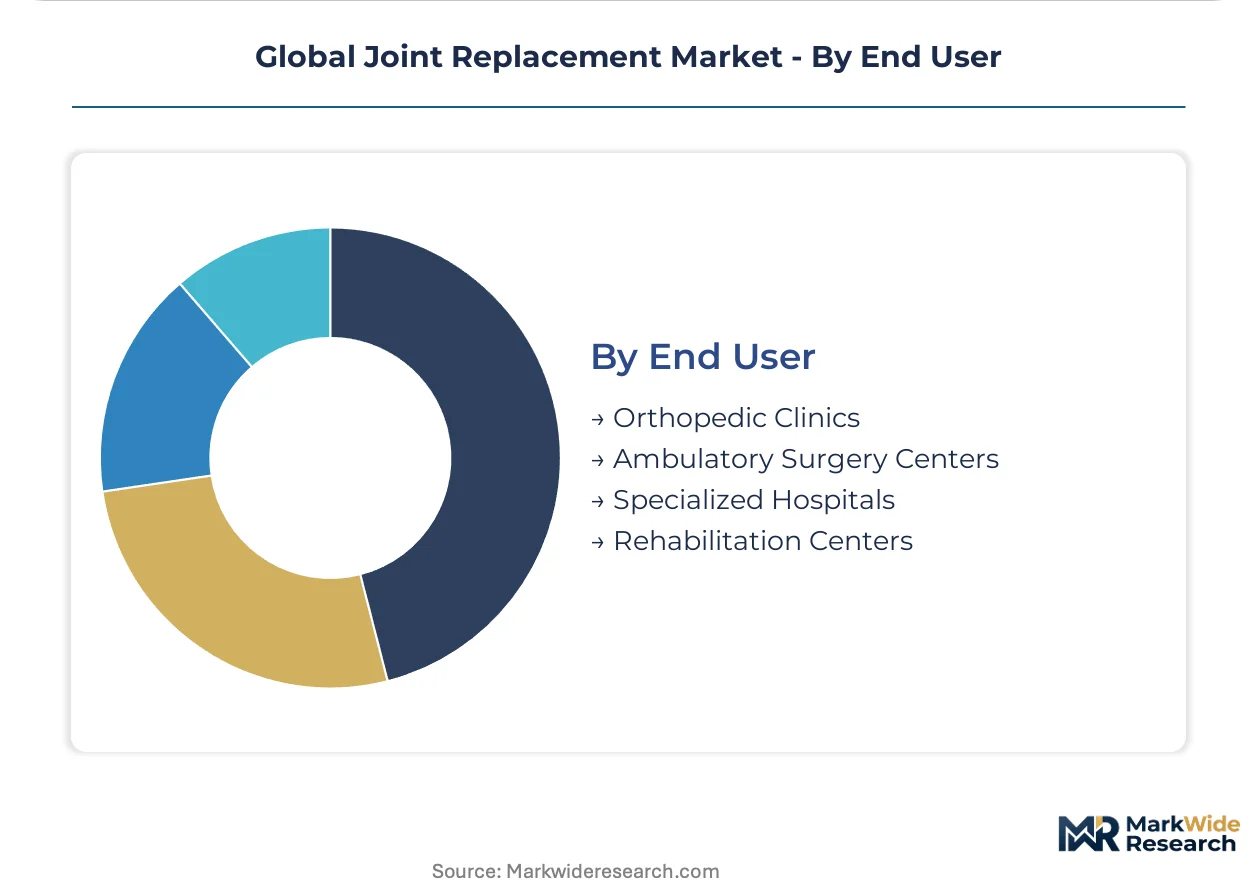
| Segmentation | Product Type: Hip Implants, Knee Implants, Shoulder Implants, Elbow Implants, Ankle Implants Technology: Ceramic, Metal-on-Metal, Polyethylene, Hybrid, Cementless Fixation, Cemented Fixation Application: Osteoarthritis, Rheumatoid Arthritis, Traumatic Injuries, Avascular Necrosis, Bone Tumors End User: Orthopedic Clinics, Ambulatory Surgery Centers, Specialized Hospitals, Rehabilitation Centers |
| Companies Covered | Zimmer Biomet Holdings, Stryker Corporation, Johnson & Johnson MedTech, Smith & Nephew, B. Braun Melsungen AG, Enovis Corporation, MicroPort Scientific Corporation, Medacta International, Arthrex, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Joint Replacement Market Shifts & Advancements
Digital surgical planning and advanced bearing materials are compressing revision rates while enabling procedure migration into lower-acuity settings, fundamentally altering where and how joint replacement is delivered.
Patient-specific instrumentation derived from preoperative CT scans is fragmenting the standard implant market. Ambulatory surgery centers in Florida and Texas are adopting these guides at twice the rate of academic medical centers, compressing operative time and instrument tray requirements while forcing manufacturers to maintain parallel conventional and customized product lines.
EU MDR Article 10 clinical evaluation requirements are extending certification timelines for hip resurfacing devices. Manufacturers must now generate prospective registry data where historical literature reviews sufficed, compressing commercialization schedules and elevating documentation costs most acutely for ceramic-on-metal bearing configurations.
Same-day discharge protocols are reshaping implant selection criteria in United States Medicare Advantage networks. Surgeons in Arizona and Colorado are prioritizing cementless fixation technologies with faster osseointegration profiles, displacing traditional hospital purchasing agreements that bundled inpatient rehabilitation services with device procurement.
Global Joint Replacement Market Segmentation
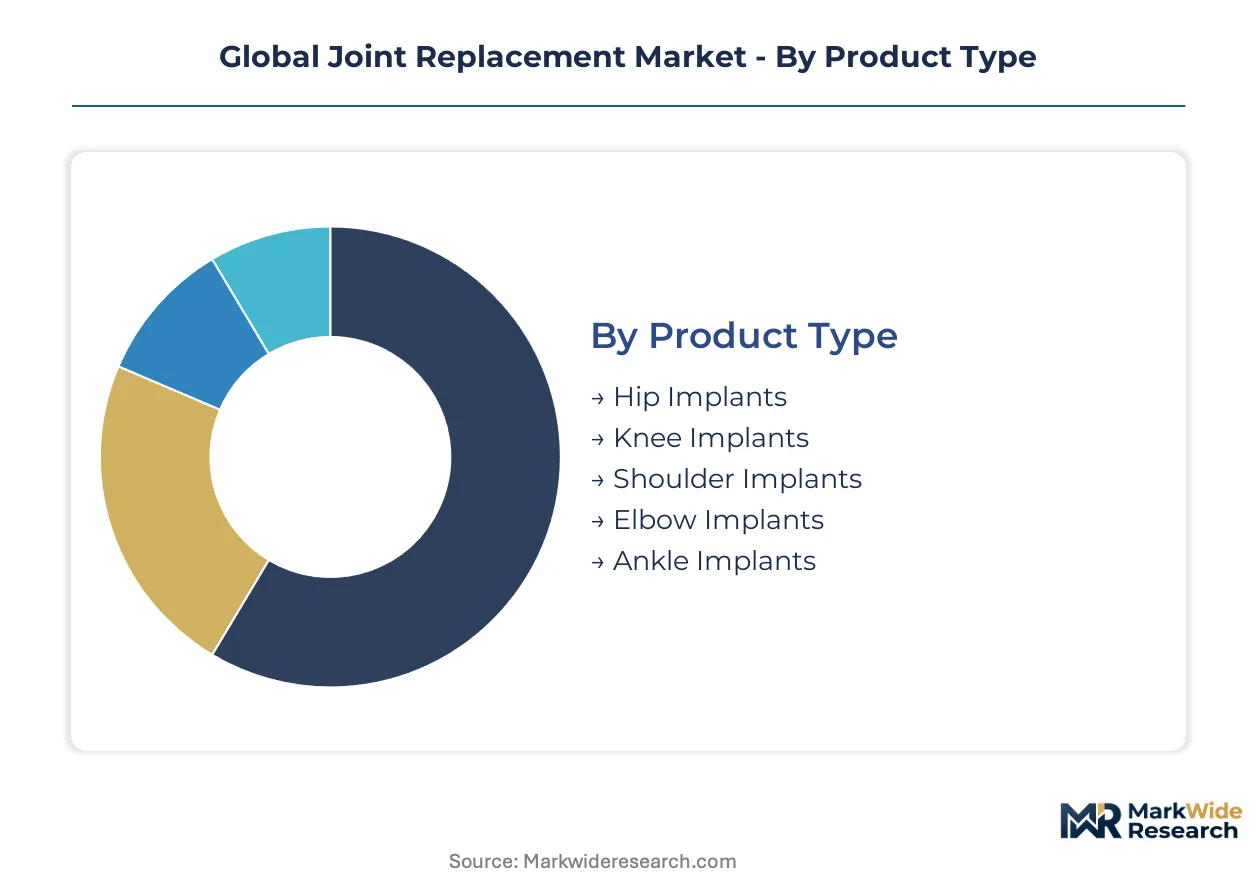
Joint replacement segmentation reveals divergent supply chain configurations across product categories. Technology and end-user splits expose distinct margin profiles and regulatory exposure that shape manufacturer portfolio priorities.
Product Type:
Domestic production dominates hip and knee categories in the United States and Germany, while shoulder and ankle segments rely more heavily on export-led supply from specialized Swiss and Japanese foundries.
- Hip Implants:Cobalt-chrome alloy femoral heads paired with acetabular cups in titanium or ceramic variants. Demand concentrates in German statutory health insurance networks where revision rate thresholds drive bearing surface selection.
- Knee Implants:Femoral, tibial, and patellar components in fixed-bearing or mobile-bearing configurations. Volume leadership in United States Medicare bundled payment corridors forces manufacturers to absorb cost compression through tray standardization.
- Shoulder Implants:Anatomical and reverse arthroplasty systems for glenohumeral reconstruction.
- Elbow Implants:Linked and unlinked designs addressing distal humerus and proximal ulna pathology.
- Ankle Implants:Three-component systems for tibiotalar joint replacement in salvage scenarios.
Knee implants command the established base. The steepest expansion runs through shoulder implants.
Technology:
Cost tier stratification separates premium ceramic bearings from commodity polyethylene configurations, with hybrid approaches occupying the contested middle ground.
- Ceramic:Alumina or zirconia-toughened alumina bearing surfaces with superior scratch resistance and biocompatibility profiles. Swiss orthopedic centers in Basel and Zurich drive adoption ahead of broader European diffusion.
- Metal-on-Metal:Cobalt-chromium alloy articulating pairs now restricted to hip resurfacing indications amid adverse local tissue reaction concerns. Regulatory scrutiny from FDA and Australia's TGA has collapsed surgeon confidence outside specialized revision contexts.
- Polyethylene:Cross-linked ultra-high molecular weight polyethylene liners in conventional and vitamin E-stabilized variants.
- Hybrid:Ceramic-on-polyethylene or metal-on-polyethylene combinations balancing cost and performance.
- Cementless Fixation:Porous-coated or trabecular metal surfaces enabling biological osseointegration.
- Cemented Fixation:Polymethylmethacrylate bone cement anchoring for immediate stability in osteoporotic bone.
Cementless fixation commands the established base. The steepest expansion runs through ceramic bearings.
Application:
Volume concentration in osteoarthritis creates procurement scale effects that rheumatoid arthritis and trauma indications cannot replicate.
- Osteoarthritis:Degenerative joint disease from cartilage erosion and subchondral bone remodeling. China's tier-two hospital expansion channels procedural volume into provincial capitals including Chengdu and Wuhan.
- Rheumatoid Arthritis:Inflammatory synovial destruction requiring disease-modifying therapy coordination preoperatively. German rheumatology-orthopedics integrated care pathways concentrate demand in Berlin and Munich academic networks.
- Traumatic Injuries:Fracture sequelae and post-traumatic arthritis from high-energy mechanisms.
- Avascular Necrosis:Osteocyte death from vascular compromise, particularly femoral head involvement.
- Bone Tumors:Limb salvage reconstruction following resection of primary or metastatic lesions.
Osteoarthritis commands the established base. The steepest expansion runs through avascular necrosis as imaging sensitivity improves detection.
End User:
Customer type fragmentation separates high-volume ambulatory settings from capital-intensive hospital infrastructure with divergent service and pricing expectations.
- Orthopedic Clinics:Physician-owned facilities performing preoperative assessment and postoperative surveillance. United States private practice consolidation in Florida and Texas generates procurement scale for implant distributors.
- Ambulatory Surgery Centers:Same-day discharge facilities with instrument sterilization and recovery capabilities. Arizona and Colorado Medicare Advantage networks are accelerating migration of uncomplicated primary arthroplasty to these settings.
- Specialized Hospitals:Academic medical centers and orthopedic specialty hospitals with revision and complex primary capabilities.
- Rehabilitation Centers:Post-acute facilities managing functional recovery and prosthetic training protocols.
Specialized hospitals command the established base. The steepest expansion runs through ambulatory surgery centers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German manufacturers export cobalt-chrome bearing surfaces to United States hospital systems, while Swiss foundries supply ceramic components to Japanese orthopedic networks. This trade-flow structure concentrates high-value production in Western Europe and distributes finished implants across North American and Asian demand corridors.
United States
Medicare Advantage bundled payment expansion and same-day discharge protocols in Arizona and Colorado are accelerating ambulatory surgery center migration. FDA 510(k) clearance pathways govern device commercialization timelines for domestic manufacturers. Warsaw, Indiana anchors the largest orthopedic device cluster, where Zimmer Biomet and DePuy Synthes maintain integrated design and production facilities.
Germany
Statutory health insurance revision rate thresholds drive bearing surface selection toward ceramic and cross-linked polyethylene configurations. EU MDR notified body capacity constraints extend certificate renewal queues 18-24 months for mid-tier manufacturers. The Warsaw-adjacent research corridor and Basel-Zurich orthopedic centers concentrate biomedical engineering expertise and early ceramic adoption.
China
Provincial health commissions channel joint replacement capacity into tier-two municipal medical centers in Chengdu and Wuhan, decentralizing procedural access from Beijing and Shanghai. NMPA registration requirements align with international standards while maintaining separate clinical trial obligations for novel materials. Yangtze River Delta foundries supply titanium femoral stems to domestic and Southeast Asian markets.
Japan
Aging demographics and universal health coverage sustain procedural volume in hip and knee categories. PMDA premarket approval timelines exceed FDA 510(k) pathways, favoring incremental device modifications over breakthrough innovations. Osaka-Kobe industrial zones concentrate precision machining capacity for cobalt-chrome alloy production serving domestic and export demand.
Brazil
Federal health ministry protocols adding hip and knee arthroplasty to SUS mandatory coverage lists unlock procedural volume in Southeast state networks. ANVISA registration requirements create parallel commercialization tracks distinct from FDA and EU pathways. São Paulo academic medical centers anchor surgeon training and complex revision capabilities for Latin American referral networks.
Global Joint Replacement Market Competitive Landscape
Player mix skews toward diversified orthopedic conglomerates with integrated robotics and digital surgery platforms. Market structure concentrates among five to seven entities commanding hospital system contracts and ambulatory surgery center purchasing committees. Strategic archetypes separate scale-driven full-line suppliers, robotics-integrated platform specialists, and regional cost-optimized manufacturers. Competitive moves center on M&A for digital surgery capabilities and direct-to-ASC distribution partnerships bypassing traditional hospital procurement.
Among diversified orthopedic conglomerates, Zimmer Biomet Holdings and Stryker Corporation exemplify scale-driven archetypes with comprehensive hip, knee, and extremities portfolios. Johnson & Johnson MedTech occupies a position bridging traditional implant manufacturing with digital surgery integration through its DePuy Synthes franchise. Smith & Nephew represents the mid-tier specialist archetype competing on sports medicine adjacencies and emerging market penetration. These three entities anchor competitive dynamics across United States Medicare corridors and EU MDR transition timelines.
| Leading Market Players |
|---|
| Zimmer Biomet Holdings |
| Stryker Corporation |
| Johnson & Johnson MedTech |
| Smith & Nephew |
| B. Braun Melsungen AG |
| Enovis Corporation |
| MicroPort Scientific Corporation |
| Medacta International |
| Arthrex |
| Others |
Supply & Pricing Matrix
FDA 510(k) clearance tiers and EU MDR conformity classes partition both supplier qualification barriers and price positioning simultaneously, with notified body backlog extending lead times for premium-certified configurations while standard-grade alternatives capture ambulatory surgery center procurement.
Pricing Analysis
Ceramic-on-polyethylene bearing surfaces command substantial generation-gap premiums over conventional metal-on-polyethylene configurations, while next-generation vitamin E-stabilized liners occupy an emerging price tier above cross-linked polyethylene baselines. Three-tier pricing structure across premium ceramic, standard metal-polyethylene, and economy cemented fixation levels stratifies procurement across Medicare Advantage networks and German statutory insurance corridors. Cost compression in standard knee implant trays intensifies because bundled payment absorption demands tray standardization from manufacturers serving United States hospital systems. Ambulatory surgery centers exhibit the highest price sensitivity, prioritizing cementless fixation technologies with faster discharge profiles over premium bearing surfaces.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes elevate inbound logistics costs for cobalt-chrome alloy femoral heads sourced from Osaka-Kobe industrial zones. Raw material concentration in Germany and Japan for specialty foundry capacity, titanium stem forging in Yangtze River Delta facilities, and ceramic powder processing in Swiss Basel-Zurich corridors creates multi-node dependency. Single-source vulnerability concentrates in cobalt-chrome bearing surface production where German and Japanese foundry capacity limits alternative sourcing. Distribution runs through hospital purchasing committees and direct-to-ambulatory distributor relationships with ASC management companies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Ambulatory surgery center consolidation into management company networks concentrates buyer power, forcing manufacturers to bypass traditional hospital procurement committees through direct distributor partnerships.
For Market Incumbents: Shield hip and knee reconstruction market share by accelerating EU MDR clinical evidence generation ahead of certificate expiration queues, while deepening backward integration into cobalt-chrome alloy foundry capacity to offset German-Japanese supply concentration risks. Prioritize robotics-integrated platform placement in Arizona and Colorado Medicare Advantage corridors where same-day discharge protocols favor cementless fixation technologies. For New Entrants and Emerging Players: FDA 510(k) substantial equivalence pathways for incremental bearing material modifications offer faster commercialization timelines than novel alloy premarket approval routes. Target shoulder implant white space in China's tier-two hospital expansion corridors where reverse arthroplasty technique adoption outpaces incumbent distribution coverage. Pursue direct-to-ambulatory distribution partnerships with Florida and Texas ASC management companies as the primary go-to-market angle. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across robotics-integrated surgical platform development, elevating funding requirements for competitive positioning. Mid-tier manufacturers with EU MDR transition gaps represent viable acquisition targets where notified body queue extensions freeze product line extensions. Monitor FDA 510(k) predicate device limitation rulings on novel material combinations as the signal to watch for regulatory arbitrage opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Clinical Evidence Generation | Accelerated registry data collection ahead of notified body queue congestion preserves certificate continuity for ceramic bearing portfolios. |
| Robotics-Integrated Platform Deployment | Haptic guidance system placement in Arizona and Colorado Medicare Advantage networks commands premium ambulatory surgery center contracts. |
| Direct-to-ASC Distribution Partnership | Bypassing hospital purchasing committees through Florida and Texas management company relationships captures same-day discharge protocol volume. |
| Cobalt-Chrome Foundry Backward Integration | In-house bearing surface production mitigates German-Japanese supply concentration vulnerability for femoral head manufacturing. |
| Reverse Shoulder Arthroplasty Training Programs | Surgeon education investments in Chengdu and Wuhan tier-two hospitals accelerate technique adoption beyond rotator cuff deficiency indications. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with orthopedic surgeons, hospital purchasing committee members, biomedical engineers, GPO contracts managers, and ambulatory surgery center administrators. Secondary validation drew from FDA 510(k) clearance databases, EU MDR notified body certificates, CMS Medicare bundled payment rules, hospital procurement contract filings, and orthopedic device registry publications. Bottom-up implant volume estimates and top-down market value reconstructions were triangulated across segmentation dimensions.
Across the analysis window, projections incorporate hip, knee, shoulder, elbow, and ankle implant categories crossed with ceramic, metal-on-metal, polyethylene, hybrid, cementless, and cemented fixation technologies. CAGRs were derived from procedural volume trajectories in osteoarthritis, rheumatoid arthritis, traumatic injury, avascular necrosis, and bone tumor applications, calibrated against reimbursement pathway evolution and ambulatory surgery center migration rates.
Decision-makers should treat outputs as directional under assumptions of stable FDA 510(k) clearance timelines and EU MDR notified body capacity recovery; material deviation would warrant model refresh. Forecasts reflect base-case assumptions regarding China tier-two hospital expansion pace and Brazil SUS reimbursement protocol implementation. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Orthopedic Devices
Pediatrics Orthotics Market
Orthopedic Devices
Europe Kyphoplasty Market
Orthopedic Devices
Animal External Fixation Market
Orthopedic Devices
Orthopaedic Cushions Market
Orthopedic Devices
Global Veterinary Orthopedics Market
Orthopedic Devices
Orthopedic Braces Market
Orthopedic Devices
Knee Cartilage Repair Market
Orthopedic Devices
India Orthopedic Braces and Supports Market
Orthopedic Devices
Veterinary Orthopedic Injectable Drug Market
Orthopedic Devices
Hip Replacement Market
Orthopedic Devices
Global Personalized 3D Printed Orthopedic Implants Market
Orthopedic Devices
Spine Devices Market
Orthopedic Devices
Orthopedic Wire Pin Driver Market
Orthopedic Devices
Cementless Total Knee Arthroplasty (TKA) Market
Orthopedic Devices
Antibacterial Orthopedic Implant Market
Orthopedic Devices
Small Bone and Joint Orthopedic Devices Market