
 Germany Post-Traumatic Stress Disorder Treatment Market | 2026-2036
Germany Post-Traumatic Stress Disorder Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Post-Traumatic Stress Disorder Treatment Market Insights
Digital therapeutic platforms is expanding access to evidence-based PTSD interventions beyond traditional clinic boundaries. Pfizer Inc. leverages its established psychiatric portfolio to sustain formulary presence across German sickness funds. Jazz Pharmaceuticals anchors its position through specialized CNS development programs targeting treatment-resistant trauma presentations. Merck KGaA competes via its broader neuroscience research infrastructure and hospital system partnerships.
Post-traumatic stress disorder treatment encompasses pharmacological agents targeting noradrenergic and serotonergic pathways, combined with structured psychotherapeutic protocols such as eye movement desensitization and reprocessing or prolonged exposure therapy, delivered to reduce intrusive symptoms and hyperarousal in trauma survivors. Therapeutic drugs occupy the largest value share due to established reimbursement pathways and chronic maintenance requirements, while digital therapeutics represents the fastest-expanding delivery category as Germany's DiGA fast-track approval pathway accelerates market entry for software-based interventions. Teletherapy delivery mode is gaining structural momentum following permanent regulatory flexibilities introduced during the pandemic period.
Germany's Federal Institute for Drugs and Medical Devices (BfArM) oversees DiGA approvals, while the Federal Joint Committee (G-BA) determines reimbursement status for novel therapeutic modalities, directly conditioning market access and provider prescribing behavior. The German Medicines Act (AMG) and Medical Devices Regulation framework impose clinical evidence standards that shape development timelines and commercialization strategies for emerging PTSD interventions. Stakeholders must monitor forthcoming G-BA benefit assessments for digital therapeutics and prepare health economic evidence dossiers that demonstrate comparative effectiveness against established face-to-face psychotherapy standards.
Market Dynamics
Germany's PTSD treatment landscape is undergoing structural transformation as the DiGA fast-track pathway accelerates software-based therapeutic entry, compressing traditional clinical trial timelines and forcing reimbursement negotiations ahead of established evidence accumulation.
Growth Catalysts
- G-BA Reimbursement Expansion:The Federal Joint Committee's broadened coverage for trauma-focused cognitive behavioral therapy through outpatient psychiatric clinics is pulling civilian trauma survivors into formal treatment pathways previously restricted to military populations.
- Teletherapy Regulatory Flexibility:Permanent pandemic-era flexibilities for remote psychotherapy delivery are dismantling geographic access barriers across rural Bavaria and eastern federal states.
- Digital Therapeutic Innovation:BfArM's streamlined approval process for prescription-grade mental health applications is attracting venture investment toward evidence-based software interventions.
Market Restraints
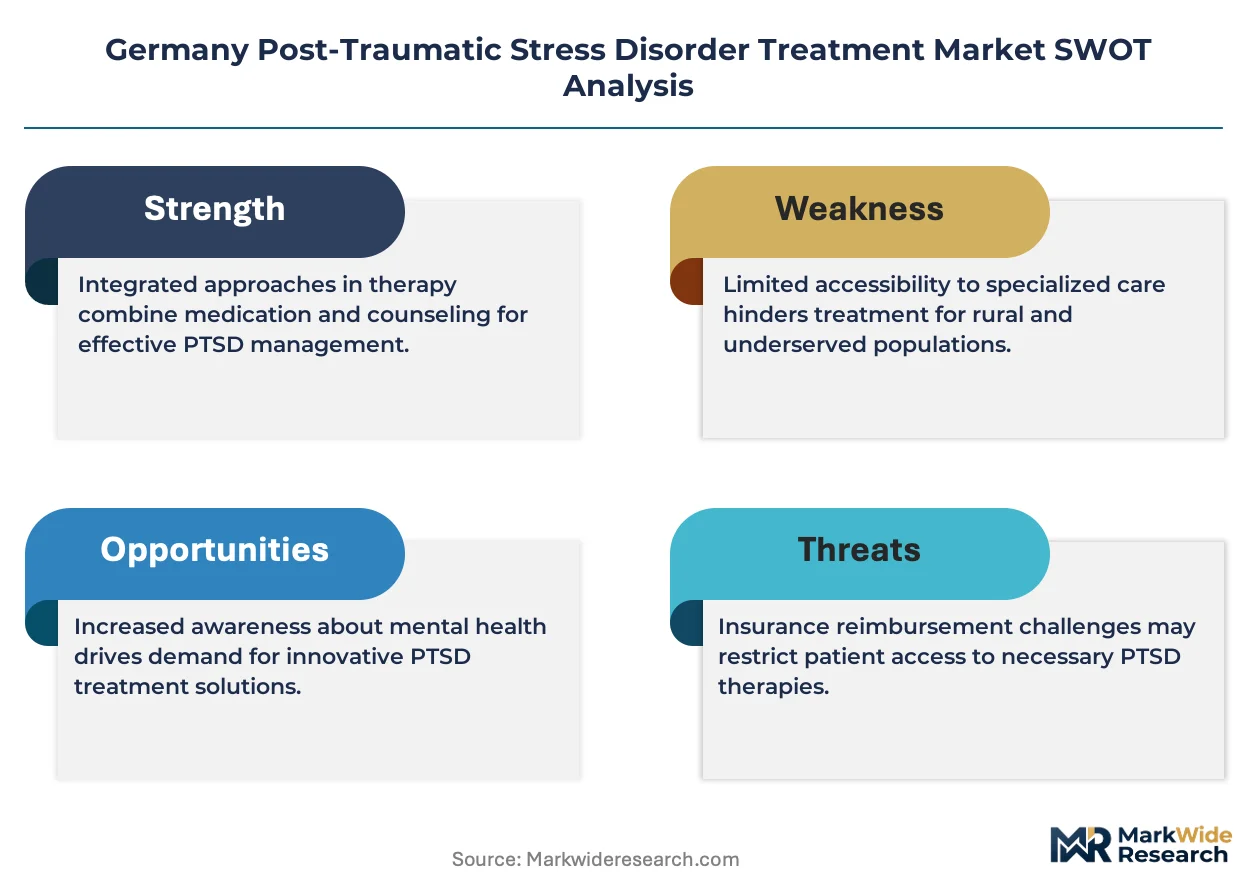
- Specialist Workforce Bottleneck:Germany's limited pool of EMDR-certified psychotherapists concentrates service delivery in metropolitan regions, extending wait times beyond six months in smaller cities.
- Pharmaceutical Reimbursement Compression:Sickness funds are tightening prior authorization requirements for novel serotonergic agents, favoring generic SSRI maintenance over branded alternatives.
- Evidence Standard Divergence:BfArM's requirement for randomized controlled trial data for DiGA approval creates friction against real-world evidence submissions common in other jurisdictions.
Strategic Opportunities
- Refugee and Asylum-Seeker Populations:Federal integration programs are creating funded channels for trauma services among displaced populations from Ukraine and the Middle East, representing underserved demand clusters in North Rhine-Westphalia reception centers.
- Employer-Sponsored Mental Health:Corporate wellness mandates under the German Occupational Safety Act are opening B2B procurement channels for preventive trauma screening and early intervention platforms.
- Integration with Neurological Care:Convergence of PTSD protocols with traumatic brain injury rehabilitation pathways in university hospital networks is creating bundled reimbursement opportunities.
Industry Challenges
- Digital-Clinical Workflow Integration:Psychiatric clinics struggle to incorporate DiGA prescriptions into existing electronic health record systems, creating administrative friction that suppresses physician adoption.
- Cross-State Licensing Complexity:Psychotherapists licensed in one federal state face procedural barriers to delivering teletherapy to patients residing in jurisdictions with divergent continuing education requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Post-Traumatic Stress Disorder Treatment Market |
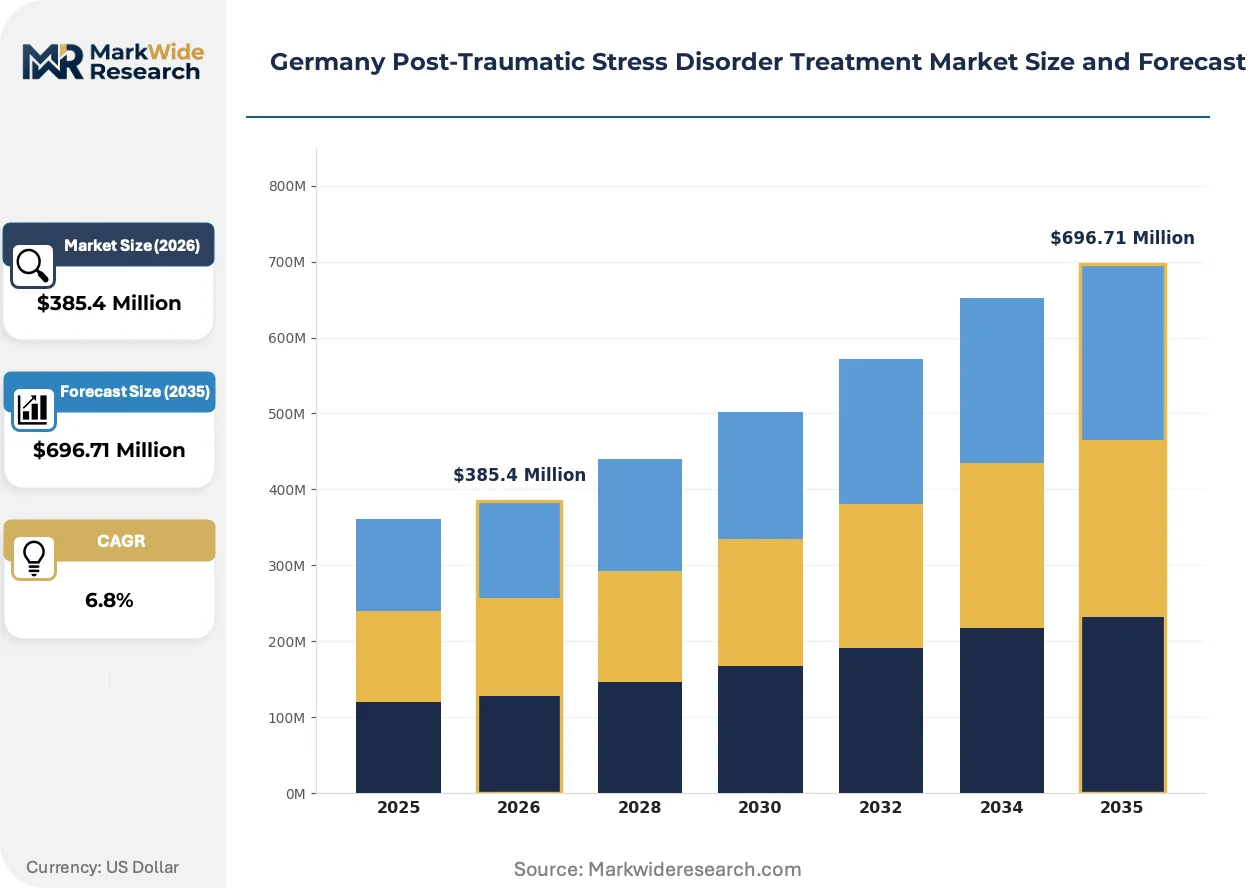
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $696.71 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Therapeutic Drugs, Psychotherapy, Digital Therapeutics, Support Groups Delivery Mode: In-Person, Online, Hybrid, Teletherapy End User: Veterans, Civilian Patients, Healthcare Providers, Nonprofits Age Group: Adults, Adolescents, Seniors, Children |
| Companies Covered | Pfizer Inc., GlaxoSmithKline plc, Merck KGaA, Jazz Pharmaceuticals, Otsuka Pharmaceutical, Viatris Inc., Aurobindo Pharma Limited, Bionomics Limited, H. Lundbeck A/S, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Post-Traumatic Stress Disorder Treatment Market Trends and Innovations
Artificial intelligence and immersive technologies are restructuring how trauma interventions are delivered, validated, and reimbursed across German healthcare infrastructure. Three developments are compressing the gap between clinical research and patient access.
Virtual reality exposure therapy systems are integrating haptic feedback and biometric monitoring to create controlled trauma re-experiencing environments. Outpatient psychiatric clinics in Berlin and Munich are piloting these platforms for treatment-resistant PTSD presentations. The technology is integrating physiological response data into algorithmic session adaptation, enabling personalized dosing of exposure intensity that manual protocols cannot replicate.
The German Medicines Act amendments implementing the EU Medical Devices Regulation are elevating clinical evidence requirements for software-based therapeutic devices. BfArM's updated guidance demands active comparator trials against face-to-face psychotherapy rather than placebo controls, extending development timelines but raising the evidentiary bar for market entry. Early-stage developers are responding by partnering with university hospitals for investigator-initiated studies.
Patient-initiated care pathways are displacing traditional physician-gatekept access models for mental health services. Direct-to-consumer digital platforms are capturing trauma survivors through employer wellness portals and health insurer prevention programs, bypassing the Hausarzt referral bottleneck. This shift is most pronounced among employed adults aged 25-40 in urban centers, where stigma concerns and scheduling constraints favor asynchronous digital engagement over clinic-based intake.
Germany Post-Traumatic Stress Disorder Treatment Market Segmentation
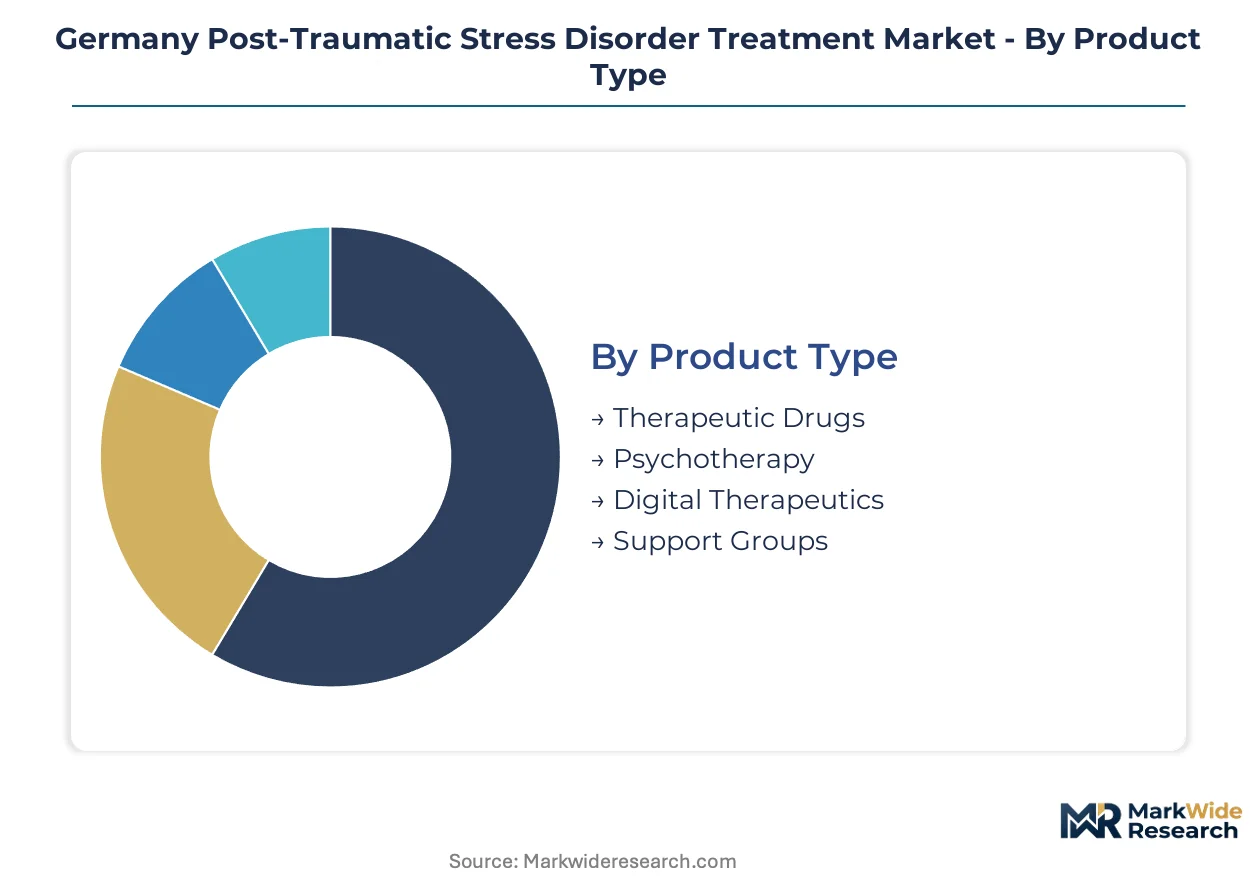
PTSD treatment modalities in Germany fragment across intervention types, delivery channels, and patient populations. Reimbursement pathways from G-BA and BfArM DiGA approvals create divergent commercial trajectories for each segment cluster.
Product Type:
Supply concentration for evidence-based PTSD interventions pools within therapeutic drugs and psychotherapy protocols, while digital therapeutics attract venture capital toward regulatory fast-tracks.
- Therapeutic Drugs:Serotonergic and noradrenergic agents targeting hyperarousal and intrusive symptoms dominate outpatient prescribing. Sickness fund reimbursement concentrates maintenance therapy volumes in metropolitan psychiatric practices across Berlin and Munich.
- Psychotherapy:Trauma-focused cognitive behavioral therapy and EMDR protocols require certified practitioner networks. Specialist workforce bottlenecks in Bavaria and eastern federal states extend wait times beyond six months.
- Digital Therapeutics:BfArM's DiGA pathway accelerates prescription-grade software entry. North Rhine-Westphalia clinics pilot VR exposure systems with haptic feedback integration.
- Support Groups:Peer-facilitated trauma recovery programs operate through nonprofit channels with limited statutory reimbursement.
Today's leader: Therapeutic Drugs. Tomorrow's challenger: Digital Therapeutics.
Delivery Mode:
Cost tier differentiation separates reimbursed clinical encounters from emerging direct-to-consumer channels reshaping patient acquisition economics.
- In-Person:Face-to-face psychiatric and psychotherapeutic sessions retain highest reimbursement rates. University hospital networks in Hamburg and Cologne anchor specialized trauma service concentration.
- Teletherapy:Permanent pandemic-era regulatory flexibilities dismantle geographic barriers. Rural Bavaria and eastern federal states access metropolitan specialist pools through video-based delivery.
- Online:Asynchronous digital platforms bypass Hausarzt referral requirements. Employer wellness portals and health insurer prevention programs drive urban adoption among employed adults aged 25-40.
- Hybrid:Blended protocols combine initial in-person assessment with digital maintenance modules. Psychiatric clinics struggle with EHR integration creating administrative adoption friction.
Volume concentrates in In-Person delivery. Margin expansion follows Teletherapy scaling.
End User:
Application-driven demand splits between statutory-funded clinical populations and emerging B2B procurement channels under occupational safety mandates.
- Civilian Patients:G-BA reimbursement expansion pulls trauma survivors into formal treatment pathways. Outpatient psychiatric clinics in Berlin and North Rhine-Westphalia widen service capacity.
- Veterans:Bundeswehr and federal police trauma services maintain dedicated referral networks with specialized CNS protocols.
- Healthcare Providers:Psychiatric clinics and university hospitals procure bundled intervention platforms integrating pharmacological and psychotherapeutic modalities.
- Nonprofits:Refugee integration programs fund trauma services for displaced Ukrainian and Middle Eastern populations in North Rhine-Westphalia reception centers.
Patient volume leader: Civilian Patients. Procurement innovation center: Healthcare Providers.
Age Group:
Customer type segmentation reflects divergent regulatory oversight intensity and developmental adaptation requirements for trauma protocols.
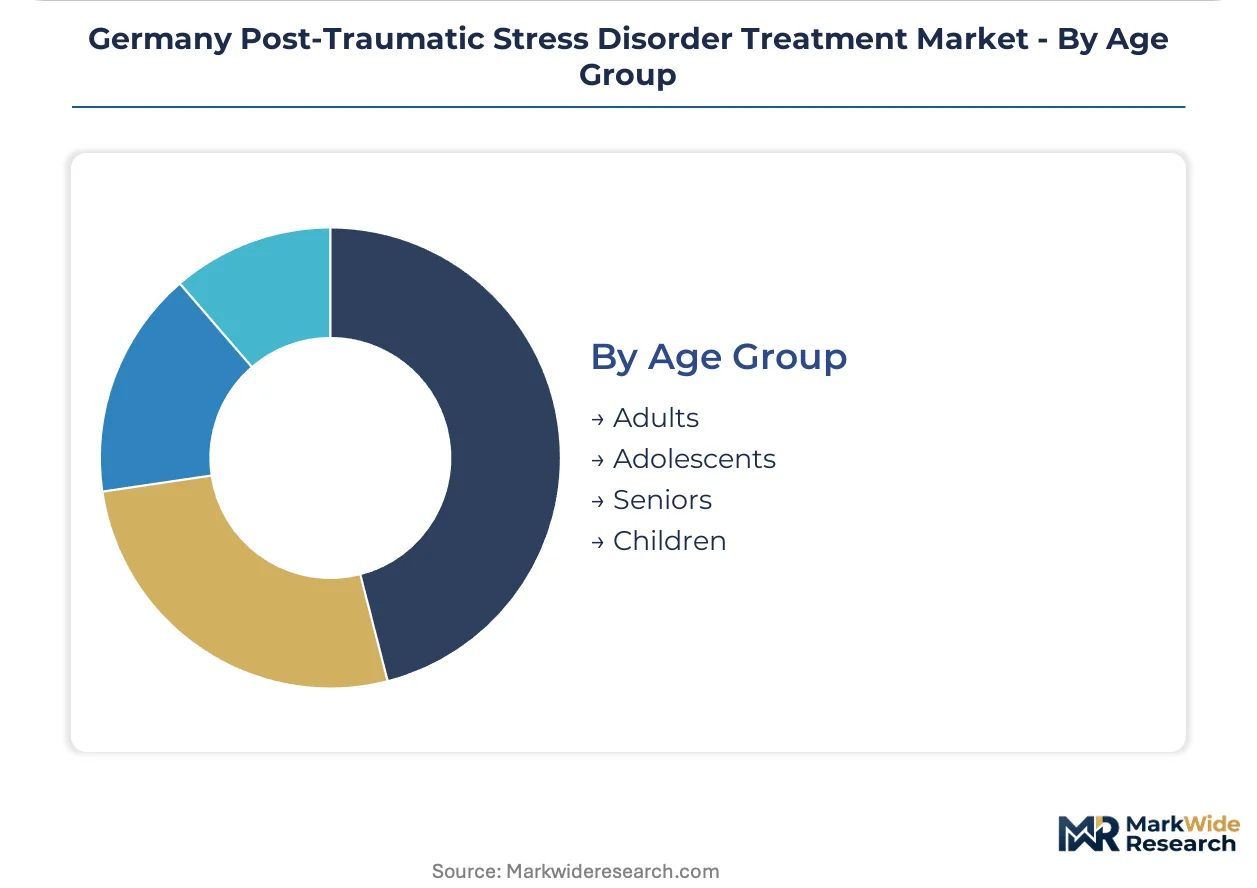
- Adults:Employed populations aged 25-55 drive employer-sponsored mental health program adoption. Corporate wellness mandates under German Occupational Safety Act expand B2B channels.
- Adolescents:School-based trauma screening and early intervention platforms target secondary education institutions. Federal state education ministries pilot preventive mental health integration.
- Seniors:Late-onset PTSD presentations from historical trauma or medical events concentrate in geriatric psychiatric services with polypharmacy complexity.
- Children:Developmentally adapted trauma protocols require specialized child and adolescent psychiatry certification limiting provider pool concentration.
Commercial maturity sits with Adults. Steepest expansion trajectory: Adolescents.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Berlin anchors Germany's PTSD treatment infrastructure through its concentration of university hospitals and outpatient psychiatric networks. The Federal Joint Committee's reimbursement policies shape regional service availability across federal states. Digital therapeutic adoption clusters in metropolitan corridors where BfArM's DiGA pathway accelerates market entry.
North Rhine-Westphalia
Refugee integration programs drive trauma service demand through reception centers serving Ukrainian and Middle Eastern populations. The state's Ministry of Health coordinates with G-BA on outpatient psychiatric expansion. Cologne and Düsseldorf host specialized university hospital networks piloting VR exposure therapy systems.
Bavaria
Rural access gaps concentrate demand for teletherapy delivery across eastern federal state regions. The Bavarian State Ministry of Health and Care administers pandemic-era regulatory flexibilities for remote psychotherapy. Munich anchors metropolitan specialist pools while smaller cities face EMDR-certified practitioner shortages exceeding six-month wait times.
Baden-Württemberg
Employer-sponsored mental health programs expand under German Occupational Safety Act corporate wellness mandates. The state's integration ministry funds trauma screening for displaced populations. Stuttgart and Mannheim concentrate psychiatric clinic capacity with emerging hybrid delivery protocols.
Hamburg
Port city logistics and maritime industries generate occupational trauma cases requiring specialized intervention pathways. The Hamburg Ministry of Health and Consumer Protection oversees hospital system partnerships with neurological rehabilitation centers. University hospital networks bundle PTSD protocols with traumatic brain injury treatment.
Lower Saxony
Bundeswehr trauma services maintain dedicated referral networks for federal police and military populations. The Lower Saxony Ministry of Social Affairs coordinates with statutory health insurers on sickness fund prior authorization processes. Hanover anchors specialized CNS development program access for treatment-resistant presentations.
Germany Post-Traumatic Stress Disorder Treatment Market Competitive Landscape
Portfolio diversification dominates the current landscape as pharmaceutical incumbents extend psychiatric formulary presence while digital therapeutic developers accelerate BfArM pathway navigation. The market structures around three tiers: established multinational drug manufacturers with sickness fund relationships, specialized CNS-focused developers, and emerging software-based intervention platforms. Strategic archetypes include reimbursement-anchored incumbents leveraging statutory health insurance contracts, evidence-building specialists pursuing DiGA fast-track approvals, and hybrid platform developers integrating pharmacological and psychotherapeutic modalities. M&A activity concentrates on digital therapeutic capability acquisition, while strategic partnerships between university hospitals and software developers accelerate clinical trial execution.
Among established pharmaceutical incumbents, Pfizer Inc. and Merck KGaA occupy positions reflecting broad neuroscience research infrastructure and hospital system partnerships. Jazz Pharmaceuticals exemplifies the specialized CNS development archetype targeting treatment-resistant trauma presentations. These three companies represent distinct competitive vectors: formulary maintenance through generic and branded portfolios, research-platform breadth, and focused development program depth.
| Leading Market Players |
|---|
| Pfizer Inc. |
| GlaxoSmithKline plc |
| Merck KGaA |
| Jazz Pharmaceuticals |
| Otsuka Pharmaceutical |
| Viatris Inc. |
| Aurobindo Pharma Limited |
| Bionomics Limited |
| H. Lundbeck A/S |
| Others |
Pricing and Supply Chain Analysis
Reimbursement-tier divergence between statutory-covered clinical services and direct-to-consumer digital platforms manifests in both pricing structures and supply configurations across German PTSD treatment markets. G-BA-determined reimbursement rates for face-to-face psychotherapy anchor premium pricing for certified practitioner networks, while DiGA-approved digital therapeutics compete on asynchronous delivery economics that bypass traditional Hausarzt gatekeeping.
Pricing Analysis
Input-cost pass-through from specialist workforce scarcity drives pricing stratification across delivery modes. Statutory reimbursement rates for EMDR-certified psychotherapists in Berlin and Munich sustain premium tier positioning, while teletherapy platforms compete on geographic arbitrage using eastern European practitioner pools. Sickness fund prior authorization tightening for novel serotonergic agents compresses pharmaceutical margins, favoring generic SSRI substitution. Employer-sponsored mental health programs exhibit lowest price sensitivity due to Occupational Safety Act compliance mandates, whereas individual civilian patients in statutory insurance demonstrate highest sensitivity to out-of-pocket cost exposure for non-reimbursed digital interventions.
Supply Chain Analysis
Direct-to-clinic channels handle specialized therapeutic drug distribution through pharmaceutical wholesalers with sickness fund contracting relationships. Active pharmaceutical ingredient supply draws from India and China for generic serotonergic agents, while proprietary CNS compounds source from Switzerland and USA manufacturing networks. Software-based therapeutic development rests on cloud infrastructure provision from Irish and German data centers compliant with BfArM cybersecurity requirements. Single-source vulnerability concentrates in EMDR-certified practitioner training pipelines accredited through limited German psychotherapy chambers. Distribution runs through statutory health insurance pharmacy networks for pharmacological agents, while DiGA platforms deploy direct-to-patient prescription fulfillment integrated with electronic health record systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Germany's PTSD treatment market offers geographic-arbitrage positioning between its stringent BfArM evidence standards and neighboring jurisdictions with accelerated real-world evidence pathways, creating cost-differential opportunities for clinical trial placement and regulatory submission sequencing.
For Market Incumbents: Deepen vertical integration into digital therapeutic development capabilities to defend against software-native entrants exploiting DiGA fast-track advantages. Acquire specialized CNS development programs targeting treatment-resistant trauma presentations before valuation inflation from refugee integration funding. Prioritize sickness fund formulary maintenance contracts as teletherapy regulatory flexibilities expand competitive pressure from asynchronous platform providers. For New Entrants and Emerging Players: Begin with employer-sponsored mental health procurement channels under German Occupational Safety Act mandates, where B2B sales cycles bypass traditional clinical adoption friction. Target refugee integration programs in North Rhine-Westphalia reception centers as the most penetrable demand cluster with dedicated federal funding streams. Pursue strategic partnerships with university hospital networks to generate BfArM-compliant randomized controlled trial data against face-to-face psychotherapy comparators. For Investors and Strategic Acquirers: Consolidation pressure builds where digital therapeutic developers lack clinical evidence generation infrastructure to satisfy BfArM's active comparator trial requirements. Position acquisition targets around software platforms with existing DiGA approvals and established university hospital investigator-initiated study relationships. Watch G-BA benefit assessment timelines for digital therapeutics as the inflection signal determining reimbursement parity with established psychotherapy protocols.| Strategic Initiative | Industry Significance |
|---|---|
| DiGA Fast-Track Navigation | BfArM approval accelerates market entry for prescription-grade mental health software platforms. |
| University Hospital Partnership | Investigator-initiated studies generate active comparator trial data against face-to-face psychotherapy standards. |
| Sickness Fund Contracting | G-BA reimbursement determination secures statutory insurance coverage for novel therapeutic modalities. |
| Refugee Integration Channel Development | Federal reception center funding creates funded demand clusters for trauma service provision. |
| Teletherapy Platform Integration | Permanent pandemic-era regulatory flexibilities enable geographic arbitrage across federal state licensing boundaries. |
Research Methodology
Direct dialogue with psychiatric clinic directors, psychotherapist chamber representatives, pharmaceutical regulatory affairs leads, and sickness fund formulary managers grounded qualitative assessment of reimbursement dynamics and adoption barriers. Secondary validation incorporated BfArM DiGA approval databases, G-BA benefit assessment documentation, German Medicines Act amendment texts, and statutory health insurance prescription volume records. Bottom-up demand modeling triangulated against top-down healthcare expenditure projections across the analysis window.
Bottom-up segmentation analysis modeled patient volume flows by delivery mode, product type, and end-user category throughout the forecast period. Top-down macro validation referenced German healthcare expenditure growth parameters and mental health service capacity expansion targets. CAGR derivation integrated historical reimbursement policy evolution patterns with projected G-BA digital therapeutic assessment timelines. Treatment-resistant population prevalence estimates and specialist workforce graduation rates served as industry-specific forecast sensitivity inputs.
Several conditions sit outside the modeled scope, including potential AMG amendments implementing EU Medical Devices Regulation revisions, unforeseen G-BA reimbursement category reclassifications, and Bundeswehr trauma service privatization initiatives. Forecasts reflect base-case assumptions regarding regulatory stability and DiGA approval pathway continuity. Periodic stress-testing of base assumptions is recommended against emerging real-world evidence submission standards and cross-border teletherapy licensing harmonization developments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Mental Health Services
Spain Post-Traumatic Stress Disorder Treatment Market
Mental Health Services
Behavioral Health Software Market
Mental Health Services
US Workplace Stress Management Market
Mental Health Services
North America Maternal Mental Health Market
Mental Health Services
Postpartum Depression Management Market
Mental Health Services
Global Mental Health Care Software and Services Market
Mental Health Services
Obsessive-Compulsive Disorder Market
Mental Health Services
Agoraphobia Market
Mental Health Services
Seasonal Affective Disorder (SAD) Market
Mental Health Services
Schizoaffective Disorders Treatment Market
Mental Health Services
US Behavioral Health Market
Mental Health Services
Depression Treatment Market
Mental Health Services
Anxiety Disorders and Depression Treatment Market
Mental Health Services
Global Workplace Stress Management Market
Mental Health Services
AI-Powered Mental Health Solutions Market
Mental Health Services
Agoraphobia Treatment Market