
 Global Intravascular Temperature Management Market | 2026-2036
Global Intravascular Temperature Management Market Size, Share, and Industry Trends Forecast 2026-2036
Global Intravascular Temperature Management Market Intelligence
Emergency services departments are redrawing procurement priorities for intravascular temperature management systems, overtaking traditional surgical center buyers as the fastest-growing customer archetype. Smiths Medical leverages its established critical care channel presence to sustain high-visibility placements in Level I trauma centers across North America. Medtronic Plc anchors its position through deep integration with cardiac surgery workflows, while Zoll Medical Corporation competes aggressively in pre-hospital and transport medicine segments where portable cooling/heating units command premium positioning.
Intravascular temperature management encompasses catheter-based systems that circulate chilled or warmed saline through closed-loop lumens to modulate core body temperature within precision ranges of 0.5°C, primarily serving therapeutic hypothermia induction and normothermia maintenance in acute neurological and cardiovascular events. Temperature control catheters generate the dominant revenue pool due to recurring catheter replacement cycles and proprietary disposable designs that lock hospitals into single-source supply agreements. Thermal regulation devices are expanding fastest among mobile medical unit deployments, where compact form factors and battery-independent operation address field evacuation scenarios that fixed hospital installations cannot serve.
FDA 510(k) clearance requirements and EU MDR technical documentation obligations are elevating barriers for new entrants while compelling incumbents to invest in clinical evidence generation for expanded indications. Japan's PMDA enforces stringent electrical safety and biocompatibility testing under JIS standards that delay market entry but reward persistent applicants with durable competitive moats. Stakeholders must monitor evolving reimbursement decisions for targeted temperature management in stroke protocols, as coverage determinations by CMS and analogous bodies will directly shape hospital capital allocation and device utilization rates.
Market Dynamics
Emergency medicine protocols are redefining the addressable patient population for catheter-based thermal modulation, as stroke and cardiac arrest guidelines incorporate therapeutic hypothermia into standard-of-care pathways across Level I trauma centers.
Growth Catalysts
- FDA 510(k) pathway consolidation:Streamlined premarket notification processes for thermal regulation devices are accelerating commercialization timelines for catheter-based systems targeting neurological indications.
- Pre-hospital emergency services:Mobile medical units and air ambulance fleets are expanding device deployments to bridge temperature management during patient transport from field to definitive care.
- Japan neurocritical care infrastructure:PMDA-authorized hospitals are scaling dedicated stroke centers that mandate precision temperature control capabilities under national cardiovascular disease reduction mandates.
Market Restraints
- Single-source catheter supply agreements:Proprietary disposable designs lock purchasing departments into elevated recurring costs with limited vendor switching flexibility.
- EU MDR technical documentation burdens:Expanded clinical evidence requirements for Class IIb thermal regulation devices are extending certification timelines and elevating compliance expenditures.
- Biocompatible polymer input volatility:Specialized medical-grade polyurethane and silicone supply concentration in East Asian manufacturing clusters creates price instability for catheter production.
Strategic Opportunities
- India tertiary hospital expansion:CDSCO-registered medical device importers are establishing distribution partnerships as corporate hospital chains build dedicated neuro-ICU capacity in Mumbai, Delhi, and Bangalore.
- Pediatric temperature management protocols:Neonatal and pediatric cardiac surgery programs represent an underserved application segment with distinct catheter sizing and flow rate requirements.
- ISO 13485:2016 quality management convergence:Harmonized international standards for medical device quality systems are reducing duplicate audit burdens for manufacturers seeking multi-jurisdiction market access.
Industry Challenges
- Specialized perfusionist staffing shortages:Qualified clinicians capable of operating extracorporeal temperature modulation systems during complex cardiac procedures remain concentrated in established academic medical centers.
- Legacy EMR integration complexity:Proprietary device data protocols require custom interface development to feed continuous temperature monitoring into hospital electronic medical record systems.
- Extended JIS electrical safety certification:PMDA-mandated testing cycles for Japanese market entry create 18-24 month approval gaps that delay revenue recognition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Intravascular Temperature Management Market |
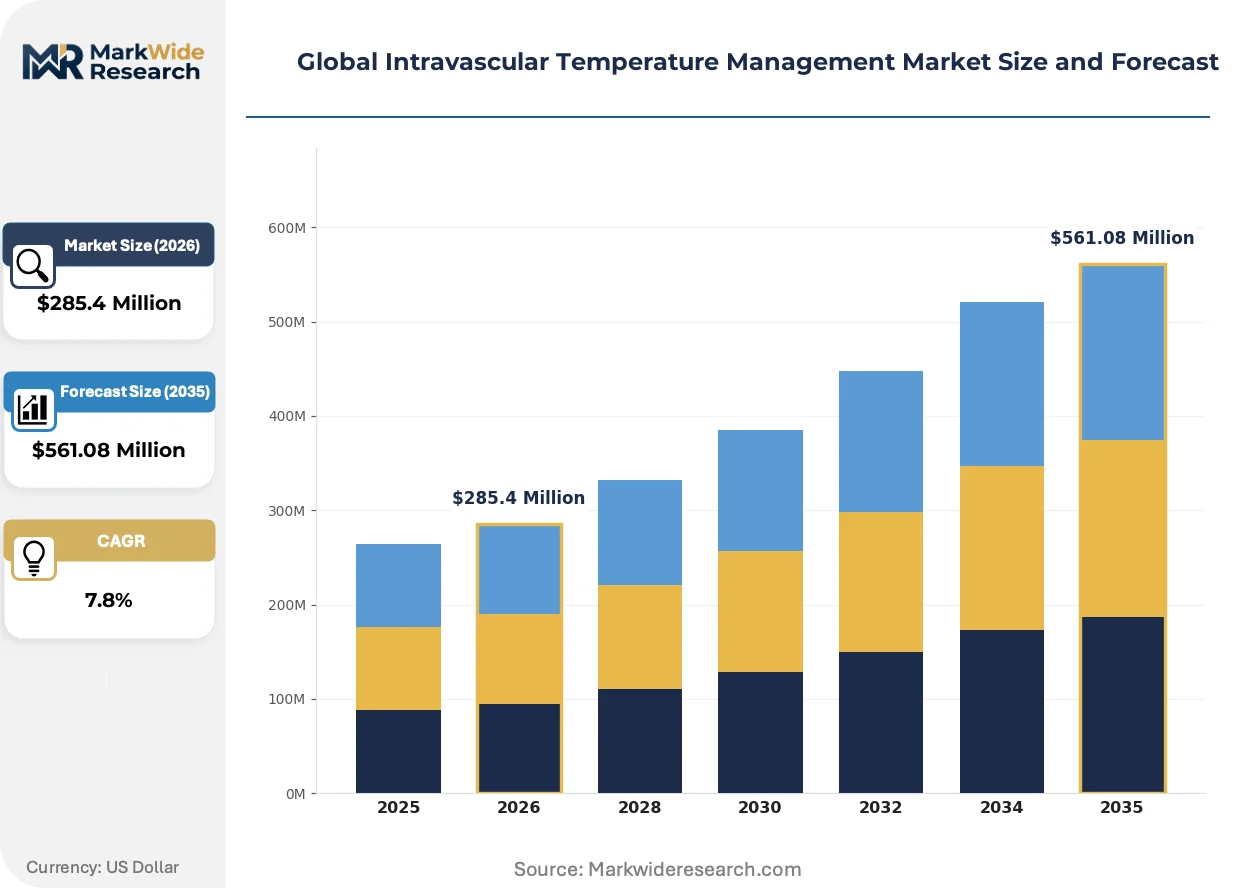
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $561.08 Million |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Temperature Control Catheters, Thermal Regulation Devices, Circulation Control Systems, Cooling/Heating Units Application: Cardiac Arrest Treatment, Stroke Management, Fever Control, Traumatic Brain Injury Therapy, Postoperative Care End User: Intensive Care Units, Neurology Departments, Emergency Services, Surgical Centers Deployment: Hospital-Based Installation, Mobile Medical Units, Specialized Clinics, Research Institutes |
| Companies Covered | 3M Company, Smiths Medical, Medtronic Plc, Belmont Instrument, Gentherm, Stryker Corporation, Becton, Dickinson And Company, Biegler GmbH, Zoll Medical Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Intravascular Temperature Management Market Strategic Shifts & Innovations
Catheter-based thermal modulation is fragmenting into modular, indication-specific platforms rather than universal systems, as manufacturers optimize form factors for distinct clinical environments from operating theaters to ground ambulances.
Closed-loop feedback control architectures are decomposing traditional open-loop temperature management workflows. These sensor-integrated catheter systems enable automated saline flow rate adjustments without continuous clinician intervention. Neuro-ICU departments in Germany and the United States are adopting these platforms fastest, compressing staffing intensity requirements for 24-hour hypothermia maintenance protocols.
EU MDR post-market surveillance obligations are tightening real-world performance documentation requirements for thermal regulation devices. Manufacturers must now submit periodic safety update reports with device-specific clinical data. Temperature control catheter suppliers are responding by embedding encrypted usage logging to automate adverse event detection and streamline PSUR preparation.
Hospital purchasing committees are consolidating temperature management device selection authority from individual service lines into centralized value analysis teams. This centralization displaces department-level procurement autonomy and elevates total cost-of-ownership calculations over upfront capital expenditure. The shift is most pronounced in United States integrated delivery networks and German hospital federations seeking standardized device fleets across multi-site systems.
Global Intravascular Temperature Management Market Segmentation
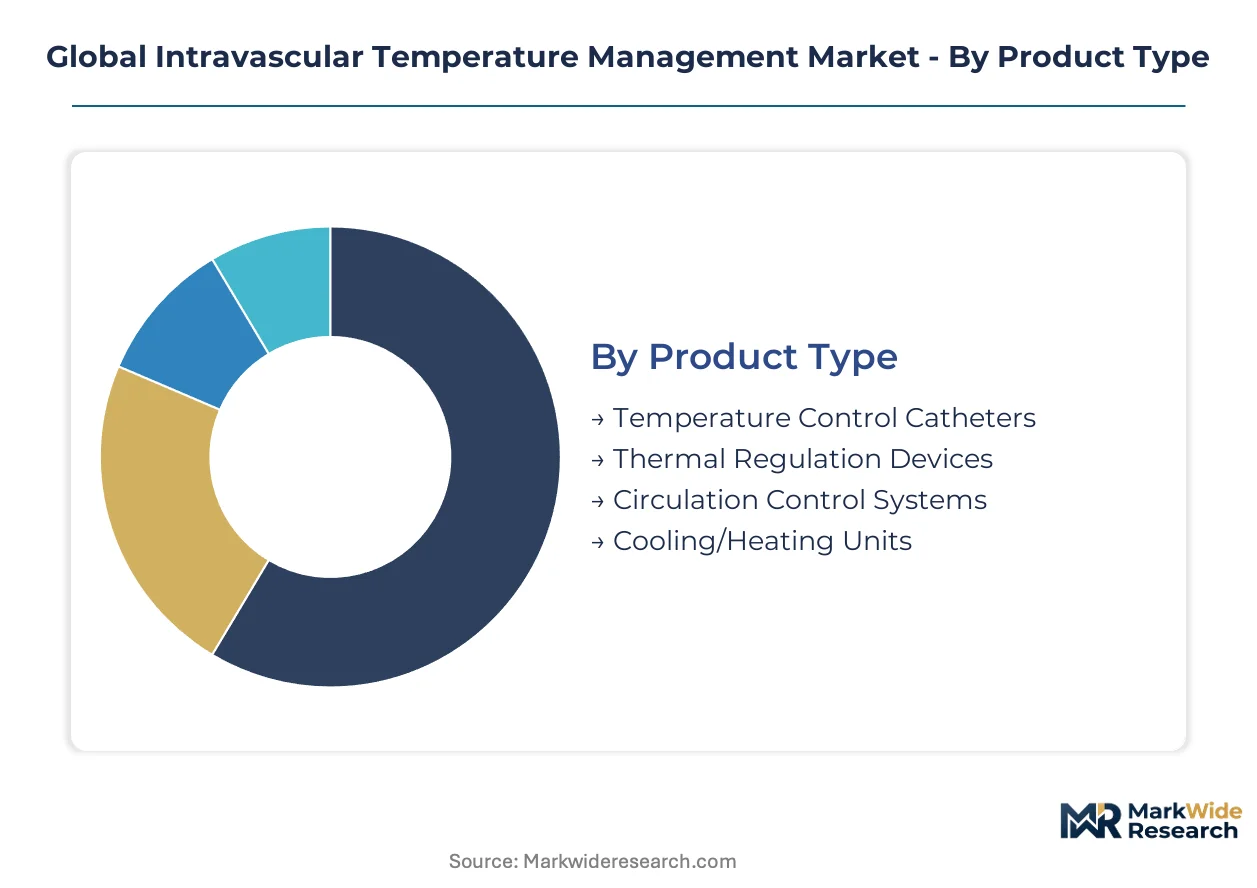
Segmentation in intravascular temperature management reveals distinct procurement patterns across acute care settings. Product architecture, clinical application, and deployment environment each shape vendor selection criteria and pricing structures differently.
Product Type:
Domestic production concentrates on thermal regulation devices in the United States and Germany, while temperature control catheters flow primarily from specialized East Asian polymer manufacturing clusters.
- Temperature Control Catheters:Closed-loop lumens circulate chilled or warmed saline through proprietary disposable designs that lock hospitals into recurring replacement cycles. Demand clusters in Level I trauma centers across the United States and stroke centers in Japan where precision 0.5°C modulation is mandatory for therapeutic hypothermia protocols.
- Thermal Regulation Devices:Console-based pump and heat exchanger systems anchor fixed hospital installations with integrated sensor feedback architectures. German neuro-ICU departments and United States academic medical centers drive adoption of automated flow rate adjustment capabilities that reduce staffing intensity for 24-hour temperature maintenance.
- Circulation Control Systems:Peripheral and central venous access platforms with integrated temperature monitoring.
- Cooling/Heating Units:Portable battery-independent systems serving pre-hospital and air ambulance transport segments.
Temperature control catheters hold the largest share; momentum sits with cooling/heating units.
Application:
Cost tier stratification separates capital-intensive cardiac surgery workflows from emergency department rapid-deployment protocols with lower equipment footprints.
- Cardiac Arrest Treatment:Therapeutic hypothermia induction within six hours of return of spontaneous circulation requires precise 32-34°C core temperature maintenance. United States hospital emergency departments and Japanese cardiovascular centers prioritize FDA-cleared and PMDA-authorized systems respectively.
- Stroke Management:Ischemic stroke protocols mandate normothermia maintenance to prevent hyperthermia-associated neurological deterioration. German stroke units and United States comprehensive stroke centers are expanding catheter-based modulation as standard-of-care infrastructure scales under national cardiovascular reduction mandates.
- Fever Control:Refractory fever management in sepsis and neurological injury.
- Traumatic Brain Injury Therapy:Targeted temperature management to reduce intracranial pressure.
- Postoperative Care:Normothermia maintenance following major thoracic and vascular procedures.
Cardiac arrest treatment commands the dominant equipment allocation; stroke management is climbing the fastest as neurocritical care infrastructure expands.
End User:
Customer type fragmentation pits centralized value analysis teams against legacy department-level procurement autonomy across integrated delivery networks.
- Intensive Care Units:Neuro-ICU and cardiac ICU departments deploy fixed-installation console systems with continuous EMR integration requirements. United States academic medical centers and German hospital federations concentrate demand for automated closed-loop platforms that compress nurse-to-patient ratios during prolonged hypothermia protocols.
- Emergency Services:Pre-hospital and transport medicine segments require compact battery-independent units for field evacuation scenarios. Air ambulance fleets in the United States and ground mobile units in Japan are expanding deployments to bridge temperature management from scene to definitive care.
- Neurology Departments:Inpatient stroke units with dedicated temperature management protocols.
- Surgical Centers:Ambulatory and short-stay facilities with selective hypothermia indications.
Intensive care units retain the installed base majority; emergency services represent the steepest expansion trajectory as pre-hospital protocols mature.
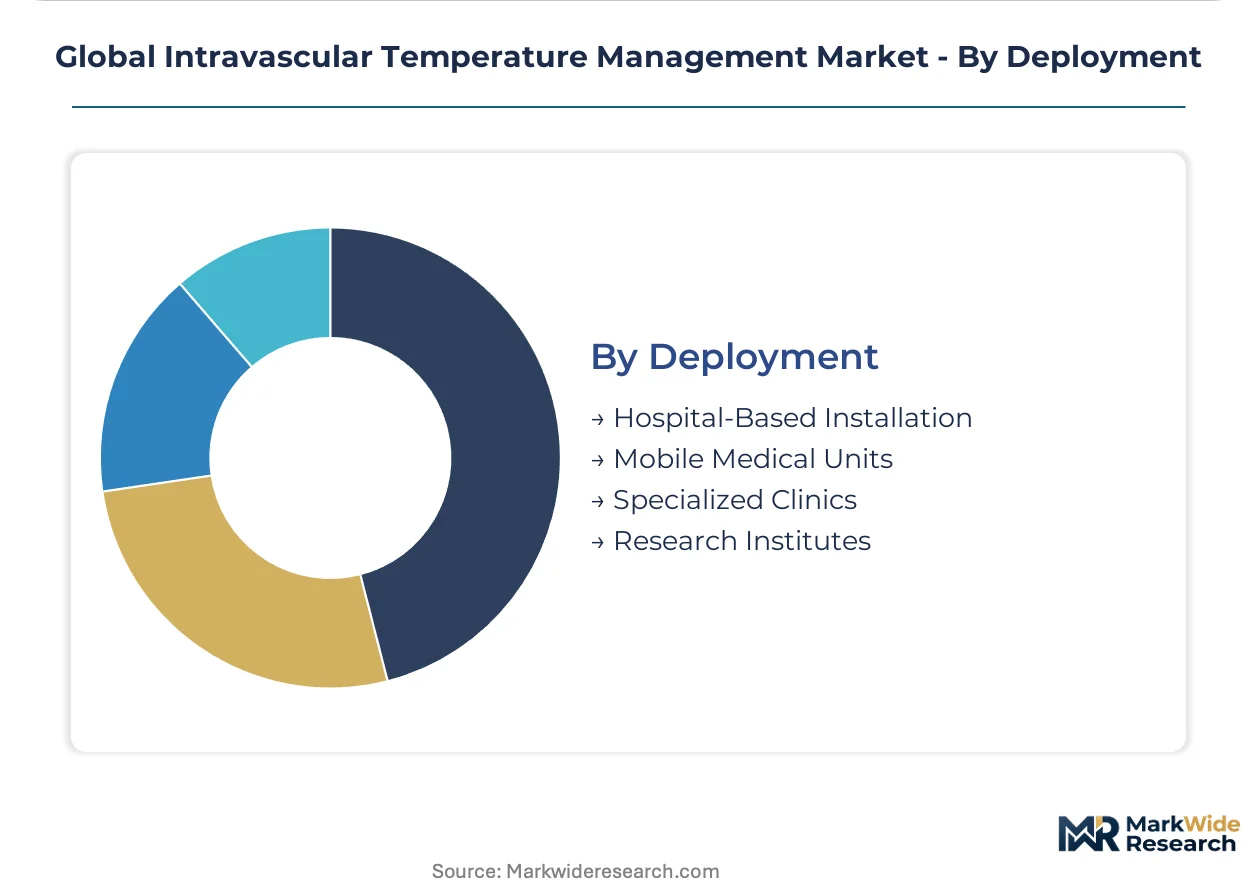
Deployment:
Supply concentration in specialized catheter manufacturing creates geographic dependency patterns that favor regional sourcing for disposable components against centralized device production.
- Hospital-Based Installation:Fixed console systems with dedicated utility connections and EMR integration infrastructure. United States Level I trauma centers and Japan PMDA-authorized stroke centers anchor demand for premium-tier automated platforms with encrypted usage logging for EU MDR post-market surveillance compliance.
- Mobile Medical Units:Ground ambulances and air ambulance fleets deploy portable cooling/heating systems with rapid deployment form factors. Pre-hospital services in the United States and emergency transport networks in Germany are scaling fleet-wide standardization to ensure continuity of temperature management during patient transfer.
- Specialized Clinics:Outpatient cardiac and neurological intervention facilities.
- Research Institutes:Academic and clinical trial settings investigating expanded indications.
Hospital-based installation dominates capital expenditure; mobile medical units are gaining share fastest as pre-hospital emergency services expand device procurement authority.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States interstate highway network and dedicated air ambulance corridors enable rapid patient transport from field to definitive care, underwriting North American leadership in pre-hospital temperature management deployment.
United States
Level I trauma centers in Houston, Chicago, and Los Angeles are expanding neuro-ICU capacity under Joint Commission stroke certification mandates. FDA 510(k) clearance pathways for catheter-based thermal regulation devices are streamlining commercialization timelines for neurological indications. Boston and Baltimore academic medical clusters anchor demand for automated closed-loop platforms with encrypted usage logging.
Germany
Comprehensive stroke centers in Munich and Berlin are scaling catheter-based normothermia maintenance under national cardiovascular disease reduction targets. EU MDR technical documentation requirements for Class IIb thermal regulation devices are extending certification timelines while elevating compliance expenditures. The Baden-Württemberg medical technology corridor concentrates console manufacturing for European hospital installations.
Japan
PMDA-authorized hospitals in Tokyo and Osaka are building dedicated stroke centers with mandatory precision temperature control capabilities. JIS electrical safety testing under METI oversight creates 18-24 month approval gaps that delay market entry but reward persistent applicants. The Kansai region hosts specialized polymer manufacturing for biocompatible catheter components.
India
Corporate hospital chains in Mumbai, Delhi, and Bangalore are constructing neuro-ICU capacity as CDSCO-registered medical device importers establish distribution partnerships. Central Drugs Standard Control Organization import licensing requirements are elevating documentation burdens for thermal regulation console suppliers. The Maharashtra pharmaceutical corridor is attracting catheter assembly partnerships with East Asian polymer suppliers.
United Kingdom
NHS England stroke unit certification in London, Manchester, and Birmingham is driving standardization of therapeutic hypothermia protocols. MHRA post-Brexit regulatory alignment with EU MDR is creating transitional uncertainty for thermal device manufacturers. The Cambridge-Oxford medical research cluster is generating clinical evidence for expanded pediatric temperature management indications.
Global Intravascular Temperature Management Market Key Industry Players
Concentration sits with diversified critical care conglomerates that leverage established hospital channel relationships to secure high-visibility placements. The vendor base spans three distinct tiers: multinational medical device conglomerates with cardiac surgery workflow integration, mid-scale temperature management specialists with neuro-ICU focus, and regional distributors serving emerging market import channels. Strategic moves center on portfolio diversification into pediatric catheter sizing and backward integration into biocompatible polymer compounding.
Within the diversified conglomerate tier, Medtronic Plc and Stryker Corporation exemplify scale-driven positioning through deep integration with surgical service lines. Smiths Medical occupies a position anchored in critical care channel density across North American trauma centers. Zoll Medical Corporation represents the pre-hospital specialist archetype, with geographic origin signaling transport medicine expertise. Biegler GmbH exemplifies German engineering-focused positioning in precision thermal regulation consoles.
| Leading Market Players |
|---|
| 3M Company |
| Smiths Medical |
| Medtronic Plc |
| Belmont Instrument |
| Gentherm |
| Stryker Corporation |
| Becton, Dickinson And Company |
| Biegler GmbH |
| Zoll Medical Corporation |
| Others |
Cost & Logistics Intelligence
Eighteen-to-twenty-four month PMDA approval cycles for JIS electrical safety certification compress inventory turnover for thermal regulation consoles and amplify pricing power for domestic Japanese distributors holding authorized stock. This lead-time band concentrates procurement risk in East Asian polymer supply clusters while elevating total cost-of-ownership calculations for hospital purchasing committees negotiating multi-year catheter supply agreements.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared automated platforms with encrypted usage logging from basic thermal regulation consoles and refurbished legacy systems. Price differentiation rests on ISO 13485:2016 certification tier and after-sales service bundling, with premium tiers commanding substantial markups for 24-hour technical support and predictive maintenance contracts. Cost compression in the economy tier is intensifying because East Asian catheter manufacturers are scaling biocompatible polymer compounding capacity. Emergency services departments exhibit highest price sensitivity due to capital constraints, while United States academic medical centers demonstrate lowest sensitivity given bundled GPO contract structures.
Supply Chain Analysis
China and South Korea anchor biocompatible polyurethane and silicone compounding for temperature control catheters, while the United States and Germany concentrate thermal regulation console assembly. Raw material dependencies center on medical-grade thermoplastic elastomers, precision pump components, and sensor-integrated catheter lumens. Single-source vulnerability runs through East Asian polymer manufacturing clusters concentrated in the Yangtze River Delta and Gyeonggi-do province. Distribution runs through specialized critical care distributors in North America, hospital federations in Germany, and CDSCO-registered importers in India.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Disposable catheter replacement cycles and companion software subscriptions for automated closed-loop platforms are expanding faster than hardware capital expenditure, reframing intravascular temperature management as a service-attach opportunity rather than episodic equipment procurement.
For Market Incumbents: Secure catheter supply agreements through backward integration into biocompatible polymer compounding or captive partnerships with East Asian manufacturers. Expand encrypted usage logging capabilities to automate EU MDR periodic safety update report preparation and defend against emerging entrants offering simplified compliance documentation. Channel control through exclusive distributor relationships in Japanese PMDA-authorized hospitals remains critical as approval timelines create switching costs. For New Entrants and Emerging Players: Pediatric catheter sizing protocols represent a service-layer gap where incumbents under-serve neonatal and pediatric cardiac surgery programs with distinct flow rate requirements. Target pre-hospital emergency services in India and Southeast Asia where corporate hospital chains are building neuro-ICU capacity without established vendor relationships. A software-first go-to-market angle emphasizing EMR integration and automated temperature protocol documentation bypasses capital-intensive console manufacturing barriers. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified medical device conglomerates seeking to divest non-core temperature management divisions amid portfolio rationalization pressures. Long-term viability hinges on recurring revenue mix from disposable catheters and software subscriptions rather than hardware replacement cycles. Watch CMS reimbursement determinations for targeted temperature management in stroke protocols as the inflection indicator for hospital capital allocation acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR technical documentation for Class IIb devices accelerates multi-jurisdiction market access. |
| Hospital System Partnership | Integrated delivery network standardization across United States trauma centers locks in fleet-wide deployments. |
| Software Companion Development | Automated closed-loop control with EMR integration compresses staffing intensity for 24-hour hypothermia protocols. |
| Reimbursement Strategy | CMS coverage determinations for stroke protocols directly shape hospital utilization rates and capital planning. |
| Backward Integration | In-house biocompatible polymer compounding mitigates East Asian supply concentration and price volatility. |
Research Approach
Findings reconcile primary fieldwork against secondary review of FDA 510(k) clearance databases, EU MDR technical documentation filings, and hospital procurement contract disclosures. Interviews with neuro-ICU clinicians, biomedical engineers, GPO contracts managers, and critical care device distributors were cross-validated against PMDA approval records and CMS reimbursement determinations. Bottom-up sizing of catheter replacement cycles and console installation bases was triangulated against top-down spending estimates from integrated delivery networks and hospital federations.
Segmentation dimensions modeled include product architecture, clinical application, end-user department, and deployment environment across the analysis window. CAGRs were derived from regression analysis of historical installation data and forward projection of protocol adoption rates in stroke and cardiac arrest guidelines. Forecast inputs incorporate neurocritical care infrastructure expansion timelines in Japan, Germany, and the United States alongside pre-hospital emergency services fleet standardization trajectories.
Forecasts assume regulatory continuity in FDA 510(k) pathways, EU MDR enforcement, and PMDA JIS certification regimes; material policy shifts would require re-modeling. Specific risks include CMS reimbursement reversals for targeted temperature management, biocompatible polymer supply disruptions from East Asian manufacturing clusters, and EU MDR post-market surveillance obligation expansions. Recalibration cycles align with material shifts in national cardiovascular disease reduction mandates and emergency medicine protocol updates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular Devices
Peripheral Intravenous Catheters Market
Cardiovascular Devices
Wearable Artificial Organs Market
Cardiovascular Devices
Cardiac Catheters Market
Cardiovascular Devices
Cardiac Cannulas Market
Cardiovascular Devices
Intra-Aortic Balloon Pump (IABP) Market
Cardiovascular Devices
Human Non-Invasive Blood Pressure (NIBP) Recording System Market
Cardiovascular Devices
Artery Compression Devices Market
Cardiovascular Devices
Single-Use Hemoperfusion Device Market
Cardiovascular Devices
Europe Vascular Access Device Market
Cardiovascular Devices
Balloon Catheters Market
Cardiovascular Devices
Atherosclerotic Renovascular Treatment Market
Cardiovascular Devices
Arteriovenous (Av) Fistula Needle Market
Cardiovascular Devices
Fluid Aspiration System Market
Cardiovascular Devices
Global Intravascular Catheters Market
Cardiovascular Devices
Vital Signs Monitoring Devices Market
Cardiovascular Devices
Netherlands Cardiovascular Devices Market