
 Arteriovenous (Av) Fistula Needle Market | 2026-2036
Arteriovenous (Av) Fistula Needle Market Size, Share, and Industry Trends Forecast 2026-2036
Arteriovenous (Av) Fistula Needle Market Outlook
China is reconfiguring regional supply dynamics through expanded domestic needle manufacturing capacity. Nipro leverages integrated stainless steel processing to sustain cost advantages across Asian markets. Fresenius Medical Care anchors demand through captive consumption at its dialysis clinic networks. B. Braun competes on precision grinding technology that reduces vascular trauma during cannulation.
An arteriovenous fistula needle is a hollow, beveled medical instrument manufactured from stainless steel or polymer composites, typically 15-17 gauge with winged hub designs for secure taping during hemodialysis access. The device punctures the surgically created AV fistula to establish blood flow rates of 300-500 mL/min required for effective renal replacement therapy. Single-use needles dominate procurement volumes due to strict infection control protocols, while coated steel variants command premium positioning through reduced puncture resistance and patient comfort improvements. Dialysis centers represent the fastest-growing end-user channel as standalone facilities displace hospital-based treatment in cost-optimized care models.
FDA 510(k) clearance requirements and EMA Medical Device Regulation standards govern biocompatibility testing and sterility assurance levels for fistula needles entering clinical use. ISO 7864 specifications define needle penetration force limits and hub connection integrity parameters that manufacturers must validate. The EU F-Gas Regulation indirectly shapes supply chains through restrictions on ethylene oxide sterilization alternatives. Stakeholders must monitor evolving EPA emissions rules for sterilization facilities and MDR transition timelines that could reshape competitive access across European markets.
Market Dynamics
Standalone dialysis centers are displacing hospital-based treatment, compressing procurement cycles and forcing manufacturers to reconfigure distribution networks around high-volume clinic chains rather than diversified hospital supply agreements.
Growth Catalysts
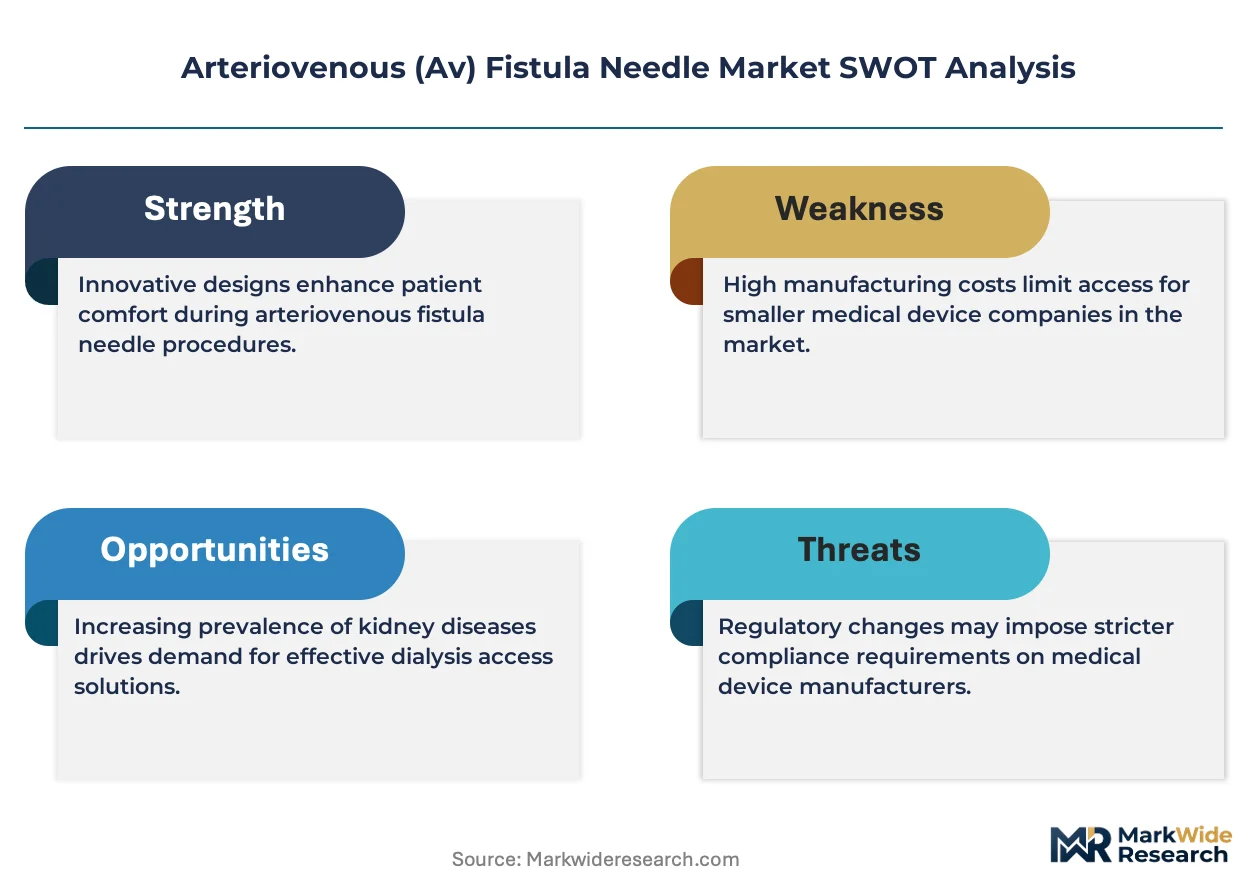
- EMA Medical Device Regulation:Stricter biocompatibility validation requirements are filtering out marginal suppliers and consolidating procurement among certified manufacturers with validated sterilization protocols.
- Stainless steel winged-hub designs:15-17 gauge needles with integrated secure-taping features are reducing cannulation complications and accelerating replacement of legacy straight-hub configurations in high-throughput dialysis centers.
- Germany:Aging demographics and expanded hemodialysis infrastructure are driving per-capita consumption of single-use fistula needles above European averages.
Market Restraints
- Ethylene oxide sterilization constraints:EU F-Gas Regulation restrictions on sterilization alternatives are tightening supply bottlenecks for manufacturers dependent on legacy EtO processing.
- Stainless steel price volatility:Medical-grade 304L and 316L alloy cost fluctuations are compressing margins for precision-ground needle producers without backward integration into raw material sourcing.
- Polymer composite substitution:Experimental bioabsorbable cannula materials threaten long-term demand for metal needles in research-intensive healthcare systems.
Strategic Opportunities
- Japan:METI incentives for domestic medical device production are opening procurement channels for manufacturers establishing local sterilization partnerships.
- Home hemodialysis expansion:Patient self-cannulation training programs are creating demand for safety-engineered needles with integrated flashback indicators and retractable mechanisms.
- Silicone coating convergence:Combination of surface lubrication technology with antimicrobial silver ion integration is enabling premium positioning against uncoated commodity needles.
Industry Challenges
- ISO 7864 validation timelines:Extended penetration-force testing and hub-connection integrity certification cycles are delaying product launches by 8-14 months.
- Precision grinding skill scarcity:Specialized bevel geometry craftsmanship required for reduced vascular trauma is concentrating in aging workforces at German and Japanese manufacturing clusters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Arteriovenous (Av) Fistula Needle Market |
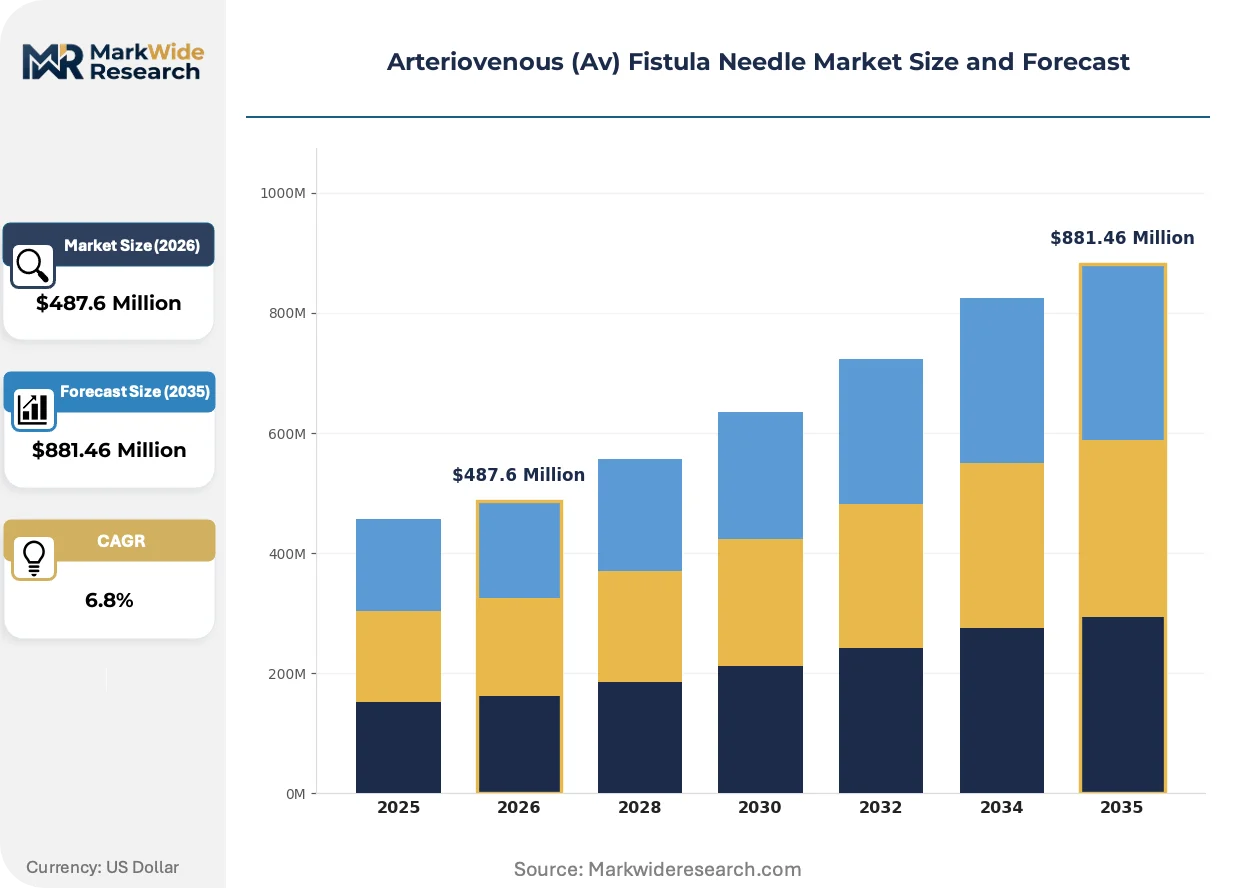
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Use Needles, Dual-Use Needles, Puncture Needles, Specialty Needles Material: Stainless Steel, Coated Steel, Plastic, Polymer End User: Hospitals, Dialysis Centers, Home Care, Clinics Distribution Channel: Online, Retail, Direct Sales, Wholesalers |
| Companies Covered | Nipro, Fresenius Medical Care, B. Braun, Kawasumi Laboratories, Asahi Kasei, Baxter, JMS, Bain Medical, Farmasol, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Arteriovenous (Av) Fistula Needle Market Strategic Shifts
Surface engineering and sterilization chemistry are reshaping competitive differentiation, with coating technologies and alternative sterilization methods displacing legacy manufacturing approaches.
Silicone-polymer hybrid coatings are migrating from premium product lines to standard-tier offerings as dialysis centers prioritize patient comfort metrics in vendor scorecards. High-volume clinic chains in the United States are specifying coated needles in 60 percent of new procurement contracts. This migration from niche to mainstream is compressing price premiums and forcing coating suppliers to scale production.
EPA emissions rules for sterilization facilities are tightening ethylene oxide discharge limits and accelerating validation of nitrogen dioxide and vaporized hydrogen peroxide alternatives. Manufacturers with captive EtO processing face retrofit capital requirements exceeding $4 million per facility. Dialysis needle producers in Ohio and Texas are relocating sterilization partnerships to states with less stringent air-quality enforcement.
Consolidated buying by dialysis clinic networks is displacing distributor-mediated procurement and forcing direct manufacturer-account relationships. Fresenius Medical Care and DaVita are unbundling needle purchasing from bundled dialysis service contracts and negotiating separate supply agreements. This pattern is most visible in Florida and California where standalone treatment centers exceed hospital-based volumes by three-to-one ratios.
Arteriovenous (Av) Fistula Needle Market Segmentation
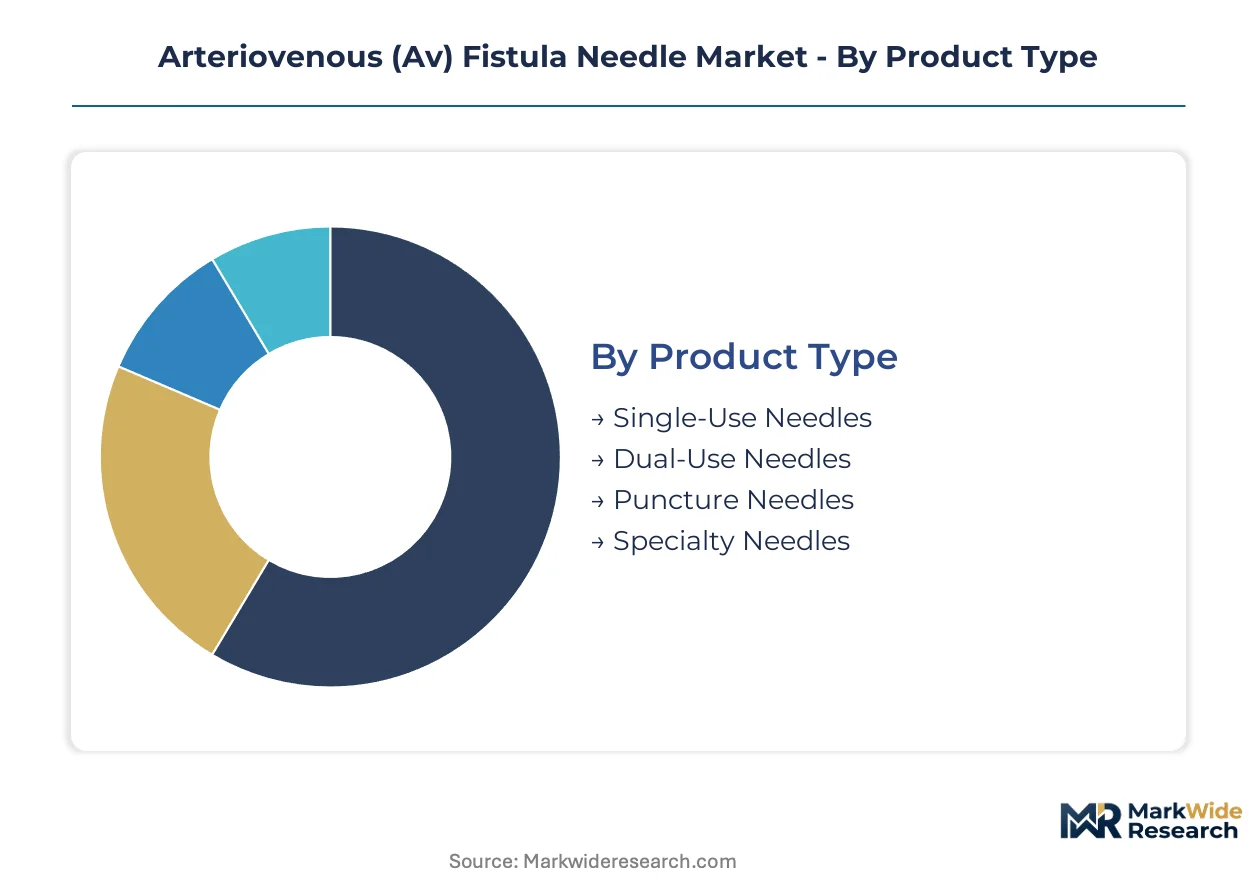
Segmentation in the AV fistula needle market reveals how procurement cycles, material specifications, and channel economics create distinct competitive battlegrounds. Understanding these divisions exposes where margin compression hits hardest and where premium positioning remains defensible.
Product Type:
Cycle times vary dramatically across needle configurations, with single-use variants turning over in days while specialty formats linger in validation queues for months.
- Single-Use Needles:Standard 15-17 gauge stainless steel configurations dominate hemodialysis protocols through strict infection control mandates. Dialysis centers in the United States specify these in procurement contracts covering 300-500 mL/min flow rates. FDA sterility assurance requirements and EMA MDR biocompatibility testing are filtering out non-compliant suppliers.
- Puncture Needles:Winged-hub designs with integrated secure-taping features reduce cannulation complications in high-throughput settings. Germany's expanded hemodialysis infrastructure is driving per-capita consumption above European averages for this configuration.
- Dual-Use Needles:Reprocessing-compatible formats face declining demand as single-use protocols tighten.
- Specialty Needles:Safety-engineered variants with retractable mechanisms serve home hemodialysis self-cannulation programs.
Single-use needles dominate installed base. Specialty needles are where expansion concentrates.
Material:
Cost tiers separate commodity metal supply from coated premium positioning, with raw material volatility compressing margins at the standard tier.
- Stainless Steel:Medical-grade 304L and 316L alloys form the backbone of precision-ground needle production. Nipro's integrated processing sustains cost advantages across Asian markets through backward integration into raw material sourcing.
- Coated Steel:Silicone-polymer hybrid surfaces reduce puncture resistance and improve patient comfort metrics. High-volume clinic chains in the United States now specify coated variants in the majority of new procurement contracts.
- Plastic:Experimental bioabsorbable formats threaten long-term metal demand in research-intensive healthcare systems.
- Polymer:Composite materials enable molded hub designs with integrated connection integrity features.
Stainless steel anchors volume. Coated steel is climbing the fastest.
End User:
Customer type determines whether procurement runs through consolidated clinic networks or fragmented hospital supply agreements.
- Dialysis Centers:Standalone facilities displace hospital-based treatment in cost-optimized care models across Florida and California. Fresenius Medical Care and DaVita are unbundling needle purchasing from bundled service contracts.
- Hospitals:Declining share as treatment migrates to outpatient settings, though academic medical centers retain complex case volumes.
- Home Care:Patient self-cannulation training programs create demand for safety-engineered needles with flashback indicators.
- Clinics:Smaller outpatient facilities with mixed nephrology services.
Dialysis centers command procurement volume. Home care is gaining share fastest.
Distribution Channel:
Channel structure is shifting as consolidated buying by clinic networks displaces traditional distributor mediation.
- Direct Sales:Manufacturer-account relationships are replacing distributor-mediated procurement for high-volume clinic chains. B. Braun competes on precision grinding technology through direct technical support.
- Wholesalers:Traditional hospital supply agreements face compression as standalone centers proliferate.
- Online:Emerging channel for standardized product procurement by smaller facilities.
- Retail:Minimal presence given prescription and sterility requirements.
Direct sales dominates large-account access. Online channels show steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA sterility requirements anchor demand concentration in the United States, while EMA Medical Device Regulation standards and Japan METI incentives shape procurement patterns across developed healthcare systems. Aging demographics and expanding dialysis infrastructure drive per-capita consumption in Germany and Japan. China's domestic manufacturing expansion is reconfiguring supply dynamics across Asian markets.
United States
Standalone dialysis centers in Florida and California now exceed hospital-based treatment volumes by three-to-one ratios, compressing procurement cycles around high-volume clinic chains. EPA emissions rules for sterilization facilities are tightening ethylene oxide discharge limits and forcing relocation of processing partnerships to states with less stringent air-quality enforcement. Cleveland and Cincinnati clusters host precision grinding operations serving Fresenius Medical Care and DaVita network demands.
Germany
Aging demographics and expanded hemodialysis infrastructure are driving per-capita consumption of single-use fistula needles above European averages. EMA Medical Device Regulation biocompatibility validation requirements are filtering out marginal suppliers and consolidating procurement among certified manufacturers. Baden-Württemberg manufacturing clusters concentrate specialized bevel geometry craftsmanship for reduced vascular trauma applications.
Japan
METI incentives for domestic medical device production are opening procurement channels for manufacturers establishing local sterilization partnerships. Patient self-cannulation training programs are creating demand for safety-engineered needles with integrated flashback indicators. Kanto region dialysis networks anchor consumption volumes while Osaka-based precision metalworking traditions support needle fabrication expertise.
China
Expanded domestic needle manufacturing capacity is reconfiguring regional supply dynamics and reducing import dependence for dialysis center procurement. NMPA medical device registration requirements are tightening quality benchmarks for locally produced fistula needles. Yangtze River Delta industrial zones concentrate integrated stainless steel processing operations serving cost-optimized Asian market segments.
India
CDSCO medical device licensing frameworks are aligning with international standards to facilitate export competitiveness for domestic manufacturers. Rising diabetes prevalence and expanding dialysis infrastructure in urban centers are accelerating hemodialysis access point proliferation. Maharashtra and Gujarat industrial corridors host emerging precision instrument fabrication capabilities for regional supply.
Arteriovenous (Av) Fistula Needle Market Competitive Environment
Vertically integrated healthcare conglomerates and specialized precision instrument fabricators split the market into distinct competitive spheres. Dialysis service providers with captive manufacturing capabilities leverage internal consumption to secure volume scale, while independent needle specialists compete on technical differentiation and direct clinic relationships. Two dominant strategic moves define current positioning: backward integration into raw material sourcing to mitigate stainless steel price volatility, and direct sales force deployment to bypass distributor margins on high-volume clinic contracts.
Among Asian manufacturers, Nipro and Kawasumi Laboratories occupy positions anchored by integrated supply chain control and regional market proximity. Fresenius Medical Care exemplifies the healthcare conglomerate archetype through captive consumption at its dialysis clinic networks. B. Braun represents European precision engineering traditions in the specialized instrument tier. These three patterns—integrated Asian manufacturing, healthcare provider verticalization, and European technical specialization—structure competitive rivalry across procurement channels.
| Leading Market Players |
|---|
| Nipro |
| Fresenius Medical Care |
| B. Braun |
| Kawasumi Laboratories |
| Asahi Kasei |
| Baxter |
| JMS |
| Bain Medical |
| Farmasol |
| Others |
Value Chain & Pricing Dynamics
Ethylene oxide sterilization constraints under the EU F-Gas Regulation determine both pricing tier spreads and supply chain shape, forcing manufacturers to absorb retrofit costs or relocate processing while tiering product lines by coating technology and regulatory compliance grade.
Pricing Analysis
Price spreads between coated and uncoated variants widen in Germany and Japan while compressing in China's domestic market. Three-tier pricing structure across premium, standard, and economy levels separates silicone-coated safety-engineered needles from standard stainless steel winged-hub configurations and commodity straight-hub alternatives. Cost compression in the standard tier is intensifying because Nipro's integrated stainless steel processing sustains cost advantages that competitors struggle to match. Dialysis center procurement committees show highest price sensitivity, while academic medical centers purchasing specialty safety-engineered formats for complex cases demonstrate lowest sensitivity.
Supply Chain Analysis
Export-control scrutiny on precision grinding equipment limits technology transfer to emerging manufacturing clusters. Supply concentrates in Japan, Germany, and China, with medical-grade 304L and 316L stainless steel drawing from specialized alloy foundries in the Yangtze River Delta and Baden-Württemberg. Single-source vulnerability clusters around ethylene oxide sterilization capacity as EPA emissions rules tighten discharge limits. Distribution runs through direct manufacturer-account relationships with Fresenius Medical Care and DaVita networks displacing traditional distributor mediation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The AV fistula needle market operates as a regulatory-moat business where EMA MDR certification and FDA 510(k) clearance create switching costs that entrench validated suppliers against unqualified challengers.
For Market Incumbents: Build regulatory-certification moats by accelerating ISO 7864 validation pipelines and securing captive ethylene oxide sterilization partnerships before EPA emissions rules tighten further. Expand precision grinding capacity in Baden-Württemberg to exploit skill scarcity concentration. Defend against polymer composite substitution threats by integrating silicone-antimicrobial coating R&D with existing stainless steel fabrication expertise. For New Entrants and Emerging Players: India's underpenetrated dialysis infrastructure offers the most accessible white-space expansion, with CDSCO alignment to international standards reducing regulatory friction for export-oriented manufacturers. Target Maharashtra and Gujarat industrial corridors for precision instrument fabrication partnerships. Pursue home hemodialysis safety-engineered needle segments where patient self-cannulation training programs create demand for flashback-indicator designs that bypass established clinic procurement relationships. For Investors and Strategic Acquirers: Specialized precision instrument fabricators with validated sterilization protocols and direct clinic network relationships represent the most defensible acquisition archetype. Long-term viability hinges on coating technology convergence and alternative sterilization method validation across a 5-10 year horizon. Watch for EPA enforcement actions against ethylene oxide facilities as an inflection indicator that would accelerate consolidation toward sterilization-capable manufacturers.| Strategic Initiative | Industry Significance |
|---|---|
| EMA MDR Certification Investment | Biocompatibility validation filters marginal suppliers and consolidates procurement among certified manufacturers. |
| Silicone-Antimicrobial Coating Development | Surface lubrication integration enables premium positioning against uncoated commodity needles in clinic scorecards. |
| Direct Sales Force Deployment | Manufacturer-account relationships bypass distributor margins on high-volume Fresenius and DaVita contracts. |
| Alternative Sterilization Validation | Nitrogen dioxide and vaporized hydrogen peroxide processing mitigates EU F-Gas Regulation ethylene oxide constraints. |
| Home Hemodialysis Product Line | Safety-engineered needles with retractable mechanisms serve patient self-cannulation training program expansion. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of FDA 510(k) filings, EMA MDR submissions, hospital procurement databases, and GPO contract records. Interviews with dialysis center operations directors, biomedical engineers, nephrologists, sterilization facility managers, and precision instrument manufacturing engineers informed demand-side and supply-side dynamics. Bottom-up modeling of needle consumption by treatment center type and top-down validation against dialysis patient population estimates ensured cross-verification.
Forecast inputs include hemodialysis patient volume trajectories, standalone center proliferation rates, coating technology adoption curves, and regulatory transition timelines. Segmentation dimensions span product type, material grade, end-user channel, and distribution structure across the analysis window. CAGRs derive from regression analysis of historical procurement patterns projected against demographic and infrastructure build-out assumptions. Stainless steel price volatility and sterilization capacity constraints inform scenario-weighted outcomes.
The forecast holds incumbent behavior within observed patterns; aggressive moves by integrated Asian manufacturers or dialysis provider conglomerates would shift outcomes. Material shifts in EPA emissions enforcement, EMA MDR transition timelines, or polymer composite regulatory approval would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular Devices
Global Ventricular Assist Device Market
Cardiovascular Devices
United Kingdom Cardiovascular Devices Market
Cardiovascular Devices
MRI-Guided Cardiac Ablation Market
Cardiovascular Devices
Aortic Aneurysm Market
Cardiovascular Devices
Perfusion Market
Cardiovascular Devices
Neuroendovascular Coil Market
Cardiovascular Devices
Global Cardiovascular Disease Monitoring and Diagnostic Devices Market
Cardiovascular Devices
Cardiogenic Shock Treatment Market
Cardiovascular Devices
Vascular Access Systems Market
Cardiovascular Devices
Global Aortic Valve Market
Cardiovascular Devices
Cardiac Ablation Catheter Market
Cardiovascular Devices
Non-Invasive Pulse Wave Tonometer Market
Cardiovascular Devices
Abdominal Aortic Aneurysm (AAA) Repair Devices Market
Cardiovascular Devices
Global Intracranial Stents Market
Cardiovascular Devices
South Africa Cardiovascular Devices Market
Cardiovascular Devices
Global Vascular Graft Market