
 Europe Vascular Access Device Market | 2026-2036
Europe Vascular Access Device Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Vascular Access Device Market Foresight
Antimicrobial-coated catheter tiers is reorganizing procurement standards across European healthcare systems. Becton, Dickinson and Company leverages its integrated manufacturing footprint to sustain supply continuity for central venous catheter lines. B. Braun Melsungen AG anchors its position through specialized dialysis access portfolios that dominate German clinic networks. Teleflex Incorporated differentiates via ultrasound-guided technology leadership that positions it ahead in interventional radiology departments.
Vascular access devices comprise sterile tubular instruments engineered from polyurethane, silicone, or thermoplastic elastomer with specified French sizes and luminal configurations, designed to establish reliable entry into the venous or arterial circulation for fluid administration, hemodynamic monitoring, or blood withdrawal. Catheters command the largest product volume pool due to their ubiquity across emergency and intensive care settings, while ports capture concentrated margin pools in long-term oncology protocols. Ultrasound-guided technology represents the fastest-expanding segment as European hospitals integrate point-of-care imaging to reduce placement complications and meet MDR-mandated safety benchmarks.
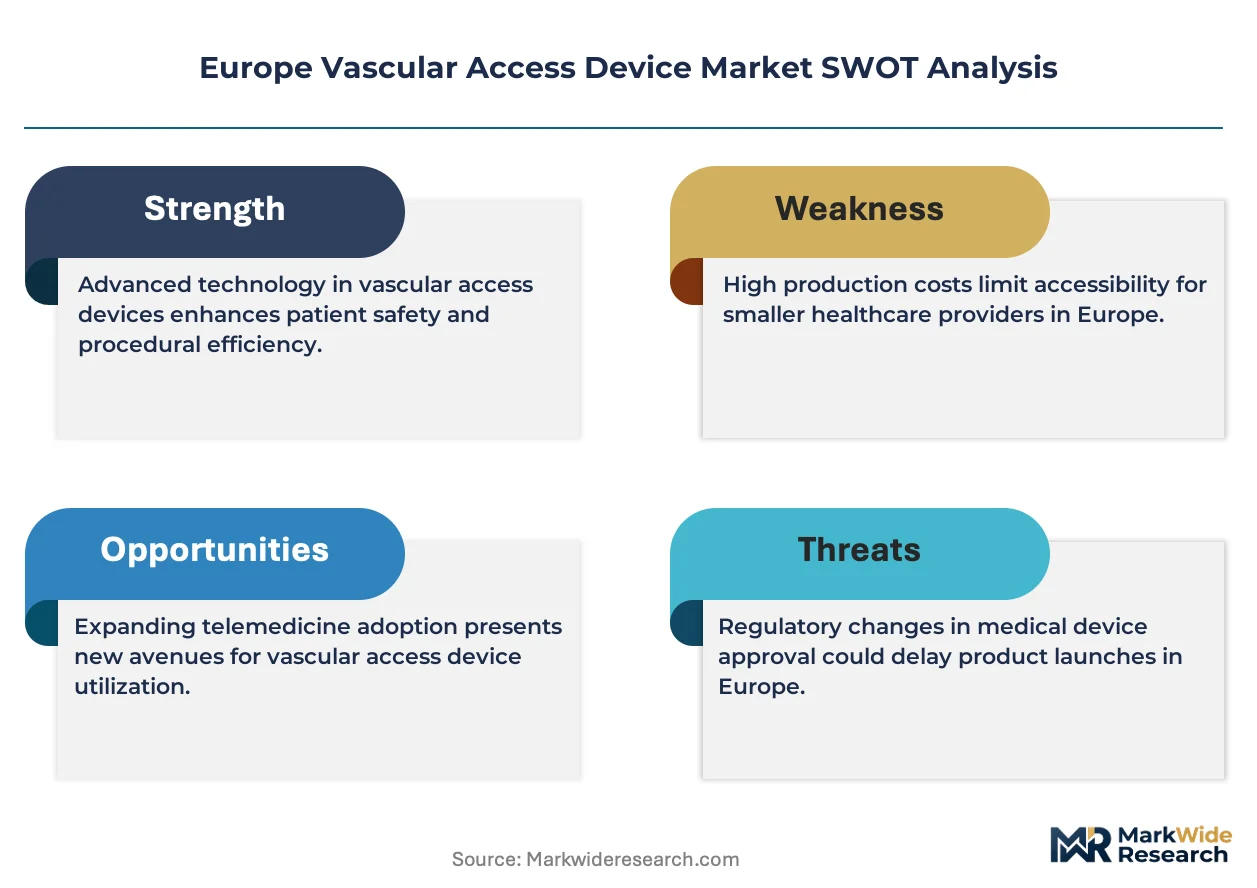
The European Medicines Agency (EMA) and EU Medical Device Regulation (MDR) enforce biocompatibility testing and post-market surveillance that elevate compliance costs but filter lower-grade competitors from commercial distribution. REACH and RoHS frameworks further constrain material selections for device polymers and antimicrobial additives, pushing manufacturers toward validated European supply chains. Stakeholders must monitor how the EU AI Act intersects with emerging smart catheter systems that integrate sensor-based complication detection, as this regulatory overlap will determine which technology platforms secure scalable market access.
Market Dynamics
The EU Medical Device Regulation (MDR) is compressing manufacturer margins while simultaneously filtering subscale competitors from European distribution networks. REACH and RoHS constraints on polymer chemistry are forcing material substitutions that reshape supply chain economics across catheter and port production lines.
Growth Catalysts
- Antimicrobial coating mandates:Hospital-acquired infection protocols in Germany and France now specify silver-ion or chlorhexidine-impregnated surfaces for indwelling devices, pulling premium-tier catheter demand upward.
- EMA post-market surveillance expansion:Enhanced biocompatibility documentation requirements favor established manufacturers with validated European quality systems, consolidating procurement toward compliant suppliers.
- Oncology protocol standardization:Implantable ports are displacing peripherally inserted central catheters in long-term chemotherapy regimens across Italian and Spanish hospital networks.
Market Restraints
- Silicone feedstock volatility:Medical-grade silicone supply concentrates among German and French chemical processors, exposing device manufacturers to input cost swings and allocation risk during polymer shortages.
- MDR certification timeline compression:The May 2024 transition deadline for legacy device recertification has created bottlenecks at notified bodies, delaying product launches and freezing commercial expansion for mid-tier suppliers.
- Ultrasound-guided placement substitution:Advanced visualization systems are reducing complication rates but extending procedure times, creating workflow friction in high-throughput emergency departments.
Strategic Opportunities
- Poland and Romania infrastructure buildout:EU structural fund investments in Central European oncology centers are creating greenfield demand for implantable port systems without entrenched supplier relationships.
- EU AI Act intersection:Smart catheters with integrated pressure or flow sensors fall under emerging algorithmic medical device classifications, opening first-mover positioning for compliant integrated systems.
- Interventional radiology channel expansion:Direct-to-department contracting models are bypassing traditional hospital procurement committees in French and Belgian academic medical centers.
Industry Challenges
- Specialized insertion technician scarcity:Ultrasound-guided central line placement requires certified operators, and training program capacity lags device adoption curves in Southern European markets.
- Legacy sterilization validation gaps:Ethylene oxide alternatives for terminal sterilization of polymer devices remain unproven at scale, complicating MDR-compliant manufacturing transitions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Vascular Access Device Market |
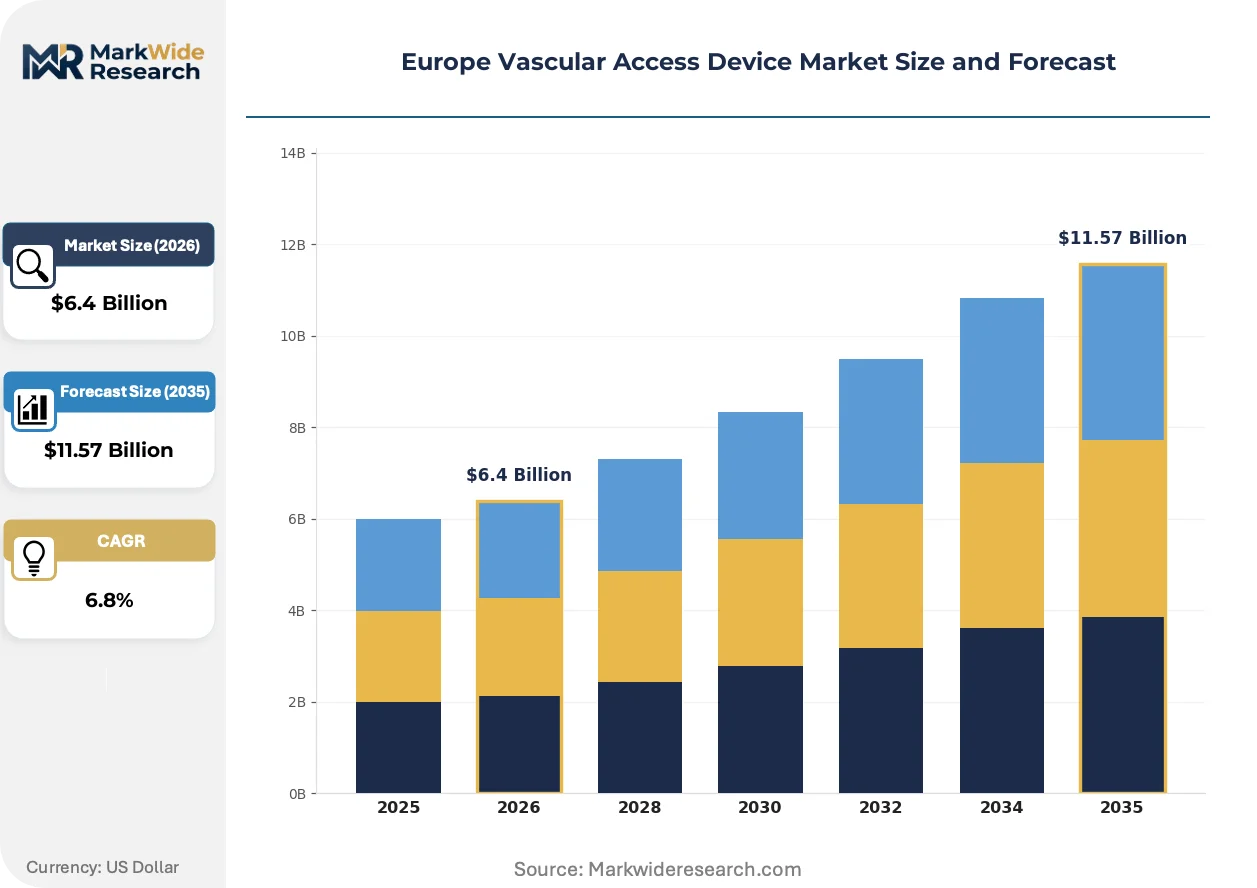
| Market Size in 2026 | $6.4 Billion |
| Market Size in 2035 | $11.57 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cannulas, Catheters, Ports, Introducers End User: Hospitals, Clinics, Home Care, Dialysis Centers Application: Oncology, Cardiology, Infectious Diseases, Emergency Medicine Technology: Ultrasound-guided, Fluoroscopy-guided, MRI-compatible, Biodegradable |
| Companies Covered | Becton, Dickinson and Company, B. Braun Melsungen AG, Teleflex Incorporated, Smiths Medical, Inc., AngioDynamics, Terumo Corporation, Edwards Lifesciences Corporation, Nipro Medical Corporation, Vygon Group, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Vascular Access Device Market Shifts & Advancements
Three interconnected developments are restructuring how vascular access devices are designed, validated, and procured across European healthcare systems. Technology convergence, regulatory stringency, and buyer behavior evolution are creating distinct competitive strata.
Antimicrobial surface engineering is bifurcating the catheter market into infection-resistant premium tiers and commodity uncoated alternatives. German university hospitals are mandating chlorhexidine-silver combinations for all central lines exceeding 48 hours indwelling time. This specification creep is compressing mid-tier positioning and forcing manufacturers to dual-source coating chemistries or exit the acute care segment entirely.
REACH substance restrictions on phthalate plasticizers and RoHS constraints on heavy metal catalyst residues are eliminating legacy polymer formulations from European supply chains. Device manufacturers must revalidate extrusion processes with bio-based alternatives, extending development timelines by 18-24 months. Dialysis access catheter producers face the steepest compliance burden given extended patient exposure durations.
Hospital procurement committees are consolidating vendor relationships around full-line suppliers capable of delivering catheters, ports, and insertion accessories under unified framework agreements. French regional health agencies pioneered this consolidation, and the model is propagating through Belgian and Dutch hospital networks. Single-source contracting reduces transaction costs but locks out specialized niche manufacturers from volume accounts.
Europe Vascular Access Device Market Segmentation
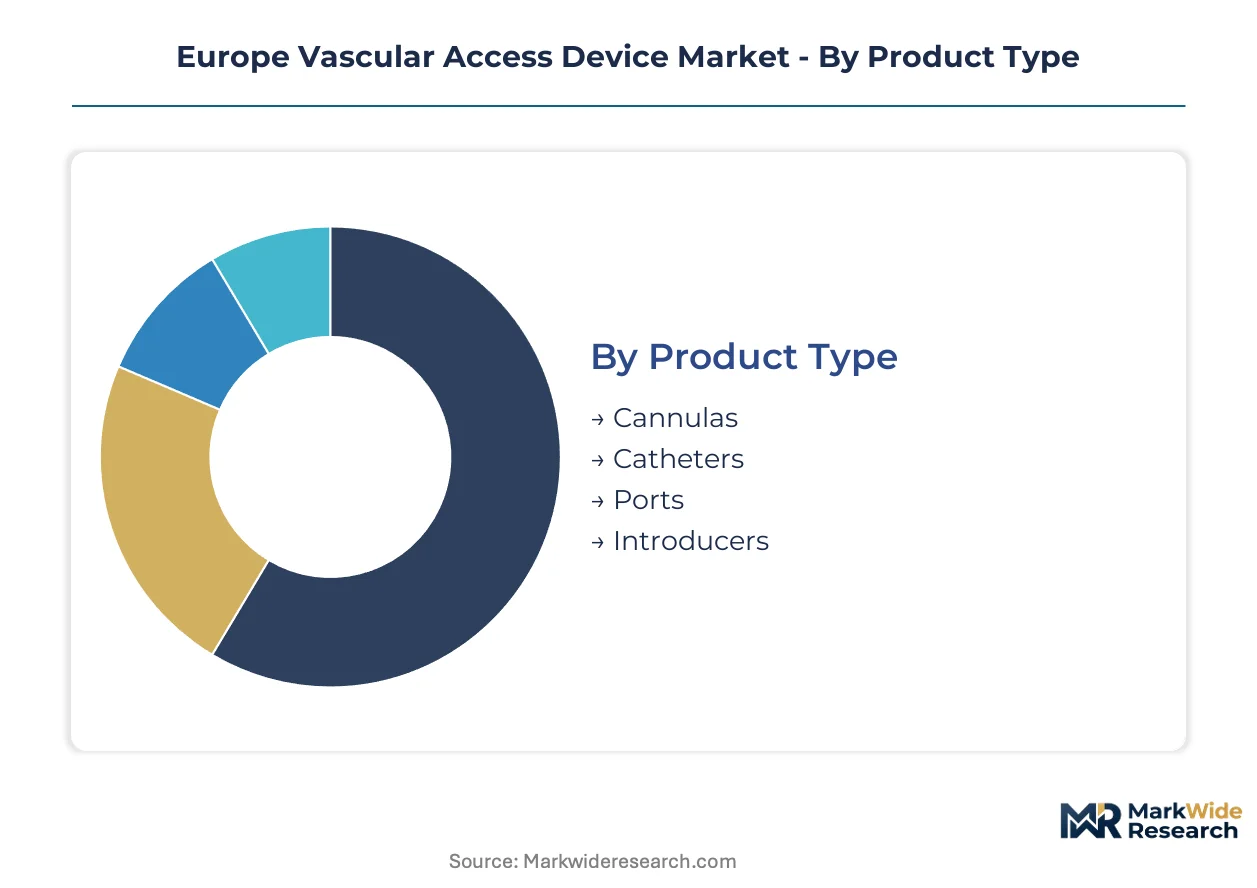
Vascular access device procurement in Europe fragments across clinical setting, patient acuity, and regulatory compliance tier. Manufacturers must align product portfolios with distinct insertion protocols, reimbursement pathways, and MDR documentation requirements that vary by segment.
Product Type:
Catheter substitution pressure is intensifying as ultrasound-guided placement reduces dwell-time complications and ports capture long-term therapy share. Cannulas face erosion from safety-engineered alternatives in acute care.
- Catheters:Polyurethane and silicone tubular instruments with specified French sizes and single-to-multi-lumen configurations. German and French emergency departments drive demand for antimicrobial-coated central venous lines under hospital-acquired infection protocols. REACH constraints on phthalate plasticizers force material revalidation across extrusion supply chains.
- Ports:Subcutaneous implantable reservoirs with titanium or plastic housings connected to silicone catheters. Italian oncology networks are standardizing port protocols for chemotherapy regimens exceeding six months, displacing peripherally inserted central catheters in long-term care pathways.
- Cannulas:Short-term steel or plastic needles for peripheral venous access. Safety-engineered designs with retractable or shielded mechanisms dominate acute care procurement in Belgium and the Netherlands.
- Introducers:Sheath systems facilitating catheter placement via Seldinger technique. Interventional radiology departments in French academic medical centers specify peel-away and dilator configurations for complex access procedures.
Catheters retain volume leadership; ports hold the steepest expansion curve.
End User:
Cost tier stratification separates capital-intensive hospital infrastructure from decentralized outpatient and home-based delivery models. Dialysis centers operate as a distinct procurement channel with specialized reimbursement mechanics.
- Hospitals:Acute care institutions with 24-hour emergency and intensive care capacity. German university hospitals mandate chlorhexidine-silver catheter combinations for all central lines exceeding 48-hour indwelling time.
- Dialysis Centers:Specialized outpatient facilities managing end-stage renal disease populations. B. Braun Melsungen AG dominates German clinic networks through dedicated dialysis access portfolios with extended patient exposure compliance.
- Clinics:Outpatient surgical and infusion centers. French regional health agencies consolidate vendor relationships around full-line suppliers capable of delivering catheters, ports, and insertion accessories under unified framework agreements.
- Home Care:Patient-resident infusion and monitoring services. Italian and Spanish networks face training capacity constraints for caregiver-managed port maintenance.
Hospitals command procurement volume; dialysis centers concentrate margin capture through specialized access protocols.
Application:
Application-based demand clusters around therapy duration and vascular fragility, with oncology and cardiology representing divergent technical specifications and reimbursement intensities.
- Oncology:Long-term chemotherapy, stem cell collection, and supportive care infusion. Implantable ports are displacing peripherally inserted central catheters across Italian and Spanish hospital networks for regimens exceeding six months.
- Cardiology:Hemodynamic monitoring, contrast injection, and electrophysiology procedures. French interventional cardiology departments specify MRI-compatible port systems for patients requiring concurrent cardiac imaging.
- Emergency Medicine:Rapid vascular access for resuscitation and trauma. Ultrasound-guided technology is expanding in German emergency departments to reduce placement complications.
- Infectious Diseases:Prolonged antimicrobial therapy and parenteral nutrition. Central line-associated bloodstream infection protocols mandate antimicrobial-coated surfaces in Belgian and Dutch networks.
Oncology anchors premium-tier revenue; emergency medicine generates the highest catheter consumption velocity.
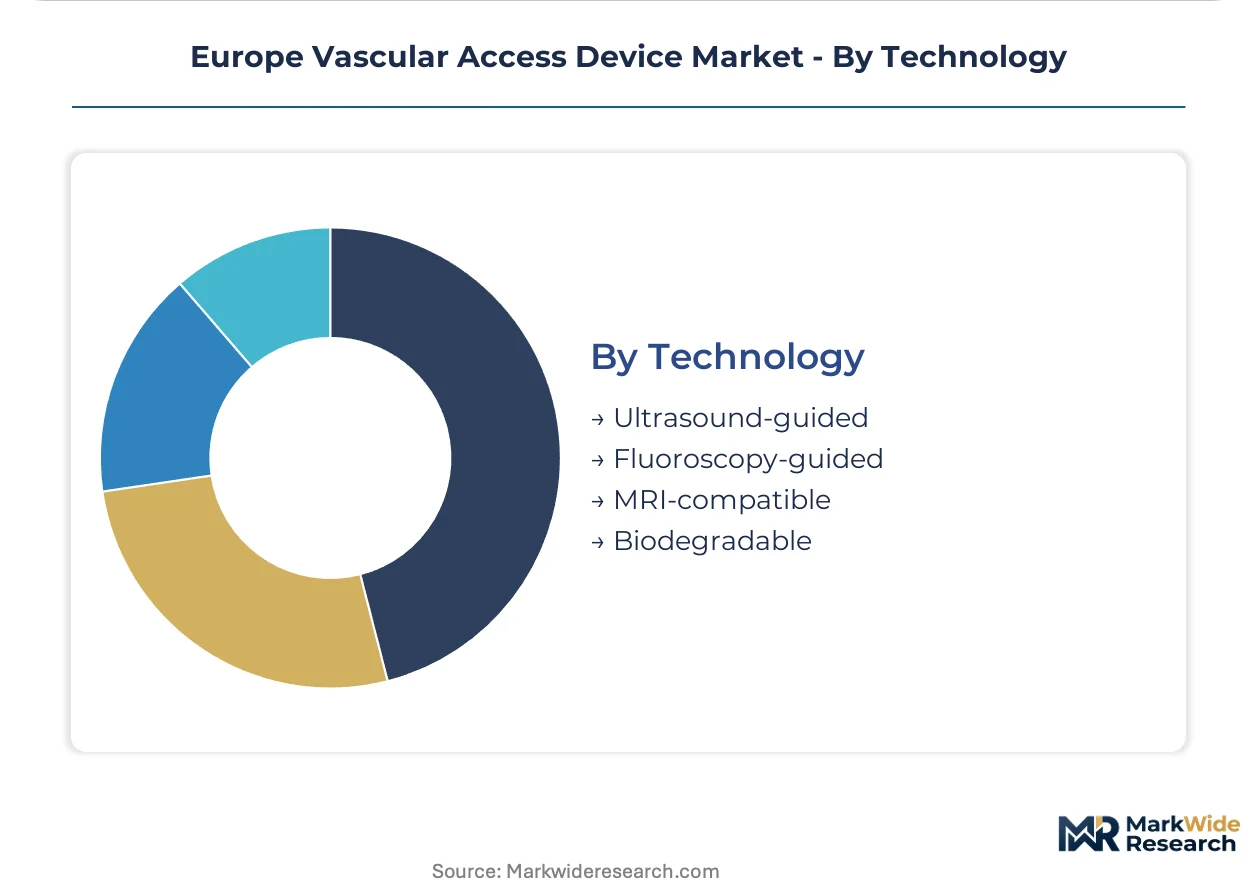
Technology:
Technology segmentation reflects the convergence of imaging integration, materials science, and regulatory classification complexity under EU MDR and emerging AI Act frameworks.
- Ultrasound-guided:Real-time visualization systems for vessel identification and needle guidance. Teleflex Incorporated positions ahead in interventional radiology departments through specialized ultrasound technology leadership.
- MRI-compatible:Non-ferromagnetic materials eliminating imaging artifact and heating risk. Cardiology and oncology applications in French and German academic centers drive specification for concurrent diagnostic imaging.
- Fluoroscopy-guided:X-ray assisted placement for central venous and arterial access. Interventional radiology suites in Belgian hospitals maintain demand for radiopaque marker configurations.
- Biodegradable:Absorbable polymers eliminating retrieval procedures. EMA biocompatibility testing requirements and REACH substance restrictions constrain commercial scale for emerging formulations.
Ultrasound-guided systems are gaining share fastest; MRI-compatible configurations command premium positioning in academic medical centers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German chemical processors concentrate medical-grade silicone supply, exposing device manufacturers across Europe to feedstock allocation risk during polymer shortages. French and Italian hospital networks drive premium-tier adoption through infection-control procurement mandates. REACH and MDR compliance costs filter subscale competitors from distribution channels in advanced economies while creating entry windows in Central European markets.
Germany
University hospitals in Berlin and Munich mandate chlorhexidine-silver catheter combinations for all central lines exceeding 48-hour indwelling time. BfArM post-market surveillance requirements favor established manufacturers with validated quality systems. B. Braun Melsungen AG anchors dialysis access supply through specialized portfolios dominating clinic networks in Baden-Württemberg and North Rhine-Westphalia.
France
Regional health agencies in Île-de-France and Auvergne-Rhône-Alpes consolidate vendor relationships around full-line suppliers capable of delivering catheters, ports, and insertion accessories under unified framework agreements. ANSM biocompatibility documentation requirements align with EU MDR transition timelines. Interventional radiology departments in Paris academic medical centers specify peel-away introducer configurations for complex access procedures.
Italy
Oncology networks in Lombardy and Lazio standardize implantable port protocols for chemotherapy regimens exceeding six months, displacing peripherally inserted central catheters in long-term care pathways. AIFA reimbursement codes favor durable access solutions with extended dwell-time validation. Milan and Rome hospital clusters drive specification for MRI-compatible port systems in concurrent diagnostic imaging protocols.
Spain
Hospital-acquired infection protocols in Catalonia and Madrid now specify antimicrobial-coated surfaces for indwelling devices, pulling premium-tier catheter demand upward. AEMPS certification timelines compress commercial expansion for mid-tier suppliers awaiting notified body review. Barcelona medical technology clusters concentrate ultrasound-guided placement training capacity for emergency department operators.
Poland
EU structural fund investments in oncology centers around Warsaw and Kraków create greenfield demand for implantable port systems without entrenched supplier relationships. Office for Registration of Medicinal Products, Medical Devices and Biocidal Products oversight aligns with harmonized EU MDR standards. Polish hospital procurement committees increasingly reference German and French framework agreements as benchmark templates.
Europe Vascular Access Device Market Competitive Landscape
Concentration sits with diversified medical technology conglomerates possessing integrated manufacturing footprints and validated European quality systems. Three archetypes define competitive positioning: full-line suppliers delivering catheters, ports, and insertion accessories under unified contracts; specialized dialysis access manufacturers with extended patient exposure compliance; and ultrasound-guided technology specialists serving interventional radiology departments. Dominant competitive moves include strategic partnerships with academic medical centers for clinical validation and portfolio diversification into smart catheter systems with sensor-based complication detection.
Within the full-line supplier tier, Becton, Dickinson and Company and B. Braun Melsungen AG exemplify scale-driven positioning through manufacturing integration and specialized portfolio depth. Teleflex Incorporated occupies a position in the ultrasound-guided technology vector. These three entities represent distinct competitive archetypes: integrated manufacturing conglomerates, dialysis access specialists, and interventional visualization technology leaders.
| Leading Market Players |
|---|
| Becton, Dickinson and Company |
| B. Braun Melsungen AG |
| Teleflex Incorporated |
| Smiths Medical, Inc. |
| AngioDynamics |
| Terumo Corporation |
| Edwards Lifesciences Corporation |
| Nipro Medical Corporation |
| Vygon Group |
| Others |
Supply & Pricing Matrix
Unified framework agreements with German and French hospital networks lock in multi-year supply commitments for antimicrobial-coated catheter portfolios, securing volume visibility while compressing margin flexibility for manufacturers navigating REACH-compliant material substitutions. These contracting structures tether pricing power to validated European quality systems and MDR documentation depth.
Pricing Analysis
EU MDR dictates the pricing tier structure across the European vascular access device landscape. Three-tier pricing structure across premium, standard, and economy levels separates chlorhexidine-silver antimicrobial combinations from uncoated alternatives and basic peripheral cannulas. Certification grade and volume scale drive price differentiation, with university hospital procurement committees extracting scale discounts that mid-tier suppliers cannot match. Cost compression in standard-tier catheters is intensifying because REACH-mandated polymer revalidation extends development timelines without commensurate price recovery. Dialysis centers exhibit the highest price sensitivity due to reimbursement pressure, while interventional radiology departments in academic medical centers prioritize technology performance over unit cost.
Supply Chain Analysis
Inventory buffers for medical-grade silicone and polyurethane feedstocks stretch to 90-120 days as German and French chemical processors concentrate polymer supply. Device manufacturing draws from specialized extrusion facilities in Germany, Italy, and Switzerland, with antimicrobial coating application anchoring in the Netherlands and Belgium. Single-source vulnerability concentrates in medical-grade silicone supply from German processors, exposing catheter and port manufacturers to allocation risk during polymer shortages. Distribution runs through regional healthcare procurement consortia that consolidate vendor relationships under framework agreements spanning catheters, ports, and insertion accessories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The European vascular access device market sits in early-cycle expansion as ultrasound-guided placement protocols penetrate emergency departments and oncology networks standardize implantable port adoption for extended chemotherapy regimens.
For Market Incumbents: Compound MDR compliance advantages by accelerating notified body certification for legacy device portfolios before bottlenecks worsen, and deepen backward integration into REACH-validated polymer supply chains to insulate margins from feedstock volatility. Emerging smart catheter systems with integrated sensors threaten to commoditize traditional placement technology, making algorithmic medical device certification under the EU AI Act the critical capability lever for sustaining premium positioning. For New Entrants and Emerging Players: Post-market surveillance service gaps in Polish and Romanian oncology centers offer white-space entry where established suppliers lack localized technical support infrastructure. Target Central European markets receiving EU structural fund investments for implantable port systems, deploying direct-to-department contracting models that bypass entrenched procurement committees in French and Belgian academic centers. For Investors and Strategic Acquirers: Capital is best deployed toward ultrasound-guided technology specialists with validated interventional radiology channel relationships and MDR-compliant manufacturing footprints. Long-term viability hinges on first-mover positioning in smart catheter platforms that integrate sensor-based complication detection. The signal to watch is EU AI Act implementation timelines determining which algorithmic medical device classifications secure scalable market access.| Strategic Initiative | Industry Significance |
|---|---|
| MDR Certification Acceleration | Notified body queue positioning in Germany and France secures legacy device continuity. |
| REACH-Compliant Polymer Sourcing | Bio-based plasticizer validation extends development timelines but filters subscale competitors. |
| Ultrasound-Guided Technology Partnership | Interventional radiology department contracts in Paris academic centers bypass procurement committees. |
| Smart Catheter Sensor Integration | EU AI Act algorithmic classification creates first-mover advantage in complication detection systems. |
| Central European Distribution Buildout | EU structural fund investments in Polish oncology centers create greenfield demand without entrenched suppliers. |
Research Methodology
Desk research of EMA guidance documents, EU MDR implementation notices, and hospital procurement databases preceded structured interviews with biomedical engineers, hospital purchasing committee chairs, interventional radiology department heads, and GPO contracts managers. Secondary validation drew from notified body certification records, REACH substance restriction filings, and academic medical center technology assessment reports. Bottom-up demand modeling across catheter, port, and cannula product categories triangulated with top-down market sizing from manufacturer revenue disclosures.
Variance decomposition across product type, end user, application, and technology segmentation dimensions shaped the analytical framework over the projection horizon. CAGRs were derived from installed base expansion rates, replacement cycle frequencies, and therapy protocol standardization curves. Forecast inputs incorporated MDR transition timeline assumptions, REACH substance restriction phase-in schedules, and ultrasound-guided placement adoption velocity in emergency medicine.
Material uncertainties — notified body capacity constraints, silicone feedstock allocation disruptions, and EU AI Act classification delays — sit outside the modeled envelope. Forecasts reflect documented assumptions about regulatory compliance cost trajectories and procurement committee consolidation patterns. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular Devices
Global 3D Vascular Ultrasound Imaging Market
Cardiovascular Devices
Remote Endarterectomy Devices Market
Cardiovascular Devices
Global Varicose Veins Treatment Market
Cardiovascular Devices
Renovascular Hypertension Treatment Market
Cardiovascular Devices
Neurovascular Coiling Assist Devices Market
Cardiovascular Devices
Cardiogenic Shock Treatment Market
Cardiovascular Devices
Centrifugal Blood Pumps Market
Cardiovascular Devices
Global External Ventricular Drain Market
Cardiovascular Devices
Intra-Aortic Balloon Pump (IABP) Market
Cardiovascular Devices
Global Vascular Graft Market
Cardiovascular Devices
Balloon Catheters Market
Cardiovascular Devices
Global Valvular Heart Disease Treatment Market
Cardiovascular Devices
Self-Expanding Stents Market
Cardiovascular Devices
Arteriotomy Closure Devices Market
Cardiovascular Devices
Infusion Catheters Market
Cardiovascular Devices
Surgical and Interventional Cardiology Devices Market