
 Asia-Pacific Ambulatory Infusion Pumps Market | 2026-2036
Asia-Pacific Ambulatory Infusion Pumps Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Ambulatory Infusion Pumps Market Outlook
Modular pump configurations paired with disposable cassette systems is broadening buyer choice across price-sensitive and premium segments. B. Braun Melsungen AG leverages its European manufacturing footprint to sustain dual-source supply for Asia-Pacific hospital networks. Baxter International Inc. anchors its position through integrated fluid-delivery ecosystems that span pumps, sets, and nutritional solutions. Terumo Corporation competes via compact, wearable designs optimized for Japan's homecare reimbursement pathways.
Ambulatory infusion pumps are programmable, portable devices that deliver controlled volumes of therapeutic fluids—typically 0.1 to 999 milliliters per hour—through intravenous, subcutaneous, or epidural routes for patients outside acute-care settings. These systems incorporate occlusion sensors, air-in-line detectors, and dose-error reduction software to ensure safe, continuous drug administration during chemotherapy, pain management, or antibiotic therapy. Syringe pumps capture premium margins in precision-critical applications such as pediatric and anesthesia delivery where flow accuracy below two percent variance commands higher pricing. Volumetric pumps dominate hospital throughput volumes but face substitution pressure in homecare where lighter, disposable gravity pumps reduce total cost of ownership. PCA pumps represent the fastest-expanding category as cancer prevalence rises and payers in Australia and South Korea expand reimbursement for patient-controlled analgesia outside institutional walls.
Japan's PMDA enforces stringent electrical safety and software validation standards that extend product development timelines but elevate barrier-to-entry for non-compliant entrants. Australia's TGA aligns with EU MDR convergence pathways, requiring clinical evidence packages that favor established manufacturers with deep regulatory affairs capabilities. China's NMPA implements tiered review tracks under its 2021 medical device rules, accelerating approvals for domestically manufactured ambulatory pumps while subjecting imports to extended technical审评. Stakeholders must monitor how India's CDSCO harmonizes with IMDRF standards for software-as-a-medical-device, as this will determine whether cloud-connected pumps gain market access ahead of local competitors.
Market Dynamics
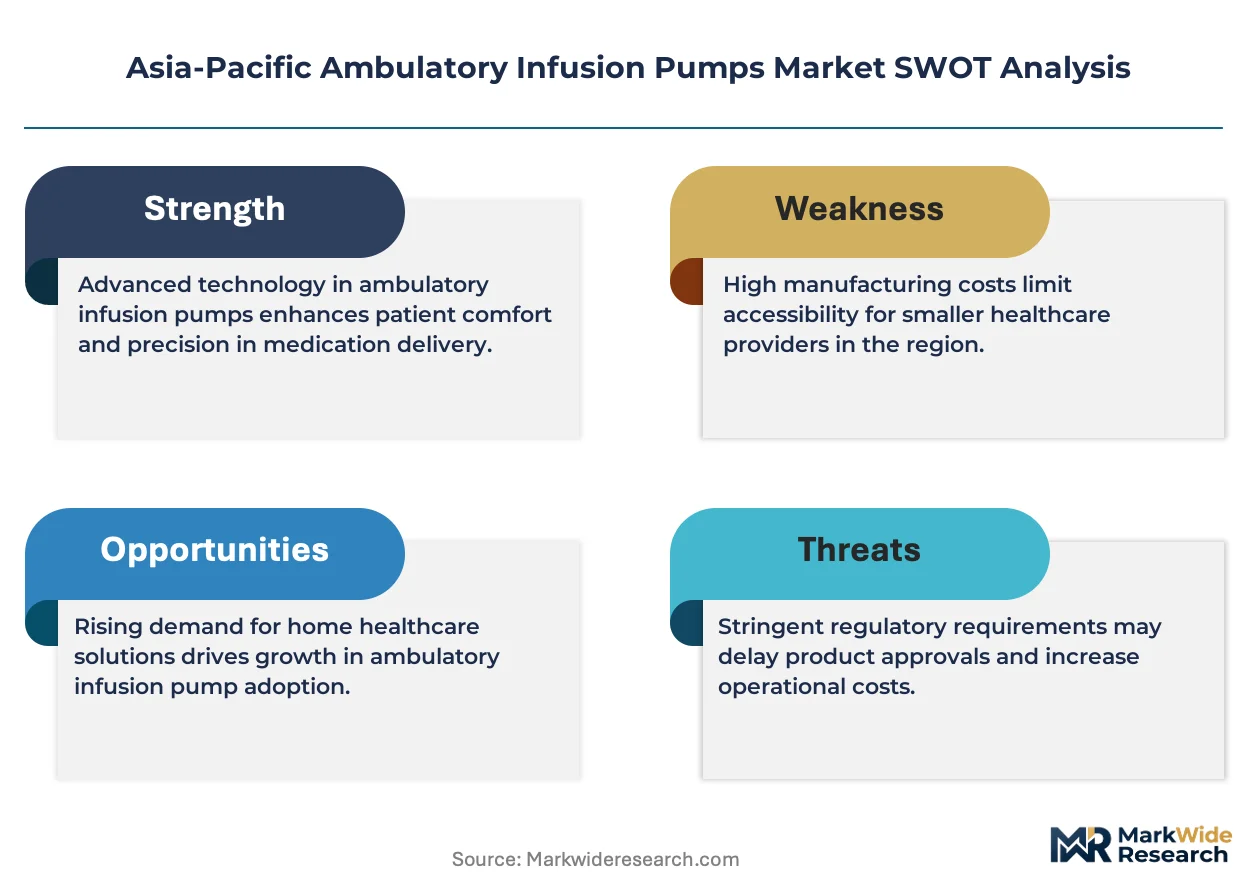
Japan's PMDA electrical safety mandates and China's NMPA tiered review tracks are compressing product development timelines while elevating compliance costs for ambulatory pump manufacturers across the Asia-Pacific region.
Growth Catalysts
- Homecare reimbursement expansion:Australia's TGA-aligned pathways and South Korea's MFDS coverage for patient-controlled analgesia outside hospitals are accelerating ambulatory pump deployment in non-institutional settings.
- Aging demographics:Japan's super-aged population profile creates sustained demand for portable chemotherapy and pain management systems that enable self-administered therapy.
- Disposable cassette innovation:Modular pump configurations paired with single-use fluid pathways are lowering total cost of ownership for price-sensitive hospital procurement committees in Southeast Asia.
Market Restraints
- Regulatory friction:China's NMPA subjects imported ambulatory pumps to extended technical审评 while accelerating domestically manufactured alternatives, tilting competitive access.
- Supply concentration risk:Precision syringe pump motors and medical-grade polymers concentrate in Japanese and German component suppliers, exposing assemblers to input bottlenecks.
- Substitution pressure:Gravity-fed disposable infusion systems displace volumetric pumps in homecare settings where flow rate precision requirements fall below clinical thresholds.
Strategic Opportunities
- Underpenetrated geographies:India's CDSCO harmonization with IMDRF software-as-a-medical-device standards will determine whether cloud-connected pumps gain market access ahead of local competitors.
- Technology convergence:Integration of occlusion sensors with Bluetooth-enabled dose-error reduction software is rewriting connectivity standards for remote patient monitoring platforms.
- Regulatory tailwind:Australia's TGA EU MDR convergence creates accelerated approval pathways for manufacturers with existing European clinical evidence packages.
Industry Challenges
- Software validation expertise scarcity:PMDA's stringent software lifecycle documentation requirements exceed the regulatory affairs capacity of mid-tier manufacturers without dedicated quality systems teams.
- Legacy system integration friction:Hospital information system compatibility gaps complicate deployment of smart pumps with electronic medical record connectivity in fragmented Southeast Asian healthcare networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Ambulatory Infusion Pumps Market |
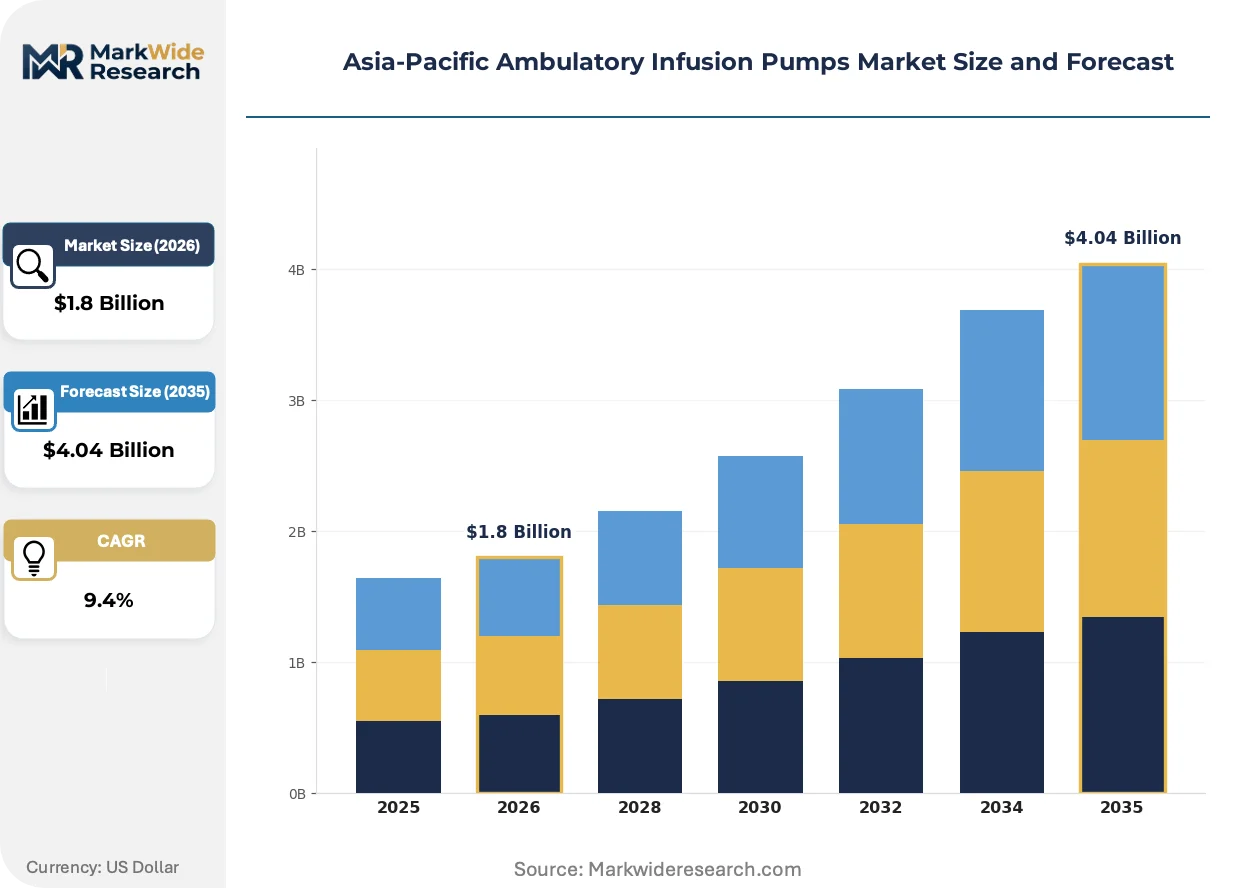
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.04 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Volumetric Pumps, Syringe Pumps, Gravity Pumps, PCA Pumps End User: Homecare Settings, Hospitals, Clinics, Rehabilitation Centers Delivery Mode: Intravenous, Subcutaneous, Epidural, Intramuscular Application: Chemotherapy, Pain Management, Antibiotic Therapy, Anesthesia |
| Companies Covered | B. Braun Melsungen AG, Baxter International Inc., Medtronic plc, BD, Fresenius Kabi AG, ICU Medical, Inc., Terumo Corporation, Nipro Corporation, JMS Co., Ltd., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Ambulatory Infusion Pumps Market Strategic Shifts
Wearable form factors and disposable fluid pathways are compressing the traditional distinction between hospital-grade precision and homecare convenience across Asia-Pacific infusion pump procurement.
Bluetooth-enabled dose-error reduction software with real-time occlusion detection is rewriting safety protocols for ambulatory chemotherapy delivery. Oncology departments in Japan's regional hospitals are adopting these connected systems ahead of scheduled PMDA software validation deadlines. The technology is compressing liability exposure for clinicians managing high-risk infusion protocols outside intensive care settings.
Australia's TGA alignment with EU MDR convergence pathways now mandates clinical evidence packages that exceed previous technical file requirements. Established manufacturers with deep regulatory affairs capabilities are consolidating tender advantages while newer entrants face extended review timelines. South Korean and Australian hospital procurement committees are prioritizing CE-MDR certified devices in centralized purchasing frameworks.
Leasing arrangements with unbundled after-sales service contracts are displacing traditional capital equipment purchases in Japan's homecare sector. Regional medical device distributors are building technical service networks to capture recurring revenue streams from wearable pump maintenance. This shift is most visible in Tokyo and Osaka metropolitan clusters where aging-in-place policy incentives concentrate patient volume.
Asia-Pacific Ambulatory Infusion Pumps Market Segmentation
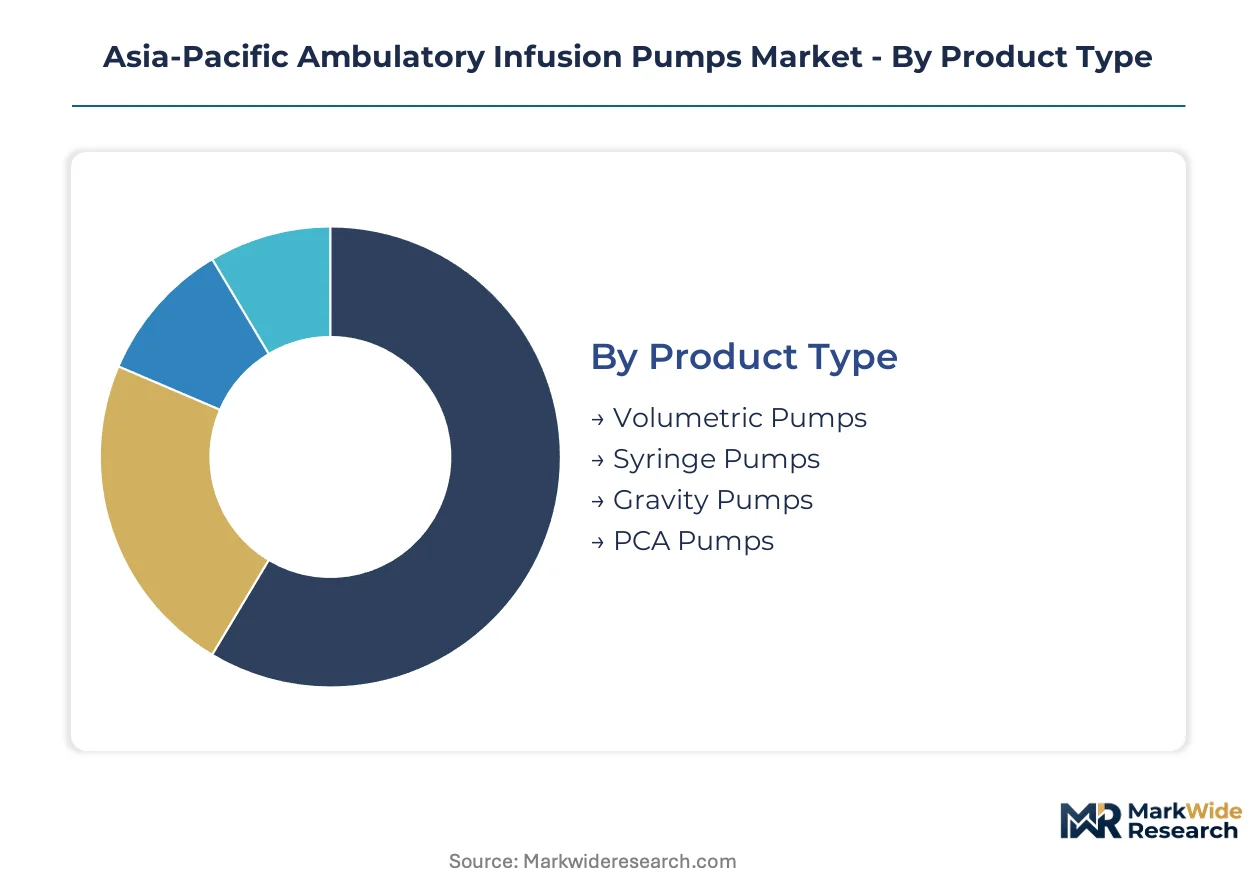
Ambulatory infusion pump procurement across Asia-Pacific bifurcates between high-throughput hospital systems and cost-optimized homecare channels. Product configurations, delivery modes, and end-use settings each command distinct specification requirements that reshape vendor positioning and margin structures.
Product Type:
Volume concentration sits with volumetric systems while premium capture belongs to precision syringe configurations.
- Volumetric Pumps:These devices deliver large fluid volumes through peristaltic or cassette mechanisms, typically 1 to 999 milliliters per hour with programmable flow profiles. Demand concentrates in China's tertiary hospital networks where chemotherapy throughput volumes strain centralized pharmacy compounding capacity. PMDA electrical safety mandates extend development timelines but protect incumbent positions against low-cost entrants.
- Syringe Pumps:Motor-driven plunger systems achieve flow accuracy below two percent variance, critical for pediatric dosing and anesthesia delivery where medication errors carry severe liability exposure. Japan's homecare reimbursement pathways favor compact, wearable syringe designs that enable self-administered opioid rotation therapy outside institutional walls.
- Gravity Pumps:Disposable, non-electric systems leverage height differential and drip-rate regulators for basic antibiotic infusion in Southeast Asian rural clinics where electricity reliability fluctuates.
- PCA Pumps:Patient-controlled analgesia devices with programmable lockout intervals and bolus dose limits address cancer pain management. Australia's TGA-aligned reimbursement expansion for outpatient oncology is accelerating deployment in Sydney and Melbourne metropolitan clusters.
Today's leader: Volumetric Pumps. Tomorrow's challenger: PCA Pumps.
End User:
Institutional procurement dominates capital equipment sales while homecare channels drive recurring revenue through disposable attachment.
- Homecare Settings:Aging-in-place policy incentives across Japan and South Korea are redirecting chemotherapy and palliative care from hospital wards to residential environments. Wearable pump form factors with Bluetooth-enabled remote monitoring satisfy reimbursement requirements for supervised self-administration.
- Hospitals:Australia's TGA EU MDR convergence mandates clinical evidence packages that favor established manufacturers in centralized purchasing frameworks across New South Wales and Victoria health districts.
- Clinics:Outpatient infusion centers in China's tier-two cities prioritize modular pump configurations with disposable cassettes to minimize sterilization infrastructure investment.
- Rehabilitation Centers:Post-acute facilities in Japan's regional prefectures deploy lightweight ambulatory systems for prolonged antibiotic therapy during functional recovery programs.
Homecare Settings capture margin expansion fastest. Hospitals retain volume concentration longest.
Delivery Mode:
Route selection follows therapeutic index requirements and vascular access durability considerations across patient populations.
- Intravenous:Peripheral and central venous catheter delivery dominates chemotherapy and fluid replacement protocols. China's NMPA tiered review tracks accelerate approvals for domestically manufactured IV pump systems while subjecting imports to extended technical evaluation.
- Subcutaneous:Interstitial infusion of insulin, opioids, and immunoglobulins enables continuous delivery without vascular access maintenance. South Korea's MFDS reimbursement expansion for subcutaneous immunoglobulin home therapy is driving wearable pump adoption in Seoul metropolitan clusters.
- Epidural:Catheter-based neuraxial delivery for labor analgesia and chronic pain management requires precision occlusion detection and air-in-line sensors that satisfy Japan's PMDA software validation standards.
- Intramuscular:Depot medication administration in psychiatric and endocrine applications employs programmable syringe pumps with depth-controlled needle insertion for consistent tissue deposition.
Intravenous maintains installed base dominance. Subcutaneous demonstrates steepest expansion trajectory among non-institutional channels.
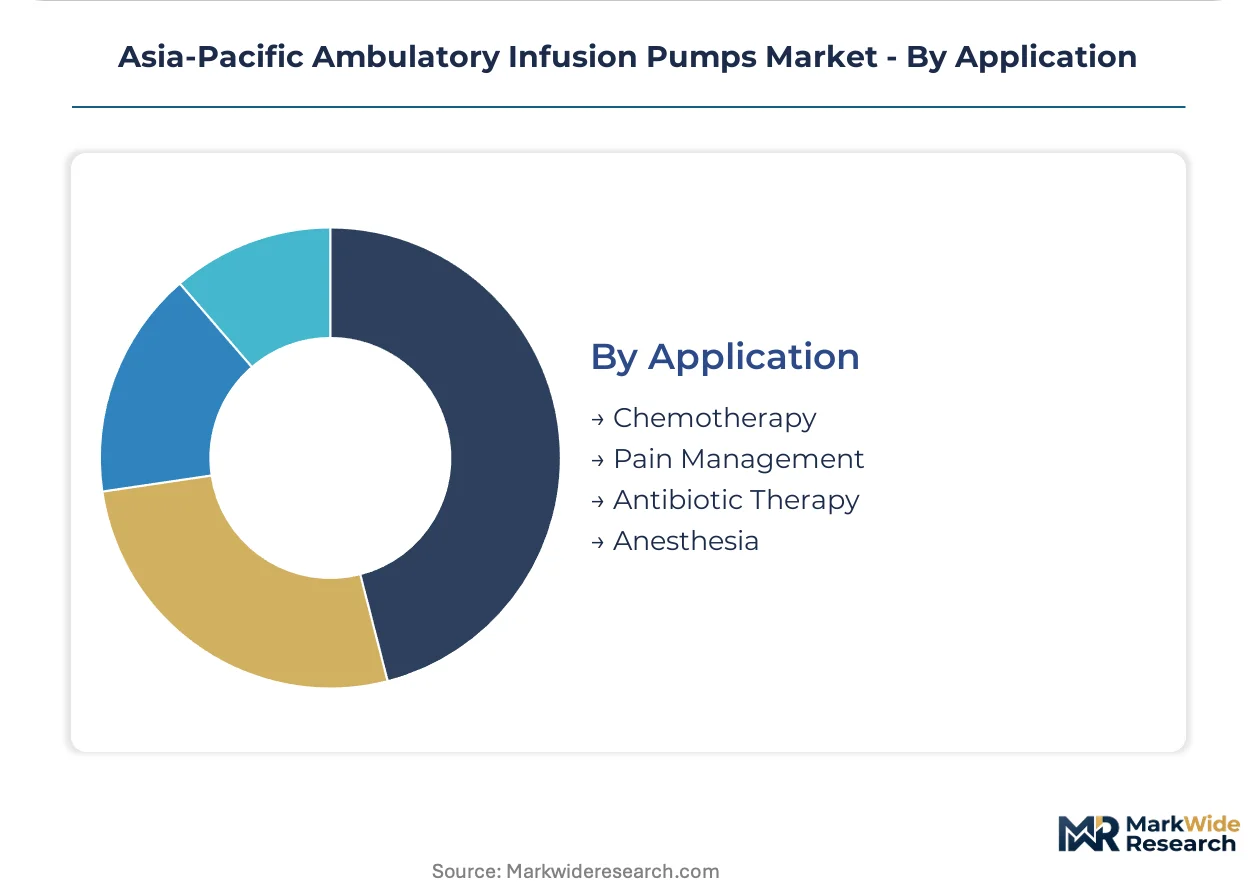
Application:
Therapeutic area concentration determines sensor sophistication, software validation tier, and service contract bundling requirements.
- Chemotherapy:Vesicant and irritant drug protocols demand dose-error reduction software with hard limits on bolus delivery and continuous occlusion pressure monitoring. Japan's regional oncology networks are adopting Bluetooth-connected systems ahead of PMDA software lifecycle documentation deadlines.
- Pain Management:Opioid rotation and neuropathic pain protocols in Australia's palliative care networks require PCA functionality with patient-controlled bolus and clinician-set lockout parameters.
- Antibiotic Therapy:Extended-duration beta-lactam and glycopeptide infusion for resistant infections favors disposable gravity systems in Southeast Asian settings where total cost of ownership constraints predominate.
- Anesthesia:Target-controlled infusion for total intravenous anesthesia commands syringe pump precision with pharmacokinetic model integration in Japan's university hospital surgical suites.
Chemotherapy anchors premium pricing power. Pain Management is gaining share fastest through reimbursement expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan pioneered ambulatory infusion pump commercialization in the Asia-Pacific, establishing the regulatory and manufacturing foundations that neighboring markets later adapted. South Korea and Australia subsequently developed reimbursement frameworks that accelerated homecare adoption. China's domestic manufacturing scale now reshapes supply dynamics across the region.
Japan
Super-aged demographics and aging-in-place policy incentives sustain demand for portable chemotherapy and pain management systems. PMDA enforces stringent electrical safety and software validation standards that extend product development timelines but elevate barriers for non-compliant entrants. Tokyo and Osaka metropolitan clusters concentrate leasing arrangements with unbundled after-sales service contracts displacing traditional capital purchases.
China
Tertiary hospital networks drive volumetric pump procurement where chemotherapy throughput strains centralized pharmacy capacity. NMPA implements tiered review tracks under its 2021 medical device rules, accelerating approvals for domestically manufactured pumps while subjecting imports to extended technical evaluation. Tier-two cities prioritize modular pump configurations with disposable cassettes to minimize sterilization infrastructure investment.
Australia
TGA-aligned reimbursement pathways for patient-controlled analgesia outside hospitals accelerate ambulatory pump deployment in non-institutional settings. TGA alignment with EU MDR convergence mandates clinical evidence packages that favor established manufacturers with deep regulatory affairs capabilities. New South Wales and Victoria health districts prioritize CE-MDR certified devices in centralized purchasing frameworks.
South Korea
MFDS coverage expansion for subcutaneous immunoglobulin home therapy drives wearable pump adoption in Seoul metropolitan clusters. Aging demographics and reimbursement support for portable infusion systems create sustained demand pull comparable to Japan's trajectory. Regional medical device distributors build technical service networks to capture recurring revenue from maintenance contracts.
India
CDSCO harmonization with IMDRF software-as-a-medical-device standards will determine whether cloud-connected pumps gain market access ahead of local competitors. Outpatient infusion centers in major metros face legacy hospital information system compatibility gaps complicating smart pump deployment. Fragmented healthcare networks create procurement challenges for electronic medical record connectivity.
Asia-Pacific Ambulatory Infusion Pumps Market Competitive Environment
Premium-margin players sit above commodity-margin players across regulatory certification tiers, with PMDA-validated and CE-MDR-certified systems commanding tender advantages in centralized purchasing frameworks. The vendor base organizes into three strategic archetypes: diversified medical technology conglomerates with integrated fluid-delivery ecosystems, specialized pump manufacturers with compact wearable designs optimized for homecare reimbursement, and regional assemblers leveraging domestic regulatory acceleration. Dominant competitive moves include geographic expansion through distributor technical service networks and portfolio diversification into disposable cassette systems that lower total cost of ownership.
Among diversified medical technology conglomerates, B. Braun Melsungen AG and Baxter International Inc. occupy positions anchoring integrated supply strategies across Asia-Pacific hospital networks. Terumo Corporation exemplifies the specialized wearable design archetype, with compact form factors aligned to Japan's homecare reimbursement pathways. These three entities represent distinct competitive vectors—European manufacturing footprint leverage, fluid-delivery ecosystem integration, and regional regulatory optimization—shaping procurement committee evaluations across institutional and non-institutional channels.
| Leading Market Players |
|---|
| B. Braun Melsungen AG |
| Baxter International Inc. |
| Medtronic plc |
| BD |
| Fresenius Kabi AG |
| ICU Medical, Inc. |
| Terumo Corporation |
| Nipro Corporation |
| JMS Co., Ltd. |
| Others |
Value Chain & Pricing Dynamics
Medical-grade polymer costs flow from Japanese and German specialty chemical suppliers through precision syringe pump motor assemblers, ultimately stratifying into premium PMDA-validated tiers and cost-optimized disposable cassette configurations for Southeast Asian procurement committees.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates PMDA-validated systems with unbundled service contracts from CE-MDR certified hospital equipment and disposable gravity pumps for rural clinics. Price differentiation rests on certification tier and after-sales service bundling, with premium tiers capturing margin from software validation documentation. Cost compression in standard-tier volumetric pumps is intensifying because China's NMPA accelerates domestic approvals. Homecare channels in Japan and South Korea show least price sensitivity due to reimbursement coverage, while Southeast Asian hospital procurement committees exhibit highest sensitivity to total cost of ownership.
Supply Chain Analysis
Workforce availability for precision motor winding and medical-grade polymer molding concentrates in Japan's Aichi prefecture and Germany's Baden-Württemberg region, with secondary assembly capacity emerging in China's Jiangsu province. Raw material dependencies center on neodymium rare-earth magnets, medical-grade polycarbonate, and silicone elastomer tubing. Single-source vulnerability from Japanese precision motor suppliers exposes assemblers to input bottlenecks when PMDA inspection backlogs delay component release. Distribution runs through regional medical device distributors building technical service networks across Tokyo, Seoul, and Sydney metropolitan clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds returns through regulatory complexity, with Australia's TGA-EU MDR convergence creating accelerated approval pathways that favor manufacturers with existing European clinical evidence packages.
For Market Incumbents: To counter substitution pressure from gravity-fed disposable systems, deepen software validation expertise for PMDA lifecycle documentation and secure dual-source supply agreements for precision syringe pump motors through backward integration into German component suppliers. For New Entrants and Emerging Players: The price-point gap between premium PMDA-validated wearable pumps and economy gravity systems opens entry vectors through compact syringe designs targeting South Korea's MFDS reimbursement expansion for subcutaneous immunoglobulin home therapy, leveraging distributor technical service partnerships for aftermarket capture. For Investors and Strategic Acquirers: Roll-up economics work for specialized wearable pump manufacturers with regional regulatory optimization because Japan's aging-in-place policy incentives concentrate patient volume in leasing arrangements with recurring maintenance revenue. Target mid-cap specialists with PMDA software validation capabilities and existing CE-MDR certification. Watch India's CDSCO harmonization with IMDRF software-as-a-medical-device standards as inflection indicator for cloud-connected pump market access timing.| Strategic Initiative | Industry Significance |
|---|---|
| PMDA Software Validation Investment | Extends development timelines but elevates barrier-to-entry for non-compliant competitors in Japan. |
| Disposable Cassette System Development | Lowers total cost of ownership for price-sensitive hospital procurement committees in Southeast Asia. |
| Bluetooth-Enabled Dose-Error Reduction | Rewrites connectivity standards for remote patient monitoring platforms in Australian oncology networks. |
| Regional Distributor Technical Service Networks | Captures recurring revenue streams from wearable pump maintenance in Tokyo and Osaka clusters. |
| CE-MDR Certification Pathway | Creates accelerated TGA approval access for established manufacturers with European clinical evidence. |
Study Parameters
Coverage spans Japan, China, Australia, South Korea, and India, with primary inputs from each market combining interviews with hospital procurement managers, biomedical engineers, GPO contracts managers, and regulatory affairs leads with secondary validation from PMDA filings, TGA registration databases, NMPA technical审评 records, and hospital procurement contract repositories. Bottom-up demand modeling and top-down supply capacity triangulation anchor volume and value estimates.
Granularity-level modeling disaggregates the analysis window by product type, end user, delivery mode, and application, with additional segmentation by regulatory certification tier. CAGRs derive from installed base growth, replacement cycle compression, and reimbursement pathway expansion across each national market. Forecast inputs incorporate aging demographic trajectories, policy incentive shifts, and software validation timeline assumptions.
Caveats apply where NMPA regulatory acceleration, PMDA inspection backlog duration, or MFDS reimbursement expansion timing could materially shift the outlook. Forecasts reflect assumptions about harmonization progress and policy continuity. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Manual Resuscitators Market
Medical Devices
Wheelchair and Components Market
Medical Devices
Sentinel Node Biopsy Market
Medical Devices
Microneedling Cartridges Market
Medical Devices
Autorefractor Keratometer Market
Medical Devices
EEG and EMG Equipment Market
Medical Devices
Uterine Fibroid Treatment Device Market
Medical Devices
Microscope Market
Medical Devices
Active Humidifier Devices Market
Medical Devices
Printed Electronics in Healthcare Market
Medical Devices
Thrombectomy System Market
Medical Devices
Self-Injections Market
Medical Devices
Hearing Devices 3D Printing Market
Medical Devices
AI Colonoscopy Withdrawal Quality Monitoring System Market
Medical Devices
Global Tumor Tracking Systems Market
Medical Devices
External Pacemakers Market