
 Cardiac Cannulas Market | 2026-2036
Cardiac Cannulas Market Size, Share, and Industry Trends Forecast 2026-2036
Cardiac Cannulas Market Outlook
Hospital procurement consolidation across integrated delivery networks is expanding the addressable base for high-volume cannula contracts. Medtronic leverages its end-to-end cardiac surgery portfolio to anchor multi-year supply agreements with major health systems. Edwards Lifesciences Corporation differentiates through specialized perfusion technologies that command premium positioning in academic medical centers. BD competes on manufacturing scale and global distribution density across surgical centers and emergency departments.
Cardiac cannulas are sterile, biocompatible tubes engineered for extracorporeal blood diversion during open-heart procedures, typically fabricated from medical-grade silicone or polyurethane with reinforced walls to prevent kinking under negative pressure. Venous cannulas dominate procedural volume due to their mandatory role in cardiopulmonary bypass circuits, while arterial cannulas capture disproportionate margin pools where hemodynamic performance requirements intensify material and design specifications. Specialty cannulas represent the fastest-growing product category as minimally invasive cardiac surgery and ECMO applications expand the functional range beyond standard perfusion setups.
FDA 510(k) premarket notification requirements and the EU MDR's tightened clinical evidence standards are elevating compliance costs and extending time-to-market for new cannula designs. ISO 10993 biocompatibility testing and ISO 13485 quality management certification function as baseline market access prerequisites across all major jurisdictions. Stakeholders must monitor how Japan's PMDA and China's NMPA converge toward harmonized biological safety standards that will reshape global product development roadmaps.
Market Dynamics
Hospital procurement consolidation across integrated delivery networks is compressing vendor margins while expanding contract volumes, forcing manufacturers to restructure pricing architectures around multi-year supply commitments rather than transactional sales.
Growth Catalysts
- EU MDR Clinical Evidence Standards:Tightened biocompatibility documentation requirements under the Medical Device Regulation are accelerating replacement cycles for legacy cannula portfolios as hospitals preempt compliance-driven supply disruptions.
- ECMO Expansion in Emergency Departments:Extracorporeal membrane oxygenation deployment outside traditional cardiac surgery suites is creating incremental demand for specialty venous-arterial cannula configurations.
- Japan's Aging Surgical Population:Elevated coronary artery bypass grafting volumes among patients over seventy-five are sustaining procedural throughput for perfusion cannulas in Tokyo and Osaka metropolitan hospital clusters.
Market Restraints
- Medical-Grade Silicone Price Volatility:Petrochemical feedstock fluctuations and semiconductor-sector competition for specialty silicones are compressing gross margins on standard venous cannula lines.
- Single-Source Concentration in Reinforced Tubing:German and Swiss specialty polymer suppliers control critical polyurethane extrusion capacity for arterial cannula walls, creating geographic supply vulnerability.
- Biocompatibility Testing Bottlenecks:ISO 10993 cytotoxicity and sensitization study backlogs at contracted laboratories are extending product development timelines by eight to fourteen months.
Strategic Opportunities
- India's PLI Scheme for Medical Devices:Production-linked incentive allocations for cardiac surgery consumables are attracting contract manufacturing investment to serve price-sensitive Asian and African markets.
- Minimally Invasive Port Configurations:Percutaneous cannula designs for robotic-assisted cardiac procedures represent unpenetrated white space beyond conventional sternotomy applications.
- Digital Supply Chain Integration:Direct EDI connectivity with hospital ERP systems enables vendor-managed inventory programs that lock out competitors through technical integration barriers.
Industry Challenges
- Perfusionist Talent Scarcity:Shrinking enrollment in certified cardiovascular perfusion training programs in the United States and Germany is constraining procedural capacity expansion regardless of cannula availability.
- EU MDR Technical Documentation Burden:Clinical evaluation report requirements for substantially equivalent devices are forcing small manufacturers to abandon product lines rather than absorb compliance costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cardiac Cannulas Market |
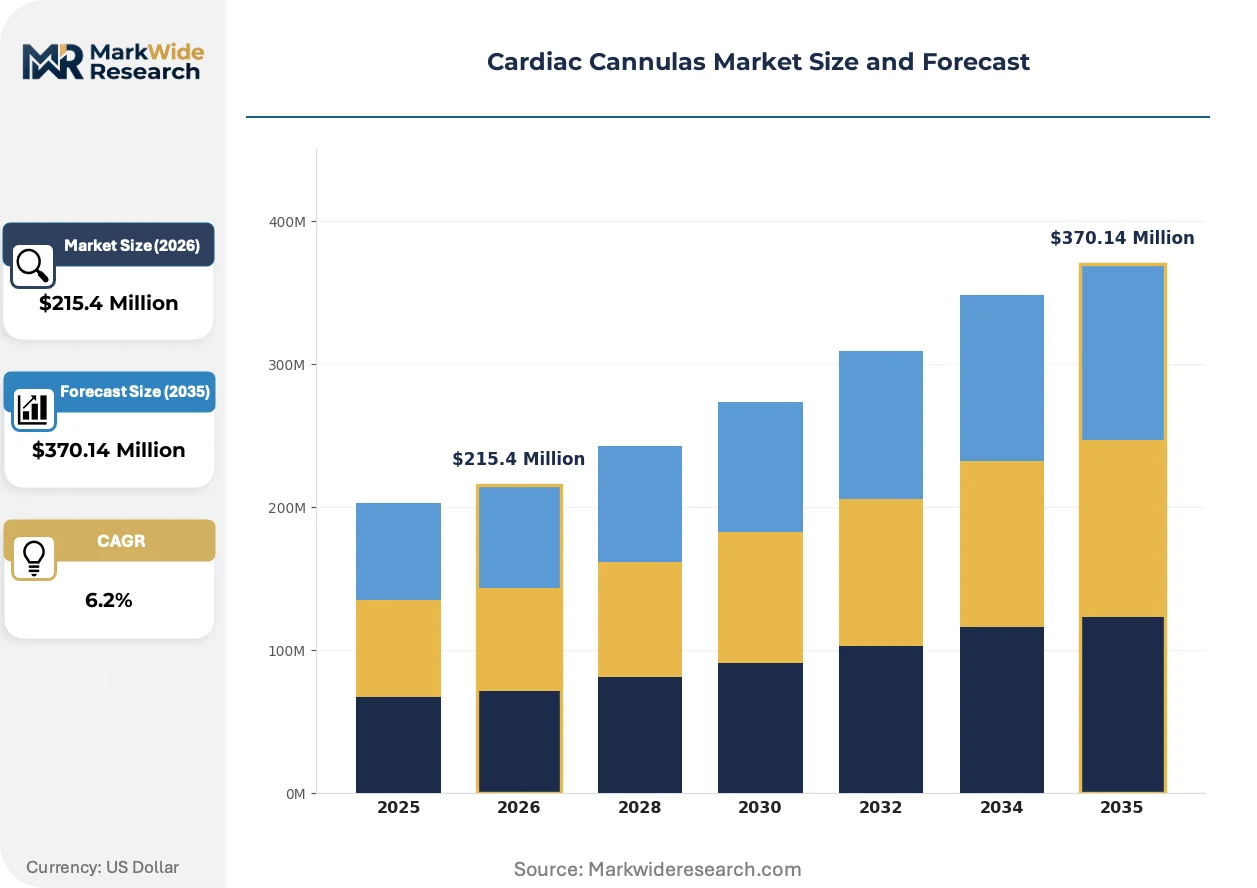
| Market Size in 2026 | $215.4 Million |
| Market Size in 2035 | $370.14 Million |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Venous Cannulas, Arterial Cannulas, Combined Cannulas, Specialty Cannulas Material: Silicone, PVC, Polyurethane, Teflon Application: Cardiac Surgery, Blood Transfusion, ECMO, Heart-Lung Machine End User: Hospitals, Surgical Centers, Cardiology Clinics, Emergency Departments |
| Companies Covered | Medtronic, BD (Becton, Dickinson and Company), Edwards Lifesciences Corporation, LivaNova PLC, Terumo Corporation, Getinge, Surge Cardiovascular, Smartcanula LLC, Braile Biomédica, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cardiac Cannulas Market Strategic Shifts
Material science advances and regulatory harmonization pressures are converging to reshape cannula design specifications, manufacturing processes, and commercialization pathways across all major cardiac surgery markets.
Reinforced hybrid cannula construction combining silicone lumens with polyurethane outer jackets is modularizing perfusion circuit architecture. Academic medical centers in Germany and Japan are adopting these configurations for complex redo sternotomy cases. The technology is modularizing supplier relationships as hospitals consolidate vendors around platforms supporting multiple cannula diameters and lengths from standardized connection hubs.
EU MDR's post-market surveillance requirements are mandating systematic implant registries and periodic safety update reports for Class IIb cardiovascular devices. Manufacturers must now maintain clinical follow-up infrastructure that was previously optional. Arterial cannula portfolios face disproportionate scrutiny given hemodynamic failure risks, prompting accelerated redesign cycles in Dublin and Stuttgart regulatory hubs.
Integrated delivery networks in the United States are consolidating cardiac surgery supply contracts under single-source agreements spanning sutures, cannulas, and oxygenators. Independent hospitals and smaller regional systems are losing negotiating leverage as purchasing volume thresholds rise. Texas and Florida health systems exhibit the most aggressive consolidation, with three-year sole-source commitments replacing annual competitive bidding cycles.
Cardiac Cannulas Market Segmentation
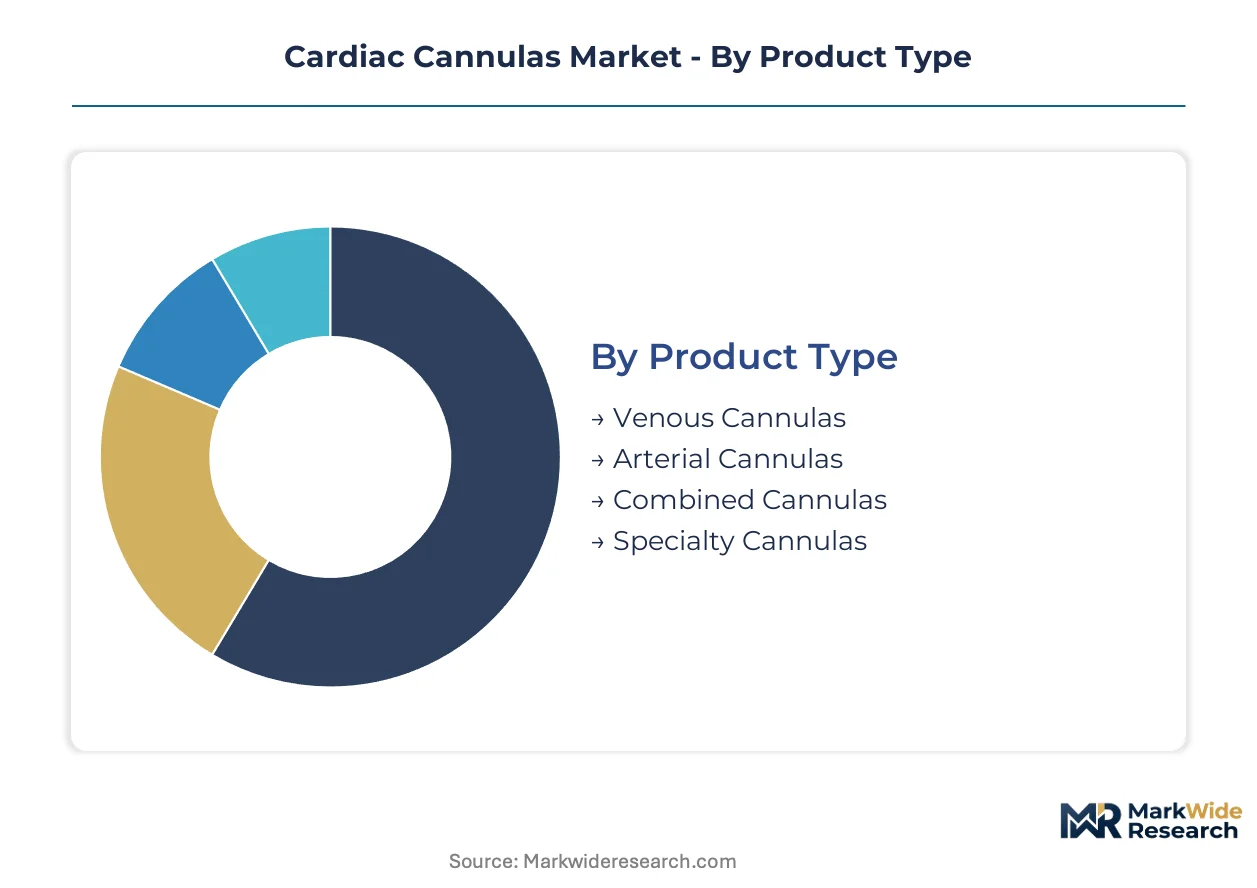
Segmentation in cardiac cannulas reveals how capital deployment, regulatory burden, and clinical workflow requirements fragment manufacturing economics. Each dimension—product architecture, material specification, procedural application, and facility type—carries distinct margin profiles and compliance thresholds that reshape competitive positioning.
Product Type:
Capital intensity escalates with hemodynamic performance requirements, as arterial and specialty configurations demand precision extrusion and reinforced wall engineering that venous alternatives avoid.
- Venous Cannulas:Fabricated from medical-grade silicone with thin-walled construction optimized for low-pressure venous return. Demand concentrates in high-volume coronary artery bypass grafting procedures across United States metropolitan hospital clusters, constrained by medical-grade silicone price volatility from petrochemical feedstock fluctuations.
- Arterial Cannulas:Reinforced polyurethane-silicone hybrid construction withstands systemic pressure and high-velocity flow profiles. Academic medical centers in Germany and Japan command premium positioning for these configurations in complex redo sternotomy cases, where hemodynamic failure risks intensify regulatory scrutiny.
- Combined Cannulas:Integrated venous-arterial designs reduce circuit complexity and connection points. Standard perfusion setups in mid-tier surgical centers drive procurement volume.
- Specialty Cannulas:Percutaneous and minimally invasive port configurations for robotic-assisted cardiac procedures and ECMO applications. Fastest expansion trajectory as extracorporeal membrane oxygenation deployment extends beyond traditional cardiac surgery suites.
Most installed capacity flows through Venous Cannulas. Expansion is steepest in Specialty Cannulas.
Material:
Raw material selection determines biocompatibility certification pathways and supply chain vulnerability, with specialty polymers commanding price premiums that stratify manufacturing economics.
- Silicone:Dominant substrate for venous cannula lumens due to superior biocompatibility and kink resistance. Standard cardiopulmonary bypass circuits in United States and German hospital systems sustain procurement volume, though semiconductor-sector competition for specialty silicones compresses margins.
- Polyurethane:Reinforced arterial cannula walls require German and Swiss specialty polymer extrusion capacity. Geographic supply concentration creates vulnerability for manufacturers dependent on European feedstock.
- PVC:Cost-optimized alternative for standard perfusion setups in price-sensitive Asian and African markets. India's PLI scheme for medical devices attracts contract manufacturing investment.
- Teflon:Low-friction coating applications and specialty arterial configurations. Limited adoption outside high-performance academic medical center procurement.
Procurement volume concentrates in Silicone. Polyurethane captures disproportionate margin pools.
Application:
Procedural setting dictates cannula specification complexity, with extracorporeal and emergency applications demanding configurations that standard cardiac surgery suites do not require.
- Cardiac Surgery:Open-heart procedures including coronary artery bypass grafting and valve replacement. Tokyo and Osaka metropolitan hospital clusters in Japan sustain elevated procedural throughput among aging surgical populations.
- ECMO:Extracorporeal membrane oxygenation for respiratory and cardiac failure. Emergency departments in Texas and Florida health systems drive incremental demand for specialty venous-arterial configurations.
- Heart-Lung Machine:Standard cardiopulmonary bypass circuits. Integrated delivery network consolidation compresses vendor margins through multi-year supply agreements.
- Blood Transfusion:Ancillary perfusion applications with lower specification requirements. Price-sensitive procurement dominates.
Revenue concentration sits with Cardiac Surgery. ECMO applications expand most quickly.
End User:
Facility scale and integration status determine contract structure, with consolidated health systems extracting volume discounts that independent hospitals cannot match.
- Hospitals:Major academic medical centers and integrated delivery networks in United States, Germany, and Japan. Texas and Florida health systems exhibit aggressive procurement consolidation with three-year sole-source commitments.
- Surgical Centers:Ambulatory and regional cardiac facilities. BD competes on manufacturing scale and distribution density across these sites.
- Emergency Departments:ECMO deployment outside traditional cardiac surgery suites. Creates incremental demand for rapid-deployment specialty cannula configurations.
- Cardiology Clinics:Diagnostic and interventional facilities with limited perfusion capabilities. Peripheral cannula consumption.
Contract value concentrates in Hospitals. Technical integration barriers lock in Emergency Department procurement fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Perfusionist training programs in the United States and Germany anchor the specialized workforce that sustains cardiac surgery throughput in these mature markets. Japan's aging surgical population and India's emerging manufacturing incentives are reshaping demand geography.
United States
Integrated delivery networks in Texas and Florida health systems drive aggressive procurement consolidation with three-year sole-source commitments replacing annual bidding cycles. FDA 510(k) clearance pathways maintain streamlined market access for substantially equivalent cannula designs. The Southeast hospital clusters sustain elevated coronary artery bypass grafting volumes among aging patient cohorts.
Germany
Academic medical centers in Stuttgart and Heidelberg command premium positioning for complex redo sternotomy cases requiring reinforced arterial configurations. EU MDR technical documentation requirements are accelerating replacement cycles for legacy cannula portfolios. German and Swiss specialty polymer suppliers control critical polyurethane extrusion capacity for arterial cannula walls.
Japan
Tokyo and Osaka metropolitan hospital clusters sustain procedural throughput for perfusion cannulas among patients over seventy-five undergoing coronary artery bypass grafting. PMDA convergence toward harmonized biological safety standards is reshaping global product development roadmaps. METI industrial policy supports domestic manufacturing capacity for cardiovascular devices.
India
Production-linked incentive allocations for cardiac surgery consumables under the PLI scheme are attracting contract manufacturing investment to serve price-sensitive Asian and African markets. CDSCO regulatory frameworks are streamlining medical device registration pathways. Maharashtra and Gujarat industrial corridors are emerging as export-oriented fabrication hubs for standard perfusion setups.
China
NMPA biological safety standards are converging with international norms, reshaping import requirements for multinational manufacturers. Domestic hospital procurement is expanding extracorporeal membrane oxygenation deployment beyond traditional cardiac surgery suites. Yangtze River Delta medical device clusters are developing captive polymer extrusion capabilities to reduce import dependency.
Cardiac Cannulas Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across procurement tiers, creating a bifurcated vendor landscape. Hospital procurement consolidation favors integrated suppliers capable of anchoring multi-year supply agreements spanning entire perfusion circuits. Three archetypes dominate: end-to-end cardiac surgery portfolio holders, specialized perfusion technology developers, and scale-driven manufacturing generalists. Competitive moves concentrate on strategic partnerships with integrated delivery networks and backward integration into polymer feedstock control.
Within the diversified medical technology tier, Medtronic and BD exemplify scale-driven positioning through manufacturing density and global distribution infrastructure. Edwards Lifesciences Corporation occupies a specialized position in premium perfusion technologies for academic medical centers. Among focused cardiovascular device developers, LivaNova PLC and Terumo Corporation represent pure-play specialists with concentrated cardiac surgery portfolios. Getinge anchors European-origin industrial positioning in perfusion and critical care systems.
| Leading Market Players |
|---|
| Medtronic |
| BD (Becton, Dickinson and Company) |
| Edwards Lifesciences Corporation |
| LivaNova PLC |
| Terumo Corporation |
| Getinge |
| Surge Cardiovascular |
| Smartcanula LLC |
| Braile Biomédica |
| Others |
Value Chain & Pricing Dynamics
Family-owned mid-cap specialists in Germany and Switzerland anchor arterial cannula feedstock production, transmitting polyurethane price volatility directly into tiered procurement contracts across United States integrated delivery networks.
Pricing Analysis
Bundled multi-year supply agreements spanning oxygenators, cannulas, and sutures dominate hospital procurement, while unbundled transactional sales persist only among independent surgical centers. Three-tier pricing structure across premium, standard, and economy levels separates reinforced arterial configurations from silicone venous lines and PVC alternatives for Asian markets. Pricing pressure stems from medical-grade silicone feedstock competition with semiconductor fabrication, compressing margins on high-volume venous cannula lines. Academic medical centers in Germany and Japan exhibit lowest price sensitivity due to hemodynamic performance requirements, while mid-tier surgical centers in India and Southeast Asia drive aggressive cost negotiation.
Supply Chain Analysis
Direct-to-hospital channels handle integrated delivery network demand through vendor-managed inventory programs with EDI integration, while distributor networks serve independent surgical centers and emergency departments. Manufacturing concentrates in Germany, Switzerland, and the United States for specialty polymer extrusion and precision cannula fabrication. Raw material dependencies center on medical-grade silicone feedstocks, reinforced polyurethane tubing, and biocompatible coating chemistries. Single-source concentration in German and Swiss specialty polymer suppliers creates geographic supply vulnerability for arterial cannula walls. Distribution runs through regional medical device distributors with cold-chain logistics capabilities for sterile product integrity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cardiac cannulas market functions as a stable compounder anchored by aging demographic profiles in Japan, Germany, and the United States that sustain procedural volume regardless of economic cyclicality.
For Market Incumbents: Hedge against silicone feedstock volatility through backward integration into polymer compounding or long-term offtake agreements with German and Swiss suppliers. Lock in multi-year sole-source commitments with Texas and Florida health systems before EU MDR compliance costs force smaller competitors to abandon product lines, consolidating addressable contract volume. For New Entrants and Emerging Players: The premium-to-economy price gap in arterial cannula configurations creates entry opportunity through mid-tier reinforced designs targeting Indian and Southeast Asian markets under production-linked incentive schemes. Target emergency department ECMO deployment with rapid-deployment specialty cannula kits, leveraging CDSCO streamlined pathways and Maharashtra industrial corridor fabrication capacity for cost-competitive positioning. For Investors and Strategic Acquirers: Valuations sit cheapest among contract manufacturers with captive polymer extrusion capabilities and dormant FDA 510(k) portfolios awaiting clinical evidence refresh. Five-to-ten year viability rests on regulatory compliance infrastructure rather than product innovation velocity. Monitor EU MDR technical documentation completion rates as inflection indicator for forced exit opportunities among legacy portfolio holders.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Technical Documentation Completion | Accelerates replacement cycles for legacy cannula portfolios as hospitals preempt compliance-driven supply disruptions. |
| Hospital System Partnership | Locks out competitors through EDI-integrated vendor-managed inventory programs with three-year sole-source commitments. |
| Backward Integration into Polymer Feedstock | Defends margin position against medical-grade silicone price volatility from semiconductor-sector competition. |
| Reimbursement Strategy | Secures favorable DRG classification for minimally invasive cannula configurations in robotic-assisted cardiac procedures. |
| CE Marking Pathway | Enables premium positioning in Stuttgart and Heidelberg academic medical centers for complex redo sternotomy cases. |
Study Parameters
Bottom-up hospital procurement modeling reconciled against top-down polymer feedstock tracking forms the analytical core of this study. Primary interviews with perfusionists, hospital purchasing committee chairs, GPO contracts managers, and biomedical engineers informed demand-side assumptions. Secondary validation drew from FDA 510(k) filings, EU MDR technical documentation databases, hospital procurement records, and trade flow data for medical-grade silicone and specialty polyurethane. Triangulation between stakeholder-reported contract structures and disclosed supply agreement volumes anchored volume estimates.
Input-output matrices mapped cannula diameter specifications to procedural throughput across cardiac surgery, ECMO, and heart-lung machine applications. Segmentation dimensions included product architecture, material specification, procedural setting, and facility integration status. CAGRs were derived from regression analysis of historical procedural volumes against demographic projections and technology adoption curves. Forecast inputs incorporated EU MDR transition timelines, India's PLI scheme allocation trajectories, and ECMO deployment expansion in emergency departments.
Caveats apply where perfusionist training program enrollment declines, raw material price spikes, or regulatory harmonization delays could materially shift the outlook. Forecasts reflect documented assumptions regarding procedural volume sustainability and compliance cost absorption capacity among mid-tier manufacturers. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular Devices
Peripheral Intravenous Catheters Market
Cardiovascular Devices
Cardiac Assist Devices Market
Cardiovascular Devices
Human Non-Invasive Blood Pressure (NIBP) Recording System Market
Cardiovascular Devices
Vascular Access Systems Market
Cardiovascular Devices
Spain Cardiovascular Devices Market
Cardiovascular Devices
Vital Signs Monitoring Devices Market
Cardiovascular Devices
Global Cardiovascular Disease Monitoring and Diagnostic Devices Market
Cardiovascular Devices
Australia Cardiovascular Devices Market
Cardiovascular Devices
Integrated Cardiology Devices Market
Cardiovascular Devices
Heart Beat Irregularity Detection Device Market
Cardiovascular Devices
Disposable Blood Pressure Cuffs Market
Cardiovascular Devices
Global Resuscitation Devices Market
Cardiovascular Devices
Global Intravascular Catheters Market
Cardiovascular Devices
3D Cardiac Mapping Systems Market
Cardiovascular Devices
Global Cardiac Arrest Treatment Market
Cardiovascular Devices
Wearable Cardiac Devices Market