
 Intra-Aortic Balloon Pump (IABP) Market | 2026-2036
Intra-Aortic Balloon Pump (IABP) Market Size, Share, and Industry Trends Forecast 2026-2036
Intra-Aortic Balloon Pump (IABP) Market Foresight
CE marking under the EU Medical Device Regulation is collapsing the competitive field for new entrants, forcing smaller manufacturers to absorb substantial conformity assessment costs. Getinge leverages its integrated critical care portfolio to sustain catheter and console placements across European catheterization labs. Teleflex anchors its position through proprietary sheath technology and dedicated perfusionist training programs. Medtronic competes on manufacturing scale, with vertically assembled console production lines supporting rapid fleet deployment.
An intra-aortic balloon pump is a percutaneous mechanical circulatory support device consisting of a polyurethane balloon catheter inserted via femoral access and synchronized to deflate during systole and inflate during diastole, typically operating at helium-driven frequencies of 1:1 to 1:8 counterpulsation ratios to reduce myocardial oxygen demand and augment coronary perfusion. Its primary commercial purpose is temporary hemodynamic stabilization for patients with refractory cardiogenic shock or weaning from cardiopulmonary bypass. The electromechanical technology segment dominates installed base economics, as console reliability and alarm precision determine hospital purchasing committees while disposable balloon catheter revenue streams generate recurring margin pools. Applications in cardiogenic shock represent the fastest-growing clinical indication, driven by expanding shock team protocols and earlier device deployment before irreversible end-organ damage.
FDA 510(k) clearance pathways and the EU MDR conformity assessment framework govern device safety, biocompatibility testing, and post-market surveillance obligations, with both regulators intensifying scrutiny of balloon fatigue failure modes and helium leak rates. Japan's PMDA enforces parallel quality system inspections that extend approval timelines but reward compliant manufacturers with protected market access. Stakeholders must monitor evolving MDR notified body capacity constraints and FDA guidance on counterpulsation software validation, as regulatory backlog risks could disrupt product renewal cycles and geographic expansion timelines.
Market Dynamics
Balloon catheter durability failures and helium leak rates are intensifying regulatory scrutiny, forcing manufacturers to revalidate fatigue testing protocols and absorb extended conformity assessment timelines that compress product renewal cycles and reshape competitive positioning.
Growth Catalysts
- EU MDR conformity deadlines:Accelerated notified body audits are filtering marginal suppliers and consolidating procurement toward manufacturers with established quality management systems.
- Shock team protocol expansion:Cardiology departments are embedding IABP deployment earlier in cardiogenic shock pathways, extending device utilization before irreversible end-organ damage.
- Helium-driven counterpulsation:Refinement of 1:1 to 1:8 frequency modulation algorithms is improving myocardial oxygen demand reduction and coronary perfusion augmentation.
Market Restraints
- Polyurethane material fatigue:Balloon membrane degradation under cyclic stress limits catheter functional lifespan and drives replacement cost burdens.
- Notified body capacity bottlenecks:EU MDR technical documentation backlogs are extending CE marking timelines by 12-18 months for new entrants.
- Impella percutaneous ventricular assist devices:Transfemoral micro-axial flow pumps are capturing hemodynamic support cases with higher cardiac output capacity.
Strategic Opportunities
- Japan PMDA quality system inspections:Parallel regulatory pathways reward compliant manufacturers with protected market access and premium pricing corridors.
- Telemetric remote monitoring:Integration of console data streams with hospital information systems enables predictive maintenance and fleet optimization.
- Cardiac surgery department expansion:Tertiary hospital infrastructure buildouts in aging demographic regions are standardizing IABP as hemodynamic support protocol.
Industry Challenges
- Perfusionist training pipeline:Specialized counterpulsation operation expertise is concentrating in established cardiac centers, constraining device deployment in emerging markets.
- 510(k) software validation:FDA guidance on counterpulsation algorithm verification is demanding expanded clinical evidence packages that prolong submission preparation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Intra-Aortic Balloon Pump (IABP) Market |
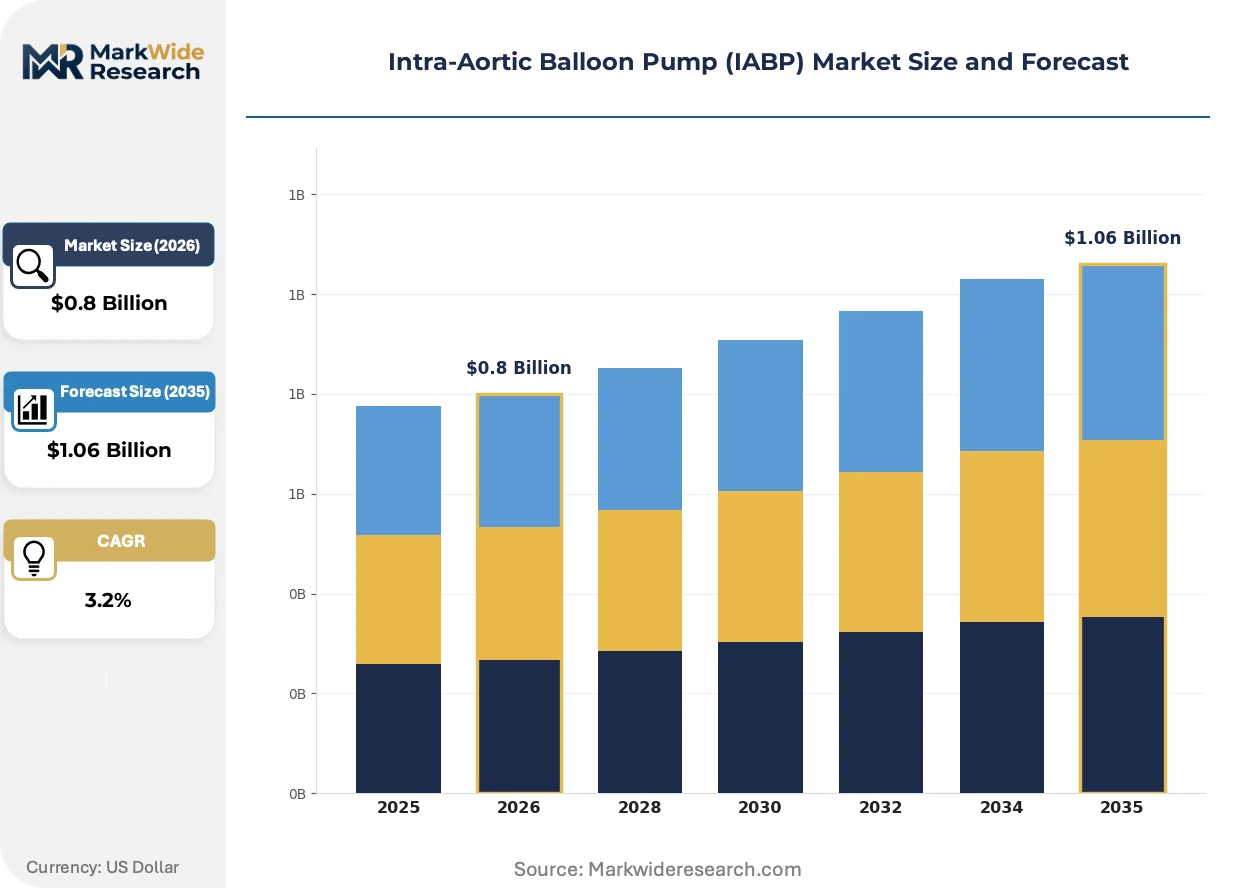
| Market Size in 2026 | $0.8 Billion |
| Market Size in 2035 | $1.06 Billion |
| CAGR (2026 – 2036) | 3.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thermal, Mechanical, Hybrid, Disposable Technology: Electromechanical, Balloon Inflation, Monitoring System, Control Software End User: Cardiology, Emergency Rooms, Cardiac Surgeries, Intensive Care Units Application: Acute Heart Failure, Cardiopulmonary Bypass, Myocardial Ischemia, Cardiogenic Shock |
| Companies Covered | Getinge, Teleflex, Abiomed, Medtronic, Abbott Laboratories, Boston Scientific, Terumo Corporation, Zeon Corporation, Tokai Medical Products, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Intra-Aortic Balloon Pump (IABP) Market Shifts & Advancements
Electromechanical console reliability and disposable catheter economics are converging to reshape hospital procurement criteria, with alarm precision and fleet uptime emerging as decisive purchasing factors alongside recurring revenue stream potential.
Polyurethane balloon membrane coextrusion with embedded radiopaque markers is supplanting conventional single-layer construction in next-generation catheter designs. Tertiary cardiac centers are adopting these enhanced-visibility configurations for fluoroscopy-guided placement accuracy. The technology is supplanting legacy catheter specifications in hospital purchasing committees by reducing malposition rates and procedural complications.
EU MDR Article 120 transition deadlines are compressing technical documentation requirements for legacy device renewals. Manufacturers face intensified biocompatibility testing obligations and post-market clinical follow-up mandates. Balloon fatigue failure mode analysis and helium leak rate documentation are absorbing disproportionate regulatory resource allocation.
Integrated critical care portfolio bundling is displacing standalone console procurement. Hospital value analysis committees are prioritizing vendors offering unified hemodynamic support ecosystems over single-product suppliers. This preference shift is most visible in United States catheterization labs consolidating vendor relationships under supply chain rationalization initiatives.
Intra-Aortic Balloon Pump (IABP) Market Segmentation
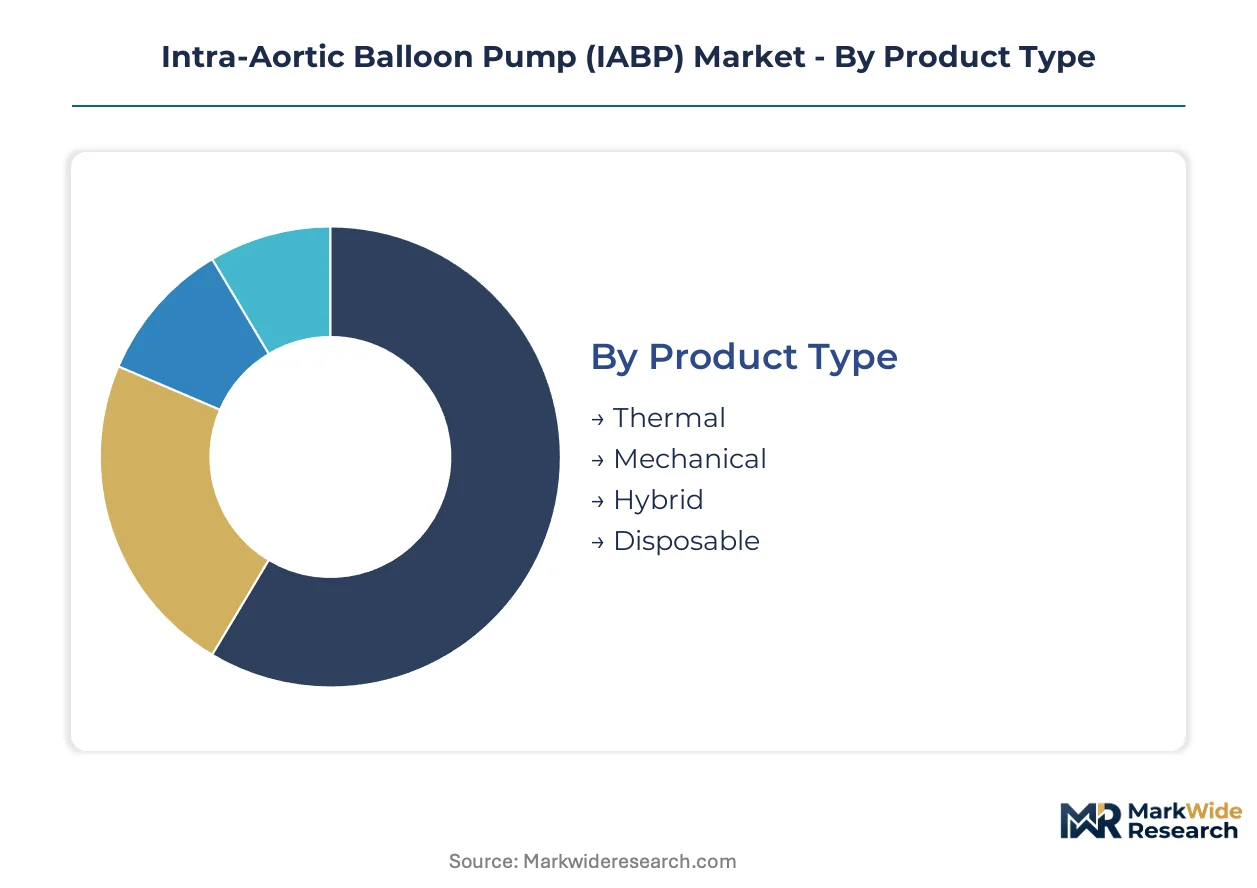
Segmentation in the IABP market reflects distinct procurement patterns across hospital departments and divergent technology stacks between capital equipment and consumables. Understanding these splits reveals where console fleet decisions concentrate versus where recurring catheter revenue accumulates.
Product Type:
Channel flow splits sharply between capital-intensive console systems and single-use disposables, with procurement committees evaluating total cost of ownership differently for each tier.
- Mechanical:Pneumatic drive consoles with helium transfer systems constitute the core installed base in tertiary cardiac centers. United States catheterization labs favor these systems for their established service networks and predictable maintenance contracts.
- Disposable:Polyurethane balloon catheters generate recurring revenue streams that dominate manufacturer margin pools. European procurement is concentrating here as MDR compliance costs squeeze out smaller suppliers and consolidate purchasing toward vendors with validated fatigue testing protocols.
- Thermal:Temperature-regulated console variants serve niche applications in prolonged counterpulsation scenarios.
- Hybrid:Combined mechanical-electronic systems integrate backup pneumatic drives with digital control interfaces.
Mechanical systems dominate installed base. Disposable catheters are where expansion concentrates.
Technology:
Cost tiering separates legacy pneumatic infrastructure from software-enabled precision control, with premium pricing attaching to algorithm-driven synchronization capabilities.
- Electromechanical:Integrated motor-drive consoles with real-time ECG synchronization represent the performance tier. Japan's PMDA quality system inspections favor manufacturers with vertically assembled production lines and validated software verification protocols.
- Control Software:Counterpulsation algorithms modulating 1:1 to 1:8 frequency ratios command premium positioning. FDA 510(k) software validation requirements are extending development timelines but protecting compliant vendors from rapid commoditization.
- Balloon Inflation:Helium delivery mechanisms with leak-rate monitoring ensure diastolic augmentation consistency.
- Monitoring System:Integrated hemodynamic display modules consolidate arterial pressure waveforms with balloon timing metrics.
Electromechanical platforms anchor fleet economics. Control software is climbing the fastest as a differentiation vector.
End User:
Volume concentration tracks cardiac intervention infrastructure density, with procedural throughput determining console placement priority.
- Cardiac Surgeries:Cardiopulmonary bypass weaning protocols sustain the highest utilization rates. United States tertiary hospitals embed IABP as standard hemodynamic support, with perfusionist-staffed teams driving consistent deployment.
- Intensive Care Units:Shock team protocols are expanding device utilization earlier in cardiogenic shock pathways. European ICUs are standardizing IABP access before irreversible end-organ damage develops.
- Cardiology:Catheterization lab placements focus on percutaneous coronary intervention support and refractory angina stabilization.
- Emergency Rooms:Pre-hospital and triage deployments concentrate in urban centers with rapid cardiac catheterization transfer capabilities.
Cardiac surgery departments dominate installed base. Intensive care units are where expansion concentrates.
Application:
Clinical urgency and reimbursement alignment shape demand concentration, with emergent indications commanding premium device allocation.
- Cardiogenic Shock:Refractory cases with multi-organ hypoperfusion drive the steepest expansion trajectory. Shock team protocol proliferation in United States health systems is embedding IABP earlier in treatment algorithms before mechanical circulatory support escalation.
- Acute Heart Failure:Decompensated presentations with hemodynamic instability represent a growing bridge-to-decision indication. European heart failure networks are integrating IABP into temporary mechanical support pathways pending definitive therapy selection.
- Cardiopulmonary Bypass:Post-surgical weaning from extracorporeal circulation remains a core utilization anchor.
- Myocardial Ischemia:Refractory angina unresponsive to medical therapy constitutes a stable but slower-growing application segment.
Cardiogenic shock dominates installed base. Acute heart failure is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA premarket notification pathways and Japan's PMDA quality system inspections are creating divergent market access conditions across major economies. Cardiac intervention infrastructure density and aging demographics determine procedural volume concentration.
United States
Tertiary hospital cardiac surgery departments sustain the highest IABP utilization rates through established perfusionist-staffed teams. FDA 510(k) clearance pathways govern balloon catheter durability and helium leak rate standards. The Cleveland Clinic and Mayo Clinic cardiac centers anchor device deployment in standardized hemodynamic support protocols.
Germany
European heart failure networks integrate IABP into temporary mechanical support pathways pending definitive therapy selection. EU MDR conformity assessment deadlines under Article 120 compress technical documentation requirements for legacy device renewals. The Rhine-Ruhr metropolitan region concentrates catheterization lab infrastructure and procurement committee decision-making.
Japan
PMDA parallel quality system inspections extend approval timelines but reward compliant manufacturers with protected market access and premium pricing corridors. METI industrial policy supports domestic medical device production scale. Tokyo and Osaka metropolitan medical centers drive counterpulsation algorithm adoption in shock team protocols.
China
NMPA medical device registration pathways are intensifying scrutiny of balloon fatigue failure modes for imported IABP systems. The country's national pharmaceutical regulator demands expanded clinical evidence packages for software-enabled consoles. Shanghai and Beijing tertiary hospitals are expanding cardiac surgery department infrastructure.
United Kingdom
NHS procurement frameworks prioritize vendors offering unified hemodynamic support ecosystems over single-product suppliers. MHRA post-market surveillance obligations align with EU MDR technical documentation standards. London and Manchester cardiac centers concentrate shock team protocol standardization.
Intra-Aortic Balloon Pump (IABP) Market Competitive Landscape
Listed leaders compete with private specialists across integrated critical care portfolios and proprietary sheath technologies. The vendor base concentrates around three manufacturers with established quality management systems and validated fatigue testing protocols. Strategic archetypes include integrated critical care portfolio bundlers, proprietary technology specialists, and manufacturing scale operators. Competitive moves center on M&A for portfolio diversification and strategic partnerships for telemetric remote monitoring integration.
Within the integrated portfolio tier, Getinge leverages its critical care ecosystem to sustain catheter and console placements across European catheterization labs. Teleflex anchors market position through proprietary technology and dedicated training programs. Medtronic competes on manufacturing scale with vertically assembled production lines supporting rapid fleet deployment. These three companies exemplify the strategic archetypes reshaping hospital value analysis committee preferences toward unified hemodynamic support vendors.
| Leading Market Players |
|---|
| Getinge |
| Teleflex |
| Abiomed |
| Medtronic |
| Abbott Laboratories |
| Boston Scientific |
| Terumo Corporation |
| Zeon Corporation |
| Tokai Medical Products |
| Others |
Supply & Pricing Matrix
Long-term maintenance contracts with bundled catheter supply lock in console fleet economics and stabilize recurring revenue visibility for manufacturers serving United States catheterization labs. These arrangements tie hospital purchasing committees to single-vendor ecosystems while insulating suppliers from spot-market volatility in polyurethane raw material costs.
Pricing Analysis
Certification level (FDA 510(k)-cleared versus CE-marked under EU MDR) creates the primary spread between premium and standard tiers. Console procurement follows capital equipment models with extended service agreements, while disposable balloon catheters command per-unit transactional pricing with volume discounts for multi-hospital systems. Price erosion runs through standard-tier mechanical consoles as notified body capacity constraints delay MDR renewals and compress margins for marginal suppliers. Academic medical centers exhibit lowest price sensitivity due to bundled critical care portfolio preferences, while community hospitals in emerging markets face acute budget constraints.
Supply Chain Analysis
Helium refining capacity concentration in the United States and Qatar shapes counterpulsation system deployment economics. Polyurethane resin supply draws from Germany and Japan, with radiopaque marker coextrusion technology concentrated among specialized compounders in the United States. Single-source vulnerability in helium transfer valve components exposes manufacturers to logistics disruption from Middle East transit routes. Distribution runs through dedicated medical device distributors with cold-chain capabilities for balloon catheter integrity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Validated fatigue testing protocols and perfusionist training infrastructure represent scarce capabilities that concentrate competitive advantage among established manufacturers with decades of clinical evidence accumulation.
For Market Incumbents: Consolidate quality management system investments to absorb EU MDR technical documentation burdens that marginalize smaller competitors. Expand backward integration into polyurethane membrane coextrusion to secure supply chain control over balloon catheter production. Defend against Impella micro-axial flow pumps by embedding IABP earlier in shock team protocols before hemodynamic support escalation decisions. For New Entrants and Emerging Players: Remote telemetry integration for predictive console maintenance represents an underserved service layer where established vendors lag software-native competitors. Target Japan's PMDA pathway for premium pricing corridors protected by parallel quality system inspection requirements. Pursue hospital information system partnerships as the primary go-to-market angle rather than direct console displacement. For Investors and Strategic Acquirers: Niche catheter technology specialists with validated helium leak rate testing protocols offer acquisition targets with defensible regulatory moats. Long-term viability hinges on shock team protocol standardization sustaining procedural volumes against percutaneous ventricular assist device substitution. Monitor FDA guidance publication on counterpulsation software validation as the inflection signal for development timeline compression.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Technical Documentation Renewal | Accelerated notified body audits under Article 120 filter marginal suppliers from CE-marked competition. |
| Helium Leak Rate Testing Protocol Investment | Validated fatigue failure mode analysis secures FDA 510(k) clearance pathways against regulatory backlog risks. |
| Hospital System Partnership Expansion | Integrated critical care portfolio bundling displaces standalone console procurement in United States catheterization labs. |
| Perfusionist Training Program Development | Dedicated counterpulsation expertise pipelines constrain device deployment in emerging markets without established cardiac centers. |
| Telemetric Remote Monitoring Integration | Console data stream connectivity with hospital information systems enables predictive maintenance and fleet optimization revenue. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA 510(k) filings, EU MDR notified body documentation, and hospital procurement database records. Clinical interviews with perfusionists, biomedical engineers, and catheterization lab directors informed utilization pattern assessment. GPO contracts and CMS Medicare reimbursement data provided procedural volume anchors. Bottom-up console installation counts triangulated against top-down manufacturer revenue disclosures.
Segmentation dimensions modeled include product type (mechanical console versus disposable catheter), technology tier (electromechanical platform versus control software), end-user department (cardiac surgery versus intensive care unit), and application indication (cardiogenic shock versus acute heart failure). CAGRs derived from installed base erosion rates and replacement cycle timing across the projection horizon. Shock team protocol proliferation rates and Impella substitution elasticity served as scenario-weighting inputs.
Underlying assumptions cover EU MDR notified body capacity recovery, helium supply chain stability, and shock team protocol standardization velocity, with deviation risk concentrated in regulatory backlog extensions and percutaneous ventricular assist device cardiac output improvements. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular Devices
Vena Cava Clips and Filters Market
Cardiovascular Devices
Cardiovascular Surgical Devices Market
Cardiovascular Devices
South Africa Cardiovascular Devices Market
Cardiovascular Devices
India Coronary Stent Market
Cardiovascular Devices
Continuous Blood Pressure Monitoring Devices Market
Cardiovascular Devices
Balloon Catheters Market
Cardiovascular Devices
Global Valvular Heart Disease Treatment Market
Cardiovascular Devices
Global Intracranial Stents Market
Cardiovascular Devices
Global Intravascular Temperature Management Market
Cardiovascular Devices
US Ventricular Assist Devices Market
Cardiovascular Devices
Peripheral Vascular Stents Market
Cardiovascular Devices
Dual Therapy Stent Market
Cardiovascular Devices
Cerebral Vascular Stent Market
Cardiovascular Devices
Global External Ventricular Drain Market
Cardiovascular Devices
Catheter-Directed Thrombolysis Market
Cardiovascular Devices
Mobile Stroke Unit (MSTU) Market