
 Fluid Aspiration System Market | 2026-2036
Fluid Aspiration System Market Size, Share, and Industry Trends Forecast 2026-2036
Fluid Aspiration System Market Analysis
ISO 13485 certification is reorganizing competitive access in fluid aspiration systems, forcing smaller manufacturers to absorb recurring audit costs or exit hospital supply chains entirely. B. Braun Melsungen leverages its vertically integrated sterilization infrastructure to sustain margin stability across European procurement tenders. Medtronic anchors North American demand through dedicated sales teams embedded in integrated delivery networks. Thermo Fisher Scientific differentiates via laboratory-grade contamination control protocols that extend into surgical fluid handling applications.
Fluid aspiration systems are electromechanical or vacuum-driven devices engineered to remove bodily fluids, surgical effluent, or wound exudate through controlled negative pressure, typically operating between 80 and 550 mmHg depending on clinical indication. Their primary purpose centers on maintaining sterile operative fields, preventing aspiration pneumonia, and enabling closed-wound drainage in postoperative and trauma settings. Electric aspirators dominate hospital capital budgets due to continuous-duty motor designs and integrated filtration, while battery-operated variants capture fastest growth in emergency medical services and field-deployed military medicine where mains power is unreliable. Vacuum technology segments retain the deepest installed base but face margin compression as digital control systems with pressure feedback loops command premium pricing in cardiovascular and neurosurgical suites.
The FDA enforces 21 CFR Part 820 quality system regulations for all commercially distributed aspiration devices, while the EU Medical Device Regulation requires notified body intervention for Class IIa and above fluid management products entering European markets. Japan's PMDA maintains distinct biological safety testing protocols that lengthen registration timelines for foreign manufacturers. Stakeholders must monitor convergence between EPA medical waste handling rules and state-level surgical fluid disposal mandates, as dual compliance obligations reshape total cost of ownership calculations and supplier qualification criteria.
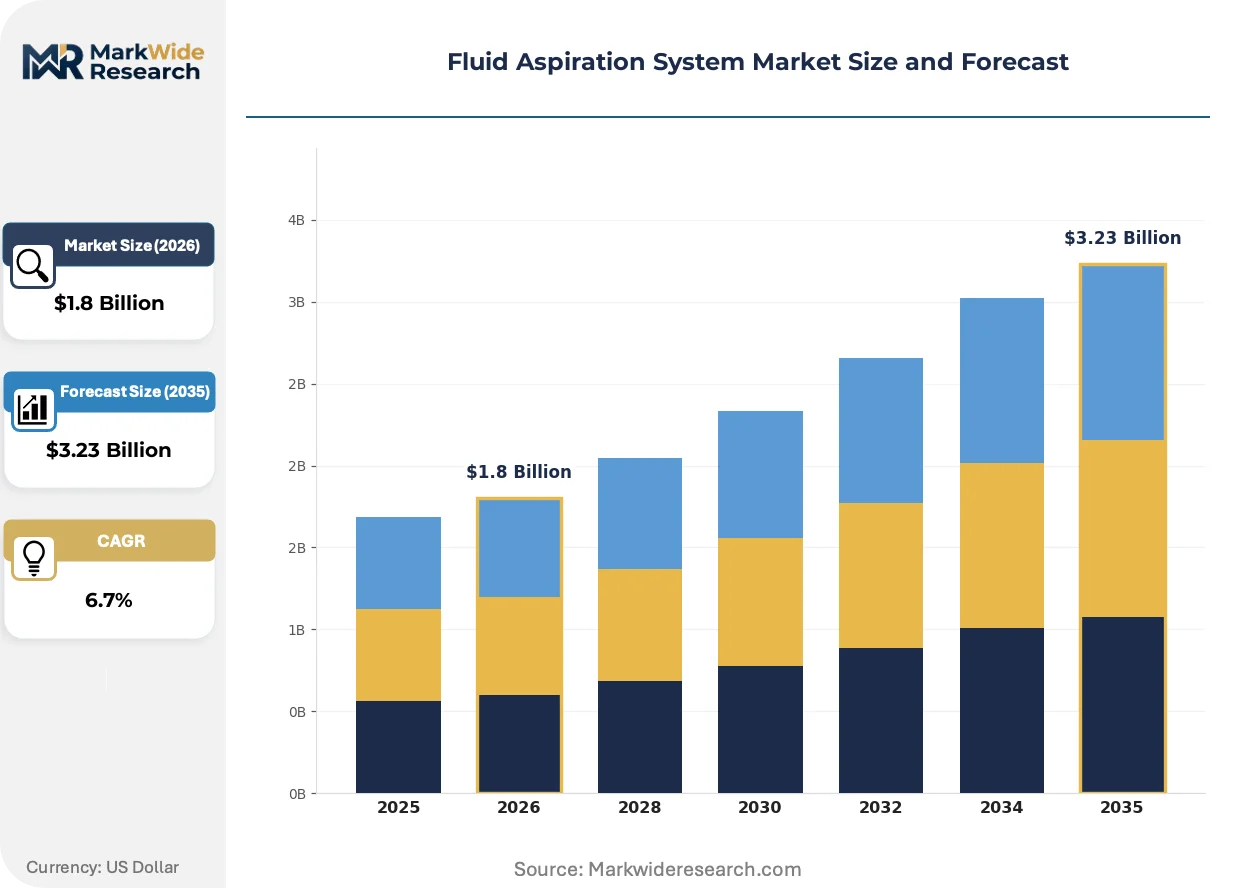
Market Dynamics
ISO 13485 certification requirements are forcing smaller manufacturers to absorb recurring audit costs or exit hospital supply chains entirely, while vacuum-based equipment replacement cycles in surgical suites accelerate demand for electromechanical platforms with integrated filtration.
Growth Catalysts
- Hospital Surgical Suite Modernization:Aging vacuum-based equipment replacement cycles are intensifying procurement of continuous-duty motor designs with digital pressure feedback loops in cardiovascular and neurosurgical settings.
- EU Medical Device Regulation:Notified body intervention requirements for Class IIa and above fluid management products are filtering out non-compliant suppliers and consolidating qualified vendor pools.
- Emergency Medical Services Expansion:Battery-operated variants are capturing fastest adoption in field-deployed military medicine and ambulance services where mains power remains unreliable.
Market Restraints
- Stainless Steel and Polymer Input Volatility:Electromechanical housing materials and medical-grade tubing polymers face price instability from energy-intensive production processes.
- German Sterilization Infrastructure Concentration:Vertically integrated sterilization capacity clusters in Central Europe create supply vulnerability for outsourced component manufacturers.
- Technical Limitation of Vacuum Technology Margins:Digital control systems with pressure feedback loops command premium pricing that compresses legacy vacuum platform profitability.
Strategic Opportunities
- Japanese PMDA Registration Tailwinds:Distinct biological safety testing protocols lengthen foreign manufacturer timelines but create first-mover advantage for compliant entrants in Tokyo and Osaka hospital networks.
- Laboratory-Grade Contamination Control Convergence:Surgical fluid handling applications are absorbing protocols from analytical instrumentation, opening cross-sector technology licensing.
- EPA-State Dual Compliance Services:Medical waste handling rules and surgical fluid disposal mandates are reshaping total cost of ownership calculations, creating bundled compliance service opportunities.
Industry Challenges
- ISO 13485 Certification Timeline Compression:Recurring audit costs and documentation requirements strain quality management staffing at mid-cap manufacturers.
- Legacy Vacuum System Integration Complexity:Digital control platform adoption requires retrofitting incompatible negative pressure infrastructure in older surgical suites.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fluid Aspiration System Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Aspirators, Electric Aspirators, Battery-Operated Aspirators, Wall-Mounted Aspirators End User: Hospitals, Clinics, Home Care Settings, Emergency Medical Services Application: Postoperative Care, Wound Management, Fluid Management, Cardiovascular Procedures Technology: Vacuum Technology, Pneumatic Technology, Electromechanical Technology, Digital Control Systems |
| Companies Covered | B. Braun Melsungen, Nordson Corporation, Medtronic, ICU Medical, Becton Dickinson, Stryker Corporation, Thermo Fisher Scientific, Integra LifeSciences, Baxter International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fluid Aspiration System Market Emerging Trajectories
Digital pressure feedback loops and closed-wound drainage protocols are actively displacing analog vacuum systems in sterile field maintenance, while regulatory convergence between waste handling and device quality standards reconfigures supplier qualification criteria.
Smart aspiration platforms with real-time pressure sensing and automated flow modulation are bifurcating the installed base between premium cardiovascular suites and cost-constrained general surgery wards. Integrated delivery networks in the United States are prioritizing these systems for continuous-duty applications. The technology is bifurcating procurement patterns into capital-intensive replacement cycles versus maintenance-driven upgrade paths.
Japan's PMDA biological safety testing protocols are extending registration timelines for foreign manufacturers while raising domestic production incentives. European notified bodies are aligning with these stricter evaluation frameworks under MDR convergence pressure. German and Swiss manufacturers with captive sterilization infrastructure are capturing accelerated approval pathways.
Service contract unbundling is separating equipment procurement from preventive maintenance and filter replacement scheduling. Ambulatory surgical centers are adopting this model fastest to convert capital expenditures into operational budgets. This pattern is most visible in United States outpatient networks where reimbursement compression favors predictable cost structures.
Fluid Aspiration System Market Segmentation
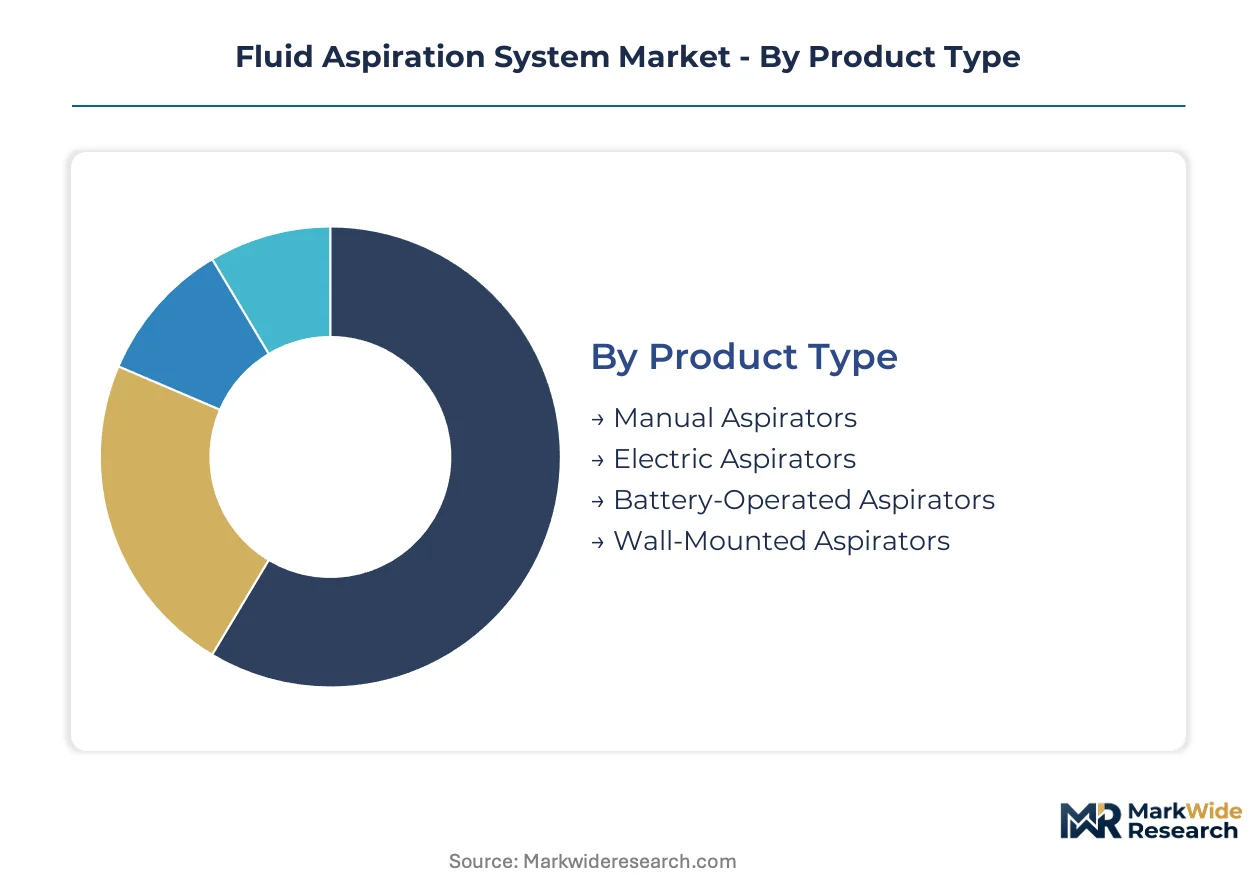
Segmentation in fluid aspiration systems reveals how procurement channels, clinical settings, and technology maturity create distinct competitive arenas. Each dimension carries implications for pricing power, regulatory burden, and replacement cycle timing.
Product Type:
Hospital capital budgets flow through group purchasing organizations for electromechanical platforms, while emergency services and home care channels favor portable variants with minimal installation requirements.
- Electric Aspirators:Continuous-duty motor designs with integrated filtration dominate cardiovascular and neurosurgical suites. Demand concentrates in Germany, Japan, and the United States where hospital procurement tenders prioritize 24/7 operational reliability and digital pressure feedback integration.
- Battery-Operated Aspirators:Lithium-ion powered units with 4-8 hour runtime specifications serve field-deployed military medicine and ambulance fleets. Expansion concentrates in emergency medical services where mains power remains unreliable and rapid deployment protocols override capital cost sensitivity.
- Manual Aspirators:Hand-powered negative pressure devices with 60-120 mmHg output range serve resource-constrained settings and backup scenarios.
- Wall-Mounted Aspirators:Fixed-installation vacuum systems with centralized suction infrastructure anchor older surgical suite configurations.
Electric aspirators dominate installed base. Battery-operated variants are where expansion concentrates most steeply.
End User:
Reimbursement compression across customer tiers is fragmenting procurement authority, with integrated delivery networks consolidating hospital purchasing while ambulatory sites seek operational expenditure models.
- Hospitals:Surgical suites and intensive care units drive replacement cycles for aging vacuum infrastructure. Demand concentrates in academic medical centers where FDA 21 CFR Part 820 compliance and ISO 13485 certification filter vendor pools aggressively.
- Emergency Medical Services:Ambulance fleets and air medical services prioritize battery-operated portability and rapid sterilization turnaround. Expansion concentrates in municipal and private EMS networks facing fleet standardization mandates.
- Clinics:Outpatient surgical centers and specialty practices balance capital constraints against procedure volume growth.
- Home Care Settings:Post-discharge wound drainage and palliative suction applications serve aging patient populations with caregiver-dependent operation.
Hospitals anchor procurement volume. Emergency medical services are climbing the fastest among customer tiers.
Application:
Procedure-specific suction requirements create performance tiering, with cardiovascular and neurological applications commanding premium specifications that general surgery cannot justify.
- Cardiovascular Procedures:Precise negative pressure control between 80-150 mmHg with real-time feedback loops prevents vessel collapse during bypass and valve procedures. Demand concentrates in tertiary cardiac centers where digital platform premiums are absorbed within bundled payment structures.
- Postoperative Care:Closed-wound drainage systems with graduated suction calibration manage seroma and hematoma prevention across general surgery recovery protocols. Expansion concentrates in enhanced recovery after surgery programs seeking reduced readmission rates.
- Wound Management:Negative pressure wound therapy integration requires aspiration systems with exudate volume monitoring and alarm capabilities.
- Fluid Management:Intraoperative suction of irrigation fluids and blood products maintains sterile fields across procedure types.
Postoperative care commands the deepest installed base. Cardiovascular procedures represent the steepest expansion trajectory for premium platform adoption.
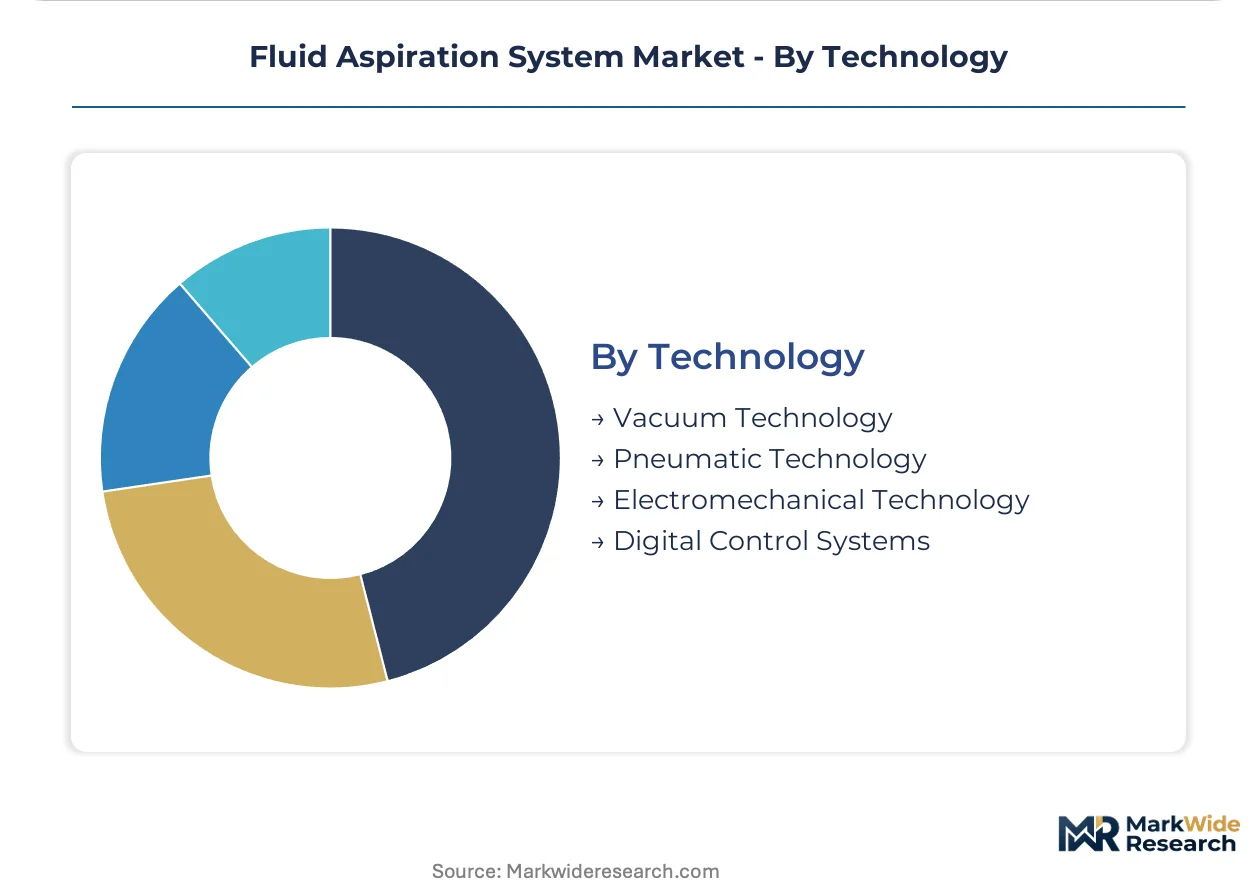
Technology:
Control system sophistication is bifurcating vendor competitiveness, with analog legacy platforms facing margin erosion as digital feedback systems capture specification-driven tenders.
- Digital Control Systems:Microprocessor-regulated pressure sensing with automated flow modulation enables procedure-specific suction profiles. Demand concentrates in Japanese and German hospital networks where PMDA and notified body requirements favor validated software-controlled platforms.
- Electromechanical Technology:Motor-driven piston or diaphragm pumps with mechanical pressure regulation serve continuous-duty applications. Expansion concentrates in mid-tier hospitals modernizing from vacuum infrastructure without absorbing full digital premium.
- Vacuum Technology:Centralized hospital suction systems with wall outlet distribution retain legacy infrastructure commitments.
- Pneumatic Technology:Compressed gas-driven aspiration serves specialized environments where electrical ignition risks constrain motor use.
Vacuum technology retains the broadest installed footprint. Digital control systems are gaining share fastest in new capital deployment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA 21 CFR Part 820 enforcement is accelerating validation timelines for new aspirator platforms in the United States. Germany's sterilization infrastructure concentration and Japan's PMDA biological safety protocols are reshaping procurement patterns across hospital networks.
United States
Academic medical centers in Boston and Houston are replacing aging vacuum infrastructure with digital pressure feedback systems. FDA quality system regulations filter vendor pools aggressively for Class IIa devices. The Southeast corridor from Atlanta to Tampa concentrates ambulatory surgical center procurement volume.
Germany
Vertically integrated sterilization capacity in Melsungen and Tuttlingen anchors European supply chains for electromechanical platforms. EU Medical Device Regulation notified body requirements for Class IIa products consolidate qualified vendor pools. The Baden-Württemberg medical technology cluster captures accelerated approval pathways.
Japan
Tokyo and Osaka hospital networks drive premium adoption of validated software-controlled aspiration platforms. PMDA biological safety testing protocols extend registration timelines for foreign manufacturers while raising domestic production incentives. The Kanto region concentrates tertiary cardiac center procurement.
United Kingdom
NHS procurement frameworks prioritize ISO 13485-certified suppliers for surgical suite modernization programs. MHRA convergence with EU MDR standards streamlines quality system documentation requirements. The Thames Valley medical technology corridor hosts sterilization service providers serving London hospital networks.
India
CDSCO medical device registration requirements are filtering import-dependent supply chains toward domestic manufacturing partnerships. Maharashtra and Karnataka state health procurement tenders favor cost-optimized battery-operated units for district hospital networks. The Hyderabad medical device cluster is developing electromechanical assembly capacity.
Fluid Aspiration System Market Vendor Landscape
Player mix skews toward diversified medical technology conglomerates with captive sterilization infrastructure and specialized fluid management divisions. Three archetypes dominate: vertically integrated European manufacturers with in-house sterilization assets, North American integrated delivery network specialists with embedded sales teams, and laboratory-grade contamination control crossovers from analytical instrumentation. Competitive moves concentrate on strategic partnerships for regulatory fast-tracking and geographic licensing agreements for digital control platform distribution.
Among diversified medical technology conglomerates, B. Braun Melsungen, Medtronic, and Thermo Fisher Scientific exemplify distinct strategic positioning. B. Braun Melsungen represents the vertically integrated archetype with German sterilization infrastructure. Medtronic anchors North American demand through integrated delivery network penetration. Thermo Fisher Scientific occupies a crossover position between laboratory-grade contamination protocols and surgical fluid handling applications.
| Leading Market Players |
|---|
| B. Braun Melsungen |
| Nordson Corporation |
| Medtronic |
| ICU Medical |
| Becton Dickinson |
| Stryker Corporation |
| Thermo Fisher Scientific |
| Integra LifeSciences |
| Baxter International |
| Others |
Supply Flow & Price Mechanics
Long-term capacity reservation agreements with German sterilization facilities lock in component access and price visibility for electromechanical aspirator manufacturers, insulating qualified vendors from spot-market volatility in medical-grade polymers while excluding smaller competitors lacking committed volume thresholds.
Pricing Analysis
Certification level (ISO 13485/FDA-grade) creates the primary spread across pricing tiers, with notified body-validated platforms commanding 40-60% premiums over uncertified alternatives in European hospital tenders. Three-tier pricing structure across premium, standard, and economy levels stratifies procurement: premium digital feedback systems serve cardiovascular suites, standard electromechanical units capture mid-tier hospital modernization, and economy vacuum-based equipment retains price-sensitive ambulatory markets. Cost compression in the economy tier is intensifying because Asian manufacturers are absorbing certification investments to qualify for NHS frameworks. Ambulatory surgical centers exhibit highest price sensitivity, deferring capital expenditure through unbundled service contracts.
Supply Chain Analysis
Port congestion at Hamburg and Rotterdam has elevated inbound logistics costs for stainless steel housings and medical-grade silicone tubing sourced from Chinese polymer processors. Manufacturing concentration centers on Germany, China, and the United States, with German facilities dominating sterilization infrastructure and Chinese plants feeding cost-optimized component streams. Electromechanical motor assemblies and filtration membranes draw from specialized suppliers in Japan and Switzerland. Single-source vulnerability concentrates in Central European sterilization capacity clusters. Distribution runs through group purchasing organizations in North America and direct hospital procurement tenders in Germany and Japan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity emerges as reimbursement compression fragments procurement authority, creating niches for specialized service providers between consolidated integrated delivery networks and cost-constrained ambulatory sites.
For Market Incumbents: Compound defensive positioning by deepening captive sterilization infrastructure in Germany and accelerating FDA 510(k) pathway investments to filter emerging competitors from North American hospital supply chains. Threat from battery-operated emergency medical specialists intensifies as municipal EMS fleets standardize procurement specifications. Certification investment remains the priority lever for margin defense. For New Entrants and Emerging Players: CE marking fast-track through German notified body partnerships opens accelerated European market entry for software-controlled aspiration platforms. White-space targets concentrate on Indian district hospital networks and Japanese home care settings, where regulatory complexity has delayed incumbent penetration. Go-to-market execution should emphasize operational expenditure models for ambulatory surgical centers seeking predictable cost structures. For Investors and Strategic Acquirers: Mid-cap sterilization service providers with ISO 13485 captive infrastructure represent the most defensible acquisition target archetype, given regulatory consolidation pressure and recurring revenue visibility. Long-term viability frames around 5-10 year regulatory convergence timelines. Signal to monitor: PMDA registration timeline compression for foreign manufacturers, which would accelerate domestic Japanese production incentives and reshape competitive positioning.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Acceleration | Faster clearance timelines capture hospital modernization cycles before competitors qualify. |
| CE Marking Pathway Investment | Notified body alignment with MDR requirements filters vendor pools and consolidates qualified supplier bases. |
| Hospital System Partnership | Embedded sales teams within integrated delivery networks anchor recurring procurement volume. |
| Software Companion Development | Digital pressure feedback integration commands premium positioning in cardiovascular and neurosurgical suites. |
| Reimbursement Strategy Alignment | Bundled payment structure compatibility ensures absorption of premium platform costs within cardiac procedure economics. |
Methodological Framework
A standing panel of hospital procurement directors, biomedical engineering managers, GPO contracts specialists, and regulatory affairs leads provided ongoing calibration against secondary validation from FDA 510(k) databases, EU MDR notified body registries, and hospital equipment procurement records. Bottom-up demand modeling triangulated with top-down market sizing across product type, end user, application, and technology segmentation dimensions.
Consistency checks validated volume and value outputs against external benchmarks including CMS Medicare expenditure data and Japanese medical device import statistics. The analytical framework modeled replacement cycle timing, regulatory approval pathway duration, and reimbursement structure evolution across the projection horizon. CAGRs derived from procedure volume growth correlations and capital expenditure elasticity estimates in academic medical center financial disclosures.
The analysis sits within stated boundaries; outcomes outside sustained FDA enforcement intensity or abrupt polymer supply disruptions would require recalibration. Forecasts reflect documented assumptions regarding hospital modernization cycle continuity and EU MDR notified body capacity expansion. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular Devices
Artificial Blood Vessels Market
Cardiovascular Devices
Japan Cardiovascular Devices Market
Cardiovascular Devices
Global Varicose Veins Treatment Market
Cardiovascular Devices
Spain Cardiovascular Devices Market
Cardiovascular Devices
Intravenous Catheters Market
Cardiovascular Devices
Global Pediatric Interventional Cardiology Market
Cardiovascular Devices
Transcatheter Heart Valve Market
Cardiovascular Devices
Epinephrine Auto-Injectors Market
Cardiovascular Devices
Cardiac Medical Device Market
Cardiovascular Devices
Global Abdominal Aortic Aneurysm Treatment Market
Cardiovascular Devices
Saphenous Vein Grafts Market
Cardiovascular Devices
Cardiac Implantable Electronic Device Market
Cardiovascular Devices
Global Coronary Stent Market
Cardiovascular Devices
Global Nitinol Medical Devices Market
Cardiovascular Devices
Infusion Catheters Market
Cardiovascular Devices
Ventricular Drainage Sets Market