
 Peripheral Intravenous Catheters Market | 2026-2036
Peripheral Intravenous Catheters Market Size, Share, and Industry Trends Forecast 2026-2036
Peripheral Intravenous Catheters Market Outlook
Aftermarket service revenue for catheter maintenance and vascular access consulting is reshaping how manufacturers capture lifetime value from hospital accounts. Becton Dickinson and Company leverages its integrated vascular access portfolio to bundle devices with clinical education programs. ICU Medical anchors its position through needle-free connector technology that reduces bloodstream infection risk. Terumo Corporation competes in Asia-Pacific through localized manufacturing of polyurethane-based catheters.
Peripheral intravenous catheters are short, flexible tubes inserted into superficial veins for temporary vascular access, typically manufactured from polyurethane or silicone and ranging from 14 to 24 gauge in diameter. These devices enable medication delivery, fluid resuscitation, and blood sampling in acute and ambulatory care settings. Over-the-Needle Catheters dominate procedural volume due to their ease of insertion and broad clinical utility across emergency and surgical workflows. Midline Catheters represent the fastest-growing product category as hospitals seek to reduce central line utilization for extended antibiotic therapy. Home Healthcare emerges as a concentrated demand node as payors shift infusion services away from institutional settings.
FDA 510(k) clearance pathways and ISO 10555 intravascular catheter standards govern device safety, biocompatibility, and sterility assurance across the United States and international markets. The EU MDR framework in Europe imposes strengthened clinical evidence requirements for Class IIa vascular access devices, extending certification timelines and consolidating supplier bases. Stakeholders must monitor evolving reimbursement policies for outpatient vascular access procedures and assess how safety-engineered device mandates in multiple jurisdictions will reshape manufacturing cost structures and competitive positioning.
Market Dynamics
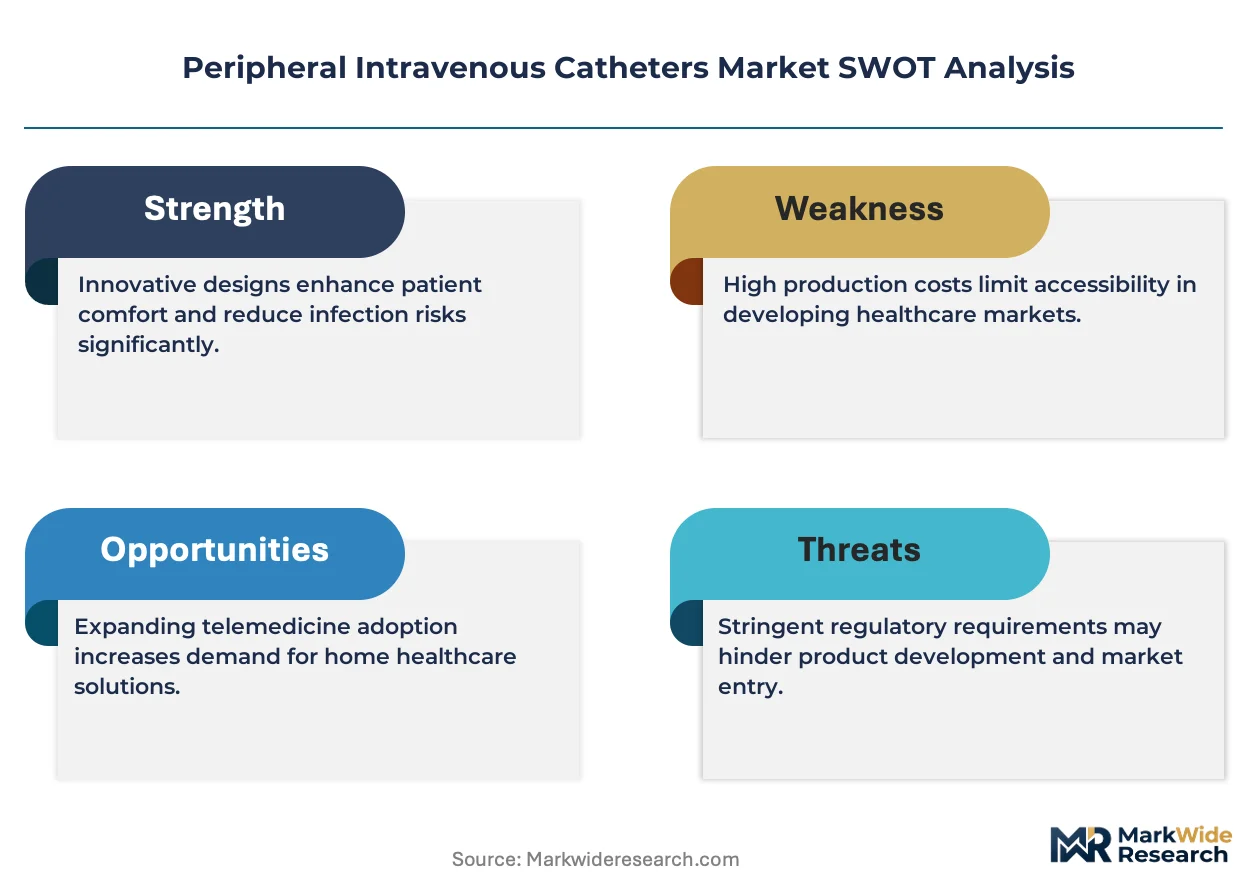
Safety-engineered device mandates across multiple jurisdictions are compressing legacy catheter margins while accelerating polyurethane-to-silicone material transitions among tier-one suppliers.
Growth Catalysts
- EU MDR clinical evidence requirements:Strengthened post-market surveillance obligations for Class IIa vascular access devices are consolidating supplier bases and elevating certified manufacturers above commodity competitors.
- Home healthcare infusion services:Payor-driven site-of-care migration from institutional to residential settings is expanding addressable catheter volume beyond acute care facilities.
- Polyurethane catheter technology:Advanced polymer formulations offering superior kink resistance and dwell time extension are displacing traditional Teflon-based alternatives in extended antibiotic therapy protocols.
Market Restraints
- Medical-grade polymer feedstock volatility:Polyether-based polyurethane resin prices fluctuate with propylene oxide supply chains concentrated in Gulf Coast petrochemical corridors.
- ISO 10555 sterility assurance compliance:Gamma irradiation validation and endotoxin testing protocols extend manufacturing cycle times and elevate batch rejection costs for mid-tier producers.
- Peripherally inserted central catheter substitution:PICC lines capture extended therapy cases exceeding 72 hours, compressing midline catheter addressable volume in oncology and infectious disease units.
Strategic Opportunities
- Ambulatory surgical center expansion in Germany:Outpatient procedure volume growth creates concentrated demand for single-use safety catheters with integrated needlestick prevention.
- Needle-free connector integration:Convergence of intravenous access devices with closed-system transfer technology opens premium pricing tiers in oncology pharmacy compounding workflows.
- FDA needlestick prevention guidance alignment:Manufacturers achieving 510(k) clearance under updated sharps injury reduction protocols secure preferred vendor status in US hospital group purchasing organizations.
Industry Challenges
- Vascular access specialist certification bottlenecks:INS-certified insertion specialists remain scarce relative to expanded midline catheter deployment targets, forcing reliance on generalist nursing staff.
- Legacy electronic health record integration:Smart catheter technologies with RFID tracking require API development against entrenched Cerner and Epic system architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Peripheral Intravenous Catheters Market |
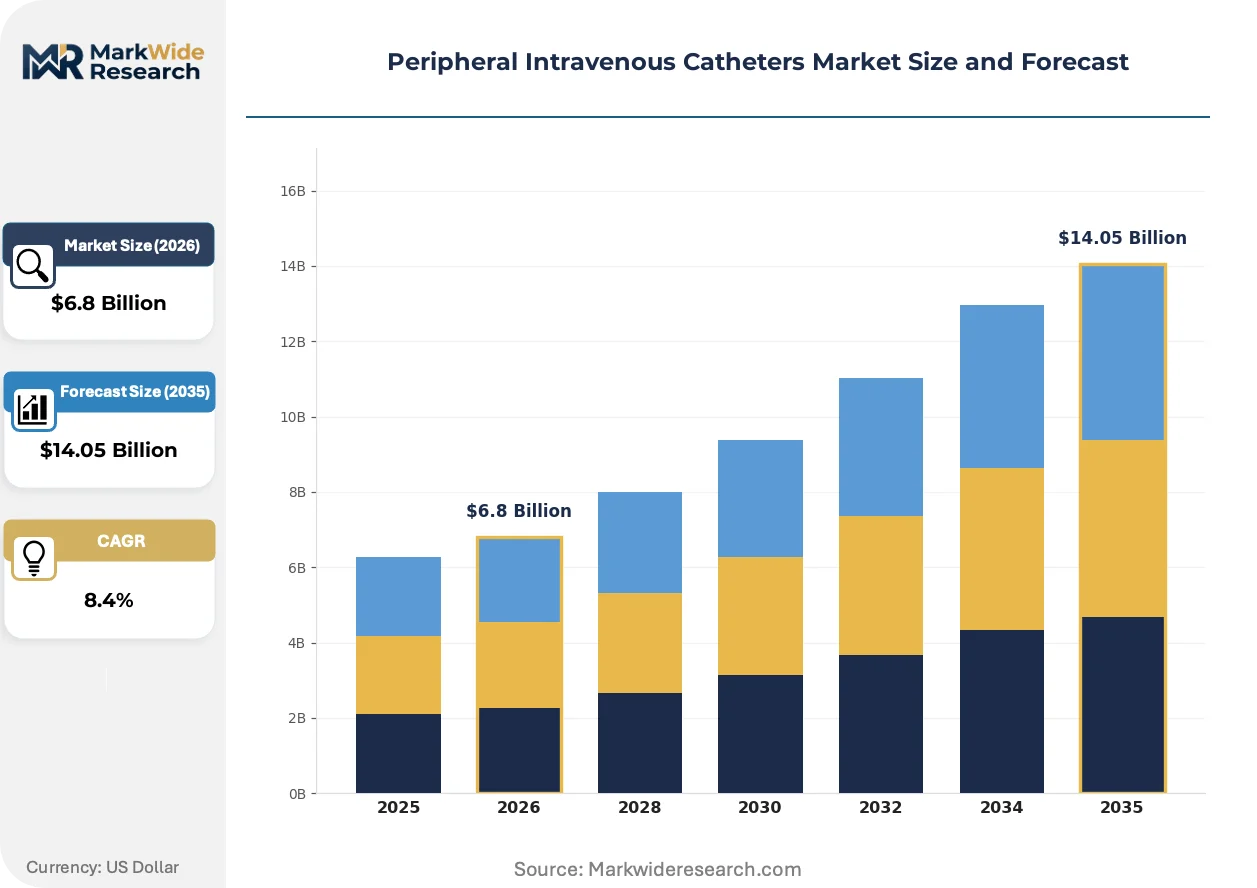
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.05 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Over-the-Needle Catheters, Intravenous Cannulas, Butterfly Needles, Midline Catheters End User: Hospitals, Outpatient Clinics, Home Healthcare, Emergency Services Material: Polyurethane, Silicone, Polyvinyl Chloride, Polyethylene Indication: Medication Administration, Blood Transfusion, Fluid Resuscitation, Nutritional Support |
| Companies Covered | Teleflex Incorporated, ICU Medical, Becton Dickinson and Company, Smiths Medical, Nipro Corporation, B. Braun Melsungen AG, Vygon SA, AngioDynamics, Terumo Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Peripheral Intravenous Catheters Market Strategic Shifts
Catheter technology is converging with closed-system drug transfer and real-time vascular monitoring, shifting competitive advantage from commodity manufacturing toward integrated clinical workflow solutions.
Polyurethane-silicone composite catheter construction is hybridizing material properties to achieve both kink resistance and biocompatibility in extended-dwell applications. Academic medical centers in the United States are piloting these dual-layer designs for chemotherapy protocols exceeding seven days. The technology is hybridizing previously separate midline and PICC categories, enabling manufacturers to capture extended therapy cases without central line placement.
EU MDR post-market clinical follow-up requirements are extending certification timelines for Class IIa vascular access devices from eighteen to thirty-six months. Small and mid-sized manufacturers face capital-intensive clinical evidence generation or exit from European markets. German hospital procurement consortia are responding by consolidating supplier panels to three preferred vendors with established MDR technical documentation.
Hospital purchasing cooperatives are unbundling device procurement from clinical education and vascular access consulting services. Group purchasing organizations now separately contract maintenance training and insertion competency programs from third-party clinical educators. This decoupling is most visible in United States integrated delivery networks seeking to optimize total cost of ownership across catheter lifecycles.
Peripheral Intravenous Catheters Market Segmentation
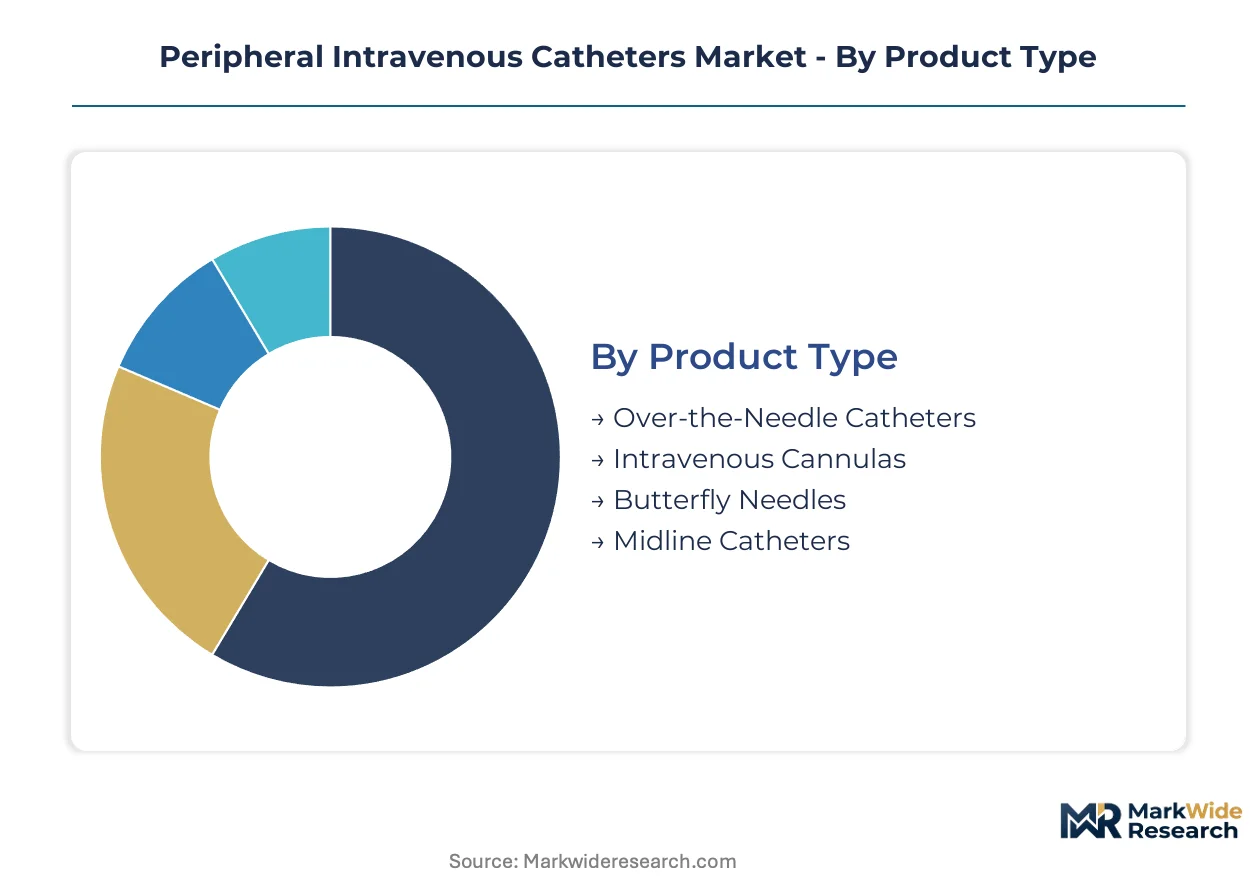
Catheter segmentation determines service revenue models and replacement cycle economics. Manufacturers align aftermarket programs to product durability profiles and end-user technical sophistication.
Product Type:
After-sales intensity varies sharply across insertion complexity tiers, with extended-dwell devices requiring vascular access specialist training and maintenance protocols.
- Over-the-Needle Catheters:These devices combine a hollow-bore needle with a retractable catheter sheath for rapid peripheral venous access. Emergency departments in the United States consume the highest procedural volumes, driven by trauma resuscitation protocols and rapid sequence intubation medication delivery requirements.
- Midline Catheters:Extended-length catheters terminating in the upper arm basilic or cephalic veins enable 2-4 week dwell times without central line placement. German ambulatory surgical centers are scaling midline deployment for outpatient parenteral antibiotic therapy, reducing central line-associated bloodstream infection risk.
- Intravenous Cannulas:Short, rigid tubes for brief vascular access in routine medication administration.
- Butterfly Needles:Winged infusion sets for small-vein access in pediatric and geriatric populations.
By volume, Over-the-Needle Catheters leads. By growth pace, Midline Catheters is ahead.
End User:
Customer procurement sophistication spans from centralized hospital supply chains to fragmented home healthcare reimbursement pathways.
- Hospitals:Acute care facilities negotiate multi-year group purchasing organization contracts bundling devices with insertion training and competency validation programs. FDA needlestick prevention guidance compliance shapes safety-engineered device specifications in United States integrated delivery networks.
- Home Healthcare:Residential infusion services demand catheters compatible with non-specialist caregiver maintenance and patient self-administration. China's expanding basic medical insurance coverage for home-based parenteral nutrition is accelerating catheter volume migration from institutional settings.
- Outpatient Clinics:Ambulatory procedure centers requiring rapid-turnover vascular access devices.
- Emergency Services:Pre-hospital and military medicine applications prioritizing insertion speed.
By installed base, Hospitals dominates. By expansion trajectory, Home Healthcare is climbing the fastest.
Material:
Polymer selection governs kink resistance, biocompatibility, and gamma sterilization compatibility.
- Polyurethane:Segmented polyether-urethane formulations deliver superior tensile strength and thromboresistance for extended-dwell applications. United States academic medical centers are adopting advanced polyurethane catheters for chemotherapy protocols exceeding seven days, displacing traditional Teflon alternatives.
- Silicone:Platinum-cured elastomer construction offers exceptional flexibility and reduced vein wall irritation for pediatric and long-term access. Japanese manufacturers are scaling silicone catheter production for aging population home infusion requirements.
- Polyvinyl Chloride:Cost-optimized formulation for short-duration, high-volume disposable applications.
- Polyethylene:Rigid polymer for specialized high-flow resuscitation scenarios.
By revenue concentration, Polyurethane leads. By technology transition momentum, Silicone is gaining share fastest.
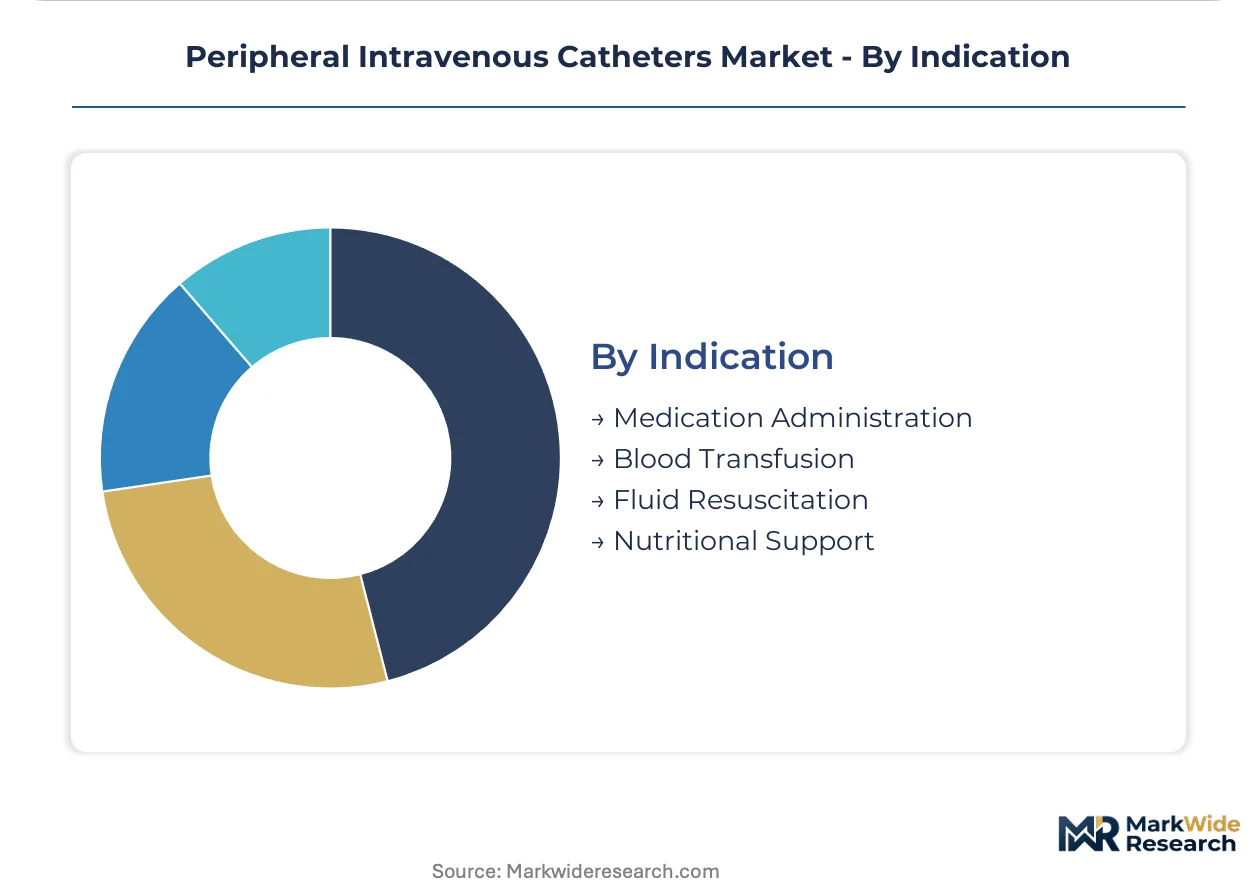
Indication:
Clinical use case determines catheter gauge, flow rate, and dwell time specifications.
- Medication Administration:Peripheral catheters enable intermittent and continuous drug delivery across antibiotic, analgesic, and antiemetic protocols. German hospital procurement consortia are standardizing safety-engineered catheters for all parenteral medication routes under EU MDR quality management requirements.
- Fluid Resuscitation:Large-bore catheter placement for rapid volume replacement in hemorrhagic shock and sepsis. Emergency services in the United States specify 14-16 gauge polyurethane catheters for pre-hospital trauma protocols.
- Blood Transfusion:Specialized large-lumen devices for erythrocyte and platelet infusion.
- Nutritional Support:Peripheral parenteral nutrition delivery requiring extended-dwell compatibility.
By procedure frequency, Medication Administration leads. By protocol expansion, Fluid Resuscitation shows the steepest trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across geographies. United States hospital purchasing cooperatives negotiate aggressively on safety-engineered device premiums, while Chinese provincial health authorities prioritize volume procurement over feature differentiation. German ambulatory surgical centers occupy the middle ground, balancing total cost of ownership against EU MDR compliance requirements.
United States
Integrated delivery networks drive concentrated demand for midline catheters supporting extended antibiotic protocols. FDA 510(k) clearance pathways for needlestick prevention devices shape procurement specifications in group purchasing organization contracts. Academic medical centers in Boston and the Research Triangle pilot polyurethane-silicone composite constructions for chemotherapy applications exceeding seven days.
Germany
Ambulatory surgical center expansion creates procurement volume for single-use safety catheters with integrated sharps protection. EU MDR technical documentation requirements for Class IIa vascular access devices consolidate supplier panels to three preferred vendors. Hospital procurement consortia in North Rhine-Westphalia standardize safety-engineered specifications across parenteral medication routes.
China
Basic medical insurance coverage expansion for home-based parenteral nutrition accelerates catheter volume migration from hospitals to residential settings. NMPA registration pathways for imported polyurethane catheters impose biocompatibility testing timelines that favor domestic manufacturers. Yangtze River Delta medical device clusters scale silicone catheter production for aging population infusion requirements.
Japan
Platinum-cured silicone catheter adoption rises for pediatric and geriatric long-term vascular access. PMDA quality management system inspections for foreign manufacturers extend market entry timelines for mid-tier suppliers. Osaka-based medical device distributors build specialized logistics networks for home healthcare infusion services.
India
CDSCO medical device rules implementation creates regulatory clarity for safety-engineered catheter imports while elevating compliance costs for local assemblers. Maharashtra and Gujarat hospital chains expand midline catheter deployment for outpatient parenteral antibiotic therapy. Government medical college hospitals in Delhi-NCR serve as clinical evaluation sites for extended-dwell polyurethane devices.
Peripheral Intravenous Catheters Market Competitive Environment
Capability concentration sits with integrated vascular access specialists; scale advantage sits with diversified medical device conglomerates. The market structure divides between premium-tier suppliers with MDR-certified technical documentation and commodity manufacturers serving price-sensitive procurement channels. Three archetypes dominate: integrated portfolio holders bundling devices with clinical education, material science specialists controlling polymer formulations, and regional fabricators leveraging proximity to hospital procurement networks. Competitive moves center on MDR certification timeline acceleration and backward integration into medical-grade polymer resin supply.
Among diversified medical technology conglomerates, Becton Dickinson and Company and Terumo Corporation occupy positions exemplifying integrated vascular access portfolio strategies. ICU Medical represents the specialized tier focused on needle-free connector convergence with peripheral catheter systems. B. Braun Melsungen AG anchors the European manufacturing archetype with established MDR technical documentation capabilities. These three named entities collectively illustrate how competitive positioning stratifies across bundled service models, material specialization, and regulatory certification depth.
| Leading Market Players |
|---|
| Teleflex Incorporated |
| ICU Medical |
| Becton Dickinson and Company |
| Smiths Medical |
| Nipro Corporation |
| B. Braun Melsungen AG |
| Vygon SA |
| AngioDynamics |
| Terumo Corporation |
| Others |
Value Chain & Pricing Dynamics
Polyether-based polyurethane resin production concentrates in Gulf Coast petrochemical corridors, tethering mid-tier catheter manufacturers to volatile propylene oxide pricing while tier-one suppliers capture margin pools through backward integration into medical-grade polymer formulation.
Pricing Analysis
After-sales service revenue from catheter maintenance programs and vascular access consulting drives lifetime value capture beyond device procurement. Pricing stratifies across premium, standard, and economy tiers based on EU MDR certification status and bundled clinical education offerings. Cost compression in standard-tier safety-engineered devices is intensifying because German hospital procurement consortia are consolidating supplier panels to three preferred vendors. Home healthcare channels exhibit highest price sensitivity due to fragmented reimbursement pathways, while United States integrated delivery networks prioritize total cost of ownership over per-unit acquisition cost.
Supply Chain Analysis
Tariff exposure between United States and China dominates supply chain risk planning for polyurethane catheter manufacturers serving North American markets. Medical-grade polymer feedstock draws from Germany, United States, and Japan, with segmented polyether-urethane resin and platinum-cured silicone elastomer serving as critical inputs. Single-source vulnerability in gamma irradiation sterilization capacity creates bottlenecks for mid-tier producers seeking ISO 10555 compliance. Distribution runs through hospital group purchasing organizations in acute care markets and specialized home healthcare distributors in residential infusion channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market is recovering from regulatory compression as EU MDR certification timelines extend and safety-engineered device mandates accelerate replacement cycles across institutional procurement channels.
For Market Incumbents: Insulate market position by accelerating MDR technical documentation completion ahead of competitor exits, and deepen backward integration into medical-grade polyurethane resin supply to offset feedstock volatility. PICC line substitution for extended therapy cases exceeding 72 hours threatens midline catheter volume in oncology units, making vascular access specialist certification programs a critical defensive lever.
For New Entrants and Emerging Players: China's expanding basic medical insurance coverage for home-based parenteral nutrition represents the most penetrable demand node, with residential infusion services lacking established supplier relationships. Target third-party clinical education partnerships as the go-to-market angle, decoupling device procurement from competency training to bypass entrenched GPO contracts.
For Investors and Strategic Acquirers: Capital is best deployed toward material science specialists controlling proprietary polyurethane-silicone composite formulations and established MDR-certified technical documentation. Long-term viability hinges on convergence with closed-system drug transfer technology and real-time vascular monitoring capabilities. Watch for FDA 510(k) clearance acceleration under updated needlestick prevention guidance as the inflection signal for preferred vendor status shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Certification Acceleration | MDR technical documentation completion elevates manufacturers above commodity competitors facing exit pressures. |
| Backward Integration into Polymer Supply | Captive medical-grade polyurethane resin production insulates margins from Gulf Coast propylene oxide volatility. |
| Needle-Free Connector Convergence | Closed-system transfer technology integration opens premium pricing tiers in oncology pharmacy compounding workflows. |
| Home Healthcare Distribution Partnership | Specialized logistics networks for residential infusion services capture volume migration from institutional settings. |
| Vascular Access Specialist Certification Programs | INS-certified training programs defend midline catheter deployment against PICC substitution in extended therapy protocols. |
Study Parameters
The analysis maps safety-engineered catheter technology tiers, material science specialization levels, and service revenue intensity, each validated through hospital procurement managers, biomedical engineers, GPO contracts managers, and vascular access specialists. Primary interview insights triangulate against FDA 510(k) clearance databases, EU MDR technical documentation registries, hospital procurement databases, and CMS Medicare reimbursement filings. Bottom-up catheter volume modeling reconciles with top-down market sizing across polyurethane and silicone material segments.
Assumptions held fixed include EU MDR certification timeline extension from eighteen to thirty-six months and continued payor-driven site-of-care migration toward residential infusion settings. The projection framework segments by product type, end user, material composition, and indication, with CAGRs derived from procedural volume trajectories and average selling price evolution across safety-engineered and conventional device tiers. Modeled inputs incorporate ambulatory surgical center expansion rates and home healthcare reimbursement pathway development.
The forecast holds incumbent behavior within observed patterns; aggressive backward integration moves by diversified medical technology conglomerates would shift outcomes through accelerated margin compression. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular Devices
Arteriovenous (Av) Fistula Needle Market
Cardiovascular Devices
Perfusion Market
Cardiovascular Devices
Global Intracranial Stents Market
Cardiovascular Devices
Umbilical Vessel Catheters Market
Cardiovascular Devices
Medical Devices Cuffs Market
Cardiovascular Devices
Global Vascular Injury Treatment Market
Cardiovascular Devices
Atherosclerotic Renovascular Treatment Market
Cardiovascular Devices
Transcatheter Heart Valve Market
Cardiovascular Devices
Pulmonary Stents Market
Cardiovascular Devices
Implantable Drug Infusion Pumps Market
Cardiovascular Devices
Cardiovascular and Soft Tissue Repair Patches Market
Cardiovascular Devices
Radiofrequency Balloon Catheter Market
Cardiovascular Devices
Europe Vascular Access Device Market
Cardiovascular Devices
Mobile Stroke Unit (MSTU) Market
Cardiovascular Devices
Intracardiac Echocardiography (ICE) and Intravascular Ultrasound (IVUS) Market
Cardiovascular Devices
Point-Of-Care Cholesterol Monitoring Device Market