
 Global Intravascular Catheters Market | 2026-2036
Global Intravascular Catheters Market Size, Share, and Industry Trends Forecast 2026-2036
Global Intravascular Catheters Market Intelligence
Ireland's expanding medical device manufacturing footprint is tilting the European supply base for specialized catheters. Becton, Dickinson and Company (BD) leverages its extensive distribution network and scale to maintain a dominant market position. Medtronic plc focuses on integrating its catheter products with its broader portfolio of cardiac and vascular therapies. Terumo Corporation differentiates through its expertise in hydrophilic coating technologies, enhancing catheter performance and patient comfort.
An intravascular catheter is a thin, flexible tube inserted into a vein or artery to administer fluids, medications, or to perform diagnostic measurements. These devices are typically constructed from biocompatible materials like polyurethane or silicone and are designed for short-term or long-term vascular access. Central Venous Catheters command a significant share due to their necessity in critical care and complex surgeries. The segment for catheters with antimicrobial coatings is expanding rapidly, driven by hospital initiatives to prevent healthcare-associated infections.
Market access is governed by stringent regulatory frameworks, including the FDA's 510(k) clearance process in the United States and the EU's Medical Device Regulation (MDR). These bodies, along with China's NMPA, mandate rigorous testing for material biocompatibility, sterility, and functional performance to ensure patient safety. A key decision for healthcare providers involves balancing the upfront cost of advanced antimicrobial-coated catheters against the long-term clinical benefit of reduced infection rates.
Market Dynamics
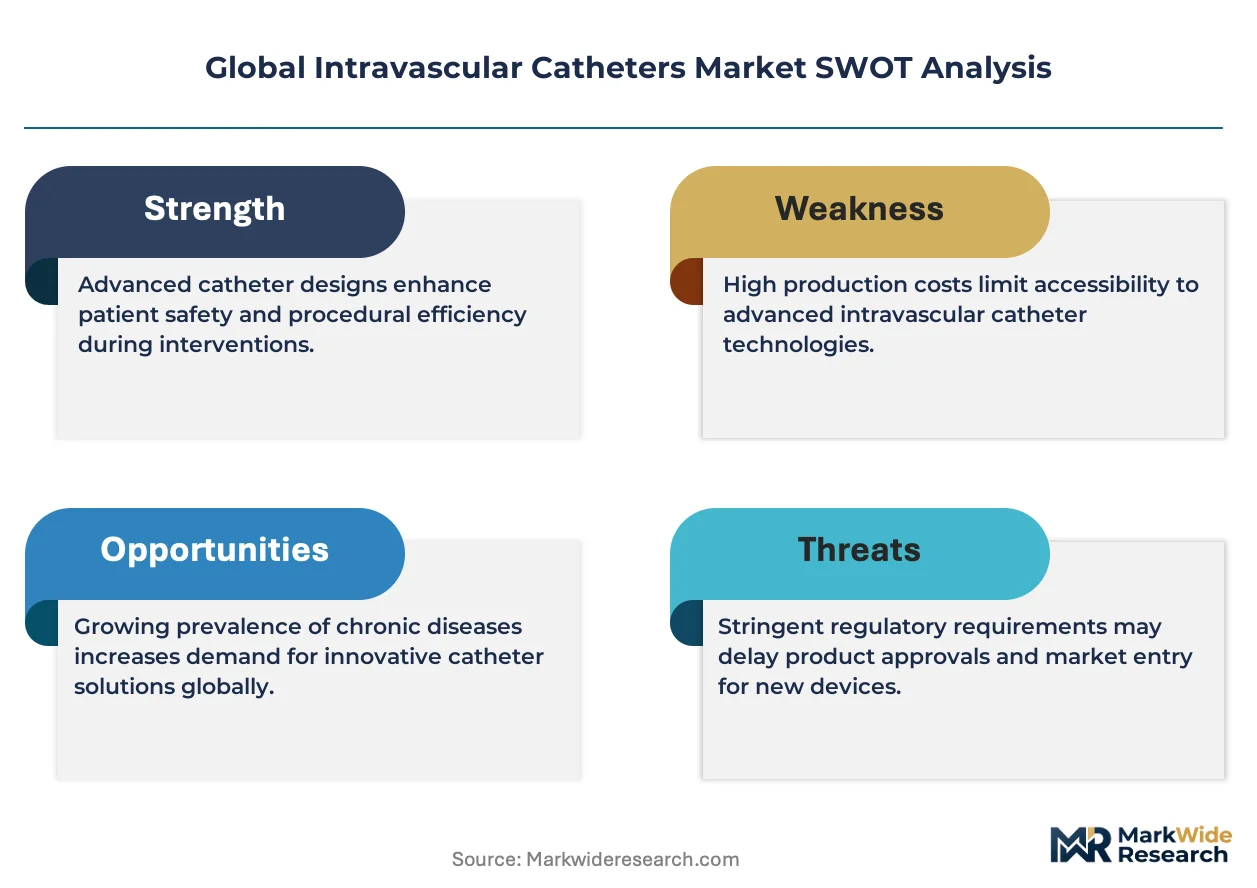
The market's central dynamic is the conflict between rising clinical demand for advanced, infection-resistant catheters and the intense cost-containment pressure within global healthcare systems. This forces providers to quantify the long-term value of preventing infections against higher upfront device costs.
Growth Catalysts
- Chronic Disease Prevalence:The increasing incidence of cardiovascular diseases and cancer globally elevates the need for central venous catheters for long-term chemotherapy, parenteral nutrition, and hemodynamic monitoring in critical care settings.
- Infection Prevention Initiatives:Mandates from hospital accreditation bodies and public health organizations to reduce catheter-related bloodstream infections (CRBSIs) drive the adoption of catheters with antimicrobial and antithrombogenic coatings.
- Healthcare Infrastructure Expansion:Significant government and private investment in expanding hospital and clinic capacity, particularly in China and India, creates new demand for a wide range of vascular access devices.
Market Restraints
- High Cost of Advanced Catheters:The premium pricing for catheters featuring antimicrobial coatings or advanced sensor technology can be prohibitive for healthcare facilities in emerging economies or those operating under strict budget constraints.
- Stringent Regulatory Hurdles:The EU's Medical Device Regulation (MDR) imposes extensive clinical data and post-market surveillance requirements, increasing the cost and time required to bring new catheter innovations to market.
- Risk of Complications:Despite advances, potential complications such as thrombosis, infection, and mechanical failure remain, necessitating skilled clinical staff for insertion and maintenance and carrying risks of litigation.
Strategic Opportunities
- Sensor-Integrated Catheters:Integrating micro-sensors for real-time monitoring of physiological parameters like blood pressure or oxygen saturation offers a path to higher-value, data-driven applications in intensive care.
- Biodegradable Materials:Developing catheters from biodegradable polymers for short-term use presents an opportunity to address environmental concerns associated with medical waste and appeal to sustainability-focused healthcare providers.
- Home Infusion Market:The expansion of home-based care creates an opportunity for developing user-friendly, long-term catheters designed for safe management by patients or home healthcare nurses, away from a hospital setting.
Industry Challenges
- Specialized Clinician Training:The effective use of specialized catheters, such as peripherally inserted central catheters (PICCs), depends on the availability of trained nursing staff, creating a bottleneck in facilities facing skill shortages.
- Sterilization Compatibility:Ensuring that advanced materials and electronic components in smart catheters can withstand standard sterilization methods like ethylene oxide (EtO) or gamma irradiation without degradation is a significant technical hurdle.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Intravascular Catheters Market |
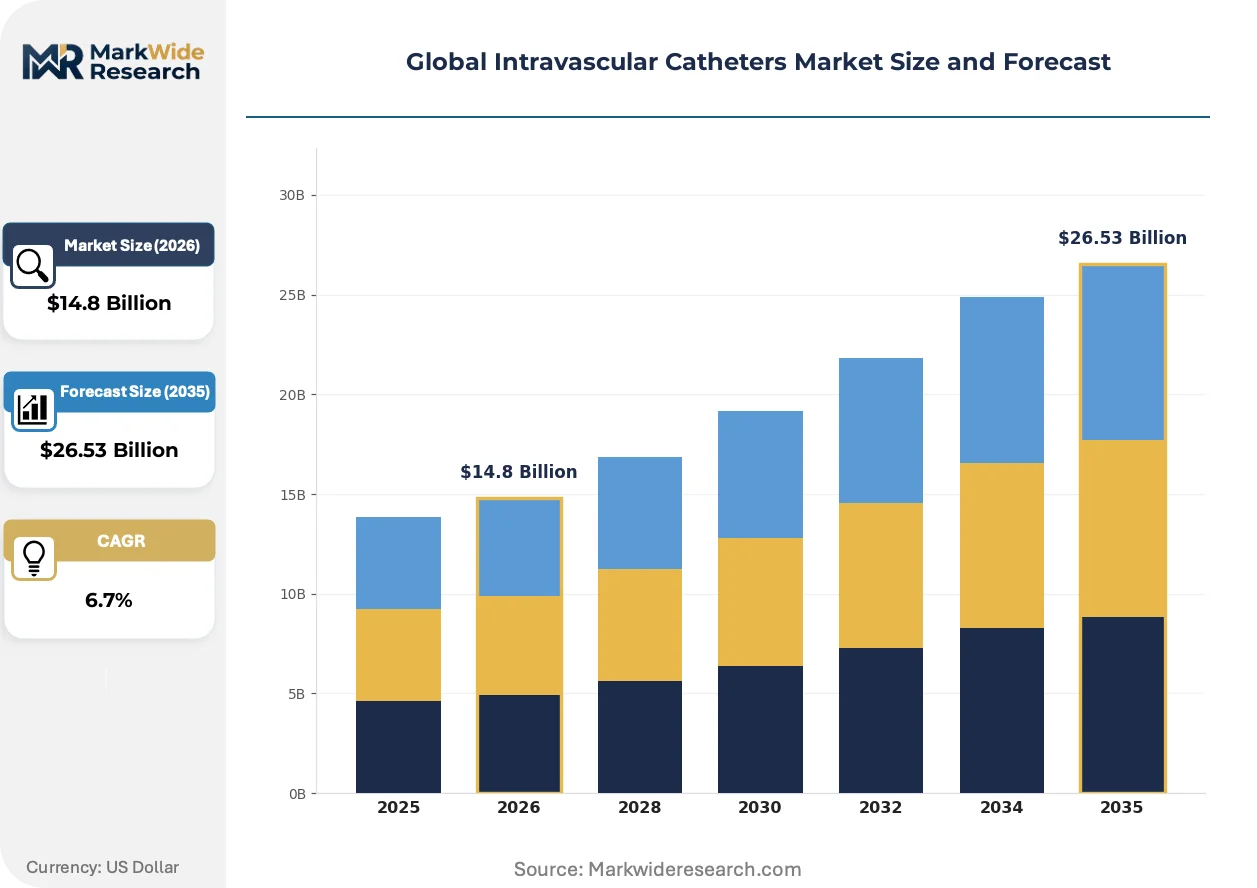
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $26.53 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Central Venous Catheters, Peripheral Intravenous Catheters, Arterial Catheters, Hemodialysis Catheters, Swan-Ganz Catheters Application: Cardiac Monitoring, Chemotherapy Delivery, Fluid Management, Blood Sampling, Dialysis Therapy, Anesthesia Administration End User: Hospitals, Specialty Clinics, Ambulatory Surgical Centers, Diagnostic Laboratories, Home Healthcare Providers Technology: Silicone, Polyurethane, Teflon, Nitinol, Hydrophilic Coating, Antimicrobial Coating |
| Companies Covered | Becton, Dickinson and Company (BD), Boston Scientific Corporation, Medtronic plc, Teleflex Incorporated, Terumo Corporation, Abbott Laboratories, Cook Medical, B. Braun Melsungen AG, Edwards Lifesciences Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Intravascular Catheters Market Strategic Shifts & Innovations
Product evolution is defined by the incorporation of active technologies that transform catheters from passive conduits into diagnostic and preventative tools. This shift is driven by a clinical need to improve patient outcomes and reduce the total cost of care associated with complications.
Smart catheters embedded with micro-fabricate sensors are designed to provide continuous, real-time data on parameters like blood flow and pressure. Critical care and interventional cardiology departments are the primary adopters, seeking to improve patient monitoring accuracy. This convergence of microelectronics and biocompatible polymers is digitizing the intravascular catheter from a simple fluid delivery device into an active data-gathering platform for clinical decision support.
The European Union’s Medical Device Regulation (MDR) has intensified requirements for clinical evidence and lifecycle management. This forces manufacturers to generate more robust data to support claims of improved safety or performance, particularly for devices with novel features. The antimicrobial-coated catheter segment is heavily impacted, as companies must now conduct more rigorous post-market studies to validate infection-reduction claims within the EU market.
A notable behavioral change is occurring in how hospital systems evaluate device efficacy. Large Group Purchasing Organizations (GPOs) and integrated delivery networks are increasingly analyzing the total cost of an episode of care, not just the unit price of the catheter. This model, which accounts for the expense of treating complications like bloodstream infections, is most visible in the United States and favors catheters with proven clinical benefits.
Global Intravascular Catheters Market Segmentation
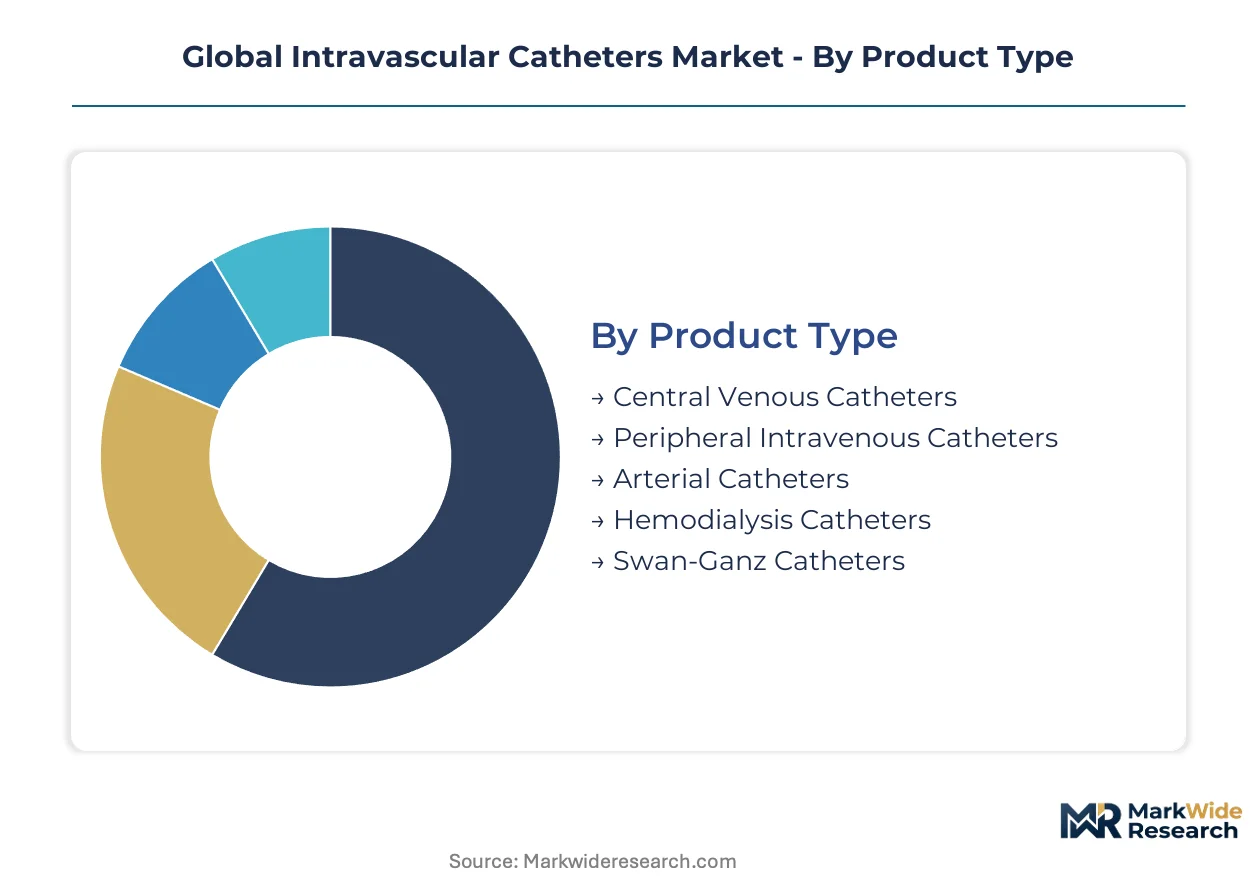
The intravascular catheters market exhibits diverse segmentation, reflecting varied clinical needs and technological advancements. Understanding these distinct segments is crucial for manufacturers to tailor product development and for healthcare providers to optimize procurement strategies. This detailed analysis highlights the specific characteristics and demand drivers across key market categories.
Product Type:
The intensity of after-sales service and ongoing clinical support significantly influences procurement decisions within the product type segment, given the critical nature of these devices.
- Central Venous Catheters:Providing long-term vascular access for critical care, chemotherapy, and parenteral nutrition, demand is high in hospitals across China and India due to expanding critical care infrastructure.
- Peripheral Intravenous Catheters:Used for short-term fluid and medication delivery, these common vascular access devices see procurement driven by high-volume usage in general hospital wards in the United States and Europe.
- Arterial Catheters:Used for continuous blood pressure monitoring and arterial blood gas sampling in intensive care units.
- Hemodialysis Catheters:Specialized for renal dialysis patients, requiring robust designs for repeated access and high flow rates.
- Swan-Ganz Catheters:Employed for advanced hemodynamic monitoring in critical care, providing detailed cardiac function data.
Central Venous Catheters hold the largest share due to their necessity in critical care; momentum sits with Peripheral Intravenous Catheters given their widespread, high-volume application.
Application:
Specific clinical applications dictate the required technological sophistication and performance characteristics of intravascular catheters.
- Chemotherapy Delivery:These catheters facilitate long-term, repeated access for cancer treatment, demanding biocompatibility and infection resistance. Demand concentrates in oncology centers globally, driven by increasing cancer incidence.
- Cardiac Monitoring:Catheters for cardiac monitoring integrate sensors to provide real-time physiological data, crucial for diagnosing and managing cardiovascular conditions. Hospitals in developed economies, particularly the United States and Germany, are primary adopters.
- Fluid Management:This application involves intravenous fluid administration to maintain hydration or deliver medications.
- Blood Sampling:Catheters enable efficient, less traumatic collection of blood samples for diagnostic testing.
- Dialysis Therapy:Specialized catheters are essential for connecting patients to hemodialysis machines for renal replacement therapy.
- Anesthesia Administration:Catheters deliver anesthetic agents directly into the bloodstream during surgical procedures.
This segment is primarily defined by the critical need for Chemotherapy Delivery, while Cardiac Monitoring continues to expand with sensor integration.
End User:
The diverse range of end-users reflects distinct operational requirements and patient care models influencing catheter selection.
- Hospitals:Hospitals represent the largest end-user segment, utilizing a full spectrum of intravascular catheters across various departments. Demand is high in large urban hospitals in the United States and Europe.
- Home Healthcare Providers:This segment expands as patient care shifts towards outpatient and home-based settings, requiring user-friendly and safe catheters for self-administration or nurse-assisted care. The United States and Canada are seeing significant growth.
- Specialty Clinics:These facilities, such as oncology or cardiology clinics, utilize catheters for specific diagnostic and therapeutic procedures.
- Ambulatory Surgical Centers:Catheters are employed in these centers for short-stay surgical procedures requiring temporary vascular access.
- Diagnostic Laboratories:Some diagnostic procedures require catheter access for specialized sample collection.
Hospitals constitute the foundational demand base, with home healthcare providers representing significant future expansion opportunities.
Technology:
The maturity level of catheter technologies, from established materials to advanced coatings, drives innovation and market differentiation.
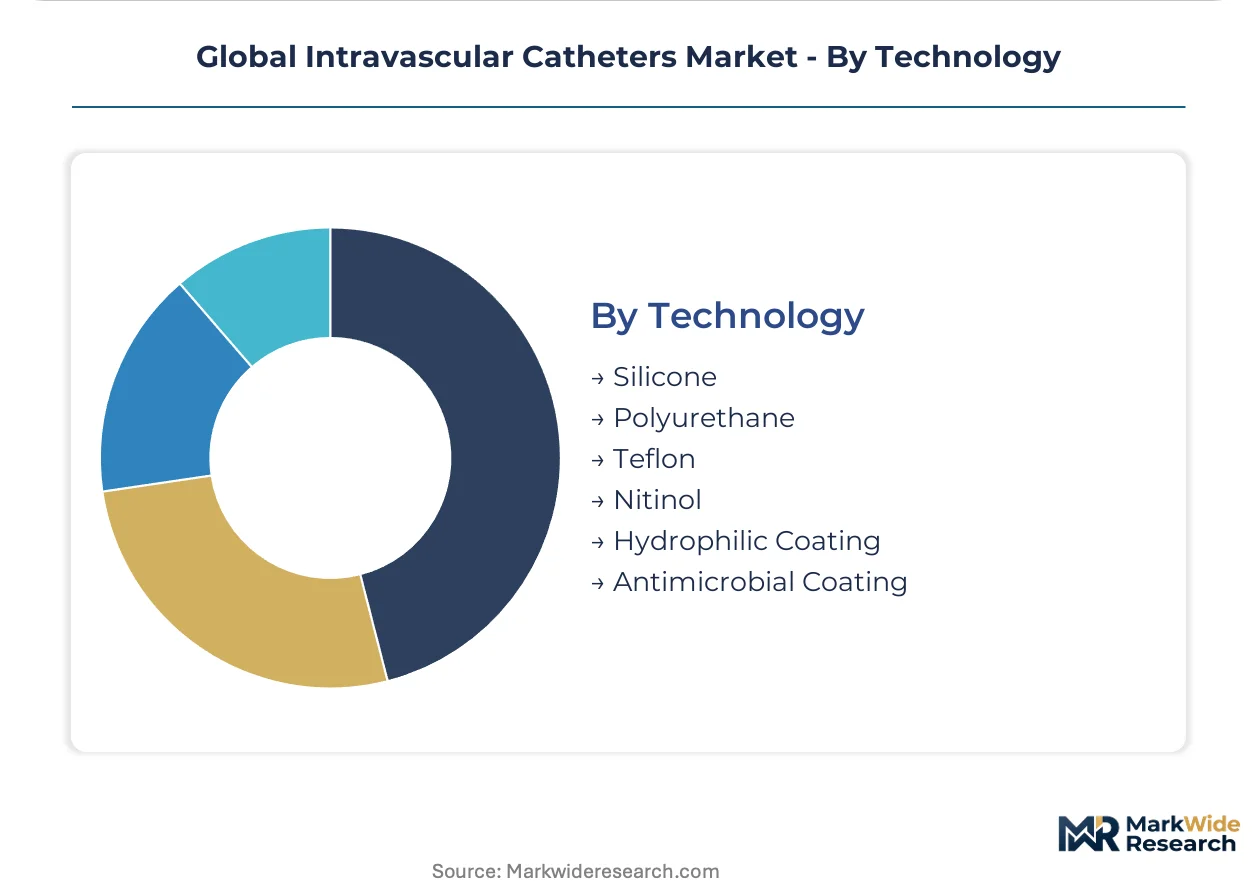
- Antimicrobial Coating:These advanced coatings reduce the risk of catheter-related bloodstream infections, significantly improving patient safety and reducing healthcare costs. Adoption accelerates in hospitals globally, driven by infection prevention initiatives and regulatory mandates.
- Hydrophilic Coating:Applied to the catheter surface, these coatings reduce friction during insertion and enhance patient comfort, improving procedural success rates. Interventional cardiology and radiology procedures are primary areas of demand, particularly in Japan and Germany.
- Silicone:A widely used biocompatible material, silicone offers flexibility and is suitable for long-term catheter implantation.
- Polyurethane:This material provides a good balance of flexibility and strength, commonly used in various catheter types.
- Teflon:Known for its low friction and chemical inertness, Teflon is often used in peripheral intravenous catheters.
- Nitinol:This superelastic alloy is employed in guidewires and some catheter components for its shape memory properties.
Antimicrobial coatings exhibit the steepest expansion trajectory, driven by hospital infection prevention mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global network of advanced healthcare infrastructure underwrites regional demand for intravascular catheters. This network facilitates specialized medical procedures and continuous patient monitoring. Key markets exhibit distinct drivers shaped by local healthcare policies and technological adoption.
United States
The United States market sees significant demand from its extensive network of critical care units, driven by a high incidence of chronic diseases. FDA's 510(k) clearance process ensures stringent safety and performance standards for new devices. The Boston-Cambridge biotechnology cluster actively develops advanced sensor-integrated catheter technologies. Large Group Purchasing Organizations in metropolitan areas influence procurement patterns.
Germany
Germany's robust healthcare infrastructure supports strong demand for specialized catheters, particularly those with hydrophilic coatings. The EU's Medical Device Regulation mandates extensive clinical data for market access. The MedTech cluster in Tuttlingen focuses on precision manufacturing for high-performance catheter components. Hospitals in major cities like Berlin prioritize infection prevention technologies.
China
China's rapidly expanding hospital capacity and increasing chronic disease burden elevate demand for central venous catheters. The NMPA mandates rigorous testing and local clinical trials for medical device market entry. Shanghai's medical device industry zone attracts significant investment for manufacturing advanced vascular access devices. Government initiatives support domestic innovation in this sector.
India
India experiences rising demand for hemodialysis catheters due to its large patient population requiring renal care. The CDSCO oversees medical device regulations, ensuring product quality and safety for local markets. Bengaluru's medical technology parks focus on developing cost-effective catheter solutions for widespread clinical use. Private healthcare investment in major cities expands critical care services.
Japan
Japan's advanced medical practices and high geriatric population drive demand for high-performance catheters, especially those with hydrophilic coatings. The PMDA ensures strict regulatory oversight for all medical devices entering the market. The Kansai region's biomedical cluster specializes in advanced material science for improved catheter performance. Tokyo hospitals are early adopters of new interventional devices.
Global Intravascular Catheters Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream, supplying critical materials and sub-assemblies for catheter manufacturing. The market structure is tiered, reflecting varying levels of technological sophistication and vertical integration among participants. Strategic archetypes include diversified medical device conglomerates offering broad portfolios and specialized vascular access solution providers focusing on niche applications. Dominant competitive moves involve strategic partnerships for market access and continuous portfolio diversification into advanced coating technologies.
Within the diversified medical device conglomerate archetype, Becton, Dickinson and Company (BD) represents a global leader with an extensive distribution network across multiple healthcare settings. Medtronic plc, a multinational company, occupies a position focused on integrating its catheter products with a broader portfolio of cardiac and vascular therapies, particularly for critical care and interventional procedures. Terumo Corporation, a Japanese company, exemplifies specialization through its expertise in advanced hydrophilic coating technologies, which significantly enhances catheter performance and patient comfort during insertion and use. These prominent entities leverage their established scale and specialized capabilities to address diverse clinical needs across various product types and end-user segments, from hospitals to home healthcare providers.
| Leading Market Players |
|---|
| Becton, Dickinson and Company (BD) |
| Boston Scientific Corporation |
| Medtronic plc |
| Teleflex Incorporated |
| Terumo Corporation |
| Abbott Laboratories |
| Cook Medical |
| B. Braun Melsungen AG |
| Edwards Lifesciences Corporation |
| Others |
Cost & Logistics Intelligence
European land freight networks, facing fluctuating fuel costs, influence the landed cost of intravascular catheters, shaping regional supply concentration and downstream price differentiation across hospital systems. This directly impacts procurement decisions for both basic and advanced catheter types.
Pricing Analysis
Volume-based contracting structures dominate the procurement of intravascular catheters, particularly for high-volume users like large hospital networks. Pricing stratifies across premium, standard, and economy tiers, driven by factors such as advanced antimicrobial coating technology and the provision of extensive after-sales clinical support. Persistent cost-containment pressure from global healthcare systems, especially from Group Purchasing Organizations in the United States, drives pricing softness for standard devices. Healthcare facilities in emerging economies exhibit the highest price sensitivity, balancing upfront costs against long-term infection prevention benefits.
Supply Chain Analysis
Stringent regulatory hurdles imposed by bodies like the EU's Medical Device Regulation create a significant structural risk for catheter manufacturers, impacting market entry and product costs. Geographic supply concentrates in countries with established medical device manufacturing, including Germany, Ireland, and China, which produce various components and finished products. Production relies on specialized biocompatible polymers like polyurethane and silicone, alongside advanced micro-sensors for smart catheters. Distribution runs through direct sales channels to hospitals and Group Purchasing Organizations, supplemented by specialized logistics for temperature-sensitive or sterile products.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The intravascular catheters market is experiencing an early-cycle expansion story, primarily driven by the significant tailwind of healthcare infrastructure expansion across China and India. This growth creates opportunities across various segments and technologies.
For Market Incumbents: Entrenchment strategies should focus on generating robust clinical evidence for advanced antimicrobial-coated catheters to justify premium pricing against persistent cost-containment pressure from Group Purchasing Organizations. Expanding R&D in sensor integration for real-time physiological monitoring provides a key lever for product differentiation and higher value applications. Diversifying manufacturing footprints to mitigate geopolitical supply chain risks also secures long-term market position.
For New Entrants and Emerging Players: Build out specialized portfolios targeting underserved niches, such as user-friendly catheters for the expanding home infusion market. Focusing on biodegradable materials for short-term use offers a white-space opportunity to address environmental concerns and appeal to sustainability-focused healthcare providers. The home healthcare provider segment in the United States represents a highly penetrable market, accessible through direct-to-consumer or specialized distribution partnerships.
For Investors and Strategic Acquirers: Specialized vascular access solution providers, particularly those with patented coating technologies or micro-sensor integration, represent attractive acquisition targets over the long term. Sustained demand from chronic disease prevalence and aging populations ensures a viable investment horizon. A key signal to watch for inflection is the widespread adoption of outcome-based reimbursement models, which would further incentivize infection-prevention technologies.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Evidence Generation | Demonstrates superior patient outcomes for advanced catheters, supporting premium pricing and regulatory compliance. |
| Geographic Manufacturing Diversification | Mitigates supply chain vulnerabilities and tariff impacts, ensuring stable product availability across regions. |
| Sensor Integration R&D | Transforms catheters into data-gathering platforms, enhancing diagnostic capabilities and clinical decision support. |
| Home Infusion Product Development | Addresses the growing demand for safe and user-friendly vascular access devices in outpatient settings. |
| Biodegradable Material Innovation | Aligns with sustainability goals and reduces medical waste, appealing to environmentally conscious healthcare systems. |
Research Approach
Operator-level perspectives from hospital procurement managers, interventional cardiologists, and critical care nurses anchored the qualitative base for this study. These primary interviews were triangulated with extensive secondary validation from sources including FDA 510(k) clearances, EU MDR compliance reports, and NMPA approval databases. A rigorous bottom-up and top-down approach ensured comprehensive data synthesis across all market segments.
Scenario-bracketing across various economic growth trajectories and healthcare policy shifts informed the analytical framework over the projection horizon. The quantitative model segmented the market by product type, application, end-user, and technology, incorporating regional healthcare spending trends. Compound annual growth rates were derived through a multifactorial analysis considering chronic disease incidence rates and healthcare infrastructure investment.
Stress conditions across global economic downturns and unforeseen regulatory changes were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect a set of carefully documented assumptions regarding technological adoption and clinical practice evolution. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular Devices
Microsclerotherapy Treatment Market
Cardiovascular Devices
Germany Cardiovascular Devices Market
Cardiovascular Devices
Transcatheter Heart Valve Market
Cardiovascular Devices
Surgical Heart Valves Market
Cardiovascular Devices
Perfusion Systems Market
Cardiovascular Devices
Arteriotomy Closure Devices Market
Cardiovascular Devices
Japan Cardiovascular Devices Market
Cardiovascular Devices
Cardiovascular Ultrasound Imaging Systems Market
Cardiovascular Devices
Cardiovascular Devices Market
Cardiovascular Devices
Heart Valves Market
Cardiovascular Devices
Endovascular Therapy Devices Market
Cardiovascular Devices
Cardiovascular and Soft Tissue Repair Patches Market
Cardiovascular Devices
Global Vascular Stents Market
Cardiovascular Devices
Endovascular Stent Market
Cardiovascular Devices
Aortic Aneurysm Market
Cardiovascular Devices
UAE Cardiovascular Devices Market