
 Single-Use Hemoperfusion Device Market | 2026-2036
Single-Use Hemoperfusion Device Market Size, Share, and Industry Trends Forecast 2026-2036
Single-Use Hemoperfusion Device Market Insights
The single-use hemoperfusion device market is rebalancing between premium cartridge systems with advanced polymeric membranes and commodity activated carbon configurations that serve cost-sensitive emergency departments. Fresenius Medical Care AG & Co. KGaA leverages its integrated dialysis platform to dominate hospital procurement channels for renal support applications. Asahi Kasei Medical anchors Japanese supply through specialized hollow-fiber membrane technology. Cytosorbents differentiates with adsorptive platforms targeting cytokine filtration in critical care settings.
A single-use hemoperfusion device is a disposable extracorporeal system designed to pass blood through an adsorbent medium—typically activated carbon, synthetic resin, or engineered polymeric membranes—to remove toxins, drugs, or inflammatory mediators without requiring dialysate fluid exchange. The cartridge housing maintains sterile isolation while controlling flow rates between 100 and 300 mL per minute depending on clinical indication. Enhanced devices with composite membrane architectures command superior margins due to broader toxin-binding specificity and reduced platelet activation. Portable units represent the fastest-growing configuration as ambulatory surgical centers and emergency departments seek point-of-care detoxification capability without capital-intensive fixed installations.
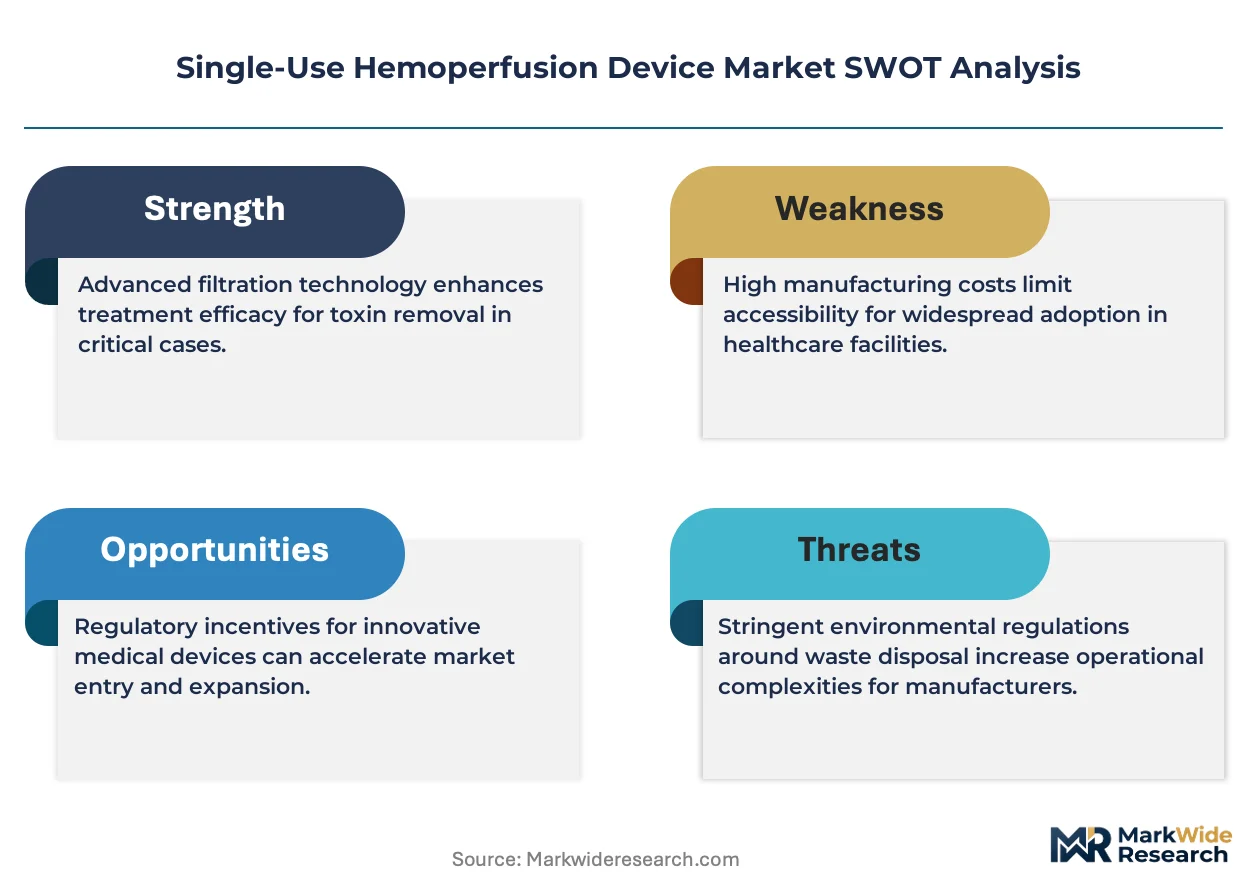
FDA 510(k) clearance pathways and EMA Medical Device Regulation (MDR) conformity assessments govern hemoperfusion cartridge biocompatibility, pyrogenicity, and adsorption kinetics validation. Japan's PMDA enforces JIS standards for blood-contacting materials that influence regional product design requirements. Stakeholders must monitor evolving regulatory convergence between FDA breakthrough device criteria and EU MDR clinical evidence expectations as these frameworks reshape market access timelines and R&D allocation priorities.
Market Dynamics
Material science advancement in synthetic polymeric membranes is compressing the performance gap between premium hemoperfusion cartridges and legacy activated carbon systems, forcing cartridge producers to justify margins through biocompatibility certification depth rather than adsorption capacity alone.
Growth Catalysts
- EMA MDR conformity pressure:Blood-contacting device manufacturers face accelerated clinical evidence requirements under the EU Medical Device Regulation, driving hospital procurement toward pre-certified cartridge suppliers with established biocompatibility dossiers.
- Critical care infrastructure expansion:Emergency departments in Germany, Japan, and the United States are installing point-of-care hemoperfusion capability for acute poisoning protocols, expanding addressable procedure volumes beyond traditional dialysis centers.
- Activated carbon supply resilience:Diversification of medical-grade carbon sourcing away from single-origin suppliers has stabilized input costs for commodity cartridge producers serving cost-sensitive hospital systems.
Market Restraints
- Polymer resin cost volatility:Specialized synthetic membrane materials derive from petroleum-based feedstocks, exposing premium cartridge margins to hydrocarbon price swings without pass-through contracting mechanisms.
- Japanese supply concentration:Hollow-fiber membrane production clusters heavily in Japanese manufacturing zones, creating geographic single-point-of-failure risk for global cartridge assembly networks.
- Substitution from continuous renal replacement:CRRT platforms with integrated adsorption modules threaten standalone hemoperfusion volumes in ICU settings where multi-modal blood purification is preferred.
Strategic Opportunities
- Portable configuration penetration:Ambulatory surgical centers in the United States represent an underpenetrated channel seeking detoxification capability without fixed installation capital requirements.
- FDA breakthrough device pathway:Accelerated review timelines for cytokine-adsorptive platforms targeting sepsis and inflammatory conditions create regulatory tailwind for novel membrane chemistries.
- Membrane-nanotechnology convergence:Integration of surface-modified nanoparticles with conventional polymeric substrates promises enhanced toxin specificity for drug overdose applications.
Industry Challenges
- Bioengineer talent scarcity:Hemoperfusion cartridge design requires cross-functional expertise in hemorheology and polymer chemistry that concentrates in limited academic and industrial clusters.
- 510(k) predicate device limitations:FDA clearance pathways for novel membrane architectures face predicate-matching constraints that extend development timelines for breakthrough adsorption technologies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Single-Use Hemoperfusion Device Market |
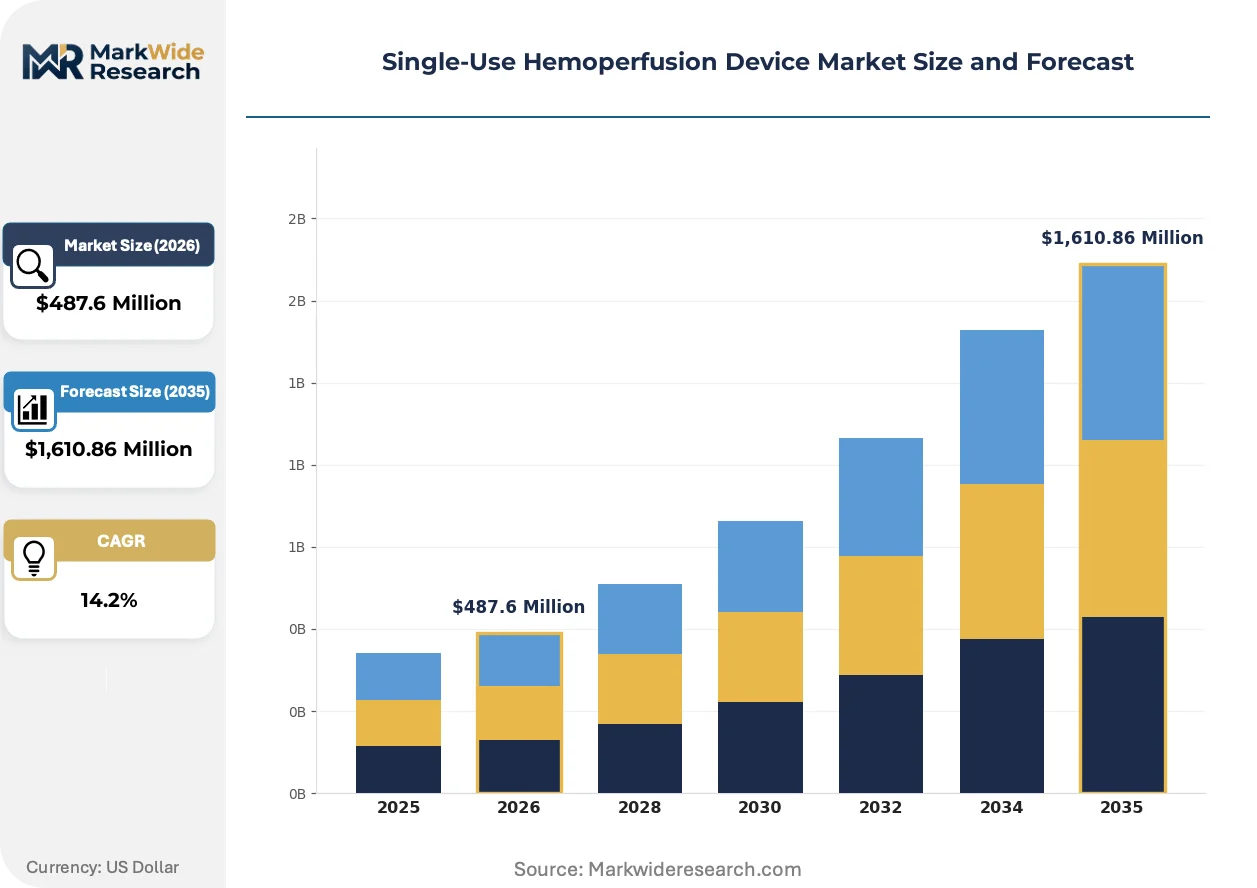
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,610.86 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Device, Enhanced Device, Portable Unit, Disposable Cartridge End User: Hospitals, Ambulatory Surgical Centers, Specialty Clinics, Emergency Departments Application: Treatment of Poisoning, Renal Support, Detoxification, Hepatic Encephalopathy Material: Polymeric Membranes, Activated Carbon, Filter Materials, Composite Materials |
| Companies Covered | Fresenius Medical Care AG & Co. KGaA, Asahi Kasei Medical, Baxter International Inc., Kaneka Corporation, Cytosorbents, Jafron Biomedical Co., Ltd., B. Braun Melsungen AG, Nikkiso Co., Ltd., Toray Medical Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Single-Use Hemoperfusion Device Market Trends and Innovations
Membrane engineering and regulatory data requirements are compressing product development cycles while fragmenting procurement authority across hospital pharmacy, critical care, and nephrology departments.
Surface-functionalized polymeric membranes with zwitterionic coatings are converging with traditional activated carbon substrates in hybrid cartridge architectures. Academic medical centers in Germany and the United States are piloting these composite systems for broad-spectrum toxin removal in polypharmacy overdoses. This convergence is converging with point-of-care deployment models that bypass centralized pharmacy oversight.
Japan's PMDA has tightened JIS standards for blood-contacting materials, requiring extended thrombogenicity testing for new membrane submissions. Domestic manufacturers face elongated approval timelines that disadvantage imported cartridge technologies. European producers seeking Japanese market access are establishing local biocompatibility testing partnerships to satisfy PMDA evidence expectations.
Hospital purchasing committees are fragmenting hemoperfusion procurement decisions away from centralized nephrology supply agreements toward emergency department-specific vendor contracts. Standalone cartridges for acute poisoning are displacing bundled dialysis-hemoperfusion packages in United States trauma centers. This pattern concentrates in Level I trauma facilities where rapid deployment protocols override long-term service relationships.
Single-Use Hemoperfusion Device Market Segmentation
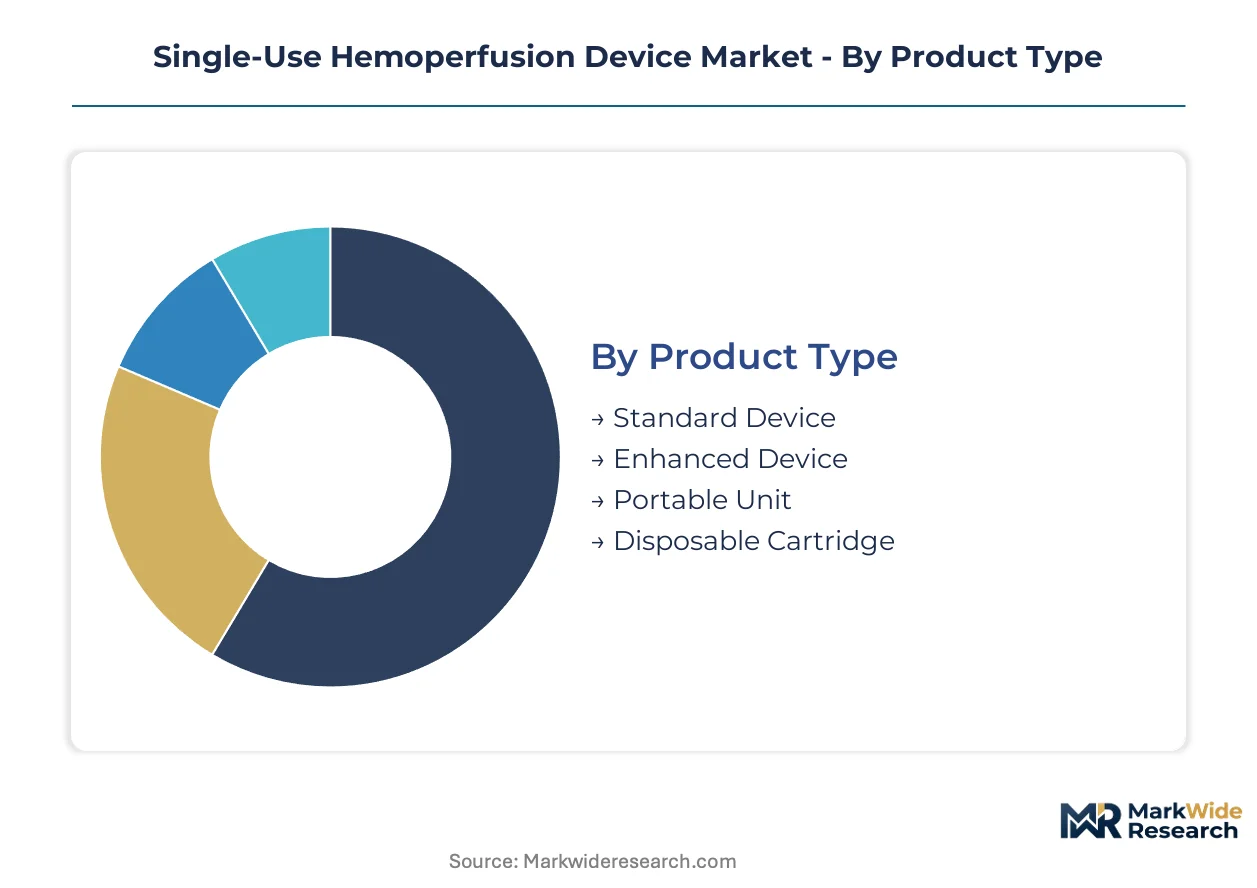
Segmentation in hemoperfusion devices reveals how clinical setting, material specification, and mobility requirements partition procurement authority across hospital departments. Manufacturers must align cartridge design with specific regulatory pathways and end-user capital constraints.
Product Type:
Device architecture determines flow control precision, adsorbent capacity, and capital deployment models across care settings.
- Standard Device:Fixed-installation systems with flow rates of 100-300 mL per minute serve dialysis centers requiring consistent throughput for renal support. Demand concentrates in Germany and Japan where specialized nephrology infrastructure supports high procedure volumes.
- Enhanced Device:Composite membrane architectures with zwitterionic surface coatings reduce platelet activation while expanding toxin-binding specificity. Premium pricing depends on biocompatibility certification depth rather than adsorption capacity alone.
- Portable Unit:Battery-powered configurations enable point-of-care deployment without fixed installation requirements. Ambulatory surgical centers in the United States seek detoxification capability without capital-intensive infrastructure.
- Disposable Cartridge:Single-use adsorbent cartridges with activated carbon or resin matrices integrate into modular hemoperfusion platforms. Emergency departments prioritize rapid cartridge exchange over multi-use system durability.
Mature deployment sits with Standard Device configurations in established dialysis networks. Newer deployment is concentrated in Portable Unit segments serving ambulatory and emergency settings.
End User:
Procurement authority fragments across clinical departments based on procedure urgency and reimbursement pathways.
- Hospitals:Integrated health systems leverage volume contracting for hemoperfusion capacity across nephrology, critical care, and emergency departments. FDA 510(k) clearance and EMA MDR certification filter supplier qualification.
- Emergency Departments:Level I trauma centers deploy standalone cartridges for acute poisoning protocols. Procurement decisions bypass centralized pharmacy oversight where rapid deployment timelines override long-term service relationships.
- Ambulatory Surgical Centers:Outpatient facilities seek detoxification capability without fixed installation capital requirements. Reimbursement constraints limit adoption to high-acuity overdose presentations.
- Specialty Clinics:Hepatology and toxicology centers utilize hemoperfusion for hepatic encephalopathy and specialized detoxification. Procedure volumes remain constrained by narrow indication profiles.
Volume concentration rests with Hospitals. Procurement autonomy is expanding fastest in Emergency Departments.
Application:
Clinical indication determines adsorbent selection, treatment duration, and regulatory evidence requirements.
- Treatment of Poisoning:Broad-spectrum toxin removal for drug overdose and chemical exposure drives emergency department adoption. Composite membrane systems with enhanced biocompatibility command premium positioning in polypharmacy cases.
- Renal Support:Adjunctive blood purification for acute kidney injury integrates with dialysis platforms. Fresenius Medical Care dominates procurement channels through bundled service agreements.
- Detoxification:Systemic inflammatory mediator removal in sepsis and critical illness utilizes cytokine-adsorptive membranes. FDA breakthrough device pathways accelerate review for novel chemistries targeting this indication.
- Hepatic Encephalopathy:Ammonia and neurotoxin filtration for liver failure represents a narrow specialty application. Limited procedure volumes constrain dedicated device development.
Established utilization centers on Renal Support. Indication expansion is proceeding fastest in Detoxification applications.
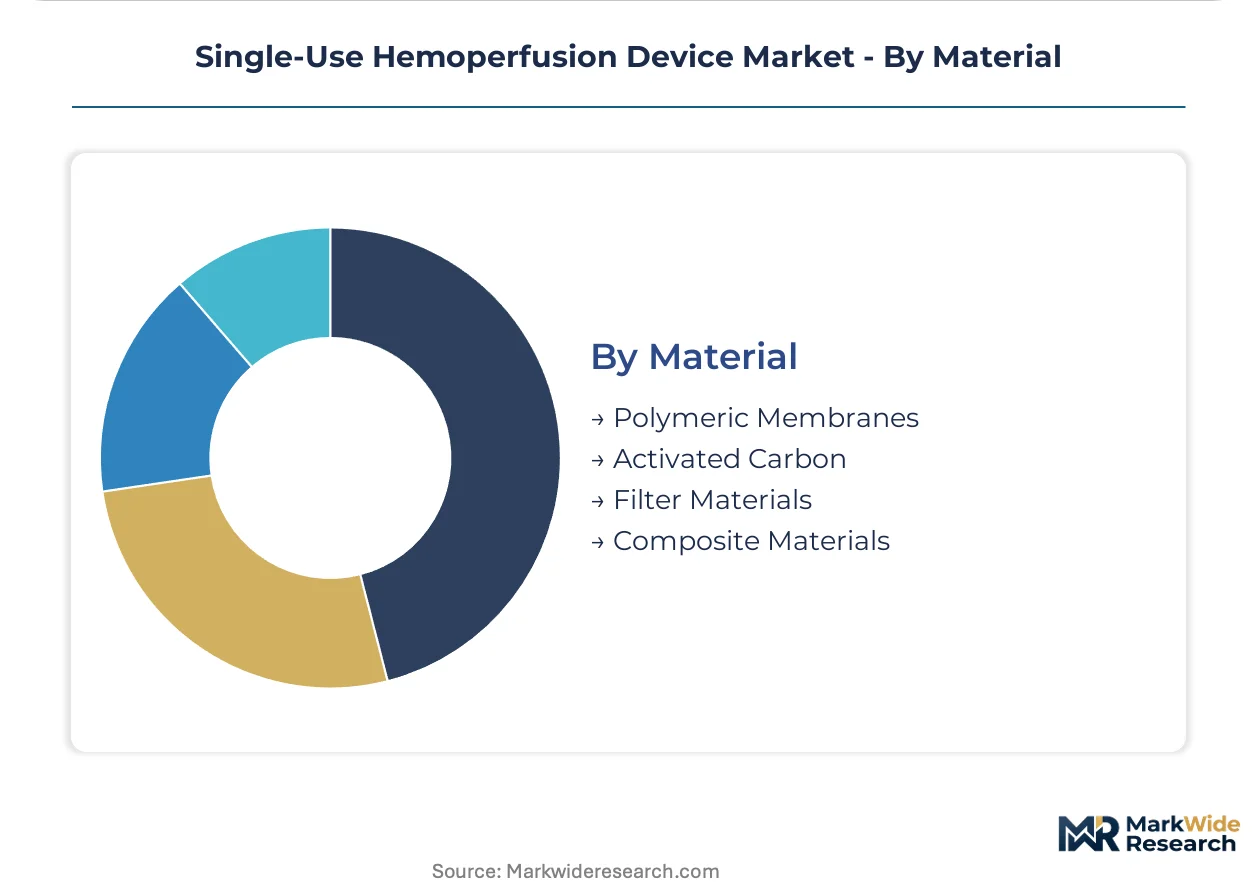
Material:
Substrate chemistry governs biocompatibility profile, manufacturing cost structure, and regulatory validation burden.
- Polymeric Membranes:Synthetic hollow-fiber materials with engineered pore architectures enable selective molecular filtration. Japanese manufacturing clusters under PMDA JIS standards concentrate production capacity.
- Activated Carbon:Medical-grade carbon with controlled particle size distribution provides non-selective toxin adsorption. Supply diversification away from single-origin producers has stabilized input costs.
- Composite Materials:Hybrid architectures combining polymeric substrates with surface-modified nanoparticles promise enhanced specificity. Academic medical centers in Germany and the United States pilot these systems for broad-spectrum applications.
- Filter Materials:Mechanical filtration media for particulate removal serve auxiliary roles in cartridge design. Limited differentiation constrains standalone commercial positioning.
Production scale sits with Activated Carbon. Technology transition is advancing fastest in Composite Materials.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Tokyo anchors hemoperfusion device manufacturing through concentrated hollow-fiber membrane production clusters serving domestic and export demand. Specialized dialysis infrastructure in Osaka-Kobe and Nagoya corridors sustains procedure volume density unmatched elsewhere.
United States
Level I trauma centers in Baltimore, Houston, and Los Angeles deploy standalone hemoperfusion cartridges for acute poisoning protocols. FDA 510(k) clearance pathways govern biocompatibility validation for blood-contacting materials. Emergency departments in the Southeast and Pacific Northwest are fragmenting procurement authority away from centralized nephrology supply agreements.
Germany
Academic medical centers in Berlin and Munich pilot composite membrane systems for polypharmacy overdose applications. EMA MDR conformity assessments accelerate clinical evidence requirements for cartridge suppliers. The Rhine-Ruhr industrial corridor concentrates specialized dialysis infrastructure supporting high renal support procedure volumes.
Japan
PMDA JIS standards for blood-contacting materials enforce extended thrombogenicity testing for new membrane submissions. Domestic manufacturers in the Kanto region face elongated approval timelines that disadvantage imported cartridge technologies. Osaka-based production clusters dominate global hollow-fiber membrane supply.
China
Jafron Biomedical and domestic producers scale activated carbon cartridge output for cost-sensitive hospital systems. NMPA medical device registration governs biocompatibility dossier requirements for blood purification products. The Yangtze River Delta corridor concentrates assembly capacity serving provincial critical care expansion.
Single-Use Hemoperfusion Device Market Competitive Landscape
Premium-margin players sit above commodity-margin players across membrane technology certification depth, with biocompatibility dossier sophistication determining tier placement rather than adsorption capacity alone. The vendor base stratifies between integrated dialysis platform operators, specialized hollow-fiber membrane fabricators, and cytokine-adsorptive platform developers. Three archetypes dominate: diversified medical technology conglomerates with bundled service capabilities, focused membrane engineering specialists with regional supply anchoring, and emergent adsorptive technology developers targeting critical care indications. Competitive moves concentrate on regulatory pre-certification investments and emergency department-specific procurement channel development.
Among Germany-based diversified operators, Fresenius Medical Care AG & Co. KGaA exemplifies the integrated platform archetype through bundled dialysis-hemoperfusion service agreements. Asahi Kasei Medical occupies a position within the specialized membrane tier, representing Japanese hollow-fiber production concentration. Cytosorbents sits within the emergent adsorptive technology vector, exemplifying cytokine-filtration positioning in critical care settings.
| Leading Market Players |
|---|
| Fresenius Medical Care AG & Co. KGaA |
| Asahi Kasei Medical |
| Baxter International Inc. |
| Kaneka Corporation |
| Cytosorbents |
| Jafron Biomedical Co., Ltd. |
| B. Braun Melsungen AG |
| Nikkiso Co., Ltd. |
| Toray Medical Co., Ltd. |
| Others |
Pricing and Supply Chain Analysis
Cross-functional expertise in hemorheology and polymer chemistry concentrates in limited academic and industrial clusters across Germany and Japan, with labor-cost differentials between these specialized bioengineering hubs and commodity manufacturing zones driving three-tier pricing spreads across premium, standard, and economy cartridge tiers.
Pricing Analysis
Throughput-based pricing anchors hemoperfusion cartridge valuation, with hospital systems contracting for guaranteed procedure volumes rather than per-unit procurement. Price differentiation rests on biocompatibility certification depth—FDA 510(k) clearance tier versus EMA MDR full conformity—and after-sales technical support bundling. Cost compression in activated carbon configurations is intensifying because supply diversification has stabilized input costs, while emergency departments exhibit highest price sensitivity due to budget autonomy constraints.
Supply Chain Analysis
Domestic-content mandates under Japan's PMDA JIS standards and China's NMPA registration requirements are reshaping sourcing patterns toward localized membrane testing partnerships. Hollow-fiber membrane production draws from Japanese manufacturing clusters in Osaka-Kobe, medical-grade activated carbon feeds from diversified Asian and European sources, and polymeric resin inputs hinge on petroleum-based feedstock markets. Single-source vulnerability in Japanese hollow-fiber supply creates geographic concentration risk. Distribution runs through hospital GPO contracts and emergency department-specific vendor agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical integration into hollow-fiber membrane fabrication and captive activated carbon processing has become the decisive competitive lever as cartridge producers seek margin defense against commodity substitution.
For Market Incumbents: Extend biocompatibility certification depth beyond baseline regulatory requirements to justify premium positioning against emerging cytokine-adsorptive platforms. Deepen backward integration into polymeric membrane feedstock production to offset petroleum-based resin cost volatility. Lock emergency department procurement channels through rapid-deployment service agreements before standalone CRRT platforms displace standalone hemoperfusion volumes in ICU settings. For New Entrants and Emerging Players: Ambulatory surgical centers in the United States Southeast represent the most penetrable channel, seeking detoxification capability without capital-intensive fixed installations. Target FDA breakthrough device pathway acceleration for cytokine-adsorptive membrane chemistries in sepsis applications. Pursue white-label manufacturing partnerships with established dialysis platform operators to bypass predicate-device constraints in 510(k) submissions. For Investors and Strategic Acquirers: The window for entry favors specialized membrane engineering specialists with established PMDA JIS testing infrastructure and hollow-fiber production assets in Japanese manufacturing corridors. Long-term viability hinges on regulatory pre-certification depth rather than adsorption capacity scale. Monitor FDA breakthrough device designation grants to cytokine-filtration platforms as the inflection signal for critical care indication expansion.| Strategic Initiative | Industry Significance |
|---|---|
| PMDA JIS Biocompatibility Partnership | Japanese regulatory pre-certification accelerates market access for hollow-fiber membrane suppliers. |
| Emergency Department Channel Development | Level I trauma center procurement autonomy fragments traditional nephrology supply relationships. |
| FDA Breakthrough Device Submission | Accelerated review timelines compress development cycles for cytokine-adsorptive platforms. |
| Activated Carbon Supply Diversification | Multi-origin sourcing stabilizes input costs for commodity cartridge producers. |
| Composite Membrane R&D Alliance | Academic partnerships in Germany and the United States pilot surface-modified nanoparticle integration. |
Research Methodology
Independent corroboration across hospital purchasing committee interviews, biomedical engineering directors at academic medical centers, and GPO contracts managers underwrites the qualitative findings. Primary fieldwork with regulatory affairs specialists at cartridge manufacturers and emergency department clinical leads combined with secondary validation from FDA 510(k) filings, EMA MDR conformity assessment databases, PMDA submission records, and hospital procurement databases. Bottom-up procedure volume estimates triangulate against top-down market sizing.
Historical reference periods spanning installed base growth and procedure volume trajectories anchor projections across the analysis window. Segmentation dimensions include device architecture, end-user department, clinical indication, and substrate chemistry. CAGRs derive from regression analysis against nephrology infrastructure expansion rates and critical care bed growth. Forecast inputs incorporate EMA MDR transition timelines and FDA breakthrough device pathway utilization rates.
Several conditions sit outside the modeled scope, including unannounced regulatory framework revisions, raw material supply disruptions from geopolitical events, and substitution velocity from integrated CRRT platforms. Forecasts reflect documented assumptions about hospital capital expenditure continuity and reimbursement stability for acute poisoning protocols. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular Devices
Global Catheters Market
Cardiovascular Devices
Catheter-Directed Thrombolysis Market
Cardiovascular Devices
LAMEA Cardiac Surgical Devices Market
Cardiovascular Devices
Balloon Catheters Market
Cardiovascular Devices
Renovascular Hypertension Treatment Market
Cardiovascular Devices
Intra-Aortic Balloon Pump (IABP) Market
Cardiovascular Devices
Transcatheter Market
Cardiovascular Devices
Cardiac Cannulas Market
Cardiovascular Devices
Congestive Heart Failure Treatment Devices Market
Cardiovascular Devices
Cardiovascular Repair and Reconstruction Devices Market
Cardiovascular Devices
Shock Wave Therapy Devices Market
Cardiovascular Devices
India Coronary Stent Market
Cardiovascular Devices
Hypertension Management Devices Market
Cardiovascular Devices
Cryptogenic Stroke Treatment Market
Cardiovascular Devices
Cardiac Ablation Catheter Market
Cardiovascular Devices
Cardiovascular Prosthetic Devices Market