
 Netherlands Cardiovascular Devices Market | 2026-2036
Netherlands Cardiovascular Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Netherlands Cardiovascular Devices Market Foresight
Remote monitoring subscription services for implantable cardiac devices is realigning vendor revenue models beyond hardware sales. Medtronic PLC leverages its CareLink network to sustain recurring revenue streams across Dutch cardiology centers. Philips Healthcare anchors its domestic position through integrated diagnostic-to-interventional platform contracts with academic medical centers.
Cardiovascular devices encompass implantable and external instruments engineered to diagnose, monitor, or treat heart and vascular pathologies, typically incorporating biocompatible alloys, drug-eluting polymers, or sensor-integrated electronics manufactured under ISO 13485 quality systems. These devices serve to restore hemodynamic function, prevent thrombotic events, or enable real-time cardiac monitoring in clinical settings. Stents and catheters dominate procedure volumes in Dutch interventional practice, while pacemakers command premium pricing due to battery longevity and leadless miniaturization. Non-invasive diagnostic technology segments are expanding fastest as hospitals deploy AI-augmented echocardiography and CT-FFR platforms to reduce unnecessary catheterization.
The EU Medical Device Regulation and notified body oversight under BSI Netherlands govern market access, mandating post-market surveillance and unique device identification that elevates compliance costs for manufacturers. Health Technology Assessment Netherlands (ZIN) evaluates reimbursement eligibility, directly shaping hospital procurement decisions for novel devices. Stakeholders must monitor evolving HTA criteria for digital health integration and bioabsorbable scaffold evidence thresholds.
Market Dynamics
The EU Medical Device Regulation is compressing market entry timelines for implantable cardiovascular devices while Dutch hospitals accelerate catheterization lab expansion to absorb rising coronary intervention volumes. This regulatory-capacity tension defines current competitive positioning.
Growth Catalysts
- Catheterization lab expansion:Dutch academic medical centers in Utrecht and Rotterdam are adding interventional suites to manage PCI volume growth. Hospital construction permits for cardiac wings rose sharply in Randstad provinces.
- MDR post-market surveillance mandates:The EU Medical Device Regulation's enhanced clinical evidence requirements favor established manufacturers with robust quality management systems. Notified bodies under BSI Netherlands are prioritizing cardiovascular device certifications.
- Leadless pacemaker miniaturization:Battery chemistry advances and transcatheter delivery systems are expanding eligible patient populations. Amsterdam's cardiology centers report shorter recovery times driving referral demand.
Market Restraints
- Notified body bottleneck:BSI Netherlands and other EU designated bodies face application backlogs exceeding 18 months for Class III implantable devices. Certification delays freeze product launches regardless of clinical readiness.
- Platinum-iridium alloy supply concentration:Electrode manufacturing depends on South African and Russian refined metal flows. Geopolitical friction elevates input cost volatility for pacing lead producers.
- HTA evidence thresholds:Health Technology Assessment Netherlands demands randomized trial data for novel bioabsorbable scaffolds. Small manufacturers lack capital to generate ZIN-compliant dossiers.
Strategic Opportunities
- Remote monitoring subscription models:Cloud-connected implantable cardiac devices generate recurring revenue streams beyond hardware margins. Dutch cardiology centers in Eindhoven and Groningen are piloting integrated monitoring platforms.
- AI-augmented diagnostic convergence:Machine learning-integrated echocardiography and CT-FFR platforms reduce unnecessary catheterization. Academic hospitals in Leiden seek vendor partnerships for algorithm validation.
- Peripheral region hospital networks:Limburg and Overijssel provinces show interventional cardiology capacity gaps. Mobile catheterization lab services or hub-and-spoke models address geographic inequity.
Industry Challenges
- Interventional cardiologist workforce scarcity:Dutch medical training programs produce insufficient specialists to staff expanded catheterization labs. Hospital groups compete for experienced operators through compensation escalation.
- Legacy device system integration:New AI-diagnostic platforms must interface with hospital information systems running decade-old architectures. IT modernization timelines lag device procurement cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Netherlands Cardiovascular Devices Market |
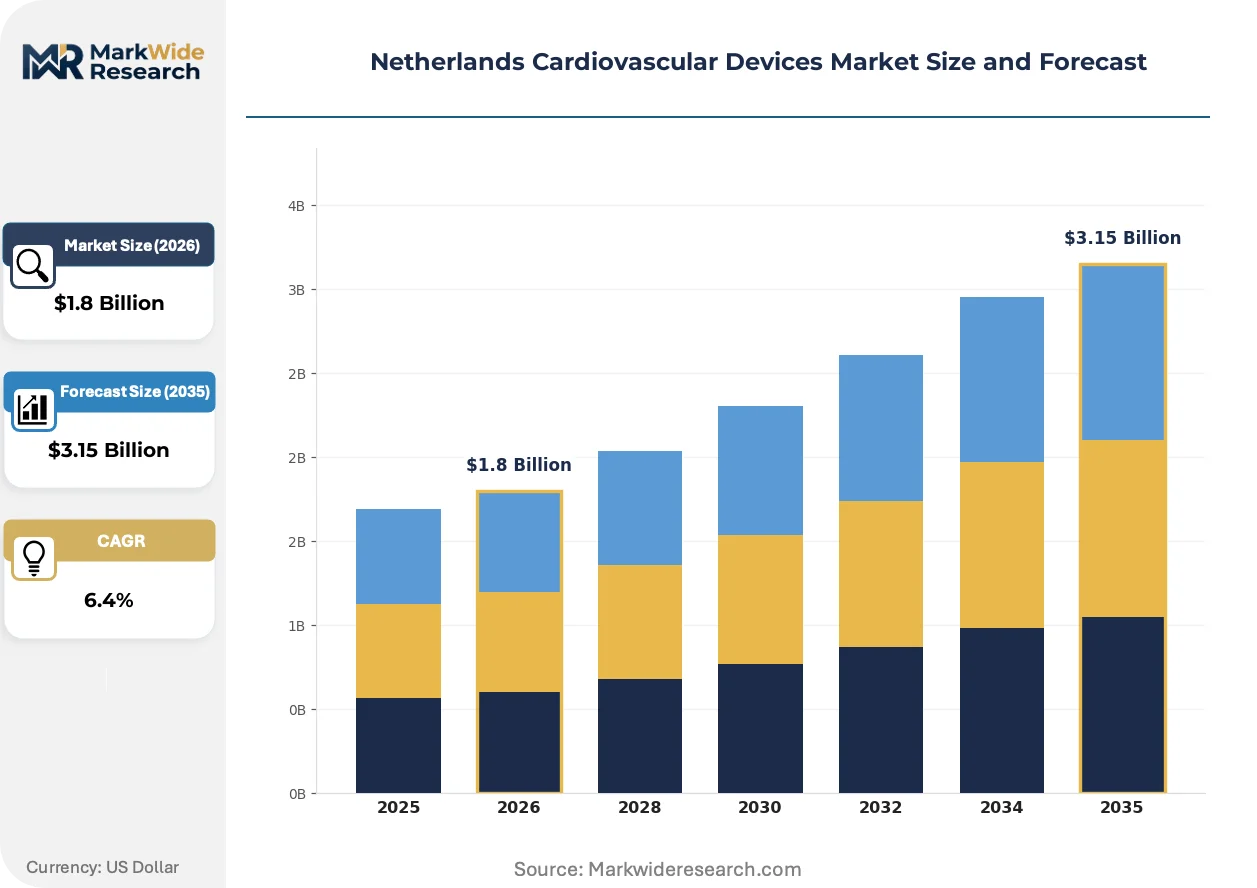
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stents, Pacemakers, Catheters, Valves End User: Hospitals, Cardiovascular Clinics, Research Institutes, Ambulatory Surgical Centers Technology: Invasive, Non-Invasive, Automated, Diagnostic Application: Heart Failure, Coronary Artery Disease, Arrhythmias, Peripheral Artery Disease |
| Companies Covered | Abbott Laboratories, Boston Scientific Corporation, Medtronic PLC, Philips Healthcare, Biotronik, GE Healthcare, Siemens Healthineers AG, Cardinal Health Inc, Nihon Kohden Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Netherlands Cardiovascular Devices Market Shifts & Advancements
Digital health integration and minimally invasive delivery systems are compressing traditional boundaries between diagnostic imaging, interventional therapy, and longitudinal patient monitoring in Dutch cardiovascular care.
Sensor-integrated leadless pacemakers are unifying cardiac rhythm management with remote hemodynamic monitoring in a single implantable device. University Medical Center Utrecht and Erasmus MC Rotterdam have adopted these dual-function systems for heart failure patients with conduction disease. The technology is unifying previously separate device categories into platform contracts that lock out standalone competitors.
The EU Medical Device Regulation's unique device identification mandate is forcing manufacturers to reconfigure labeling and traceability systems across entire product portfolios. Dutch distributors must now maintain serialized inventory records linking each implant to patient outcomes. Implantable device segments face the steepest compliance cost escalation as legacy stock requires retrospective UDI assignment.
Hospital procurement committees are consolidating vendor relationships around integrated diagnostic-to-interventional platform contracts. Academic medical centers in Amsterdam and Leiden now specify bundled imaging, catheterization, and monitoring equipment from single suppliers. This concentration is most visible in Randstad metropolitan networks where standardization reduces training and maintenance complexity.
Netherlands Cardiovascular Devices Market Segmentation
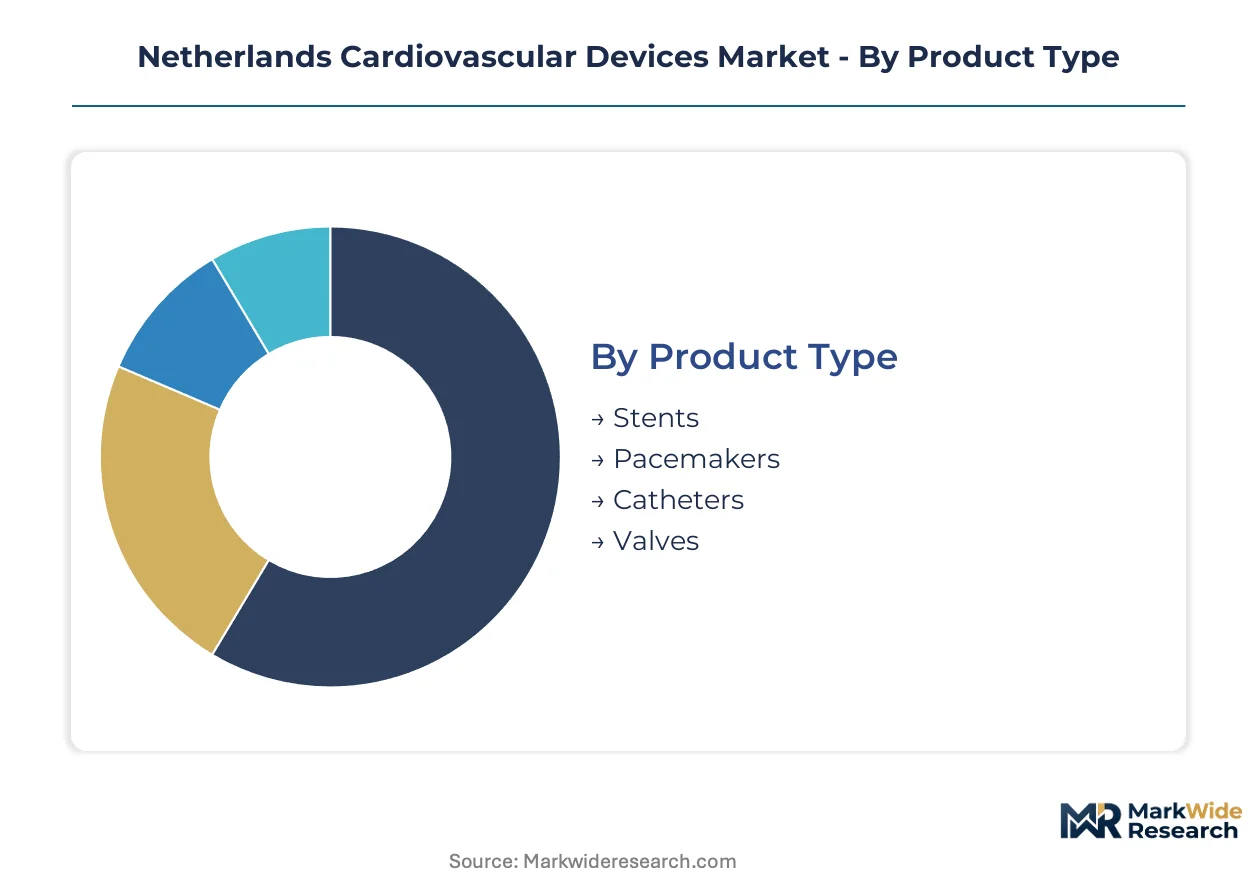
Segmentation in the Netherlands cardiovascular devices market reveals distinct procurement patterns across Dutch hospital networks. Randstad academic medical centers concentrate demand for premium implantable devices, while peripheral provinces prioritize cost-efficient diagnostic platforms.
Product Type:
Capital intensity varies sharply across implantable categories, with pacemaker manufacturing requiring cleanroom assembly and long-term battery testing infrastructure that stents and catheters do not demand.
- Pacemakers:Miniaturized pulse generators with lithium-iodine battery chemistry and transvenous or leadless delivery systems. Amsterdam UMC and Erasmus MC Rotterdam concentrate procurement for dual-chamber and MRI-conditional models as catheterization lab expansion accelerates device utilization.
- Stents:Metallic or polymeric scaffolds with drug-eluting coatings deployed via percutaneous coronary intervention. Dutch interventional cardiology volumes in Utrecht and Leiden hospital networks drive demand for bioresorbable variants despite HTA reimbursement scrutiny.
- Catheters:Guiding and diagnostic catheters manufactured under ISO 13485 quality systems for coronary and peripheral vascular access.
- Valves:Transcatheter aortic and mitral valve replacements requiring specialized delivery sheaths and fluoroscopic guidance.
Pacemakers absorb the bulk of installed capacity due to battery longevity requirements and replacement cycles; stents are expanding most quickly as PCI volumes rise across Dutch catheterization labs.
End User:
Procurement authority concentrates differently across Dutch healthcare infrastructure, with academic medical centers controlling high-value implantable decisions while ambulatory centers manage diagnostic workflows.
- Hospitals:Academic and tertiary centers with catheterization labs, electrophysiology suites, and cardiac surgery departments. University Medical Centers in Groningen and Maastricht anchor demand for integrated diagnostic-to-interventional platforms as construction permits for cardiac wings increase.
- Cardiovascular Clinics:Specialized outpatient facilities performing diagnostic echocardiography and stress testing. Randstad metropolitan networks in The Hague and Eindhoven concentrate this segment as referral pathways formalize.
- Research Institutes:Academic centers conducting clinical trials for novel bioabsorbable scaffolds and sensor-integrated devices.
- Ambulatory Surgical Centers:Same-day intervention facilities for diagnostic catheterization and pacemaker implantation.
Hospitals command the largest procurement budgets; cardiovascular clinics are gaining share fastest as diagnostic triage shifts away from inpatient settings.
Technology:
Regulatory burden under EU MDR scales with invasiveness, creating divergent compliance cost structures across technology categories.
- Invasive:Implantable and interventional devices requiring sterile surgical or percutaneous deployment. Dutch notified bodies under BSI Netherlands prioritize Class III certifications for these systems as post-market surveillance mandates tighten clinical evidence requirements.
- Non-Invasive:External diagnostic and monitoring platforms including echocardiography and CT-FFR systems. Leiden University Medical Center pilots AI-augmented algorithms to reduce unnecessary catheterization referrals.
- Automated:Cloud-connected remote monitoring systems for implantable cardiac devices with subscription revenue models.
- Diagnostic:Imaging and physiological measurement tools for cardiac function assessment.
Invasive technology dominates current revenue; non-invasive platforms are climbing the fastest as hospitals deploy AI-integrated diagnostics to manage PCI volume growth.
Application:
Patient demographics and intervention complexity create distinct device requirements across cardiac pathologies treated in Dutch practice.
- Coronary Artery Disease:Stent deployment and revascularization procedures addressing atherosclerotic narrowing. Rotterdam catheterization labs report sustained PCI volume growth as smoking prevalence and metabolic syndrome drive incident cases.
- Heart Failure:Cardiac resynchronization therapy and remote hemodynamic monitoring for reduced ejection fraction. University Medical Center Utrecht adopts dual-function leadless pacemakers unifying rhythm management with monitoring capabilities.
- Arrhythmias:Pacemaker and implantable cardioverter-defibrillator therapy for conduction disorders.
- Peripheral Artery Disease:Endovascular intervention for lower extremity ischemia using specialized catheters and stents.
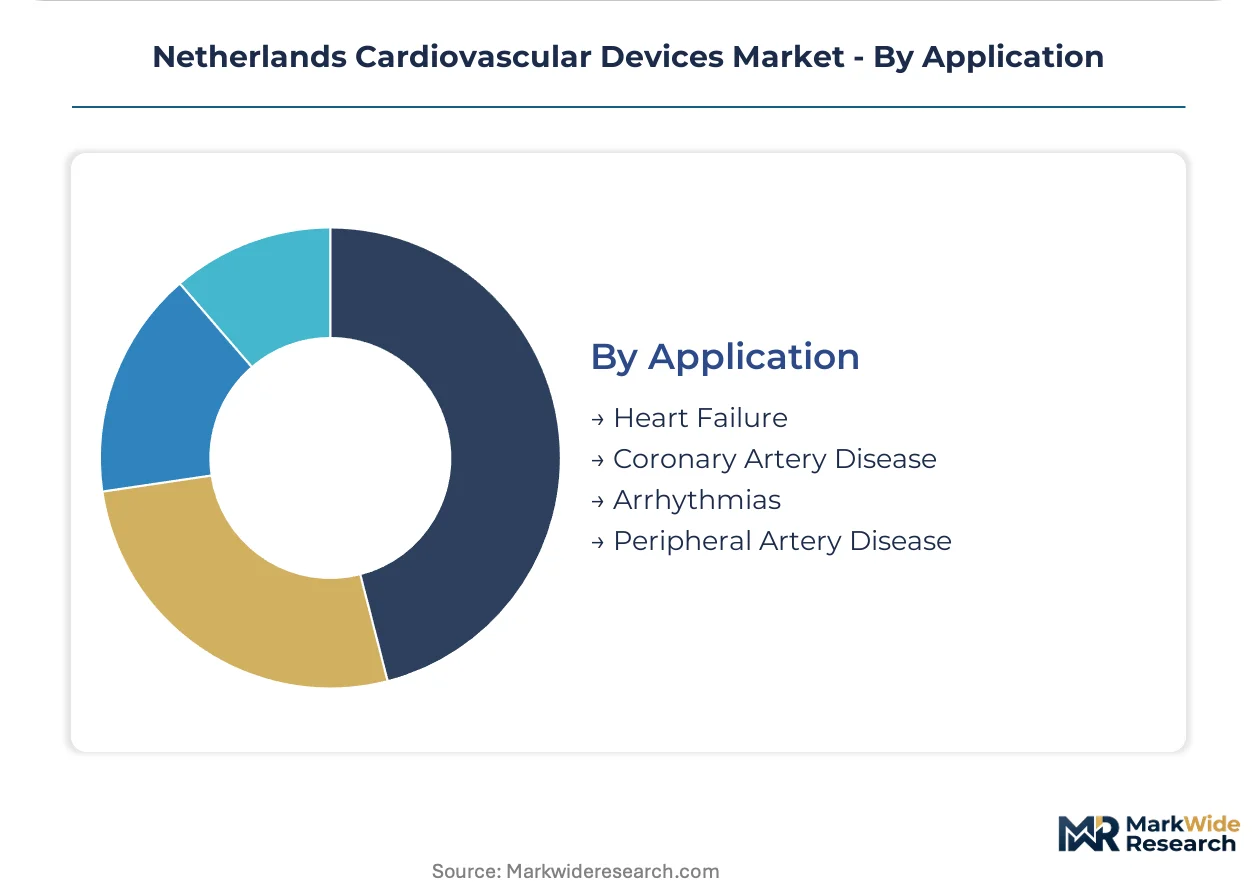
Coronary artery disease applications anchor installed device base; heart failure is gaining share fastest as sensor-integrated platforms expand eligible monitoring populations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production of cardiovascular devices concentrates in Germany, Switzerland, and Ireland, while Dutch hospitals consume advanced implantables and diagnostic platforms that these manufacturing hubs export. The Netherlands functions as a high-value absorption market rather than a production center.
Randstad
Amsterdam UMC and Erasmus MC Rotterdam drive demand for leadless pacemakers and integrated diagnostic-to-interventional platforms. Health Technology Assessment Netherlands evaluates reimbursement for novel bioabsorbable scaffolds before these devices enter hospital formularies. The Utrecht-Leiden corridor anchors catheterization lab expansion as construction permits for cardiac wings accelerate.
Brabant
Eindhoven's cardiology centers pilot remote monitoring subscription models for cloud-connected implantable devices. The EU Medical Device Regulation mandates unique device identification that elevates compliance costs for distributors serving this manufacturing-intensive province. Philips Healthcare maintains deep procurement relationships with regional hospital networks.
Eindhoven Region
High-tech medical device ecosystems in this southern cluster attract AI-augmented diagnostic platform trials. ZIN reimbursement criteria for machine learning-integrated echocardiography shape vendor selection at Catharina Hospital Eindhoven. The Brainport technology corridor generates cross-pollination between semiconductor and medical sensor engineering.
Northern Netherlands
University Medical Center Groningen anchors demand for cardiac resynchronization therapy in this peripheral zone. BSI Netherlands notified body certification delays freeze product launches for smaller manufacturers targeting this lower-volume market. Hub-and-spoke referral patterns concentrate complex interventions in Groningen while peripheral hospitals manage diagnostics.
Limburg
Maastricht UMC+ serves cross-border patient flows from Belgium and Germany alongside Dutch demand. The province's interventional cardiology capacity gaps create openings for mobile catheterization lab services. EU MDR post-market surveillance requirements complicate inventory management for distributors covering this southeastern periphery.
Netherlands Cardiovascular Devices Market Competitive Landscape
Capital-heavy producers compete with asset-light designers as vertically integrated device manufacturers face specialized component suppliers. The Dutch market exhibits tiered concentration with premium implantable segments dominated by established multinationals while diagnostic platforms support broader vendor participation. Three archetypes prevail: integrated diagnostic-to-interventional platform providers, implantable rhythm management specialists, and AI-augmented diagnostic software vendors. Competitive moves center on hospital procurement consolidation through bundled platform contracts and recurring revenue models via remote monitoring subscriptions.
Within the integrated platform tier, Philips Healthcare and Siemens Healthineers AG exemplify capital-intensive manufacturers anchoring academic medical center relationships through imaging-to-intervention workflows. Medtronic PLC occupies a position representing the implantable specialist archetype, with its CareLink network illustrating subscription-based revenue migration beyond hardware sales. Among diversified health technology conglomerates, GE Healthcare sits within the diagnostic imaging vector serving Dutch cardiology centers with echocardiography and CT-FFR platforms.
| Leading Market Players |
|---|
| Abbott Laboratories |
| Boston Scientific Corporation |
| Medtronic PLC |
| Philips Healthcare |
| Biotronik |
| GE Healthcare |
| Siemens Healthineers AG |
| Cardinal Health Inc |
| Nihon Kohden Corporation |
| Others |
Supply & Pricing Matrix
Certification-grade divergence between Class III implantables and diagnostic platforms splits Dutch procurement budgets and supplier qualification requirements simultaneously. EU MDR compliance costs concentrate pricing power with notified body-certified manufacturers while peripheral hospitals absorb premium markups through GPO consolidation.
Pricing Analysis
Margin tightening in implantable rhythm management reflects platinum-iridium electrode cost volatility and BSI Netherlands certification backlogs. Three-tier pricing structure across premium MRI-conditional, standard dual-chamber, and economy single-chamber pacemakers stratifies by battery longevity and leadless capability. Cost-down pressure on diagnostic catheters accelerates as Dutch hospital groups centralize procurement through Philips Healthcare platform contracts. Academic medical centers show lowest price sensitivity for integrated imaging-to-intervention bundles; ambulatory surgical centers in Limburg and Overijssel exhibit highest sensitivity to per-unit stent pricing.
Supply Chain Analysis
ISO 13485 quality system certification gates access to Dutch hospital formularies, filtering component suppliers through cleanroom assembly and sterilization validation requirements. Manufacturing concentrates in Germany, Switzerland, and Ireland for finished devices; South African and Russian refined platinum-iridium flows feed electrode production. Raw material dependencies span lithium-iodine battery chemistry, drug-eluting polymer coatings, and sensor-integrated microelectronics. Single-source vulnerability in precious metal refining elevates input cost unpredictability for pacing lead producers. Distribution runs through specialized medical device distributors with serialized UDI tracking capabilities mandated under EU MDR.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
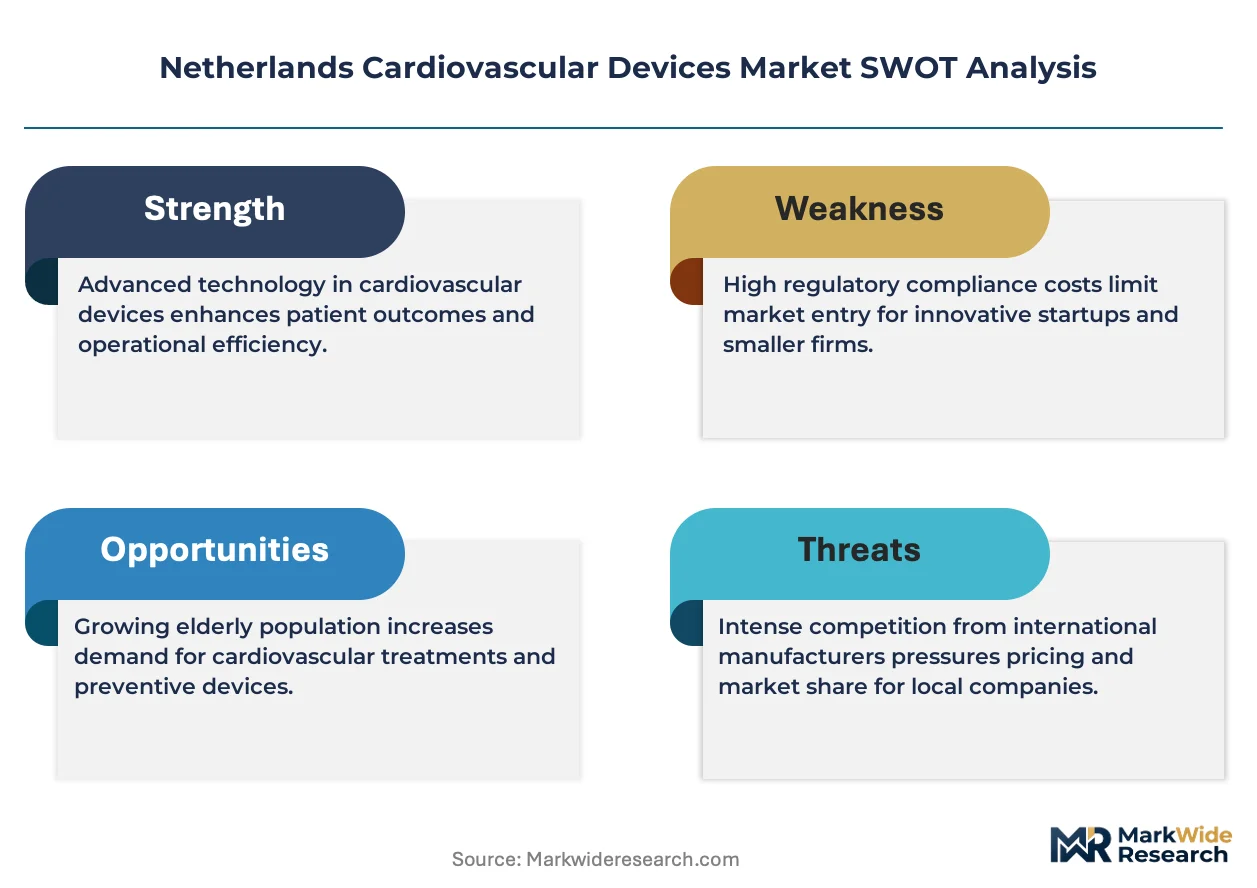
This market represents a consolidation play as notified body certification delays and HTA evidence thresholds force capital-constrained manufacturers toward exit or acquisition.
For Market Incumbents: Anticipate margin compression from AI-augmented diagnostic convergence by securing exclusive algorithm validation partnerships with Leiden and Amsterdam academic medical centers. Deepen backward integration into sensor-integrated pacemaker battery chemistry to offset platinum-iridium supply volatility. Lock in catheterization lab expansion contracts across Randstad construction pipelines before competitor platform bundling freezes access. For New Entrants and Emerging Players: Begin with peripheral region hub-and-spoke service models in Limburg and Overijssel where interventional cardiologist scarcity creates mobile catheterization lab demand. Target bioabsorbable scaffold niches awaiting ZIN reimbursement clarity with focused clinical evidence generation. Pursue software-as-a-service entry through remote monitoring platform white-labeling for regional hospital networks lacking IT infrastructure. For Investors and Strategic Acquirers: Re-rating potential sits with notified body-certified component specialists given EU MDR's quality system consolidation mandate. Long-term viability favors manufacturers with captive supply of lithium-iodine cells and established BSI Netherlands technical file portfolios. Watch for inflection in ZIN reimbursement decisions for bioabsorbable scaffolds as signal for premium segment repricing.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | BSI Netherlands certification accelerates market access for Class III implantables ahead of competitor backlogs. |
| Hospital System Partnership | Platform contracts with Amsterdam UMC and Erasmus MC Rotterdam lock out standalone diagnostic competitors. |
| Software Companion Development | AI-augmented echocardiography algorithms at Leiden University Medical Center reduce unnecessary catheterization referrals. |
| Reimbursement Strategy | ZIN dossier preparation for bioabsorbable scaffolds determines hospital formulary inclusion before competitor evidence. |
| Backward Integration | In-house lithium-iodine battery production insulates Medtronic and Biotronik from supply concentration risk. |
Research Methodology
Document review covered EU MDR implementation guidance, ZIN HTA evaluation reports, and hospital construction permit databases, complemented by interviews with interventional cardiologists, biomedical engineers, GPO contracts managers, and notified body auditors. Secondary validation drew from BSI Netherlands certification records, hospital procurement databases, and customs trade flows for platinum-iridium alloys. Bottom-up procedure volume modeling and top-down manufacturer revenue triangulation anchored market sizing.
Cross-referencing historical catheterization lab expansion patterns against clinician panel input shaped installation base projections across the analysis window. Segmentation dimensions modeled encompassed product type, end user facility tier, technology invasiveness level, and application pathology. CAGRs derived from weighted average of procedure volume growth and price trajectory assumptions. Forecast inputs incorporated EU MDR compliance cost pass-through rates and ZIN reimbursement decision timelines.
Regulatory enforcement intensity, precious metal supply disruption, and HTA evidence threshold elevation are the dominant revision risks to modeled outcomes. Forecasts embed assumptions regarding BSI Netherlands certification throughput and Randstad hospital construction completion. A model refresh is warranted upon material change in ZIN reimbursement criteria for sensor-integrated devices.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular Devices
Percutaneous Coronary Intervention Guidance Devices Market
Cardiovascular Devices
Global Vascular Injury Treatment Market
Cardiovascular Devices
Transcatheter Aortic Valve Replacement Market
Cardiovascular Devices
Drug Eluting Stent (DES) Market
Cardiovascular Devices
Global Valvular Heart Disease Treatment Market
Cardiovascular Devices
Cerebral Vascular Stent Market
Cardiovascular Devices
Chronic Venous Occlusions Treatment Market
Cardiovascular Devices
Chronic Total Occlusion Catheter Market
Cardiovascular Devices
Cardiac Cryoablation Device Market
Cardiovascular Devices
South Korea Cardiovascular Devices Market
Cardiovascular Devices
Percutaneous Transluminal Coronary Angioplasty (PTCA) Balloon Catheters Market
Cardiovascular Devices
Global Intravascular Temperature Management Market
Cardiovascular Devices
Global Aortic Valve Market
Cardiovascular Devices
Endovascular Aneurysm Repair Market
Cardiovascular Devices
Heart Beat Irregularity Detection Device Market
Cardiovascular Devices
Heart Valves Market