
 Human Non-Invasive Blood Pressure (NIBP) Recording System Market | 2026-2036
Human Non-Invasive Blood Pressure (NIBP) Recording System Market Size, Share, and Industry Trends Forecast 2026-2036
Human Non-Invasive Blood Pressure (NIBP) Recording System Market Analytics
Equipment leasing and pay-per-use financing is reconfiguring competitive access for mid-sized health systems that previously deferred capital purchases. GE Healthcare leverages manufacturing scale to anchor hospital supply contracts across North America. Koninklijke Philips N.V. sustains R&D intensity in connected care platforms that integrate NIBP data into broader patient monitoring ecosystems. Omron Healthcare dominates retail and pharmacy channels with specialized home-use devices that bypass traditional clinical procurement.
A human non-invasive blood pressure recording system measures arterial pressure through external cuff-based sensors without vascular penetration, typically employing oscillometric algorithms that detect pressure oscillations during cuff deflation to calculate systolic, diastolic, and mean arterial values for diagnostic and longitudinal monitoring purposes. Digital monitors lead volume shipments while wearable devices represent the fastest-expanding segment as ambulatory and telemedicine applications require continuous, unobtrusive data streams. Oscillometric technology occupies the mature core of installed hospital bases, whereas volume clamp methods compete in critical care settings demanding beat-to-beat precision.
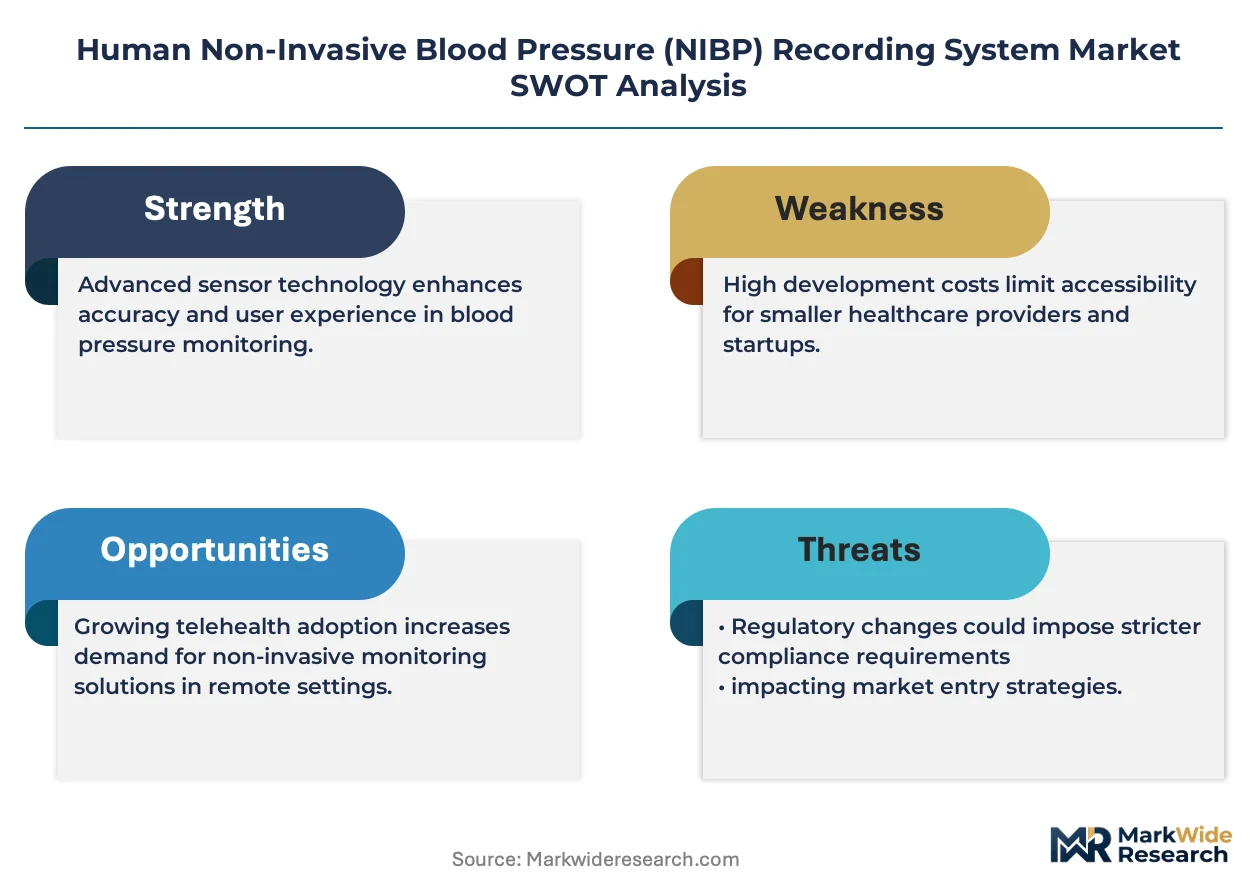
The FDA regulates these devices under 21 CFR 870.1130 with software validation requirements that extend clearance timelines for algorithm-driven products, while the EU MDR imposes stricter clinical evidence thresholds for Class IIa monitoring equipment that filter market entrants. Japan's PMDA maintains distinct pharmacovigilance reporting for home-use versus clinical-grade NIBP systems, creating dual compliance tracks for manufacturers. Stakeholders must weigh regulatory capital requirements against the margin profiles of wearable and automated system segments where reimbursement pathways remain unsettled.
Market Dynamics
Hospital procurement departments are expanding device fleets to support remote patient monitoring programs, while the FDA's evolving guidance on software-as-a-medical-device is reshaping product clearance pathways for algorithm-driven NIBP systems.
Growth Catalysts
- Telemedicine infrastructure mandates:CMS reimbursement expansion for remote patient monitoring services is pulling ambulatory NIBP device deployments into home health and post-acute care settings across United States health systems.
- EU MDR Class IIa clinical evidence requirements:Stricter performance validation standards for connected monitoring equipment are filtering low-quality entrants and consolidating demand around validated oscillometric platforms.
- Japan's aging cardiovascular burden:PMDA pharmacovigilance differentiation between home-use and clinical-grade systems is creating dual compliance tracks that reward specialized manufacturers with distinct product portfolios.
Market Restraints
- Semiconductor component volatility:Pressure sensor MEMS supply concentrates in Taiwan and South Korea foundries, exposing device manufacturers to input cost swings and allocation rationing during demand surges.
- Algorithm validation bottlenecks:FDA 21 CFR 870.1130 software validation requirements extend clearance timelines for machine learning-enhanced oscillometric interpretation, compressing competitive windows for innovation.
- Wearable photoplethysmography substitution:Consumer-grade optical pulse monitoring from smartwatch ecosystems threatens standalone NIBP device attach rates in preventive health segments.
Strategic Opportunities
- Underpenetrated German outpatient cardiac rehabilitation:Cardiology practice networks lack standardized ambulatory blood pressure monitoring protocols, creating whitespace for integrated NIBP-ECG platform vendors.
- Volume clamp method convergence with arterial line validation:Beat-to-beat precision technologies are penetrating ICU settings previously dominated by invasive monitoring, enabled by catheter-free validation studies.
- Pharmacy retail channel bypass:Direct-to-consumer distribution through omni-channel health platforms is circumventing traditional clinical procurement for home-use device segments.
Industry Challenges
- Embedded systems firmware expertise scarcity:Oscillometric algorithm optimization requires rare combinations of biomedical signal processing and real-time embedded engineering talent.
- Legacy hospital IT integration friction:HL7 FHIR connectivity standards vary across United States, German, and Japanese health system EMR deployments, forcing redundant certification cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Human Non-Invasive Blood Pressure (NIBP) Recording System Market |
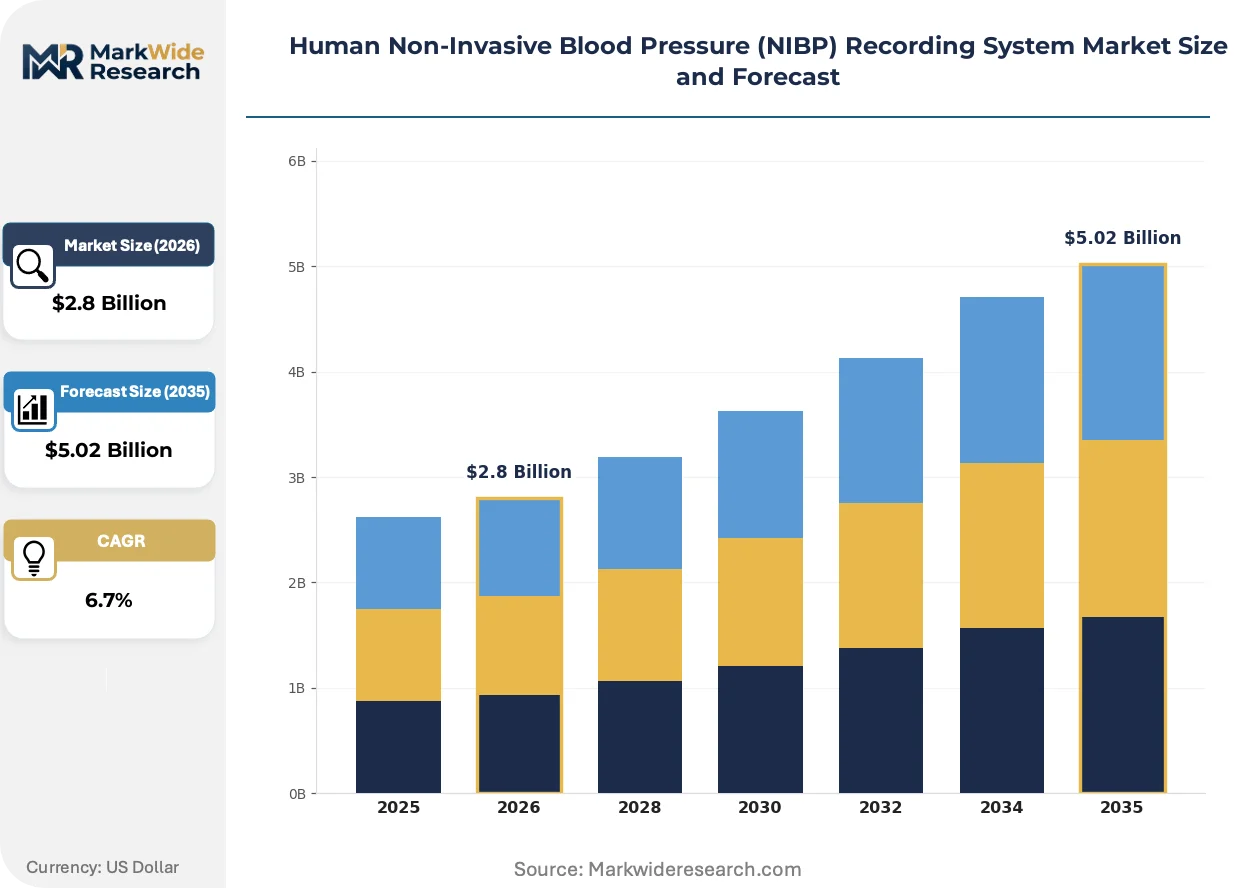
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Digital Monitors, Analog Monitors, Wearable Devices, Automated Systems Technology: Oscillometric, Intra-arterial, Volume Clamp, Atrial End User: Hospitals, Home Care, Ambulatory Surgical Centers, Clinics Application: Cardiology, Emergency Medicine, Preventive Care, Telemedicine |
| Companies Covered | GE Healthcare, Koninklijke Philips N.V., Omron Healthcare, A&D Company, Hill-Rom Holdings, Welch Allyn, SCHILLER AG, American Diagnostic Corporation, Microlife Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Human Non-Invasive Blood Pressure (NIBP) Recording System Market Evolving Landscape
Continuous monitoring architectures are collapsing the distinction between episodic clinical measurement and longitudinal ambulatory tracking, forcing technology convergence across previously separate device categories.
Wearable cuffless blood pressure estimation using pulse transit time algorithms is collapsing the form-factor constraints that previously segmented hospital, clinic, and home-use markets. Cardiology departments at Mayo Clinic and Charité Berlin are piloting wrist-worn systems for 24-hour ambulatory protocols previously requiring arm-cuff oscillometry. The structural boundary between consumer wellness and clinical-grade monitoring is compressing as PMDA and FDA draft parallel validation frameworks for optical-based continuous NIBP.
EU MDR recertification deadlines for legacy Class IIa monitoring devices are forcing portfolio rationalization among manufacturers with extensive pre-2021 product lines. Clinical evidence requirements for substantial equivalence claims now demand prospective validation studies that add 18-24 months to renewal timelines. German notified bodies are prioritizing connected-care platforms with integrated cybersecurity documentation, disadvantaging standalone NIBP vendors without ecosystem partnerships.
Hospital supply chain managers are unbundling device procurement from consumable and service contracts, reversing decades of bundled leasing arrangements. United States IDN procurement offices now separate capital equipment acquisition from multi-year calibration and maintenance agreements, enabling competitive displacement at contract renewal. This disintermediation is most visible in Kaiser Permanente and Veterans Health Administration systems where standardization committees mandate interoperable data formats over single-vendor ecosystems.
Human Non-Invasive Blood Pressure (NIBP) Recording System Market Segmentation
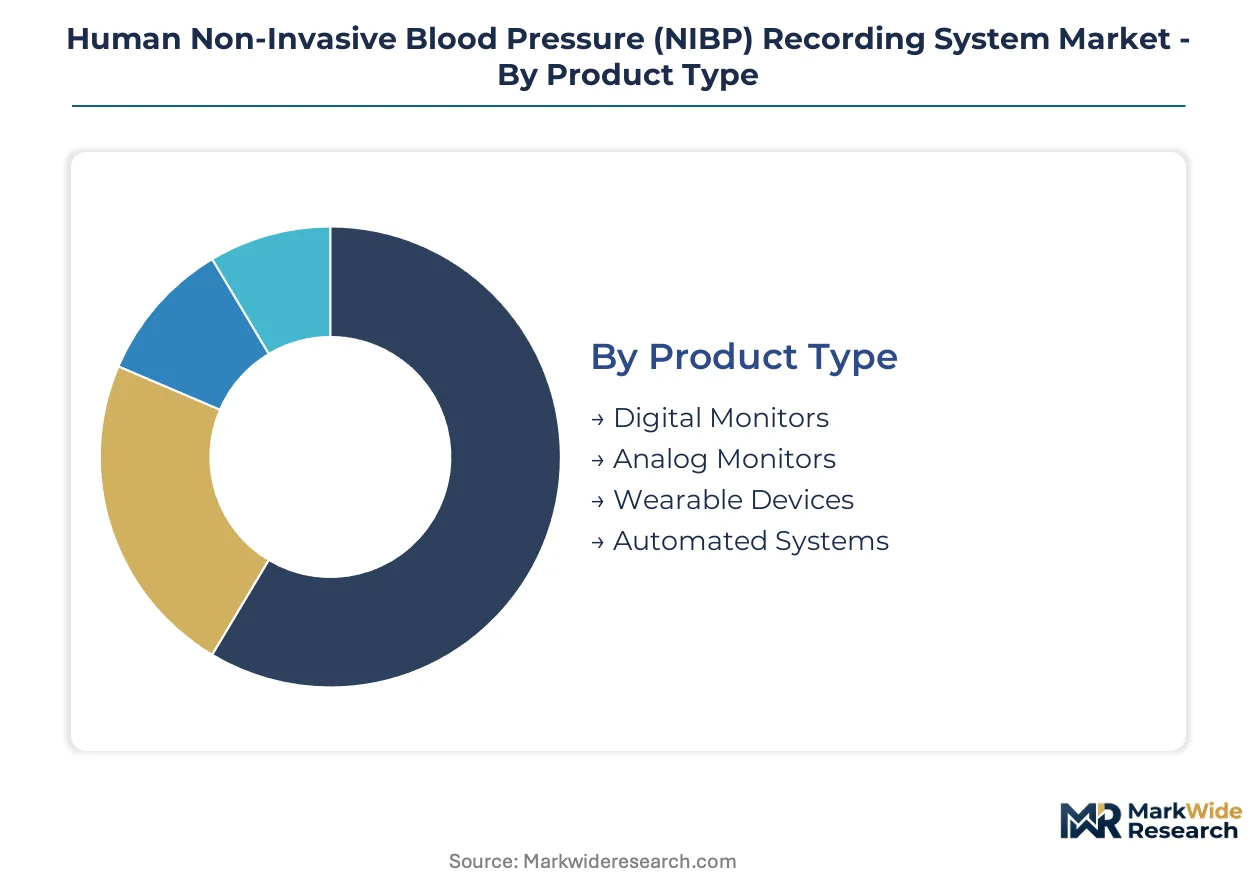
Segmentation in the NIBP recording system market reveals how clinical workflows, patient acuity levels, and reimbursement pathways fragment demand across incompatible device specifications. Each category reflects distinct procurement channels, regulatory burdens, and margin structures that manufacturers must navigate simultaneously.
Product Type:
Device categories span from precision hospital instruments to consumer-accessible wearables, with cost tiers determining channel access and reimbursement eligibility.
- Digital Monitors:Microprocessor-controlled oscillometric units with LCD displays and memory storage dominate hospital ward deployments and pharmacy retail channels. United States health systems prioritize these for remote patient monitoring programs where CMS reimbursement requires documented measurement accuracy.
- Wearable Devices:Cuffless wrist-worn systems employing pulse transit time or photoplethysmography algorithms enable continuous ambulatory monitoring without sleep disruption. Mayo Clinic and Charité Berlin pilot programs validate these for 24-hour protocols previously requiring arm-cuff oscillometry.
- Analog Monitors:Auscultatory manual sphygmomanometers with mercury or aneroid gauges persist in low-resource settings and regulatory backup applications where electromagnetic interference resistance matters.
- Automated Systems:Multi-parameter monitoring platforms integrate NIBP modules with pulse oximetry and ECG for operating room and intensive care unit workflows.
The dominant share belongs to digital monitors, while wearable devices are closing the gap fastest.
Technology:
Measurement principles differentiate precision capabilities, with algorithmic complexity determining clinical versus wellness positioning.
- Oscillometric:Pressure cuff deflation detects arterial wall oscillations to calculate systolic, diastolic, and mean arterial pressure through proprietary algorithms. This mature technology anchors installed hospital bases across Germany, Japan, and the United States despite FDA software validation bottlenecks under 21 CFR 870.1130.
- Volume Clamp:Finger cuff pressure servocontrol maintains arterial wall position constant, enabling beat-to-beat precision comparable to invasive arterial lines. Critical care settings in tertiary hospitals adopt this for hemodynamically unstable patients where intermittent measurement risks diagnostic gaps.
- Intra-arterial:Catheter-based invasive measurement provides continuous waveform analysis reserved for high-acuity surgical and shock management scenarios.
- Atrial:Specialized cardiac catheterization laboratory applications measure left atrial pressure through transseptal access during electrophysiology procedures.
Oscillometric platforms command the installed base, yet volume clamp methods are penetrating ICU settings most aggressively.
End User:
Procurement authority and reimbursement pathways fragment demand across institutional, retail, and direct-to-consumer channels.
- Hospitals:IDN supply chain managers unbundle device procurement from service contracts, enabling competitive displacement at renewal. Kaiser Permanente and Veterans Health Administration standardization committees mandate interoperable HL7 FHIR data formats over single-vendor ecosystems.
- Home Care:Post-acute and chronic disease management programs drive ambulatory device deployment where pharmacy retail channels bypass traditional clinical procurement. Japan's PMDA maintains distinct pharmacovigilance reporting tracks for home-use versus clinical-grade systems.
- Ambulatory Surgical Centers:Same-day procedure volumes require compact, rapid-cycle monitors with disposable cuff inventories.
- Clinics:Outpatient cardiology and primary care practices balance acquisition cost against calibration maintenance requirements.
Hospitals retain the largest procurement volume, though home care is expanding most quickly.
Application:
Clinical use cases determine performance specifications, with acuity levels driving differentiation between episodic measurement and continuous monitoring architectures.
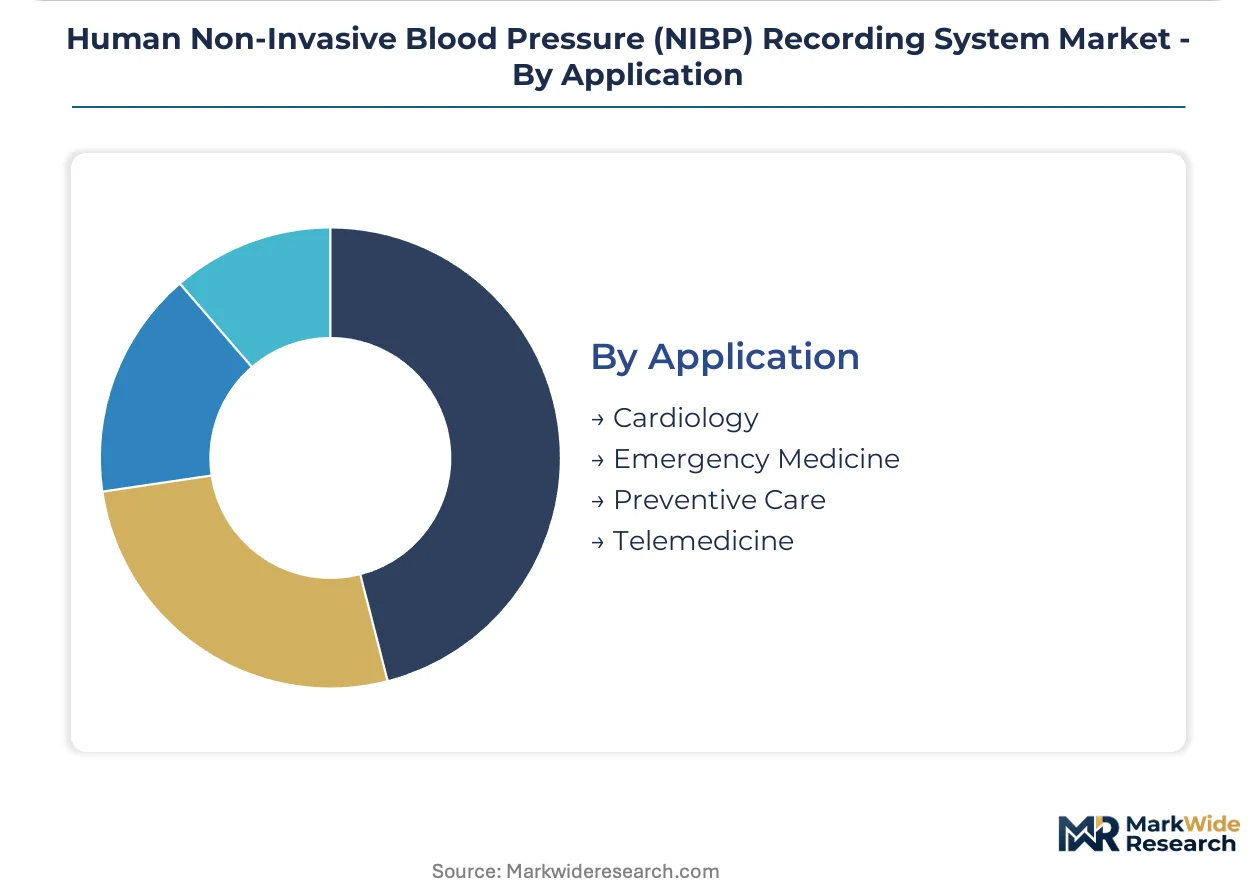
- Cardiology:Ambulatory blood pressure monitoring protocols and stress testing applications demand validated accuracy across exercise-induced pressure ranges. German outpatient cardiac rehabilitation networks lack standardized protocols, creating whitespace for integrated NIBP-ECG platforms.
- Telemedicine:Remote patient monitoring reimbursement expansion pulls device deployments into home health settings. Continuous data streams collapse the distinction between episodic clinical measurement and longitudinal ambulatory tracking.
- Emergency Medicine:Rapid triage and transport applications prioritize durability, battery life, and shock resistance over precision granularity.
- Preventive Care:Workplace wellness and insurance incentive programs drive consumer-grade device adoption where smartwatch photoplethysmography threatens standalone NIBP attach rates.
Cardiology applications generate the highest revenue per unit, while telemedicine is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export flows concentrate oscillometric modules and pressure sensor MEMS from Taiwan and South Korea foundries toward assembly operations in Germany, Japan, and the United States. Import dependency for semiconductor inputs creates vulnerability during demand surges, while finished device re-exports circulate through Swiss and Dutch distribution hubs serving Middle Eastern and African markets.
United States
CMS reimbursement expansion for remote patient monitoring services accelerates ambulatory device deployment into home health settings. FDA 21 CFR 870.1130 software validation requirements extend clearance timelines for algorithm-driven products. Kaiser Permanente and Veterans Health Administration procurement offices in California and Washington D.C. mandate interoperable HL7 FHIR data formats over single-vendor ecosystems.
Germany
Outpatient cardiac rehabilitation networks lack standardized ambulatory blood pressure monitoring protocols, creating whitespace for integrated platform vendors. EU MDR Class IIa clinical evidence requirements filter low-quality entrants and consolidate demand around validated oscillometric platforms. Berlin and Munich host notified bodies prioritizing connected-care platforms with integrated cybersecurity documentation.
Japan
Aging demographics strain cardiovascular care infrastructure and expand home-use device demand. PMDA maintains distinct pharmacovigilance reporting tracks for home-use versus clinical-grade systems, creating dual compliance tracks. Tokyo and Osaka metropolitan areas concentrate tertiary hospital procurement authority for critical care volume clamp adoption.
China
Domestic manufacturing scale supports cost-competitive digital monitor production for Southeast Asian and African export markets. NMPA regulatory harmonization efforts with international standards accelerate market access for multinational device vendors. Shenzhen and Shanghai clusters integrate MEMS pressure sensor fabrication with downstream monitor assembly.
Switzerland
Precision engineering heritage anchors high-accuracy volume clamp technology development for critical care applications. Swissmedic maintains stringent post-market surveillance requirements that validate device reliability claims. Basel and Zurich serve as European distribution hubs for Middle Eastern and African re-export markets.
Human Non-Invasive Blood Pressure (NIBP) Recording System Market Competitive Landscape
On the supply side, the industry is consolidating around three strategic tiers: multinational conglomerates with manufacturing scale, specialized monitoring technology developers, and consumer health electronics manufacturers. Hospital procurement unbundling and EU MDR recertification deadlines favor players with diversified regulatory expertise and ecosystem partnerships. Dominant competitive moves include strategic partnerships for HL7 FHIR connectivity certification and portfolio diversification into wearable cuffless platforms.
Within the conglomerate tier, GE Healthcare and Koninklijke Philips N.V. represent integrated health technology platforms that span diagnostic imaging through patient monitoring ecosystems. Omron Healthcare occupies a distinct position as a consumer health electronics specialist with pharmacy retail channel dominance. These three anchors illustrate how regulatory capital requirements and reimbursement pathway complexity filter market participation toward entities with multi-market compliance infrastructure.
| Leading Market Players |
|---|
| GE Healthcare |
| Koninklijke Philips N.V. |
| Omron Healthcare |
| A&D Company |
| Hill-Rom Holdings |
| Welch Allyn |
| SCHILLER AG |
| American Diagnostic Corporation |
| Microlife Corporation |
| Others |
Value Network & Pricing Analysis
Taiwan and South Korea foundries concentrate MEMS pressure sensor fabrication, anchoring margin capture at the component tier while downstream device assemblers in Germany, Japan, and the United States compete on calibration service bundling and FDA clearance speed.
Pricing Analysis
Hospital procurement departments anchor contract-based pricing structures that unbundle capital equipment from multi-year calibration and maintenance agreements. Price differentiation rests on FDA 510(k) clearance tier and HL7 FHIR interoperability certification, with premium tiers commanding attach rates for remote monitoring software. Cost compression in mid-sized health system segments is intensifying because CMS reimbursement uncertainty delays replacement cycles. Ambulatory surgical centers exhibit highest price sensitivity; integrated delivery networks with GPO contracts show lowest.
Supply Chain Analysis
Extended payment terms from German and Japanese hospital procurement offices now stretch to 90-120 days, forcing Taiwan and South Korea MEMS suppliers to absorb working capital pressure or cede share to vertically integrated Chinese competitors. Raw material dependencies center on silicon wafers, piezoelectric ceramics, and medical-grade polymers. Single-source vulnerability concentrates in Taiwan semiconductor foundries. Distribution runs through Swiss and Dutch hubs serving Middle Eastern and African re-export markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach revenue from calibration, cybersecurity updates, and remote monitoring platform subscriptions is expanding faster than hardware shipments, transforming capital equipment vendors into recurring-revenue enterprises.
For Market Incumbents: Insulate installed base positions through backward integration into MEMS pressure sensor design and captive FDA regulatory affairs capacity. Consolidate around HL7 FHIR connectivity certification investments that Kaiser Permanente and Veterans Health Administration procurement committees now mandate, displacing standalone vendors lacking ecosystem partnerships. For New Entrants and Emerging Players: German outpatient cardiac rehabilitation networks lacking standardized ambulatory blood pressure monitoring protocols represent the most penetrable entry point for integrated NIBP-ECG platform vendors. Pharmacy retail channel bypass through direct-to-consumer omni-channel health platforms offers a lower-friction go-to-market angle than hospital procurement penetration. For Investors and Strategic Acquirers: Capital is best deployed toward specialized monitoring technology developers with dual FDA-PMDA clearance infrastructure and wearable cuffless algorithm portfolios. Long-term viability across the 5-10 year window hinges on software-as-a-medical-device validation speed. Watch FDA draft guidance on optical-based continuous NIBP as the inflection signal for consumer-clinical boundary collapse.| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Secures multi-year device fleet contracts with IDNs unbundling procurement from service agreements. |
| Software Companion Development | Enables CMS-compliant remote patient monitoring data streams that trigger reimbursement eligibility. |
| FDA Submission | Accelerates 510(k) clearance timelines for machine learning-enhanced oscillometric interpretation algorithms. |
| CE Marking Pathway | Navigates EU MDR Class IIa clinical evidence requirements that filter low-quality connected monitoring entrants. |
| Reimbursement Strategy | Aligns device specifications with CMS remote patient monitoring billing codes expanding across United States health systems. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with hospital procurement managers, biomedical engineers, GPO contracts specialists, and PMDA regulatory consultants; and secondary validation against FDA 510(k) filings, CMS Medicare reimbursement databases, EU MDR notified body guidance documents, and hospital supply chain procurement records. Bottom-up and top-down triangulation cross-checked device shipment estimates against reimbursement claim volumes.
Forecast inputs span product type segmentation across digital monitors, wearable devices, and automated systems; technology differentiation between oscillometric and volume clamp methods; and end-user channel splits among hospitals, home care, and ambulatory surgical centers. CAGRs derive from regression analysis of historical reimbursement expansion rates and semiconductor input cost trajectories across the projection horizon. Modeled variables include EU MDR recertification timeline delays and Taiwan foundry allocation rationing scenarios.
Macroeconomic conditions sit as an overlay; deviation in CMS reimbursement policy, Taiwan semiconductor export restrictions, or EU MDR clinical evidence cost inflation would shift the trajectory. Forecasts reflect documented assumptions about regulatory clearance speed and hospital IT integration friction. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular Devices
Transcatheter Heart Valve Market
Cardiovascular Devices
Pressure Infusion Bags Market
Cardiovascular Devices
Percutaneous Coronary Intervention Guidance Devices Market
Cardiovascular Devices
Europe Cardiac Assist Devices Market
Cardiovascular Devices
Endovascular Therapy Devices Market
Cardiovascular Devices
Cardiac Surgery Devices Market
Cardiovascular Devices
Neurovascular Stent Retrievers Market
Cardiovascular Devices
Cardiovascular Needle Market
Cardiovascular Devices
Percutaneous Coronary Intervention Market
Cardiovascular Devices
Surgical and Interventional Cardiology Devices Market
Cardiovascular Devices
Iliac Artery Stents Market
Cardiovascular Devices
Cryptogenic Stroke Treatment Market
Cardiovascular Devices
United Kingdom Cardiovascular Devices Market
Cardiovascular Devices
Balloon Catheters Market
Cardiovascular Devices
Pressure Infusion Cuffs Market
Cardiovascular Devices
Percutaneous Transluminal Coronary Angioplasty (PTCA) Balloon Catheters Market