
 Yellow Fever Treatment Market | 2026-2036
Yellow Fever Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Yellow Fever Treatment Market Outlook
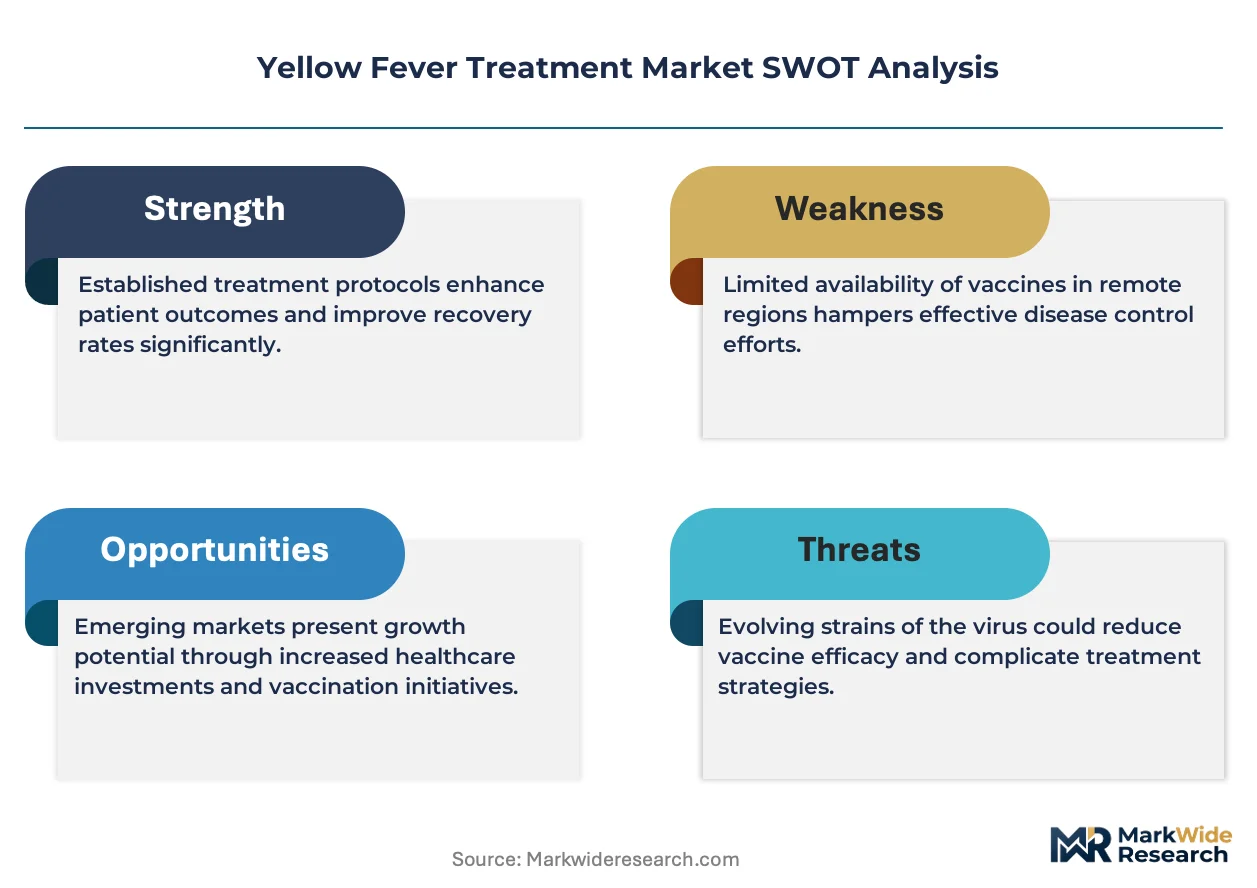
The Yellow Fever Treatment Market is rebalancing between premium vaccine tiers and commodity supportive care segments. Sanofi Pasteur SA dominates live-attenuated vaccine production through captive supply of yellow fever 17D strain manufacturing. BIOCRYST PHARMACEUTICALS, INC. differentiates via antiviral R&D intensity against flavivirus targets. Bio-Manguinhos anchors Latin American supply through in-house production capacity at Brazil's national immunization institute.
Yellow fever treatment encompasses prophylactic vaccination, antiviral intervention, and critical care management for acute hemorrhagic manifestations of Flavivirus infection. The 17D vaccine requires thermostable cold chain maintenance at two to eight degrees Celsius through lyophilized formulation. Vaccines command the dominant value share across product type segments due to preventive program scale in endemic corridors. Supportive care occupies narrower margin pools concentrated in hospital intensive care settings during urban outbreak response.
WHO prequalification standards govern international procurement eligibility for yellow fever vaccines distributed through Gavi and PAHO revolving funds. FDA and EMA pathways shape regulatory access for novel antiviral candidates entering clinical development. Brazil's ANVISA and Nigeria's national pharmaceutical regulator enforce import licensing for travel health and emergency stockpile deployment. Stakeholders must monitor evolving pandemic treaty negotiations affecting sovereign vaccine reserve obligations and technology transfer terms.
Market Dynamics
WHO prequalification standards are tightening thermostability requirements for yellow fever 17D vaccines, forcing manufacturers to reformulate lyophilized products or risk exclusion from Gavi procurement pools. This regulatory compression is redrawing competitive access between established suppliers and emerging national producers.
Growth Catalysts
- Preventive program scale:Government health departments in endemic African nations are expanding routine immunization schedules to cover previously unvaccinated adult cohorts in high-transmission corridors.
- Cold chain infrastructure:Solar-powered refrigeration networks deployed through PAHO revolving funds are extending vaccine reach into remote Amazon basin communities previously outside distribution range.
- EMA approval pathways:Accelerated assessment procedures for flavivirus antivirals are compressing clinical-to-market timelines for novel therapeutic candidates targeting hemorrhagic fever manifestations.
Market Restraints
- Single-strain supply concentration:Yellow fever 17D seed stock maintenance depends on a limited number of WHO-certified reference laboratories, creating biological raw material bottleneck risk.
- Thermostability input costs:Stabilizer excipients and specialized vial packaging for two-to-eight-degree Celsius maintenance consume disproportionate share of per-dose manufacturing expense.
- Substitution by personal protection:Vector control programs deploying Wolbachia-infected Aedes mosquitoes in Brazilian urban centers are reducing perceived urgency of vaccine uptake among low-risk travelers.
Strategic Opportunities
- Underpenetrated geography:Nigeria's national pharmaceutical regulator is streamlining import licensing for fractional-dose vaccination campaigns in densely populated Lagos-Ibadan corridor.
- Technology convergence:mRNA platform adaptation for flavivirus envelope protein expression is attracting platform-technology investors seeking pandemic preparedness diversification.
- Distribution innovation:Drone-based last-mile delivery pilot programs in Ghana are demonstrating viability for bypassing road infrastructure gaps in savanna outbreak zones.
Industry Challenges
- Fill-finish skill scarcity:Aseptic handling certification for live-attenuated virus products requires specialized training pipelines that African manufacturing partners struggle to staff.
- Compliance timeline compression:WHO prequalification re-inspection cycles have shortened from five to three years, straining quality documentation systems at national immunization institutes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Yellow Fever Treatment Market |
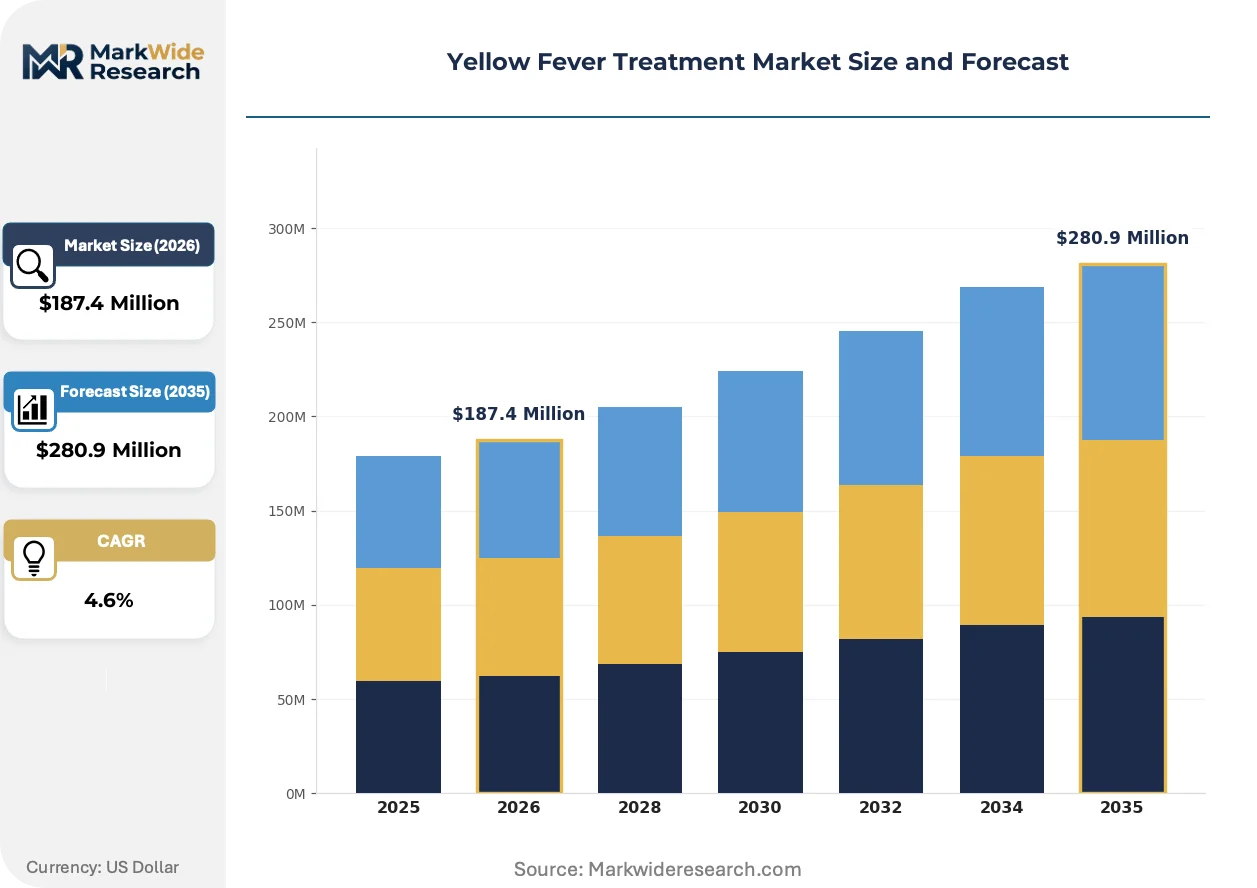
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $280.9 Million |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vaccines, Antivirals, Supportive Care, Immunoglobulins Administration Route: Intramuscular, Subcutaneous, Oral, Intravenous End User: Hospitals, Clinics, Research Laboratories, Government Health Departments Market Type: Public Health Programs, Private Clinics, International Health Organizations, Travel Health Services |
| Companies Covered | Sanofi Pasteur SA, Johnson & Johnson Services, Inc., Pfizer Inc., GlaxoSmithKline plc, Takeda Pharmaceutical Company Limited, Bayer AG, BIOCRYST PHARMACEUTICALS, INC., Tychan Pte. Ltd., Bio-Manguinhos, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Yellow Fever Treatment Market Strategic Shifts
Novel adjuvant formulations are entering clinical evaluation to extend dose sparing and reduce vial volume requirements for outbreak response stockpiles. These platform shifts promise to reshape manufacturing economics and distribution logistics simultaneously.
Heat-stable lyophilization technology is absorbing development resources across flavivirus vaccine portfolios. Sanofi Pasteur and Bio-Manguinhos are both retrofitting fill-finish lines to accommodate modified excipient chemistries that tolerate thirty-day ambient temperature exposure. This thermostability advance is absorbing cold chain infrastructure investment that would otherwise flow into refrigerated transport fleet expansion.
EMA's revised guidelines on live-attenuated vaccine environmental risk assessment now mandate extended shedding studies for novel 17D substrain candidates. Manufacturers must submit aerosol dispersion data and primate neurovirulence profiles before centralized marketing authorization. Brazilian ANVISA has aligned its import licensing with these EMA standards, forcing Latin American applicants to duplicate European dossier preparation.
Hospital procurement of antiviral stockpiles is consolidating under centralized ministry-of-health tendering in West African outbreak-prone nations. Previously fragmented state-level purchasing is yielding to national strategic reserve management with pre-positioned supply agreements. Ghana's health service pioneered this centralization model, with Nigeria's national pharmaceutical regulator now drafting comparable framework legislation.
Yellow Fever Treatment Market Segmentation
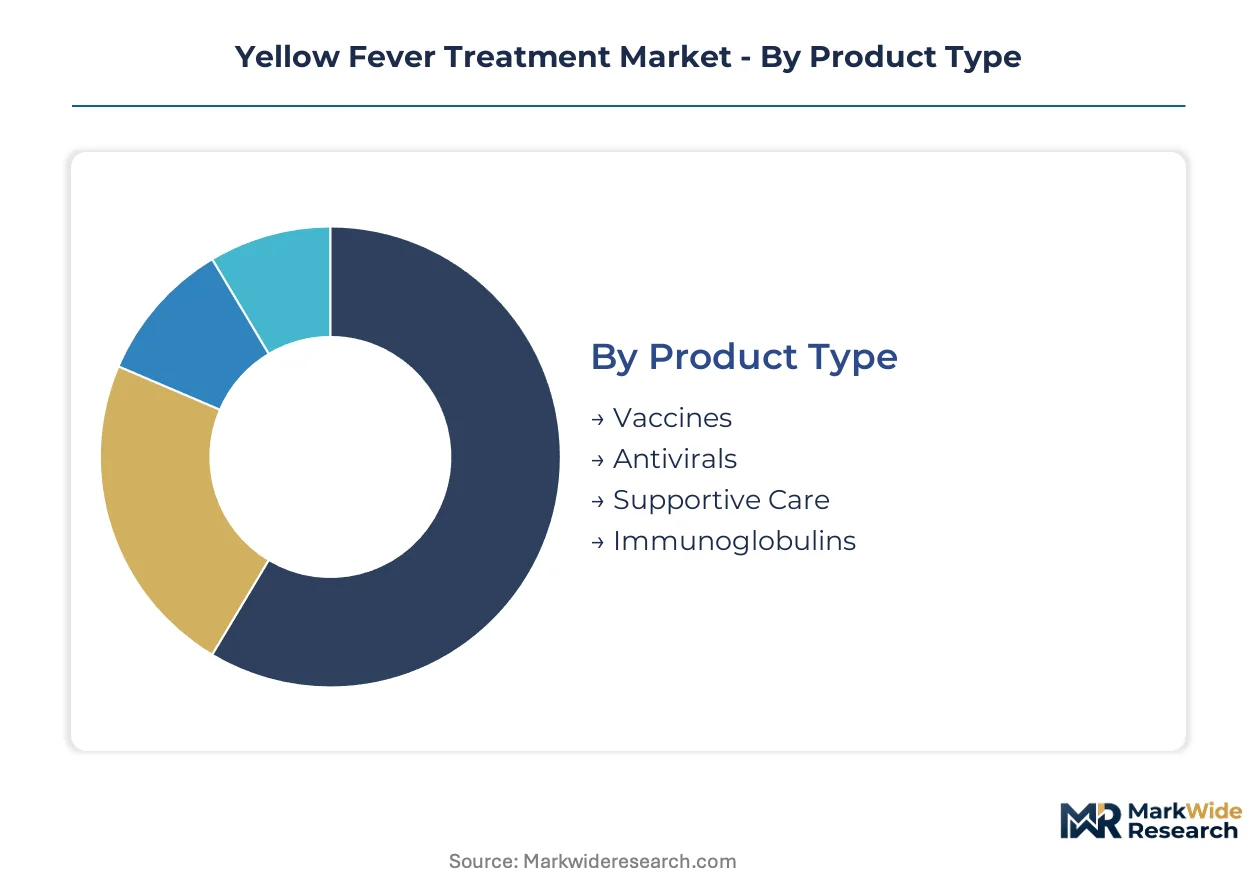
Yellow fever treatment segments split sharply between preventive mass deployment and acute intervention niches. Procurement patterns diverge across WHO prequalified supply chains, national immunization programs, and hospital-based critical care. Understanding these fault lines clarifies where manufacturing investment and distribution infrastructure concentrate.
Product Type:
Standardization dominates at the vaccine tier while antivirals and supportive care permit limited formulation customization for outbreak protocols.
- Vaccines:Live-attenuated 17D strain products require lyophilized thermostable formulations maintaining potency at two-to-eight degrees Celsius. Demand concentrates in Brazil's Amazon basin states and West African corridors where government health departments are scaling routine immunization to cover unvaccinated adult cohorts.
- Antivirals:Flavivirus-targeting small molecules and RNA polymerase inhibitors remain in clinical development with EMA accelerated assessment pathways compressing approval timelines. BIOCRYST PHARMACEUTICALS anchors R&D intensity in this segment through viral target prioritization.
- Supportive Care:Intravenous fluid resuscitation, blood product transfusion, and intensive care management address hemorrhagic fever manifestations in hospital settings.
- Immunoglobulins:Hyperimmune plasma derivatives provide passive immunization for exposed unvaccinated individuals in post-exposure prophylaxis protocols.
Most installed capacity flows through Vaccines. Expansion is steepest in Antivirals.
Administration Route:
Cost tier separation runs from single-dose intramuscular deployment to multi-dose intravenous critical care delivery.
- Intramuscular:Standard delivery for 17D vaccine doses in mass immunization campaigns with deltoid or anterolateral thigh placement.
- Subcutaneous:Alternative route for fractional-dose vaccination in outbreak response when antigen sparing is prioritized.
- Oral:Limited application for antiviral candidates in development, though flavivirus blood-brain barrier penetration challenges oral bioavailability.
- Intravenous:Critical care administration for antiviral infusion and supportive hemodynamic management in severe hemorrhagic presentations.
Volume concentration sits with Intramuscular. Margin expansion is climbing fastest in Intravenous.
End User:
Customer type fragmentation separates centralized government procurement from fragmented private clinic purchasing.
- Hospitals:Tertiary centers manage acute hemorrhagic fever cases with intensive care capacity and blood bank access.
- Clinics:Primary care and travel health facilities administer pre-travel vaccination and initial case detection.
- Research Laboratories:WHO-certified reference facilities maintain 17D seed stocks and conduct neurovirulence testing for substrain qualification.
- Government Health Departments:National immunization institutes in endemic African nations and Brazil's Bio-Manguinhos anchor public procurement scale.
Procurement volume concentrates in Government Health Departments. Capability investment is expanding most quickly in Research Laboratories.
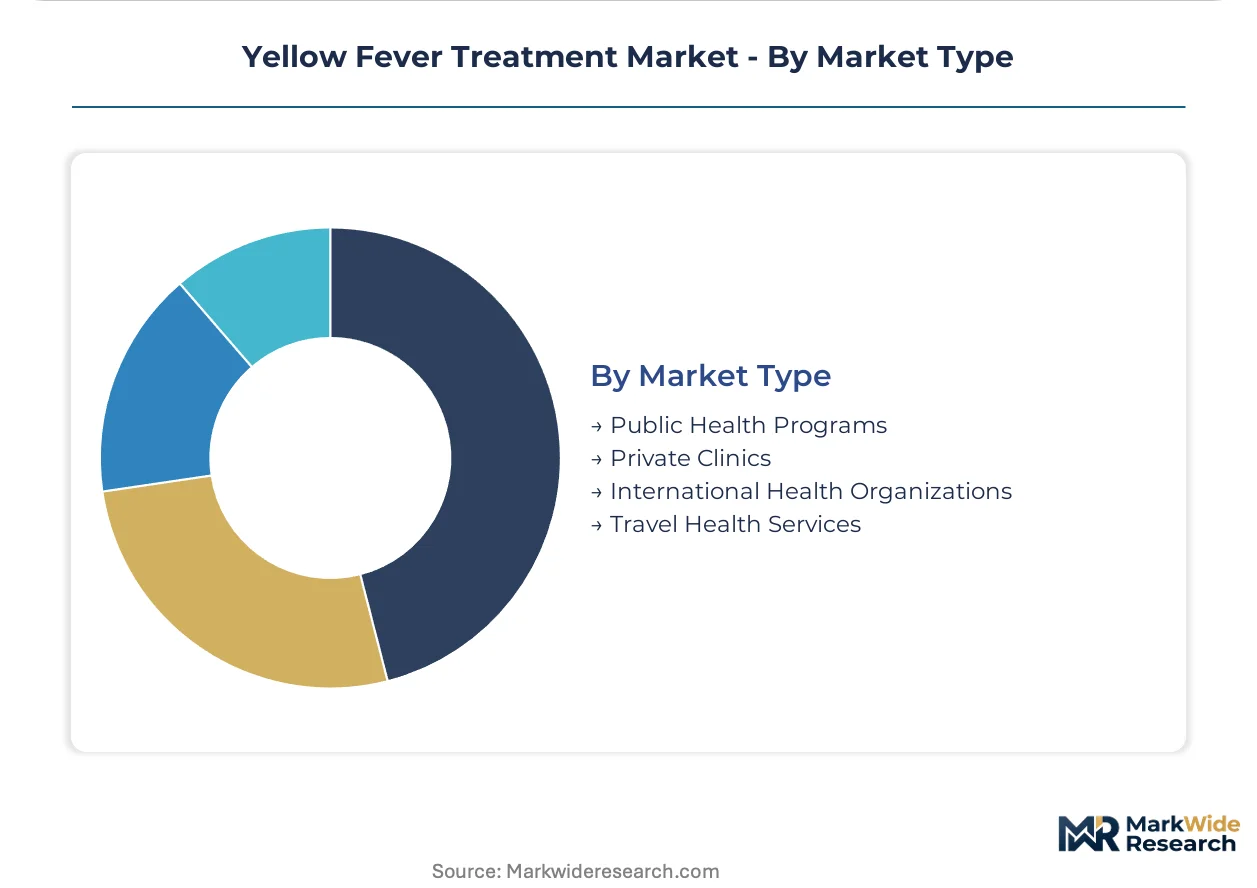
Market Type:
Application maturity varies from decades-established public health programs to emerging travel health commercial channels.
- Public Health Programs:Routine immunization schedules and reactive outbreak campaigns in endemic regions with Gavi and PAHO revolving fund financing.
- Private Clinics:Travel health services in non-endemic countries serving pre-departure vaccination for tourists and business travelers.
- International Health Organizations:WHO strategic stockpile management and emergency deployment coordination through prequalified supplier networks.
- Travel Health Services:Airport-based vaccination clinics and occupational health programs for mining and agricultural expatriates.
Supply commitment flows predominantly through Public Health Programs. Commercial development is gaining share fastest in Travel Health Services.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil's Bio-Manguinhos immunization institute anchors the deepest technical workforce concentration for yellow fever vaccine production outside Europe. West African regulatory capacity concentrates in Nigeria's national pharmaceutical authority. WHO-certified reference laboratory networks span Senegal, Colombia, and Thailand.
Brazil
Amazon basin states drive vaccine procurement volume through PAHO revolving fund financing. ANVISA aligns import licensing with EMA environmental risk assessment standards for live-attenuated products. Bio-Manguinhos in Rio de Janeiro retrofits fill-finish lines for thermostable lyophilization formats.
Nigeria
The Lagos-Ibadan corridor presents underpenetrated demand for fractional-dose vaccination campaigns in dense urban settlements. The national pharmaceutical regulator streamlines emergency import licensing for outbreak response stockpiles. Northern savanna states host drone-based last-mile delivery pilots bypassing road infrastructure gaps.
Senegal
Pasteur Institute Dakar maintains WHO-certified 17D seed stock reference capacity for West African manufacturing partners. The country's national immunization program scales routine adult cohort coverage through Gavi procurement channels. Dakar's biomedical research cluster conducts neurovirulence testing for substrain qualification protocols.
Colombia
Orinoco basin municipalities expand cold chain reach through solar-powered refrigeration networks. The national health institute enforces thermostability documentation for vaccine prequalification submissions. Bogotá-based procurement offices coordinate Andean regional stockpile positioning.
Thailand
Research laboratories in Bangkok specialize in flavivirus antiviral development for hemorrhagic fever indications. The national regulatory pathway accommodates EMA-aligned accelerated assessment procedures for novel therapeutic candidates. Thai manufacturing partners supply stabilizer excipients to regional lyophilization facilities.
Yellow Fever Treatment Market Competitive Environment
Top-tier vendors anchor vaccine production through captive 17D strain manufacturing, while mid-tier antiviral developers concentrate R&D investment against flavivirus targets. The competitive structure splits between established immunization institutes with WHO prequalification status and platform-technology entrants pursuing mRNA adaptation. Two strategic archetypes dominate: thermostability-focused reformulators and outbreak-response logistics specialists. Capacity expansion and technology licensing represent the dominant competitive moves as regulatory timelines compress.
Within the established supplier tier, Sanofi Pasteur SA and Bio-Manguinhos exemplify contrasting geographic anchoring strategies for endemic market access. BIOCRYST PHARMACEUTICALS, INC. occupies a position representing antiviral R&D intensity against viral polymerase targets. These three entities collectively illustrate the market's bifurcation between preventive manufacturing scale and therapeutic development depth.
| Leading Market Players |
|---|
| Sanofi Pasteur SA |
| Johnson & Johnson Services, Inc. |
| Pfizer Inc. |
| GlaxoSmithKline plc |
| Takeda Pharmaceutical Company Limited |
| Bayer AG |
| BIOCRYST PHARMACEUTICALS, INC. |
| Tychan Pte. Ltd. |
| Bio-Manguinhos |
| Others |
Value Chain & Pricing Dynamics
Lyophilized stabilizer excipient costs cascade through yellow fever vaccine manufacturing into three-tier pricing structure across premium, standard, and economy levels. WHO prequalification tiers segment procurement pools, with thermostability-certified products commanding differential access to Gavi financing against commodity stockpiles.
Pricing Analysis
Bundled cold chain logistics separate premium-tier vaccine supply from unbundled vial-only procurement in economy segments. Price differentiation hinges on WHO prequalification status and thermostability certification grade, with EMA-aligned manufacturers capturing brand premiums against national immunization institute products. Cost compression in standard-tier lyophilization is intensifying because stabilizer chemistry patent expirations are democratizing formulation access. Government health departments in endemic African nations exhibit highest price sensitivity, while PAHO revolving fund purchasers prioritize supply security over unit cost.
Supply Chain Analysis
17D seed stock maintenance rests on WHO-certified reference laboratories concentrated in Senegal, Thailand, and France. Manufacturing draws from specialized bovine serum albumin, sucrose stabilizer chemistries, and borosilicate vial packaging. Single-source vulnerability permeates live-attenuated virus fill-finish capacity, where aseptic handling certification scarcity constrains qualified facility expansion. Distribution runs through PAHO and Gavi revolving funds into national immunization institute cold chain networks, with last-mile drone pilots emerging in Ghana and Nigeria.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunity concentrates in thermostable lyophilization technology licensing, as heat-stable formulation investments reduce per-dose cold chain burden across endemic corridors.
For Market Incumbents: Anchor WHO prequalification status through accelerated compliance with tightened three-year re-inspection cycles. Sanofi Pasteur SA and Bio-Manguinhos should deepen captive 17D seed stock control against emerging mRNA platform substitution threats. Thermostability retrofit investments at Rio de Janeiro fill-finish lines defend margin position against fractional-dose competitors.
For New Entrants and Emerging Players: EMA accelerated assessment pathways for flavivirus antivirals open a window for BIOCRYST PHARMACEUTICALS and platform-technology entrants to capture hemorrhagic fever therapeutic share. Target underpenetrated Lagos-Ibadan corridor fractional-dose campaigns through streamlined ANVISA-aligned import licensing. Position via drone-based last-mile distribution partnerships with Ghana Health Service infrastructure.
For Investors and Strategic Acquirers: Asymmetric upside sits with mRNA platform adapters pursuing pandemic preparedness diversification into flavivirus envelope protein expression. Long-term viability frames around thermostability IP consolidation over a multi-year horizon. Acquisition target archetype: national immunization institutes with WHO prequalification pipeline and captive 17D substrain qualification capability. Watch EMA environmental risk assessment guideline revisions as inflection signal for shedding study burden and neurovirulence testing cost escalation.
| Strategic Initiative | Industry Significance |
|---|---|
| Thermostable Lyophilization Retrofit | Bio-Manguinhos extends ambient temperature tolerance to thirty days, reducing Amazon basin cold chain infrastructure investment. |
| EMA Accelerated Assessment Pathway | BIOCRYST PHARMACEUTICALS compresses antiviral clinical-to-market timelines for hemorrhagic fever indications. |
| Drone-Based Last-Mile Distribution | Ghana Health Service pilots bypass savanna road infrastructure gaps for outbreak response stockpile positioning. |
| Fractional-Dose Regulatory Streamlining | Nigeria's national pharmaceutical regulator accelerates Lagos-Ibadan corridor adult cohort coverage campaigns. |
| mRNA Platform Technology Adaptation | Platform-technology investors diversify pandemic preparedness portfolios into flavivirus envelope protein expression. |
Study Parameters
Multiple input streams — regulatory filing databases, procurement tender records, and cold chain infrastructure investment disclosures — were reconciled across primary interviews with WHO prequalification officers, national immunization program directors, and hospital procurement managers. Secondary validation incorporated EMA assessment reports, PAHO revolving fund disbursement records, and ANVISA import licensing documentation. Bottom-up dose demand modeling and top-down vaccine market sizing were triangulated for convergence.
Historical procurement volume trajectories were cross-referenced against expert panel inputs from endemic region health economists. Segmentation dimensions spanned product type, administration route, end user archetype, and market type across the analysis window. CAGRs were derived from epidemiological burden projections and immunization schedule expansion policies. Forecast inputs incorporated Gavi financing commitment cycles and PAHO stockpile rotation protocols.
Revisions become necessary when WHO prequalification standards tighten beyond current thermostability thresholds or when pandemic treaty negotiations alter sovereign vaccine reserve obligations. Forecasts reflect documented assumptions on regulatory timeline compression and fractional-dose campaign adoption rates. Regulatory guideline shifts, seed stock contamination events, and vector control program efficacy warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Treatment
Asthma Treatment Market
Medical Treatment
US Direct Anterior Approach (Total Hip Replacement) Market
Medical Treatment
Cleft Lip Surgery Market
Medical Treatment
Pelvic Organ Prolapse Repair Market
Medical Treatment
Urea Cycle Disorders Treatment Market
Medical Treatment
Radioactive Iodine Ablation Therapy Market
Medical Treatment
Tetanus Treatment Market
Medical Treatment
Burns Treatment Market
Medical Treatment
Gallbladder Treatment Market
Medical Treatment
Rabies Treatment Market
Medical Treatment
Ventral Hernia Treatment Market
Medical Treatment
Hypercalcemia Treatment Market
Medical Treatment
Vulvodynia Treatment Market
Medical Treatment
Myasthenia Gravis Treatment Market
Medical Treatment
Scoliosis Management Market
Medical Treatment
Endovenous Laser Therapy Market