
 Biomedical Temperature Sensors Market | 2026-2036
Biomedical Temperature Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
Biomedical Temperature Sensors Market Outlook
Software-defined calibration and remote diagnostic subscription layers is restructuring how biomedical temperature sensor vendors capture lifetime value from hospital clients. TE Connectivity leverages its sensor-to-cloud integration capabilities to sustain recurring revenue streams across acute care networks. Honeywell International anchors its position through backward integration into MEMS fabrication, controlling cost structures for high-volume thermistor production. Texas Instruments Incorporated competes on semiconductor-level precision, extending its analog front-end expertise into clinical-grade signal conditioning.
Biomedical temperature sensors are transduction devices that convert thermal energy into electrical signals with clinical-grade accuracy, typically achieving ±0.1°C precision through platinum thin-film elements or negative temperature coefficient ceramic oxides, and they serve to enable continuous patient thermoregulation monitoring, equipment thermal protection, and laboratory protocol compliance. Infrared sensors lead the product type landscape due to their non-invasive deployment in neonatal and isolation settings, while wireless technology within the technology dimension represents the fastest-expanding margin pool as hospitals phase out tethered bedside configurations. The end user segmentation shows diagnostic labs occupying mature, price-sensitive demand, whereas homecare channels are attracting new entrant investment on the strength of remote patient monitoring reimbursement pathways.
The FDA governs clinical accuracy claims and cybersecurity post-market obligations for connected temperature devices, while ISO 13485 quality management standards shape supplier qualification thresholds for OEM sensor procurement. The EU MDR and CE marking requirements impose additional biocompatibility and electrical safety testing burdens on manufacturers seeking European market access. Stakeholders must monitor how converging cybersecurity mandates and homecare reimbursement expansion will reshape R&D prioritization between clinical precision and consumer-grade connectivity architectures.
Market Dynamics
The migration toward wireless-enabled temperature monitoring architectures is compressing product lifecycles and forcing sensor vendors to restructure R&D budgets around cybersecurity compliance rather than pure precision engineering.
Growth Catalysts
- Non-contact infrared protocols:Infection control mandates in acute care facilities are accelerating replacement of contact-based thermometry with infrared systems for neonatal and isolation ward workflows.
- FDA cybersecurity guidance:Post-market surveillance obligations for connected medical devices are compelling hospitals to standardize on wireless platforms with embedded encryption and remote diagnostic capabilities.
- Remote patient monitoring reimbursement:CMS and private payers in the United States are expanding coverage for home-based temperature tracking, opening new channel economics for disposable sensor formats.
Market Restraints
- Platinum thin-film input costs:Precious metal price volatility constrains margin stability for manufacturers dependent on RTD elements achieving clinical-grade precision.
- MEMS foundry concentration:Fabrication capacity for thermistor-grade ceramic oxides clusters in East Asian contract manufacturers, creating single-source vulnerability for high-volume OEMs.
- EU MDR biocompatibility testing:Extended validation timelines for CE marking are delaying European market entry and freezing working capital in regulatory compliance.
Strategic Opportunities
- Homecare channel expansion:Post-acute monitoring programs in Germany and Japan are creating first-mover advantages for vendors with cloud-integrated disposable patches.
- AI-enabled predictive thermoregulation:Machine learning convergence with continuous temperature streaming is enabling sepsis early-warning systems in ICU settings.
- ISO 13485 supplier qualification:Quality management certification gaps among component vendors create acquisition targets for integrated platform builders.
Industry Challenges
- Embedded firmware engineering talent:Shortage of developers with dual competency in clinical signal processing and cybersecurity hardening is throttling product roadmap velocity.
- Legacy bedside infrastructure integration:Hospital IT departments face fragmented API standards when connecting new wireless sensors to existing EMR architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Biomedical Temperature Sensors Market |
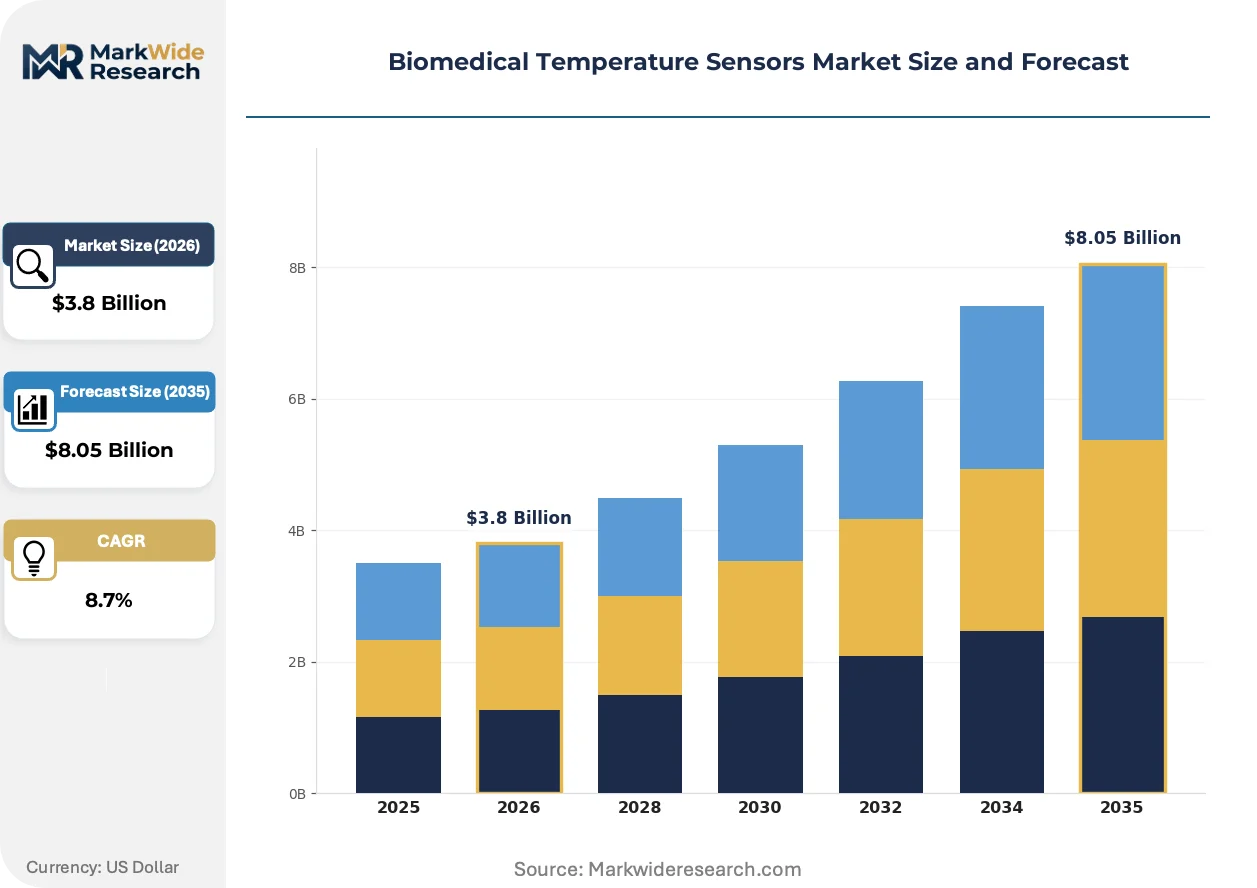
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Infrared Sensors, Thermocouples, Thermistors, Resistance Temperature Detectors End User: Hospitals, Homecare, Diagnostic Labs, Research Institutions Technology: Contact Measurement, Non-Contact Measurement, Wireless Technology, Analog Technology Application: Patient Monitoring, Equipment Calibration, Laboratory Research, Clinical Trials |
| Companies Covered | TE Connectivity, Honeywell International, Amphenol Advanced Sensors, Texas Instruments Incorporated, Analog Devices, STMicroelectronics, GE Healthcare, Smiths Medical, First Sensor, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Biomedical Temperature Sensors Market Strategic Shifts
Sensor-to-cloud integration is collapsing the traditional boundary between hardware procurement and software subscription, enabling vendors to capture recurring revenue through calibration-as-a-service models.
Multi-sensor fusion architectures are unifying temperature, SpO2, and respiratory rate into single wearable form factors. Cardiology departments at major US health systems are piloting these consolidated patches for continuous monitoring of post-surgical patients. This unification is compressing the addressable market for standalone temperature probes while expanding total contract values for integrated platform vendors.
The EU AI Act's risk classification framework is redefining liability exposure for algorithmic temperature interpretation in diagnostic workflows. Manufacturers must now document training data provenance and performance drift monitoring for any AI-enhanced fever detection feature. Neonatal intensive care units in France and the Netherlands are demanding third-party conformity assessments before procurement, slowing adoption curves for unvalidated algorithms.
Hospital supply chain directors are consolidating vendor panels around full-stack temperature monitoring platforms rather than discrete sensor purchases. Group purchasing organizations are negotiating enterprise licenses spanning hardware, cloud storage, and predictive analytics. This concentration is most visible in the United States, where IDN consolidation has reduced the number of approved temperature sensor suppliers by half across the largest fifty health systems.
Biomedical Temperature Sensors Market Segmentation
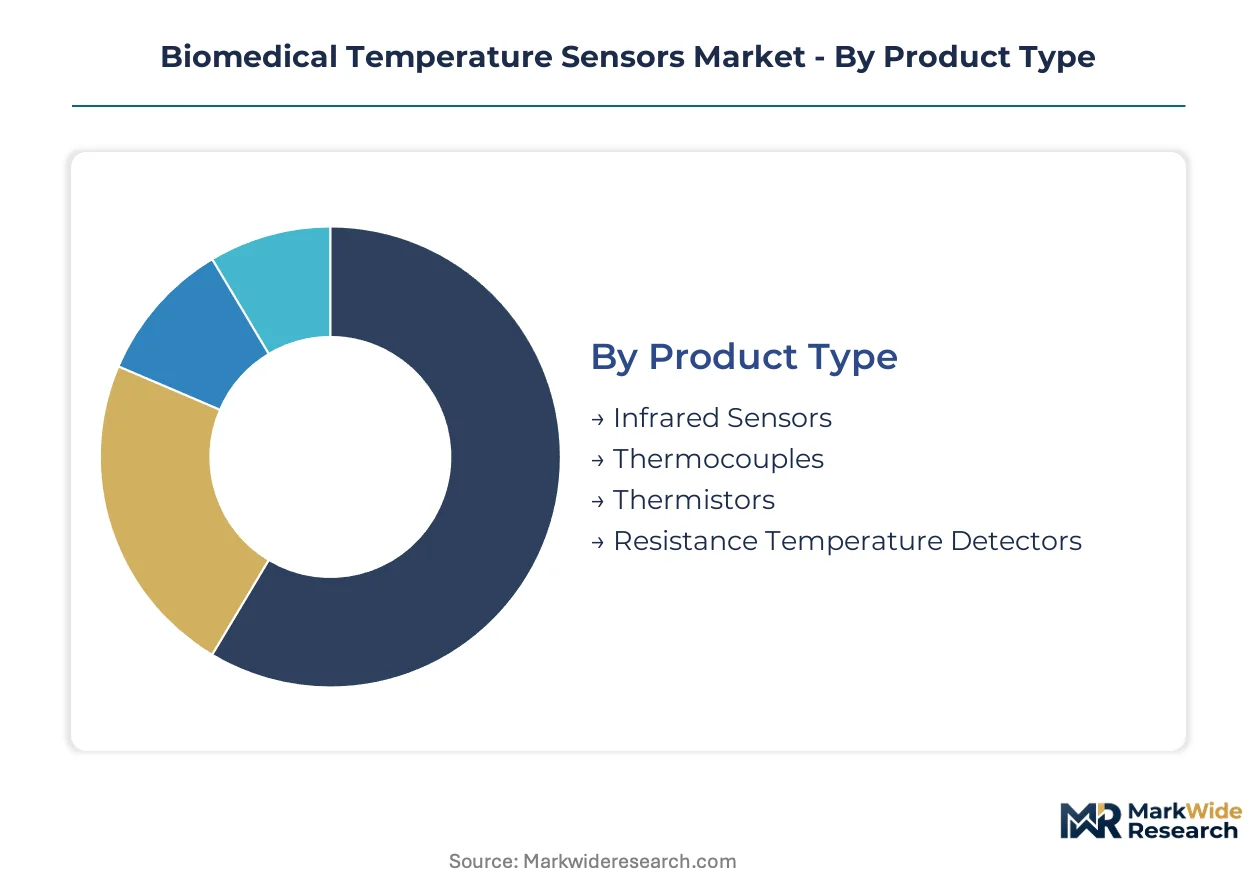
Biomedical temperature sensor procurement patterns diverge sharply across clinical settings. Hospital IT departments prioritize wireless integration and cybersecurity hardening, while diagnostic labs emphasize calibration stability and traceability to ISO 17025 standards.
Product Type:
Capital intensity clusters heavily in platinum thin-film deposition equipment for clinical-grade precision elements, while thermistor ceramic oxide fabrication demands lower upfront tooling but higher raw material working capital.
- Infrared Sensors:Pyroelectric detectors and thermopile arrays convert thermal radiation into voltage signals without patient contact. Neonatal intensive care units in the United States and isolation wards in Germany are standardizing on these systems to eliminate cross-contamination vectors from reusable probes.
- Thermocouples:Junctions of dissimilar metals generate temperature-dependent electromotive force through the Seebeck effect. Research institutions in Japan favor Type T copper-constantan configurations for cryogenic protocol compliance where platinum resistance elements fail.
- Thermistors:Ceramic oxide beads with negative temperature coefficient exhibit exponential resistance decay with heating.
- Resistance Temperature Detectors:Platinum thin-film elements wound on ceramic substrates deliver the ±0.1°C precision required for pharmaceutical stability testing.
Infrared sensors absorb the bulk of installed capacity in acute care networks; wireless-enabled RTD configurations are expanding most quickly into cloud-integrated homecare platforms.
End User:
Procurement authority and reimbursement pathways shape distinct purchasing behaviors across settings, with hospitals consolidating around enterprise platform contracts while homecare channels fragment across direct-to-consumer and remote patient monitoring program suppliers.
- Hospitals:Acute care networks deploy multi-parameter monitoring ecosystems where temperature serves as one input stream among SpO2, ECG, and respiratory rate. Infection control officers at major US health systems mandate non-contact protocols for emergency department triage.
- Homecare:Post-acute monitoring programs in Germany and Japan reimburse disposable patch sensors for chronic condition management. Cloud-integrated disposable formats with cellular backhaul are capturing first-mover advantages as CMS expands coverage codes.
- Diagnostic Labs:PCR thermal cyclers and incubators demand NIST-traceable calibration chains with documented uncertainty budgets.
- Research Institutions:Cryogenic storage monitoring and cell culture incubation require specialized probe configurations.
Hospitals command the largest procurement volumes by absolute dollar; homecare channels are gaining share fastest on reimbursement expansion and aging-in-place policy priorities.
Technology:
Engineering talent scarcity and firmware development costs concentrate in wireless architectures requiring embedded encryption, over-the-air updates, and FDA cybersecurity documentation.
- Wireless Technology:Bluetooth Low Energy and proprietary 2.4 GHz protocols transmit encrypted temperature streams to hospital gateways and home hubs. FDA post-market surveillance obligations are compelling manufacturers to embed remote diagnostic capabilities for firmware vulnerability patching.
- Non-Contact Measurement:Infrared thermometry eliminates probe sterilization cycles and disposable cover costs. Isolation ward workflows in France and the Netherlands mandate these systems for Ebola and respiratory pathogen containment protocols.
- Contact Measurement:Thermistor and RTD probes maintain dominance where sub-0.1°C precision is non-negotiable.
- Analog Technology:Voltage-output sensors persist in legacy bedside monitors requiring minimal IT integration.
Contact measurement retains the deepest installed base; wireless technology is climbing the fastest as hospitals phase out tethered configurations.
Application:
Regulatory burden and validation timelines vary dramatically, with clinical trials demanding GCP-compliant documentation chains while equipment calibration focuses on metrological traceability.
- Patient Monitoring:Continuous thermoregulation tracking enables early sepsis detection and anesthesia depth assessment. ICU departments at US academic medical centers are piloting AI-enabled predictive algorithms that flag temperature trajectory anomalies.
- Equipment Calibration:Autoclave validation, incubator qualification, and cold chain verification require reference-grade sensors with ISO 17025-accredited calibration certificates.
- Laboratory Research:Cell culture incubation and enzyme reaction kinetics demand stability and uniformity mapping.
- Clinical Trials:GCP-compliant temperature documentation supports investigational drug stability and patient safety endpoints.
Patient monitoring deploys the greatest sensor count across acute settings; equipment calibration generates the most recurring revenue through subscription-based validation services.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Boston's medical device corridor anchors North American demand for connected temperature monitoring platforms, with acute care networks along the US East Coast driving standardization on wireless-enabled architectures.
United States
Major health systems in Massachusetts and California are consolidating vendor panels around full-stack temperature monitoring platforms with embedded cybersecurity. FDA post-market surveillance obligations for connected devices compel hospitals to select wireless architectures with remote diagnostic capabilities. The Minneapolis-St. Paul metro area hosts concentrated procurement decision-making for integrated patient monitoring ecosystems.
Germany
Post-acute monitoring programs in Bavaria and Baden-Württemberg reimburse cloud-integrated disposable patch sensors for chronic condition management. EU MDR biocompatibility testing requirements extend validation timelines for CE marking, freezing working capital in regulatory compliance. The Munich medical technology cluster concentrates engineering talent for MEMS-grade thermistor fabrication.
Japan
Research institutions in the Kanto region favor Type T copper-constantan thermocouple configurations for cryogenic protocol compliance. METI aging-in-place policy priorities accelerate homecare channel investment for remote patient monitoring reimbursement pathways. The Osaka-Kobe industrial corridor maintains specialized foundry capacity for ceramic oxide thermistor production.
France
Neonatal intensive care units in Paris and Lyon demand third-party conformity assessments for AI-enhanced fever detection features under EU AI Act risk classification frameworks. ANSM biocompatibility standards shape supplier qualification thresholds for OEM sensor procurement. The Île-de-France region concentrates diagnostic lab demand for NIST-traceable calibration chains.
China
Domestic health systems in Shanghai and Beijing are phasing in non-contact infrared protocols for infection control in isolation ward workflows. NMPA medical device cybersecurity guidance pushes manufacturers toward wireless-enabled architectures with embedded encryption. The Yangtze River Delta hosts contract manufacturing capacity for high-volume thermistor-grade ceramic oxides.
Biomedical Temperature Sensors Market Competitive Environment
Capital-heavy producers compete with asset-light designers across the biomedical temperature sensor value chain, with foundry-dependent players facing margin pressure from precious metal input volatility. The vendor base clusters around three strategic archetypes: integrated platform builders capturing recurring software revenue, MEMS fabricators controlling upstream ceramic oxide supply, and semiconductor specialists extending analog front-end expertise into clinical-grade signal conditioning. Dominant competitive moves include backward integration into MEMS fabrication to secure captive thermistor supply and strategic partnerships with hospital IT departments for EMR architecture integration.
Among diversified industrial technology conglomerates, TE Connectivity and Honeywell International exemplify platform-scale archetypes with sensor-to-cloud integration capabilities, while Texas Instruments Incorporated occupies a position within the semiconductor precision tier. These three anchors represent distinct competitive vectors: TE Connectivity exemplifies recurring revenue capture through calibration-as-a-service models, Honeywell International demonstrates backward integration into MEMS fabrication for cost structure control, and Texas Instruments Incorporated extends analog semiconductor expertise into clinical-grade applications.
| Leading Market Players |
|---|
| TE Connectivity |
| Honeywell International |
| Amphenol Advanced Sensors |
| Texas Instruments Incorporated |
| Analog Devices |
| STMicroelectronics |
| GE Healthcare |
| Smiths Medical |
| First Sensor |
| Others |
Value Chain & Pricing Dynamics
Platinum thin-film price indices cascade through biomedical temperature sensor supply chains into three-tier pricing structures across premium, standard, and economy levels. Precious metal volatility compresses margins for RTD-dependent manufacturers while concentrating procurement power among hospital systems with enterprise-scale contracts.
Pricing Analysis
Margin tightening in clinical-grade sensor tiers reflects platinum input cost volatility and MEMS foundry concentration in East Asia. Pricing stratifies across premium, standard, and economy tiers based on ISO 13485 certification grade and volume scale, with diagnostic labs exhibiting highest price sensitivity and ICU procurement committees least sensitive due to infection control mandates. Cost-down pressure on disposable patch formats accelerates because CMS reimbursement expansion attracts commodity-grade competitors.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale health system demand while specialized distributors serve research institutions with low-volume, high-mix requirements. Ceramic oxide thermistor fabrication concentrates in China, Japan, and South Korea, with platinum thin-film deposition equipment anchored in Germany and the United States. Raw material dependencies span platinum group metals, high-purity alumina substrates, and medical-grade silicone encapsulants. Single-source vulnerability in MEMS foundry capacity creates structural risk. Distribution runs through group purchasing organizations consolidating vendor panels at major US health systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Biomedical temperature sensor supply chains face platinum foundry capacity constraints propping pricing power for backward-integrated manufacturers. MEMS fabrication bottlenecks and cybersecurity engineering scarcity reinforce incumbent advantages.
For Market Incumbents: Anticipate margin compression from wireless-enabled new entrants by securing captive MEMS foundry capacity in Japan or Germany. Hospital IT department partnership depth serves as the defensive lever against EMR integration fragmentation threatening platform stickiness. For New Entrants and Emerging Players: Group purchasing organization contract managers represent the fastest path to hospital system procurement panels. Homecare reimbursement expansion in Germany and Japan offers the most penetrable white-space, with cloud-integrated disposable patches enabling direct-to-patient subscription models bypassing traditional distribution. For Investors and Strategic Acquirers: Distressed-cycle entries favor ISO 13485-certified component suppliers with dormant hospital relationships in France and the Netherlands. Long-term viability hinges on cybersecurity firmware competency convergence with clinical signal processing. Watch FDA post-market surveillance enforcement intensity as inflection indicator for wireless platform valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into MEMS Fabrication | Captive ceramic oxide supply secures margin stability against East Asian foundry concentration. |
| Hospital System Partnership | Enterprise platform contracts with Massachusetts and California health systems lock out competitor access. |
| FDA Cybersecurity Documentation | Post-market surveillance compliance enables wireless architecture procurement at major US IDNs. |
| Software Companion Development | Calibration-as-a-service models transform hardware transactions into recurring revenue streams. |
| CE Marking Pathway | EU MDR biocompatibility validation opens Bavaria and Baden-Württemberg post-acute monitoring reimbursement. |
Study Parameters
Multi-period observation of platinum price indices, MEMS foundry utilization rates, and hospital procurement database entries anchored the trend analysis, supplemented by interviews with biomedical engineers, hospital purchasing committee members, GPO contracts managers, and FDA regulatory affairs specialists. Secondary validation drew from FDA 510(k) filings, CMS reimbursement code updates, ISO 13485 certification registries, and EU MDR notified body documentation. Bottom-up sensor shipment estimates triangulated against top-down health system capital expenditure surveys.
Segment-weighting across product type, technology architecture, end-user setting, and application intensity shaped the analytical framework over the projection horizon. Modeled dimensions included infrared versus contact measurement modalities, wireless versus tethered configurations, acute care versus homecare channels, and patient monitoring versus calibration applications. CAGRs derived from installed base replacement cycles and reimbursement expansion trajectories. Forecast inputs incorporated FDA cybersecurity guidance implementation timelines and EU AI Act risk classification adoption curves.
Caveats apply where platinum price spikes, MEMS foundry capacity constraints, or FDA enforcement intensity shifts could materially shift the outlook. Forecasts reflect assumptions about wireless technology adoption rates and homecare reimbursement expansion pace. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Urology Guidewires Market
Medical Devices
Photomedicine Technology Market
Medical Devices
Video-Guided Pericardial Access Device Market
Medical Devices
Breast Biopsy Marker Market
Medical Devices
Peri-Implantitis Market
Medical Devices
In Vitro Fertilization Monitoring System Market
Medical Devices
Medical Bionic Implant/Artificial Organs Market
Medical Devices
Surgical Mesh Market
Medical Devices
Tattoo Removal Lasers Market
Medical Devices
Middle East and Africa Non-Surgical Procedures Market
Medical Devices
China Ultrasound Devices Market
Medical Devices
Soft Tissue Release Systems Market
Medical Devices
Europe Ambulatory Infusion Pumps Market
Medical Devices
Global Endodontic Reparative Cement Market
Medical Devices
South Africa Aesthetic Devices Market
Medical Devices
Intrasaccular Embolization Systems Market