
 Wearable Artificial Organs Market | 2026-2036
Wearable Artificial Organs Market Size, Share, and Industry Trends Forecast 2026-2036
Wearable Artificial Organs Market Intelligence
Soft robotics and flexible printed circuit integration is reconfiguring how wearable artificial organs achieve conformal body contact and real-time physiological feedback. Medtronic leverages polymer-based actuator architectures to extend its cardiac assist portfolio into outpatient settings. Cochlear Ltd. anchors its product lineage through sustained R&D intensity in electrode-neural interface design. Abbott Laboratories competes via sensor miniaturization that enables continuous metabolite tracking without tethered power.
Wearable artificial organs constitute electromechanical systems engineered to replicate or augment native organ function through biomaterial interfaces, microprocessor-controlled feedback loops, and portable power architectures; these devices typically incorporate biocompatible membranes, wireless telemetry modules, and rechargeable energy cells to sustain therapeutic output outside clinical facilities. Heart assist devices occupy the dominant revenue position due to established reimbursement pathways and the acute clinical need among congestive heart failure patients awaiting transplant. Artificial kidneys represent the fastest-expanding category as silicon nanopore filtration membranes and sorbent-based regeneration systems reduce dependency on dialysis center infrastructure. Bionic limbs sustain mature margin pools through prosthetic socket customization and myoelectric control algorithms, though growth rates trail organ-replacement modalities.
The FDA breakthrough device program and the EU Medical Device Regulation (MDR) establish divergent compliance thresholds for clinical evidence and post-market surveillance, with MDR's stricter notified body requirements extending certification timelines for European market entry. Japan's PMDA operates an accelerated review pathway for orphan medical devices that reduces regulatory friction for novel wearable kidney and pancreas systems. Stakeholders must monitor evolving software-as-medical-device classifications that could reclassify AI-enabled predictive algorithms in wearable organs as distinct regulatory submissions.
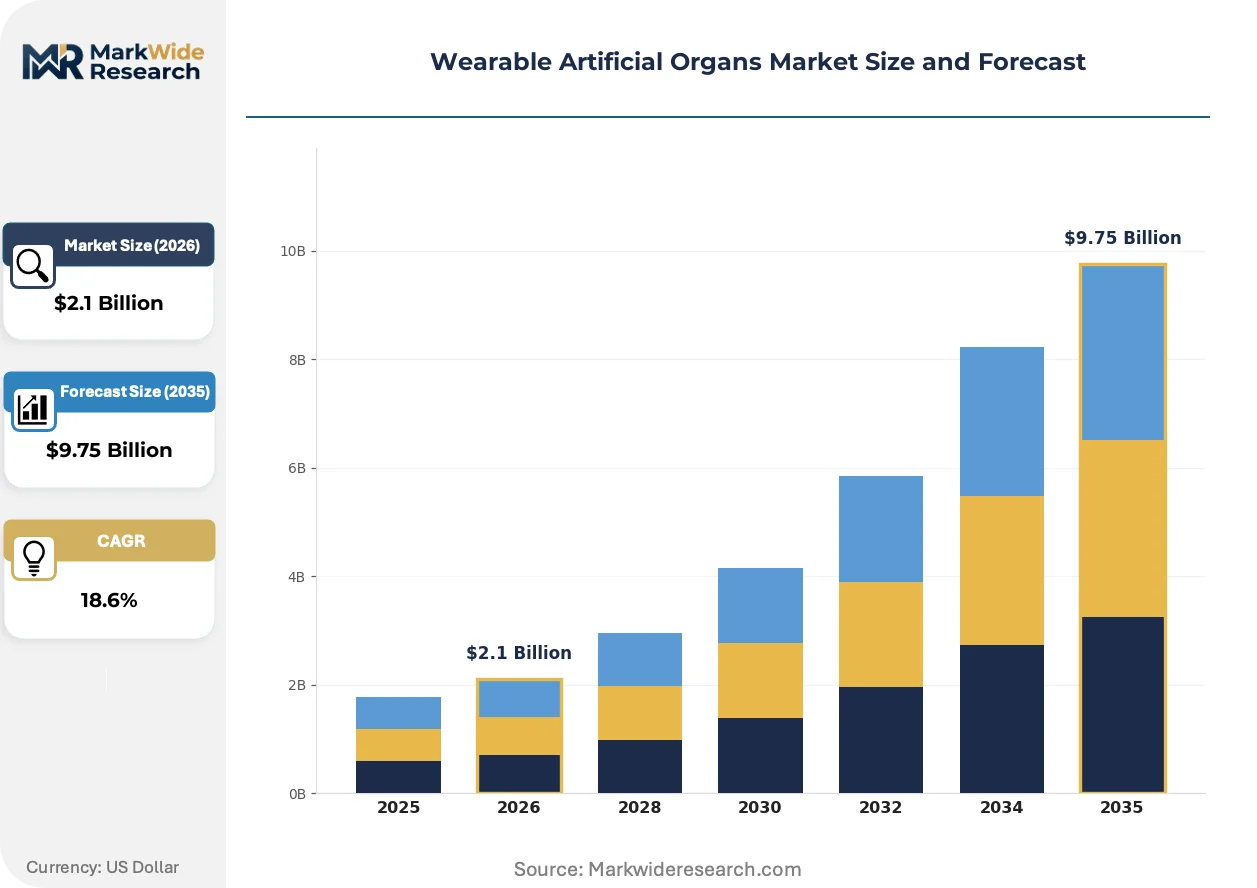
Market Dynamics
Soft robotics integration and flexible printed circuit architectures are compressing device form factors while expanding ambulatory care eligibility, forcing manufacturers to reconfigure power management and biocompatibility testing protocols simultaneously.
Growth Catalysts
- Silicon nanopore filtration membranes:Dialysis centers in Germany and Japan are accelerating procurement of wearable kidney systems that eliminate tethered infrastructure.
- FDA breakthrough device designation:The pathway compresses commercial timelines for implantable-wearable hybrids targeting congestive heart failure.
- Reimbursement framework maturation:Chronic disease management policies in the United States now cover outpatient cardiac assist device deployment.
Market Restraints
- Lithium-ion cell supply concentration:Portable power architectures depend on East Asian battery chemistry suppliers exposed to export control volatility.
- EU MDR notified body capacity:Stricter clinical evidence requirements extend certification timelines for European market entry by 12-18 months.
- Biocompatibility testing costs:Polymer-based actuator materials require extended ISO 10993 cytotoxicity validation that inflates R&D burn rates.
Strategic Opportunities
- Home-based dialysis substitution:Sorbent-based regeneration systems create white space for patients in rural United States counties lacking clinic infrastructure.
- AI-enabled predictive algorithms:Software-as-medical-device reclassification by FDA could unlock new revenue streams in glucose forecasting for wearable pancreas systems.
- Electrode-neural interface convergence:Cochlear implant manufacturers are extending expertise into vestibular restoration and sleep apnea neurostimulation.
Industry Challenges
- Embedded systems firmware talent scarcity:Real-time physiological feedback loops require specialized engineers conversant in both biomedical signal processing and low-power wireless stacks.
- Wireless telemetry module certification:FCC Part 15 and EU RED compliance for body-area networks demands parallel testing protocols that fragment engineering resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wearable Artificial Organs Market |
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $9.75 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Heart Assist Devices, Artificial Kidneys, Bionic Limbs, Wearable Pancreas Technology: Biomaterials, Microelectronics, Sensors, Actuators End User: Healthcare Providers, Patients, Research Institutions, Rehabilitation Centers Application: Chronic Disease Management, Surgical Procedures, Patient Monitoring, Rehabilitation |
| Companies Covered | Medtronic, Cochlear Ltd., Ekso Bionics, Boston Scientific Corporation, Abbott Laboratories, Zhejiang Nurotron Biotechnology Co., Ltd., AWAK Technologies, Touch Bionics, Second Sight Medical Products, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wearable Artificial Organs Market Strategic Shifts & Innovations
Biomaterial interfaces and microprocessor-controlled feedback loops are converging to enable continuous therapeutic output outside clinical facilities, compressing the boundary between implantable and wearable device categories.
Flexible printed circuit integration with polymer-based actuator architectures is digitizing how cardiac assist devices achieve conformal thoracic contact. Outpatient cardiology clinics in the United States are adopting these systems within six-month procurement cycles. The technology is digitizing patient monitoring workflows by embedding multi-lead ECG telemetry directly into garment-integrated pumps.
Japan's PMDA orphan medical device accelerated review pathway is compressing regulatory friction for novel wearable kidney systems. Manufacturers file parallel submissions with FDA breakthrough designation to synchronize commercial launches. Hemodialysis device categories face the steepest timeline compression as silicon nanopore filtration meets PMDA's unmet medical need criteria.
Hospital purchasing committees are unbundling after-sales service contracts from capital equipment leases. Dialysis center networks now procure wearable organ maintenance through third-party clinical engineering firms. This restructuring is most visible in German outpatient nephrology chains where technical service margins now exceed hardware financing spreads.
Wearable Artificial Organs Market Segmentation
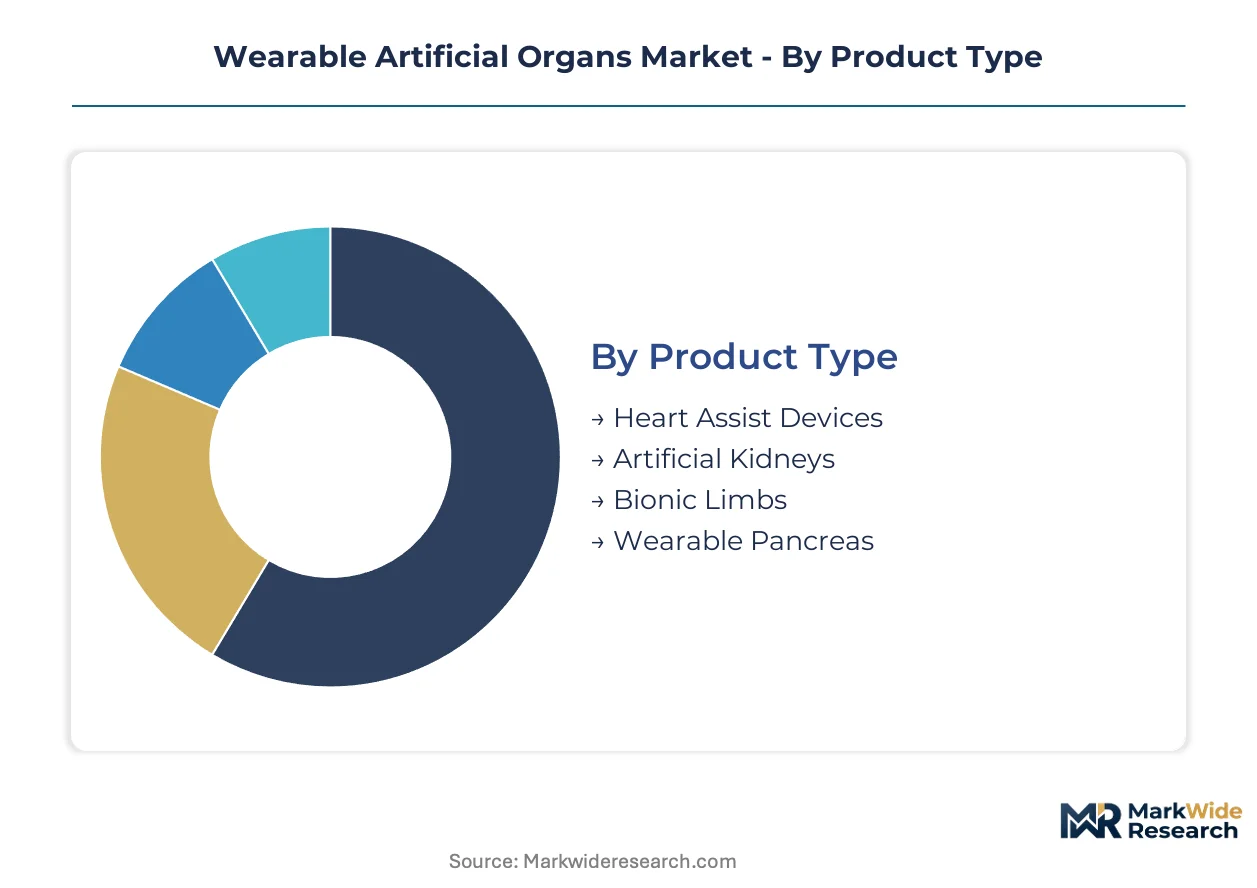
Segmentation in wearable artificial organs determines procurement cycles, reimbursement pathways, and R&D resource allocation. Device categories exhibit starkly different replacement timelines and regulatory burdens.
Product Type:
Replacement cycles range from 5-7 years for mechanical heart systems to 2-3 years for filtration membrane cartridges in kidney units.
- Heart Assist Devices:Polymer-based actuator architectures and rechargeable energy cells sustain ventricular support functions outside transplant centers. Demand concentrates in United States outpatient cardiology clinics where congestive heart failure patients await donor availability.
- Artificial Kidneys:Silicon nanopore filtration membranes and sorbent-based regeneration systems eliminate tethered dialysis infrastructure. German and Japanese dialysis centers are accelerating procurement as reimbursement frameworks mature for home-based renal replacement.
- Bionic Limbs:Myoelectric control algorithms and prosthetic socket customization sustain mature margin pools in rehabilitation networks.
- Wearable Pancreas:Continuous metabolite tracking via sensor miniaturization targets Type 1 diabetes populations in research-intensive healthcare systems.
Heart assist devices dominate installed base. Artificial kidneys are where expansion concentrates.
Technology:
Cost tiers separate materials-science components from semiconductor-intensive subsystems, with sensor modules commanding premium pricing against commodity biomaterials.
- Biomaterials:Biocompatible membranes and polymer architectures require extended ISO 10993 cytotoxicity validation that inflates development timelines.
- Microelectronics:Microprocessor-controlled feedback loops integrate wireless telemetry for real-time physiological monitoring in ambulatory settings.
- Sensors:Miniaturized metabolite detection enables continuous glucose forecasting without tethered power, attracting FDA software-as-medical-device scrutiny.
- Actuators:Soft robotics and flexible printed circuit integration achieve conformal body contact for cardiac assist garments.
Microelectronics capture the steepest expansion trajectory. Biomaterials anchor volume production.
End User:
Customer type determines contract structure, with institutional procurement favoring capital leases and patient-direct channels requiring retail financing infrastructure.
- Healthcare Providers:Hospital purchasing committees unbundle after-sales service from equipment leases, shifting technical service margins to third-party clinical engineering firms.
- Patients:Home-based deployment demands portable power architectures and patient-operated maintenance protocols, concentrating in United States counties lacking clinic infrastructure.
- Research Institutions:Orphan medical device pathways in Japan and breakthrough designations in the United States synchronize commercial launch timelines for novel systems.
- Rehabilitation Centers:Outpatient procurement cycles compress to six months for garment-integrated cardiac pumps with embedded ECG telemetry.
Healthcare providers dominate installed base. Patients are where expansion concentrates.
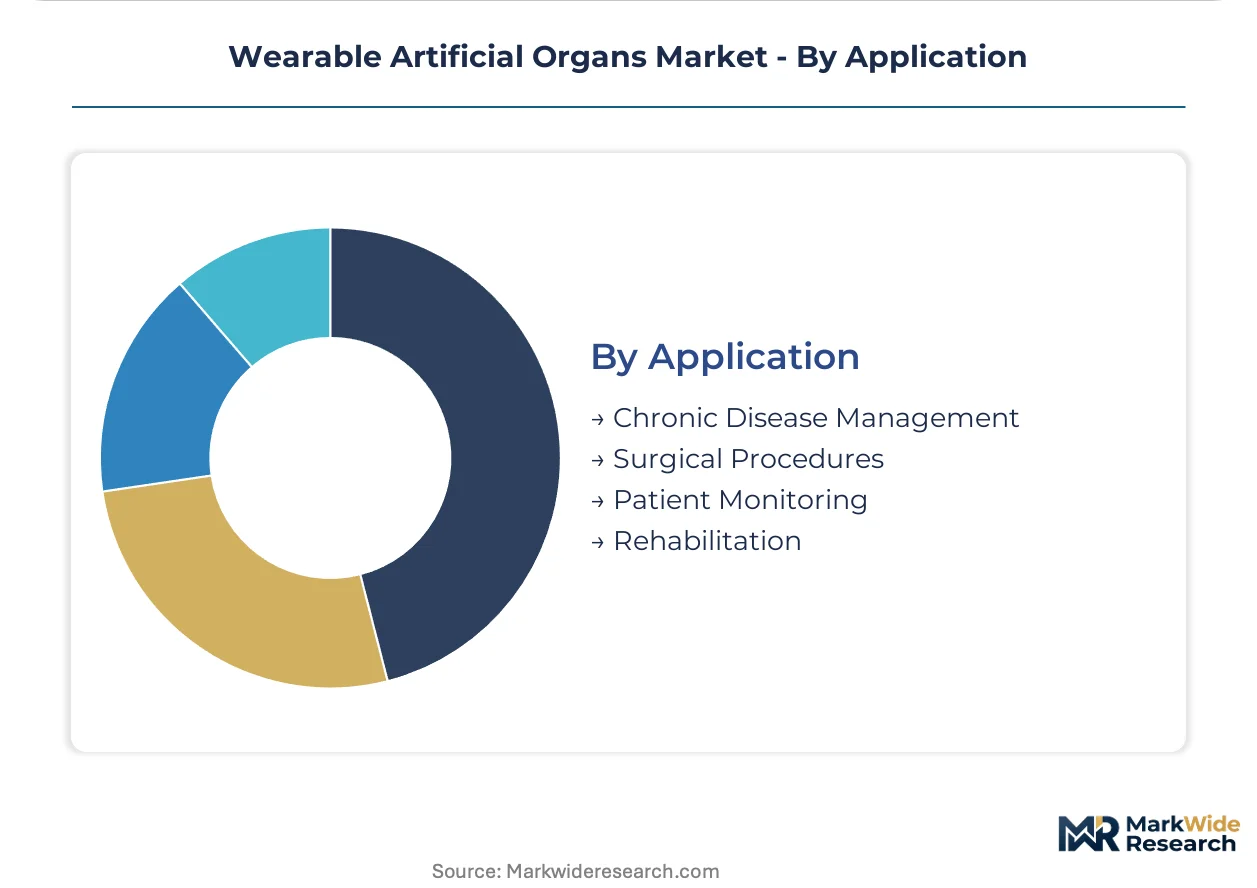
Application:
Maturity gradients separate established chronic disease management from emerging predictive monitoring applications.
- Chronic Disease Management:Congestive heart failure and end-stage renal disease drive recurring revenue through device servicing and consumable replacement.
- Surgical Procedures:Temporary circulatory support during high-risk interventions requires rapid deployment protocols in tertiary cardiac centers.
- Patient Monitoring:AI-enabled predictive algorithms embedded in wearable systems face evolving regulatory classification as distinct software submissions.
- Rehabilitation:Neurostimulation and vestibular restoration extend cochlear implant expertise into sleep apnea and balance disorder populations.
Chronic disease management dominates installed base. Patient monitoring is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dialysis centers and cardiac rehabilitation clinics concentrate procurement in jurisdictions with mature reimbursement frameworks. The United States, Germany, and Japan anchor demand through distinct regulatory pathways and clinical infrastructure configurations.
United States
Outpatient cardiology clinics deploy ventricular assist devices for congestive heart failure patients awaiting transplant. FDA breakthrough device designation compresses commercial timelines for implantable-wearable hybrids. The Greater Boston cluster houses clinical engineering firms that unbundle after-sales service from capital equipment leases.
Germany
Outpatient nephrology chains accelerate procurement of wearable kidney systems with silicon nanopore filtration. EU MDR notified body requirements extend certification timelines, yet reimbursement frameworks mature for home-based renal replacement. Technical service margins in Bavaria now exceed hardware financing spreads.
Japan
PMDA's orphan medical device accelerated review pathway reduces regulatory friction for novel wearable kidney and pancreas systems. Hemodialysis device categories face steep timeline compression as manufacturers file parallel submissions with FDA. Tokyo-based purchasing committees synchronize commercial launches through research-intensive healthcare networks.
United Kingdom
Rehabilitation centers compress procurement cycles to six months for garment-integrated cardiac pumps with embedded ECG telemetry. MHRA alignment with EU MDR post-Brexit creates transitional certification complexity. The Oxford-Cambridge corridor concentrates R&D in electrode-neural interface convergence.
South Korea
MFDS operates streamlined review pathways for wearable pancreas systems targeting Type 1 diabetes populations. Sensor miniaturization capabilities in Seoul Capital Area enable continuous metabolite tracking without tethered power. Busan-Ulsan manufacturing clusters supply polymer-based actuator architectures for regional cardiac assist portfolios.
Wearable Artificial Organs Market Key Industry Players
Channel-controlling players compete with product-specialist players across procurement networks. The vendor base organizes into three tiers: diversified medical technology conglomerates, single-organ specialists, and emerging sorbent-regeneration startups. Strategic moves concentrate on regulatory pathway optimization and third-party clinical engineering partnerships rather than price-based competition.
Within the diversified conglomerate tier, Medtronic and Abbott Laboratories occupy positions defined by polymer actuator and sensor miniaturization capabilities respectively. Cochlear Ltd. exemplifies the single-organ specialist archetype through sustained electrode-neural interface expertise. Among Asia-Pacific entrants, Zhejiang Nurotron Biotechnology Co., Ltd. represents regional challengers pursuing accelerated domestic regulatory approvals.
| Leading Market Players |
|---|
| Medtronic |
| Cochlear Ltd. |
| Ekso Bionics |
| Boston Scientific Corporation |
| Abbott Laboratories |
| Zhejiang Nurotron Biotechnology Co., Ltd. |
| AWAK Technologies |
| Touch Bionics |
| Second Sight Medical Products, Inc. |
| Others |
Cost & Logistics Intelligence
East Asian lithium-ion cell chemistry suppliers anchor portable power architectures for wearable artificial organs, concentrating margin pools in battery management system integrators and clinical engineering service firms rather than device OEMs. This upstream concentration forces downstream buyers into long-term offtake contracts indexed to cobalt and nickel price volatility, compressing hardware financing spreads while elevating technical service margins.
Pricing Analysis
Cost-plus contracts with raw material indexation dominate procurement between dialysis center networks and wearable kidney manufacturers. Pricing stratifies across FDA breakthrough-designated premium tiers, EU MDR-certified standard tiers, and pre-certification economy tiers for research-intensive healthcare systems. Cost compression in standard-tier cardiac assist garments is intensifying as German outpatient nephrology chains unbundle after-sales service from capital leases. Research institutions exhibit lowest price sensitivity due to orphan medical device pathway subsidies, while rural United States counties lacking clinic infrastructure face acute budget constraints.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities from East Asian battery chemistry suppliers sustain working capital for silicon nanopore filtration membrane manufacturers in Germany and Japan. Raw material dependencies center on lithium carbonate from Chile, cobalt hydroxide from the Democratic Republic of Congo, and high-purity silicon wafers from Taiwan. Single-source vulnerability in sorbent-based regeneration cartridge production creates exposure to export control volatility. Distribution runs through third-party clinical engineering firms that have displaced hospital purchasing committees in technical service margin capture.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Wearable artificial organs represent high-growth medical device disruption, with FDA breakthrough designation and EU MDR divergence creating asymmetric regulatory arbitrage opportunities for pathway-optimized players.
For Market Incumbents: Build regulatory pathway moats through parallel FDA breakthrough and PMDA orphan medical device submissions to synchronize commercial launches. Incumbents should deepen backward integration into polymer-based actuator architectures to defend against emerging sorbent-regeneration startups. Capacity addition in Bavaria and Tokyo clusters secures proximity to reimbursement-mature dialysis center networks.
For New Entrants and Emerging Players: Home-based dialysis substitution in rural United States counties lacking clinic infrastructure represents the most penetrable entry point for wearable kidney systems. AI-enabled predictive algorithms for glucose forecasting in wearable pancreas applications offer white-space revenue through software-as-medical-device reclassification. Go-to-market execution should prioritize third-party clinical engineering partnerships over direct hospital purchasing committee engagement.
For Investors and Strategic Acquirers: Capital is best deployed toward single-organ specialists with sustained electrode-neural interface expertise and diversified conglomerates with sensor miniaturization capabilities. Long-term viability over the next decade hinges on reimbursement framework maturation outpacing regulatory timeline extension. The signal to watch is FDA software-as-medical-device classification decisions for AI-enabled predictive algorithms embedded in wearable systems.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Designation Pathway | Compresses commercial timelines for implantable-wearable cardiac hybrids targeting congestive heart failure. |
| CE Marking Pathway Under EU MDR | Extends certification timelines for European market entry due to stricter notified body requirements. |
| Hospital System Partnership | Enables outpatient cardiology clinic deployment of garment-integrated pumps with embedded ECG telemetry. |
| Software Companion Development | Unlocks new revenue streams through AI-enabled predictive algorithms for glucose forecasting. |
| Reimbursement Strategy | Secures coverage for home-based renal replacement in German and Japanese dialysis center networks. |
Research Approach
The analysis maps heart assist devices, artificial kidneys, bionic limbs, and wearable pancreas systems, each validated through biomedical engineers, hospital purchasing committee members, GPO contracts managers, and dialysis center procurement leads. Primary interviews with these stakeholders combined with secondary validation from FDA 510(k) filings, PMDA submission databases, CMS Medicare reimbursement data, and EU MDR notified body registers. Bottom-up installed base modeling and top-down expenditure flow analysis triangulate market sizing across the projection horizon.
Assumptions held fixed include reimbursement framework maturation trajectories in the United States, Germany, and Japan, while regulatory timeline variables incorporated EU MDR notified body capacity constraints and PMDA orphan pathway acceleration. Segmentation dimensions modeled encompass product type, technology tier, end-user channel structure, and application maturity gradient. CAGRs derive from replacement cycle analysis for mechanical heart systems and filtration membrane cartridges, cross-referenced with procurement cycle compression observed in outpatient cardiology clinics.
Practitioners should monitor FDA software-as-medical-device reclassification decisions, East Asian battery chemistry export control developments, and EU MDR notified body capacity expansion for early signals of forecast revision. Macroeconomic contraction affecting chronic disease management reimbursement, regulatory divergence exceeding modeled scenarios, or silicon nanopore filtration membrane yield breakthroughs would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular Devices
Serration Balloon Catheters Market
Cardiovascular Devices
India Coronary Stent Market
Cardiovascular Devices
Mobile Cardiac Telemetry Device Market
Cardiovascular Devices
Global Blood Pressure Cuffs Market
Cardiovascular Devices
Cardiac Rhythm Management Devices Market
Cardiovascular Devices
Drug Eluting Stent (DES) Market
Cardiovascular Devices
Global Ventricular Assist Device Market
Cardiovascular Devices
Europe Cardiac Assist Devices Market
Cardiovascular Devices
Transcatheter Aortic Valve Replacement Market
Cardiovascular Devices
Absorbable Heart Stent Market
Cardiovascular Devices
Epinephrine Auto-Injectors Market
Cardiovascular Devices
Peripheral Intravenous Catheters Market
Cardiovascular Devices
Bioresorbable Coronary Stents Market
Cardiovascular Devices
Atherectomy Devices Market
Cardiovascular Devices
North America Vascular Graft Market
Cardiovascular Devices
Cardiac Assist Devices Market