
 Cardiac Catheters Market | 2026-2036
Cardiac Catheters Market Size, Share, and Industry Trends Forecast 2026-2036
Cardiac Catheters Market Analysis
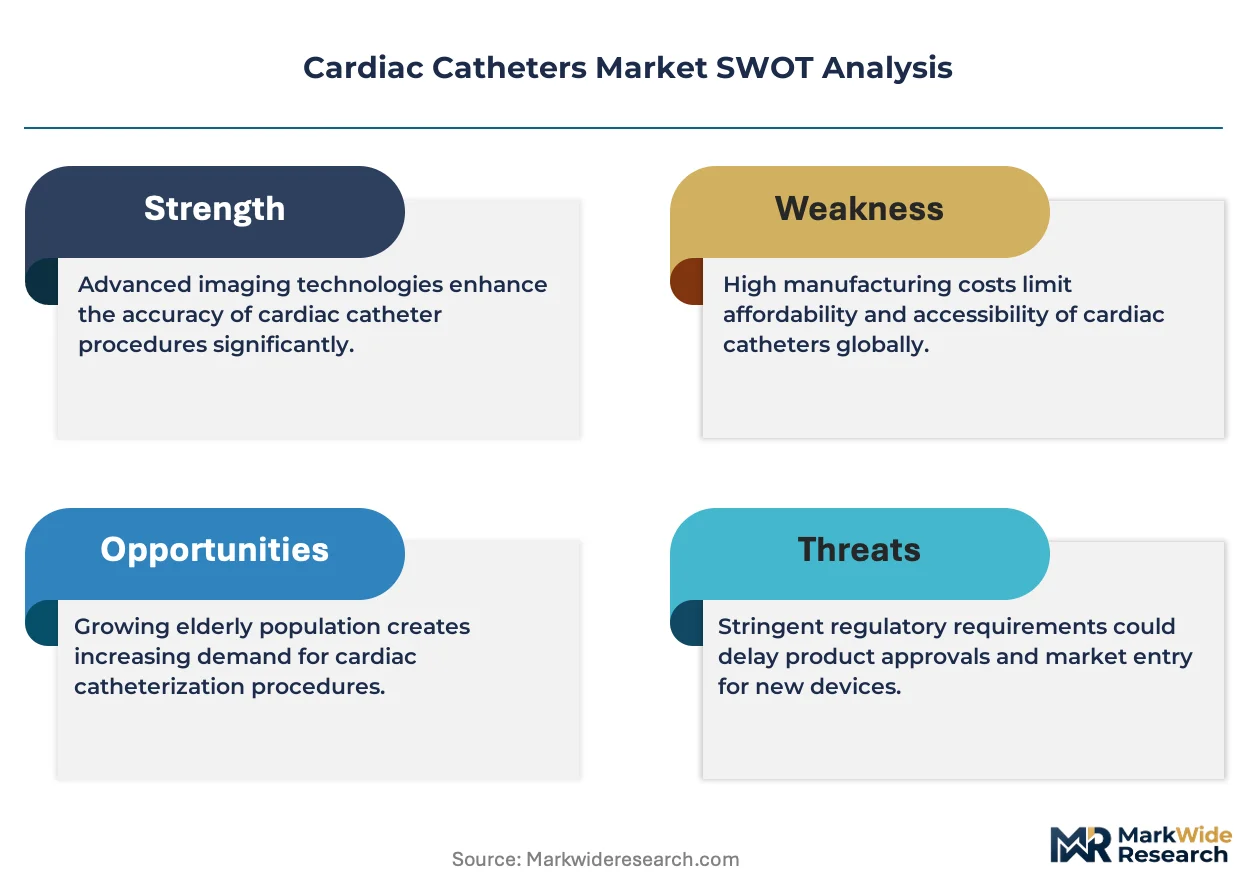
MDR compliance timelines in Europe are shifting the cost-of-entry calculus for catheter manufacturers seeking CE marking. Boston Scientific Corporation leverages its integrated manufacturing footprint to absorb regulatory testing burdens without outsourcing validation. Medtronic anchors its European portfolio through dedicated notified-body relationships and legacy MDD certificates grandfathered under transitional provisions. Abbott Laboratories differentiates via predicate-device libraries that accelerate MDR technical-documentation reviews.
Cardiac catheters are flexible, biocompatible tubes engineered from polyurethane, nylon, or polyethylene with distal-tip steerability, designed for intravascular navigation to diagnose or treat cardiac conditions. Manufacturing employs extrusion, tip-forming, and hydrophilic-coating processes to achieve French sizes ranging from 3F to 8F and torque response specifications. Diagnostic catheters dominate current revenue owing to repeat utilization in electrophysiology mapping and coronary angiography. Guiding catheters represent the fastest-expanding product category as complex percutaneous coronary intervention procedures require larger-lumen platforms with backup support. Implantable devices command premium pricing but face longer regulatory pathways that constrain new entrant participation.
FDA premarket notification requirements, the EU MDR framework, and Japan's PMDA QMS ordinances collectively elevate quality-system rigor and clinical-evidence thresholds for market authorization. These standards shape demand by restricting supply to manufacturers with validated sterilization assurance and biocompatibility testing. Stakeholders must monitor evolving equivalence criteria under MDR Article 61 and FDA's evolving expectations for computational modeling in catheter-design submissions.
Market Dynamics
MDR compliance deadlines are compressing European market entry timelines for catheter manufacturers, forcing accelerated biocompatibility validation and clinical evidence generation while predicate-device pathways narrow under stricter equivalence criteria.
Growth Catalysts
- Electrophysiology procedure volumes:Rising ablation caseloads in tertiary cardiac centers drive repeat diagnostic catheter utilization and mapping system upgrades.
- FDA streamlined premarket pathways:The 510(k) program's computational modeling acceptance reduces bench-testing burdens for iterative catheter designs.
- Hydrophilic coating advances:Lubricious polymer formulations reduce vascular trauma and enable smoother lesion crossing in complex anatomy.
Market Restraints
- Polyether block amide supply concentration:Three European compounders control specialty catheter-grade polymer feedstocks, exposing manufacturers to allocation risk.
- MDR Article 61 equivalence restrictions:The European framework's narrowed predicate-device criteria force costly prospective clinical trials for new entrants.
- Reusable catheter reprocessing:Third-party sterilization services extend functional life of diagnostic devices, compressing replacement cycles in cost-constrained hospital systems.
Strategic Opportunities
- Japan's PMDA QMS harmonization:The regulator's mutual recognition arrangements with FDA and European notified bodies create consolidated audit pathways for multi-market manufacturers.
- Robotic navigation integration:Magnetic and electromechanical steering platforms converge with catheter hardware to enable remote procedure execution.
- Ambulatory surgery center penetration:Diagnostic angiography and simple interventions migrate to outpatient settings, creating demand for compact, single-use catheter kits.
Industry Challenges
- Polymer extrusion technician scarcity:Precision micro-extrusion operations require 18-24 month training curves that outpace workforce pipeline output.
- MDR technical documentation backlog:Notified body capacity constraints extend CE marking timelines to 18-36 months for novel catheter submissions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cardiac Catheters Market |
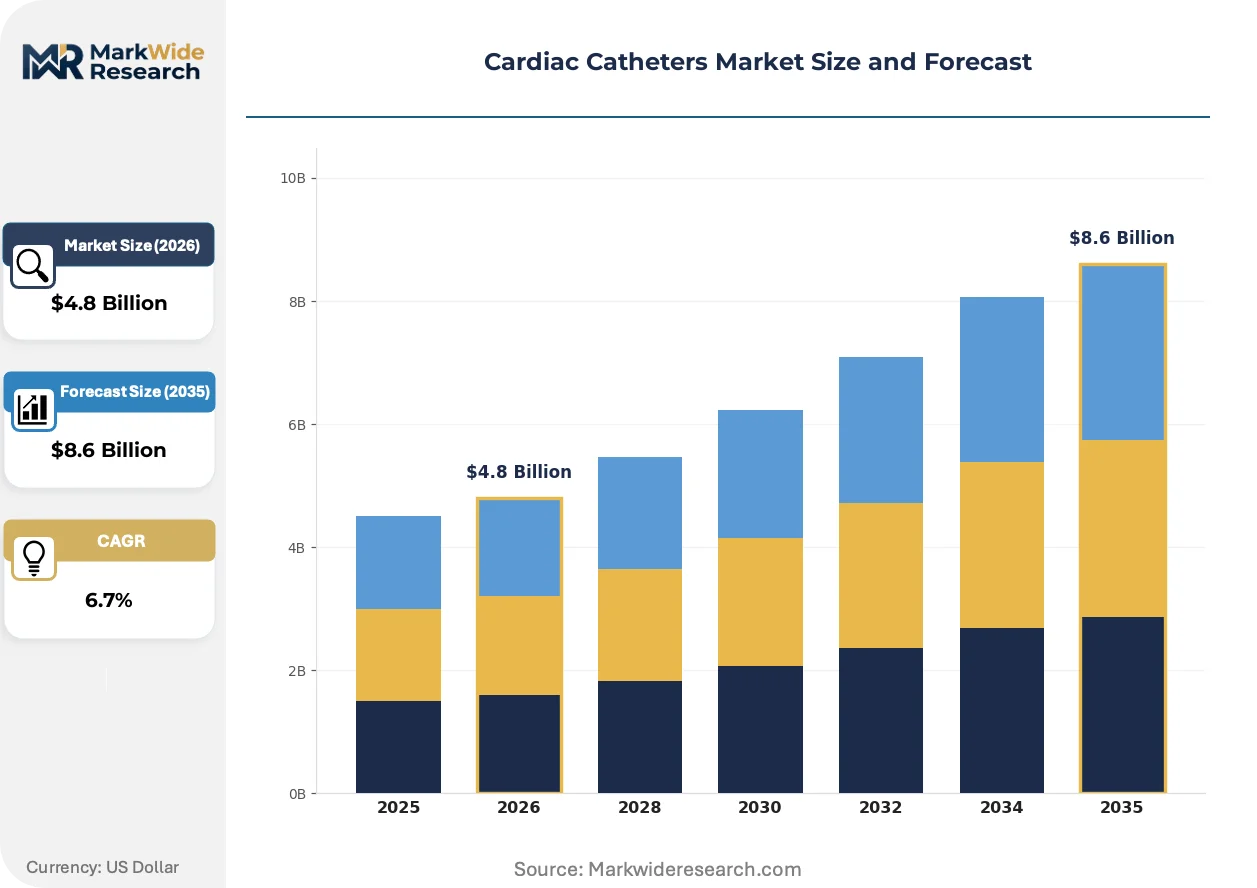
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
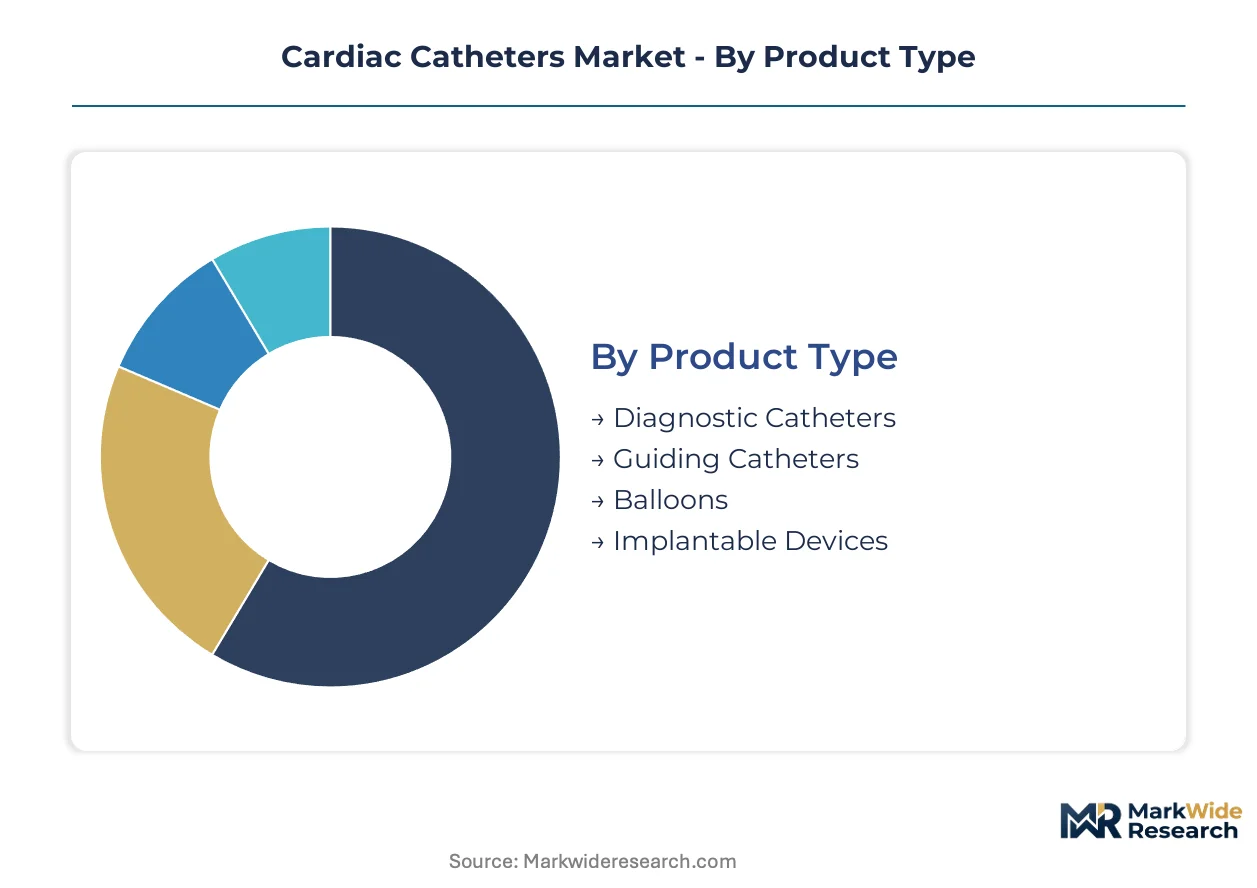
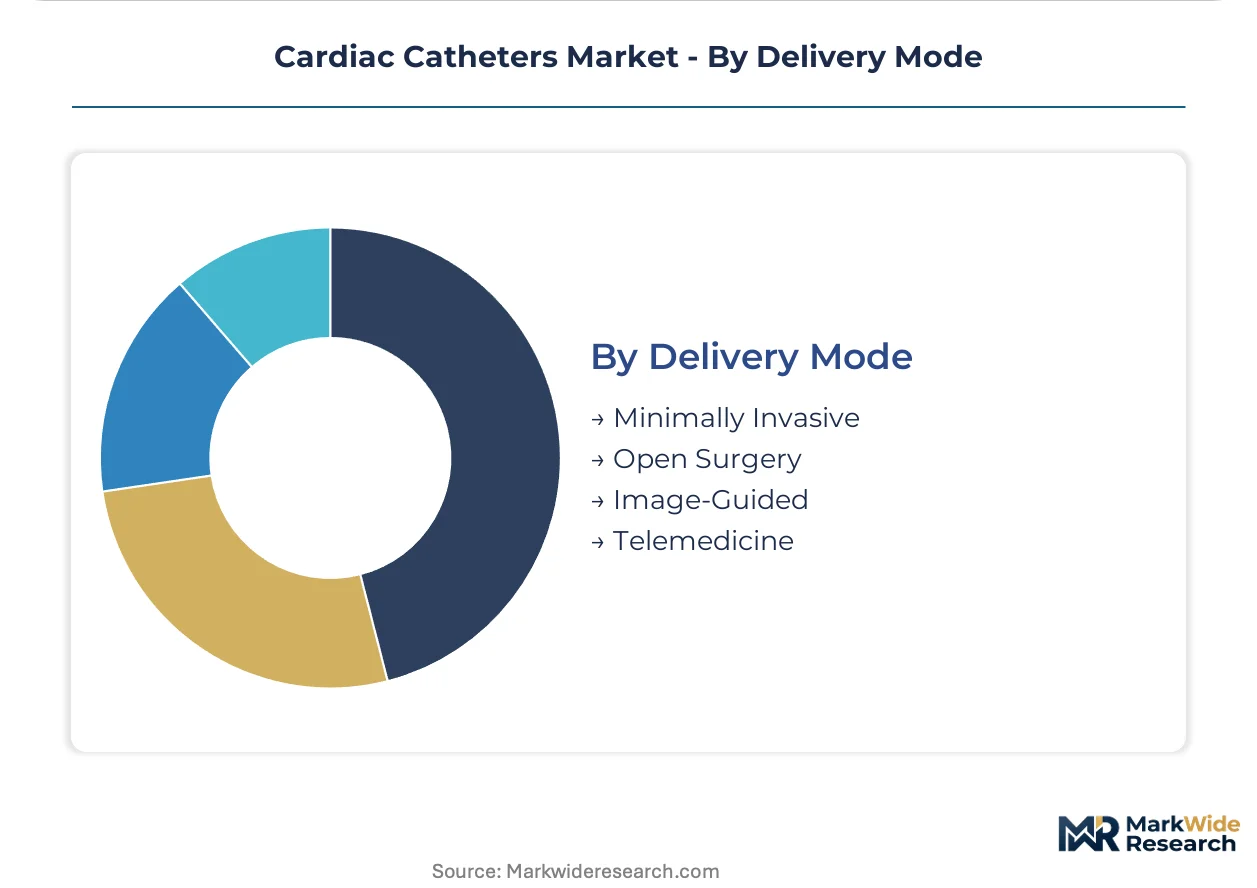
| Segmentation | Product Type: Diagnostic Catheters, Guiding Catheters, Balloons, Implantable Devices Therapy Area: Coronary Artery Disease, Heart Valve Disease, Arrhythmia Management, Congenital Heart Defects End User: Hospitals, Cardiology Clinics, Ambulatory Surgery Centers, Research Institutions Delivery Mode: Minimally Invasive, Open Surgery, Image-Guided, Telemedicine |
| Companies Covered | Boston Scientific Corporation, Medtronic, Abbott Laboratories, Terumo Corporation, Becton Dickinson and Company, Teleflex Incorporated, B. Braun SE, Cordis, Johnson & Johnson Services, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cardiac Catheters Market Emerging Trajectories
Active catheter tip technologies and integrated sensor architectures are displacing passive mechanical designs, while regulatory data requirements reshape how manufacturers validate iterative product generations across multiple jurisdictions.
Steerable sheath platforms with integrated pressure sensing are expanding into complex PCI and structural heart procedures. Interventional cardiologists in high-volume US academic centers adopt these systems for chronic total occlusion and left main interventions. The technology is expanding into cases previously requiring surgical standby, compressing the addressable market for conventional fixed-curve guiding catheters.
The EU MDR's enhanced post-market surveillance requirements mandate systematic implant registries and periodic safety update reports for cardiovascular devices. Manufacturers must restructure quality management systems to capture real-world performance data across distributed hospital networks. Class III catheter devices face the steepest compliance burden, with legacy MDD certificates expiring under non-extendable transitional provisions.
Hospital procurement departments now bundle catheter purchases with capital equipment commitments, conditioning volume discounts on exclusive mapping system or imaging platform acquisitions. This consolidated sourcing model displaces traditional product-by-product tendering in integrated delivery networks. The shift is most pronounced in US metropolitan markets where health system consolidation has concentrated purchasing authority.
Cardiac Catheters Market Segmentation
Cardiac catheter manufacturers configure production lines around distinct performance specifications that separate high-volume diagnostic platforms from premium interventional systems. Each segment carries unique sterilization protocols, regulatory pathways, and margin profiles that reshape competitive positioning across the value chain.
Product Type:
Supply concentration in precision extrusion capacity favors manufacturers with captive polymer compounding operations over contract-dependent competitors.
- Diagnostic Catheters:Electrode-equipped polyurethane shafts with 2-8 French diameters enable electrophysiology mapping and pressure monitoring. Demand concentrates in United States tertiary cardiac centers where repeat ablation procedures drive inventory turnover and catheter replacement cycles.
- Guiding Catheters:Large-lumen nylon or Pebax constructs with preformed curves provide backup support for balloon and stent delivery. Complex PCI adoption in German and Japanese academic hospitals accelerates demand for 7F and 8F platforms with integrated hemostasis valves.
- Balloons:Semicompliant and noncompliant polyethylene terephthalate designs for lesion preparation and valve dilatation.
- Implantable Devices:Lead delivery and left atrial appendage closure systems commanding premium pricing but extended FDA PMA timelines.
Today's leader: Diagnostic Catheters. Tomorrow's challenger: Guiding Catheters.
Therapy Area:
Reimbursement intensity varies sharply across indications, with structural heart procedures capturing triple the catheter spend per case compared to diagnostic angiography.
- Coronary Artery Disease:Guiding catheter and balloon platforms dominate procedural economics. United States hospital systems bundle PCI catheter purchases with stent volume commitments, compressing standalone product margins while locking in multi-year supply agreements.
- Arrhythmia Management:Diagnostic mapping catheters and ablation delivery systems constitute the fastest-expanding therapy segment. Electrophysiology lab expansion in South Korean and Australian metropolitan markets outpaces infrastructure growth in other developed economies.
- Heart Valve Disease:Transcatheter valve replacement and repair drive demand for large-bore delivery sheaths.
- Congenital Heart Defects:Pediatric-specific catheter sizes and configurations requiring specialized manufacturing tooling.
Coronary interventions anchor current revenue. Arrhythmia platforms are climbing the fastest.
End User:
Procurement authority consolidation determines pricing leverage, with integrated delivery networks extracting steeper discounts than independent specialty practices.
- Hospitals:Comprehensive catheter portfolios spanning diagnostic through interventional applications. United States health system consolidation has concentrated purchasing decisions into centralized supply chain offices, displacing individual physician preference contracting.
- Ambulatory Surgery Centers:Single-use diagnostic kits and streamlined interventional platforms for same-day discharge protocols. German and Dutch outpatient cardiology expansion creates demand for compact, disposable catheter systems with minimal reprocessing infrastructure.
- Cardiology Clinics:Diagnostic-focused inventory with limited interventional capabilities.
- Research Institutions:Preclinical and first-in-human study devices with custom specifications.
Hospitals command present volume. Ambulatory Surgery Centers are gaining share fastest.
Delivery Mode:
Technology integration requirements separate premium-positioned systems from commodity catheter categories.
- Minimally Invasive:Transfemoral and transradial access platforms constituting the standard of care. Japanese operators pioneered radial-first adoption, creating demand for thinner-wall diagnostic catheters optimized for smaller arterial access.
- Image-Guided:Intravascular ultrasound and optical coherence tomography-compatible catheter designs for lesion assessment. United States interventionalists in high-volume centers increasingly mandate integrated imaging for complex PCI, driving dual-purpose catheter development.
- Open Surgery:Surgical standby configurations for hybrid operating rooms.
- Telemedicine:Remote procedural monitoring and robotic catheter control interfaces.
Minimally Invasive dominates current procedure mix. Image-Guided platforms show steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Interventional cardiology infrastructure first scaled in the United States during the 1970s, with subsequent diffusion to Germany and Japan establishing the tripartite foundation of modern catheter manufacturing and procedural expertise.
United States
Tertiary cardiac centers in Cleveland and Houston drive diagnostic catheter turnover through repeat electrophysiology ablations. FDA's 510(k) computational modeling acceptance accelerates iterative design clearances. Minneapolis and Boston host concentrated corporate R&D campuses where catheter prototyping integrates with mapping system development.
Germany
Academic hospitals in Munich and Heidelberg adopt 7F and 8F guiding catheters for complex PCI procedures. EU MDR notified body relationships in TÜV SÜD and BSI anchor technical documentation workflows. The Rhine-Main cluster around Frankfurt sustains precision polymer extrusion capacity serving catheter-grade polyurethane supply chains.
Japan
Radial-first adoption pioneered in Tokyo and Osaka creates demand for thinner-wall diagnostic catheter designs. PMDA QMS harmonization with FDA and European notified bodies enables consolidated audit pathways. Nagoya's medical device corridor concentrates hydrophilic coating application facilities.
China
Domestic catheter consumption rises in Shanghai and Beijing interventional cardiology departments. NMPA's updated cardiovascular device guidance documents streamline domestic manufacturer registration. The Suzhou industrial park hosts foreign-owned catheter assembly operations serving Asia-Pacific distribution.
Switzerland
Swissmedic's streamlined Class III device reviews attract catheter manufacturers seeking European market entry. The Basel-Zurich corridor concentrates precision polymer processing expertise. Geneva's proximity to ISO secretariats facilitates standards participation for steerable sheath developers.
Cardiac Catheters Market Vendor Landscape
The competitive structure tilts toward diversified medical technology conglomerates with captive cardiovascular portfolios. Three to five integrated manufacturers command premium interventional segments while mid-scale specialists populate diagnostic catheter supply. Strategic archetypes separate polymer-compounding integrated players from design-only licensors and regional contract manufacturers. Capacity expansion and M&A consolidation represent the dominant competitive moves as firms absorb MDR compliance costs and secure notified body relationships.
Among US-based diversified medical technology groups, Boston Scientific Corporation, Medtronic, and Abbott Laboratories occupy positions spanning diagnostic through interventional catheter portfolios. These conglomerates exemplify the integrated archetype through in-house polymer compounding and captive sterilization validation. Terumo Corporation represents the Japan-based precision manufacturing archetype with concentrated interventional cardiology expertise. Becton Dickinson and Company anchors the diversified life sciences conglomerate model with vascular access catheter extensions. The specialist tier includes Teleflex Incorporated and B. Braun SE, which sit within focused interventional device positioning. Cordis and Johnson & Johnson Services, Inc. exemplify corporate carve-out and reintegration dynamics within cardiovascular portfolios.
| Leading Market Players |
|---|
| Boston Scientific Corporation |
| Medtronic |
| Abbott Laboratories |
| Terumo Corporation |
| Becton Dickinson and Company |
| Teleflex Incorporated |
| B. Braun SE |
| Cordis |
| Johnson & Johnson Services, Inc. |
| Others |
Supply Flow & Price Mechanics
Polyether block amide spot pricing indices in European polymer markets cascade through catheter manufacturing tiers, compressing margins on standard diagnostic platforms while premium interventional systems absorb feedstock volatility through longer-term supply agreements with German and Swiss compounders.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates MDR-validated Class III devices from legacy MDD grandfathered products and unvalidated regional alternatives. Price differentiation hinges on notified-body certification tier and sterilization assurance level. Cost compression in economy diagnostic catheters is intensifying because third-party reprocessing services extend device functional life. Ambulatory surgery centers exhibit highest price sensitivity; academic medical centers purchasing through integrated delivery networks show lowest.
Supply Chain Analysis
Single-source vulnerability sits with specialty catheter-grade polyurethane feedstock production concentrated in Germany, Switzerland, and the Netherlands. Manufacturing draws from polyether block amide resins, hydrophilic coating polymers, and precision extrusion tooling. Tariff exposure on Chinese-sourced nitinol hypotubes creates supply risk. Distribution runs through hospital GPO contracts and direct manufacturer agreements with integrated delivery networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cardiac catheters market functions as a stable compounder, with aging demographics in developed economies sustaining procedure volume growth irrespective of macroeconomic cycles.
For Market Incumbents: Hedge against MDR technical documentation bottlenecks by securing dedicated notified-body relationships before capacity constraints extend CE marking timelines further. Backward integration into polymer compounding insulates margin structures from European feedstock allocation risk. Prioritize captive sterilization validation to maintain supply continuity under evolving FDA quality system requirements. For New Entrants and Emerging Players: Launch via ambulatory surgery center distribution partnerships targeting German and Dutch outpatient cardiology expansion. White-space opportunities concentrate in compact single-use diagnostic kits for same-day discharge protocols and robotic navigation-compatible catheter platforms. Avoid direct hospital GPO competition; instead pursue specialist clinic channels with limited interventional capabilities. For Investors and Strategic Acquirers: Consolidation pressure builds where MDR compliance costs exceed standalone revenue bases for mid-scale diagnostic catheter specialists. Long-term viability favors manufacturers with validated sterilization assurance and biocompatibility testing infrastructure. Acquisition target archetype: European notified-body relationships with legacy MDD certificates under transitional provisions. Watch electrophysiology procedure volume inflection in South Korean and Australian metropolitan markets as early demand signal.| Strategic Initiative | Industry Significance |
|---|---|
| MDR Technical Documentation Investment | Accelerates CE marking timelines through dedicated notified-body relationships with TÜV SÜD or BSI. |
| Polymer Compounding Backward Integration | Captures catheter-grade polyurethane supply chain control against European feedstock allocation risk. |
| Ambulatory Surgery Center Partnership | Captures German and Dutch outpatient cardiology expansion with compact single-use diagnostic kits. |
| Robotic Navigation Platform Integration | Aligns catheter hardware development with magnetic and electromechanical steering system roadmaps. |
| Hospital System GPO Contract Consolidation | Locks multi-year supply agreements through bundled catheter and capital equipment purchasing. |
Methodological Framework
Bottom-up hospital procurement modeling reconciled against top-down polymer feedstock tracking forms the analytical core. Primary interviews with interventional cardiologists, hospital purchasing committee chairs, biomedical engineers, and GPO contracts managers triangulate demand-side validation. Secondary sources include FDA 510(k) filings, EU MDR technical documentation databases, CMS Medicare procedure data, and hospital procurement contract disclosures. Supply-side verification draws from European polymer compounding capacity reports and precision extrusion equipment installation records.
Input-output matrices project catheter demand across product type, therapy area, end user, and delivery mode dimensions throughout the forecast period. CAGRs derive from procedure volume elasticity models calibrated to demographic aging trajectories and interventional cardiology infrastructure expansion. Industry-specific forecast inputs incorporate electrophysiology lab buildout rates and MDR compliance timeline assumptions.
Forecast precision tightens around the base case; tail outcomes carry wider variance under notified-body capacity constraints or abrupt polymer feedstock allocation disruptions. Forecasts reflect documented assumptions regarding regulatory pathway evolution and hospital procurement consolidation trajectories. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular Devices
Intravascular Stents Market
Cardiovascular Devices
Latin America Compression Therapy Market
Cardiovascular Devices
Pressure Infusion Bags Market
Cardiovascular Devices
Percutaneous Coronary Intervention Market
Cardiovascular Devices
Drug-Coated Balloon Catheter Market
Cardiovascular Devices
Cardiovascular Ultrasound Market
Cardiovascular Devices
Global Aortic Endografts Market
Cardiovascular Devices
Extracorporeal Membrane Oxygenation (ECMO) Market
Cardiovascular Devices
North America Cardiac Assist Devices Market
Cardiovascular Devices
Vascular Snare Market
Cardiovascular Devices
Heart Valves Market
Cardiovascular Devices
Vena Cava Clips and Filters Market
Cardiovascular Devices
Global Vascular Plugs Market
Cardiovascular Devices
Global Percutaneous Coronary Intervention (PCI) Devices Market
Cardiovascular Devices
Venous Reservoirs Market
Cardiovascular Devices
Global Vascular Graft Market