
 Patient Temperature Management Systems Market | 2026-2036
Patient Temperature Management Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Patient Temperature Management Systems Market Analytics
The EU Green Deal's medical device sustainability criteria is consolidating procurement preferences around energy-efficient temperature platforms. Stryker Corporation leverages its integrated surgical workflow portfolio to bundle warming and cooling systems with operating room equipment. Medtronic anchors its position through deep R&D investment in closed-loop feedback algorithms for precise thermal control. Cincinnati Sub-Zero Products specializes in custom hypothermia systems for specialized cardiac and neurological procedures.
Patient temperature management systems encompass active and passive devices that regulate core body temperature through surface or intravascular heat exchange, typically achieving set points within 0.5 degrees Celsius accuracy via circulating water, forced air, or phase-change materials. These systems serve primarily to prevent perioperative hypothermia, manage therapeutic hypothermia in critical care, and support normothermia during extended surgical interventions. Warming devices dominate current revenue given universal prewarming protocols and PACU recovery standards, while cooling devices represent the fastest-expanding segment driven by rising therapeutic hypothermia indications in post-cardiac arrest and traumatic brain injury protocols. Monitoring systems command premium pricing through integrated sensor arrays that track multiple body sites simultaneously, though accessories generate recurring revenue streams that sustain long-term vendor relationships.
FDA 510(k) clearance pathways and ISO 80601-2-35 thermal regulation standards shape product development timelines and international market access for temperature management device manufacturers. The EU Medical Device Regulation imposes additional clinical evidence requirements that favor established players with robust quality management systems and post-market surveillance infrastructure. Stakeholders must evaluate how emerging conductive and evaporative technologies will challenge incumbent convection-based platforms in ambulatory and home-based care settings.
Market Dynamics
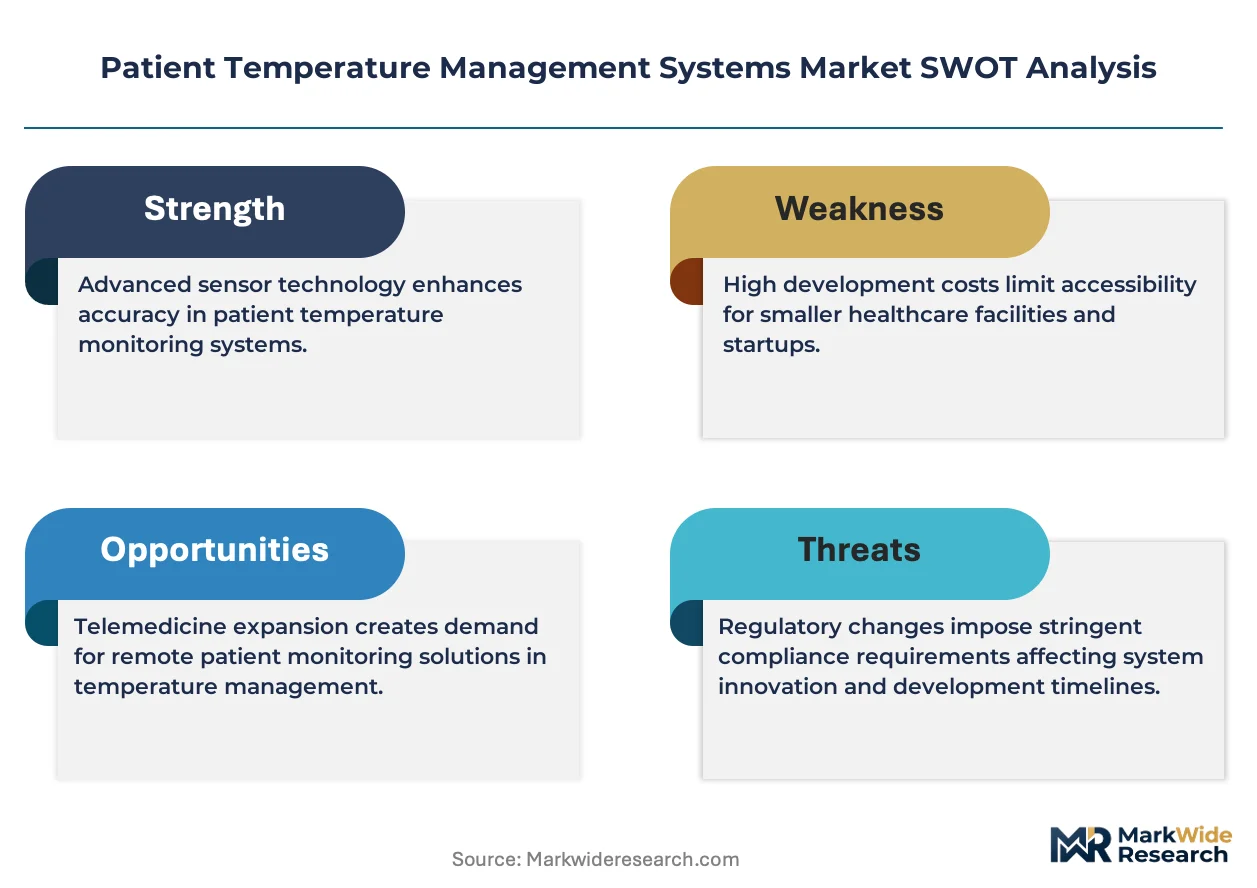
The FDA's updated medical device cybersecurity guidance is forcing manufacturers to redesign temperature management platforms with embedded encryption and continuous monitoring capabilities, extending product development cycles while raising barriers for new entrants.
Growth Catalysts
- Surgical Volume Expansion:Rising procedure counts in hospital operating rooms and ambulatory surgery centers drive perioperative warming device procurement, particularly for orthopedic and cardiovascular interventions requiring extended anesthesia.
- EU Green Deal Sustainability Criteria:Energy-efficiency mandates for medical devices are consolidating procurement preferences around low-consumption temperature platforms, favoring vendors with ISO 14001-certified manufacturing.
- Closed-Loop Feedback Algorithms:Precision thermal control systems achieving sub-0.5°C accuracy are displacing manual adjustment protocols in neurosurgical and cardiac procedures where temperature stability is critical.
Market Restraints
- Copper and Semiconductor Input Volatility:Temperature management systems rely on heat exchangers and sensor arrays whose raw material costs fluctuate with electronics supply chain disruptions.
- EU MDR Clinical Evidence Requirements:The Medical Device Regulation imposes additional post-market surveillance obligations that extend time-to-revenue for Class IIa and IIb temperature devices.
- Passive Warming Substitutes:Disposable forced-air blankets and chemical warming packs retain cost advantages in price-sensitive acute care settings, limiting premium active system penetration.
Strategic Opportunities
- Home-Based Therapeutic Hypothermia:Post-cardiac arrest cooling protocols are migrating to residential settings, creating demand for portable, consumer-grade temperature management devices with simplified interfaces.
- Conductive-Evaporative Technology Convergence:Hybrid platforms combining water-circulating garments with phase-change materials are opening ambulatory surgery center segments previously served only by hospital-grade convection systems.
- US ASC Expansion:Medicare reimbursement changes favoring outpatient surgical procedures are accelerating replacement cycles for aging warming equipment in freestanding facilities across Texas, Florida, and Arizona.
Industry Challenges
- Biomedical Engineering Talent Scarcity:The intersection of thermal physiology, embedded systems programming, and regulatory compliance requires specialized expertise that outpaces university program output.
- Legacy EMR Integration Complexity:Temperature management data streams must interface with Epic, Cerner, and Meditech installations through HL7 FHIR protocols, requiring customized middleware development for each health system.
- ISO 80601-2-35 Certification Timelines:Third-party testing for thermal regulation safety standards adds 8-14 months to product commercialization schedules, compressing effective patent life.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Patient Temperature Management Systems Market |
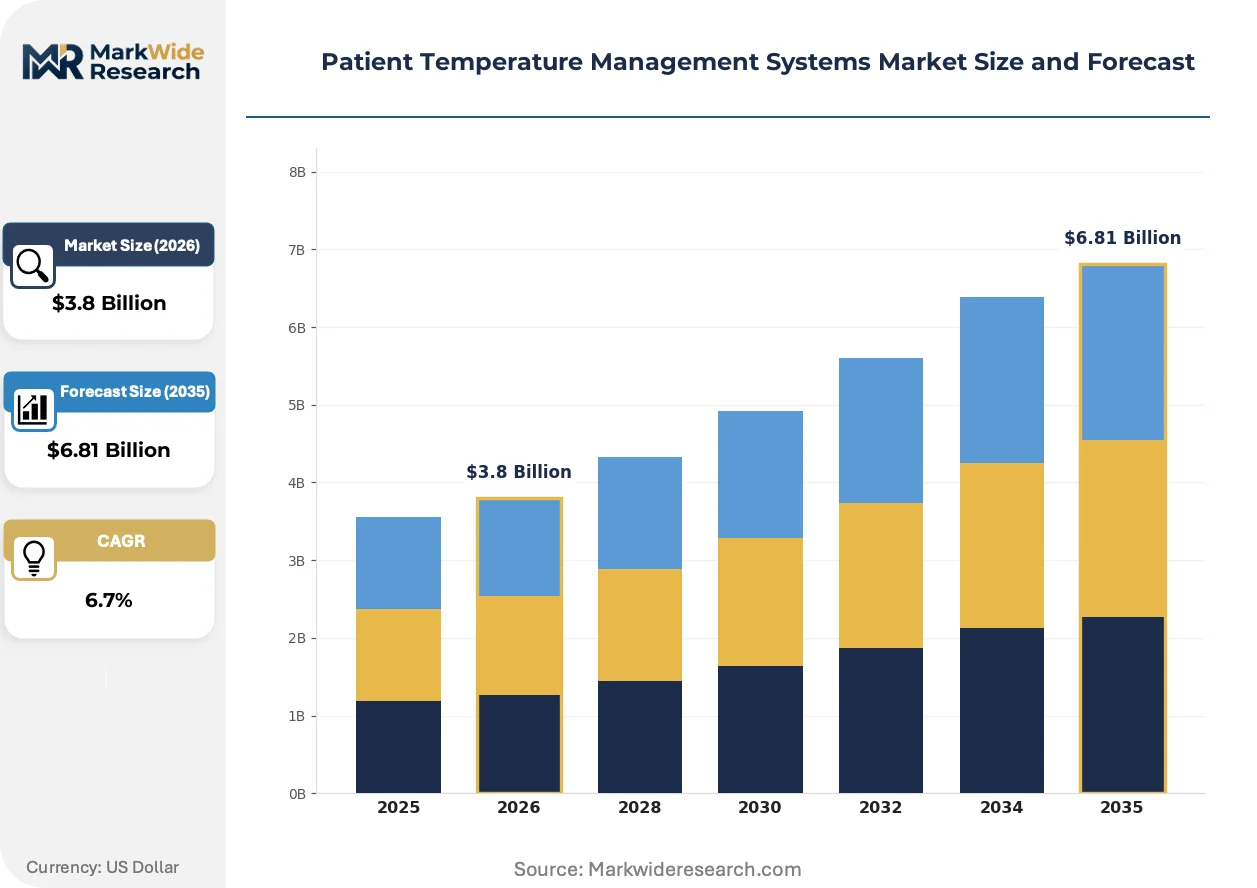
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cooling Devices, Warming Devices, Monitoring Systems, Accessories End User: Hospitals, Clinics, Home Care, Emergency Services Application: Perioperative Care, Critical Care, Cardiology, Oncology Technology: Convection, Conductive, Evaporative, Infrared |
| Companies Covered | 3M Company, Stryker Corporation, Medtronic, ZOLL Medical Corporation, Cincinnati Sub-Zero Products, BD, GE Healthcare, Gentherm Medical, Drägerwerk AG & Co. KGaA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Patient Temperature Management Systems Market Evolving Landscape
Digital integration and precision sensing architectures are redefining competitive differentiation in temperature management, shifting value capture from hardware margins to data-enabled clinical decision support.
Intravascular temperature management catheters with integrated fiber-optic sensors are unifying thermal regulation and continuous core temperature monitoring into single-lumen devices. Academic medical centers in Germany and the United States are piloting these systems for traumatic brain injury protocols. This convergence is compressing the addressable market for standalone monitoring accessories while elevating catheter ASPs.
REACH restrictions on perfluorinated compounds are compelling manufacturers to reformulate phase-change materials used in cooling vests and blankets. The European Chemicals Agency's 2023 substance evaluation timeline is forcing inventory write-downs and supplier qualification programs. Cardiac surgery cooling applications face the steepest compliance costs given thermal performance requirements.
Hospital procurement departments are consolidating temperature management spend through integrated operating room equipment bundles. Original equipment manufacturers with surgical table and lighting portfolios are capturing warming system placements previously won by standalone vendors. This concentration is most visible in the United States, where health system consolidation has reduced the number of independent purchasing decision-makers by approximately 40 percent since 2015.
Patient Temperature Management Systems Market Segmentation
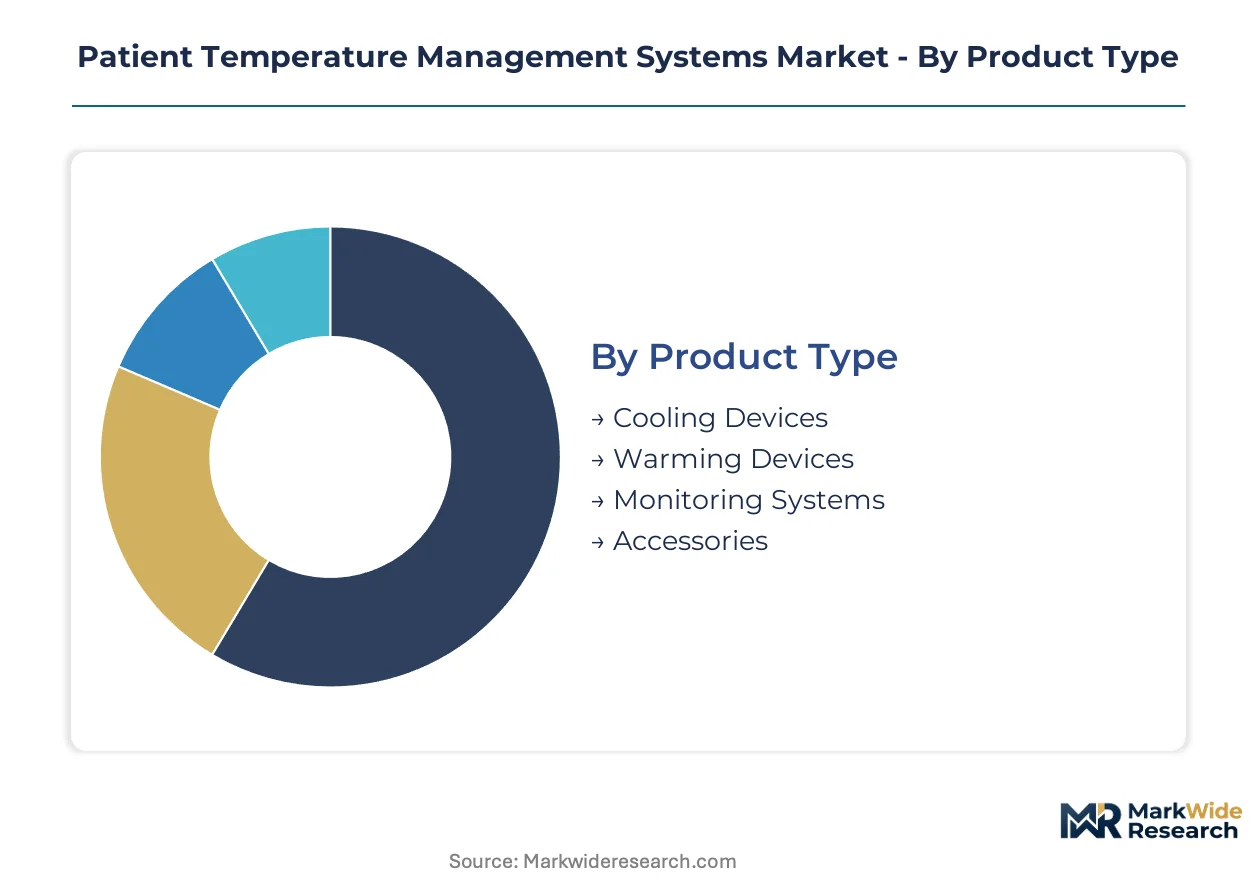
Segmentation in patient temperature management systems reveals distinct procurement patterns across clinical settings, with technology choices and application requirements driving vendor specialization and pricing architecture.
Product Type:
Supply concentration clusters around integrated platform manufacturers with captive sensor production and in-house heat exchanger fabrication.
- Warming Devices:Forced-air and water-circulating systems achieve core temperature set points through surface heat exchange, typically deployed in preoperative holding areas and post-anesthesia care units. Demand concentrates in United States hospital systems implementing universal warming protocols for orthopedic and cardiovascular procedures, with procurement favoring vendors bundling warming systems with surgical tables.
- Cooling Devices:Intravascular catheters and surface cooling systems regulate temperature through conductive or convective heat removal, serving therapeutic hypothermia protocols. Demand is accelerating in German and United States academic medical centers adopting post-cardiac arrest cooling standards, though REACH compliance costs for phase-change materials constrain European suppliers.
- Monitoring Systems:Multi-site sensor arrays track core and surface temperatures simultaneously via esophageal, bladder, or skin probes.
- Accessories:Disposable blankets, pads, and catheter kits generate recurring revenue streams sustaining long-term vendor relationships.
Warming devices absorb the bulk of installed capacity; cooling devices are expanding most quickly.
End User:
Procurement authority varies sharply across settings, with consolidated health systems wielding volume leverage distinct from fragmented ambulatory purchasers.
- Hospitals:Integrated delivery networks in Texas, Florida, and Arizona drive replacement cycles for aging perioperative warming equipment, with capital budgets favoring energy-efficient platforms meeting EU Green Deal sustainability criteria for multinational system standardization.
- Clinics:Ambulatory surgery centers in the United States face Medicare reimbursement shifts favoring outpatient procedures, accelerating demand for compact warming systems with simplified interfaces.
- Home Care:Portable temperature management devices with consumer-grade interfaces serve post-cardiac arrest cooling protocols migrating to residential settings.
- Emergency Services:Prehospital warming and cooling systems require ruggedized construction and battery operation for field deployment.
Hospitals command the dominant share of capital expenditure; home care is gaining share fastest.
Application:
Clinical evidence requirements and reimbursement pathways create divergent margin profiles across therapeutic indications.
- Perioperative Care:Universal prewarming and intraoperative normothermia maintenance represent the highest-volume application, with Stryker Corporation and Medtronic competing through integrated surgical workflow bundles.
- Critical Care:Therapeutic hypothermia for traumatic brain injury and post-cardiac arrest protocols demands precise temperature stability, favoring closed-loop feedback systems with sub-0.5°C accuracy.
- Cardiology:Cardiac surgery cooling applications face steepest REACH compliance costs for phase-change material reformulation.
- Oncology:Chemotherapy-induced hypothermia management employs surface warming devices in infusion center settings.
Perioperative care accounts for the largest installed base; critical care shows the steepest expansion trajectory.
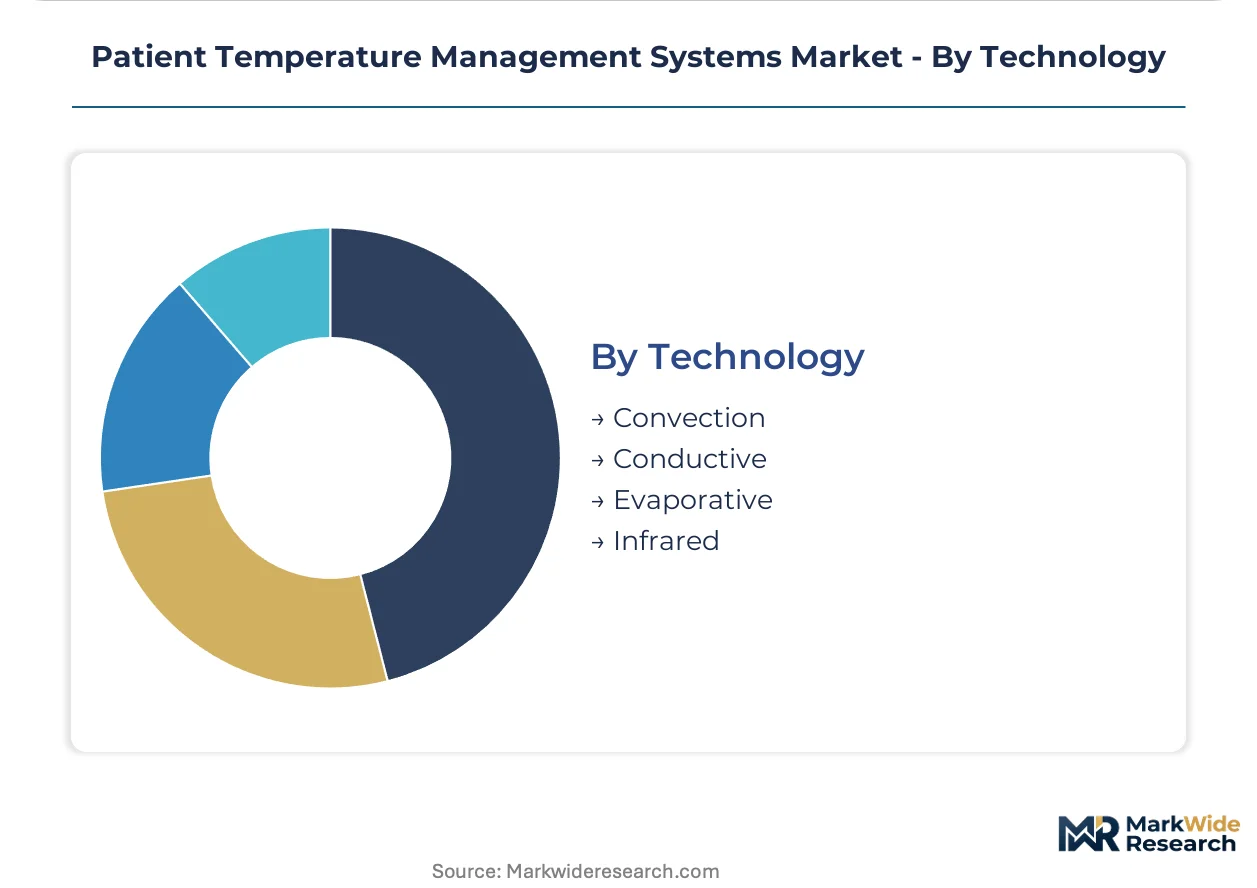
Technology:
Platform selection determines energy consumption profiles, maintenance requirements, and compatibility with existing surgical infrastructure.
- Convection:Forced-air warming dominates current revenue through low capital cost and rapid deployment, though FDA cybersecurity guidance is forcing embedded encryption redesigns extending development cycles.
- Conductive:Water-circulating garments and gel pads offer precise temperature control for neurosurgical procedures requiring stability.
- Evaporative:Phase-change materials face European Chemicals Agency inventory pressures under 2023 substance evaluation timelines.
- Infrared:Radiant warming systems serve neonatal applications with minimal airflow disruption.
Convection retains the dominant technology position; conductive platforms are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing concentrates in Germany and the United States, while demand growth accelerates fastest in aging healthcare systems across Texas, Florida, and Arizona. Supply chains route precision sensors through Swiss and Japanese component specialists before final assembly. Regulatory divergence between FDA cybersecurity mandates and EU MDR clinical evidence requirements is fragmenting product development roadmaps.
United States
Ambulatory surgery center expansion in Texas, Florida, and Arizona drives replacement cycles for aging perioperative warming equipment. Medicare reimbursement shifts favoring outpatient procedures accelerate procurement timelines. The FDA's updated medical device cybersecurity guidance forces embedded encryption redesigns that extend development cycles for convection-based platforms.
Germany
Academic medical centers in Berlin and Munich pilot intravascular catheters with integrated fiber-optic sensors for traumatic brain injury protocols. REACH restrictions on perfluorinated compounds compel phase-change material reformulation for cardiac surgery cooling applications. The EU Green Deal's medical device sustainability criteria consolidate procurement preferences around ISO 14001-certified temperature platforms.
Japan
PMDA alignment with ISO 80601-2-35 thermal regulation standards shapes market access timelines for imported warming and cooling devices. METI initiatives on medical device cybersecurity create parallel compliance obligations to FDA guidance. Manufacturing clusters in the Kansai region supply precision heat exchangers to global temperature management system assemblers.
Switzerland
Swissmedic's streamlined Class IIa device pathways attract manufacturers seeking faster European market entry than EU MDR routes permit. Precision sensor specialists in the Lake Geneva region export fiber-optic temperature probes to catheter integrators in Germany and the United States. The country's medical technology export infrastructure supports niche hypothermia system vendors serving cardiac and neurological segments.
India
CDSCO regulatory harmonization efforts with ISO standards reduce technical barriers for imported active warming devices. Price-sensitive acute care settings in Maharashtra and Karnataka retain preference for disposable forced-air blankets over capital-intensive active systems. Domestic distributors increasingly bundle temperature management accessories with surgical equipment imports from European and North American suppliers.
Patient Temperature Management Systems Market Competitive Landscape
The competitive structure tilts toward diversified medical technology conglomerates with integrated surgical workflow portfolios. Consolidation pressure from health system procurement centralization favors vendors bundling temperature systems with operating room equipment. Three archetypes dominate: integrated surgical platform suppliers, precision thermal control specialists, and regional component fabricators. Strategic moves concentrate on portfolio bundling and conductive-evaporative technology convergence for ambulatory segments.
Among diversified medical technology conglomerates, Stryker Corporation and Medtronic exemplify the integrated platform archetype, leveraging broad surgical equipment portfolios to capture warming system placements through bundled procurement contracts. Cincinnati Sub-Zero Products occupies a specialist position, representing vendors focused on custom hypothermia configurations for cardiac and neurological procedures where precise thermal stability commands premium positioning.
| Leading Market Players |
|---|
| 3M Company |
| Stryker Corporation |
| Medtronic |
| ZOLL Medical Corporation |
| Cincinnati Sub-Zero Products |
| BD |
| GE Healthcare |
| Gentherm Medical |
| Drägerwerk AG & Co. KGaA |
| Others |
Value Network & Pricing Analysis
Family-owned mid-cap specialists in Germany and Switzerland anchor precision sensor and heat exchanger fabrication, enabling disciplined pricing power through captive component supply and ISO 80601-2-35 certification premiums that hospital procurement committees cannot easily substitute.
Pricing Analysis
Cost-down pressure on convection-based warming systems accelerates because FDA cybersecurity redesign mandates extend development timelines and concentrate procurement authority within integrated delivery networks. Three-tier pricing structure across premium closed-loop systems, standard forced-air platforms, and economy passive warming separates vendors by thermal accuracy certification and EMR integration depth. Pricing pressure stems from copper and semiconductor input volatility squeezing heat exchanger margins. Ambulatory surgery centers exhibit highest price sensitivity, while academic medical centers in Germany and the United States absorb premiums for sub-0.5°C precision control.
Supply Chain Analysis
Refurbishment flows for water-circulating garments and phase-change cooling vests create secondary supply channels that compete with new equipment sales in cost-constrained acute care settings. Manufacturing concentrates in Germany for precision catheter assembly, the United States for integrated platform production, and Japan for fiber-optic sensor fabrication. Raw material dependencies center on copper heat exchangers, semiconductor sensor arrays, and perfluorinated compounds facing REACH restriction. Single-source vulnerability looms for Swiss precision temperature probes. Distribution runs through hospital GPO contracts and surgical equipment bundling arrangements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around vendors with captive sensor production and ISO 14001-certified manufacturing, as EU Green Deal sustainability criteria and FDA cybersecurity mandates force subscale competitors toward exit or acquisition.
For Market Incumbents: Deploy bundled surgical workflow contracts to lock out standalone warming system vendors. Integrate closed-loop feedback algorithms with Epic and Cerner installations through HL7 FHIR protocols to raise switching costs. Defend against conductive-evaporative hybrid entrants by accelerating conductive platform R&D for ambulatory surgery center segments. For New Entrants and Emerging Players: Swissmedic's streamlined Class IIa device pathways in Switzerland open a window for faster European market entry than EU MDR routes permit. Target portable therapeutic hypothermia devices for home care settings where incumbent footprint remains shallow. Pursue conductive-evaporative technology convergence as the go-to-market angle for Texas, Florida, and Arizona ASC expansion. For Investors and Strategic Acquirers: Distressed-cycle entries favor precision thermal control specialists with ISO 80601-2-35 certification and cardiac surgery cooling expertise in Germany. Long-term viability hinges on conductive technology transition and EMR integration depth. Monitor REACH compliance cost burdens for phase-change material suppliers as inflection indicator for European supplier distress.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Cybersecurity Compliance Pathway | Embedded encryption redesigns extend development cycles, raising barriers for new entrants without capital reserves. |
| CE Marking Under EU MDR | Clinical evidence requirements for Class IIb temperature devices favor established players with post-market surveillance infrastructure. |
| Hospital System Partnership | Integrated delivery network bundling contracts in Texas and Florida capture warming system placements through surgical table alliances. |
| Software Companion Development | HL7 FHIR middleware for Epic and Cerner integration elevates data-enabled clinical decision support value capture. |
| Reimbursement Strategy | Medicare outpatient procedure shifts accelerate ASC equipment replacement cycles in Arizona and Florida markets. |
Research Methodology
Document review covered FDA 510(k) filings, EU MDR technical documentation, and ISO 80601-2-35 certification records, complemented by interviews with biomedical engineering directors, hospital GPO contract managers, and surgical equipment procurement leads. Secondary validation drew from hospital capital expenditure databases, CMS Medicare reimbursement schedules, and European Chemicals Agency substance evaluation timelines. Bottom-up installed base modeling and top-down surgical volume projections were triangulated against vendor shipment data.
Segment-level outputs across product type, end user, application, and technology dimensions were generated through the projection horizon. CAGRs were derived from surgical volume elasticity models and replacement cycle dynamics for perioperative warming equipment. Forecast inputs incorporated REACH restriction compliance costs for phase-change materials and PMDA alignment timelines for Japanese market access.
The model assumes a particular technology adoption path; alternative pathways for conductive-evaporative hybrid platforms would alter the outlook if ambulatory surgery center penetration accelerates faster than projected. Forecasts reflect assumptions about FDA cybersecurity implementation timelines and EU MDR clinical evidence acceptance rates. Practitioners should monitor copper and semiconductor spot price volatility and Swissmedic pathway application volumes for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Patient Monitoring
Sleep Tracking Devices Market
Patient Monitoring
South Africa Patient Monitoring Market
Patient Monitoring
Global Home Blood Pressure Monitoring Devices Market
Patient Monitoring
Urine Output Monitoring Systems Market
Patient Monitoring
South America Respiratory Monitoring Market
Patient Monitoring
Canada Patient Monitoring Devices Market
Patient Monitoring
Asthma Monitoring Devices Market
Patient Monitoring
Germany Patient Care Monitoring Equipment Market
Patient Monitoring
Wireless Fetal Monitoring Systems Market
Patient Monitoring
Europe Respiratory Monitoring Market
Patient Monitoring
Brain Tissue Oxygen Monitoring Systems Market
Patient Monitoring
Global Biomedical Sensor Market
Patient Monitoring
South America Fetal and Neonatal Monitoring Market
Patient Monitoring
Remote Patient Monitoring Software and Services Market
Patient Monitoring
Digital Patient Monitoring Systems Market
Patient Monitoring
MRI Pulse Oximeters Market