
 Global High Strength Aluminum Alloys Market | 2026-2036
Global High Strength Aluminum Alloys Market Size, Share, and Industry Trends Forecast 2026-2036
Global High Strength Aluminum Alloys Market Intelligence
The substitution of traditional steel with high-strength aluminum alloys in automotive body structures is rebalancing material sourcing economics for vehicle platforms. Constellium SE specializes in advanced automotive body-in-white solutions for transportation manufacturers. Alcoa Corporation leverages its integrated production chain to supply the demanding aerospace sector. Hindalco Industries competes through its extensive portfolio of rolled and extruded products for industrial applications.
High strength aluminum alloys are metallic materials, primarily from the 2xxx, 6xxx, and 7xxx series, which contain alloying elements like copper, magnesium, and zinc. These additions impart superior strength-to-weight ratios and fatigue resistance compared to pure aluminum. The 7xxx series alloys, known for their exceptional strength, dominate the aerospace components application, a key high-value segment. In terms of form, extrusions and plates represent significant volume, driven by demand from transportation manufacturers.
Material specifications are governed by stringent standards from bodies like the US Federal Aviation Administration (FAA) for aerospace applications and the EU's REACH regulation under ECHA. In parallel, China's MIIT directives influence material standards for domestic automotive and electronics industries. Suppliers must therefore navigate these divergent regional qualification processes and performance requirements to secure market access.
Market Dynamics
The imperative for lightweighting in the transportation sector, driven by stringent emissions regulations and the operational economics of fuel efficiency, is the central force shaping the high strength aluminum alloys market. This pressure compels aerospace and automotive manufacturers to substitute heavier traditional materials.
Growth Catalysts
- Automotive Lightweighting Mandates:Regulations in major automotive markets, such as corporate average fuel economy standards in the US, mandate improved vehicle efficiency. This directly stimulates the substitution of steel with aluminum alloys in body structures, closures, and chassis components to reduce overall vehicle mass.
- Electric Vehicle Architectures:The design of battery electric vehicles creates new demand for high strength aluminum. It is used extensively for battery enclosures and crash management systems, where its combination of strength, thermal conductivity, and low weight is critical for maximizing range and safety.
- Aerospace and Rail Expansion in China:China's state-led industrial expansion in commercial aviation and high-speed rail networks creates significant, concentrated demand. Domestic manufacturing programs for aircraft like the COMAC C919 and an expanding bullet train system rely heavily on 7xxx and 2xxx series aluminum alloys.
Market Restraints
- High Energy Input Costs:The production of primary aluminum is an extremely energy-intensive process. Volatility in electricity prices creates significant cost instability for alloy producers, which can make aluminum less cost-competitive against materials with lower embodied energy, like advanced steels.
- Threat from Substitute Materials:High strength aluminum alloys face intense competition from alternative lightweight materials. Carbon fiber reinforced plastics (CFRPs) offer superior strength-to-weight ratios in high-end aerospace and automotive applications, while advanced high-strength steels (AHSS) present a lower-cost alternative for many automotive body parts.
- Manufacturing and Joining Complexity:Certain high-strength aluminum alloys, particularly in the 7xxx series, exhibit lower formability and are more challenging to weld compared to steel. This necessitates specialized equipment, processes like friction stir welding, and worker training, adding cost and complexity to manufacturing operations.
Strategic Opportunities
- Additive Manufacturing Applications:The development of alloy powders for selective laser melting and other 3D printing technologies opens opportunities for producing highly complex, topology-optimized components. This is particularly valuable in aerospace for creating lightweight parts that are impossible to manufacture with traditional subtractive methods.
- Recycled Content and Circular Economy:Promoting alloys with high percentages of recycled content provides a strategic advantage. As regulations like the EU Green Deal prioritize sustainability, secondary aluminum, which uses significantly less energy, becomes a more attractive raw material for industrial and automotive customers.
- Penetration into Industrial Machinery:A significant opportunity exists in displacing steel in applications like robotics, factory automation, and material handling equipment. Using lightweight aluminum alloys for robotic arms or moving gantries can increase operational speed, reduce energy consumption, and improve precision.
Industry Challenges
- Lengthy Qualification Cycles:The process for certifying new alloys for safety-critical applications is a major hurdle. Gaining approval from bodies like the FAA for aerospace use can take years and involve extensive testing, delaying the market entry of innovative materials and increasing development costs.
- Navigating Divergent Global Standards:Suppliers must manage a complex web of regional material specifications. An alloy qualified for the Chinese automotive market under MIIT directives may not meet the requirements of the EU's REACH regulation, forcing producers to maintain separate supply chains or undergo redundant qualification processes.
- Specialized Workforce Scarcity:Manufacturing with high strength aluminum requires specific expertise in areas like forming, joining, and surface treatment. A shortage of technicians and engineers skilled in aluminum-specific welding and design can constrain a manufacturer's ability to scale production or adopt new alloy technologies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global High Strength Aluminum Alloys Market |
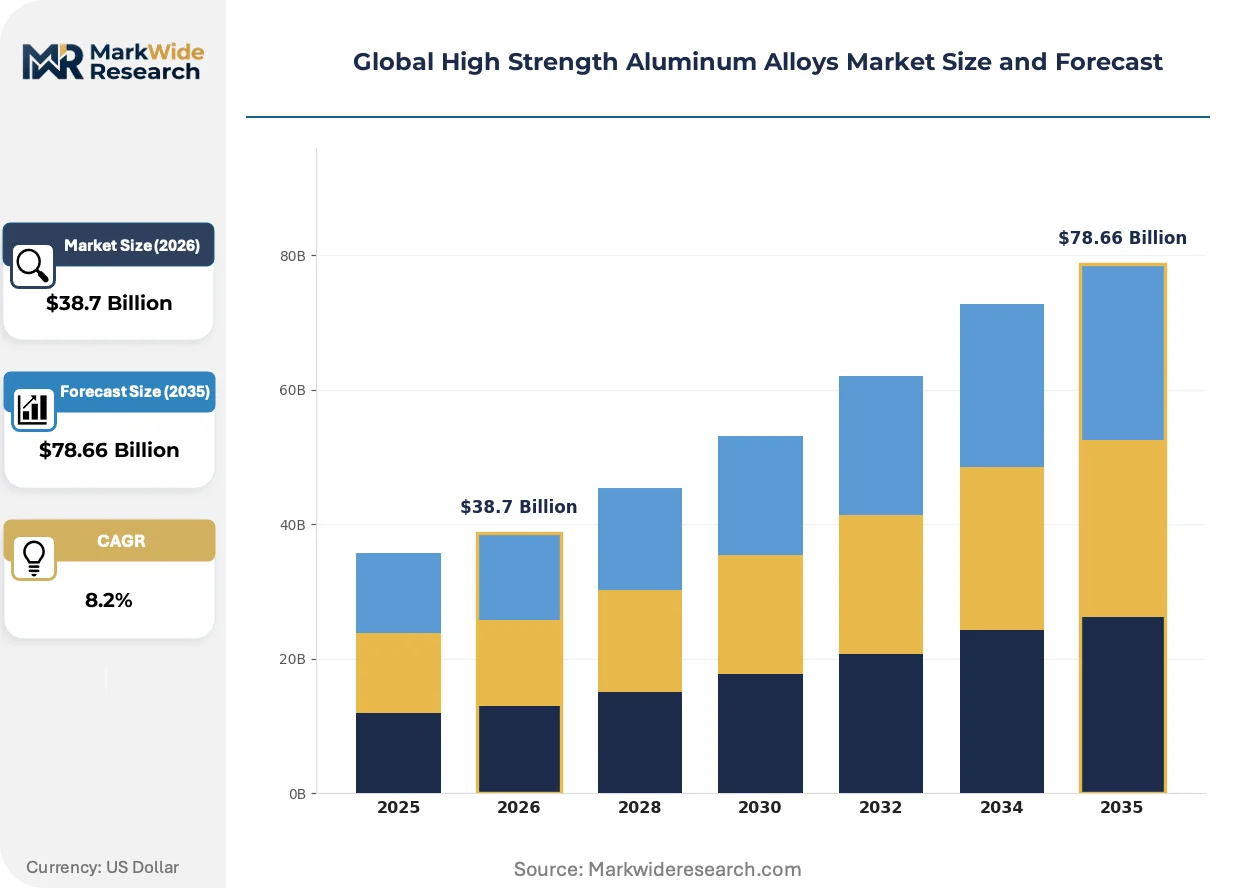
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $78.66 Billion |
| CAGR (2026 – 2036) | 8.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: 7xxx Series, 6xxx Series, 5xxx Series, 2xxx Series, 1xxx Series Form: Sheets, Plates, Extrusions, Forgings, Rods Application: Aerospace Components, Marine Structures, Consumer Electronics, Rail Manufacturing, Defense Equipment End User Industry: Transportation Manufacturers, Packaging Companies, Construction Firms, Electrical Equipment Makers, Sports Goods Producers |
| Companies Covered | Alcoa Corporation, Constellium SE, Hindalco Industries, Rio Tinto, Novelis Inc, Kaiser Aluminum Corporation, Norsk Hydro ASA, UACJ Corporation, Aluminum Corporation of China Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global High Strength Aluminum Alloys Market Strategic Shifts & Innovations
The competitive landscape is defined by a materials science race to develop alloys that simultaneously improve performance, reduce production costs, and enhance sustainability credentials. This pursuit of multi-objective optimization is pushing innovation in both alloy composition and processing technology.
Advanced scandium-containing aluminum alloys provide exceptional strength, weldability, and corrosion resistance. Aerospace and defense programs are the primary adopters of these materials for high-performance structural components. In niche applications where performance is paramount, Al-Sc alloys are overtaking traditional 7xxx series alloys due to their superior fatigue life and stability at elevated temperatures.
The EU's Carbon Border Adjustment Mechanism (CBAM) is a pivotal policy shift. This regulation applies a carbon price to imported goods, including aluminum, based on their embedded emissions. This directly impacts material sourcing for European automotive and industrial sectors, which are now incentivized to procure aluminum from producers utilizing low-carbon energy or high levels of recycled content.
A notable behavioral shift is occurring in how vehicle manufacturers evaluate materials, moving from upfront cost-per-kilogram to a total lifecycle cost analysis. This new procurement logic disrupts traditional purchasing models for body-in-white structures. The trend is most pronounced in the electric vehicle segment, where the impact of lightweighting on battery size and vehicle range is a critical factor in design and sourcing decisions.
Global High Strength Aluminum Alloys Market Segmentation
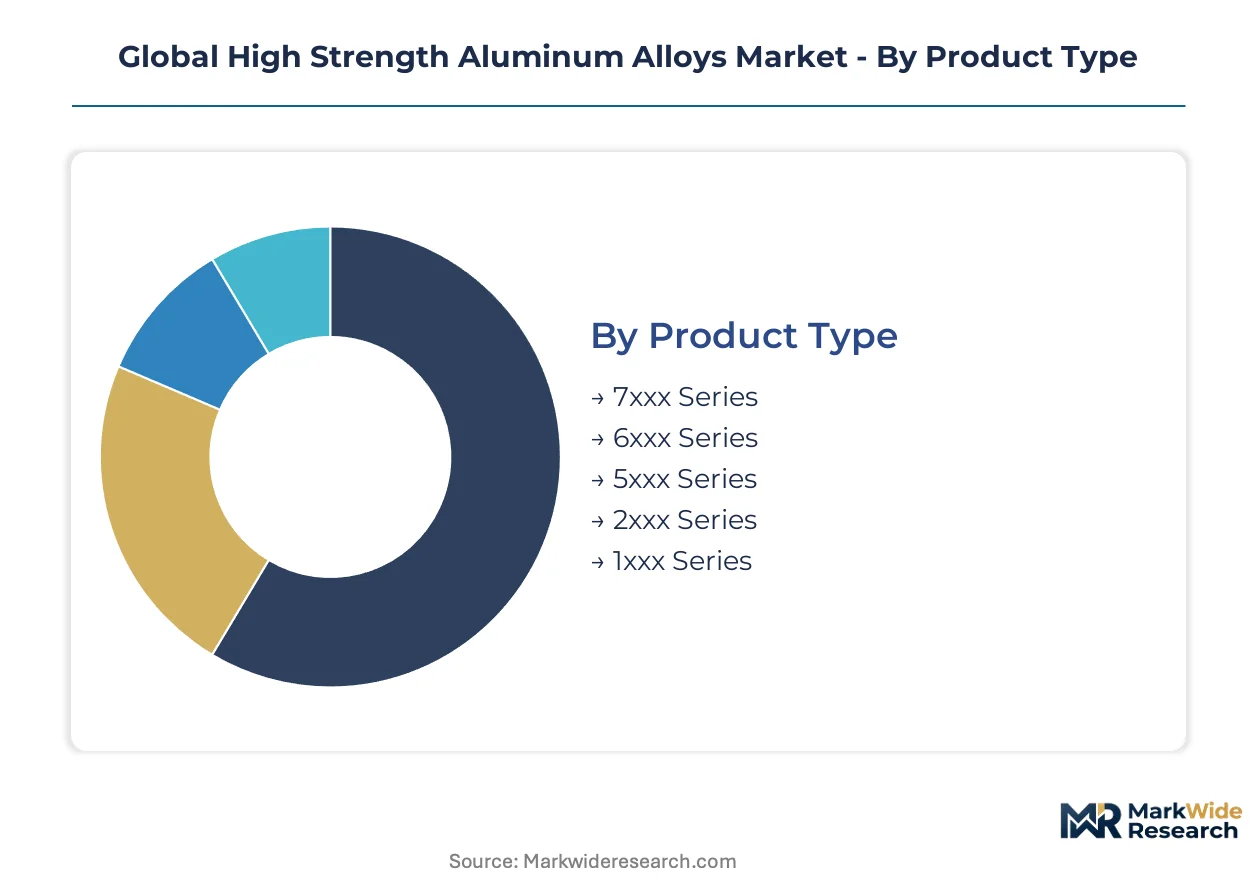
The high strength aluminum alloys market segments by product type, form, application, and end-user industry, reflecting the diverse material requirements and performance specifications across critical sectors. Understanding these distinctions is essential for suppliers to tailor product offerings and navigate complex regulatory landscapes. This granular segmentation provides clarity on demand drivers and competitive dynamics.
Product Type:
The selection of specific high strength aluminum alloy series often depends on stringent performance mandates and certification processes from bodies like the US Federal Aviation Administration (FAA) for aerospace or the EU's REACH regulation for industrial use.
- 7xxx Series:These alloys, primarily aluminum-zinc-magnesium, deliver exceptional strength-to-weight ratios, making them critical for structural components in demanding applications. Demand concentrates in the aerospace sector for aircraft fuselages and wings, driven by the need for superior fatigue resistance and operational safety.
- 2xxx Series:Comprising aluminum-copper alloys, these materials offer high strength and good fracture toughness, crucial for high-stress applications. Significant consumption occurs in China's expanding high-speed rail and commercial aviation programs, such as the COMAC C919, where performance under dynamic loads is paramount.
- 6xxx Series:These aluminum-magnesium-silicon alloys balance strength with good formability and weldability.
- 5xxx Series:Known for their excellent corrosion resistance and moderate strength, these alloys find use in marine and general industrial applications.
- 1xxx Series:Primarily unalloyed aluminum, this series provides high electrical conductivity and corrosion resistance but lower strength compared to other series.
Leading the category by volume: 6xxx Series. Growing fastest: 7xxx Series.
Form:
The physical form of high strength aluminum alloys directly influences their processing and integration into end products, with specific forms dominating volume contribution across different manufacturing techniques.
- Extrusions:Produced by forcing heated aluminum through a die, extrusions offer complex cross-sections and excellent dimensional consistency, vital for automotive body structures. Transportation manufacturers in Europe and North America increasingly specify these for lightweight chassis and frame components, reducing overall vehicle mass.
- Plates:These flat, thick sheets are essential for large structural elements requiring high strength and rigidity, particularly in aerospace and defense. Demand for high-quality plates is significant in the US for military aircraft and naval vessel construction, where material integrity is non-negotiable.
- Sheets:Thinner than plates, sheets are widely used for non-structural and semi-structural components due to their lighter weight and formability.
- Forgings:Forgings provide superior mechanical properties and grain structure, making them suitable for high-stress parts like landing gear components.
- Rods:Rods are versatile forms used for machining into various components, including fasteners and small structural parts.
These forms collectively address diverse market needs, with Extrusions showing significant expansion due to automotive lightweighting.
Application:
The application segments highlight the specific end-uses where high strength aluminum alloys deliver critical performance advantages, often commanding premium margin profiles due to stringent performance requirements.
- Aerospace Components:This segment demands the highest performance alloys for parts like wing skins, fuselage sections, and structural frames. The necessity for superior strength-to-weight ratios and fatigue life drives consistent investment in advanced 7xxx series alloys, contributing to high-value market segments.
- Rail Manufacturing:High strength aluminum alloys are crucial for high-speed train bodies and structural elements, reducing weight and improving energy efficiency. China's extensive high-speed rail network expansion creates substantial concentrated demand for these materials, particularly 2xxx series alloys.
- Marine Structures:Aluminum alloys provide corrosion resistance and reduced weight for ship and boat components, improving fuel efficiency.
- Consumer Electronics:Lightweight and strong aluminum alloys are used for device casings and internal frames, enhancing durability and aesthetics.
- Defense Equipment:These alloys are vital for military vehicles, aircraft, and armor, offering a balance of protection and mobility.
The integration of high strength aluminum alloys in Aerospace Components continues to drive innovation, while Rail Manufacturing demonstrates robust market adoption.
End User Industry:
End-user industries determine the scale and nature of demand for high strength aluminum alloys, with varying levels of market maturity and adoption rates across sectors.
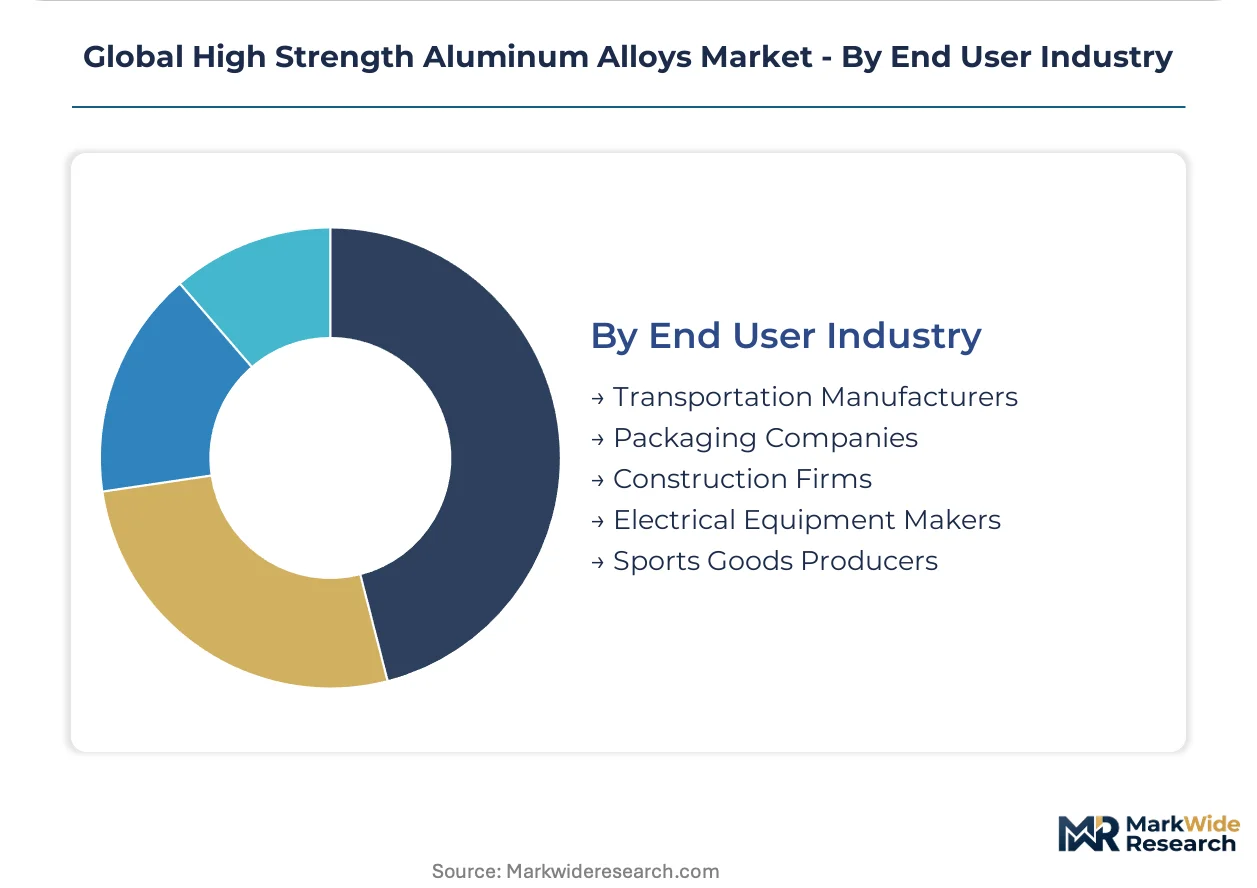
- Transportation Manufacturers:This segment encompasses automotive, aerospace, and rail industries, which are the primary drivers for high strength aluminum alloys due to lightweighting mandates and fuel efficiency requirements. Automotive manufacturers, particularly in Europe and North America, are rapidly integrating these alloys into electric vehicle architectures for battery enclosures and crash management systems.
- Construction Firms:High strength aluminum alloys find use in architectural structures, facades, and infrastructure projects where durability, aesthetics, and corrosion resistance are valued. This sector represents a mature but steadily expanding market for aluminum products.
- Packaging Companies:While not typically using high strength alloys, some specialized packaging requires enhanced material properties for structural integrity.
- Electrical Equipment Makers:Aluminum's conductivity and light weight make it suitable for various electrical components and housings.
- Sports Goods Producers:Lightweight and durable aluminum alloys are used in equipment like bicycle frames, tennis rackets, and camping gear.
Transportation Manufacturers consistently represent a core market, with Construction Firms exhibiting a strong growth trajectory due to sustainable building practices.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand-side concentration for high strength aluminum alloys is particularly pronounced in regions with advanced manufacturing capabilities and stringent environmental regulations. Key countries are driving innovation and adoption across transportation sectors, balancing performance needs with sustainability goals.
China
China's extensive state-led industrial expansion in aerospace and high-speed rail networks creates significant demand for high strength aluminum alloys. MIIT directives influence material standards for domestic automotive and electronics industries, promoting local sourcing. Manufacturing hubs like Shanghai and Chengdu are central to COMAC C919 aircraft production, heavily utilizing 2xxx and 7xxx series alloys.
United States
The United States aerospace and defense sectors are primary consumers of high strength aluminum, driven by stringent FAA certification processes. Automotive lightweighting mandates, such as corporate average fuel economy standards, stimulate aluminum use in electric vehicle architectures. Major aerospace clusters in Seattle and Wichita demand advanced plates and extrusions for aircraft components.
Germany
Germany's automotive industry, particularly in electric vehicle development, increasingly integrates high strength aluminum for battery enclosures and crash management systems. The EU's REACH regulation under ECHA governs material specifications, impacting alloy selection for industrial applications. Automotive manufacturing centers in Bavaria and Baden-Württemberg are at the forefront of this material substitution.
Japan
Japan's high-speed rail infrastructure and advanced automotive manufacturing require high strength aluminum alloys for lightweighting and performance. METI guidelines encourage material innovation and efficiency across industrial sectors. Major industrial regions like Nagoya and Osaka are key centers for producing and incorporating these specialized aluminum forms.
Global High Strength Aluminum Alloys Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, reflecting varied R&D intensity and production scales. The market structure exhibits a tiered consolidation, with a few large integrated producers alongside numerous specialized fabricators. Key strategic archetypes include integrated primary aluminum producers, downstream alloy specialists, and advanced material solution providers. Dominant competitive moves involve strategic partnerships for alloy development and capacity expansion in key growth regions.
Among integrated primary aluminum producers, Alcoa Corporation leverages its extensive production chain to supply demanding sectors like aerospace. Constellium SE occupies a position as a specialist in advanced automotive body-in-white solutions, catering to transportation manufacturers. Hindalco Industries, with its broad portfolio of rolled and extruded products, represents a diversified player addressing various industrial applications across different geographies.
| Leading Market Players |
|---|
| Alcoa Corporation |
| Constellium SE |
| Hindalco Industries |
| Rio Tinto |
| Novelis Inc |
| Kaiser Aluminum Corporation |
| Norsk Hydro ASA |
| UACJ Corporation |
| Aluminum Corporation of China Limited |
| Others |
Cost & Logistics Intelligence
Automotive lightweighting mandates compel manufacturers to seek cost-effective high-strength aluminum, shaping supply responses and influencing alloy pricing across the value chain. This demand-side pressure drives material sourcing economics for vehicle platforms.
Pricing Analysis
Volume-driven segments like automotive prioritize cost efficiency, while aerospace components command premium margins due to stringent performance requirements. The dominant pricing model involves contract-based long-term offtake agreements, influenced by specific quality grade certifications and volume scale. Cost compression in automotive grades stems from intense competition among suppliers and the availability of advanced high-strength steels. Automotive manufacturers exhibit high price sensitivity, whereas aerospace buyers prioritize material integrity and certification, showing less price elasticity.
Supply Chain Analysis
Dual-sourcing requirements from major transportation manufacturers aim to mitigate supply risks and ensure material availability for critical applications. The supply of primary aluminum and high-strength alloys concentrates in China, the United States, and Germany. Production heavily relies on consistent access to bauxite, electricity, and key alloying elements like copper and zinc. Commodity price volatility for energy and raw materials presents a significant structural risk, with distribution primarily through direct sales to OEMs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The high-strength aluminum alloys market is characterized by a vertical-integration race, with producers actively pursuing upstream control over primary aluminum production to manage input costs. This strategic focus aims to secure raw material supply and enhance cost stability.
For Market Incumbents: Lock in long-term supply agreements with major aerospace OEMs to secure consistent demand against competition from carbon fiber reinforced plastics. Invest heavily in advanced alloy research and development for next-generation electric vehicle platforms, focusing on improved formability and weldability. Prioritize certification investment with bodies like the FAA and ECHA to maintain market access and differentiate offerings.
For New Entrants and Emerging Players: Small and medium-sized industrial machinery manufacturers represent an underserved buyer archetype, particularly in robotics and factory automation. Target the European industrial machinery sector by offering customized alloy formulations that displace steel in moving gantries and robotic arms. A go-to-market angle emphasizing rapid prototyping and technical support can build early market share.
For Investors and Strategic Acquirers: The window for entry favors strategic acquirers seeking to consolidate fragmented downstream processing capabilities. Long-term viability remains strong, driven by sustained demand for lightweighting across transportation sectors over the next decade. Target specialized fabricators possessing advanced joining technologies or producers of high-performance scandium-containing alloys. Increased merger and acquisition activity among downstream processors signals market consolidation and growth opportunities.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion for 7xxx Series | Supports growing aerospace and defense demand in the United States and China. |
| Green Manufacturing Transition | Aligns with EU Green Deal and CBAM regulations, reducing embedded carbon emissions. |
| Long-term Supply Agreements with OEMs | Secures stable demand from automotive manufacturers for electric vehicle components. |
| Joint Venture for Additive Manufacturing | Accelerates development of complex, topology-optimized parts for aerospace applications. |
| Certification Investment for New Alloys | Ensures market access and compliance with stringent FAA and ECHA material standards. |
Research Approach
Trade association data, regulatory filings from bodies like the FAA and MIIT, and customs records anchored secondary inputs for this study. Primary interviews with R&D directors, OEM procurement leads, material scientists, and supply chain managers provided critical qualitative insights. This approach combined bottom-up market sizing with top-down validation, ensuring comprehensive data triangulation.
Data-stream reconciliation integrated historical trends with future projections across the analysis window, utilizing a robust analytical framework. Segmentation dimensions included product type, form, application, end-user industry, and regional manufacturing clusters. Compound Annual Growth Rates were derived from an assessment of demand drivers and supply-side capacities. Key forecast inputs included global vehicle production volumes and commercial aircraft delivery schedules.
Revisions become necessary when significant energy price shocks, unforeseen new material breakthroughs, or shifts in geopolitical trade policies materialize. Forecasts reflect assumptions regarding technological adoption rates and regulatory stability. Deviation in these critical external factors would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aerospace and Aircraft Materials
Supersonic Wind Tunnel Market
Aerospace and Aircraft Materials
Out-of-Autoclave Composite Skin Panels for Regional and Business Jets Market
Aerospace and Aircraft Materials
Defense Aircraft Material Market
Aerospace and Aircraft Materials
Europe Advanced Aerospace Coatings Market
Aerospace and Aircraft Materials
Aerospace Titanium Market
Aerospace and Aircraft Materials
Aerospace Coatings Market
Aerospace and Aircraft Materials
Aerospace Carbon Fiber Market
Aerospace and Aircraft Materials
Aircraft AFP and ATL Composites Market
Aerospace and Aircraft Materials
Global Composite Materials Aluminum Alloys Aerospace Market
Aerospace and Aircraft Materials
Radiation Shielding Market
Aerospace and Aircraft Materials
Global Flame Retardant for Aerospace Plastics Market
Aerospace and Aircraft Materials
Global Anti-Icing Coating Market
Aerospace and Aircraft Materials
Aerospace Lightweight Materials Market
Aerospace and Aircraft Materials
Aerospace Materials Market
Aerospace and Aircraft Materials
Aerospace Composites Market
Aerospace and Aircraft Materials
Aerospace Ceramic Matrix Composites Market