
 Europe Advanced Aerospace Coatings Market | 2026-2036
Europe Advanced Aerospace Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Advanced Aerospace Coatings Market Analysis
Maintenance providers are redrawing demand patterns in the Europe advanced aerospace coatings landscape as aging narrowbody fleets drive heavier overhaul cycles. PPG Industries leverages its broad MRO distribution network across Western Europe to capture recurring revenue streams. Akzo Nobel anchors its position through deep R&D ties with Dutch and German OEM engineering centers. Mankiewicz Group specializes in high-performance interior and exterior aviation finishes that meet stringent OEM qualification protocols.
Advanced aerospace coatings comprise engineered surface treatments—typically ceramic-metallic thermal barriers, chromate-free polymer primers, or vapor-deposited functional films—applied to airframes, engines, and landing systems to resist oxidation, erosion, and thermal fatigue while reducing drag and ice accretion. Their primary purpose is extending component life and improving fuel efficiency under extreme operational stress. Thermal barrier coatings command the deepest margin pools given turbine entry temperature thresholds that demand yttria-stabilized zirconia formulations. Anti-corrosion coatings dominate volume through structural airframe applications where salt-laden European maritime routes accelerate substrate degradation. Ceramic materials lead technology roadmaps as engine OEMs pursue higher thrust-to-weight ratios.
EMA chemical safety assessments, REACH substance restrictions, and the EU Green Deal industrial emissions framework collectively mandate chromate elimination and solvent reduction across coating supply chains. EASA airworthiness directives further tighten flame resistance and outgassing standards for cabin interior applications. Stakeholders must monitor regulatory divergence between EU harmonized rules and post-Brexit UKCA marking requirements that could fragment qualification pathways for cross-border suppliers.
Market Dynamics
REACH substance restrictions and the EU Green Deal are forcing chromate elimination across European coating supply chains, compressing qualification timelines while raising R&D burn rates for reformulators serving EASA-certified applications.
Growth Catalysts
- Fleet Age Dynamics:European narrowbody fleets are approaching heavy overhaul cycles, driving MRO procurement of thermal barrier and anti-corrosion systems at elevated volumes.
- EU Green Deal Mandates:The industrial emissions framework is accelerating solvent reduction requirements, pulling demand toward waterborne and high-solids formulations that meet tightened VOC thresholds.
- Ceramic-Metallic Formulations:Yttria-stabilized zirconia thermal barriers are capturing expanded share of turbine maintenance spend as OEMs push turbine entry temperatures higher.
Market Restraints
- Raw Material Concentration:Specialty zirconia and rare earth oxide supply concentrates among Chinese processors, exposing European formulators to export restriction risk and price volatility.
- Qualification Friction:EASA airworthiness directives impose multi-year certification timelines for new chemistries, freezing out experimental formulations from revenue-generating applications.
- Chromate Substitution Costs:Non-chromate corrosion inhibitors require 15-40% higher application thickness to match legacy hexavalent chromium performance, inflating material and labor costs per airframe.
Strategic Opportunities
- UKCA Divergence Arbitrage:Post-Brexit qualification pathway fragmentation creates first-mover advantage for suppliers establishing parallel certification infrastructure in both EU and UK jurisdictions.
- Interior Outgassing Compliance:EASA flame resistance and cabin air quality standards are pulling demand toward low-emission polyurethane and epoxy systems for seating and panel applications.
- Plasma-Deposited Functional Films:Physical vapor deposition is converging with polymer topcoats to enable multi-functional surfaces combining erosion resistance with ice-phobic properties.
Industry Challenges
- Formulation Chemist Scarcity:Expertise in chromate-free corrosion science and ceramic precursor chemistry sits concentrated among retiring specialists at German and Dutch research institutes.
- Application Equipment Retrofit:Waterborne and high-solids chemistries require heated spray systems and controlled-environment booths that MRO facilities must finance amid compressed airline maintenance budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Advanced Aerospace Coatings Market |
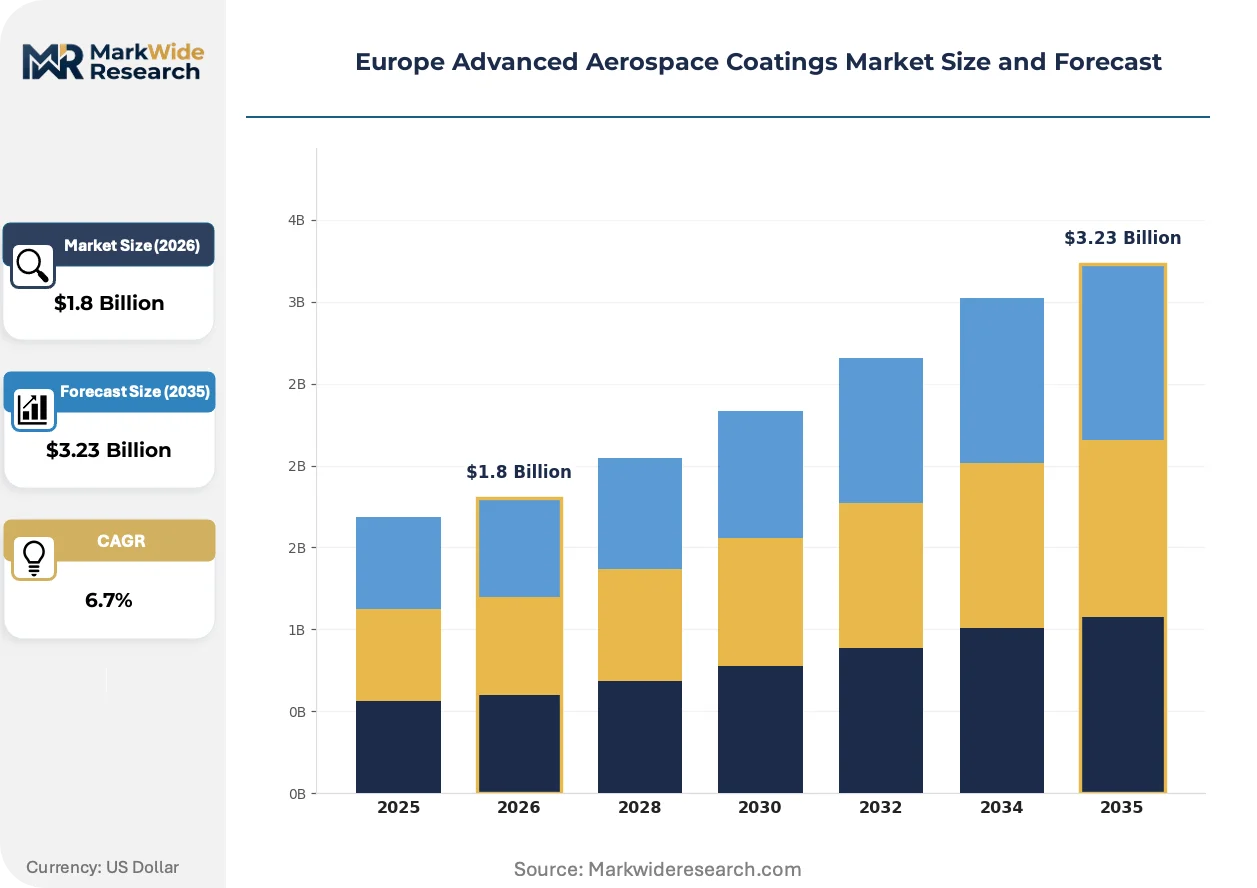
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Coating Type: Thermal Barrier Coatings, Anti-Corrosion Coatings, Low Friction Coatings, Anti-Icing Coatings Application: Aerospace Structures, Engine Components, Interior Surfaces, Landing Gear Material: Ceramic, Polymer, Metal, Composite End User: Commercial Aviation, Military Aviation, Space Exploration, Maintenance Providers |
| Companies Covered | The Sherwin Williams Company, Akzo Nobel, PPG Industries, Henkel AG & Co. KGaA, BASF SE, Mankiewicz Group, IHI Ionbond AG, Praxair, PG Technologies, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Advanced Aerospace Coatings Market Emerging Trajectories
Formulation chemistry and application methodology are undergoing simultaneous transformation as regulatory deadlines collide with engine performance roadmaps, reshaping competitive position among European qualified suppliers.
Sol-gel derived ceramic coatings are supplanting traditional plasma-sprayed thermal barriers in select turbine applications, offering reduced thermal conductivity at thinner deposition profiles. German engine MRO specialists are adopting these systems for hot-section component restoration, compressing turnaround times while extending part life cycles beyond OEM specification limits.
REACH Annex XVII restrictions on chromium trioxide are tightening substance authorization requirements, forcing reformulators to complete substitution dossiers before 2027 sunset dates. Airframe maintenance providers in France and the United Kingdom are accelerating chromate-free primer trials, though qualification lag with OEM engineering authorities is delaying fleet-wide rollout.
Airline technical procurement teams are consolidating coating supply under multi-year framework agreements that bundle material, application labor, and performance warranties. This behavior is concentrating purchasing power among top-tier European flag carriers, squeezing margins for independent MRO shops that lack volume leverage with PPG, Akzo Nobel, and Mankiewicz distribution networks.
Europe Advanced Aerospace Coatings Market Segmentation
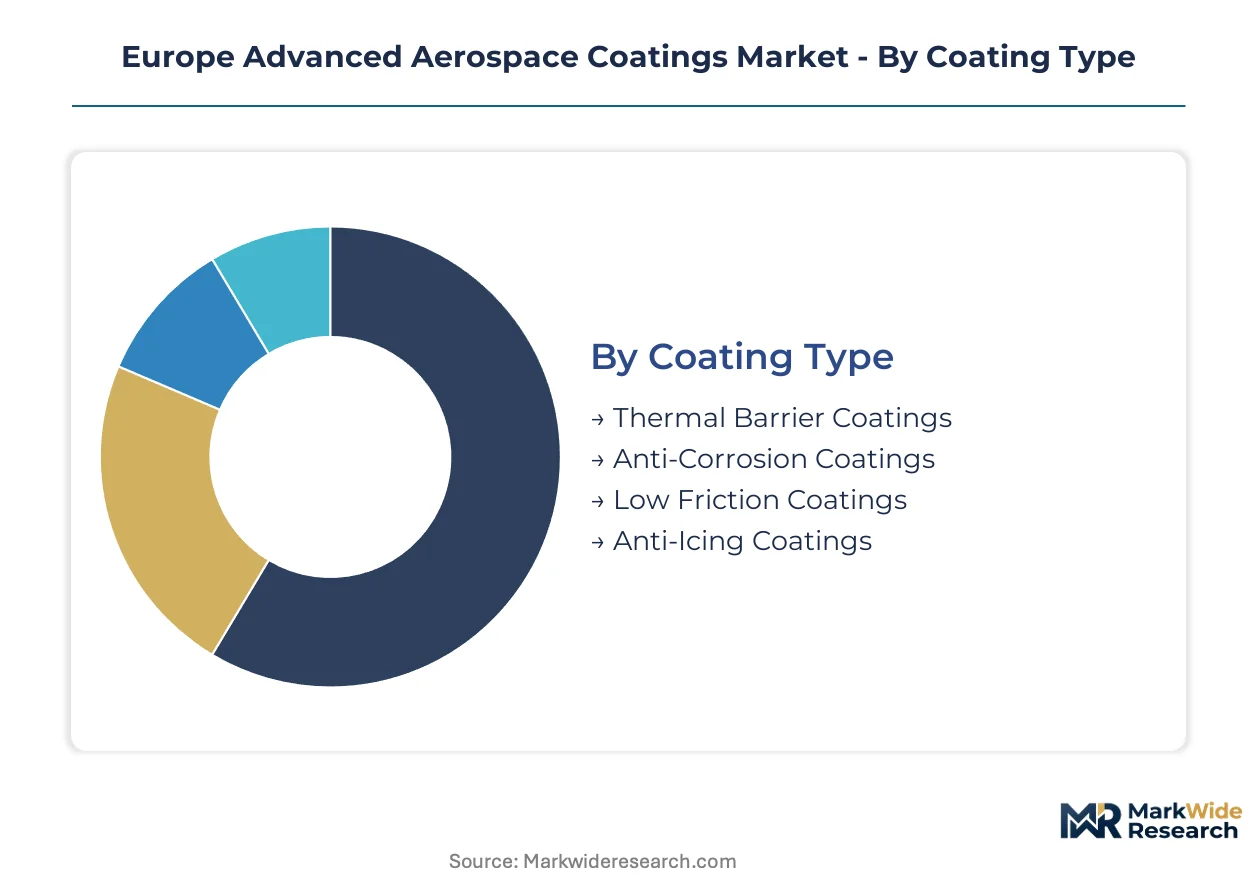
Advanced aerospace coatings in Europe fragment across functional chemistries, application sites, and procurement channels. Each segmentation axis carries distinct qualification requirements under EASA airworthiness directives and REACH substance restrictions, shaping supplier positioning and margin structures.
Coating Type:
REACH substance restrictions and EASA flame resistance standards differentiate coating chemistries by hazard classification and authorization burden.
- Thermal Barrier Coatings:Yttria-stabilized zirconia ceramic-metallic formulations insulate turbine blades and combustor liners from temperatures exceeding 1,200°C. German engine MRO clusters in Hamburg and Munich drive procurement as narrowbody fleets age into hot-section overhaul cycles.
- Anti-Corrosion Coatings:Chromate-free polymer primers and sacrificial metallic layers protect aluminum airframes from salt-laden maritime routes across the North Atlantic and Mediterranean. French and UK maintenance providers face compressed substitution timelines as chromium trioxide authorization sunsets approach.
- Low Friction Coatings:PTFE-impregnated and MoS2-based dry lubricants reduce actuation drag in flight control systems.
- Anti-Icing Coatings:Hydrophobic nano-structured surfaces and resistive heating films prevent ice accretion on leading edges and engine inlets.
Established volume favors Anti-Corrosion Coatings; emerging adoption favors Thermal Barrier Coatings.
Application:
Application site determines thermal exposure severity, accessibility for rework, and OEM engineering authority involvement in qualification.
- Aerospace Structures:Exterior skins, lap joints, and pressure vessels require multi-layer primer-topcoat systems resisting UV degradation and cyclic loading. UK and French airframe MROs concentrate procurement where aging A320 and 737 fleets enter heavy check cycles.
- Engine Components:Combustors, turbines, and afterburners demand ceramic thermal barriers and abradable seal coatings. German OEM engineering centers in Munich and Stuttgart set specification standards that cascade through European supply chains.
- Interior Surfaces:Cabin panels, seating, and galleys need low-outgassing polyurethanes meeting EASA flame resistance and air quality directives.
- Landing Gear:Oleo struts, wheels, and brakes utilize hard chrome alternatives and corrosion-resistant topcoats for high-cycle fatigue environments.
Procurement scale concentrates in Aerospace Structures; technology complexity peaks in Engine Components.
Material:
Raw material sourcing geography and processing energy intensity separate material classes by supply security and carbon footprint.
- Ceramic:Yttria-stabilized zirconia and alumina formulations dominate turbine applications. Chinese rare earth oxide concentration creates supply vulnerability for European formulators.
- Polymer:Epoxy, polyurethane, and polysiloxane systems span primers, topcoats, and interior finishes. REACH solvent restrictions accelerate waterborne and high-solids formulation transitions.
- Metal:Aluminum-filled sacrificial primers and plasma-sprayed MCrAlY bond coats provide corrosion barriers and oxidation resistance.
- Composite:Carbon fiber-compatible surfacing films and lightning strike coatings address conductivity and galvanic isolation in CFRP primary structures.
Ceramic commands the steepest expansion trajectory as engine OEMs push turbine entry temperatures higher.
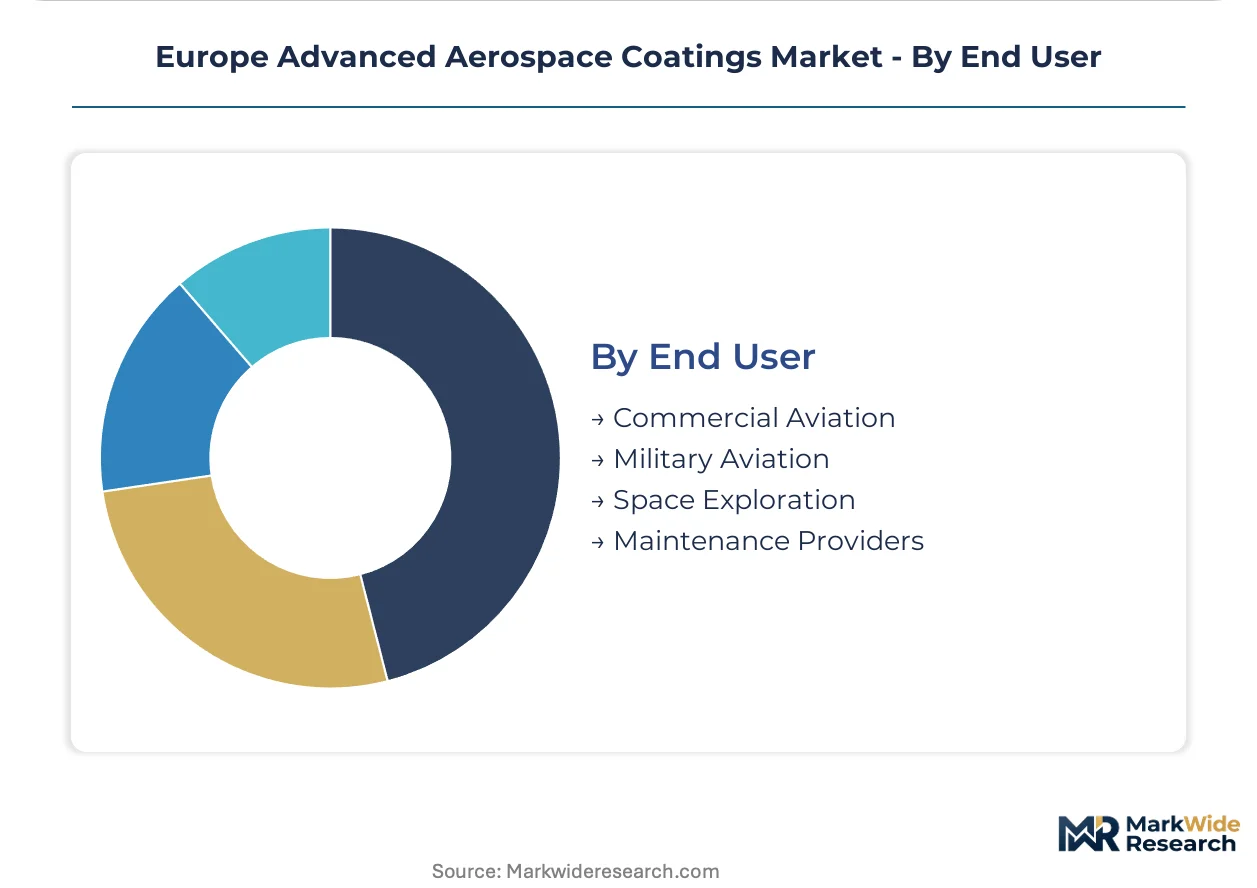
End User:
Procurement consolidation patterns and qualification sovereignty distinguish end-user channels across European jurisdictions.
- Commercial Aviation:Flag carriers and low-cost operators bundle coating procurement under multi-year framework agreements. Lufthansa, Air France-KLM, and IAG concentrate purchasing power, squeezing independent MRO margins.
- Military Aviation:National defense procurement offices in France, Germany, and the UK specify MIL-PRF qualified systems with enhanced stealth and signature management requirements.
- Space Exploration:ArianeGroup and emerging UK launch providers drive demand for thermal control coatings and atomic oxygen-resistant finishes.
- Maintenance Providers:Independent MRO shops and airline captive facilities represent the fragmented procurement channel most exposed to REACH compliance cost inflation.
Commercial Aviation anchors procurement volume; Space Exploration offers the most rapid adoption curve for novel functional coatings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialty coating formulation concentrates among German and French industrial clusters, with supply chains radiating through Dutch distribution hubs and UK MRO corridors. REACH compliance costs and EASA qualification requirements create geographic moats that favor established European suppliers over import-dependent competitors.
Germany
Aging narrowbody fleets at Lufthansa and Eurowings drive thermal barrier coating procurement for engine overhaul cycles. The EU Green Deal industrial emissions framework mandates solvent reduction timelines that German formulators must meet by 2027. Munich and Stuttgart host OEM engineering centers that set ceramic-metallic specification standards cascading through European supply chains.
United Kingdom
Post-Brexit UKCA marking requirements fragment qualification pathways for cross-border coating suppliers serving British Airways and Virgin Atlantic fleets. The Health and Safety Executive enforces REACH-aligned substance restrictions with divergent sunset dates from EU harmonized rules. London and Bristol MRO clusters accelerate chromate-free primer trials despite OEM engineering authority delays.
France
Air France-KLM procurement consolidation concentrates purchasing power for anti-corrosion systems protecting widebodies on North Atlantic maritime routes. ANSM chemical safety assessments add national-layer authorization burdens atop EMA harmonized standards. Toulouse and Paris aerospace corridors anchor OEM specification development for next-generation low-VOC formulations.
Netherlands
Schiphol cargo hub expansion drives demand for corrosion-resistant landing gear coatings on high-cycle freighter operations. ECHA substance authorization processes in The Hague create regulatory proximity advantages for Dutch-headquartered formulators. Amsterdam and Eindhoven R&D centers specialize in chromate-free corrosion science with deep ties to German OEM engineering networks.
Italy
Leonardo's helicopter and regional jet production lines pull specialty coatings for composite-compatible surfacing films and lightning strike protection. The country's national chemical regulator enforces REACH Annex XVII restrictions with sector-specific guidance for aerospace applications. Turin and Rome maintenance corridors serve Mediterranean carrier fleets requiring salt-spray-resistant structural coatings.
Europe Advanced Aerospace Coatings Market Vendor Landscape
Concentration sits with diversified chemical conglomerates and specialized coating formulators that have secured EASA qualification lock-in through multi-decade OEM engineering relationships. The competitive structure tiers across three archetypes: integrated chemical majors with aerospace divisions, pure-play coating specialists with MRO distribution depth, and regional European champions with national procurement ties. Dominant competitive moves include strategic partnerships for REACH-compliant formulation development and geographic expansion through MRO network acquisition.
Among diversified chemical majors, The Sherwin Williams Company and PPG Industries exemplify the scale-driven archetype with broad MRO distribution networks spanning Western Europe. Akzo Nobel occupies a position within the European-centric tier, anchoring R&D proximity to Dutch and German OEM engineering centers. Mankiewicz Group represents the specialized formulator archetype, with qualification depth in interior and exterior aviation finishes meeting stringent OEM protocols.
| Leading Market Players |
|---|
| The Sherwin Williams Company |
| Akzo Nobel |
| PPG Industries |
| Henkel AG & Co. KGaA |
| BASF SE |
| Mankiewicz Group |
| IHI Ionbond AG |
| Praxair |
| PG Technologies |
| Others |
Supply Flow & Price Mechanics
Ninety-day inventory cycles for yttria-stabilized zirconia precursors signal supply chain rigidity that amplifies pricing power among Chinese rare earth processors, while European formulators absorb cost volatility through long-term offtake contracts with MRO networks. REACH compliance investments and chromate-free formulation R&D further stratify procurement tiers across the value chain.
Pricing Analysis
REACH substance authorization deadlines dictate the pricing tier structure across European aerospace coatings, separating EASA-qualified premium formulations from experimental chemistries awaiting certification. Price differentiation hinges on OEM engineering authority endorsement and chromate-free corrosion inhibitor performance equivalence, with volume-scale discounts concentrating among Lufthansa, Air France-KLM, and IAG framework agreements. Cost compression in mid-tier anti-corrosion primers is intensifying because non-chromate alternatives require thicker application profiles, inflating material and labor inputs. Independent MRO shops exhibit the highest price sensitivity due to compressed airline maintenance budgets, while engine OEMs demonstrate lowest sensitivity given turbine entry temperature thresholds that demand certified ceramic-metallic thermal barriers.
Supply Chain Analysis
China anchors rare earth oxide processing and specialty zirconia precursor production, while Germany and the Netherlands concentrate high-performance formulation and EASA qualification expertise. European coating manufacturers draw from Chinese yttria and alumina feedstocks, German polymer resin supply, and Dutch distribution infrastructure. Single-source vulnerability concentrates in rare earth oxide supply, where export restriction risk from Chinese processors exposes formulators to price spikes and allocation disruptions. Distribution runs through Schiphol cargo hubs and Munich-Stuttgart OEM engineering corridors, with MRO procurement consolidating under multi-year material-plus-labor bundles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized expertise in chromate-free corrosion science and ceramic precursor chemistry is retiring from German and Dutch research institutes faster than knowledge transfer programs can replenish it, compressing the window for capability-building investments.
For Market Incumbents: Consolidate EASA qualification lock-in through accelerated chromate-free primer dossier submissions ahead of REACH sunset deadlines, while securing captive supply of yttria-stabilized zirconia via backward integration into rare earth oxide offtake agreements with Chinese processors. Threat of formulation chemist scarcity demands preemptive recruitment from retiring specialists at Munich and Stuttgart engineering centers. For New Entrants and Emerging Players: Application equipment retrofit services represent an under-served layer where incumbent formulators lack direct MRO facility relationships, offering entry points for technical service providers. Target independent maintenance shops in Italy and Spain requiring heated spray system upgrades for waterborne chemistry compliance. Go-to-market leverage rests on financing partnerships for booth modernization bundled with chromate-free primer supply. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-moat play because EASA multi-year certification timelines freeze out experimental formulations and concentrate value among established qualified suppliers. Acquisition target archetype: mid-tier Dutch or German formulators with existing OEM engineering authority relationships and REACH-compliant product pipelines. Signal to watch is UKCA-EU regulatory divergence accelerating parallel certification infrastructure buildout.| Strategic Initiative | Industry Significance |
|---|---|
| Chromate-Free Formulation Dossier Completion | REACH Annex XVII compliance secures market access beyond 2027 authorization sunsets. |
| Rare Earth Oxide Offtake Agreements | Long-term supply contracts with Chinese processors mitigate yttria price volatility exposure. |
| UKCA Parallel Certification Infrastructure | Post-Brexit qualification pathways capture British Airways and Virgin Atlantic procurement. |
| Application Equipment Financing Partnerships | Heated spray system leases unlock independent MRO shops constrained by capital budgets. |
| OEM Engineering Authority Co-Development | Munich and Stuttgart specification influence cascades through European supply chains. |
Methodological Framework
Two parallel data streams informed the analysis: primary interviews with coating formulators, MRO procurement directors, airline technical fleet managers, and EASA certification specialists; and secondary validation through REACH Annex XVII substance restriction databases, EMA chemical safety assessment filings, customs trade data on rare earth oxide imports, and SEC disclosures from diversified chemical majors. Bottom-up triangulation across MRO procurement volumes and top-down reconciliation against OEM specification standards anchored market size estimates.
Across the analysis window, the forecasting framework modeled coating type segmentation by functional chemistry, application site by thermal exposure severity, material class by raw material sourcing geography, and end-user channel by procurement consolidation patterns. CAGRs were derived from fleet age dynamics, regulatory deadline impacts, and technology substitution curves for ceramic-metallic thermal barriers. Industry-specific inputs included narrowbody heavy overhaul cycle timing and EU Green Deal solvent reduction implementation trajectories.
Forecasts assume regulatory continuity in REACH authorization processes and EASA airworthiness directives; material policy shifts including accelerated chromate sunset dates or divergent UKCA substance restrictions would require re-modeling. Recalibration cycles align with material shifts in fleet age demographics, rare earth oxide export policy, and OEM turbine temperature roadmaps.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aerospace and Aircraft Materials
Aerospace and Defense Composites Market
Aerospace and Aircraft Materials
Aerospace Foam Market
Aerospace and Aircraft Materials
Commercial Aerospace 3D Printing Market
Aerospace and Aircraft Materials
Commercial Aerospace Carbon Brakes Market
Aerospace and Aircraft Materials
Aerospace Superalloys Market
Aerospace and Aircraft Materials
Aircraft Coatings Market
Aerospace and Aircraft Materials
Aircraft Insulation Materials Market
Aerospace and Aircraft Materials
Aerospace Lightweight Materials Market
Aerospace and Aircraft Materials
Aerographite Market
Aerospace and Aircraft Materials
Additive Manufactured Pressure Vessel Proof and Burst Test Rigs Market
Aerospace and Aircraft Materials
Global Aerospace Adhesives Market
Aerospace and Aircraft Materials
Global Aerospace Adhesives and Sealants Market
Aerospace and Aircraft Materials
Beryllium Aluminum Alloy Market
Aerospace and Aircraft Materials
Aeroengine Composites Market
Aerospace and Aircraft Materials
Composites in United States Defense Market
Aerospace and Aircraft Materials
Thermal Spray Coating Market