
 Supersonic Wind Tunnel Market | 2026-2036
Supersonic Wind Tunnel Market Size, Share, and Industry Trends Forecast 2026-2036
Supersonic Wind Tunnel Market Insights
China is rewriting capacity dynamics in supersonic wind tunnel infrastructure with expanded government-funded aerodynamic research complexes. Lockheed Martin Corporation sustains deep integration between classified defense programs and captive tunnel testing protocols. Boeing Company leverages its long-standing Calspan partnership to secure priority access for commercial and military airframe validation. ONERA dominates European high-speed aerodynamic research through its Modane-Avrieux facility and collaborative frameworks with DNW.
A supersonic wind tunnel accelerates airflow through a convergent-divergent nozzle to Mach numbers exceeding 1.0, typically operating with total pressures between 100 kPa and 2 MPa and Reynolds numbers up to 100 million per meter for full-scale aircraft simulation. Its primary purpose remains validation of compressible flow behavior, shock-boundary layer interaction, and thermal protection system performance for flight vehicles. Blowdown tunnels capture the largest installed base due to lower capital requirements and operational flexibility across university and mid-tier defense laboratory settings. Continuous wind tunnels command premium positioning among government agencies and prime contractors requiring sustained test durations for missile and reusable spacecraft development. Ludwieg Tube configurations represent the fastest-growing product category, driven by their ability to deliver steady supersonic flow for several hundred milliseconds with significantly reduced energy consumption versus conventional blowdown systems.
FAA airworthiness certification standards and NASA institutional test requirements shape domestic facility investment and capability roadmaps in the United States. ESA's coordination with national European facilities and Japan's METI-funded aerospace technology programs establish parallel regulatory and funding frameworks overseas. Stakeholders must weigh captive facility construction against shared-access partnerships as test queue competition intensifies for hypersonic and next-generation commercial aircraft programs.
Market Dynamics
Hypersonic weapons programs and next-generation commercial aircraft certification timelines are compressing test queue availability at existing facilities, forcing defense primes and aerospace OEMs to choose between captive facility construction and premium-priced priority access contracts.
Growth Catalysts
- NASA Artemis thermal protection validation:Sustained lunar return missions require expanded supersonic and hypersonic test capacity for heat shield materials and aerodynamic configurations.
- FAA Part 25 certification protocols:Next-generation commercial transports with novel wing designs must demonstrate flutter and buffet boundaries through documented wind tunnel campaigns.
- China aerodynamic research complex expansion:Government-funded facility construction in Sichuan and Hebei provinces is adding domestic test capacity for indigenous fighter and spaceplane programs.
Market Restraints
- Energy cost volatility:Continuous wind tunnel operation requires sustained electrical loads exceeding 50 MW, exposing facility operators to regional grid pricing fluctuations.
- Specialized compressor manufacturing concentration:Axial compressor systems for Mach 2+ operation rely on a limited supplier base concentrated in Germany and the United States.
- Reynolds number scaling limitations:Full-scale aircraft simulation demands total pressures beyond 2 MPa, requiring structural reinforcements that extend facility construction timelines.
Strategic Opportunities
- India defense laboratory modernization:DRDO and HAL are expanding indigenous test infrastructure under offset agreements tied to foreign fighter procurement programs.
- Ludwieg Tube technology convergence:Integration of heated driver gas techniques with conventional blowdown architectures is opening mid-duration test segments previously reserved for continuous facilities.
- Japan METI aerospace technology funding:METI grants for hypersonic transport research are channeling investment toward shared-access tunnel networks linking JAXA, Mitsubishi Heavy Industries, and university laboratories.
Industry Challenges
- Computational fluid dynamics validation expertise:Facility operators struggle to recruit engineers capable of correlating tunnel measurements with CFD predictions for complex shock-interaction flows.
- Model fabrication precision:Instrumented test articles for transonic and supersonic regimes require tolerance control below 0.025 mm, constraining qualified supplier networks.
- Test data security protocols:Classified defense programs impose compartmentalized facility access requirements that fragment scheduling efficiency and inflate operational overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Supersonic Wind Tunnel Market |
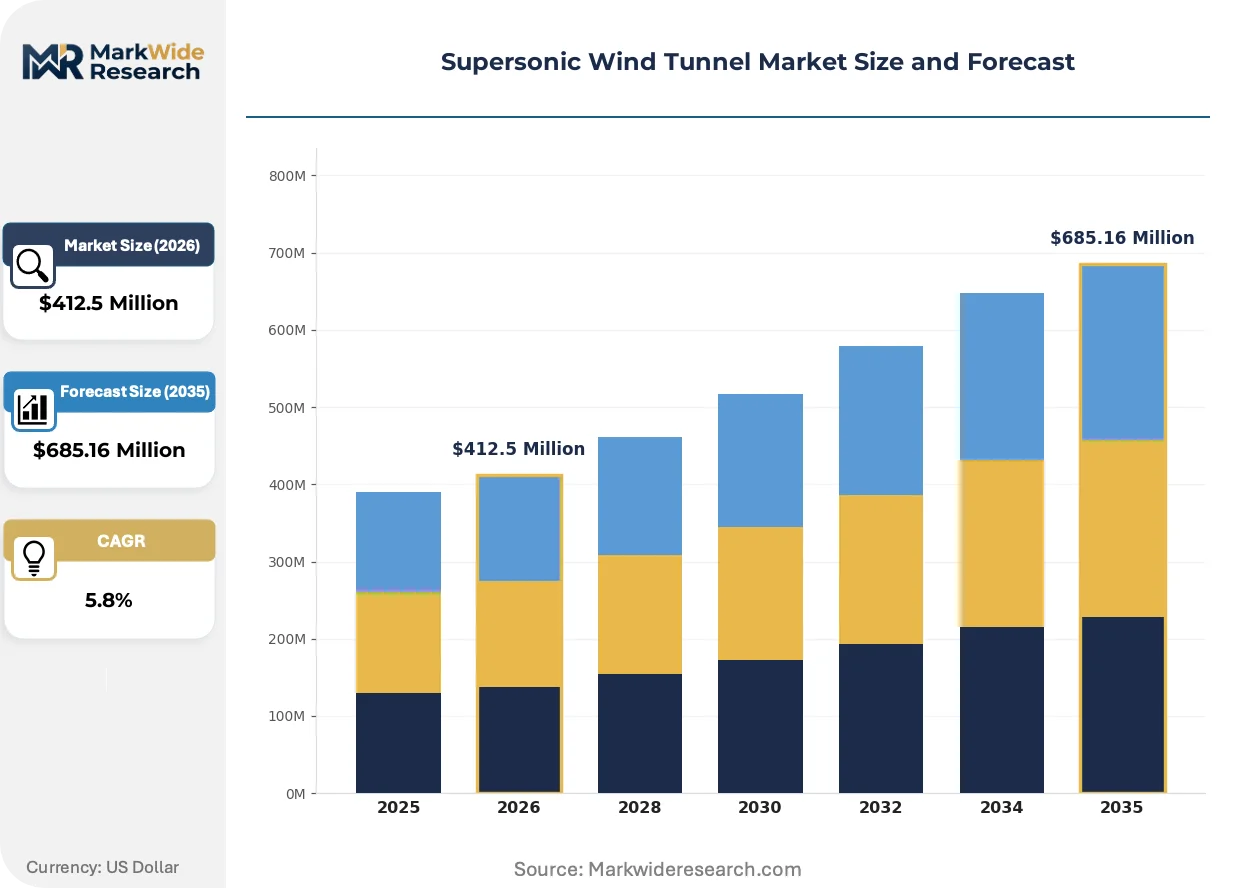
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $685.16 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Blowdown, Indraft, Pressurized, Continuous, Ludwieg Tube Technology: Shock Tube, Nozzle Design, Laser Doppler Anemometry, Particle Image Velocimetry, Pressure Sensitive Paint Application: Aircraft Aerodynamics, Missile Testing, Spacecraft Development, Automotive Aerodynamics, Sports Equipment Analysis End User: Research Laboratories, Government Agencies, Defense Contractors, Aerospace Component Manufacturers, Academic Institutions |
| Companies Covered | Boeing Company, Lockheed Martin Corporation, European Transonic Windtunnel, Calspan Corporation, RUAG Group, ONERA, DNW, Mitsubishi Heavy Industries, NASA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Supersonic Wind Tunnel Market Trends and Innovations
Digital twin integration and additive manufacturing are transforming how test articles are designed, instrumented, and validated, compressing the iteration cycle between computational prediction and empirical verification.
Adaptive wall wind tunnel technology is rendering obsolete fixed-geometry test sections that required extensive wall interference corrections. NASA Glenn and ONERA Modane-Avrieux have commissioned actively controlled flexible walls that adjust contour in real-time to minimize blockage effects. Defense contractors testing classified configurations are accelerating adoption to reduce uncertainty margins and repeat runs.
EU F-Gas Regulation phase-down schedules are forcing facility operators to abandon sulfur hexafluoride as a test gas for high-Reynolds-number simulation. Replacement working fluids with lower global warming potential require redesigned heat exchangers and modified safety protocols. German and French national laboratories are leading qualification campaigns for hydrofluoroolefin blends.
Hypersonic program proliferation is compressing test queue booking windows from twelve months to six months at priority facilities. Boeing and Lockheed Martin are negotiating multi-year block purchase agreements with Calspan and AEDC to secure guaranteed access. University researchers and tier-two suppliers face exclusion or displacement to lower-capability blowdown tunnels.
Supersonic Wind Tunnel Market Segmentation
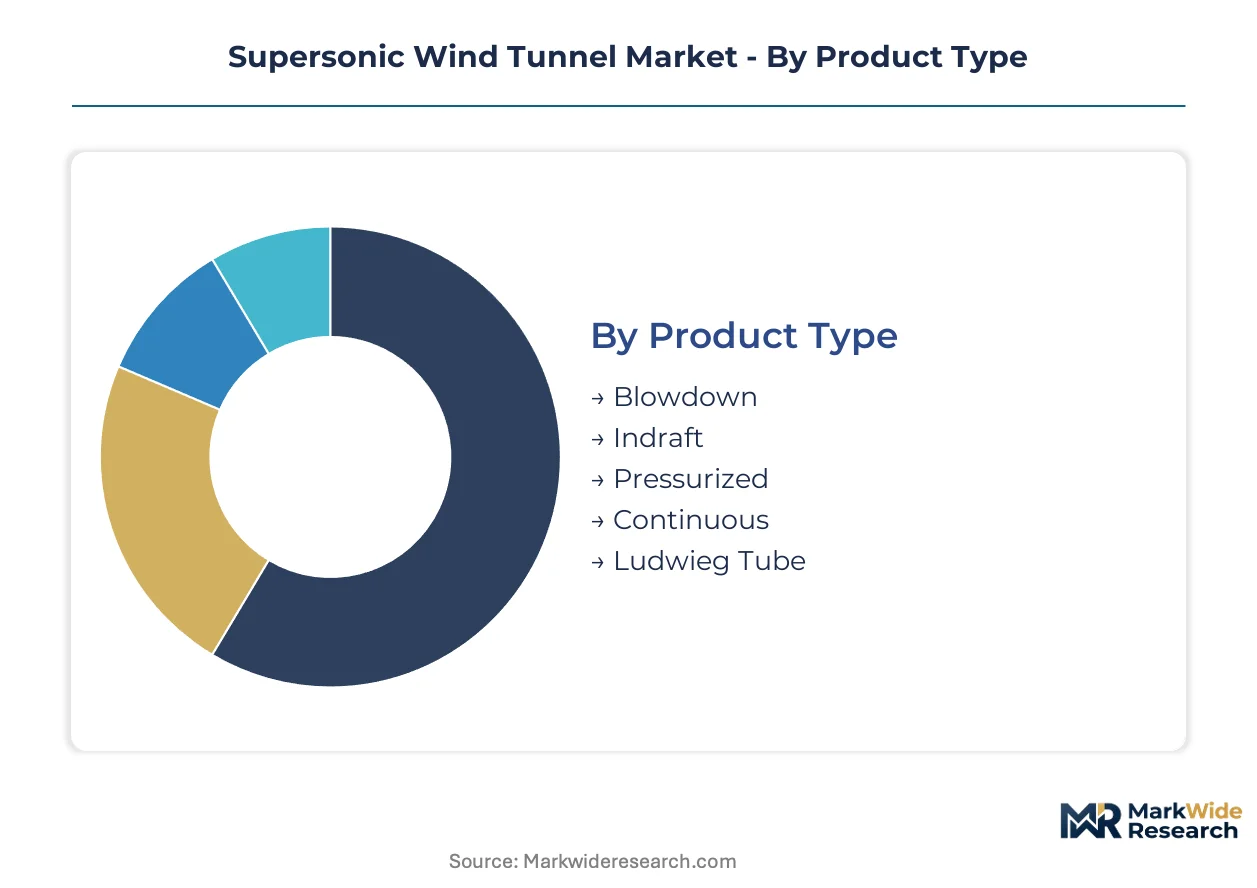
Segmentation in supersonic wind tunnel procurement reflects divergent capital intensity, test duration requirements, and security classification levels. Facility operators and equipment vendors must align product portfolios with distinct operational cadences across defense, commercial aerospace, and research institutional buyers.
Product Type:
Blowdown tunnels turn over fastest in procurement cycles, while continuous facilities lock capital for decades through specialized compressor infrastructure.
- Blowdown:Stores compressed air in high-pressure reservoirs that discharge through convergent-divergent nozzles for test durations of seconds to minutes. Demand concentrates at university laboratories and mid-tier defense facilities in the United States and Germany seeking operational flexibility without continuous electrical loads.
- Continuous:Sustains steady supersonic flow indefinitely through powered compressor loops exceeding 50 MW electrical demand. NASA Glenn Research Center and AEDC in Tennessee anchor demand for missile and reusable spacecraft programs requiring extended thermal soak and flutter boundary mapping.
- Indraft:Draws atmospheric air through vacuum storage vessels to achieve supersonic conditions with minimal compression infrastructure. Suited for low-Reynolds-number aerodynamic studies at reduced capital outlay.
- Pressurized:Elevates test section static pressure to match full-scale Reynolds numbers for commercial transport certification. Boeing and Airbus leverage pressurized tunnels at ONERA Modane-Avrieux for flutter validation.
- Ludwieg Tube:Generates steady supersonic flow for several hundred milliseconds through an unsteady expansion wave in a long driver tube. JAXA and DNW facilities are expanding Ludwieg capacity for hypersonic program support.
Blowdown tunnels dominate installed base. Ludwieg Tube configurations are where expansion concentrates.
Technology:
Measurement technology selection tracks the shift from intrusive probe-based methods toward non-intrusive optical diagnostics that preserve flow fidelity.
- Nozzle Design:Convergent-divergent contour machining determines Mach number precision and boundary layer uniformity. Demand clusters with defense primes in the United States requiring interchangeable nozzle blocks for classified configuration testing.
- Particle Image Velocimetry:Seeds flow with tracer particles and captures velocity fields through pulsed laser sheets and high-speed cameras. ONERA and German DNW facilities are retrofitting test sections with PIV arrays for unsteady flow characterization.
- Shock Tube:Generates step changes in pressure and temperature for millisecond-duration aerodynamic and materials testing. Supports hypersonic impulse facility networks.
- Laser Doppler Anemometry:Measures pointwise velocity through Doppler frequency shift of scattered laser light. Remains prevalent for boundary layer profile validation.
- Pressure Sensitive Paint:Maps surface pressure distributions through oxygen-quenched luminescence imaging. NASA Langley and JAXA deploy PSP for complex shock interaction visualization.
Nozzle Design commands foundational investment. Particle Image Velocimetry is gaining share fastest through facility modernization cycles.
Application:
Application mix shifts with defense procurement waves and commercial aircraft program cadences, creating uneven demand intensity across test facility networks.
- Aircraft Aerodynamics:Validates transonic buffet boundaries, flutter margins, and control surface effectiveness for Part 25 certification. FAA protocols in the United States and EASA requirements in Europe sustain institutional demand at Calspan and ONERA.
- Missile Testing:Characterizes store separation trajectories, fin flutter, and thermal protection performance at Mach 2-5 conditions. Lockheed Martin and Raytheon programs in the United States compress queue availability at AEDC.
- Spacecraft Development:Simulates ascent and reentry aerothermodynamic environments for thermal protection system qualification. NASA Artemis lunar return missions are expanding test capacity requirements.
- Automotive Aerodynamics:Evaluates high-speed stability and drag reduction for performance vehicle programs. Limited supersonic relevance constrains segment scale.
- Sports Equipment Analysis:Optimizes ball flight and cycling aerodynamics through subsonic and low-supersonic regimes. Niche academic and commercial research applications.
Aircraft Aerodynamics anchors facility revenue. Missile Testing is where queue competition intensifies most acutely.
End User:
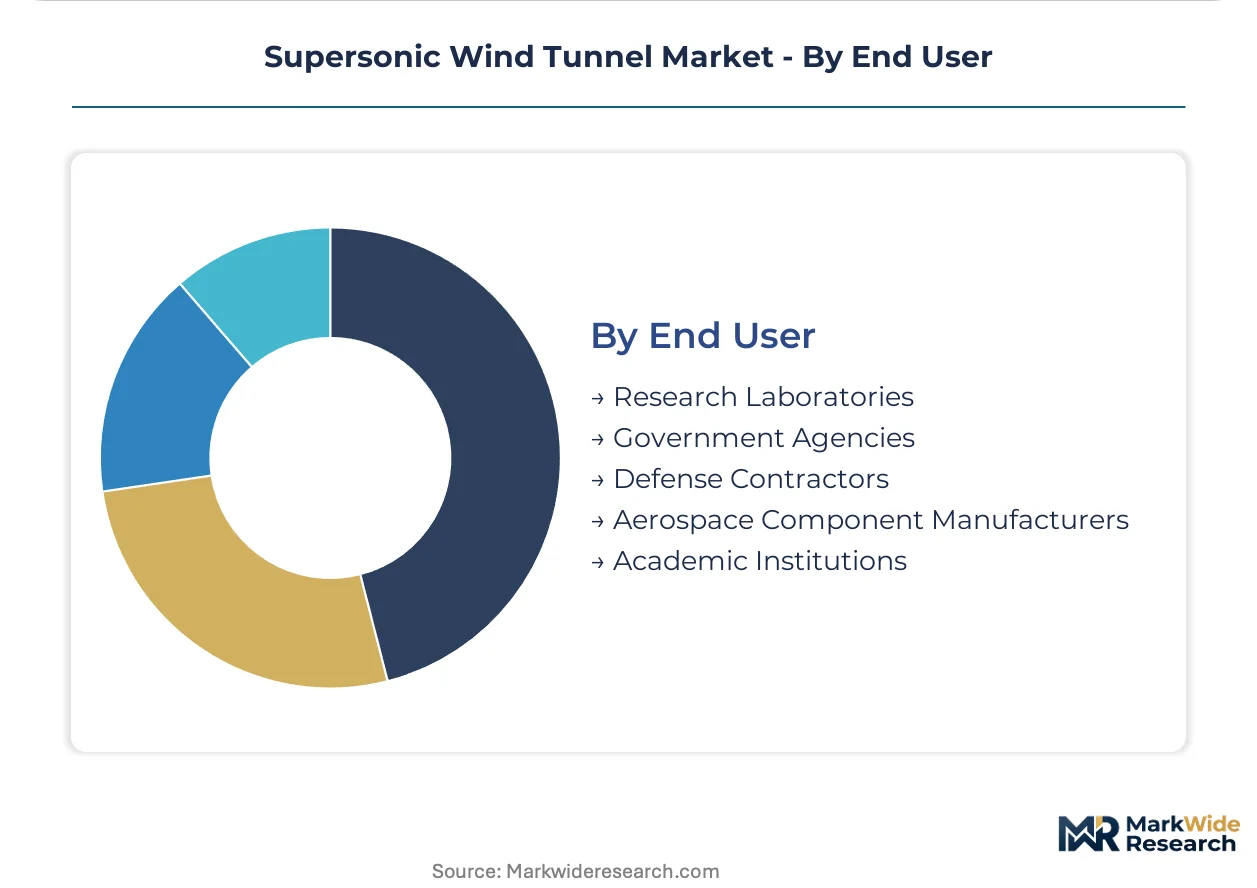
End user structure fragments across funding mechanisms, security clearance requirements, and test article ownership models that reshape procurement authority.
- Government Agencies:Owns and operates national facility infrastructure including AEDC, NASA Glenn, and ONERA Modane-Avrieux. Direct congressional and parliamentary appropriations fund capability expansion.
- Defense Contractors:Procures priority access contracts or constructs captive facilities for classified program protection. Lockheed Martin Skunk Works and Boeing Phantom Works sustain embedded tunnel operations.
- Research Laboratories:National laboratories and federally funded research centers execute multi-user test campaigns with peer-reviewed allocation processes.
- Aerospace Component Manufacturers:Tier-one suppliers validate subsystem aerodynamics through shared-access partnerships with prime contractors or commercial tunnel operators.
- Academic Institutions:University laboratories operate reduced-scale blowdown facilities for fundamental research and student training with limited test budgets.
Government Agencies retain infrastructure ownership concentration. Defense Contractors are where captive facility investment is accelerating.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized compressor fabrication and high-pressure vessel manufacturing concentrate in Germany and the United States, anchoring the supply base for Mach 2+ tunnel infrastructure. Facility ownership patterns diverge sharply between government-operated national laboratories and defense contractor captive installations.
United States
NASA's Artemis program and hypersonic weapons development at AEDC in Tennessee sustain institutional demand for continuous tunnel capacity. FAA Part 25 certification protocols for next-generation commercial transports require documented flutter and buffet validation campaigns at Calspan facilities in New York. Lockheed Martin Skunk Works and Boeing Phantom Works maintain embedded tunnel operations in California and Washington for classified program protection.
Germany
DNW and German Aerospace Center facilities anchor European high-speed aerodynamic research through coordinated national laboratory networks. EU F-Gas Regulation phase-down schedules are forcing qualification campaigns for hydrofluoroolefin test gas replacements at Cologne and Göttingen sites. Axial compressor system suppliers concentrated in Bavaria and Baden-Württemberg face extended order backlogs from global tunnel modernization programs.
France
ONERA's Modane-Avrieux facility dominates European pressurized tunnel capacity for full-scale Reynolds number simulation. ESA coordination with national facilities establishes funding frameworks for shared-access hypersonic test campaigns. The Provence-Alpes-Côte d'Azur cluster concentrates adaptive wall technology development and particle image velocimetry retrofit installations.
China
Government-funded aerodynamic research complexes in Sichuan and Hebei provinces are adding domestic test capacity for indigenous fighter and spaceplane programs. MIIT-directed aerospace technology roadmaps prioritize captive facility construction over foreign partnership access. State-owned defense conglomerates in Chengdu and Xi'an are commissioning blowdown and Ludwieg Tube configurations for hypersonic weapons validation.
Japan
METI grants for hypersonic transport research channel investment toward shared-access tunnel networks linking JAXA, Mitsubishi Heavy Industries, and university laboratories. Chubu/Nagoya aerospace clusters concentrate Ludwieg Tube expansion for reduced-energy test segments. JIS standards compliance requirements shape procurement specifications for domestic facility construction and foreign equipment import.
Supersonic Wind Tunnel Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying compressors, nozzles, and measurement instrumentation. The market structures around a concentrated core of government-owned national facilities and a fragmented periphery of university and mid-tier defense laboratories. Two dominant archetypes emerge: captive defense contractor installations protecting classified programs, and shared-access commercial operators selling priority queue positions. Competitive moves center on multi-year block purchase agreements for guaranteed access, and adaptive wall technology licensing to reduce uncertainty margins.
Among US-based defense primes, Boeing Company and Lockheed Martin Corporation exemplify the captive facility archetype through embedded tunnel operations and long-standing Calspan partnerships. ONERA represents the European shared-access model through its Modane-Avrieux facility and collaborative frameworks with DNW. These three anchors illustrate the divergence between classified program protection strategies and multi-user commercial operations.
| Leading Market Players |
|---|
| Boeing Company |
| Lockheed Martin Corporation |
| European Transonic Windtunnel |
| Calspan Corporation |
| RUAG Group |
| ONERA |
| DNW |
| Mitsubishi Heavy Industries |
| NASA |
| Others |
Pricing and Supply Chain Analysis
Overcapacity in Chinese government-funded aerodynamic research complexes is compressing queue premiums at legacy facilities while elevating price competition for shared-access contracts. Test queue scarcity at AEDC and ONERA Modane-Avrieux sustains pricing power for priority access agreements, even as energy cost volatility erodes margins for continuous tunnel operators.
Pricing Analysis
FAA Part 25 certification protocols dictate the pricing tier structure across supersonic wind tunnel services, separating continuous facility rates for extended flutter campaigns from blowdown pricing for shorter aerodynamic validation. Three-tier pricing structure across premium, standard, and economy levels tracks test duration, instrumentation density, and security classification clearance. Cost compression in continuous tunnel operations is intensifying because regional grid electricity pricing exceeds 50 MW sustained loads. Academic institutions exhibit highest price sensitivity, while defense contractors absorb premium rates for compartmentalized facility access.
Supply Chain Analysis
Tariff exposure between Germany and the United States dominates supply chain risk for axial compressor systems essential to Mach 2+ tunnel infrastructure. Specialized manufacturing concentrates in Bavaria and Baden-Württemberg for compressor fabrication, with high-pressure vessel forging anchored in Pittsburgh and Houston industrial clusters. Component sourcing draws from precision-machined nozzle contours, cryogenic heat exchangers, and optical measurement arrays. Single-source vulnerability persists for heated driver gas systems in Ludwieg Tube configurations. Distribution runs through national laboratory procurement channels and defense contractor captive facility construction programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Supersonic wind tunnel infrastructure sits in early-cycle expansion as hypersonic weapons programs and Artemis thermal protection validation create sustained demand tailwinds. Facility operators and equipment vendors face strategic choices between capacity addition and technology differentiation.
For Market Incumbents: Insulate queue positioning at priority facilities through multi-year block purchase agreements with Lockheed Martin and Boeing before Chinese domestic capacity erodes Western pricing power. Deepen backward integration into axial compressor manufacturing through partnerships with German suppliers in Bavaria to reduce lead time exposure. Adaptive wall technology licensing represents a defensible moat against low-cost blowdown alternatives. For New Entrants and Emerging Players: Ludwieg Tube retrofit opportunities at mid-tier university laboratories in India and Southeast Asia represent the most penetrable entry point for reduced-energy test segment capture. METI-funded hypersonic transport networks in Japan offer partnership pathways through shared-access commercialization models. Go-to-market positioning should emphasize energy efficiency credentials against legacy continuous tunnel incumbents. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among defense contractor captive facility operators with classified program backlogs. Long-term viability hinges on sustained hypersonic procurement cycles and lunar return mission cadence. Acquisition targets should display embedded tunnel operations with Skunk Works or Phantom Works integration. The signal to watch is queue booking compression at AEDC below six-month windows indicating demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Adaptive Wall Technology Licensing | NASA Glenn and ONERA deployments reduce uncertainty margins for classified defense configurations. |
| Ludwieg Tube Capacity Expansion | JAXA and DNW facilities capture hypersonic program demand with reduced energy consumption profiles. |
| Multi-Year Block Purchase Agreements | Boeing and Lockheed Martin secure guaranteed access as queue competition intensifies at priority facilities. |
| Hydrofluoroolefin Test Gas Qualification | German and French national laboratories lead EU F-Gas Regulation compliance campaigns. |
| Captive Facility Construction | State-owned defense conglomerates in Chengdu and Xi'an commission blowdown tunnels for indigenous programs. |
Research Methodology
A standing panel of facility operations directors, defense program test engineers, aerospace OEM certification managers, and national laboratory procurement officers provided ongoing calibration across the study. Primary interviews combined with secondary validation from FAA certification databases, NASA procurement records, ESA facility coordination agreements, and METI grant disclosure filings. Bottom-up segmentation modeling triangulated against top-down institutional budget appropriation analysis.
Scenario-bracketing framed demand projections across the analysis window, with segmentation dimensions spanning tunnel type, measurement technology, application category, and end-user funding mechanism. CAGRs derived from facility utilization rates, procurement cycle timing, and hypersonic program pipeline assessment. Forecast inputs incorporated Artemis mission cadence, FAA Part 25 certification queue depth, and EU F-Gas Regulation implementation timelines.
Practitioners should monitor hypersonic weapons procurement acceleration, Chinese domestic capacity utilization rates, and energy pricing volatility at major grid interconnections for early signals. Forecasts reflect assumptions regarding sustained defense spending trajectories and commercial aircraft certification timelines. Macroeconomic contraction, regulatory restriction on test gas chemistry, or breakthrough computational fluid dynamics validation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aerospace and Aircraft Materials
Ablative Coatings Market
Aerospace and Aircraft Materials
Global Military Aerospace Coatings Market
Aerospace and Aircraft Materials
3D Printing for Aerospace Market
Aerospace and Aircraft Materials
Aerospace Superalloys Market
Aerospace and Aircraft Materials
Global Flame Retardant for Aerospace Plastics Market
Aerospace and Aircraft Materials
Radiation Shielding Market
Aerospace and Aircraft Materials
Aerospace Fluoropolymers Market
Aerospace and Aircraft Materials
Aviation Coatings Market
Aerospace and Aircraft Materials
Aerospace Sealants Market
Aerospace and Aircraft Materials
Additive Manufactured Pressure Vessel Proof and Burst Test Rigs Market
Aerospace and Aircraft Materials
Global High Strength Aluminum Alloys Market
Aerospace and Aircraft Materials
Aircraft Insulation Materials Market
Aerospace and Aircraft Materials
Titanium Aerospace Forgings Market
Aerospace and Aircraft Materials
Asia-Pacific Aerospace Composites Market
Aerospace and Aircraft Materials
Aerospace Ceramic Matrix Composites Market
Aerospace and Aircraft Materials
Aircraft AFP and ATL Composites Market