
 Aerospace Lightweight Materials Market | 2026-2036
Aerospace Lightweight Materials Market Size, Share, and Industry Trends Forecast 2026-2036
Aerospace Lightweight Materials Market Analysis
AS9100 certification is bifurcating the supplier landscape into qualified aerospace tier providers and commodity material vendors. Toray Industries leverages its carbon fiber precursor technology to sustain leadership in primary structural prepreg supply. Solvay S.A. anchors its position through broad thermoplastic and thermoset chemistry portfolios serving multiple OEM qualification lists. Hexcel Corporation dominates North American narrowbody programs with qualified tape and fabric formats.
Aerospace lightweight materials are engineered substances, typically below five grams per cubic centimeter, that deliver specific strength ratios exceeding 150 MPa per g/cm³ through controlled microstructures and fiber architectures. Carbon fiber reinforced polymers achieve 30-40% weight reduction versus aluminum in wing box applications while maintaining fatigue resistance across pressurization cycles. Aluminum alloys remain the volume leader in fuselage skins and stringers due to established forming infrastructure and repair protocols. Titanium alloys command premium positioning in engine compressor sections where creep resistance at 540°C separates qualified suppliers from aspirants.
FAA airworthiness directives and EASA CS-25 certification standards govern material substitution protocols, creating multi-year qualification barriers that protect incumbent suppliers. EPA and REACH frameworks restrict hexavalent chromium surface treatments and certain epoxy hardeners, forcing reformulation investments across the supply chain. Stakeholders must monitor OEM platform ramp schedules and dual-source qualification timelines to align capacity commitments with actual production pull.
Market Dynamics
AS9100 qualification requirements are compressing the supplier base into a narrow tier of certified aerospace material providers, locking out commodity vendors from primary structural contracts and consolidating procurement power among Boeing, Airbus, and their qualified supply chains.
Growth Catalysts
- FAA and EASA emissions mandates:Tightening fuel efficiency standards force airframers to substitute aluminum with carbon fiber reinforced polymers in wing and fuselage structures.
- Commercial aviation fleet renewal:Narrowbody and widebody production ramps at Boeing and Airbus pull qualified prepreg and tape capacity into long-term supply agreements.
- Titanium alloy creep resistance:Engine OEMs specify Ti-6Al-4V and Ti-5Al-5V-5Mo-3Cr grades for compressor sections operating above 540°C, sustaining premium material demand.
Market Restraints
- Acrylonitrile and pitch precursor volatility:Carbon fiber production depends on petrochemical feedstocks exposed to energy price swings, compressing margin visibility for prepreg suppliers.
- Japanese and US carbon fiber concentration:Toray, Mitsubishi Chemical, and Hexcel control 70% of aerospace-grade precursor capacity, creating single-source vulnerability for tier-two laminators.
- REACH Annex XVII restrictions:ECHA classification of certain amine hardeners and hexavalent chromium surface treatments forces multi-year reformulation programs, delaying new material qualifications.
Strategic Opportunities
- Urban air mobility airframes:eVTOL manufacturers in the United States and Germany seek thermoplastic composites for rapid thermoforming of aerostructures, bypassing autoclave curing bottlenecks.
- India defense aerospace localization:Hindustan Aeronautics and DRDO procurement policies mandate domestic composite fabrication for fighter and UAV programs, opening qualification pathways for local prepreg converters.
- Recyclable thermoplastic resins:PEEK and PEKK matrices enable end-of-life fiber recovery, aligning with EU Green Deal circular economy targets for aerospace waste reduction.
Industry Challenges
- Autoclave operator and NDT technician scarcity:Aerospace composite manufacturing requires specialized curing and ultrasonic inspection skills that outpace vocational training pipeline output in the United States and Europe.
- Multi-year OEM qualification timelines:Boeing and Airbus material approval processes span 3-5 years from coupon testing to full-scale structural validation, freezing supplier switching costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aerospace Lightweight Materials Market |
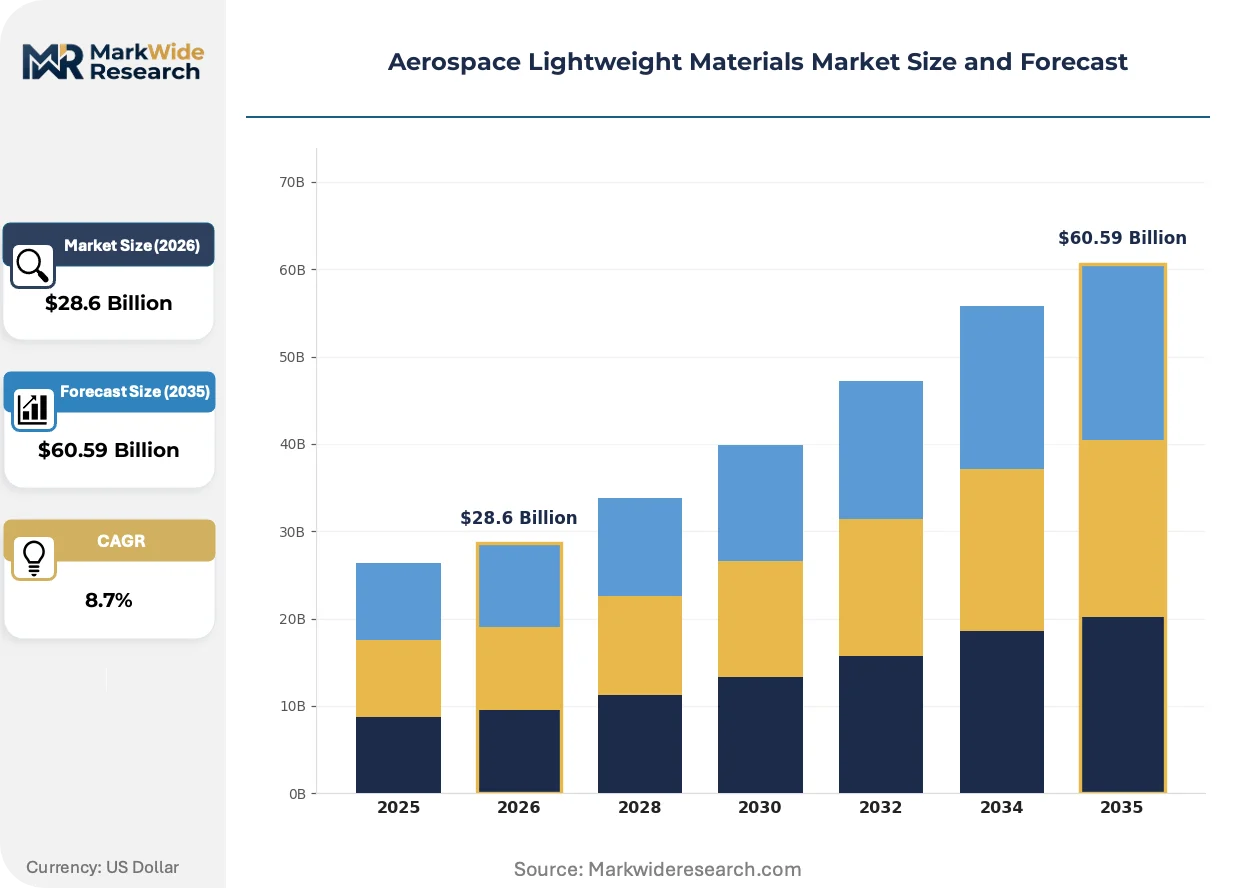
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $60.59 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Aluminum Alloys, Carbon Fiber Reinforced Polymers, Titanium Alloys, Composites Application: Airframe Structures, Interior Components, Engine Parts, Wing Components End User: Commercial Aviation, Military Aviation, Space Exploration, General Aviation Manufacturing Process: Stamping, Injection Molding, Layup, 3D Printing |
| Companies Covered | Toray Industries, Inc., Solvay S.A., Alcoa Corporation, Hexcel Corporation, Teijin Limited, DuPont de Nemours, Inc., Mitsubishi Chemical Group Corporation, SGL Carbon, Constellium SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aerospace Lightweight Materials Market Emerging Trajectories
Automated fiber placement and out-of-autoclave curing are compressing manufacturing cycle times while thermoplastic composites threaten to displace thermoset dominance in secondary structures. Material suppliers now compete on qualification speed and repair protocol compatibility.
Thermoplastic composite tapes using PEEK and PEKK matrices are displacing epoxy-based thermosets in aircraft interior brackets and cargo floor beams. Tier-one suppliers in Germany and France are qualifying these materials for 20-minute press-forming cycles versus 8-hour autoclave cures. This shift is displacing capital-intensive autoclave infrastructure from new facility designs.
EPA restrictions on hexavalent chromium surface treatments and EASA adoption of REACH-aligned substance restrictions are forcing aluminum and titanium suppliers to convert to trivalent chrome and sol-gel pretreatments. Surface treatment houses in the United States and Europe are investing $15-50 million per conversion line. Military and commercial fixed-wing programs face concurrent qualification delays as OEMs validate alternative corrosion protection.
Airframers are consolidating qualified supplier lists from 12-15 composite vendors to 4-6 strategic partners per platform, compressing procurement negotiation cycles and demanding volume commitments. Boeing's 787 and 777X programs exemplify this concentration in the United States, while Airbus enforces similar consolidation for A350 and A320neo families in Europe. Long-term agreements now span 10-15 years with price-down trajectories tied to learning curve assumptions.
Aerospace Lightweight Materials Market Segmentation
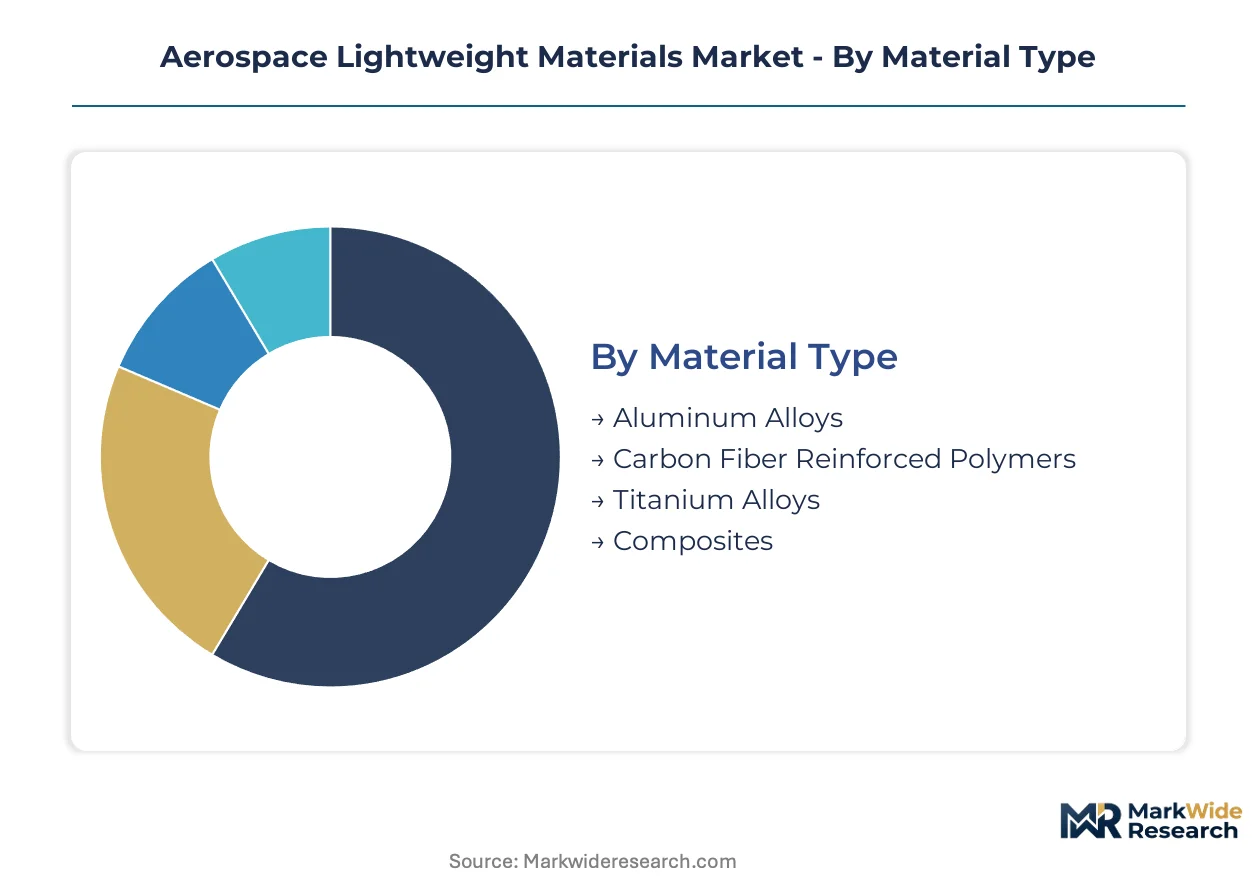
Aerospace lightweight materials segment along four critical dimensions that determine qualification pathways, pricing power, and supplier switching costs. Material chemistry governs OEM approval timelines. Application specificity dictates performance thresholds. End-user category shapes volume scale and contract duration.
Material Type:
Carbon fiber reinforced polymers command the widest margin spreads due to autoclave curing bottlenecks and Japanese precursor concentration.
- Aluminum Alloys:2xxx and 7xxx series dominate fuselage skins and stringer applications through established stretch-forming infrastructure. Boeing 737 MAX and Airbus A320neo programs in the United States and France pull 80% of aerospace-grade plate and extrusion volume, though REACH Annex XVII hexavalent chromium restrictions are forcing trivalent chrome conversion investments at surface treatment houses.
- Carbon Fiber Reinforced Polymers:Epoxy-based prepregs and thermoplastic tapes achieve 30-40% weight reduction in wing boxes versus aluminum. Toray T800H and IM7 fiber specifications anchor Boeing 787 and Airbus A350 qualification lists, with out-of-autoclave cyanate ester formulations gaining traction for rate-sensitive narrowbody programs.
- Titanium Alloys:Ti-6Al-4V and Ti-5Al-5V-5Mo-3Cr grades serve compressor sections where creep resistance at 540°C separates qualified suppliers. Premium positioning reflects vacuum arc remelting capacity scarcity and Russian VSMPO-AVISMA supply uncertainty.
- Composites:Glass fiber and aramid hybrid laminates fill interior panels and cargo liners where smoke-toxicity FAR 25.853 compliance outweighs structural efficiency. Lower qualification barriers attract secondary-structure specialists.
The dominant share belongs to aluminum alloys, while carbon fiber reinforced polymers are closing the gap fastest.
Application:
Airframe structures concentrate procurement power through Boeing and Airbus consolidated supplier lists, compressing margin for tier-two laminators.
- Airframe Structures:Fuselage barrels, floor beams, and pressure bulkheads demand AS9100-certified fabrication with full traceability. Automated fiber placement and filament winding are displacing hand layup at Spirit AeroSystems and GKN Aerospace facilities.
- Wing Components:Spar caps, ribs, and skin panels drive 60% of aerospace carbon fiber consumption. Wing box applications require damage tolerance validation across 100,000+ pressurization cycles.
- Engine Parts:Fan blades, containment cases, and compressor disks specify titanium aluminide intermetallics and ceramic matrix composites. GE Aviation and Pratt & Whitney qualification protocols span 5-7 years.
- Interior Components:Overhead bins, galleys, and seating structures prioritize thermoplastic processability for 20-minute press-forming cycles. PEEK and PEKK matrices enable end-of-life fiber recovery aligned with EU Green Deal targets.
Airframe structures absorb the majority of qualified prepreg capacity, though wing components are expanding most quickly as next-generation narrowbodies increase composite wing area.
End User:
Commercial aviation locks suppliers into 10-15 year agreements with price-down trajectories, while military programs tolerate higher unit costs for domestic sourcing mandates.
- Commercial Aviation:Boeing and Airbus production ramps pull 75% of qualified material capacity. Fleet renewal mandates from FAA and EASA emissions standards force aluminum substitution in wing and fuselage structures.
- Military Aviation:F-35, Eurofighter, and Rafale programs specify US and European qualified suppliers exclusively. ITAR and EU defense procurement directives block non-allied material sources.
- Space Exploration:Reusable launch vehicle demand from SpaceX and Blue Origin is accelerating cryogenic-compatible composite development for propellant tanks.
- General Aviation:Cirrus, Textron Aviation, and Diamond Aircraft orders represent smaller batch sizes with less stringent OEM qualification requirements.
Commercial aviation commands the volume base, while space exploration is climbing the fastest on reusable launch vehicle demand.
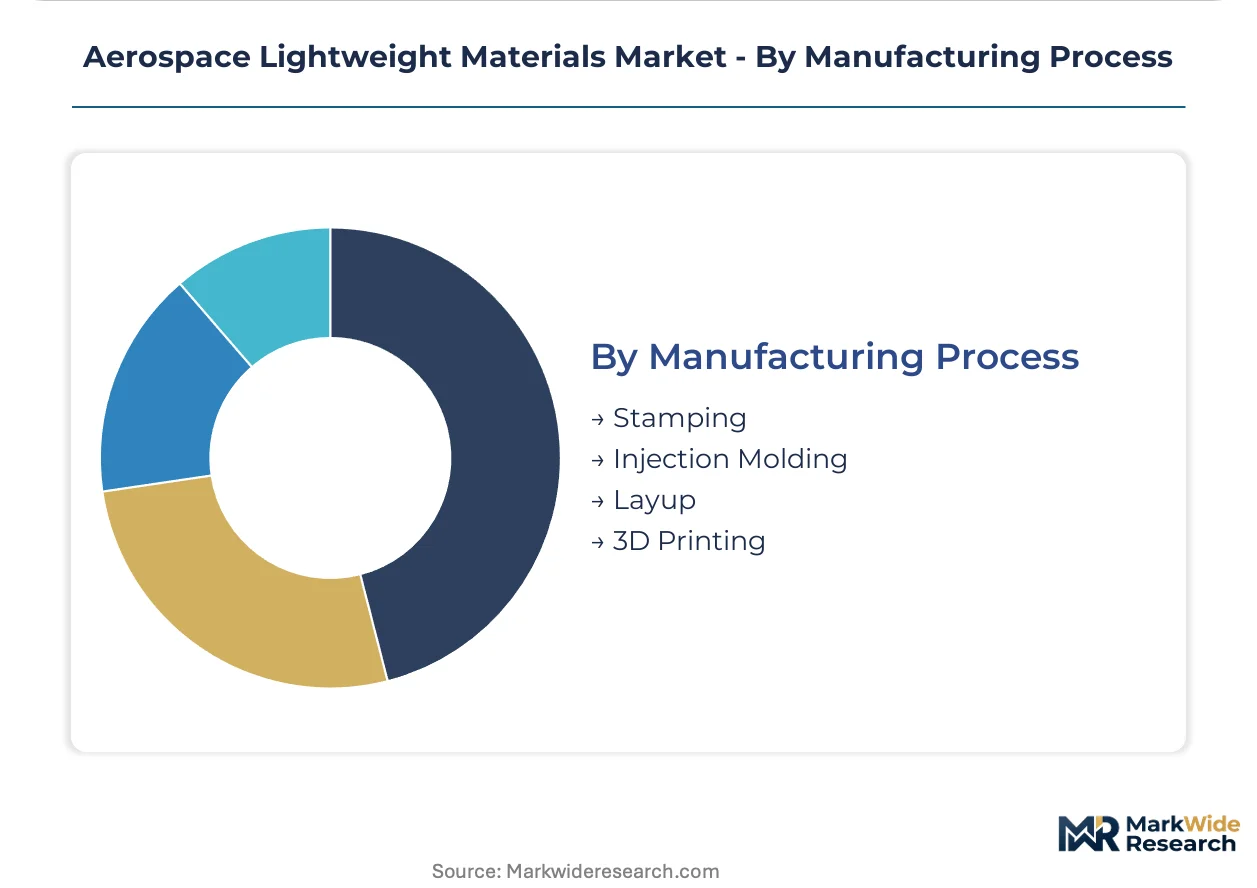
Manufacturing Process:
Layup and autoclave curing anchor capital investment profiles, though out-of-autoclave alternatives are compressing facility costs for new entrants.
- Layup:Automated fiber placement and tape laying dominate wing and fuselage production at Boeing Charleston and Airbus Hamburg. Capital intensity exceeds $50 million per production line.
- Stamping:Aluminum and titanium sheet forming serves stringers, clips, and brackets with established brake press and hydroforming infrastructure.
- Injection Molding:Thermoplastic composite pellets enable rapid cycling of interior brackets and cable management components at tier-three suppliers.
- 3D Printing:Electron beam melting and laser powder bed fusion qualify titanium and aluminum lattice structures for non-critical brackets. FAA certification of printed flight hardware remains case-by-case.
Layup retains the dominant process share, while 3D printing is gaining share fastest on qualification momentum for non-structural applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Airframers and engine OEMs concentrate procurement authority in the United States, France, and Japan, where qualified supplier networks lock in multi-year material commitments. FAA and EASA certification protocols create geographic moats around Boeing, Airbus, and their tier-one fabricators.
United States
Boeing 737 MAX and 777X production ramps pull qualified prepreg capacity into long-term agreements at Charleston and Everett facilities. FAA airworthiness directives govern material substitution protocols for wing box applications. Wichita, Kansas hosts Spirit AeroSystems and tier-two laminators automating fiber placement for narrowbody fuselages.
France
Airbus A350 and A320neo families consolidate supplier lists at Toulouse and Hamburg-adjacent facilities. EASA CS-25 certification standards enforce REACH-aligned substance restrictions on hardeners and surface treatments. Auvergne-Rhône-Alpes clusters specialty chemical houses supplying thermoplastic matrices for interior brackets.
Japan
Toray Industries and Mitsubishi Chemical Group control aerospace-grade carbon fiber precursor capacity serving Boeing and Airbus qualification lists. METI industrial policy supports domestic composite R&D for next-generation narrowbody programs. Nagoya aerospace corridor integrates material suppliers with Mitsubishi Heavy Industries airframe assembly.
Germany
Premium Aerotec and Premium AEROTEC suppliers qualify thermoplastic tapes for 20-minute press-forming cycles at Augsburg and Nordenham. ECHA Annex XVII restrictions force trivalent chrome conversion at aluminum surface treatment houses. Bavaria hosts SGL Carbon operations serving engine containment case programs.
United Kingdom
GKN Aerospace and BAE Systems platforms specify UK-qualified suppliers for F-35 and Eurofighter structural components. UK defense procurement directives block non-allied material sources for military programs. Bristol and Portsmouth clusters concentrate automated fiber placement capacity for wing spar production.
Aerospace Lightweight Materials Market Vendor Landscape
Player mix skews toward integrated chemical conglomerates with captive precursor supply and specialized aerospace composites fabricators. The supplier base compresses into two tiers: AS9100-certified primary structural providers serving Boeing and Airbus direct, and secondary-structure specialists qualifying for interior and non-critical applications. Dominant competitive moves include backward integration into carbon fiber precursor production and strategic partnerships with OEMs for co-developed qualification protocols.
Among Japanese and US-based material suppliers, Toray Industries, Hexcel Corporation, and Solvay S.A. occupy positions exemplifying the integrated precursor-to-prepreg archetype. Toray represents vertical control over PAN-based fiber production. Hexcel anchors North American narrowbody program supply. Solvay exemplifies broad chemistry portfolio diversification across thermoset and thermoplastic matrices.
| Leading Market Players |
|---|
| Toray Industries, Inc. |
| Solvay S.A. |
| Alcoa Corporation |
| Hexcel Corporation |
| Teijin Limited |
| DuPont de Nemours, Inc. |
| Mitsubishi Chemical Group Corporation |
| SGL Carbon |
| Constellium SE |
| Others |
Supply Flow & Price Mechanics
Carbon fiber substitution for aluminum wing structures simultaneously redraws supply geography toward Japanese precursor producers and compresses margin visibility for European laminators facing acrylonitrile indexation. Boeing and Airbus long-term agreements now embed raw material pass-through clauses that tether prepreg pricing to petrochemical feedstock volatility.
Pricing Analysis
Cost-plus contracts with acrylonitrile indexation dominate Boeing and Airbus procurement, transferring feedstock risk to tier-one suppliers while locking in volume commitments. Price differentiation rests on AS9100 certification tier and autoclave curing capacity access, with qualified primary structural providers commanding premiums over secondary-structure specialists. Cost compression in thermoset prepregs is intensifying because out-of-autoclave formulations bypass capital-intensive curing infrastructure. Tier-two laminators exhibit highest price sensitivity, while Toray and Hexcel leverage qualification scarcity to resist discounting.
Supply Chain Analysis
Japanese carbon fiber precursor capacity concentrated in Toray and Mitsubishi Chemical facilities anchors aerospace-grade supply, creating single-source vulnerability for European and North American tier-two converters. The supply chain draws from acrylonitrile and pitch feedstocks, aerospace-qualified epoxy resins, and titanium sponge. Tariff exposure on Russian VSMPO-AVISMA titanium sponge imports threatens compressor section material availability. Distribution runs through AS9100-certified tier-one fabricators at Boeing Charleston, Airbus Hamburg, and Spirit AeroSystems Wichita before OEM assembly pull.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The aerospace lightweight materials market sits at a cyclical recovery phase driven by narrowbody production ramps at Boeing and Airbus, with fleet renewal mandates sustaining qualified capacity absorption through the decade.
For Market Incumbents: Shield qualification moats by accelerating backward integration into carbon fiber precursor production, capturing margin currently lost to Japanese suppliers. Invest in out-of-autoclave curing capacity to defend against thermoplastic entrants threatening autoclave-heavy cost structures. Prioritize AS9100 certification maintenance as REACH Annex XVII reformulation deadlines approach. For New Entrants and Emerging Players: Differentiate on thermoplastic composite process speed for urban air mobility airframes, where eVTOL manufacturers seek 20-minute press-forming cycles absent autoclave bottlenecks. Target India defense aerospace localization mandates as Hindustan Aeronautics and DRDO procurement policies open qualification pathways for domestic prepreg converters. Pursue joint development agreements with eVTOL original equipment manufacturers to bypass traditional Boeing and Airbus qualification timelines. For Investors and Strategic Acquirers: The market sits at an early-cycle expansion phase that favors captive precursor-to-prepreg integrators with established OEM qualification lists. Long-term viability centers on suppliers with demonstrated multi-platform approval spanning Boeing 787, 777X, Airbus A350, and A320neo families. Watch eVTOL platform certification milestones as inflection indicators for thermoplastic composite demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precursor Production | Toray's PAN-based fiber captive supply locks margin and reduces acrylonitrile price exposure for Boeing and Airbus contracts. |
| Out-of-Autoclave Curing Capacity Expansion | Cyanate ester formulation investments at Hexcel compress cycle times for rate-sensitive narrowbody programs. |
| Thermoplastic Composite Qualification | PEEK and PEKK matrix approvals at Premium Aerotec enable 20-minute press-forming for A350 interior brackets. |
| REACH-Aligned Reformulation Program | Trivalent chrome conversion investments at Constellium surface treatment houses preserve EASA CS-25 certification eligibility. |
| Urban Air Mobility Partnership | Joby Aviation and Lilium supplier qualifications open alternative revenue streams outside Boeing and Airbus procurement. |
Methodological Framework
A spread of perspectives from Boeing and Airbus procurement executives, Spirit AeroSystems plant managers, Toray carbon fiber technical directors, and FAA certification engineers converged on the working assumptions. Primary fieldwork combined structured interviews with tier-one and tier-two supplier leadership alongside secondary validation through FAA airworthiness directives, EASA CS-25 certification databases, EPA surface treatment regulations, and SEC filings from publicly traded material suppliers. Bottom-up capacity assessments at Charleston, Hamburg, and Nagoya facilities triangulated against top-down OEM production schedule analysis.
Segmentation dimensions modeled span material chemistry, application specificity, end-user category, and manufacturing process across the projection horizon. Carbon fiber reinforced polymer, aluminum alloy, titanium alloy, and glass fiber composite volumes were cross-referenced against Boeing 737 MAX, 777X, Airbus A320neo, and A350 ramp schedules. CAGRs were derived from production pull assumptions tied to fleet renewal mandates and emissions compliance deadlines. Forecast inputs incorporated acrylonitrile price index trajectories and REACH Annex XVII substance restriction implementation timelines.
The analysis sits within stated boundaries; outcomes outside sustained narrowbody production rates and stable Japanese precursor supply would require recalibration. Forecasts reflect assumptions on OEM dual-source qualification timelines and eVTOL platform certification progress. Practitioners should keep alternative scenarios live as FAA and EASA emissions standard stringency and titanium sponge trade flows evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aerospace and Aircraft Materials
Aerographite Market
Aerospace and Aircraft Materials
Commercial Aircraft Honeycomb Core Market
Aerospace and Aircraft Materials
Global Aerospace Metal Closed-Die Forging Market
Aerospace and Aircraft Materials
Aerospace Coatings Market
Aerospace and Aircraft Materials
Commercial Aerospace 3D Printing Market
Aerospace and Aircraft Materials
Supersonic Wind Tunnel Market
Aerospace and Aircraft Materials
Aircraft Soft Goods Market
Aerospace and Aircraft Materials
Coated Fabrics for Defense Market
Aerospace and Aircraft Materials
Aerospace Forging Market
Aerospace and Aircraft Materials
Global Military Aerospace Coatings Market
Aerospace and Aircraft Materials
Advanced Materials for Flying Cars Market
Aerospace and Aircraft Materials
Aerospace Additive Manufacturing Market
Aerospace and Aircraft Materials
Global Aerospace Adhesives and Sealants Market
Aerospace and Aircraft Materials
Commercial Aircraft Materials Market
Aerospace and Aircraft Materials
Aerospace 3D Printing Consumables Market
Aerospace and Aircraft Materials
Thermal Spray Coating Market