
 Global Composite Materials Aluminum Alloys Aerospace Market | 2026-2036
Global Composite Materials Aluminum Alloys Aerospace Market Size, Share, and Industry Trends Forecast 2026-2036
Global Composite Materials Aluminum Alloys Aerospace Market Foresight
Defense contractors is reorganizing procurement priorities toward lightweight aluminum matrix composites for next-generation military airframes. Toray Industries anchors Japanese supply chains through fiber-reinforced prepreg dominance. Alcoa Corporation controls North American primary aluminum-lithium output with captive smelting and rolling assets. Constellium SE differentiates European positioning through AS9100-certified extrusion capabilities serving Airbus Tier-1 suppliers.
Composite materials aluminum alloys aerospace encompasses engineered material systems combining aluminum matrices with ceramic or metallic reinforcements, typically achieving specific strength ratios exceeding 200 MPa per g/cm³ through powder metallurgy or casting routes. These systems serve primarily to reduce structural mass in flight-critical components while maintaining fatigue resistance under cyclic loading. Aluminum lithium alloys lead product type demand due to density reductions of 8-10% versus conventional 2xxx series, though additive manufacturing represents the fastest-expanding technology segment as Boeing and Lockheed Martin qualify laser powder bed fusion for non-structural brackets. Airframe structures capture the dominant application share, while UAV frames concentrate margin pools through low-volume, high-mix production economics.
FAA Part 25 airworthiness standards, EASA CS-25 certification requirements, and China's GB/T standards collectively dictate material qualification timelines and testing protocols for commercial aerospace adoption. REACH restrictions on hexavalent chromium surface treatments are forcing conversion to sealed anodizing and sol-gel coating systems across European supply chains. Stakeholders must monitor evolving MEE enforcement of dual carbon goals in Chinese primary aluminum smelting, as Scope 3 emissions thresholds threaten to bifurcate supplier eligibility for Western OEM contracts.
Market Dynamics
Defense procurement is reorganizing around aluminum matrix composites for next-generation fighter airframes, while FAA and EASA certification timelines compress supplier qualification windows and concentrate procurement among pre-qualified Tier-1 integrators.
Growth Catalysts
- Aluminum-lithium density reductions:8-10% mass savings versus conventional 2xxx series alloys are pulling demand from Boeing and Airbus narrowbody programs.
- FAA Part 25 airworthiness standards:Tightened material traceability requirements are locking in incumbent suppliers with established qualification dossiers.
- Additive manufacturing qualification:Laser powder bed fusion for non-structural brackets is opening new design freedom in UAV frame production.
Market Restraints
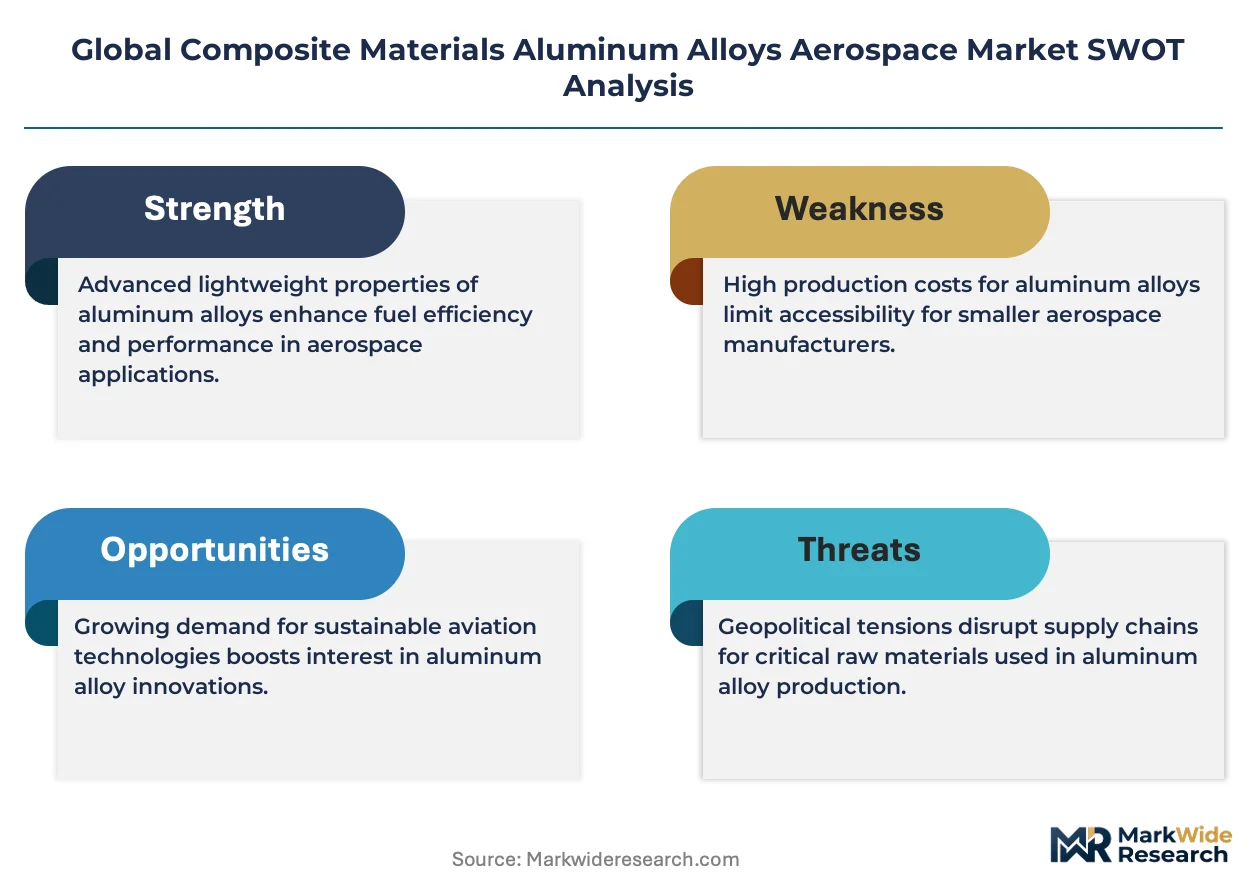
- Primary aluminum-lithium supply concentration:Captive smelting and rolling assets in North America create single-source vulnerability for European airframers.
- REACH hexavalent chromium restrictions:Mandatory conversion to sealed anodizing and sol-gel coatings is extending surface treatment lead times across European supply chains.
- Carbon fiber reinforced polymer substitution:Boeing 787 and Airbus A350 primary structures demonstrate competitive specific strength ratios above 250 MPa per g/cm³.
Strategic Opportunities
- Chinese MEE dual carbon enforcement:Scope 3 emissions thresholds threaten to bifurcate supplier eligibility, creating first-mover advantage for Western OEMs with verified low-carbon primary aluminum sourcing.
- SpaceX Texas operations:Reusable launch vehicle airframe demand is generating high-mix, low-volume production economics for aluminum matrix composite suppliers.
- AS9100-certified extrusion capability gaps:Airbus Tier-1 supplier consolidation in Europe is opening qualification slots for new entrants with certified thermal management extrusions.
Industry Challenges
- Powder metallurgy technician scarcity:Qualified operators for aluminum matrix composite casting and infiltration processes are concentrated at legacy defense contractors.
- FAA-EASA concurrent certification:Divergent testing protocols for fatigue resistance under cyclic loading are duplicating qualification costs for dual-certified suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Composite Materials Aluminum Alloys Aerospace Market |
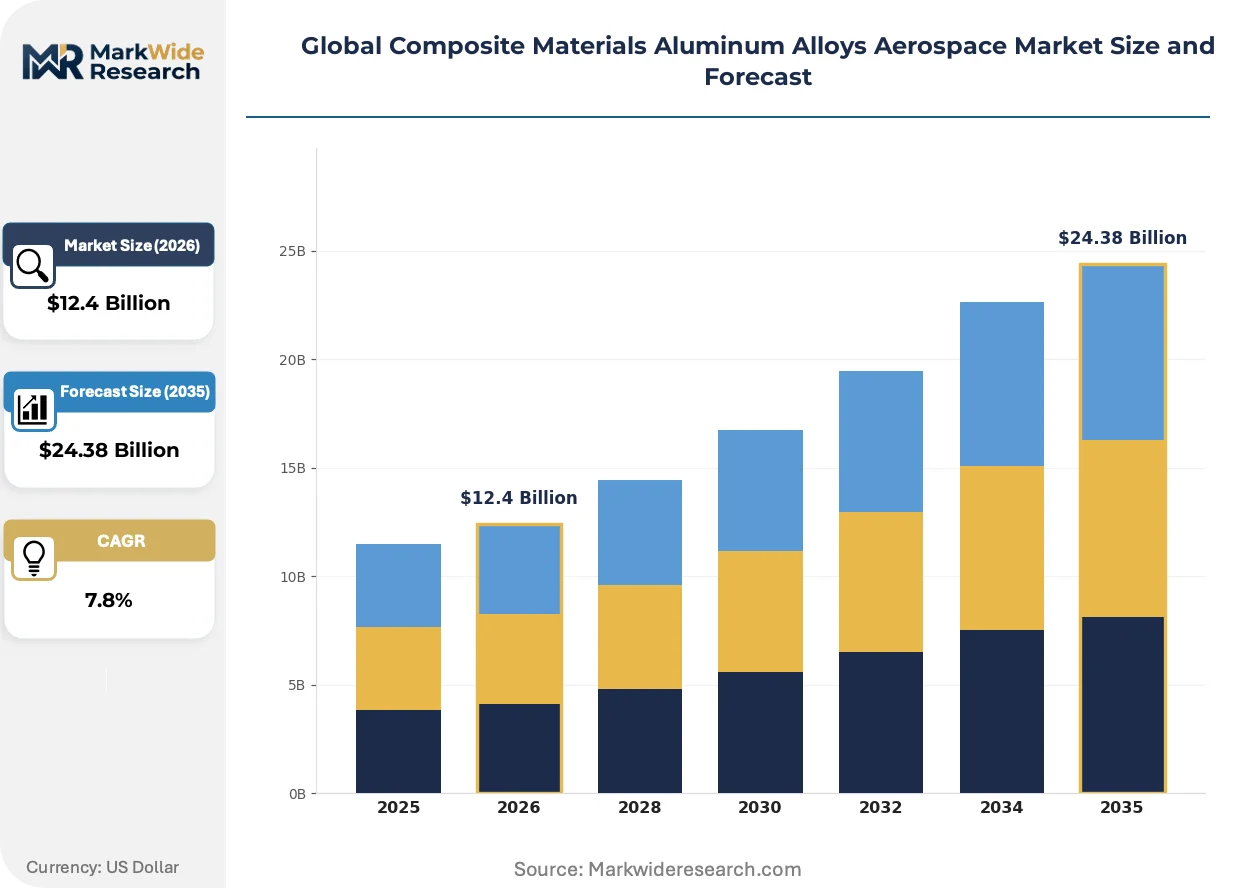
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $24.38 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aluminum Lithium, 7xxx Series, 6xxx Series, Aluminum Matrix Composites, Metal Matrix Composites Technology: Fiber Reinforced, Powder Metallurgy, Casting, Extrusion, Additive Manufacturing Application: Airframe Structures, Engine Components, Landing Gear, Interior Components, UAV Frames End User: Commercial Aircraft Manufacturers, Defense Contractors, Spacecraft Builders, Maintenance Repair Operations, Research Laboratories |
| Companies Covered | Renegade Materials Corp., HEXEL Works Inc., Toray Industries Inc., Alcoa Corporation, Solvay S.A., Koninklijke Ten Cate B.V., Materion Corp., Constellium SE, Teijin Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Composite Materials Aluminum Alloys Aerospace Market Shifts & Advancements
Material qualification timelines and manufacturing process innovation are compressing development cycles while regulatory fragmentation across FAA, EASA, and China's GB/T standards is forcing parallel certification strategies.
Laser powder bed fusion for aluminum-lithium alloys is decomposing traditional subtractive machining workflows for non-structural aerospace brackets. Lockheed Martin and Boeing are qualifying these processes for production volumes below five hundred units annually. This technology is decomposing the economics of conventional five-axis machining centers in low-volume defense applications.
REACH restrictions on hexavalent chromium surface treatments are mandating sealed anodizing and sol-gel coating conversions across European aerospace supply chains. EASA CS-25 amendments are incorporating these environmental compliance timelines into airworthiness certification requirements. Airbus Tier-1 suppliers in Germany and France are absorbing eighteen-month qualification delays for alternative surface treatment approvals.
Defense procurement consolidation around next-generation fighter programs is compressing supplier qualification cycles from sixty months to thirty-six months. Boeing's Washington State manufacturing cluster and SpaceX's Texas operations are concentrating demand for aluminum matrix composites with established fatigue resistance dossiers. Japan's METI is accelerating domestic fiber-reinforced prepreg development to reduce import dependency for military airframe applications.
Global Composite Materials Aluminum Alloys Aerospace Market Segmentation
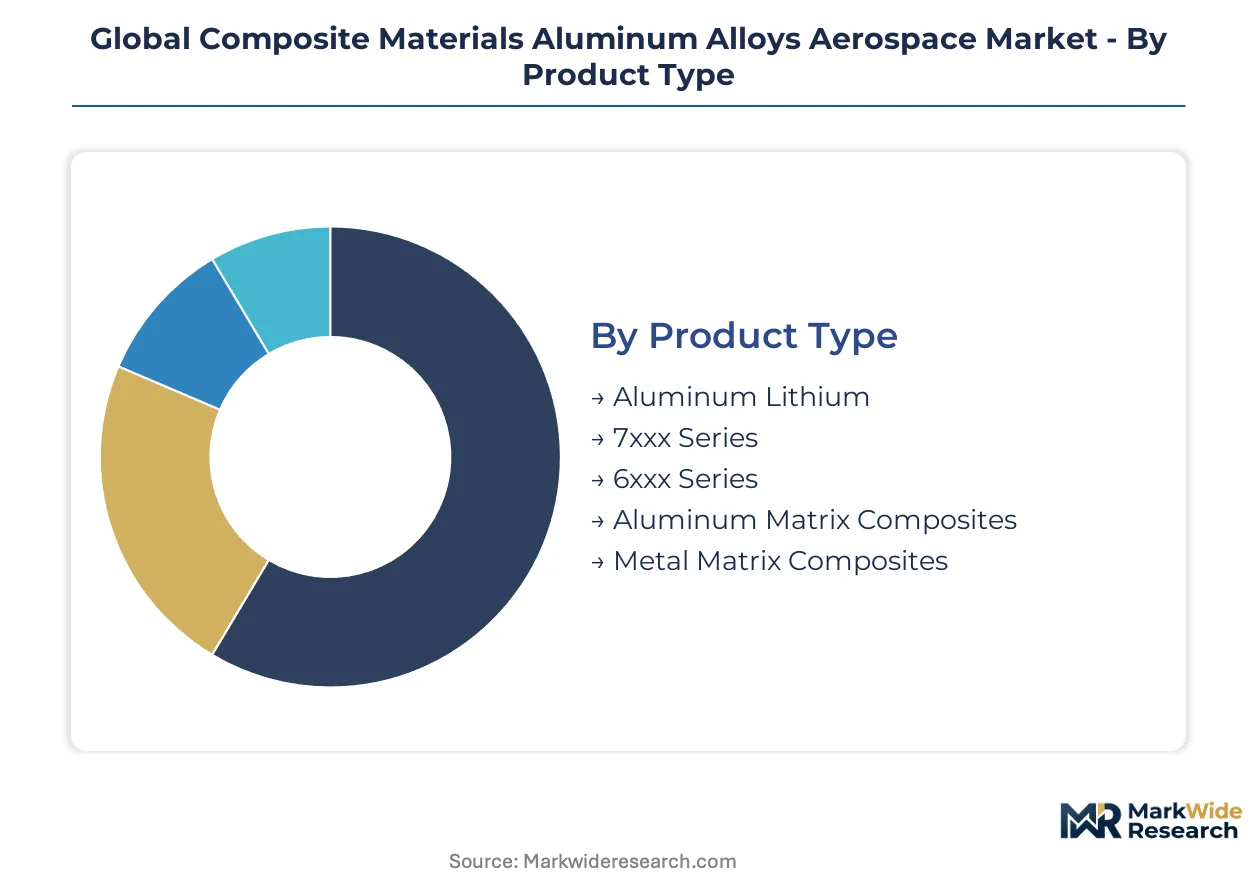
Segmentation in composite materials aluminum alloys aerospace reveals how material specifications, manufacturing processes, and end-use requirements channel demand through distinct procurement pathways. Each dimension carries implications for qualification timelines, supplier certification, and margin structures across the value chain.
Product Type:
Channel flow splits between qualified legacy alloys for high-volume commercial programs and emerging matrix composites for defense and space applications with accelerated procurement cycles.
- Aluminum Lithium:Density reductions of 8-10% versus conventional 2xxx series alloys position this material for Boeing and Airbus narrowbody fuselage skins and lower wing structures. FAA Part 25 qualification dossiers for 2195 and 2050 variants lock in incumbent suppliers with established rolling mill certifications.
- Aluminum Matrix Composites:Silicon carbide or boron fiber reinforcements in aluminum matrices achieve specific stiffness ratios exceeding conventional alloys by 30-40%. Demand concentrates at SpaceX Texas operations and next-generation fighter programs where mass reduction justifies powder metallurgy processing costs.
- 7xxx Series:High-strength zinc-magnesium-copper alloys dominate commercial aircraft upper wing structures and bulkheads requiring 500 MPa yield strength.
- 6xxx Series:Extrudable magnesium-silicon alloys serve lower-stress airframe brackets and interior structural elements with moderate corrosion resistance requirements.
- Metal Matrix Composites:Broader category encompassing titanium and magnesium matrices; niche applications in satellite thermal management structures.
Aluminum Lithium dominates installed base across commercial fleets. Aluminum Matrix Composites are where expansion concentrates for reusable launch vehicles and unmanned combat airframes.
Technology:
Cost tier stratification separates capital-intensive powder routes for defense premiums from high-throughput extrusion serving commercial volume programs.
- Powder Metallurgy:Gas atomization and mechanical alloying produce fine-grain aluminum matrix composites with isotropic properties. Technician scarcity constrains capacity expansion beyond legacy defense contractor facilities in the United States and United Kingdom.
- Additive Manufacturing:Laser powder bed fusion of AlSi10Mg and Scalmalloy alloys decomposes traditional five-axis machining economics for UAV brackets and satellite structural nodes. Lockheed Martin qualifies these processes for production volumes below five hundred units annually.
- Fiber Reinforced:Continuous boron or SiC fiber preforms infiltrated with molten aluminum serve selectively reinforced landing gear trunnions.
- Casting:Squeeze casting and investment casting routes for complex engine housing geometries with internal cooling passages.
- Extrusion:AS9100-certified thermal management profiles for Airbus Tier-1 suppliers in Germany and France.
Extrusion commands highest volume throughput. Additive Manufacturing represents the steepest expansion trajectory as design freedom unlocks topology-optimized brackets previously machined from solid billet.
Application:
Customer type determines margin structure: commercial airframers squeeze material costs while defense and space buyers absorb premiums for performance-optimized specifications.
- Airframe Structures:Fuselage skins, wing boxes, and empennage components absorb 60-70% of aluminum-lithium demand by mass. Boeing 787 and Airbus A350 primary structures demonstrate carbon fiber substitution pressure above 250 MPa per g/cm³ specific strength thresholds.
- UAV Frames:Low-volume, high-mix production economics concentrate margin pools for aluminum matrix composite suppliers serving military drone programs. Turkish Aerospace Industries and General Atomics procurement specifications prioritize rapid design iteration over unit cost minimization.
- Engine Components:Compressor cases and fan blades requiring elevated temperature resistance to 150°C.
- Landing Gear:High-strength 7xxx series forgings for main and nose gear struts with 200,000-cycle fatigue requirements.
- Interior Components:Seating tracks, overhead bin supports, and galley structures with flammability certification to FAR 25.853.
Airframe Structures dominate installed base. UAV Frames concentrate expansion as autonomous system procurement accelerates across NATO and Indo-Pacific defense budgets.
End User:
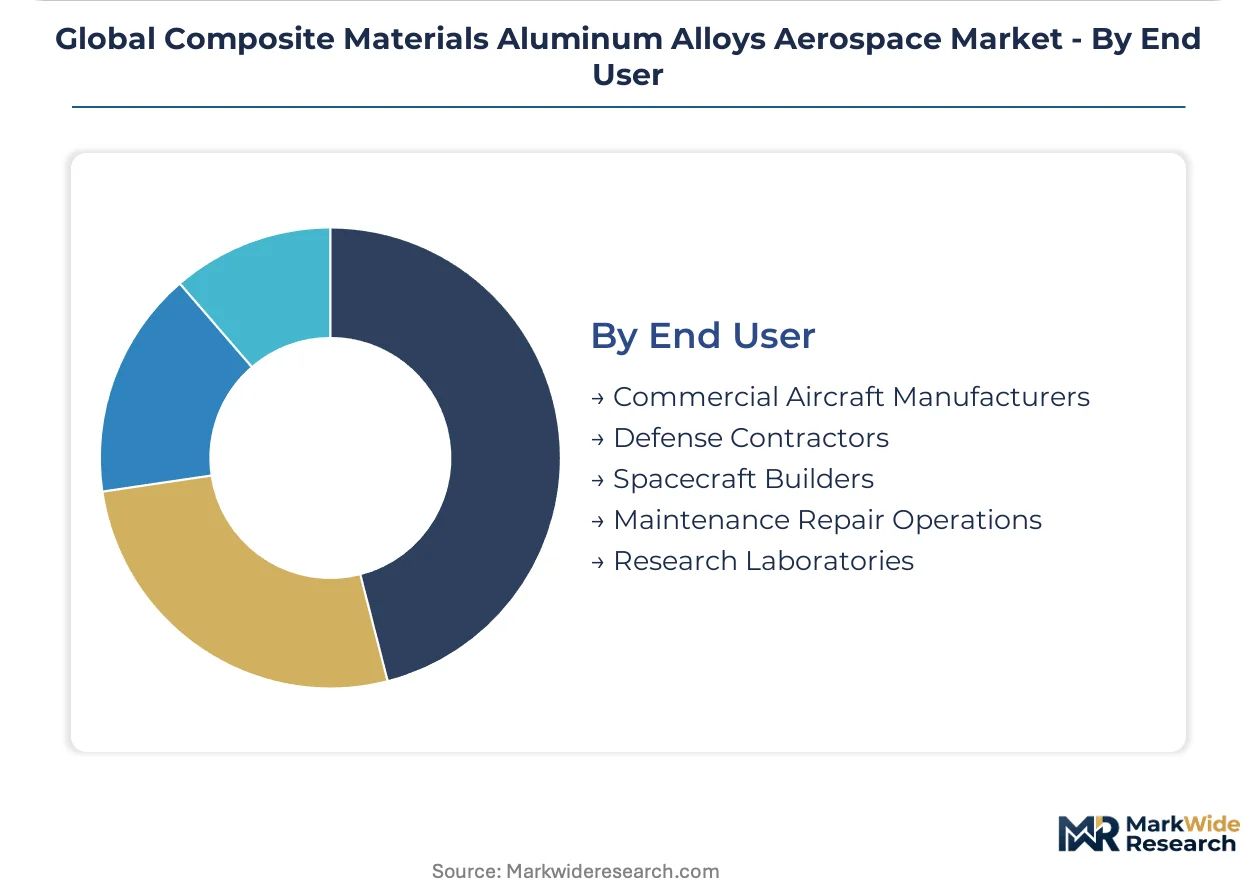
Geography shapes procurement patterns: United States concentrates defense and space demand while Europe fragments across Airbus supply chains and national fighter programs.
- Defense Contractors:Lockheed Martin F-35 and B-21 programs, together with next-generation fighter initiatives, are reorganizing procurement priorities toward aluminum matrix composites. Thirty-six-month qualification cycles compress supplier onboarding versus sixty-month commercial timelines.
- Commercial Aircraft Manufacturers:Boeing Washington State manufacturing cluster and Airbus Hamburg and Toulouse facilities concentrate aluminum-lithium demand for narrowbody and widebody programs. REACH hexavalent chromium restrictions extend surface treatment lead times across European supply chains.
- Spacecraft Builders:SpaceX Texas operations and Blue Origin Kent, Washington facilities generate reusable launch vehicle airframe demand.
- Maintenance Repair Operations:Spare parts sourcing for aging 737NG and A320ceo fleets drives 2xxx and 7xxx series alloy demand.
- Research Laboratories:NASA Glenn and DARPA materials programs fund additive manufacturing process development for non-structural bracket qualification.
Commercial Aircraft Manufacturers dominate installed base. Defense Contractors concentrate expansion as sixth-generation fighter and hypersonic vehicle programs advance to engineering manufacturing development phases.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States aluminum-lithium exports flow predominantly to Airbus facilities in Germany and France, while Japanese fiber-reinforced prepreg shipments supply Boeing's Washington State manufacturing cluster.
United States
Boeing's Washington State manufacturing cluster and SpaceX's Texas operations concentrate demand for aluminum matrix composites in reusable launch vehicle airframes. FAA Part 25 airworthiness standards tighten material traceability requirements, locking in incumbent suppliers with established qualification dossiers. Lockheed Martin's F-35 and B-21 programs in Texas and California drive thirty-six-month qualification cycles for next-generation fighter procurement.
Germany
Airbus Hamburg and Toulouse facilities source AS9100-certified thermal management extrusions from German Tier-1 suppliers. REACH restrictions on hexavalent chromium surface treatments mandate conversion to sealed anodizing and sol-gel coatings, extending qualification timelines by eighteen months. Bavaria's aerospace supply chain concentrates high-strength 7xxx series forging capacity for landing gear applications.
France
Airbus Toulouse and Safran operations anchor aluminum-lithium demand for narrowbody fuselage skins and engine components. EASA CS-25 amendments incorporate environmental compliance timelines into airworthiness certification requirements. The Occitanie region hosts specialized surface treatment facilities adapting to REACH-mandated coating conversions.
Japan
METI accelerates domestic fiber-reinforced prepreg development to reduce import dependency for military airframe applications. JIS standards govern material qualification protocols for commercial aerospace adoption. Toray Industries anchors Japanese supply chains through prepreg dominance serving domestic and export markets.
China
COMAC Shanghai and Xi'an facilities drive aluminum-lithium procurement for C919 and ARJ21 programs. MEE enforcement of dual carbon goals in primary aluminum smelting threatens to bifurcate supplier eligibility for Western OEM contracts. Yangtze River Delta manufacturing clusters concentrate GB/T-certified extrusion capacity for domestic airframe production.
Global Composite Materials Aluminum Alloys Aerospace Market Competitive Landscape
Player mix skews toward integrated primary producers with captive smelting assets and specialized composite fabricators serving defense qualification pathways. Market structure concentrates around aluminum-lithium rolling mill certifications and powder metallurgy technician pools. Two strategic archetypes dominate: legacy defense contractors with sixty-year qualification dossiers and European extrusion specialists with AS9100-certified thermal management capabilities. Competitive moves center on backward integration into primary aluminum-lithium supply and strategic partnerships for additive manufacturing process qualification.
Among North American integrated producers, Alcoa Corporation anchors primary aluminum-lithium output with captive smelting and rolling assets. Constellium SE exemplifies European positioning through AS9100-certified extrusion capabilities serving Airbus Tier-1 suppliers. Toray Industries represents Japanese supply chain anchoring through fiber-reinforced prepreg development.
| Leading Market Players |
|---|
| Renegade Materials Corp. |
| HEXEL Works Inc. |
| Toray Industries Inc. |
| Alcoa Corporation |
| Solvay S.A. |
| Koninklijke Ten Cate B.V. |
| Materion Corp. |
| Constellium SE |
| Teijin Limited |
| Others |
Supply & Pricing Matrix
Eighteen-month qualification delays for alternative surface treatment approvals under REACH restrictions concentrate pricing power among incumbent European suppliers with established EASA CS-25 dossiers. This lead-time compression reinforces cost premiums for AS9100-certified extrusions while squeezing margins for new entrants lacking qualified surface treatment partnerships.
Pricing Analysis
Technology-generation pricing gaps separate legacy aluminum-lithium rolling mill outputs from powder metallurgy aluminum matrix composites and emerging laser powder bed fusion brackets. Three-tier pricing structure across qualified legacy alloys, defense-grade matrix composites, and additive-manufactured prototypes reflects certification burden and volume scale. Cost compression in commercial airframe alloys intensifies because Boeing and Airbus procurement teams consolidate supplier panels. Defense contractors exhibit lowest price sensitivity due to performance-specification procurement protocols.
Supply Chain Analysis
The United States anchors primary aluminum-lithium smelting and rolling capacity through captive integrated assets, while Germany and France concentrate AS9100-certified extrusion and surface treatment capabilities. Raw material flows draw from bauxite processing in Australia, lithium carbonate from Chile, and ceramic fiber preforms from Japan. Single-source vulnerability in North American primary aluminum-lithium supply threatens European airframer procurement security. Distribution runs through Tier-1 integrator consolidation around Boeing's Washington State cluster and Airbus Hamburg-Toulouse facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in a cyclical recovery phase as defense procurement budgets expand for sixth-generation fighter and hypersonic vehicle programs, reversing prior commercial aerospace contraction.
For Market Incumbents: Secure backward integration into primary aluminum-lithium supply to defend against carbon fiber reinforced polymer substitution in wing structures. Lock in powder metallurgy technician pipelines through apprenticeship partnerships with legacy defense contractors. Certification investment in concurrent FAA-EASA qualification pathways protects against divergent testing protocol cost duplication. For New Entrants and Emerging Players: AS9100-certified thermal management extrusion fast-tracks open qualification slots as Airbus Tier-1 supplier consolidation creates capability gaps in Germany and France. Target UAV frame production economics where low-volume, high-mix procurement prioritizes rapid design iteration over unit cost. Go-to-market leverage rests on sealed anodizing and sol-gel coating partnerships that bypass REACH-mandated eighteen-month approval delays. For Investors and Strategic Acquirers: Long-term, this sits as a defense procurement cycle play because sixth-generation fighter and reusable launch vehicle programs are accelerating aluminum matrix composite qualification timelines. Acquisition targets should concentrate on powder metallurgy specialists with established fatigue resistance dossiers and captive technician pools. The signal to watch is SpaceX Texas operations procurement volume inflection as reusable launch vehicle production scales.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Primary Aluminum-Lithium | Alcoa Corporation's captive smelting assets demonstrate how upstream control insulates against European supply chain fragmentation. |
| Additive Manufacturing Process Qualification | Lockheed Martin's laser powder bed fusion certification for non-structural brackets unlocks topology-optimized designs previously machined from solid billet. |
| Concurrent FAA-EASA Certification Investment | Dual-qualified suppliers avoid duplicated fatigue resistance testing costs as divergent protocols compress qualification windows. |
| Powder Metallurgy Technician Pipeline Development | Legacy defense contractor apprenticeship programs concentrate scarce qualified operators for aluminum matrix composite casting and infiltration processes. |
| Alternative Surface Treatment Qualification | Sealed anodizing and sol-gel coating approvals under REACH restrictions restore competitive position for European Tier-1 suppliers facing eighteen-month delays. |
Research Methodology
Desk research of FAA Part 25 airworthiness directives, EASA CS-25 amendment filings, and customs trade data preceded structured interviews with defense procurement officers, aerospace materials engineers, Tier-1 supplier quality directors, and powder metallurgy technicians. Secondary validation drew from SEC 10-K filings, AS9100 certification registries, and REACH compliance documentation. Bottom-up segment sizing triangulated against top-down defense budget allocation analysis.
Variance decomposition across product type, technology route, application segment, and end-user procurement channel shaped the analytical framework over the projection horizon. Modeled dimensions encompassed aluminum-lithium versus matrix composite material classes, powder metallurgy versus additive manufacturing process economics, airframe versus UAV application margins, and commercial versus defense contractor buying behavior. CAGRs derived from segment-level volume trajectories and input cost elasticity modeling, with aluminum-lithium density reduction premiums and carbon fiber substitution thresholds as aerospace-specific forecast inputs.
Decision-makers should treat outputs as directional under sustained defense procurement expansion and stable FAA-EASA regulatory convergence assumptions; material deviation in either driver would warrant model refresh. Specific risks include MEE dual carbon enforcement bifurcating Chinese supplier eligibility, REACH hexavalent chromium restriction timeline acceleration, and carbon fiber reinforced polymer specific strength ratio improvements displacing aluminum-lithium in wing structures. Recalibration cycles align with material shifts in defense procurement budget appropriations and EASA CS-25 amendment publication schedules.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aerospace and Aircraft Materials
Aerospace Titanium Market
Aerospace and Aircraft Materials
Commercial Aircraft Materials Market
Aerospace and Aircraft Materials
Radiation Shielding Market
Aerospace and Aircraft Materials
India Aerospace Coating Market
Aerospace and Aircraft Materials
Aerospace Composites Market
Aerospace and Aircraft Materials
Aviation Titanium Alloy Market
Aerospace and Aircraft Materials
Aerospace Forging Market
Aerospace and Aircraft Materials
Global Aerospace Adhesives Market
Aerospace and Aircraft Materials
Aerospace Fiber Optics Market
Aerospace and Aircraft Materials
Global Aerospace Titanium Machining Market
Aerospace and Aircraft Materials
Magnesium Beryllium Alloy Market
Aerospace and Aircraft Materials
Beryllium Aluminum Alloy Market
Aerospace and Aircraft Materials
Aerospace Materials Market
Aerospace and Aircraft Materials
Global Anti-Icing Coating Market
Aerospace and Aircraft Materials
Europe Advanced Aerospace Coatings Market
Aerospace and Aircraft Materials
Aerospace Superalloys Market