
 More Electric Aircraft Market | 2026-2036
More Electric Aircraft Market Size, Share, and Industry Trends Forecast 2026-2036
More Electric Aircraft Market Analysis
Modular power-distribution architectures are restructuring how airlines evaluate lifecycle costs across electric and hybrid-electric platforms. Safran SA leverages its integrated actuator and power-electronics portfolio to capture recurring aftermarket revenue. Boeing anchors its position through defense-funded more-electric demonstrators that de-risk commercial derivatives. Honeywell International Inc. competes by extending its auxiliary power unit expertise into high-voltage generator systems for next-generation narrowbodies.
More electric aircraft replace conventional hydraulic, pneumatic, and mechanical systems with electrically powered alternatives, typically operating at 270 V DC or 230 V AC to reduce fuel burn and maintenance burden. The technology's primary purpose is to improve propulsive and thermal efficiency while enabling distributed propulsion configurations. Hybrid electric and turboelectric architectures currently dominate development spending, with fuel cell systems representing the fastest-growing segment as energy density improves. Power electronics and battery systems concentrate the highest margin pools due to qualification barriers and thermal management complexity.
The FAA certifies more-electric systems under Part 25 special conditions, while EASA's CS-25 amendments address high-voltage arc-fault risks, creating dual-compliance costs for global programs. The EU Green Deal's ReFuelEU Aviation mandate shapes demand by penalizing carbon-intensive operations, pushing carriers toward electrified short-haul fleets. China's MIIT sets domestic voltage and electromagnetic compatibility standards that influence supplier design choices for programs targeting that market. Stakeholders must monitor how divergent certification timelines between regulators affect platform launch sequencing and fleet commonality.
Market Dynamics
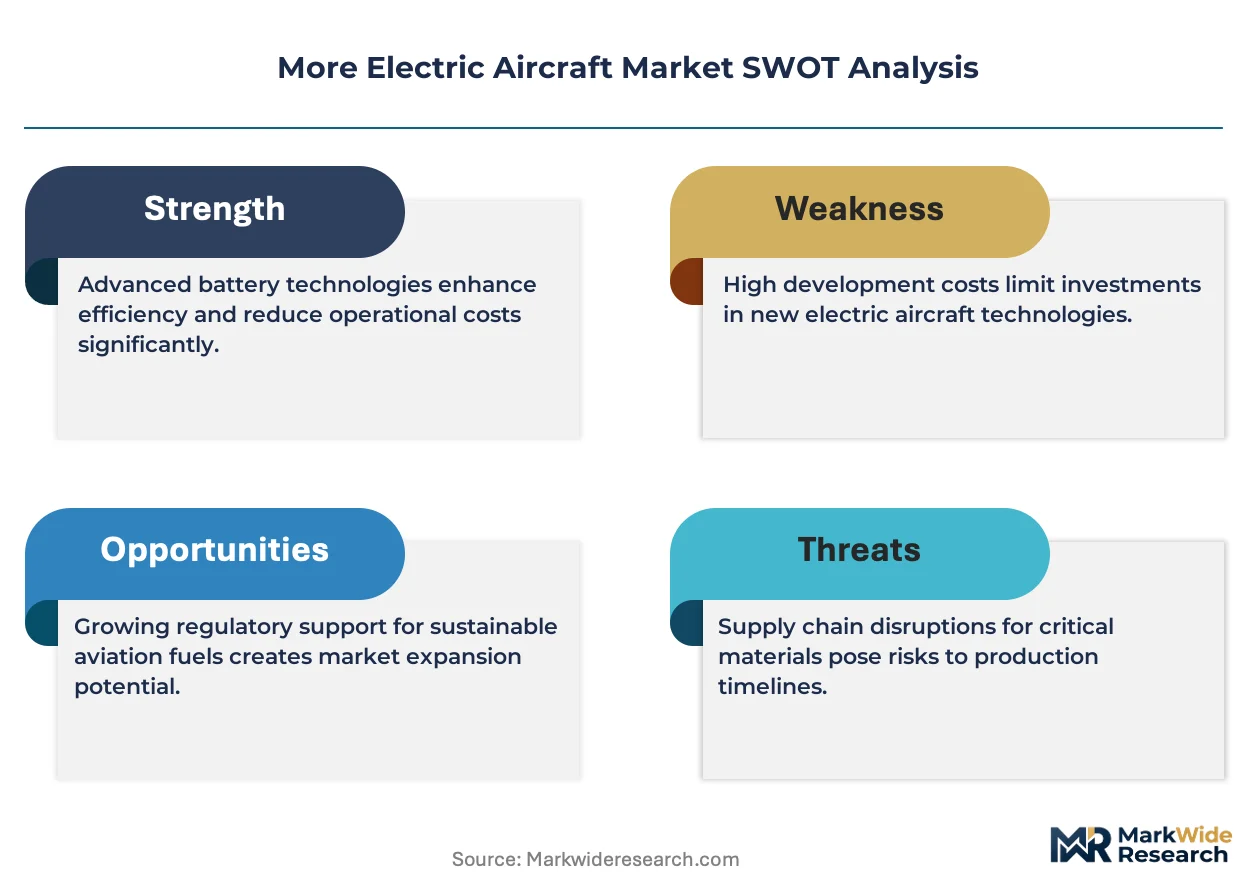
Airframe electrification mandates from the EU Green Deal are forcing airlines to restructure fleet procurement around hybrid-electric platforms, compressing development timelines and supplier qualification windows.
Growth Catalysts
- ReFuelEU Aviation mandate:Penalties on carbon-intensive operations push European carriers toward electrified short-haul fleets, creating guaranteed demand pools for hybrid-electric regional jets.
- Distributed propulsion architectures:Turboelectric and hybrid-electric configurations enable novel airframe designs that improve propulsive efficiency beyond conventional turbofan limits.
- German research clustering:Concentrated R&D investment around Munich and Hamburg accelerates power-electronics qualification and reduces supplier development risk.
Market Restraints
- Battery energy density ceiling:Lithium-ion cell performance limits all-electric range to sub-500 nautical miles, constraining viable route networks for pure-electric platforms.
- Dual-certification cost burden:Divergent FAA Part 25 special conditions and EASA CS-25 high-voltage amendments force redundant testing for global programs.
- Power-electronics supply concentration:Silicon carbide module fabrication concentrates among East Asian foundries, exposing programs to geopolitical supply disruption.
Strategic Opportunities
- Urban air mobility corridors:Vertiport infrastructure deployment in France and Germany creates demand for megawatt-class electric propulsion units in sub-regional applications.
- Fuel cell system integration:Hydrogen-electric architectures bypass battery density constraints for medium-haul routes, opening segments currently unreachable to battery-electric designs.
- Aftermarket power-electronics services:Thermal cycling degradation of high-voltage inverters generates recurring revenue streams through scheduled replacement and refurbishment programs.
Industry Challenges
- High-voltage arc-fault containment:EASA's CS-25 amendments require novel detection and suppression systems that extend certification timelines by 18-24 months.
- Electromechanical actuator integration:Replacing hydraulic flight control surfaces demands recertification of entire control laws, creating program risk for derivative airframes.
- Thermal management engineering scarcity:Qualified specialists for liquid-cooled power-distribution systems command premium compensation, constraining supplier scaling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | More Electric Aircraft Market |
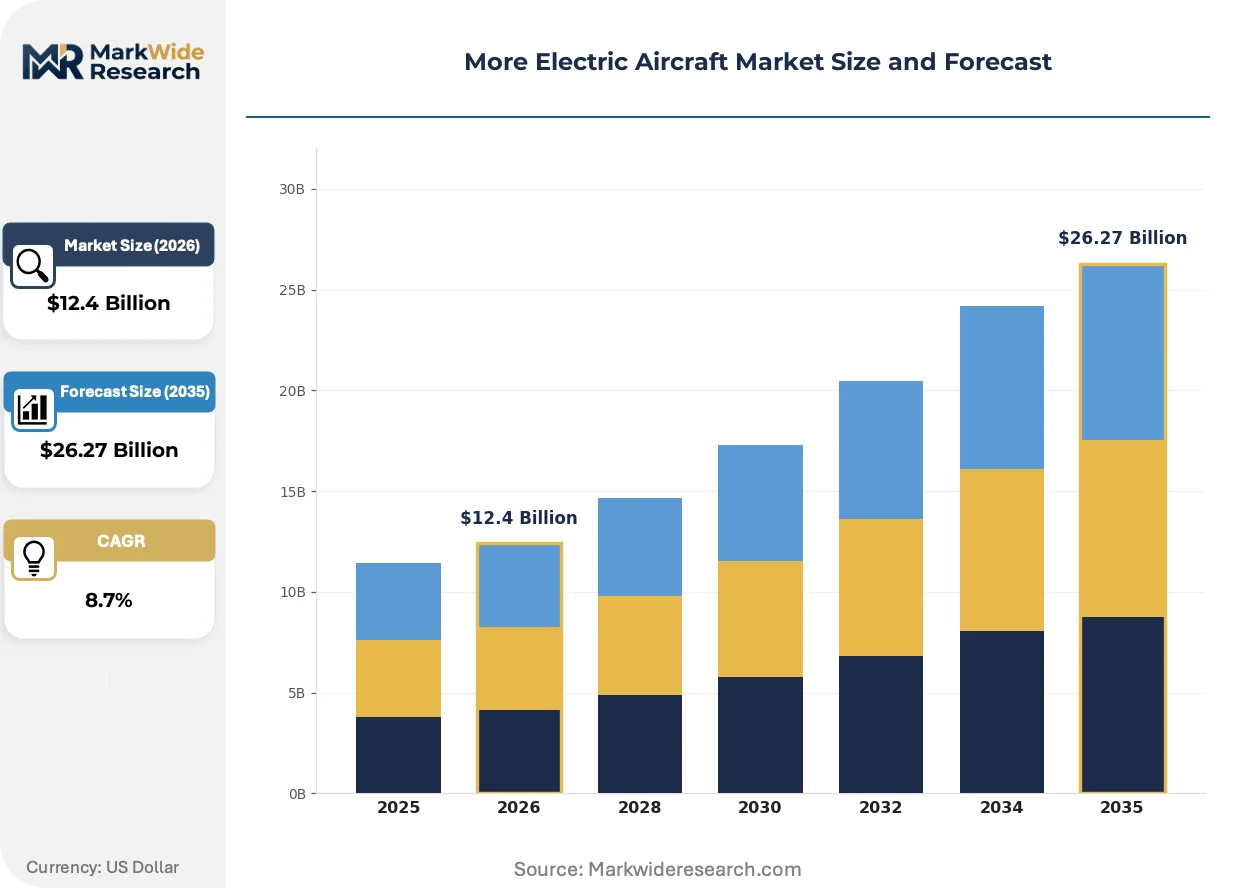
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $26.27 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Hybrid Electric, Fully Electric, Fuel Cell, Turboelectric Component: Power Electronics, Battery Systems, Electric Motors, Propulsion Systems End User: Commercial Aviation, Military Aviation, Cargo Transport, Private Aviation Application: Short-Haul Flights, Urban Air Mobility, Freight Transport, Training Aircraft |
| Companies Covered | The Boeing Company, Airbus SE, Safran SA, Honeywell International Inc., RTX Corporation, Thales Group, Siemens AG, Lockheed Martin Corporation, Raytheon Technologies Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
More Electric Aircraft Market Emerging Trajectories
Model-based systems engineering is compressing development cycles for electric propulsion integration, while regulatory pressure and buyer consolidation reshape competitive requirements.
Silicon carbide power modules are automating thermal management design for 270 V DC distribution buses. Tier-one suppliers adopt these devices faster than silicon IGBT predecessors, enabling higher switching frequencies that reduce magnetics mass. This automation is compressing inverter packaging volumes by 40 percent versus first-generation more-electric systems.
EASA's CS-25 amendments addressing high-voltage arc-fault risks impose mandatory detection thresholds and suppression response times. European OEMs must redesign power-distribution zones to isolate faults without catastrophic propagation. Narrowbody programs targeting dual FAA-EASA certification face the steepest compliance cost increases.
Airline technical procurement teams now require power-by-the-hour contracts for electric propulsion subsystems, mirroring engine maintenance agreements. Traditional component suppliers must build residual-value models and field service networks to win platform selections. This shift concentrates supplier selection authority with Lufthansa Technik and similar MRO-integrated carriers in Germany.
More Electric Aircraft Market Segmentation
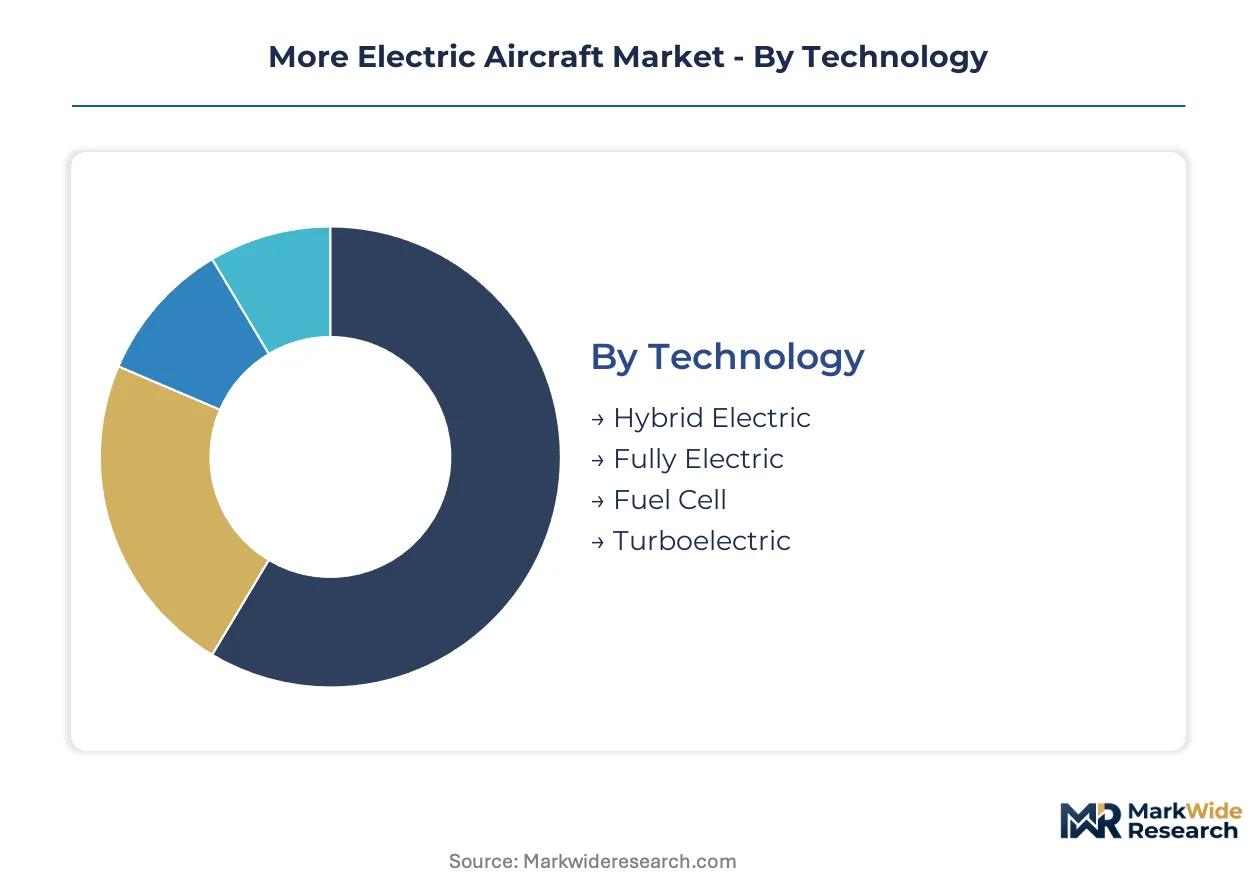
Segmentation in the More Electric Aircraft Market reveals how power-system architectures, component technologies, and operational use cases concentrate supplier investment and regulatory scrutiny. Distinct voltage standards, certification pathways, and thermal management requirements fragment competitive positioning across each dimension.
Technology:
Supply concentration in silicon carbide foundries and battery cell manufacturing tilts competitive advantage toward architectures with the highest power-electronics content.
- Hybrid Electric:Combines conventional turbofan propulsion with electric boost systems operating at 270 V DC. Commercial aviation operators in Germany and France anchor demand as ReFuelEU Aviation penalties reshape short-haul fleet procurement.
- Fuel Cell:Hydrogen-electric architectures bypass lithium-ion density constraints through proton-exchange membrane stacks. Japanese and South Korean energy conglomerates are expanding demonstration programs for medium-haul routes beyond battery-electric range.
- Fully Electric:Battery-powered systems for sub-500 nautical mile missions.
- Turboelectric:Gas turbine generators feeding distributed electric propulsors.
Hybrid Electric absorbs the bulk of installed capacity; Fuel Cell is expanding most quickly.
Component:
Cost tier stratification separates qualified aerospace-grade systems from commercial-industrial derivatives, with margin pools concentrating where thermal cycling endurance demands specialized packaging.
- Power Electronics:Silicon carbide inverters and DC-DC converters manage voltage conversion across 270 V DC distribution buses. EASA's CS-25 arc-fault amendments extend qualification timelines for European-targeted programs.
- Battery Systems:Lithium-ion packs with liquid thermal management dominate current platforms. China's MIIT voltage standards influence cell chemistry selection for programs seeking domestic certification.
- Electric Motors:High-torque-density machines for propulsion and actuation.
- Propulsion Systems:Integrated motor-fan units for distributed thrust configurations.
Power Electronics commands the steepest pricing premiums; Battery Systems are climbing the fastest as energy density improvements unlock new route segments.
End User:
Application maturity varies sharply, with military-funded demonstrators de-risking technologies that commercial carriers adopt once field-proven.
- Commercial Aviation:Regional jet and narrowbody operators restructuring fleets around hybrid-electric platforms. Lufthansa and Air France-KLM procurement mandates concentrate supplier selection authority with MRO-integrated carriers.
- Military Aviation:Defense-funded more-electric demonstrators anchor Boeing's technology pipeline. US Department of Energy grants accelerate high-voltage generator development for next-generation airlifters.
- Cargo Transport:Express freight operators evaluating electric conversions for short-haul feeder networks.
- Private Aviation:Owner-flown electric aircraft for training and recreational missions.
Commercial Aviation carries the largest committed order backlog; Military Aviation is gaining share fastest through classified development spending.
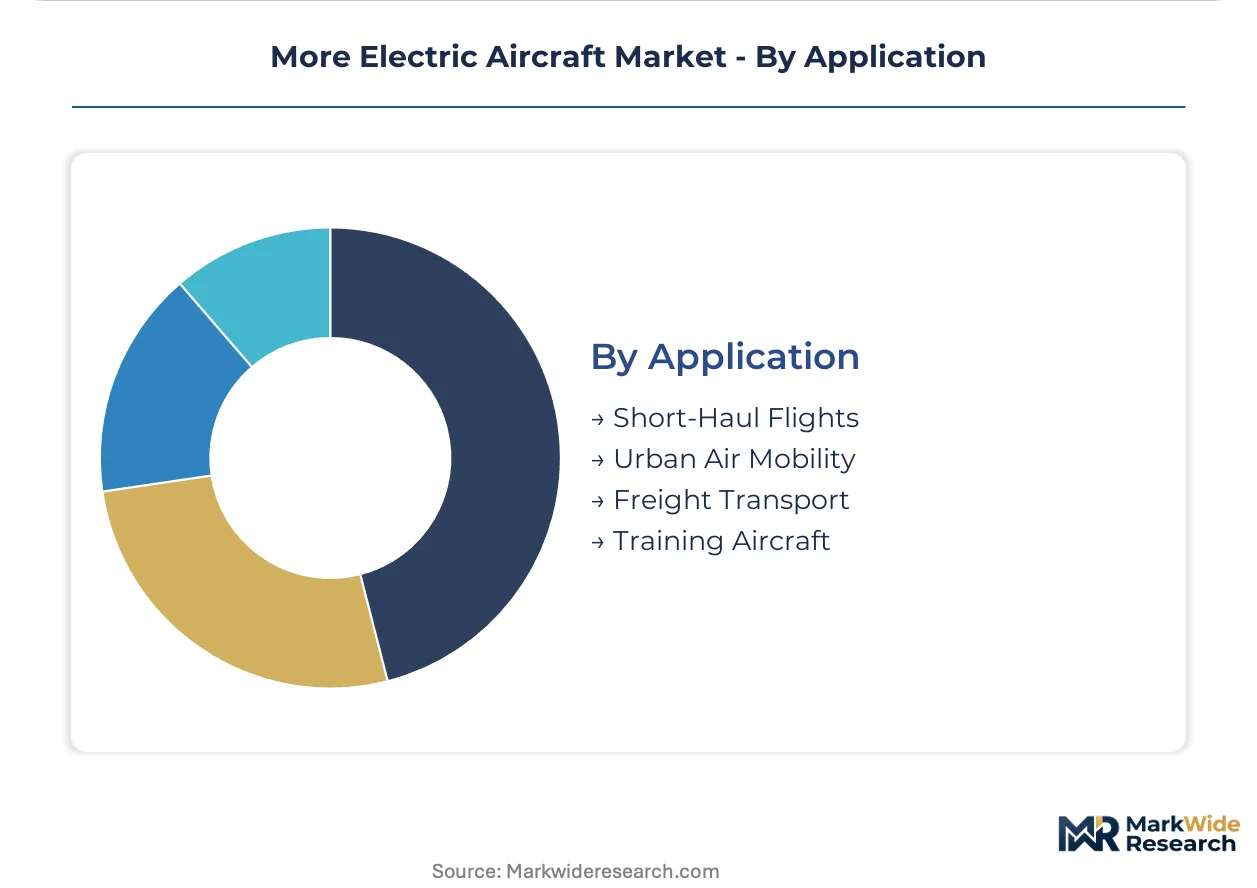
Application:
Customer type fragmentation separates infrastructure-dependent urban networks from autonomous route operations, with procurement patterns diverging between airline fleet planners and vertiport developers.
- Urban Air Mobility:Electric vertical takeoff and landing operations requiring megawatt-class propulsion. Vertiport deployment in France and Germany creates demand for sub-regional electric propulsion units with rapid turnaround cycles.
- Short-Haul Flights:Regional routes under 500 nautical miles where battery-electric economics challenge turboprop operating costs. Scandinavian carriers lead operational trials under Nordic climate conditions.
- Freight Transport:Unmanned cargo drones and electric freighters for last-mile logistics.
- Training Aircraft:Electric-powered basic trainers for flight schools reducing fuel expenditure.
Short-Haul Flights account for the deepest committed investment; Urban Air Mobility shows the steepest expansion trajectory as ground infrastructure matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
France's aerospace special-economic-zone incentives near Toulouse concentrate airframe electrification R&D, drawing tier-one suppliers into clustered development facilities. Tax credits for clean aviation technology accelerate facility construction timelines.
Germany
Lufthansa Technik's procurement mandates and Airbus SE's Hamburg assembly lines drive hybrid-electric platform demand. The EU Green Deal's ReFuelEU Aviation penalties reshape short-haul fleet procurement for German carriers. Munich anchors Siemens AG's power-electronics research cluster, accelerating silicon carbide inverter qualification.
United States
Defense-funded more-electric demonstrators and commercial narrowbody re-engining programs concentrate investment. FAA Part 25 special conditions for high-voltage systems extend certification timelines for dual-approval programs. Boeing anchors development in Washington state, leveraging Department of Energy grants for generator system advancement.
France
Air France-KLM restructuring around electrified regional jets and Safran SA's integrated actuator portfolio concentrate supplier selection authority. EASA's CS-25 arc-fault amendments impose mandatory detection thresholds on European-targeted programs. Toulouse-Blagnac aerospace cluster hosts Thales Group power-distribution development facilities.
China
Domestic narrowbody programs and urban air mobility trials expand addressable demand for electric propulsion units. MIIT voltage and electromagnetic compatibility standards influence cell chemistry selection for certification-seeking suppliers. COMAC's Shanghai facilities integrate local power-electronics suppliers into indigenous platform development.
United Kingdom
Rolls-Royce's turboelectric research and regional airport electrification trials create dual demand streams. CAA alignment with EASA high-voltage standards reduces compliance burden for European-export programs. Bristol-Southwest England cluster concentrates electric motor development for hybrid propulsion applications.
More Electric Aircraft Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across power-electronics and propulsion subsystems. Tier-one aerospace integrators anchor platform-level decisions while component specialists capture recurring aftermarket revenue. Three archetypes dominate: vertically integrated airframers, power-system conglomerates, and specialized actuator suppliers. Competitive moves concentrate on strategic partnerships for thermal management and M&A targeting silicon carbide fabrication capacity.
Among European-anchored conglomerates, Airbus SE and Safran SA exemplify the integrated-platform archetype, while Siemens AG occupies a position within the power-electronics specialist tier. These entities represent contrasting strategic postures: airframer-led system integration versus component-level technology depth.
| Leading Market Players |
|---|
| The Boeing Company |
| Airbus SE |
| Safran SA |
| Honeywell International Inc. |
| RTX Corporation |
| Thales Group |
| Siemens AG |
| Lockheed Martin Corporation |
| Raytheon Technologies Corporation |
| Others |
Supply Flow & Price Mechanics
The EU Green Deal's ReFuelEU Aviation mandate gates both qualified supply and premium-tier pricing access, as carriers seeking penalty avoidance pay steep certification premiums for arc-fault-compliant power-electronics systems while suppliers with EASA CS-25 qualification capture margin premiums unavailable to commercial-industrial component vendors.
Pricing Analysis
Margin tightening in aerospace-grade power-electronics reflects silicon carbide module scarcity and dual-certification testing burdens. Three-tier pricing structure across flight-qualified, industrial-adapted, and commercial-off-the-shelf levels separates EASA-certified inverters from unqualified alternatives. Cost-down pressure on battery systems accelerates because lithium-ion cell suppliers compete for aviation thermal-management contracts. Regional jet operators exhibit highest price sensitivity; defense-funded demonstrator programs show lowest.
Supply Chain Analysis
China's MIIT domestic-content mandates reshape sourcing for programs seeking certification in that market, compelling foreign suppliers to localize silicon carbide packaging or partner with indigenous foundries. Silicon carbide wafer fabrication concentrates in Japan, Germany, and the United States; lithium-ion cell production draws from South Korea and China. Single-source vulnerability pervades high-voltage inverter assembly. Distribution runs through tier-one aerospace integrators with captive MRO networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Silicon carbide foundry capacity constraints prop pricing premiums across qualified power-electronics tiers, making supply security the decisive competitive variable.
For Market Incumbents: Lock in long-term offtake agreements with Japanese and German silicon carbide foundries before urban air mobility procurement waves absorb remaining capacity. Deepen backward integration into thermal management engineering to offset specialist compensation inflation. Anchor position through EASA CS-25 amendment pre-compliance investments that extend certification lead times for unqualified rivals. For New Entrants and Emerging Players: Begin with aftermarket power-electronics refurbishment services, where scheduled inverter replacement cycles generate recurring revenue without airframe platform qualification burdens. Urban air mobility vertiport networks in France and Germany offer the most penetrable demand cluster. Pursue power-by-the-hour contracting models that mirror Lufthansa Technik procurement mandates. For Investors and Strategic Acquirers: First-military-commercial derivative certification is the leading indicator that technology de-risking has reached inflection, signaling readiness for regional jet platform selection. Five-to-ten year viability hinges on fuel cell system integration capabilities beyond battery-electric range limits. Watch for Siemens AG or Thales Group power-distribution unit spinouts as acquisition targets.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Foundry Partnership | Secures qualified wafer supply for EASA-certified inverter programs ahead of demand surges. |
| Arc-Fault Detection System Certification | Accelerates EASA CS-25 compliance timelines for European-targeted narrowbody electrification. |
| Fuel Cell Stack Integration | Opens medium-haul route segments unreachable to battery-electric architectures. |
| Power-by-the-Hour Service Launch | Aligns supplier offerings with Lufthansa Technik and Air France-KLM procurement mandates. |
| Urban Air Mobility Propulsion Unit Development | Captures megawatt-class demand from vertiport deployment in France and Germany. |
Methodological Framework
Multi-period observation of ReFuelEU Aviation penalty schedules, EASA CS-25 amendment implementation timelines, and silicon carbide foundry capacity announcements anchored the trend analysis, supplemented by interviews with airframer platform engineers, tier-one power-electronics procurement leads, MRO contract managers, and thermal management specialists. Secondary validation drew from FAA Part 25 special condition filings, EASA certification bulletins, EU Green Deal policy documents, and Department of Energy grant disclosures. Bottom-up platform demand estimates triangulated against top-down fleet electrification spending projections.
Input-output matrices mapped hybrid-electric, fuel cell, turboelectric, and fully electric architectures against power-electronics, battery, motor, and propulsion component demand across commercial, military, cargo, and private aviation end uses. CAGRs derived from segment-level adoption curves and technology-readiness thresholds. Forecast inputs incorporated battery energy density improvement trajectories and dual-certification cost burdens.
Underlying measurement precision varies by segment; military aviation development spending carries tighter precision than commercial order backlog conversion. Forecasts reflect assumptions regarding ReFuelEU Aviation penalty enforcement and silicon carbide supply expansion. Geopolitical disruption to East Asian foundry operations or EASA-FAA regulatory divergence could revise projections. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Power Systems
Thrust Vector Control (TVC) Systems Market
Aircraft Power Systems
Aircraft Propeller System Market
Aircraft Power Systems
Aircraft Electrical Systems Market
Aircraft Power Systems
Aircraft Hydraulic Actuators Market
Aircraft Power Systems
Global Aircraft Electrification Market
Aircraft Power Systems
Fly-By-Wire System Market
Aircraft Power Systems
Aircraft Turbocharger Market
Aircraft Power Systems
Aerospace Battery Technology Market
Aircraft Power Systems
Asia-Pacific Aircraft Circuit Breakers Market
Aircraft Power Systems
Military Aircraft Actuation System Market
Aircraft Power Systems
Electrified Aircraft Propulsion Market
Aircraft Power Systems
Aircraft Drive Shaft and Couplings Market
Aircraft Power Systems
Global Aircraft Micro Turbine Market
Aircraft Power Systems
Space Power System Hardware-in-the-Loop Test Platforms Market
Aircraft Power Systems
Air Independent Propulsion Systems (AIP) Market
Aircraft Power Systems
Aircraft Thrust Reverser Market