
 Global Flame Retardant for Aerospace Plastics Market | 2026-2036
Global Flame Retardant for Aerospace Plastics Market Size, Share, and Industry Trends Forecast 2026-2036
Global Flame Retardant for Aerospace Plastics Market Foresight
The split between premium and commodity tiers is shifting as OEMs demand FAA-certified halogen-free systems while aftermarket buyers tolerate legacy brominated grades. Clariant leverages its phosphorus-based portfolio to anchor European OEM supply chains. Albemarle Corporation dominates brominated chemistry for defense applications where legacy approvals persist. LANXESS sustains pricing power through reactive technology integration with major Tier-1 suppliers.
Flame retardant for aerospace plastics denotes specialty additives engineered into thermoset and thermoplastic matrices to achieve vertical burn ratings below sixty seconds and smoke density limits specified under FAR 25.853, with loadings typically ranging from fifteen to forty percent by weight depending on base resin and certification tier. These formulations serve the primary purpose of preventing flame propagation in cabin interiors, avionics housings, and structural brackets without compromising mechanical performance at altitude. Phosphorus-based systems capture expanding share as halogen-free mandates proliferate across commercial aviation procurement specifications. Additive technology remains the volume leader for retrofit and MRO channels, while reactive and nanocomposite approaches concentrate among next-generation airframe programs seeking weight reduction.
FAA Part 25.853 and EASA CS-25 airworthiness codes dictate smoke, toxicity, and heat-release thresholds that determine material qualification timelines and supplier eligibility. China's CAAC and Japan's JCAB maintain bilateral recognition agreements with FAA standards, though domestic certification testing adds cost layers for imported formulations. REACH restrictions on halogenated compounds in Europe and evolving EPA risk evaluations under TSCA in the United States are forcing reformulation cycles across legacy product lines. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded inventory and recertification delays.
Market Dynamics
Commercial aircraft OEM procurement mandates for halogen-free formulations are compressing certification timelines and forcing reformulation investments across specialty chemical suppliers. This structural pressure is reconfiguring competitive positioning between phosphorus-based innovators and legacy brominated producers.
Growth Catalysts
- FAA Part 25.853 smoke-toxicity thresholds:Tighter heat-release and smoke-density specifications are disqualifying legacy formulations from new commercial airframe contracts. Tier-1 suppliers must qualify replacement chemistries to maintain OEM eligibility.
- Urban Air Mobility cabin materials:Electric vertical takeoff aircraft programs require thermoplastic composites with flame-retardant loadings below thirty percent by weight to preserve battery range. This specification is pulling novel intumescent systems into qualification pipelines.
- Defense aviation procurement persistence:Military platforms in the United States and Germany continue procuring brominated grades under grandfathered approvals. This demand sustame production lines while commercial channels transition.
Market Restraints
- Phosphorus feedstock concentration:Elemental phosphorus production clusters in China and Kazakhstan. Geopolitical friction or export controls would disrupt European and North American formulator supply chains.
- REACH authorization timelines:ECHA's substance evaluation procedures for novel halogen-free chemistries extend eighteen to thirty-six months. Formulators face stranded R&D investment if authorization delays persist.
- Mechanical performance trade-offs:Reactive flame-retardant integration reduces impact strength in polycarbonate blends. Engineers must accept weight penalties or redesign bracket geometries.
Strategic Opportunities
- India defense indigenization:The country's PLI scheme for aerospace components is creating demand for domestically certified flame-retardant formulations. Suppliers establishing local testing partnerships can capture platform-specific approvals.
- Recycled thermoplastic integration:Circular material mandates from EASA and OEM sustainability targets are converging with flame-retardant challenges. Formulators solving thermal stability in reprocessed PEEK can differentiate on Scope 3 emissions.
- Space tourism cabin interiors:Suborbital vehicle operators are specifying commercial aviation-grade fire safety without full FAR 25 certification. This regulatory gap permits faster qualification cycles for adapted formulations.
Industry Challenges
- Fire-test engineer scarcity:Qualified personnel capable of interpreting FAR 25.853 Appendix F results and managing OEM witness testing are concentrated at legacy suppliers. New entrants face recruitment bottlenecks.
- Dual-certification complexity:Formulators must simultaneously maintain FAA and EASA qualification for identical SKUs. Divergent audit schedules and documentation requirements inflate quality-system overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Flame Retardant for Aerospace Plastics Market |
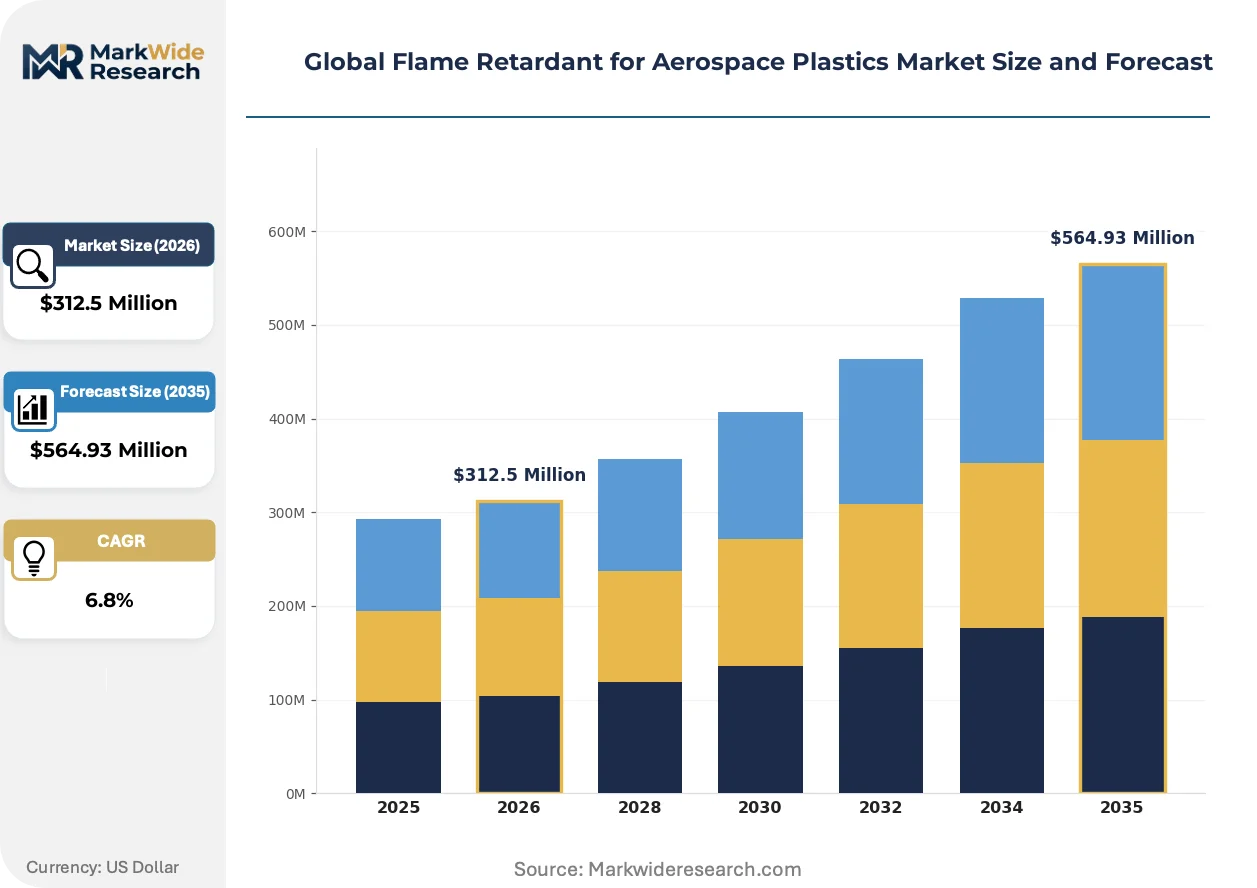
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $564.93 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Phosphorus-Based, Halogen-Free, Aluminum Hydroxide, Intumescent, Melamine, Nitrogen-Based Technology: Reactive, Additive, Synergistic, Coating, Encapsulation, Nanocomposite Application: Aircraft Interiors, Structural Components, Avionics Enclosures, Engine Parts, Landing Gear Systems, Cabin Accessories End User: OEMs, Tier-1 Suppliers, Aircraft Maintenance, Aerospace Research Centers, Defense Contractors, Component Manufacturers |
| Companies Covered | Huber Engineered Materials, Clariant, RTP Company, BASF SE, LANXESS, ICL Industrial Products, Italmatch Chemicals, Albemarle Corporation, DuPont, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Flame Retardant for Aerospace Plastics Market Shifts & Advancements
Material science advances are compressing the performance gap between additive and reactive systems. This convergence is enabling weight reduction in structural brackets without sacrificing vertical burn compliance.
Phosphorus-nitrogen synergist technology is converging with nano-layered silicate dispersion techniques to produce intumescent coatings below one millimeter thickness. Tier-1 composite laminators in Germany and Japan are adopting these systems for thermoplastic wing access panels. The resulting density reduction is converging with airframe electrification priorities to extend unrefueled range in hybrid regional jets.
REACH restrictions on halogenated flame retardants are forcing reformulation cycles across legacy product portfolios. ECHA's 2023-2025 substance evaluation roadmap specifically targets brominated diphenyl ethers in aerospace applications. European formulators are accelerating phosphorus-based development programs to maintain OEM supply chain position before authorization deadlines.
Airline procurement departments are consolidating qualified material lists to reduce MRO complexity. Technical buyers at major carriers in the United States and China are demanding dual-source availability for all cabin interior chemistries. This concentration is compressing supplier margins while extending contract durations for incumbents who achieve sole-source positions on specific airframe programs.
Global Flame Retardant for Aerospace Plastics Market Segmentation
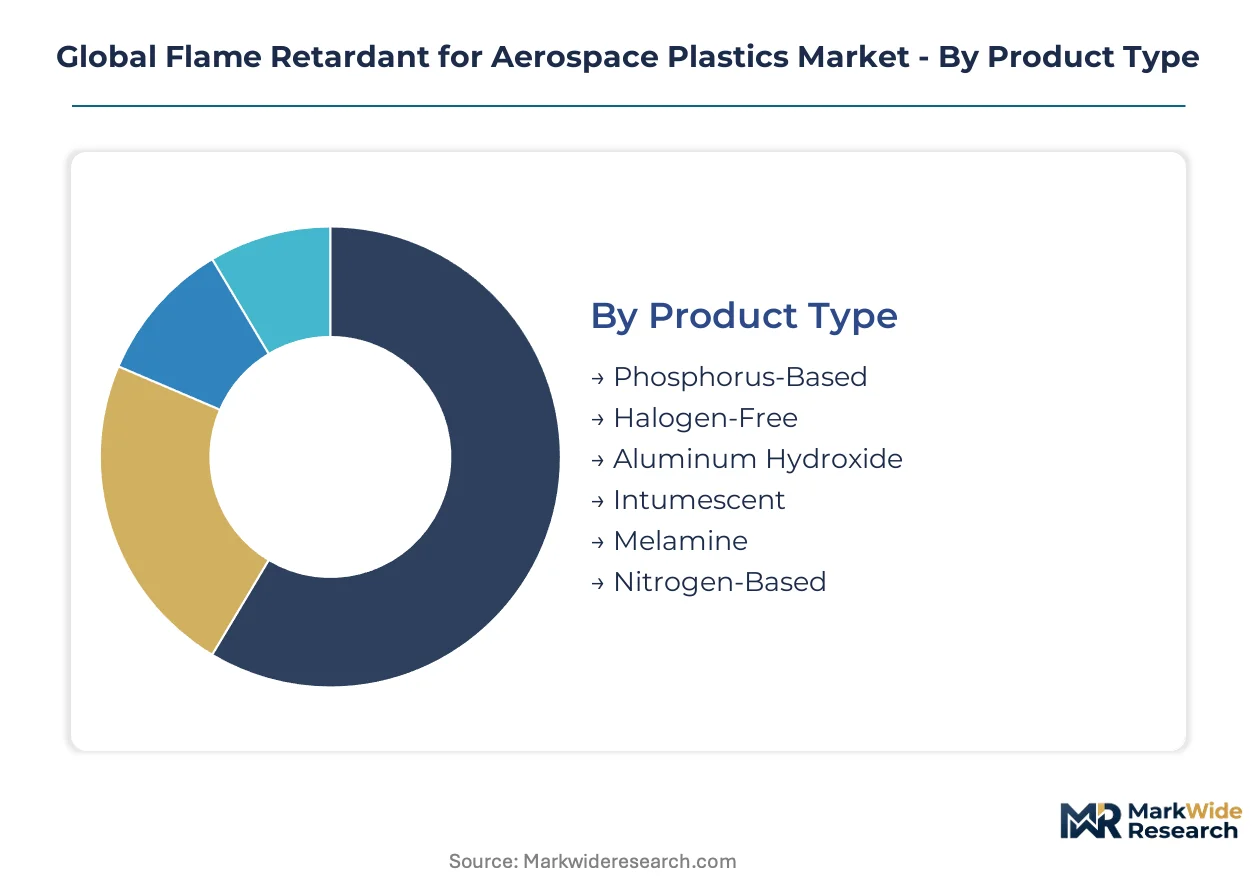
Certification tier determines supplier eligibility and pricing power across every segment of this market. FAA Part 25.853 and EASA CS-25 requirements create divergent qualification burdens that fragment competitive positioning by product chemistry, technology approach, and end-user procurement authority.
Product Type:
Phosphorus-based and halogen-free formulations carry the heaviest certification burden under tightening FAA smoke-toxicity thresholds, while legacy chemistries operate under grandfathered approvals with lighter requalification requirements.
- Phosphorus-Based:These systems utilize organic and inorganic phosphorus compounds to achieve vertical burn ratings below sixty seconds without halogen content. Boeing and Airbus procurement mandates are concentrating demand in Germany and the United States as European REACH deadlines approach.
- Halogen-Free:Formulations exclude bromine and chlorine entirely to meet emerging OEM sustainability specifications. China's CAAC is aligning certification testing with FAA standards, compressing approval timelines for domestic suppliers serving COMAC programs.
- Aluminum Hydroxide:ATH fillers provide cost-effective flame suppression in thermoset composites for cargo liner applications.
- Intumescent:Expanding char-forming systems enable thin-wall designs in thermoplastic wing access panels.
- Melamine:Nitrogen-rich chemistry finds niche use in cabin acoustic insulation layers.
- Nitrogen-Based:Pure nitrogen synergists complement phosphorus in next-generation synergistic blends.
Leading the category by volume: Halogen-Free. Growing fastest: Phosphorus-Based.
Technology:
Reactive integration commands premium pricing through permanent chemical bonding, while additive approaches dominate aftermarket channels where lower certification costs align with MRO budget constraints.
- Reactive:Flame-retardant moieties covalently bond to polymer backbones, preventing migration and preserving mechanical properties at altitude. LANXESS maintains supply chain control through captive reactive technology serving major Tier-1 suppliers in Germany.
- Additive:Physical dispersion of flame-retardant particles into thermoplastic melts requires lower capital investment and faster formulation cycles. Aftermarket buyers in the United States tolerate legacy brominated additive grades where full FAR 25.853 recertification is economically unjustified.
- Synergistic:Phosphorus-nitrogen combinations reduce total loading requirements.
- Coating:Surface-applied intumescent layers protect complex geometries.
- Encapsulation:Microencapsulated additives control release kinetics.
- Nanocomposite:Layered silicate dispersions enable sub-thirty-percent loadings for Urban Air Mobility battery range preservation.
Highest margin capture: Reactive. Volume concentration: Additive.
Application:
Aircraft interiors impose the strictest heat-release and smoke-density specifications, while structural components prioritize mechanical retention under burn conditions.
- Aircraft Interiors:Seat shells, overhead bins, and sidewall panels must simultaneously satisfy FAR 25.853 vertical burn, smoke density, and toxicity limits. OEM procurement consolidation in the United States and China is compressing qualified supplier lists to dual-source configurations.
- Structural Components:Brackets, clips, and floor beams require flame-retardant integration without compromising impact strength or fatigue resistance. Engineers in Germany accept weight penalties or redesign geometries to accommodate reactive flame-retardant integration in polycarbonate blends.
- Avionics Enclosures:EMI-shielded housings demand conductive fillers alongside flame suppression.
- Engine Parts:High-temperature thermosets near nacelles face specialized FAA fire containment rules.
- Landing Gear Systems:Hydraulic fluid resistance complicates flame-retardant selection.
- Cabin Accessories:Galley inserts and lavatory components follow relaxed certification tiers.
Certification intensity peaks: Aircraft Interiors. Fastest specification evolution: Structural Components.
End User:
OEMs and Tier-1 suppliers control new airframe qualification pathways, while defense contractors and maintenance operators sustain legacy chemistry demand through grandfathered approvals.
- OEMs:Boeing, Airbus, and COMAC specify halogen-free formulations in new commercial airframe contracts, forcing Tier-1 suppliers to qualify replacement chemistries. Procurement departments consolidate qualified material lists to reduce MRO complexity.
- Tier-1 Suppliers:Spirit AeroSystems and GKN Aerospace integrate flame-retardant formulations into composite laminates and injection-molded brackets. Technical buyers demand dual-source availability for all cabin interior chemistries.
- Aircraft Maintenance:MRO channels in the United States procure additive brominated grades for retrofit applications.
- Aerospace Research Centers:NASA and JAXA fund next-generation nanocomposite development.
- Defense Contractors:Lockheed Martin and Rheinmetall sustain brominated production lines under military grandfathered approvals.
- Component Manufacturers:Specialized bracket and fastener producers follow Tier-1 specifications.
Procurement authority concentrates: OEMs. Fastest contract velocity: Tier-1 Suppliers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Seattle anchors commercial aerospace manufacturing demand through Boeing's final assembly lines, while Toulouse and Hamburg concentrate Airbus operations. Regulatory divergence between FAA and EASA certification timelines fragments supplier strategies across these manufacturing clusters.
United States
Defense aviation programs at Lockheed Martin sustain brominated formulation demand under grandfathered approvals. FAA Part 25.853 mandates compress qualification timelines for halogen-free alternatives. Wichita's Spirit AeroSystems facility drives Tier-1 procurement consolidation for thermoplastic composites.
Germany
Airbus Hamburg final assembly and Premium Aerotec operations concentrate phosphorus-based specification demand. ECHA REACH authorization timelines extend eighteen to thirty-six months for novel chemistries. Bavaria's composite laminators adopt reactive technology integration for next-generation wing access panels.
China
COMAC C919 production ramp and Urban Air Mobility battery range requirements pull intumescent systems into qualification. CAAC aligns certification testing with FAA standards under bilateral recognition agreements. Shanghai's Yangtze River Delta hosts expanding thermoplastic composite manufacturing for domestic programs.
France
Toulouse-Blagnac aerospace cluster concentrates cabin interior specification authority for Airbus programs. ANSM maintains pharmaceutical-grade chemical oversight that overlaps with specialty additive imports. Lyon-based composite suppliers qualify phosphorus-nitrogen synergist blends for thermoplastic applications.
Japan
JAXA-funded nanocomposite development programs target sub-thirty-percent flame-retardant loadings for weight-critical applications. METI standards harmonization with FAA reduces duplicate testing for export formulations. Nagoya's Chubu region concentrates Tier-2 bracket manufacturing with reactive technology integration.
Global Flame Retardant for Aerospace Plastics Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across formulation and certification services. The supplier base fragments between integrated chemical conglomerates with captive phosphorus supply and specialized compounders serving regional MRO channels. Three archetypes dominate: halogen-free innovators, legacy brominated defenders, and reactive technology specialists. Competitive moves concentrate on dual-certification capacity expansion and strategic partnerships with Tier-1 laminators.
Within the halogen-free innovation tier, Clariant and LANXESS occupy positions anchored by European OEM supply chain relationships. Albemarle Corporation exemplifies the legacy defense-focused archetype, sustaining production lines through military grandfathered approvals. These three entities represent the competitive spectrum from phosphorus-based development to brominated continuity.
| Leading Market Players |
|---|
| Huber Engineered Materials |
| Clariant |
| RTP Company |
| BASF SE |
| LANXESS |
| ICL Industrial Products |
| Italmatch Chemicals |
| Albemarle Corporation |
| DuPont |
| Others |
Supply & Pricing Matrix
Captive phosphorus supply integration anchors competitive position for European formulators serving Airbus and Boeing procurement channels. This upstream control over elemental phosphorus feedstock enables margin defense against REACH-driven reformulation cycles while locking in multi-year supply agreements with Tier-1 laminators in Germany and the United States.
Pricing Analysis
Certification-grade pricing anchors value capture across the market, with FAA Part 25.853 and EASA CS-25 qualification tiers commanding substantial premiums over MRO-grade additive formulations. Price differentiation separates reactive technology integration for OEM airframe contracts from legacy brominated additive grades serving defense maintenance channels. Cost compression in the aftermarket tier is intensifying because airline procurement departments are consolidating qualified material lists to dual-source configurations. Tier-1 suppliers exhibit lowest price sensitivity due to sole-source positioning on specific airframe programs, while component manufacturers face highest sensitivity from specification pass-through.
Supply Chain Analysis
Single-source vulnerability sits with elemental phosphorus production clustering in China and Kazakhstan, exposing European and North American formulators to geopolitical friction or export control disruption. Raw material dependencies center on phosphate rock, red phosphorus, and brominated intermediates for legacy defense applications. Supply chain risk manifests as regulatory restriction through ECHA authorization timelines extending eighteen to thirty-six months for novel halogen-free chemistries. Distribution runs through qualified supplier lists maintained by Boeing, Airbus, and COMAC procurement departments, with Tier-1 composite laminators in Germany, the United States, and Japan serving as specification gatekeepers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
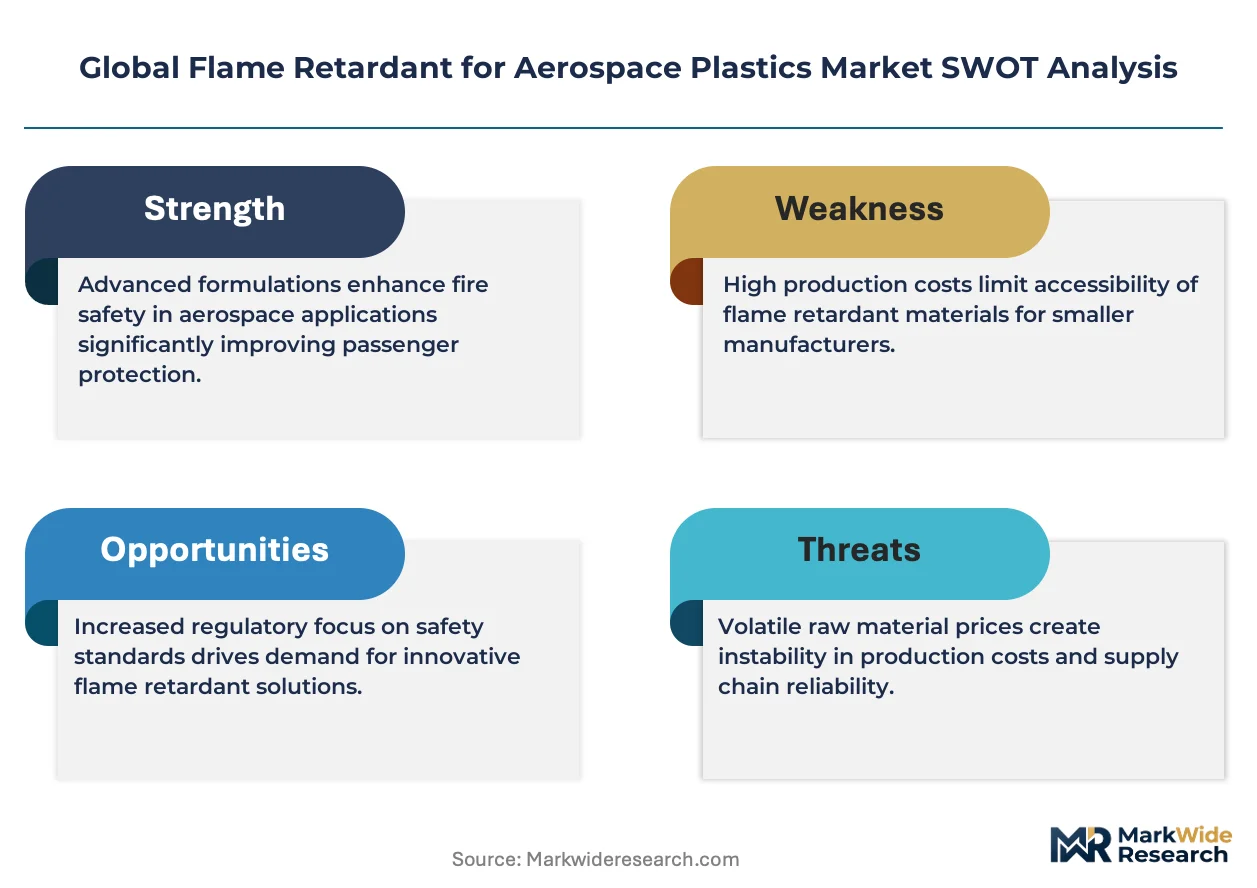
This market functions as a cost-of-compliance story where FAA Part 25.853 certification creates a barrier-to-entry moat that protects qualified incumbents from commodity chemical competition. The regulatory burden compresses new entrant timelines while extending contract durations for compliant players.
For Market Incumbents: Deepen reactive technology integration partnerships with major Tier-1 suppliers in Germany to defend against phosphorus-based innovators. Expand dual-certification capacity across FAA and EASA jurisdictions to capture procurement consolidation at Boeing and Airbus. Anchor supply position through captive phosphorus arrangements or long-term offtake agreements with Chinese producers.
For New Entrants and Emerging Players: E-commerce-enabled formulation sampling offers a low-friction route to qualify with smaller MRO operators in the United States before scaling to OEM channels. Target India's defense indigenization programs under the PLI scheme for aerospace components, where domestic certification partnerships can bypass entrenched European supply relationships. Lead with rapid qualification services for Urban Air Mobility battery range specifications.
For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to integrated chemical conglomerates seeking phosphorus-based aerospace positioning. Long-term viability favors formulators with reactive technology IP and established OEM supply chain relationships over commodity additive producers. Watch for ECHA authorization delays as an inflection indicator that would strand R&D investment and compress valuation multiples for halogen-free development programs.
| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Certification Capacity Expansion | Simultaneous FAA and EASA qualification reduces quality-system overhead for Boeing and Airbus supply. |
| Backward Integration into Phosphorus Supply | Captive feedstock access defends margin position against REACH-driven reformulation cycles. |
| Urban Air Mobility Partnership | Sub-thirty-percent loading specifications for battery range preservation open new qualification pipelines. |
| India Defense Localization Joint Venture | PLI scheme alignment enables platform-specific approvals with Hindustan Aeronautics and Bharat Electronics. |
| Recycled Thermoplastic Integration Program | Thermal stability solutions for reprocessed PEEK differentiate on Scope 3 emissions under EASA circular mandates. |
Research Methodology
Trade databases, regulatory filing repositories, and specialty chemical industry associations formed the secondary backbone for this analysis. Primary fieldwork involved structured interviews with flame-retardant formulator R&D directors, Tier-1 aerospace composite procurement managers, FAA designated engineering representatives, and ECHA authorization specialists. Bottom-up and top-down triangulation validated volume estimates against customs data for phosphorus compound trade flows and OEM production forecasts.
Bottom-up modeling anchored projections across the analysis window, with top-down cross-checks against aerospace plastics consumption trends. Segmentation dimensions included product chemistry tier, technology approach, application certification intensity, and end-user procurement authority. CAGRs were derived from fitted growth curves incorporating airframe delivery schedules and regulatory deadline impacts. Industry-specific inputs comprised FAR 25.853 Appendix F test result databases and REACH authorization pipeline status.
The model holds under stable bilateral recognition between FAA and EASA; deviation in CAAC unilateral standard-setting or phosphorus export controls would shift trajectory. Forecasts reflect documented assumptions on airframe production rates and regulatory enforcement intensity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aerospace and Aircraft Materials
Aerospace Plastics Market
Aerospace and Aircraft Materials
Aerospace Additive Manufacturing Market
Aerospace and Aircraft Materials
Global Military Aerospace Coatings Market
Aerospace and Aircraft Materials
Commercial Aerospace 3D Printing Market
Aerospace and Aircraft Materials
Global Aerospace Insulation Market
Aerospace and Aircraft Materials
Composites in United States Defense Market
Aerospace and Aircraft Materials
Aerospace Threaded Fasteners Market
Aerospace and Aircraft Materials
Aerospace Materials Market
Aerospace and Aircraft Materials
Aramid Honeycomb Market
Aerospace and Aircraft Materials
Aeroengine Composites Market
Aerospace and Aircraft Materials
Aircraft Coatings Market
Aerospace and Aircraft Materials
Radiation Shielding Market
Aerospace and Aircraft Materials
Aerospace Raw Materials Market
Aerospace and Aircraft Materials
Defense Aircraft Material Market
Aerospace and Aircraft Materials
Commercial Aerospace Carbon Brakes Market
Aerospace and Aircraft Materials
Aerospace Cold Forgings Market