
 Out-of-Autoclave Composite Skin Panels for Regional and Business Jets Market | 2026-2036
Out-of-Autoclave Composite Skin Panels for Regional and Business Jets Market Size, Share, and Industry Trends Forecast 2026-2036
Out-of-Autoclave Composite Skin Panels for Regional and Business Jets Market Insights
Power-by-the-hour leasing and asset-light manufacturing partnerships are reshaping capital deployment across the regional and business jet supply chain. Spirit AeroSystems leverages in-house autoclave elimination to reduce tooling capital for narrowbody-derived regional programs. GKN Aerospace anchors European OOA capacity through its Bristol and Munich process centers. Hexcel specializes in toughened epoxy prepreg formulations that compete on out-time and tack life at room temperature cure.
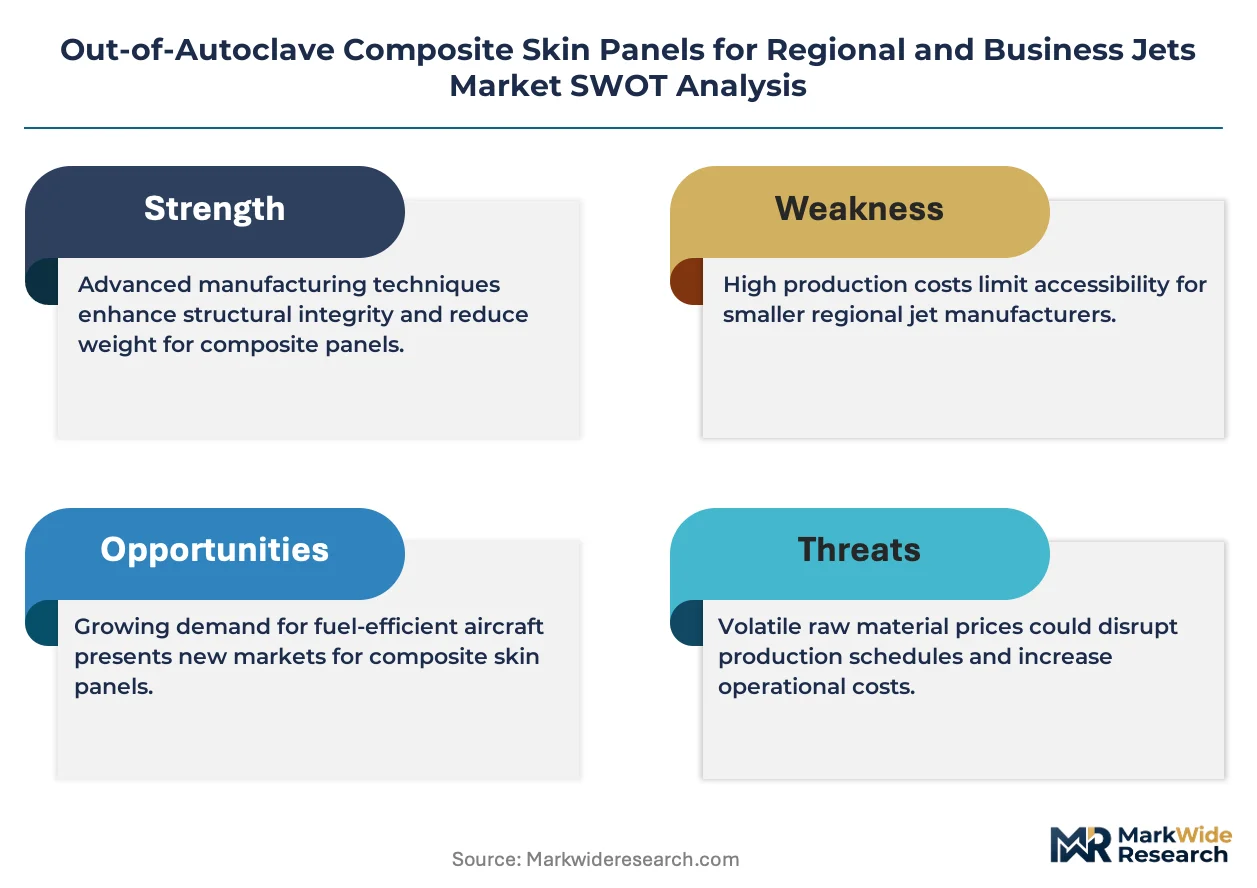
Out-of-Autoclave Composite Skin Panels for Regional and Business Jets are fiber-reinforced polymer laminates cured under vacuum pressure at temperatures below 180°C, eliminating the autoclave's superheated nitrogen environment while achieving 90-95% of autoclave-grade mechanical properties. These panels serve as primary aerostructures where weight reduction must balance damage tolerance and repairability. Carbon fiber dominates fuselage panel applications where specific stiffness requirements are highest, while hybrid composites gain share in tail cone assemblies where cost sensitivity intersects with moderate load paths. Thermoplastic composites represent the fastest-growing product type as welding-compatible PEEK and PPS matrices enable fusion-bonded assembly without adhesive cure cycles.
FAA Part 25 airworthiness standards and EASA CS-25 certification frameworks govern damage tolerance and fatigue life for bonded primary structures, forcing material suppliers to qualify each resin-fiber combination through full-scale structural tests. The EU Green Deal's aviation decarbonization targets pressure OEMs to adopt low-temperature cure chemistries that cut manufacturing energy intensity per kilogram of structure. Stakeholders must monitor whether emerging thermoplastic welding standards from ISO and ASTM will displace mechanical fastening in next-generation regional jet wing boxes.
Market Dynamics
OOA composite skin panels for regional and business jets are experiencing accelerated qualification cycles as FAA and EASA tighten bonded primary structure standards, forcing material suppliers to front-load certification investments before production contracts finalize.
Growth Catalysts
- FAA Part 25 Damage Tolerance Standards:Updated airworthiness requirements for bonded structures are compelling OEMs to adopt qualified OOA materials with established traceability protocols, expanding addressable supply base.
- Thermoplastic Welding Compatibility:PEEK and PPS matrix systems enable fusion-bonded assembly without adhesive cure cycles, compressing wing box integration timelines for next-generation regional programs.
- United States Final Assembly Concentration:Active production lines in Kansas, Georgia, and Quebec sustain localized demand clusters where OOA panel suppliers co-locate technical support teams.
Market Restraints
- Carbon Fiber Prepreg Input Volatility:Aerospace-grade tow pricing fluctuates with energy-intensive PAN precursor costs, squeezing margin predictability for OOA panel converters.
- Single-Source Qualification Risk:FAA-approved resin-fiber combinations often lock OEMs into sole-qualified suppliers, creating vulnerability if primary producers face capacity constraints.
- Autoclave-Grade Property Gap:OOA laminates achieve 90-95% of autoclave mechanical performance, limiting substitution in the most highly loaded wing skin applications.
Strategic Opportunities
- Brazilian Regional Jet Programs:Embraer's E2 family production in São José dos Campos offers untapped OOA panel penetration where local content incentives intersect with weight reduction targets.
- EU Green Deal Aviation Decarbonization:Manufacturing energy intensity mandates favor low-temperature cure chemistries that slash per-kilogram processing emissions versus autoclave cycles.
- Digital Thread Integration:Convergence of automated fiber placement with real-time cure monitoring is digitizing quality assurance, reducing manual inspection labor in panel production.
Industry Challenges
- Bonded Structure NDT Technician Scarcity:Ultrasonic and shearography inspection expertise for OOA laminates remains concentrated among legacy autoclave-qualified personnel, constraining workforce scaling.
- Full-Scale Structural Test Timeline Compression:FAA certification protocols require multi-year fatigue and damage tolerance campaigns that delay program revenue recognition despite panel delivery readiness.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Out-of-Autoclave Composite Skin Panels for Regional and Business Jets Market |
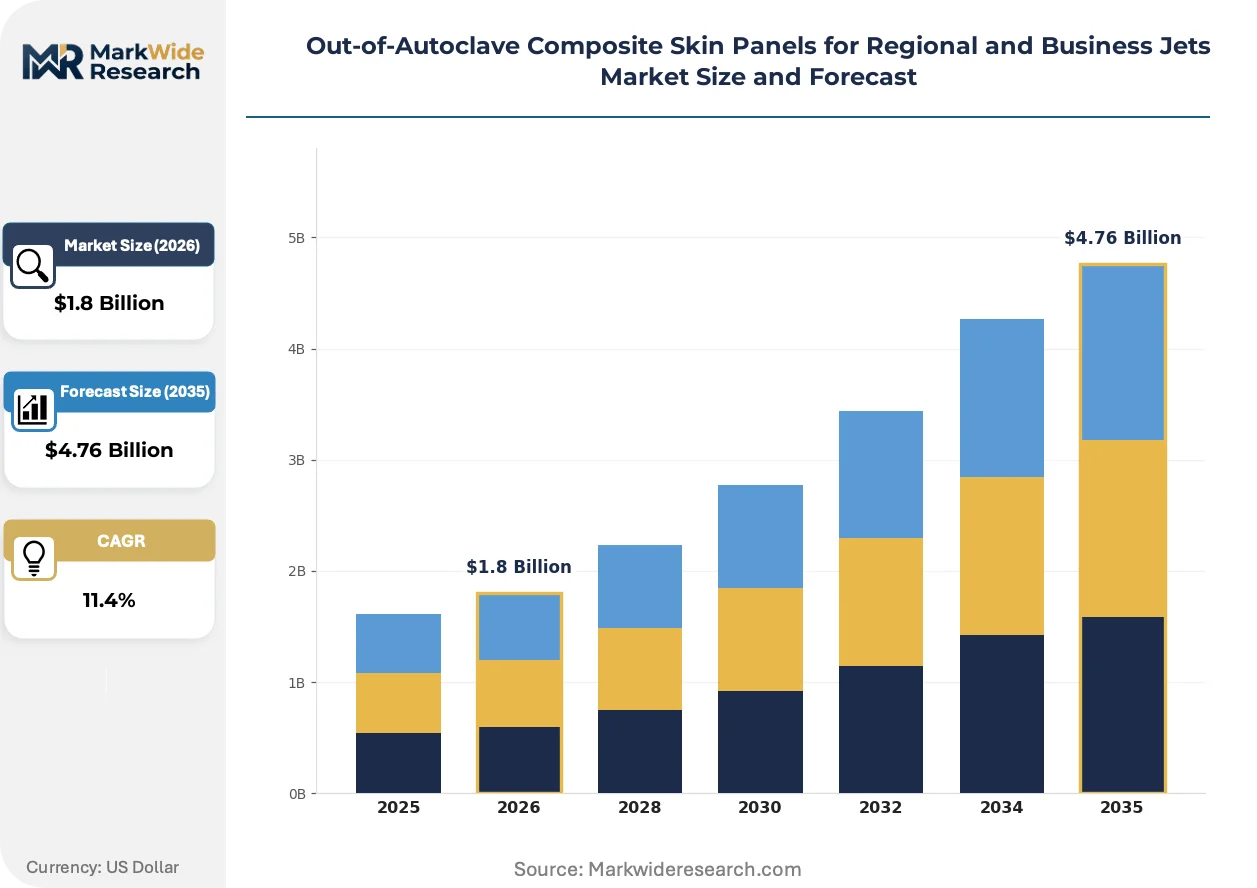
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Carbon Fiber, Fiberglass, Aramid Fiber, Hybrid Composites, Thermoplastic Composites Application: Fuselage Panels, Wing Skin, Tail Cone, Engine Nacelle, Cabin Interior Panels End User: Aircraft Manufacturers, Maintenance Providers, Aero-Structure Assemblers, Retrofitters, Design Engineers Manufacturing Stage: Lamination, Curing, Trimming, Inspection, Surface Finishing |
| Companies Covered | Airbus, Boeing, Collins Aerospace, GKN Aerospace, Spirit AeroSystems, FACC, Dassault Aviation, Embraer, Hexcel, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Out-of-Autoclave Composite Skin Panels for Regional and Business Jets Market Trends and Innovations
Process automation and regulatory digitization are converging to reshape how OOA composite skin panels qualify for bonded primary structures, compressing development cycles while elevating data integrity requirements.
Automated fiber placement with in-situ thermoplastic consolidation is digitizing layup accuracy and eliminating secondary debulking steps. Business jet OEMs in Wichita and Savannah are piloting these systems for fuselage barrel sections, enabling real-time ply orientation verification that reduces manual rework and accelerates first-article approval timelines.
EASA's evolving CS-25 certification framework for damage tolerance is mandating enhanced material traceability through digital birth certificates. European panel suppliers must now embed RFID-enabled resin batch records that follow components from prepreg freezer to final assembly, increasing compliance costs but creating audit-ready documentation that speeds regulatory approval.
Power-by-the-hour maintenance contracts are restructuring procurement toward total cost-per-flight-hour agreements rather than unit panel pricing. Lessors and fleet operators in the United States are consolidating purchasing authority, forcing Tier-1 aerostructure suppliers to absorb inventory risk and guarantee replacement panel availability under compressed lead times.
Out-of-Autoclave Composite Skin Panels for Regional and Business Jets Market Segmentation
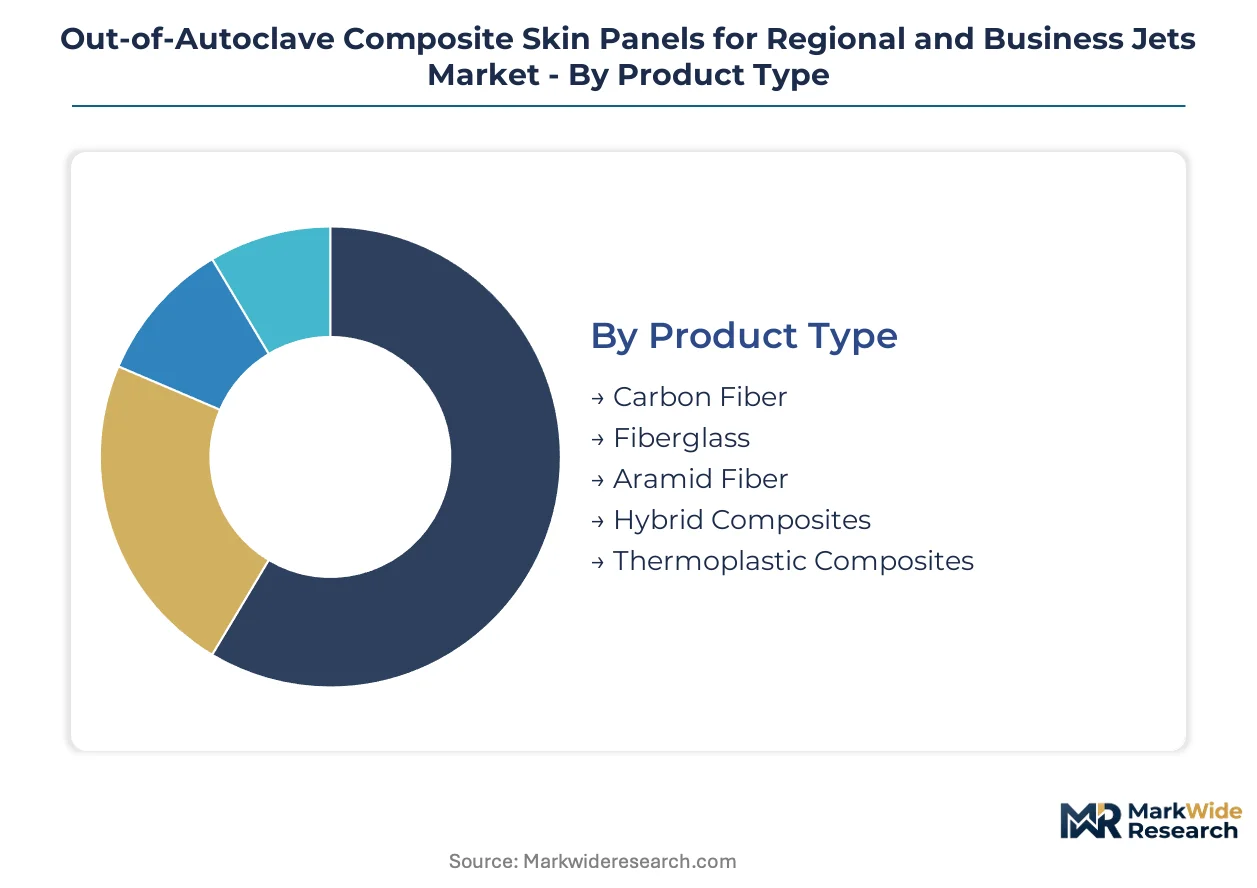
OOA composite skin panels serve distinct functional roles across regional and business jet platforms, with material selection and manufacturing stage specialization determining qualification pathways and procurement economics. Segmentation reveals where technical differentiation creates pricing power versus where standardization drives volume concentration.
Product Type:
Cost tier stratification separates premium aerospace-grade reinforcements from emerging thermoplastic alternatives competing on processing efficiency.
- Carbon Fiber:PAN-based tows with intermediate modulus ratings dominate fuselage applications where specific stiffness requirements exceed 100 GPa/(g/cm³). Wichita and Savannah assembly lines specify Toray T800H-equivalent grades for pressure-bearing barrel sections.
- Thermoplastic Composites:PEEK and PPS matrices enable welding-compatible consolidation without adhesive cure cycles, compressing wing box integration timelines. EU Green Deal manufacturing energy mandates accelerate qualification.
- Hybrid Composites:Carbon-glass combinations balance cost and performance in tail cone assemblies.
- Aramid Fiber:Kevlar-reinforced laminates serve impact-critical nacelle applications.
- Fiberglass:E-glass variants occupy non-structural interior panels and cost-sensitive regional jet programs.
Carbon fiber commands the established base. The steepest expansion runs through thermoplastic composites.
Application:
Structural load intensity governs material qualification depth and supplier certification requirements across aerodynamic surfaces.
- Fuselage Panels:Cylindrical barrel sections carry pressurization loads requiring damage tolerance validation per FAA Part 25. Textron Aviation and Gulfstream programs in Kansas and Georgia specify toughened epoxy OOA systems with established traceability protocols.
- Wing Skin:Highly loaded upper and lower surfaces demand 90-95% autoclave-grade mechanical properties, limiting OOA substitution to mid-size business jets below maximum takeoff weight thresholds.
- Tail Cone:Moderate load paths accommodate hybrid composite cost optimization.
- Engine Nacelle:Acoustic and thermal requirements drive aramid-carbon hybrids.
- Cabin Interior Panels:Fire-smoke-toxicity regulations from FAA and EASA constrain resin selection.
Fuselage applications absorb the dominant share of qualified supplier capacity. Wing skin represents the highest technical barrier for OOA penetration.
End User:
Customer type determines contract structure, with OEM direct procurement favoring long-term qualification investments versus aftermarket spot purchasing.
- Aircraft Manufacturers:Bombardier, Gulfstream, and Embraer maintain approved supplier lists requiring full-scale structural test documentation.
- Aero-Structure Assemblers:Tier-1 suppliers like Spirit AeroSystems consolidate panel sourcing across multiple OEM programs.
- Maintenance Providers:MRO facilities in the United States face bonded structure NDT technician scarcity.
- Retrofitters:Cabin reconfiguration specialists source interior-grade panels with reduced certification burden.
- Design Engineers:Consultancy-driven specification influences early program material selection.
Aircraft manufacturers anchor procurement volume. Aero-structure assemblers are gaining purchasing authority through power-by-the-hour contract consolidation.
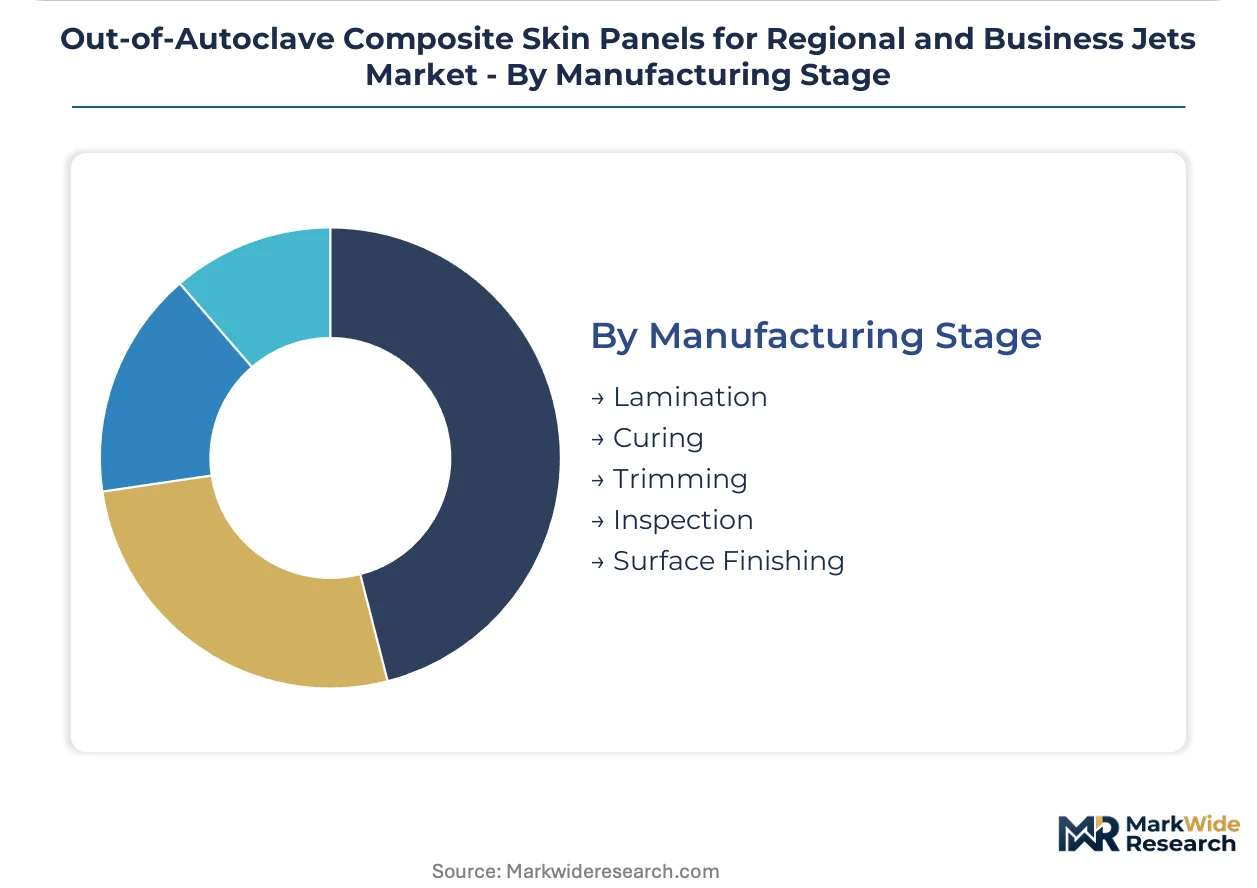
Manufacturing Stage:
Process step specialization separates capital-intensive prepreg conversion from labor-dependent finishing operations.
- Lamination:Automated fiber placement systems with real-time ply verification reduce manual rework in Wichita and Savannah facilities.
- Curing:Vacuum-bag-only ovens below 180°C eliminate nitrogen infrastructure while achieving target glass transition temperatures.
- Trimming:Five-axis CNC routing of cured laminates requires specialized dust containment for carbon fiber particulate.
- Inspection:Ultrasonic and shearography protocols follow EASA CS-25 damage tolerance frameworks.
- Surface Finishing:Paint-ready surfacing films and lightning strike protection layers complete panel deliverables.
Curing operations concentrate the highest capital deployment. Inspection represents the primary throughput constraint as qualified technician availability lags demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Business jet OEMs and regional aircraft manufacturers concentrate procurement authority among final assembly lines in the United States, Brazil, and select European aerospace clusters. FAA Part 25 and EASA CS-25 certification requirements shape supplier qualification investments across these geographies.
United States
Textron Aviation in Wichita and Gulfstream in Savannah drive qualified OOA panel demand for light and mid-size business jet programs. FAA airworthiness standards for bonded primary structures require full-scale structural test documentation from approved suppliers. Kansas and Georgia assembly corridors sustain localized technical support teams from Tier-1 aerostructure suppliers.
Brazil
Embraer's E2 family production in São José dos Campos creates untapped penetration potential where local content incentives intersect with weight reduction targets. ANVISA-equivalent aerospace material regulations align with FAA damage tolerance frameworks for bonded structures. São Paulo state's aerospace cluster attracts OOA panel suppliers seeking proximity to regional jet final assembly.
United Kingdom
GKN Aerospace anchors European OOA capacity through its Bristol process center serving Airbus and Bombardier programs. EASA CS-25 certification requirements mandate enhanced material traceability through digital birth certificates. The Southwest England aerospace corridor concentrates thermoplastic composite welding expertise for next-generation wing box applications.
Germany
Airbus Defence and Space and Premium AEROTEC facilities in Bavaria and Hamburg drive demand for low-temperature cure chemistries. EU Green Deal aviation decarbonization targets pressure OEMs to cut manufacturing energy intensity per kilogram of structure. Munich process centers specialize in automated fiber placement systems with real-time cure monitoring.
Canada
Bombardier's Challenger and Global series production in Quebec sustains demand for toughened epoxy OOA systems with established traceability protocols. Transport Canada airworthiness standards mirror FAA Part 25 damage tolerance requirements for bonded primary structures. Montreal's aerospace cluster concentrates MRO facilities facing bonded structure NDT technician scarcity.
Out-of-Autoclave Composite Skin Panels for Regional and Business Jets Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a tiered supplier base where qualification investments create durable switching costs. Tier-1 aerostructure assemblers consolidate purchasing authority through power-by-the-hour contracts, while material suppliers compete on resin-fiber combination certification depth. Three archetypes dominate: integrated airframe manufacturers with captive composite capabilities, independent Tier-1 aerostructure suppliers, and specialized prepreg formulators. Competitive moves concentrate on strategic partnerships for thermoplastic welding qualification and backward integration into automated fiber placement systems.
Among integrated airframe manufacturers, Airbus and Boeing exemplify channel control through captive supply chain authority over qualified material specifications. Within the independent Tier-1 tier, GKN Aerospace and Spirit AeroSystems occupy positions where process center investments in Bristol, Munich, Wichita, and Kinston anchor regional OOA capacity. Specialized prepreg formulators include Hexcel, whose toughened epoxy formulations represent the chemistry-centric competitive vector where out-time and tack life at room temperature cure determine procurement decisions.
| Leading Market Players |
|---|
| Airbus |
| Boeing |
| Collins Aerospace |
| GKN Aerospace |
| Spirit AeroSystems |
| FACC |
| Dassault Aviation |
| Embraer |
| Hexcel |
| Others |
Pricing and Supply Chain Analysis
Wichita-Savannah freight corridors carry aerospace-grade prepreg from Hexcel facilities in Colorado and Utah to Kansas and Georgia final assembly lines, with logistics costs amplifying the pricing power of qualified suppliers while compressing margins for converters lacking FAA-approved resin-fiber combinations.
Pricing Analysis
Cost-plus contracts with aerospace-grade carbon fiber tow indexation dominate procurement between Tier-1 assemblers and qualified panel suppliers. Three-tier pricing structure across aerospace-certified, industrial-grade, and developmental material levels separates damage-tolerant fuselage laminates from tail cone hybrids and experimental thermoplastic formulations. Cost compression in industrial-grade segments is intensifying because Brazilian and Chinese converters are qualifying lower-modulus fiber alternatives. Regional jet OEMs exhibit highest price sensitivity due to thin program margins, while Gulfstream and Bombardier business jet divisions absorb premiums for established traceability protocols.
Supply Chain Analysis
Contract manufacturing for OOA panel finishing concentrates at Spirit AeroSystems facilities in Kinston and GKN Aerospace process centers in Bristol and Munich. Aerospace-grade PAN precursor draws from Japan, the United States, and Germany, while toughened epoxy resin formulations rest on Huntsman and Solvay supply commitments. Single-source vulnerability pervades FAA-qualified resin-fiber combinations, where OEM lock-in creates catastrophic disruption risk if primary producers face capacity constraints. Distribution runs through Tier-1 aerostructure assemblers consolidating purchasing authority across multiple OEM programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is recovering from cyclical lows in business jet deliveries, with FAA certification backlogs clearing and pre-owned inventory absorption restoring OEM production rates.
For Market Incumbents: Build certification moats around thermoplastic welding standards for next-generation regional jet wing boxes. Deepen backward integration into automated fiber placement systems to capture capital equipment savings that Spirit AeroSystems has demonstrated. Anchor capacity in São José dos Campos to intercept Embraer's E2 supply chain localization mandates before competitors qualify alternative panel sources.
For New Entrants and Emerging Players: Establish a beachhead in Brazilian regional jet programs where ANVISA-aligned regulations create lower qualification barriers than FAA Part 25 direct entry. Target thermoplastic composite welding equipment supply as the most penetrable segment, serving GKN Aerospace and Premium AEROTEC process centers with fusion-bonding quality assurance systems. Pursue power-by-the-hour maintenance contract partnerships with lessors seeking alternative panel sources under compressed lead time guarantees.
For Investors and Strategic Acquirers: Specialized prepreg formulators with established FAA damage tolerance test documentation represent the most defensible acquisition archetype. Long-term viability hinges on thermoplastic matrix qualification velocity over the next decade as EU Green Deal manufacturing energy mandates accelerate chemistry transitions. Watch for ISO/ASTM thermoplastic welding standard finalization as the inflection signal that will displace mechanical fastening in regional jet primary structures.
| Strategic Initiative | Industry Significance |
|---|---|
| Thermoplastic Welding Qualification | PEEK and PPS matrix certification enables fusion-bonded wing box assembly without adhesive cure cycles. |
| Automated Fiber Placement Investment | Real-time ply verification systems in Wichita and Savannah facilities reduce manual rework and accelerate first-article approvals. |
| Brazilian Supply Chain Localization | São José dos Campos proximity captures Embraer E2 local content incentives intersecting with weight reduction targets. |
| Digital Birth Certificate Implementation | RFID-enabled resin batch records satisfy EASA CS-25 traceability mandates while creating audit-ready documentation. |
| Power-by-the-Hour Contract Restructuring | Total cost-per-flight-hour agreements shift inventory risk from lessors to Tier-1 aerostructure suppliers. |
Research Methodology
Operator-level perspectives from composite manufacturing engineers, FAA certification specialists, Tier-1 aerostructure procurement directors, and MRO facility maintenance managers anchored the qualitative base. Primary interview findings triangulated against secondary sources including FAA Part 25 airworthiness directives, EASA CS-25 certification frameworks, EU Green Deal aviation decarbonization policy documents, and customs records of aerospace-grade carbon fiber tow trade flows. Bottom-up panel production estimates across Wichita, Savannah, São José dos Campos, Bristol, and Munich facilities converged with top-down OEM delivery forecasts.
Scenario-bracketing framed low, baseline, and high cases across the projection horizon, with CAGRs derived from regression analysis of historical business jet delivery cycles and regional jet order backlogs. Segmentation modeling incorporated product type stratification by fiber reinforcement, application intensity by structural load requirements, end-user contract structure, and manufacturing stage capital deployment. Industry-specific inputs included PAN precursor pricing volatility indices and thermoplastic welding standard development timelines from ISO and ASTM technical committees.
Stress conditions across carbon fiber input cost spikes, FAA certification timeline extensions, and Brazilian real exchange rate volatility were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect assumptions about continued EASA and FAA regulatory alignment on bonded primary structure standards. Quarterly review of thermoplastic welding qualification progress and OEM power-by-the-hour contract penetration rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aerospace and Aircraft Materials
Aircraft Aluminium Plate Market
Aerospace and Aircraft Materials
3D Printing for Aerospace Market
Aerospace and Aircraft Materials
Aerospace Fasteners Market
Aerospace and Aircraft Materials
Aircraft AFP and ATL Composites Market
Aerospace and Aircraft Materials
Global AFP/ATL Machines Market
Aerospace and Aircraft Materials
Aerospace Raw Materials Market
Aerospace and Aircraft Materials
Commercial Aircraft Materials Market
Aerospace and Aircraft Materials
Aerospace Materials Market
Aerospace and Aircraft Materials
Titanium Aerospace Forgings Market
Aerospace and Aircraft Materials
Aerospace Composites Market
Aerospace and Aircraft Materials
Global Aerospace Adhesives and Sealants Market
Aerospace and Aircraft Materials
Aerospace Composite Ducting Market
Aerospace and Aircraft Materials
Aerospace Plastics Market
Aerospace and Aircraft Materials
Aerospace Carbon Fiber Market
Aerospace and Aircraft Materials
Aerospace Coatings Market
Aerospace and Aircraft Materials
Advanced Materials for Flying Cars Market