
 Aircraft Fuel System Market | 2026-2036
Aircraft Fuel System Market Size, Share, and Industry Trends Forecast 2026-2036
Aircraft Fuel System Market Analysis
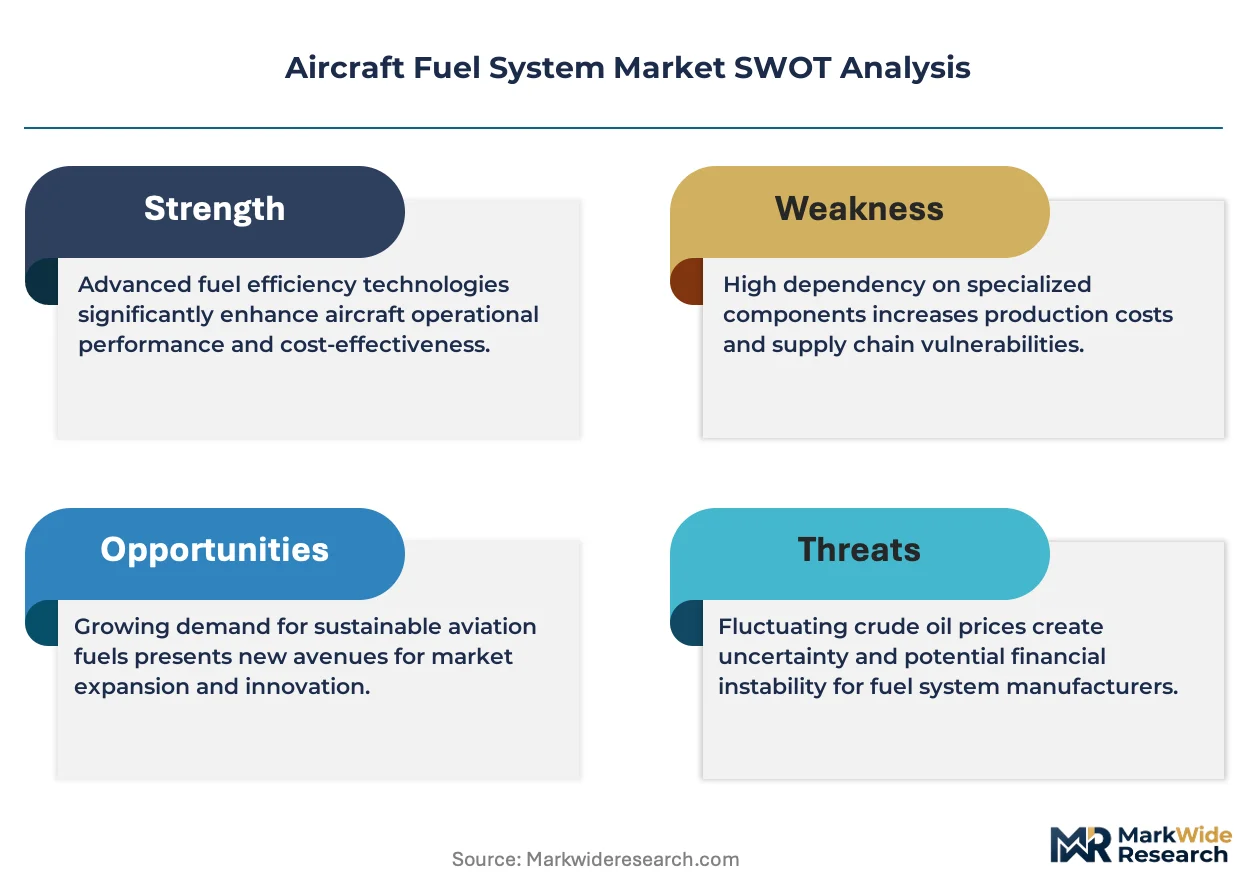
DO-160G environmental qualification standards for fuel system components is collapsing the gap between commercial and military-grade hardware. Parker-Hannifin Corporation leverages its integrated motion and control portfolio to anchor defense contracts across multiple NATO air forces. Eaton Corporation plc dominates fluid conveyance and engine fuel pump architectures for next-generation narrow-body platforms.
Aircraft fuel systems encompass the integrated network of pumps, valves, tubing, filters, and tanks that store, transfer, and deliver aviation fuel to propulsion systems under varying altitude, temperature, and gravitational conditions; these assemblies must maintain seal integrity at pressure differentials exceeding 50 psi and operate across temperature ranges from -65°F to 250°F. The primary purpose is to ensure uninterrupted fuel flow while preventing ignition hazards, microbial contamination, and structural fatigue during flight envelope extremes. Fuel pumps and fuel valves command the largest margin pools due to recurring overhaul cycles and precision machining requirements, while composite material adoption in fuel tanks accelerates as airframers pursue weight reduction targets. Fixed-wing aircraft applications sustain the dominant revenue share, though rotary-wing military modernization programs are expanding addressable scope for specialized in-flight refueling and crashworthy tank designs.
FAA airworthiness directives on fuel tank system ignition source prevention, EASA certification specifications for CS-25 transport category fuel systems, and EPA vapor recovery mandates collectively elevate engineering validation costs while screening out uncertified suppliers. Military aviation procurement through NAVAIR and Defense Logistics Agency imposes additional ITAR and MIL-STD-810G testing layers that favor incumbent producers with established compliance infrastructure. Stakeholders must monitor evolving sustainable aviation fuel compatibility standards, as alternative hydrocarbon blends impose new elastomer seal and coating material requirements across installed and new-build fleets.
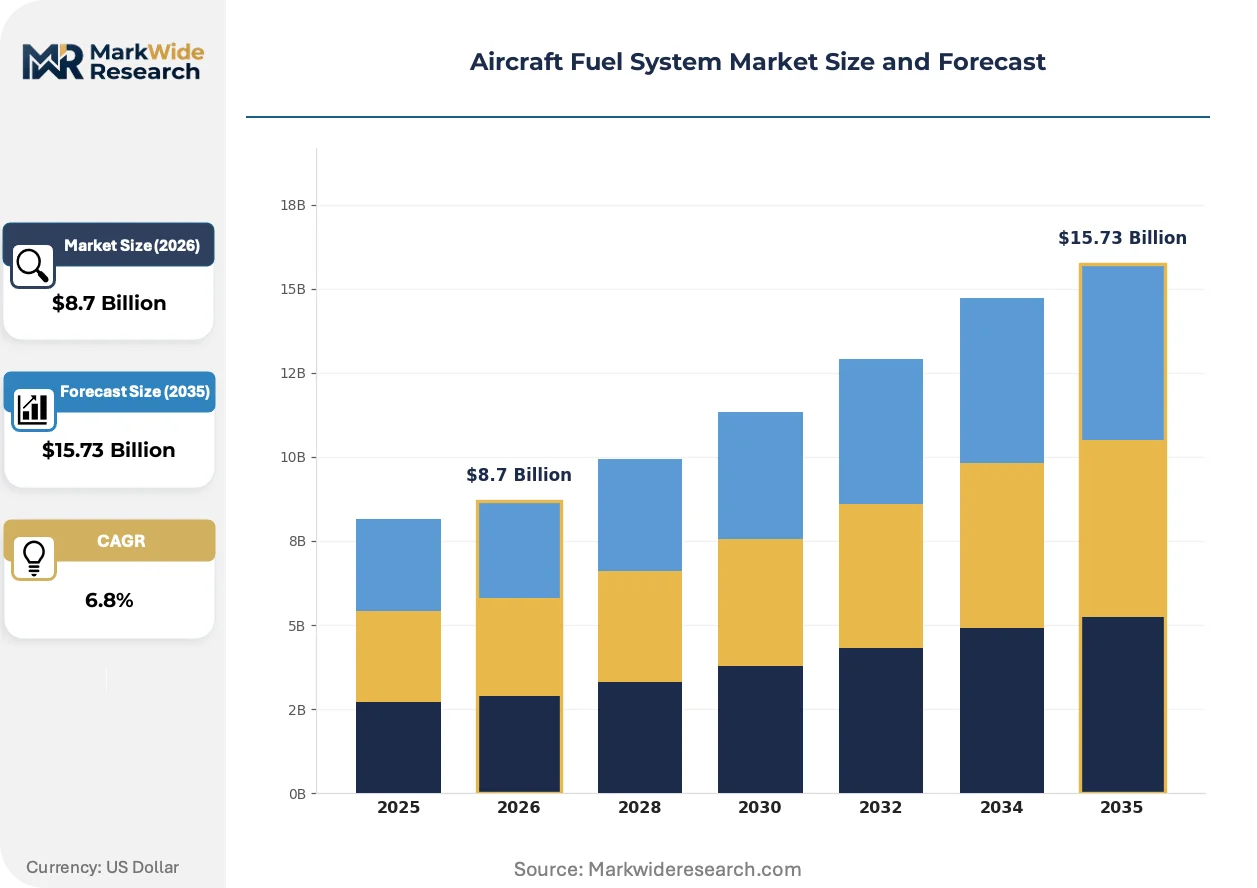
Market Dynamics
FAA airworthiness directives on fuel tank ignition source prevention are compressing supplier qualification timelines while elevating non-recurring engineering costs for component manufacturers serving both commercial and military platforms.
Growth Catalysts
- Narrow-body fleet renewal:Commercial operators in the United States are accelerating replacement schedules for aging single-aisle aircraft, creating sustained demand for integrated fuel system architectures.
- CS-25 certification specifications:EASA mandates on transport category fuel system integrity are pulling European suppliers toward higher-tier testing capabilities and documentation standards.
- Crashworthy tank technology:Military rotary-wing modernization programs are adopting self-sealing bladder systems and ballistic-tolerant designs for enhanced crew survivability.
Market Restraints
- Titanium and nickel alloy volatility:Precision-machined fuel pump housings and valve bodies face input cost pressure from aerospace-grade metal supply concentration in Russian and Chinese smelters.
- ITAR compliance infrastructure:Defense Logistics Agency procurement rules impose fixed-cost barriers that screen out suppliers lacking established export control legal frameworks and secure facility certifications.
- Sustainable aviation fuel compatibility gaps:Alternative hydrocarbon blends with elevated aromatic content degrade legacy elastomer seals, forcing premature replacement cycles and fleet-wide material recertification.
Strategic Opportunities
- India defense aviation expansion:Indigenous fighter programs and helicopter fleet upgrades under the Ministry of Defence's Make in India initiative are opening tender opportunities for foreign OEMs with local partnership structures.
- Urban air mobility fuel systems:Electric-hybrid and hydrogen-electric propulsion architectures for eVTOL platforms demand lightweight, high-pressure fuel storage and distribution solutions absent from incumbent product portfolios.
- EPA vapor recovery mandates:Ground service equipment and aircraft fueling infrastructure face tightening emission controls, creating retrofit demand for closed-system nozzles and vapor capture technologies.
Industry Challenges
- Systems integration engineering talent:Cross-functional expertise spanning fluid dynamics, electromagnetic compatibility, and composite material science remains scarce relative to program ramp rates.
- DO-160G test cycle duration:Environmental qualification for lightning indirect effects and electromagnetic interference consumes 14-18 months, compressing development windows for platform-specific customizations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aircraft Fuel System Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fuel Pumps, Fuel Filters, Fuel Tanks, Fuel Valves Material: Aluminum, Composite, Stainless Steel, Plastic End User: Commercial Aviation, Military Aviation, Cargo Carriers, OEMs Application: Fixed-Wing Aircraft, Rotary-Wing Aircraft, UAVs, Others |
| Companies Covered | Woodward, Inc., RTX Corporation, Eaton Corporation plc, Triumph Group Inc., GKN Aerospace Services Limited, Parker-Hannifin Corporation, Crane Aerospace & Electronics, Honeywell International Inc., Safran SA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aircraft Fuel System Market Emerging Trajectories
Additive manufacturing of titanium fuel system brackets and manifolds is collapsing lead times for low-volume military spares while introducing new non-destructive inspection protocols for porosity detection.
Conformable thermoplastic fuel tanks are fragmenting the traditional metallic tank supplier base by enabling complex geometry integration with wing box structures. Boeing and Airbus narrow-body programs are qualifying these designs for center wing box applications. The shift is fragmenting procurement patterns as airframers bypass legacy tank specialists in favor of composite aerostructures suppliers with automated fiber placement capabilities.
EU F-Gas Regulation phase-down schedules are pressuring manufacturers to eliminate sulfur hexafluoride from fuel system leak detection equipment. Industrial gas suppliers and MRO service providers are retrofitting existing test benches with helium mass spectrometry alternatives. European maintenance networks face the steepest compliance cost curves, accelerating equipment replacement cycles ahead of regulatory deadlines.
Airline technical procurement teams are consolidating vendor relationships around integrated fuel system module suppliers capable of single-source accountability for pumps, valves, and sensors. Component-level specialists without system integration capabilities are losing share to full-line providers. United States-based network carriers and low-cost operators are driving this consolidation most aggressively through long-term performance-based logistics contracts.
Aircraft Fuel System Market Segmentation
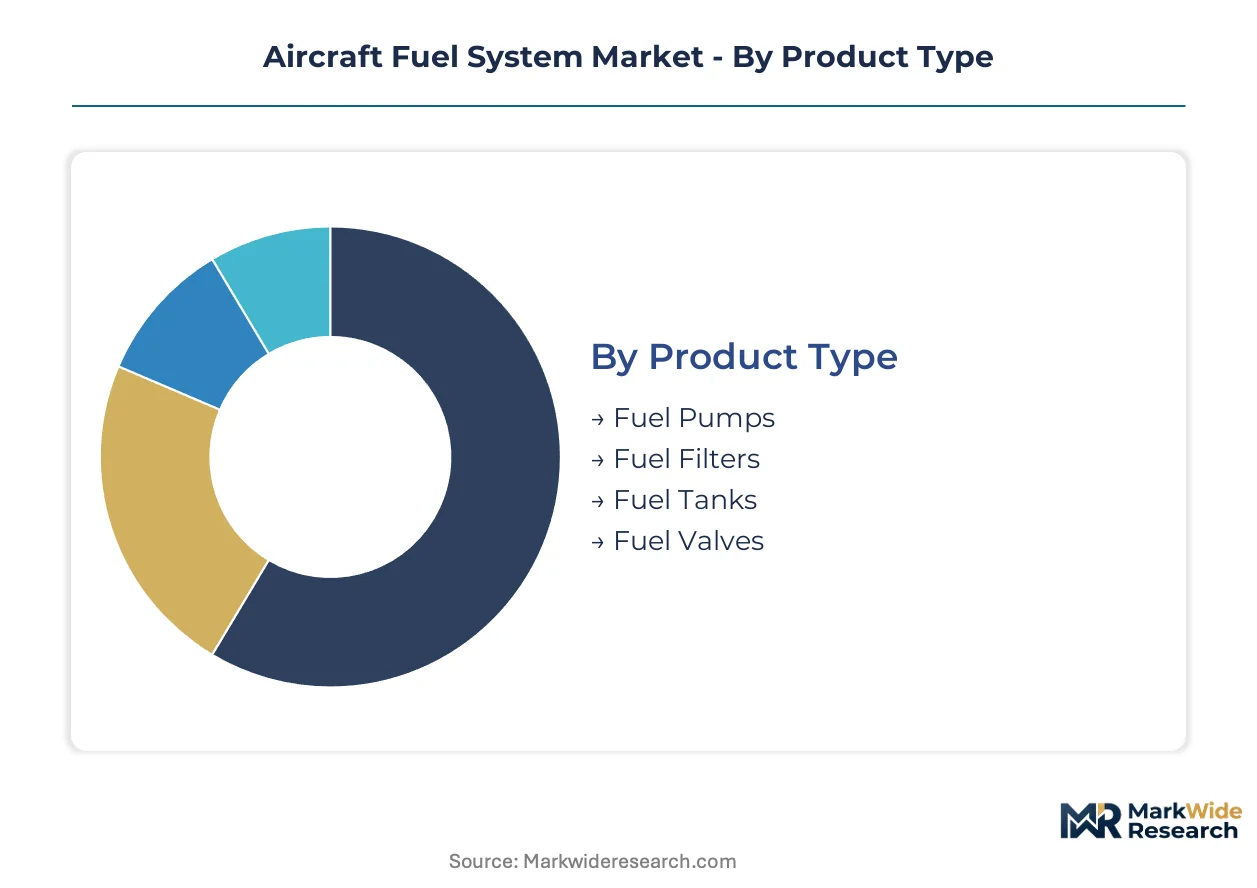
Segmentation in the aircraft fuel system market determines procurement channel access and aftermarket service bundling. Component-level specialists face consolidation pressure as airframers and MRO networks favor integrated module suppliers capable of single-source accountability across multiple product categories.
Product Type:
Channel strategy varies sharply by product complexity, with precision-machined components flowing through OEM direct contracts and consumable elements distributing via airline procurement consortia.
- Fuel Pumps:Precision-machined housings in titanium and nickel alloys deliver pressurized fuel flow across altitude differentials exceeding 40,000 feet. Commercial narrow-body fleet renewals in the United States concentrate demand for next-generation engine-mounted pump architectures with integrated electronic controls.
- Fuel Valves:Electromechanical and pneumatic actuation systems manage fuel routing, shutoff, and cross-feed functions under FAA ignition source prevention mandates. Military rotary-wing programs are accelerating procurement of crashworthy valve designs with ballistic tolerance specifications.
- Fuel Filters:Microglass and sintered metal media remove particulate and water contamination from jet fuel streams.
- Fuel Tanks:Conformable thermoplastic and metallic bladder systems store fuel across wing box and fuselage cavities.
Fuel pumps dominate installed base. Fuel valves are where expansion concentrates.
Material:
Cost tier stratification separates premium aerospace alloys from commodity-grade alternatives, with certification requirements acting as the primary price differentiator.
- Composite:Carbon fiber-reinforced thermoplastics enable conformable tank geometries integrated directly with wing box structures. Boeing and Airbus narrow-body programs are qualifying these designs for center wing box applications, displacing legacy metallic tank specialists.
- Aluminum:2000 and 7000 series alloys provide fatigue-resistant structural tank skins and baffle assemblies with established repair protocols. United States-based MRO networks favor aluminum for retrofit programs where damage tolerance documentation is mature.
- Stainless Steel:Corrosion-resistant grades serve fuel line tubing and valve body applications in marine-environment operating profiles.
- Plastic:Engineered polymers in non-structural brackets and sensor housings reduce weight in non-critical fuel system zones.
Aluminum retains largest installed base. Composite is gaining share fastest.
End User:
Customer type determines contract structure, with military procurement imposing ITAR compliance barriers that screen out commercial-only suppliers.
- Commercial Aviation:Network carriers and low-cost operators drive integrated fuel system module procurement through long-term performance-based logistics contracts. United States airline technical teams are consolidating vendor relationships around full-line providers capable of single-source accountability.
- Military Aviation:Defense Logistics Agency and NAVAIR procurement channels demand MIL-STD-810G environmental qualification and ITAR-compliant facility infrastructure. NATO air force modernization programs concentrate demand for crashworthy tank and in-flight refueling system upgrades.
- Cargo Carriers:Dedicated freighter operators prioritize fuel system reliability metrics to maximize aircraft utilization rates.
- OEMs:Airframe and engine manufacturers source fuel system architectures for new-build platform integration.
Commercial aviation commands volume leadership. Military aviation shows steepest expansion trajectory.
Application:
Application scope dictates performance requirements, with rotary-wing and unmanned platforms demanding specialized solutions absent from fixed-wing product portfolios.
- Fixed-Wing Aircraft:Transport category fuel system architectures serve narrow-body, wide-body, and regional jet platforms under FAA and EASA certification specifications. Fleet renewal schedules for aging single-aisle aircraft sustain recurring demand for pump, valve, and tank replacements.
- Rotary-Wing Aircraft:Military helicopter modernization programs require self-sealing bladder systems and ballistic-tolerant tank designs for enhanced crew survivability. Crashworthy fuel system standards are tightening across NATO member state procurement specifications.
- UAVs:Unmanned platforms demand miniaturized fuel storage and distribution solutions with extended endurance profiles.
- Others:Specialized applications include aerial refueling tankers and experimental aircraft configurations.
Fixed-wing aircraft anchor revenue. Rotary-wing applications are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Commercial operators in the United States demonstrate the lowest price elasticity for integrated fuel system modules, while defense procurement across NATO member states tolerates premium pricing for crashworthy architectures. Asian carriers exhibit higher sensitivity to component-level sourcing costs.
United States
Boeing's 737 MAX production ramp and airline fleet renewal schedules concentrate demand for next-generation pump and valve architectures. FAA airworthiness directives on fuel tank ignition source prevention compress supplier qualification timelines for domestic manufacturers. The Seattle-Tacoma aerospace cluster anchors integrated fuel system engineering, with Parker-Hannifin and Eaton Corporation plc maintaining defense and commercial procurement relationships.
Germany
Airbus Hamburg final assembly lines pull European supply chains toward CS-25 certification specifications for transport category fuel systems. EASA mandates on lightning protection and electromagnetic compatibility elevate testing documentation requirements. The Hamburg-Nordenham corridor hosts specialized valve and sensor manufacturers serving A320 family production rates.
France
Safran's engine fuel pump architectures dominate narrow-body platform integration for LEAP-powered aircraft. French military aviation procurement through DGA imposes additional MIL-STD environmental qualification layers favoring incumbent producers. The Toulouse-Blagnac aerostructures ecosystem concentrates conformable thermoplastic fuel tank development for next-generation wing box applications.
United Kingdom
Rolls-Royce UltraFan development programs sustain demand for high-pressure fuel distribution components in Derby and Bristol engineering centers. UK Ministry of Defence helicopter modernization under the New Medium Helicopter program accelerates crashworthy tank procurement. GKN Aerospace's Bristol and Cowes facilities anchor composite fuel system manufacturing for fixed-wing and rotary-wing platforms.
India
Indigenous fighter programs under the Ministry of Defence's Make in India initiative open tender opportunities for foreign OEMs with local partnership structures. HAL's helicopter and light combat aircraft production creates demand for fuel system technology transfer agreements. The Bangalore-Hyderabad defense aviation corridor concentrates offset manufacturing requirements for international suppliers.
Aircraft Fuel System Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes across the aircraft fuel system market. Integrated motion and control specialists with established FAA and EASA certification infrastructure occupy premium positions, while component-level machinists compete on precision manufacturing scale. Three archetypes dominate: full-line system integrators, precision-machined component specialists, and composite aerostructures suppliers with automated fiber placement capabilities. Competitive moves center on long-term performance-based logistics contracts with network carriers and strategic partnerships for India defense offset requirements.
Within the full-line system integrator tier, Eaton Corporation plc and Parker-Hannifin Corporation exemplify archetypes capable of single-source accountability across pumps, valves, and sensors. Safran SA occupies a position representing European engine-integrated fuel system leadership. These three anchors demonstrate how geographic certification infrastructure and military procurement relationships create defensive moats against component-level competitors lacking system integration capabilities.
| Leading Market Players |
|---|
| Woodward, Inc. |
| RTX Corporation |
| Eaton Corporation plc |
| Triumph Group Inc. |
| GKN Aerospace Services Limited |
| Parker-Hannifin Corporation |
| Crane Aerospace & Electronics |
| Honeywell International Inc. |
| Safran SA |
| Others |
Supply Flow & Price Mechanics
FAA airworthiness directives on fuel tank ignition source prevention gate both supplier qualification timelines and price differentiation across component tiers simultaneously. Certification infrastructure investments function as fixed-cost barriers that compress margins for uncertified entrants while insulating incumbent full-line integrators from price competition.
Pricing Analysis
Aftermarket service contracts and recurring overhaul cycles drive lifetime value for precision-machined fuel pumps and valves. Three-tier pricing structure across premium, standard, and economy levels separates FAA-certified system integrators from component specialists and uncertified machinists. Price differentiation hinges on ITAR compliance infrastructure and DO-160G environmental qualification documentation. Cost compression in titanium and nickel alloy pump housings is intensifying because aerospace-grade metal supply concentrates in Russian and Chinese smelters. Cargo carriers exhibit highest price sensitivity due to utilization-maximization procurement mandates, while NATO defense programs tolerate premium pricing for crashworthy architectures.
Supply Chain Analysis
Titanium sponge processing capacity in Russia and China underwrites raw material availability for precision-machined fuel system housings. Manufacturing draws from United States, Germany, and France for final assembly of integrated pump and valve modules. Raw material dependencies include aerospace-grade titanium alloys, nickel-based superalloys, and carbon fiber-reinforced thermoplastics for conformable tanks. Single-source vulnerability concentrates in Russian titanium sponge exports subject to sanctions exposure. Distribution runs through OEM direct contracts for new-build platforms and airline procurement consortia for aftermarket consumables.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in a cyclical recovery phase. Narrow-body fleet renewal schedules at United States network carriers and low-cost operators provide the demand inflection.
For Market Incumbents: Shield certification infrastructure investments from margin erosion by locking long-term performance-based logistics contracts with United States network carriers. Deepen backward integration into titanium alloy supply through captive sourcing agreements with alternative smelters outside sanctioned jurisdictions. Prioritize MIL-STD-810G environmental qualification expansion to capture NATO rotary-wing modernization programs.
For New Entrants and Emerging Players: Lead with conformable thermoplastic fuel tank fabrication capabilities targeting Boeing and Airbus narrow-body center wing box applications. Penetrate the India defense aviation corridor through technology transfer partnerships with HAL under Make in India offset requirements. Anchor go-to-market strategy around automated fiber placement competencies that legacy metallic tank suppliers lack.
For Investors and Strategic Acquirers: EPA vapor recovery mandate implementation reshapes the acquisition landscape for ground service equipment retrofit specialists. Five-to-ten year viability favors full-line system integrators with established FAA and EASA certification infrastructure over component-level machinists. Target acquisition archetype: composite aerostructures suppliers with automated fiber placement capabilities entering fuel system adjacent markets. Watch sustainable aviation fuel compatibility recertification cycles as inflection indicator for elastomer seal replacement demand.
| Strategic Initiative | Industry Significance |
|---|---|
| ITAR Compliance Infrastructure Expansion | Defense Logistics Agency procurement rules screen out suppliers lacking secure facility certifications. |
| Conformable Thermoplastic Tank Qualification | Boeing and Airbus narrow-body programs displace legacy metallic tank specialists with composite integration. |
| Performance-Based Logistics Contracts | United States network carriers consolidate vendor relationships around single-source accountability providers. |
| Sustainable Aviation Fuel Compatibility Testing | Alternative hydrocarbon blends force premature elastomer seal replacement cycles across installed fleets. |
| India Defense Offset Partnership Structure | Ministry of Defence's Make in India initiative mandates local manufacturing for foreign OEM tender access. |
Methodological Framework
Cross-validation between primary interviews with industry stakeholders and secondary regulatory filings anchors the qualitative findings. This study combined discussions with fuel system engineering directors, airline technical procurement managers, MRO aftermarket heads, and defense logistics procurement officers at NAVAIR and the Defense Logistics Agency. Secondary validation drew from FAA airworthiness directive databases, EASA certification specifications, SEC 10-K filings of listed aerospace suppliers, and customs trade data for titanium alloy imports. Bottom-up segment sizing triangulated against top-down market aggregation across component categories.
Sensitivity analysis around titanium price volatility and fleet renewal timing assumptions tested forecast robustness. The analytical framework modeled segmentation across product type, material grade, end-user category, and application platform throughout the projection horizon. CAGRs derived from regression analysis of historical production rates against announced OEM delivery schedules. Industry-specific inputs included Boeing 737 MAX production ramp trajectories and Airbus A320 family output planning.
The analysis sits within stated boundaries; outcomes outside sustained narrow-body fleet renewal velocity or escalated sanctions on titanium supply would require recalibration. Forecasts reflect documented assumptions regarding certification timeline compression and sustainable aviation fuel blend penetration. Revision becomes warranted when EPA vapor recovery mandate enforcement crosses implementation thresholds or when India defense offset requirements shift localization percentages.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Fuel Systems
Aerospace and Defense Fuel Market
Aircraft Fuel Systems
Jet Fuel Market
Aircraft Fuel Systems
Aircraft Refueler Market
Aircraft Fuel Systems
Asia-Pacific Aviation Fuel Market
Aircraft Fuel Systems
Refueling Aircraft Market
Aircraft Fuel Systems
Hydrogen Aircraft Market
Aircraft Fuel Systems
Global Aircraft Pumps Market
Aircraft Fuel Systems
North America Renewable Aviation Fuel Market
Aircraft Fuel Systems
Military Jet Fuel Market
Aircraft Fuel Systems
Aircraft Refueling Hose Market
Aircraft Fuel Systems
Middle-East and Africa Aviation Fuel Market
Aircraft Fuel Systems
Aviation Gasoline (Avgas) Market
Aircraft Fuel Systems
Aerospace Fluid Conveyance System Market
Aircraft Fuel Systems
Fuel Tank Inerting Systems Market
Aircraft Fuel Systems
Global Aircraft Fuel Tanks Market
Aircraft Fuel Systems
Aerial Refueling Systems Market