
 Military Aircraft Market | 2026-2036
Military Aircraft Market Size, Share, and Industry Trends Forecast 2026-2036
Military Aircraft Market Intelligence
Aftermarket service revenue is tilting toward platform sustainment and life-extension programs as original equipment margins compress. Lockheed Martin leverages its vertical integration across avionics and stealth coatings to capture recurring modernization contracts. Boeing sustains broad manufacturing scale across strategic bombers and tanker derivatives, while Northrop Grumman specializes in unmanned systems and electronic warfare payloads.
Military aircraft encompass fixed-wing and rotary-wing platforms engineered for defense missions, typically featuring reinforced airframes, advanced radar-absorbing materials, and thrust-to-weight ratios exceeding unity for combat maneuverability; these systems serve national security objectives spanning air superiority, strategic deterrence, and tactical mobility. Fighter jets anchor procurement budgets across major defense ministries, reflecting sustained investment in stealth and sensor fusion architectures. Unmanned Combat Aerial Vehicles represent the fastest-expanding segment as autonomous targeting algorithms mature and operator-risk tolerance shifts. Transport aircraft occupy a mature but stable position where turboprop variants compete for intra-theater logistics against turbofan strategic lift platforms.
The FAA and EASA shape civilian-airspace integration standards for military platforms operating in dual-use corridors, while national procurement offices enforce country-specific technical requirements that fragment supplier qualification pathways. Defense export controls under ITAR and analogous European regimes restrict technology transfer and segment market access for non-allied nations. Stakeholders must monitor how sixth-generation development programs and open-architecture avionics standards reshape supplier hierarchies and platform upgrade economics.
Market Dynamics
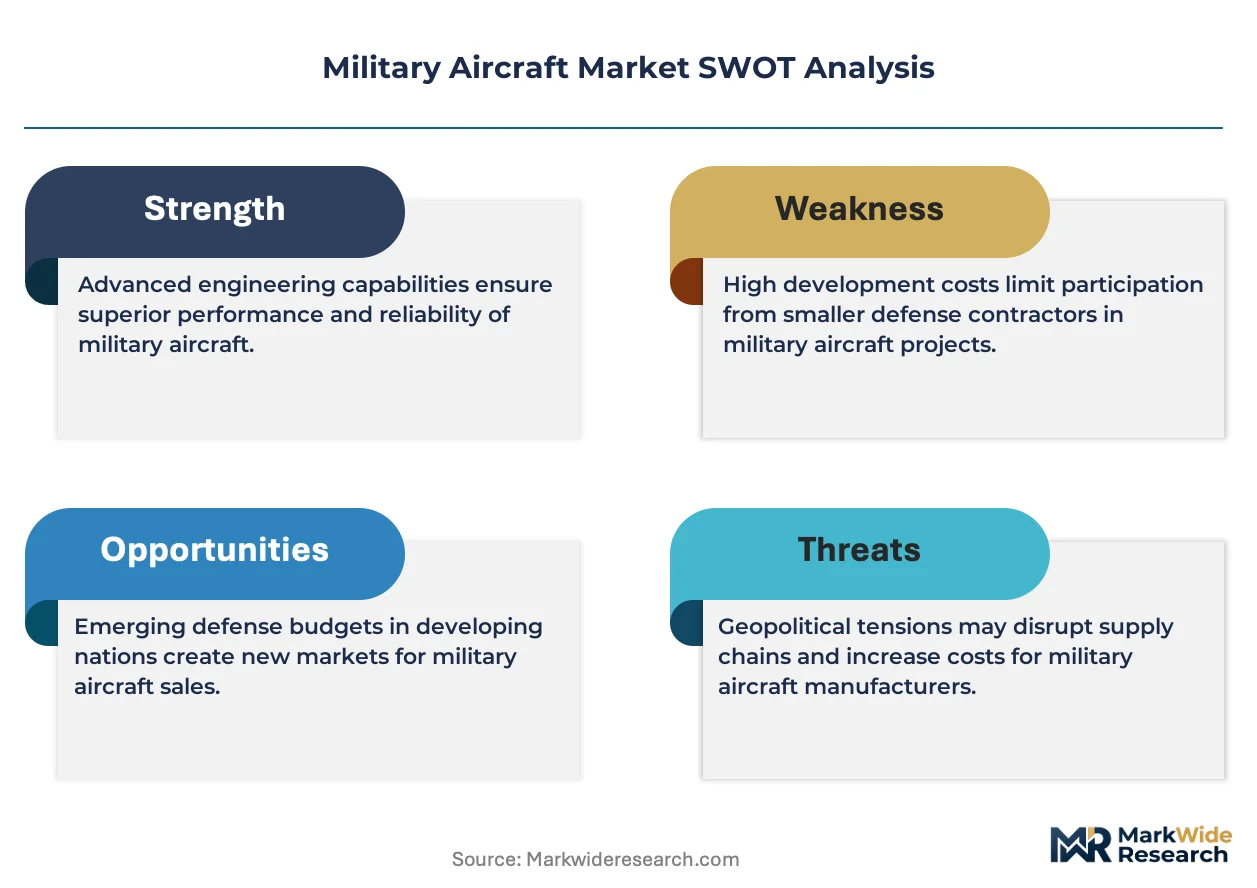
Defense procurement offices are consolidating platform architectures around open-system standards that fragment traditional supplier hierarchies and compress upgrade cycles for legacy fleets.
Growth Catalysts
- Sensor Fusion Architectures:Multi-spectral targeting pods and distributed aperture systems are pulling R&D investment toward avionics-integrated platforms. NATO airworthiness directives are accelerating fleet-wide retrofit mandates.
- Indo-Pacific Theater Buildup:Territorial surveillance requirements across littoral zones are expanding maritime patrol and airborne early-warning procurement. Island-chain defense postures favor long-endurance platforms with reduced radar cross-section.
- Autonomous Wingman Programs:Loyal unmanned platforms operating alongside crewed fighters are reshaping force-structure planning. Manned-unmanned teaming algorithms are maturing through DARPA and national defense lab pipelines.
Market Restraints
- Titanium and Superalloy Concentration:Russian and Chinese dominance in sponge titanium and nickel-based superalloy refining creates input vulnerability. Western defense ministries are stockpiling strategic materials under national security frameworks.
- ITAR Compliance Friction:US export control regimes restrict subsystem transfer to non-allied nations, segmenting addressable demand pools. License approval timelines extend platform delivery schedules by 18-36 months.
- Stealth Coating Technical Limitations:Radar-absorbent material durability under sustained supersonic flight remains below operational thresholds. Fleet availability rates suffer from frequent depot-level resurfacing cycles.
Strategic Opportunities
- Poland and Romania Defense Modernization:Former Soviet-bloc NATO members are replacing MiG and Sukhoi fleets with Western-compatible platforms. Offset agreements and local assembly clauses create industrial participation openings.
- Space-Layer Integration:Low-earth-orbit constellations are converging with airborne command nodes for beyond-line-of-sight targeting. JADC2 frameworks are mandating cross-domain data links as procurement requirements.
- Digital Twin Lifecycle Management:Physics-based modeling of airframe fatigue and avionics degradation is enabling predictive maintenance contracts. Performance-based logistics agreements are displacing traditional spare-part sales.
Industry Challenges
- Airworthiness Certification Bottlenecks:FAA and military type-certification backlogs for software-intensive flight control systems extend development timelines. DO-178C compliance for autonomous functions requires specialized verification engineering talent pools.
- Legacy Platform Integration Complexity:Fourth-generation fleets with proprietary bus architectures resist open-architecture retrofits. Middleware development for hybrid old-new system interoperability consumes disproportionate program resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Military Aircraft Market |
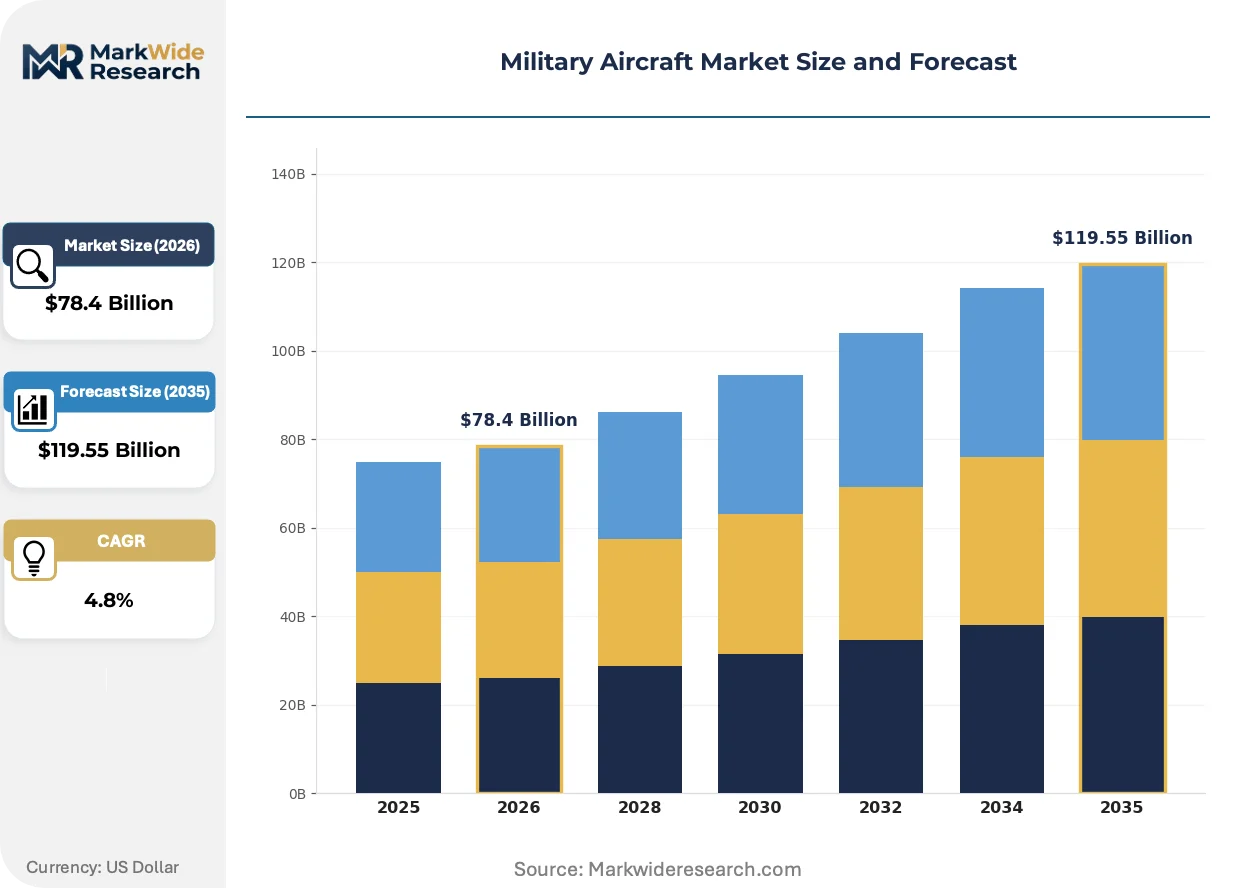
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $119.55 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Aircraft Type: Fighter Jets, Transport Aircraft, Reconnaissance Aircraft, Unmanned Combat Aerial Vehicles, Strategic Bombers Propulsion Type: Turbofan, Turbojet, Turboprop, Rocket, Hybrid Electric Application: Surveillance, Tactical Airlift, Electronic Warfare, Air Superiority, Ground Attack End User: Defense Forces, Naval Aviation Units, Airborne Early Warning Squadrons, Training Institutes |
| Companies Covered | Dassault Aviation, Airbus, Lockheed Martin, Textron Aviation, Embraer, Boeing, Hindustan Aeronautics, Sukhoi, Northrop Grumman, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Military Aircraft Market Strategic Shifts & Innovations
Adaptive cycle engines and directed-energy defensive systems are compressing traditional propulsion and countermeasure paradigms while reshaping platform design priorities across fighter and bomber categories.
Additive manufacturing of titanium structural nodes is collapsing lead times for low-volume, high-complexity airframe components. Tier-one suppliers are qualifying electron-beam and laser powder-bed processes for flight-critical parts. This fabrication shift is collapsing the economic rationale for consolidated forging facilities and enabling distributed, responsive supply configurations.
EU defense procurement directives under the European Defence Fund are mandating cross-border industrial participation and joint capability development. Member states must allocate 35% of collaborative program value to partners outside the lead nation. This regulatory architecture is fragmenting national champion structures and forcing consortium-based platform development.
Defense ministries are unbundling platform acquisition from through-life support, awarding sustainment contracts to third-party integrators independent of original manufacturers. Australia's AIR 7000 and UK's Team Tempest frameworks exemplify this disaggregation. Aftermarket service margins are concentrating with specialized MRO providers possessing airworthiness delegation authority.
Military Aircraft Market Segmentation
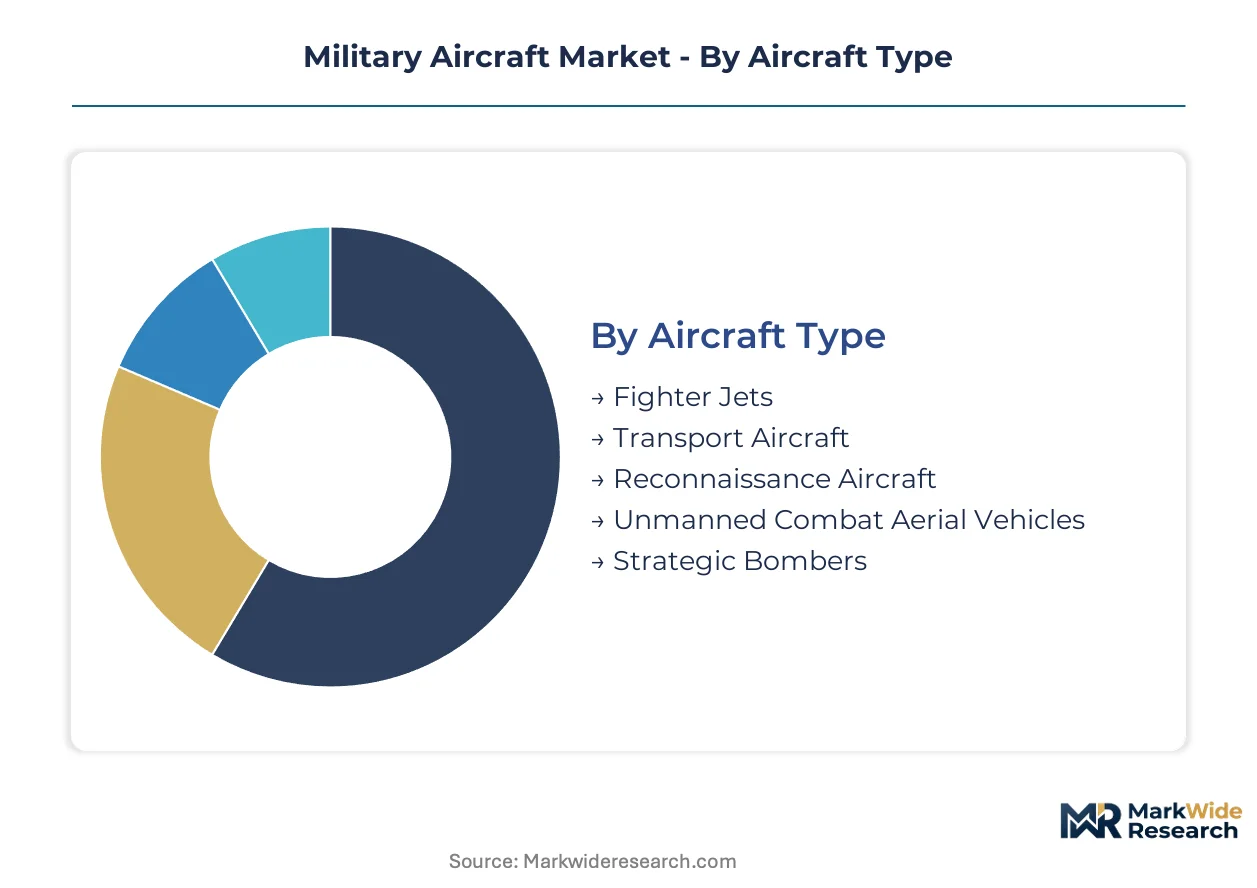
Military aircraft procurement patterns diverge sharply across mission profiles and operational envelopes, with platform selection driven by threat environment, basing infrastructure, and interoperability requirements within allied command structures. Understanding these segment boundaries illuminates where defense budgets concentrate and where technology transitions create supplier entry points.
Aircraft Type:
Fighter jets through strategic bombers span distinct use-case spectra from air dominance to nuclear deterrence, each demanding specialized airframe architectures and sustainment ecosystems.
- Fighter Jets:Crewed combat platforms integrate thrust-vectoring propulsion with low-observable shaping for contested airspace penetration. Demand clusters in NATO's eastern flank states replacing Soviet-era fleets, constrained by airworthiness certification backlogs for software-intensive flight control systems.
- Unmanned Combat Aerial Vehicles:Autonomous strike platforms operate at reduced radar cross-section with satellite-linked command architectures. Procurement accelerates in the Indo-Pacific theater where operator-risk tolerance shifts toward expendable assets for littoral surveillance missions.
- Transport Aircraft:Strategic and tactical lift platforms move personnel and materiel across theater distances.
- Reconnaissance Aircraft:Manned and unmanned platforms gather signals intelligence and imagery across contested borders.
- Strategic Bombers:Long-range nuclear-capable platforms provide deterrence through second-strike survivability.
The dominant share belongs to Fighter Jets, while Unmanned Combat Aerial Vehicles is closing the gap fastest.
Propulsion Type:
Engine architecture selection traces cost-performance tradeoffs across flight regimes, with thermal efficiency and specific thrust dictating platform economics.
- Turbofan:High-bypass engines deliver subsonic fuel efficiency for transport and tanker applications. Western defense ministries stockpile nickel-based superalloy reserves against Russian and Chinese refining dominance.
- Turbojet:Compact powerplants optimize supersonic thrust-to-weight ratios for interceptor and fighter missions. Demand concentrates in platforms requiring sustained Mach performance with minimal frontal area.
- Turboprop:Efficient low-altitude propulsion suits maritime patrol and intra-theater logistics.
- Rocket:Hypersonic boost-glide vehicles and experimental platforms require chemical propulsion.
- Hybrid Electric:Emerging architectures promise thermal management advantages for directed-energy weapons integration.
Turbofan systems command installed base volume, though Hybrid Electric configurations are expanding most quickly through experimental demonstrator programs.
Application:
Mission type determines sensor payload integration and rules of engagement, with electronic warfare and air superiority demanding the most sophisticated avionics suites.
- Surveillance:Persistent airborne platforms fuse electro-optical and synthetic aperture radar for border monitoring. Island-chain defense postures in the Indo-Pacific favor long-endurance airframes with reduced observability.
- Electronic Warfare:Specialized aircraft carry high-power jamming and signals intelligence payloads. NATO interoperability mandates are accelerating open-architecture retrofits for spectrum dominance.
- Tactical Airlift:Intra-theater logistics platforms operate from austere runways.
- Air Superiority:Fighter missions establish control over contested airspace.
- Ground Attack:Close air support platforms deliver precision munitions against surface targets.
Surveillance holds the largest committed program of record, while Electronic Warfare is gaining share fastest through JADC2 integration requirements.
End User:
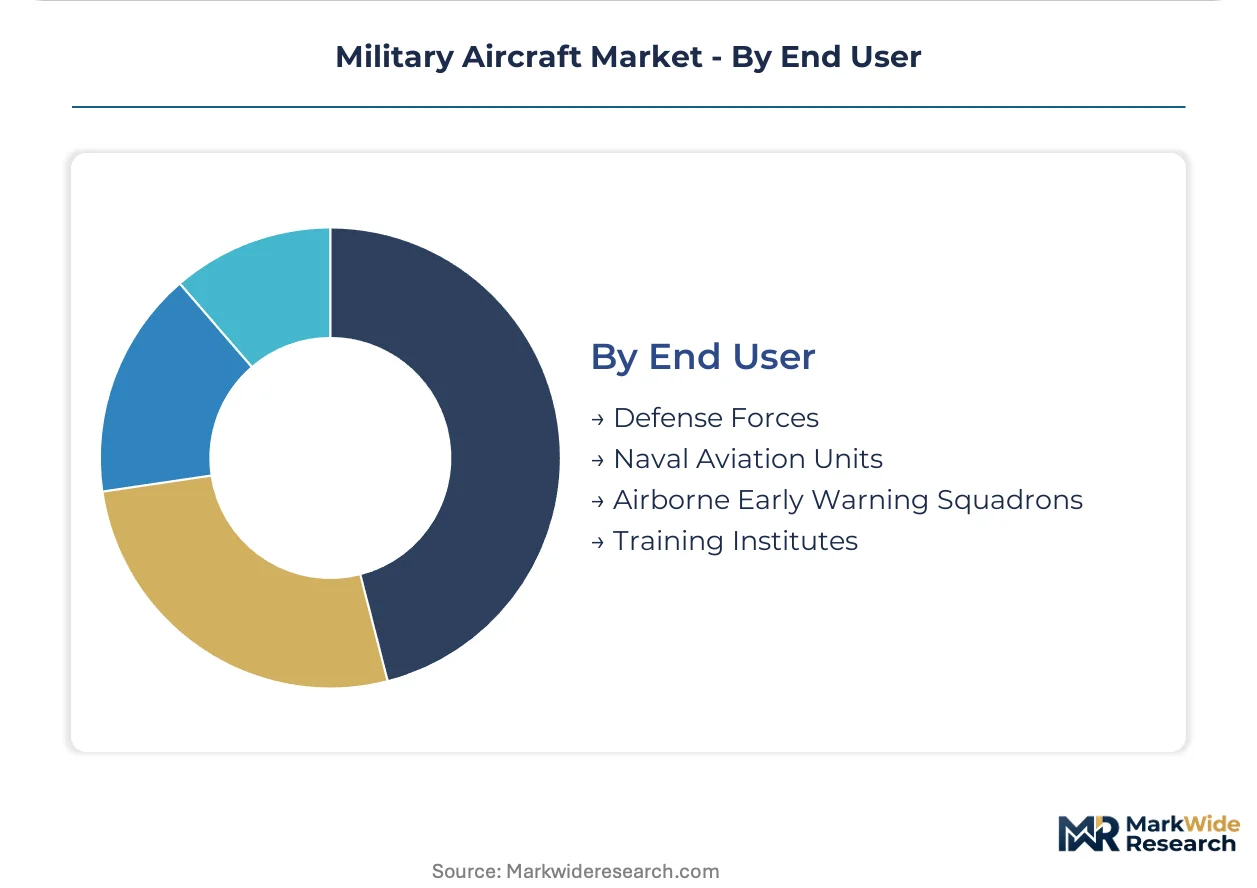
Organizational structure shapes procurement authority and through-life support arrangements, with service-specific maintenance cultures influencing platform selection.
- Defense Forces:National air arms execute the majority of fighter and bomber procurement. Poland and Romania are replacing MiG and Sukhoi fleets with Western-compatible platforms under offset agreements.
- Naval Aviation Units:Carrier-based and maritime patrol operations require corrosion-resistant airframes. Littoral surveillance requirements are expanding maritime patrol procurement across Pacific rim nations.
- Airborne Early Warning Squadrons:Specialized units operate radar and command platforms.
- Training Institutes:Flight schools require durable, cost-effective platforms for pilot qualification.
Defense Forces retain the dominant procurement volume, though Naval Aviation Units are climbing the fastest through Indo-Pacific theater buildup.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Sponge titanium refining and nickel-based superalloy processing cluster in Russia and China, creating Western defense procurement vulnerability. National stockpiling programs in the United States, Germany, Japan, and Australia attempt to offset this concentration. Platform assembly and systems integration concentrate in established aerospace clusters across NATO member states and allied Indo-Pacific nations.
United States
Fifth-generation fighter production and autonomous wingman development drive procurement volume at Lockheed Martin and Northrop Grumman facilities. The FAA coordinates military-civilian airspace integration standards while ITAR export controls segment addressable demand pools. Seattle and Fort Worth aerospace clusters anchor final assembly lines for strategic bombers and fighter platforms.
United Kingdom
Team Tempest sixth-generation development and open-architecture avionics mandates reshape supplier hierarchies. The Ministry of Defence unbundles platform acquisition from through-life support under AIR 7000 frameworks. Lancashire and Bristol defense corridors concentrate BAE Systems integration facilities and Rolls-Royce propulsion research.
Germany
FCAS program participation and NATO eastern flank air policing commitments expand fighter replacement budgets. The KBA enforces dual-use export licensing while the European Defence Fund mandates cross-border industrial participation. Bavaria and Hamburg host Airbus Defence assembly lines for transport and tanker derivatives.
Japan
F-X indigenous fighter development and JADC2 integration requirements accelerate domestic platform investment. METI coordinates strategic material stockpiling under national security frameworks. Aichi and Gifu prefectures concentrate Mitsubishi Heavy Industries final assembly and flight test infrastructure.
Australia
F-35A acquisition and maritime patrol expansion respond to Indo-Pacific theater surveillance requirements. The TGA coordinates airworthiness delegation for regional MRO providers. South Australian defense precincts at Edinburgh and Osborne host sustainment facilities for allied platform through-life support.
Military Aircraft Market Key Industry Players
Vertically integrated primes and specialized subsystem suppliers split the market between platform control and component depth. The vendor base concentrates around three strategic archetypes: full-spectrum integrators capturing multi-billion dollar development programs; avionics and payload specialists extracting recurring modernization revenue; and regional champions serving non-aligned demand pools through offset agreements. Competitive positioning hardens through captive supply of titanium structures and in-house production of radar-absorbent coatings.
Among American full-spectrum integrators, Lockheed Martin and Boeing anchor the platform-development tier with sustained bomber and fighter production lines. Northrop Grumman occupies a position within the unmanned systems and electronic warfare specialization tier. European consolidation centers on Airbus and Dassault Aviation representing the transnational consortium model for multirole combat aircraft.
| Leading Market Players |
|---|
| Dassault Aviation |
| Airbus |
| Lockheed Martin |
| Textron Aviation |
| Embraer |
| Boeing |
| Hindustan Aeronautics |
| Sukhoi |
| Northrop Grumman |
| Others |
Cost & Logistics Intelligence
Undercapacity in Western titanium sponge refining is forcing defense ministries to absorb premium pricing for airframe-grade material while simultaneously accelerating strategic stockpile programs. This utilization squeeze cascades through the supplier base, compressing margins for mid-tier fabricators and concentrating pricing power with integrated primes possessing captive metallurgical capacity.
Pricing Analysis
Aftermarket service contracts now drive lifetime value capture, with performance-based logistics agreements displacing transactional spare-part sales across NATO fleets. Pricing stratifies across platform tier, certification grade, and bundled sustainment scope, with fifth-generation fighters commanding substantial premiums for low-observable coating replenishment. Cost compression in fourth-generation retrofit programs is intensifying because of open-architecture mandates fragmenting proprietary subsystem lock-in. Emerging NATO members in Eastern Europe exhibit highest price sensitivity due to offset agreement pressures, while Indo-Pacific naval aviation units demonstrate lowest sensitivity given mission-critical littoral surveillance requirements.
Supply Chain Analysis
Sponge titanium and nickel-based superalloy feedstock draws from Russian and Chinese refining dominance, creating structural vulnerability for Western airframe manufacturers. Critical inputs include radar-absorbent material precursors, advanced composite fibers, and semiconductor-grade gallium arsenide for phased-array radars. Single-source vulnerability concentrates in electron-beam melting equipment for additive manufacturing nodes. Distribution runs through national procurement offices with ITAR-compliant subsystem tiering, segmenting accessible demand pools by alliance status.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Military aircraft procurement sits in early-cycle expansion as sixth-generation development programs and autonomous wingman architectures reset platform replacement timelines. JADC2 integration mandates are accelerating cross-domain data link adoption across allied defense ministries.
For Market Incumbents: Insulate proprietary avionics architectures through accelerated open-standard middleware development that locks in subsystem upgrade pathways. Captive supply of titanium structures and in-house production of stealth coatings defend against Russian and Chinese material export leverage. Certification investment in FAA and EASA military-civilian integration standards preserves airworthiness delegation authority against emerging MRO competitors.
For New Entrants and Emerging Players: Establish a beachhead in digital twin lifecycle management services for legacy fourth-generation fleets resisting full platform replacement. Poland and Romania defense modernization programs offer most penetrable entry points through offset-driven local assembly clauses. Go-to-market positioning should emphasize predictive maintenance algorithms that reduce depot-level resurfacing cycles for radar-absorbent materials.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across unmanned combat aerial vehicle sub-segments as autonomous targeting algorithms mature through DARPA pipelines. Long-term viability favors acquisition targets possessing airworthiness delegation authority and performance-based logistics contract portfolios. Watch for inflection signals in European Defence Fund collaborative program allocations exceeding the 35 percent cross-border industrial participation threshold.
| Strategic Initiative | Industry Significance |
|---|---|
| Open-Architecture Avionics Certification | DO-178C compliance investment unlocks NATO retrofit mandates and fragments proprietary subsystem lock-in. |
| Strategic Material Stockpiling Partnership | Long-term offtake agreements with Australian and Japanese sponge titanium producers reduce Russian supply exposure. |
| Autonomous Wingman Platform Development | DARPA algorithm maturation through manned-unmanned teaming programs reshapes force-structure planning. |
| Digital Twin Lifecycle Management | Physics-based modeling contracts displace traditional spare-part sales across F-35 and Eurofighter fleets. |
| Indo-Pacific MRO Hub Establishment | TGA airworthiness delegation at South Australian facilities captures through-life support disaggregation from OEMs. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with defense procurement officers, platform engineering directors, airworthiness certification leads, and aftermarket service heads at tier-one integrators. Secondary validation drew from FAA military-civilian integration directives, ITAR license approval databases, European Defence Fund collaborative program disclosures, and national stockpiling framework announcements. Bottom-up segment sizing triangulated against top-down defense budget allocation analysis across NATO and Indo-Pacific allied ministries.
Calibration against historical platform delivery schedules and retrofit cycle data anchored the analytical framework across the projection horizon. Segmentation dimensions modeled encompass aircraft type, propulsion architecture, mission application, and end-user organizational structure alongside regional regulatory cluster alignment. CAGRs were derived through trend extrapolation of procurement program of record commitments and technology transition timelines. Forecast inputs incorporated sixth-generation development program funding trajectories and autonomous wingman demonstration milestones.
Stress conditions across titanium supply disruption, ITAR license approval delays, and stealth coating technical limitation severity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding alliance cohesion and defense budget priority stability. Cross-checking against national military expenditure-to-GDP trajectories and platform retirement schedules is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft
GCC General Aviation Market
Aircraft
Aircraft Nacelle Systems Market
Aircraft
Aerospace Turbojet Market
Aircraft
Aircraft Strut Market
Aircraft
Fixed Wing Turbine Aircraft Market
Aircraft
Aircraft Flight Control System Market
Aircraft
Latin America Business Jet Market
Aircraft
Commercial Aircraft Leasing Market
Aircraft
Europe Turboprop Aircraft Market
Aircraft
US Military Aviation Market
Aircraft
Airplane Landing Gear Market
Aircraft
Southeast Asia Business Jet Market
Aircraft
US Aviation Market
Aircraft
Aircraft Fairings Market
Aircraft
Aircraft Window Frame Market
Aircraft
Search and Rescue Helicopter Market