
 Aerospace Titanium Market | 2026-2036
Aerospace Titanium Market Size, Share, and Industry Trends Forecast 2026-2036
Aerospace Titanium Market Intelligence
The International Civil Aviation Organization's CORSIA framework for emissions reduction is pivoting the aerospace industry toward lighter, more fuel-efficient airframes. This shift amplifies the value of high-strength titanium alloys in aircraft structures and engines. Precision Castparts Corporation leverages its expertise in complex structural castings and airfoils. VSMPO-AVISMA sustains its market position through large-scale integrated production, while Allegheny Technologies Incorporated specializes in advanced alloys and flat-rolled products for demanding applications.
Aerospace titanium refers to a family of high-performance metallic alloys valued for their exceptional strength-to-weight ratio and stability at elevated temperatures. The most common variant, Ti-6Al-4V, is an α/β Titanium alloy used extensively in critical applications. Demand for these titanium alloys is highest for manufacturing engine components and structural airframe parts like landing gear and wing boxes. Within product forms, forgings and plates command significant value due to the complex processing required to meet performance specifications.
Material certification and component airworthiness are governed by stringent regulations from bodies like the US Federal Aviation Administration (FAA) and the European Union Aviation Safety Agency (EASA). These authorities mandate exhaustive testing and process documentation for all flight-critical titanium parts. Consequently, navigating the qualification pathway for new alloys or manufacturing methods represents a primary strategic consideration for all supply chain participants, from raw material producers to Tier-1 suppliers.
Market Dynamics
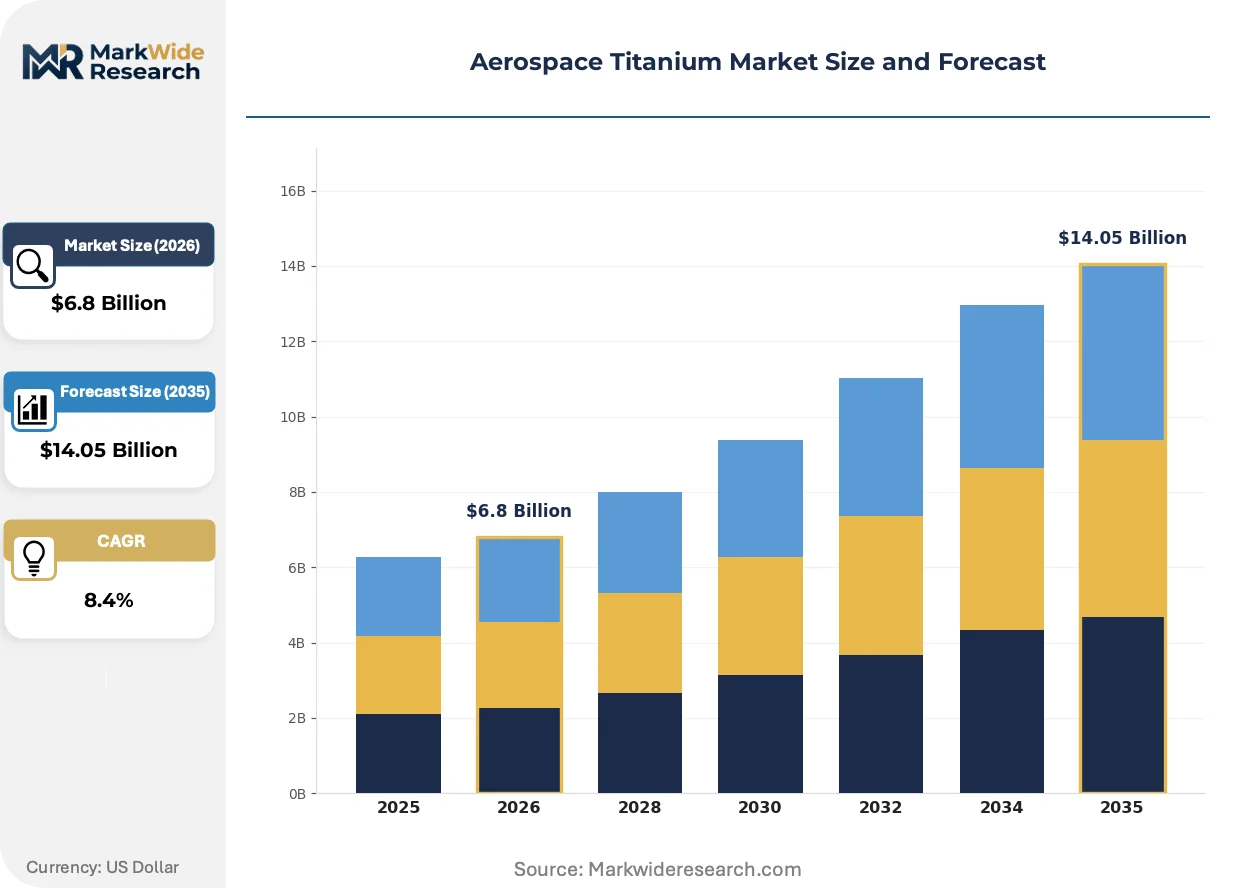
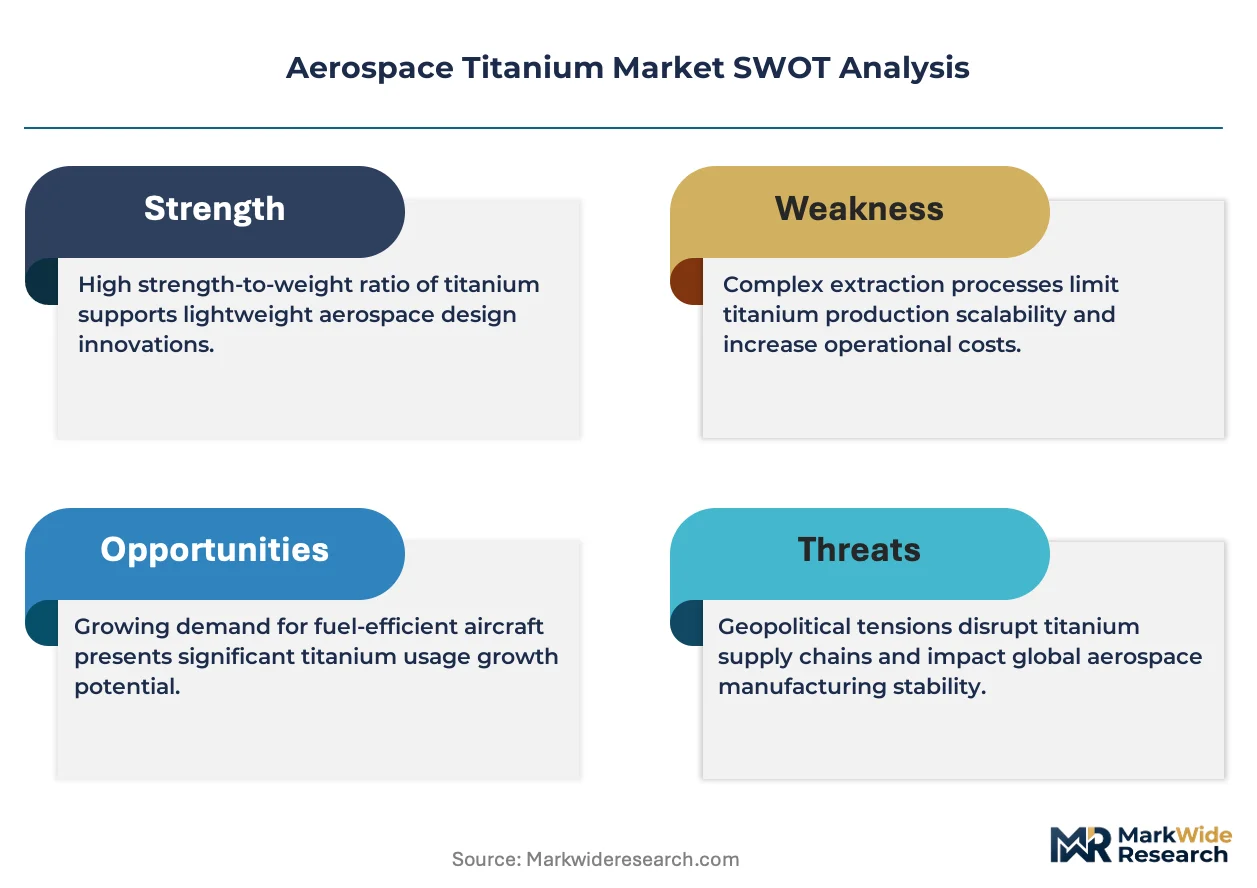
The aerospace titanium market is defined by the structural tension between intense demand for lightweighting driven by next-generation aircraft programs and the concentrated, high-cost nature of the material's supply chain. This dynamic forces a continuous focus on process efficiency and supply security.
Growth Catalysts
- Additive Manufacturing:The qualification of titanium powders for additive manufacturing processes reduces the high buy-to-fly ratio common in subtractive machining, enabling more affordable and complex component designs for airframes and satellites.
- Emissions Reduction Mandates:Frameworks like the ICAO's CORSIA push airlines toward more fuel-efficient aircraft, directly increasing the specification of high strength-to-weight titanium alloys over heavier steel or less durable aluminum in critical structures.
- Next-Generation Aircraft Production:The production ramp-up for new commercial and military aircraft platforms, particularly in established aerospace clusters in the United States and France, creates a consistent demand pull for titanium forgings, plates, and extrusions.
Market Restraints
- High Processing Costs:The multi-stage vacuum arc remelting (VAR) process required for aerospace-grade ingots, combined with the energy-intensive and difficult nature of forging and machining titanium, creates a significant cost disadvantage versus aluminum alloys.
- Titanium Sponge Supply Concentration:A reliance on a limited number of countries for aerospace-grade titanium sponge, the primary raw material, introduces significant price volatility and geopolitical supply chain risks for the entire downstream value chain.
- Substitution from Composites:In certain non-load-bearing and temperature-neutral airframe applications, advanced carbon fiber reinforced plastics (CFRP) can offer a lighter-weight alternative, posing a substitution threat in specific structural components.
Strategic Opportunities
- Commercial Space Sector:The rapid growth of private space exploration and satellite constellation deployment creates a new and expanding market for high-performance titanium alloys in launch vehicle structures, tanks, and engine components.
- Advanced Powder Metallurgy:Developing novel, lower-cost titanium powder production techniques can unlock broader adoption in additive manufacturing and near-net-shape part production, particularly for the automotive and industrial sectors.
- Hypersonic Applications:Research and development in hypersonic flight for both defense and commercial applications opens a future market for specialized, high-temperature titanium alloys and metal matrix composites capable of withstanding extreme conditions.
Industry Challenges
- Stringent Qualification Timelines:Navigating the extensive and costly material and process qualification pathways mandated by airworthiness authorities like the FAA and EASA represents a significant barrier to introducing new alloys or manufacturing methods.
- Specialized Labor Scarcity:A persistent shortage of skilled machinists, welders, and engineers with deep expertise in the difficult metallurgy and fabrication characteristics of titanium alloys acts as a bottleneck for component manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aerospace Titanium Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.05 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: β Titanium, α Titanium, α/β Titanium, Titanium Alloys Application: Aircraft, Spacecraft, Missiles, Engine Components Form: Sheet, Plate, Bar, Forging End User: OEMs, Tier-1 Suppliers, Maintenance Providers, Defense Contractors |
| Companies Covered | Carpenter Technology Corporation, GE Aviation, VSMPO-AVISMA Corporation, Aperam Ltd., GKN Aerospace Services Limited, Precision Castparts Corporation, Titanium Metals Corporation, Toho Titanium Co., Allegheny Technologies Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aerospace Titanium Market Strategic Shifts & Innovations
The defining trend is a push towards process digitalization and vertical integration to manage the inherent cost and complexity of the titanium supply chain. This involves creating digital threads from raw material to certified component, improving traceability and production efficiency.
Additive manufacturing of titanium powders, utilizing processes like powder bed fusion, enables the production of near-net-shape components with optimized topologies. Aerospace OEMs and their top-tier suppliers are adopting this technology to reduce material waste and shorten lead times for complex brackets and internal structures. This technology is expanding into the fabrication of larger and more critical airframe parts, challenging the dominance of traditional subtractive manufacturing.
The European Union's Clean Aviation program, a key pillar of the EU Green Deal, provides a regulatory and funding framework that incentivizes the development of ultra-efficient aircraft. This policy directly stimulates research into lightweight materials and advanced propulsion systems where titanium's properties are critical. Engine and airframe manufacturers based in Europe are most affected, accelerating their R&D investments in high-temperature titanium alloys and metal-matrix composites.
A clear behavioral shift is occurring away from purely transactional component purchasing towards collaborative long-term supply agreements. This model displaces arms-length competitive bidding for individual parts, favoring suppliers who can manage risk and provide design-for-manufacturing input early in a program's lifecycle. This procurement evolution is most advanced within the engine supply chains serving major OEMs in the United States and France.
Aerospace Titanium Market Segmentation
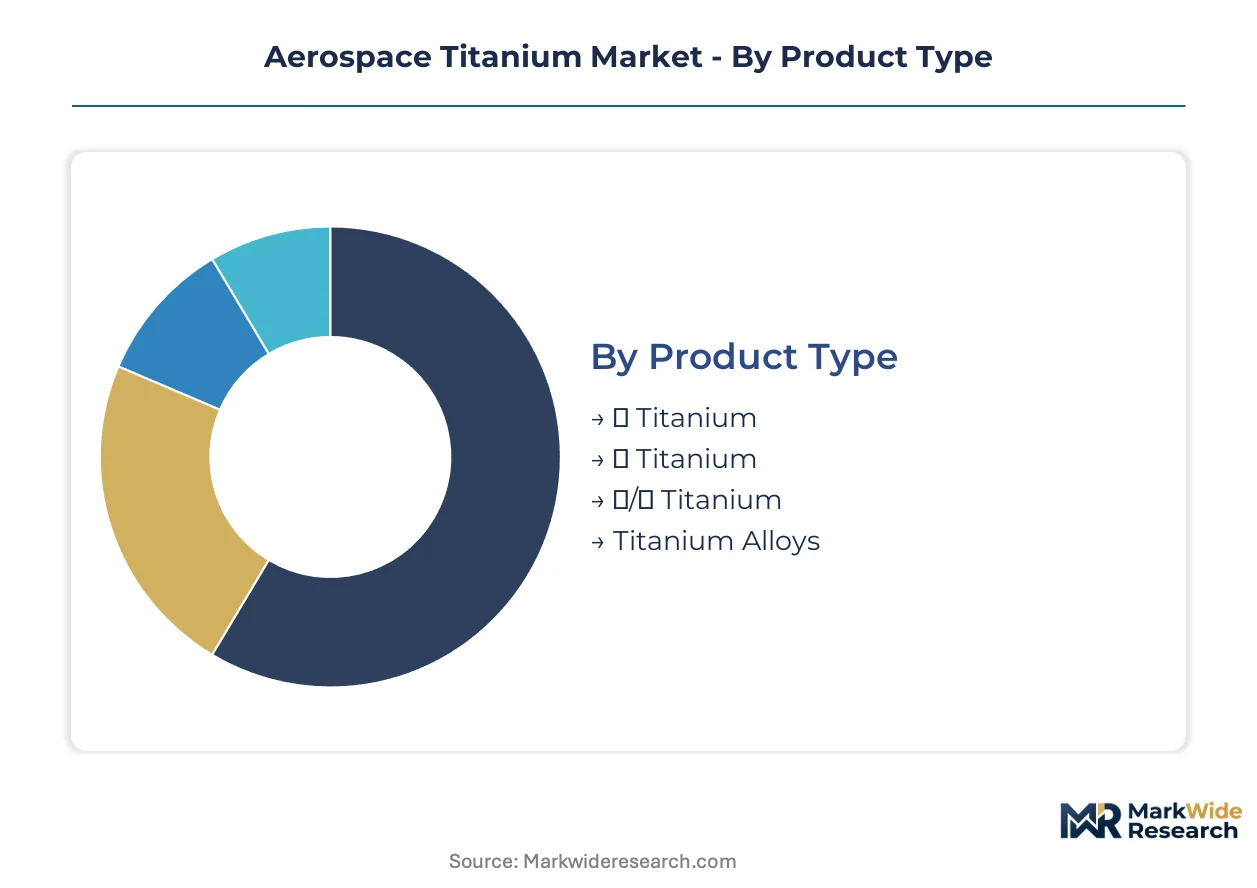
The aerospace titanium market exhibits diverse requirements across its value chain, necessitating a granular understanding of material types, forms, applications, and end-users. This segmentation clarifies how specific material properties and processing methods align with the stringent performance and airworthiness demands of the aerospace industry. Each segment reflects distinct technological advancements and supply chain dynamics.
Product Type:
The continuous upgrade and replacement cycles for commercial and military aircraft drive specific demand for advanced titanium product types, balancing performance and manufacturing efficiency.
- α/β Titanium:This alloy class, prominently featuring Ti-6Al-4V, combines high strength, ductility, and excellent corrosion resistance, making it the most widely specified variant for critical structural airframe components and engine parts. Demand concentrates within established aerospace manufacturing hubs in the United States and France for new aircraft programs.
- Titanium Alloys:This broad category encompasses specialized compositions engineered for extreme conditions, including high-temperature alloys for engine hot sections and high-strength variants for landing gear. The demand for these advanced alloys is driven by next-generation aircraft designs requiring superior performance and weight reduction.
- β Titanium:These alloys offer high strength and good formability, often used in fasteners and springs, benefiting from their deep hardenability.
- α Titanium:Known for their good weldability and creep resistance at elevated temperatures, these alloys find applications in non-structural aircraft components.
α/β Titanium sits at the top of the volume ranking, with specialized Titanium Alloys climbing the fastest.
Application:
Titanium's application across the aerospace value chain reflects its unique strength-to-weight ratio and thermal stability, crucial for flight-critical systems and structural integrity.
- Aircraft:This segment represents the largest consumption of aerospace titanium, primarily for commercial and military airframes, where lightweighting directly translates to fuel efficiency and payload capacity. Demand is particularly high for new wide-body and narrow-body aircraft production in Seattle and Toulouse.
- Engine Components:Titanium alloys are indispensable for jet engine fan blades, compressor disks, and casings due to their ability to withstand high temperatures and rotational stresses. The qualification of new high-temperature alloys is critical for advancing engine performance and reducing emissions.
- Spacecraft:Titanium is used in satellite structures and propulsion systems, valued for its low density and resistance to the harsh vacuum environment.
- Missiles:High-strength titanium alloys provide structural integrity and thermal protection for advanced missile systems, enhancing range and maneuverability.
Aircraft applications demonstrate the highest strategic importance, while Engine Components drive significant material innovation.
Form:
The diverse forms of aerospace titanium are dictated by specific manufacturing processes and the structural requirements of final components, often involving complex and energy-intensive production.
- Forging:Titanium forgings are critical for highly stressed components like landing gear, engine disks, and structural bulkheads, benefiting from improved grain structure and mechanical properties achieved through deformation. The specialized equipment and expertise for large-scale titanium forging are concentrated among a few global suppliers.
- Plate:Titanium plates serve as foundational material for large structural airframe components, including wing boxes and fuselage sections, where high strength and fatigue resistance are paramount. Demand for aerospace-grade plates is consistent across major airframe manufacturers in North America and Europe.
- Sheet:Thin titanium sheets are utilized for non-structural fairings, heat shields, and internal ducting, prized for their lightweight properties and corrosion resistance.
- Bar:Titanium bars are machined into fasteners, shafts, and smaller structural elements, providing high strength and dimensional stability.
Forging and Plate forms generate the highest value per unit due to their intricate processing and critical applications.
End User:
The end-user landscape for aerospace titanium is characterized by stringent qualification processes and long-term supply agreements, reflecting the high-stakes nature of aerospace manufacturing and maintenance.
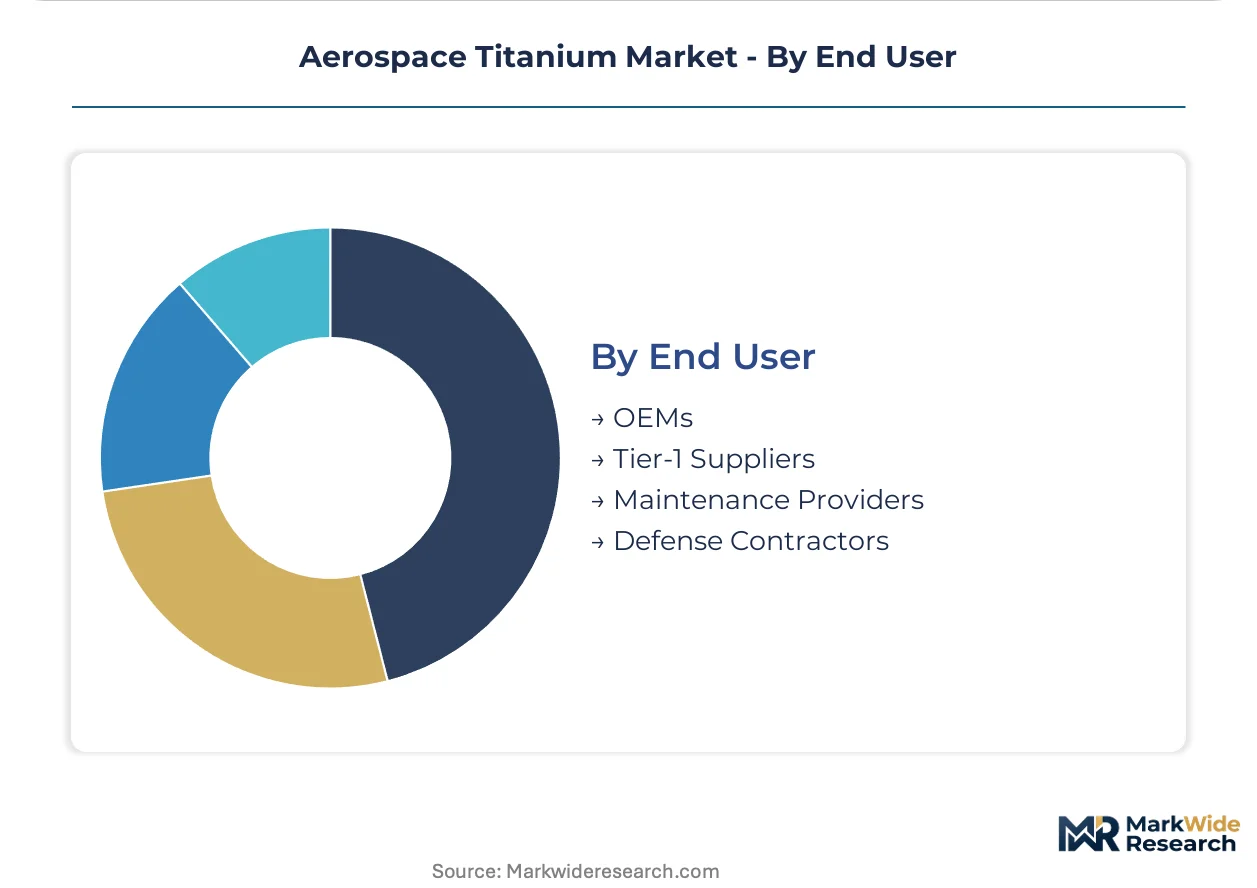
- OEMs:Original Equipment Manufacturers like Boeing and Airbus drive the primary demand for raw titanium and semi-finished products, integrating them into new aircraft and engine platforms. Their procurement strategies often involve direct engagement with large titanium producers and dictate material specifications.
- Tier-1 Suppliers:These companies, such as Spirit AeroSystems or Safran, transform titanium forms into complex sub-assemblies and components for OEMs, leveraging specialized manufacturing capabilities and advanced processing techniques. They often manage their own material sourcing and qualification processes.
- Maintenance Providers:Firms specializing in aircraft repair and overhaul require titanium for replacement parts and structural repairs, adhering to strict airworthiness standards.
- Defense Contractors:These entities procure titanium for military aircraft, missile systems, and specialized defense applications, prioritizing performance and reliability.
OEMs hold significant influence over material specifications, while Tier-1 Suppliers are crucial for advanced component fabrication.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The aerospace titanium industry historically scaled in nations with advanced aviation and defense sectors, pioneering jet engine technology and high-performance airframes. These countries invested heavily in metallurgical research and complex manufacturing, establishing key regional concentrations for titanium production.
United States
Demand in the United States is driven by robust commercial and military aircraft production, alongside expanding space exploration programs. The US Federal Aviation Administration (FAA) mandates exhaustive qualification for all flight-critical titanium parts. Major aerospace manufacturing clusters in Seattle consistently require titanium forgings and plates for new airframe assemblies.
France
French aerospace titanium demand stems from large-scale Airbus commercial aircraft manufacturing and engine component production for Safran. The European Union Aviation Safety Agency (EASA) governs stringent airworthiness standards for titanium alloys in European aerospace. Toulouse serves as a primary hub for Airbus final assembly, consuming significant volumes of titanium for structural components.
China
Growth in China's market is propelled by ambitious indigenous commercial aircraft programs and ongoing military aviation modernization efforts. China's GB standards define comprehensive material specifications and quality control for aerospace titanium. Xi'an is rapidly developing as an aerospace manufacturing center, increasing domestic titanium alloy consumption.
United Kingdom
United Kingdom demand focuses on Rolls-Royce engine component manufacturing and advanced airframe structures for military and commercial platforms. The UK Civil Aviation Authority (CAA) ensures compliance with airworthiness directives for titanium parts. Bristol hosts significant aerospace engineering facilities, concentrating on high-temperature titanium alloy development.
Japan
Japanese aerospace titanium consumption supports Mitsubishi Heavy Industries aircraft programs and specialized component manufacturing for global supply chains. METI (Ministry of Economy, Trade and Industry) actively promotes research into advanced materials for next-generation aerospace applications. Nagoya remains a key aerospace manufacturing region, contributing high-precision titanium parts to international projects.
Aerospace Titanium Market Key Industry Players
Premium-margin players sit above commodity-margin players across the aerospace titanium value chain, reflecting specialized material science and complex processing. The market exhibits a tiered structure, with large-scale integrated producers, specialized alloy manufacturers, and precision component fabricators forming distinct strategic archetypes. Companies pursue vertical integration into raw material processing and advanced manufacturing techniques like additive manufacturing. Strategic partnerships and long-term supply agreements are also common competitive moves to secure market position.
At the scale-driven end, VSMPO-AVISMA Corporation, a Russian company, exemplifies the integrated production model from raw sponge to finished mill products. Precision Castparts Corporation, a US-based entity, represents expertise in complex structural castings and airfoils, occupying a niche for high-value, intricate components. Allegheny Technologies Incorporated, also US-based, anchors the market for advanced alloys and flat-rolled products, catering to demanding applications requiring specialized material properties.
| Leading Market Players |
|---|
| Carpenter Technology Corporation |
| GE Aviation |
| VSMPO-AVISMA Corporation |
| Aperam Ltd. |
| GKN Aerospace Services Limited |
| Precision Castparts Corporation |
| Titanium Metals Corporation |
| Toho Titanium Co. |
| Allegheny Technologies Incorporated |
| Others |
Cost & Logistics Intelligence
Highly certified, premium-grade aerospace titanium versus less critical, standard grades represents a significant tier divergence. This bifurcation manifests in both pricing structures and the intricate configurations of the material supply chain.
Pricing Analysis
Contract-based long-term offtake agreements dominate the aerospace titanium market, ensuring supply stability for critical components. Price differentiation stems from the rigorous material certification level mandated by authorities like the FAA and EASA, alongside the high degree of customization required for specific airframe or engine designs. Pricing softness reflects the high processing costs and concentrated raw material supply, particularly for specialized alloys. OEMs exhibit the least price sensitivity for flight-critical components, while maintenance providers are more sensitive for standard replacement parts.
Supply Chain Analysis
Domestic content mandates and strategic national interests increasingly reshape sourcing strategies for aerospace titanium. Geographic supply concentration remains significant, with major producers in Russia, the United States, and China. The supply chain draws from critical raw material dependencies, primarily titanium sponge and high-purity alloying elements. Geopolitical instability affecting titanium sponge availability creates significant commodity price volatility, posing a structural supply chain risk. Direct long-term agreements between integrated producers and Tier-1 suppliers or OEMs define the dominant distribution model.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The aerospace titanium market functions as a stable compounder, driven by continuous next-generation aircraft production cycles. Stringent airworthiness regulations ensure consistent demand for certified, high-performance alloys.
For Market Incumbents: Anticipate increasing demand for advanced alloys by investing in R&D for high-temperature and metal matrix composites. Reinforce market position through strategic vertical integration into raw material processing to mitigate titanium sponge supply concentration risks. Focus on process digitalization to counter specialized labor scarcity and improve qualification timelines.
For New Entrants and Emerging Players: Digital platforms offering rapid prototyping and small-batch additive manufacturing services present a viable entry point for new players. Target the commercial space sector and specialized defense applications, where qualification processes can be more agile than for commercial aviation. Develop expertise in advanced powder metallurgy to penetrate the near-net-shape component market.
For Investors and Strategic Acquirers: Consolidation pressure builds where specialized manufacturing capabilities and material certification are paramount. The long-term viability of this market remains strong over the next 5-10 years due to persistent aerospace demand. Target mid-sized precision component fabricators or specialized alloy developers with established OEM relationships. Watch for accelerated qualification of new additive manufacturing processes as a key inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Forging | Addresses consistent demand for structural airframe components in established aerospace clusters. |
| Advanced Powder Metallurgy R&D | Unlocks broader adoption of titanium in additive manufacturing, reducing material waste for OEMs. |
| Long-term Supply Agreements | Secures raw material access and stabilizes pricing for Tier-1 suppliers and airframe manufacturers. |
| Process Digitalization Implementation | Enhances traceability and efficiency across the complex supply chain for flight-critical parts. |
| High-Temperature Alloy Development | Supports next-generation engine components requiring superior performance and emissions reduction. |
Research Approach
Bottom-up end-use modeling reconciled against top-down supply-side tracking forms the analytical core, validated through primary interviews and extensive secondary research. Industry stakeholders, including procurement leads at OEMs, R&D directors at alloy producers, and manufacturing engineers at Tier-1 suppliers, provided qualitative insights. Secondary sources comprised aerospace industry reports, FAA/EASA regulatory filings, and company financial disclosures. This dual approach ensures robust data integrity and market understanding.
Historical trendline analysis informed the quantitative projections across the analysis window, alongside regression modeling for key growth drivers. Segmentation dimensions modeled included product type, application, form, end-user, and specific regional demand centers. CAGRs were derived from a blend of historical performance and anticipated future market dynamics. Key forecast inputs included commercial aircraft order backlogs and military spending projections.
The model assumes a particular technology adoption path; alternative pathways for additive manufacturing would alter the outlook. Forecasts reflect assumptions regarding geopolitical stability and raw material supply chain resilience. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aerospace and Aircraft Materials
Middle-East and Africa Aerospace Composites Market
Aerospace and Aircraft Materials
Aerospace Ceramic Matrix Composites Market
Aerospace and Aircraft Materials
Commercial Aircraft Materials Market
Aerospace and Aircraft Materials
Global Aerospace Adhesives Market
Aerospace and Aircraft Materials
Aerospace Lightweight Materials Market
Aerospace and Aircraft Materials
Aramid Honeycomb Market
Aerospace and Aircraft Materials
Aerospace Forging Market
Aerospace and Aircraft Materials
Aircraft Carbon Brake Disc Market
Aerospace and Aircraft Materials
Commercial Aerospace Carbon Brakes Market
Aerospace and Aircraft Materials
Beryllium Aluminum Alloy Market
Aerospace and Aircraft Materials
Aerogel Blanket Market
Aerospace and Aircraft Materials
Honeycomb Panel for Aircraft Market
Aerospace and Aircraft Materials
Aerospace Carbon Fiber Market
Aerospace and Aircraft Materials
Magnesium Beryllium Alloy Market
Aerospace and Aircraft Materials
Aeroengine Composites Market
Aerospace and Aircraft Materials
Aerospace 3D Printing Consumables Market