
 Aerospace Composites Market | 2026-2036
Aerospace Composites Market Size, Share, and Industry Trends Forecast 2026-2036
Aerospace Composites Market Analysis
Certified composite laminators and AFP technicians is bifurcating the supplier landscape into tiered capability bands. Toray Industries sustains one of the broadest carbon fiber portfolios, supplying prepreg to both commercial and defense airframers across multiple continents. Hexcel Corporation dominates thermoset prepregs for primary structures, leveraging long-standing qualifications with Boeing and Airbus. Spirit AeroSystems anchors North American fuselage output, specializing in large-scale automated fiber placement for single-aisle programs.
Aerospace composites encompass fiber-reinforced polymer systems, typically carbon fiber embedded in epoxy or thermoplastic matrices, engineered to achieve specific strength-to-weight ratios exceeding 200 MPa per gram per cubic centimeter in primary load-bearing directions. These materials replace aluminum and titanium in wings, fuselage sections, and empennage to reduce operating empty weight and extend range-payload envelopes. CFRP occupies the dominant value position across product types, reflecting its entrenched role in wing skins and control surfaces where fatigue resistance governs design selection. Automated Fiber Placement is expanding fastest among manufacturing processes, displacing hand lay-up in high-rate programs as equipment costs amortize across multi-thousand-unit backlogs.
FAA certification standards under Part 25 dictate damage tolerance and flammability requirements that shape composite architecture in US-registered aircraft. EASA's continuing airworthiness regulations and the EU Green Deal's emissions benchmarks are pressuring European OEMs to accelerate thermoplastic adoption for recyclability and out-of-autoclave processing. China's GB standards and CAAC type certification pathways are conditioning market access for foreign suppliers serving COMAC programs. Stakeholders must monitor evolving qualification protocols as regulators weigh novel resin systems against established epoxy benchmarks for primary structure approval.
Market Dynamics
Automated Fiber Placement equipment amortization across multi-thousand-unit narrowbody backlogs is compressing manufacturing cycle times and requalifying supplier capability tiers. This capital intensity bifurcation separates qualified laminators from hand-lay-up operations.
Growth Catalysts
- FAA Part 25 damage tolerance mandates:US airworthiness standards for composite primary structures accelerate material qualification investments among tier-1 aerostructures suppliers.
- Thermoplastic resin systems:Out-of-autoclave processing reduces cure cycle energy consumption and enables fusion welding for fuselage joining operations.
- Single-aisle fleet renewal:Boeing 737 MAX and Airbus A320neo production rate targets concentrate procurement volumes for wing skins and control surfaces.
Market Restraints
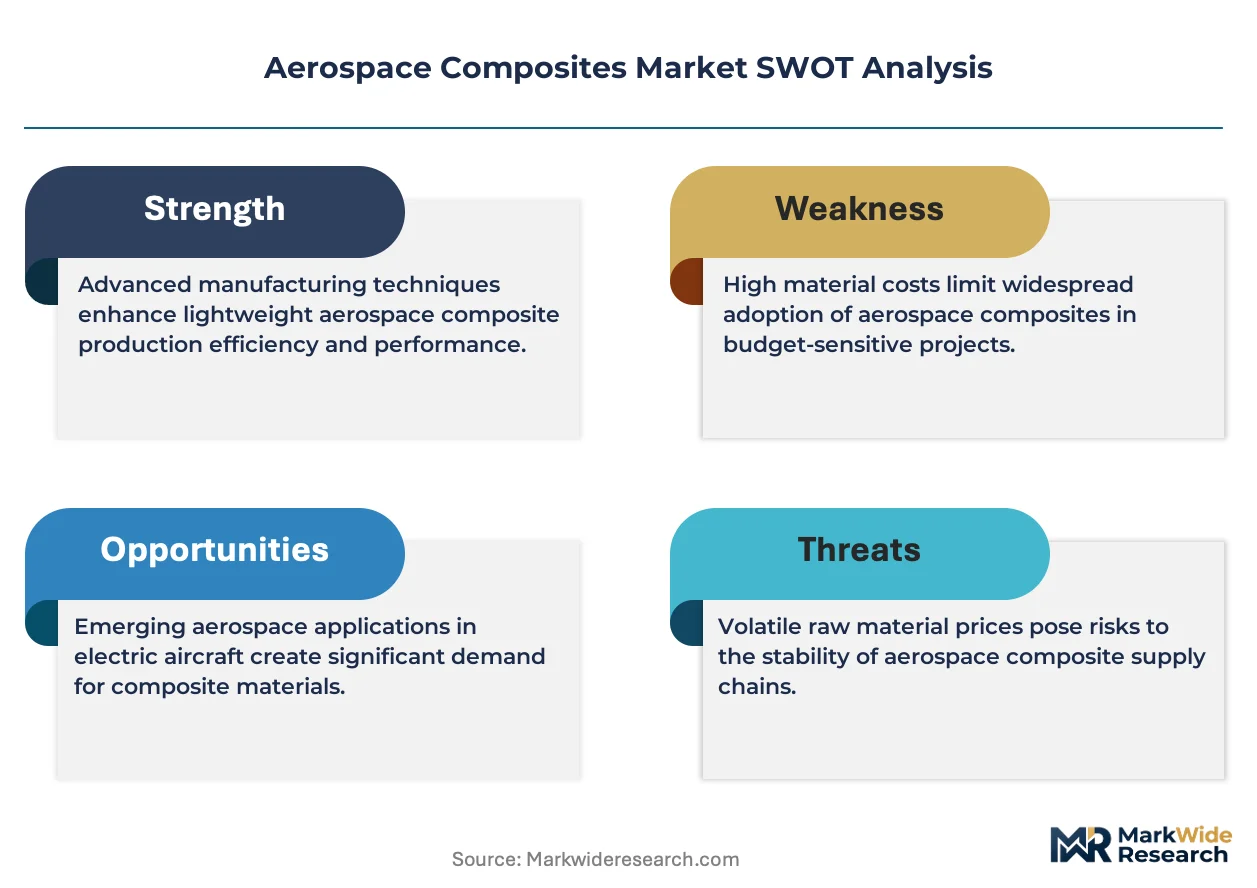
- Carbon fiber precursor cost volatility:Acrylonitrile feedstock exposure ties composite input costs to petrochemical pricing cycles.
- Japanese precursor concentration:Toray, Teijin, and Mitsubishi Chemical anchor PAN-based carbon fiber supply, creating geographic single-point vulnerability.
- Thermoset epoxy recyclability limits:Cross-linked polymer matrices resist mechanical or chemical reclamation, constraining end-of-life pathways under EU Green Deal circularity benchmarks.
Strategic Opportunities
- Urban air mobility airframes:eVTOL manufacturers seek certified composite structures for tilt-rotor hubs and battery enclosures at sub-Part-25 certification burden.
- India defense indigenization:HAL Tejas and AMCA programs create import-substitution demand for domestic prepreg qualification under DRDO specifications.
- PEKK-thermoplastic welding:Automated ultrasonic consolidation enables rib-to-skin joining without mechanical fasteners, reducing assembly labor content.
Industry Challenges
- AFP technician certification scarcity:Machine programming and in-situ consolidation expertise lags equipment installation rates at tier-2 suppliers.
- Qualification timeline compression:FAA and EASA concurrent type certification reviews for novel resin systems extend material allowables development by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aerospace Composites Market |
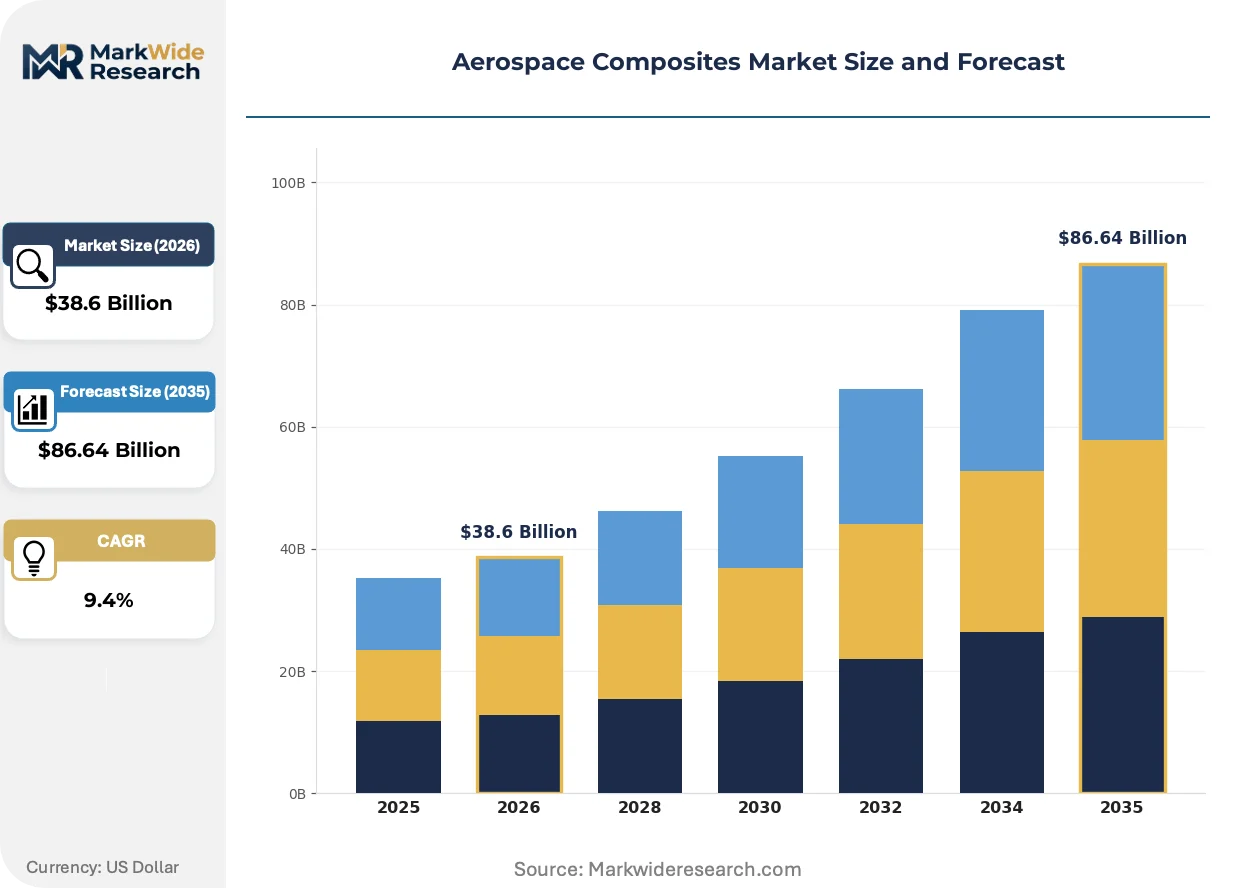
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $86.64 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: CFRP, GFRP, Hybrid Composites, Resin Systems Application: Airframes, Interiors, Propulsion Systems, Cargo Doors End User: Commercial Aviation, Military Aviation, Aerospace MRO, UAV Manufacturers Manufacturing Process: Lay-Up, Filament Winding, Resin Transfer Molding, Automated Fiber Placement |
| Companies Covered | Mitsubishi Chemical Group Corporation, Gurit Holding AG, Toray Industries, Inc., Spirit AeroSystems, Teijin Limited, Hexcel Corporation, SGL Carbon SE, Materion Corporation, Solvay SA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aerospace Composites Market Emerging Trajectories
Digital thread integration from fiber placement to non-destructive inspection is collapsing feedback loops between manufacturing and quality assurance. Real-time tow tension monitoring and automated defect detection now govern acceptance criteria.
Thermoplastic automated fiber placement is fragmenting the traditional thermoset dominance in wing structures. Airbus A350 follow-on programs and Gulfstream business jet applications adopt PEEK and PEKK matrices for damage tolerance and weldability. Equipment suppliers configure dual-tow-placement heads for thermoplastic in-situ consolidation, compressing capital recovery timelines across smaller production runs.
EASA's continuing airworthiness regulations and EU Green Deal emissions benchmarks are pressuring European OEMs to accelerate thermoplastic adoption for recyclability. The F-Gas Regulation constrains solvent-based prepreg processing, favoring aqueous or hot-melt resin film alternatives. Wing and empennage manufacturers in Germany and France requalify out-of-autoclave cure cycles to eliminate autoclave energy intensity from scope-3 emissions accounting.
Airline technical procurement teams now specify damage tolerance data packages upfront, displacing traditional build-to-print subcontracting. Tier-1 aerostructures suppliers in Wichita and Broughton assume design authority for composite detail parts, compressing OEM engineering oversight. This consolidation concentrates risk-bearing with Spirit AeroSystems and GKN Aerospace while reducing airframer direct labor headcount.
Aerospace Composites Market Segmentation
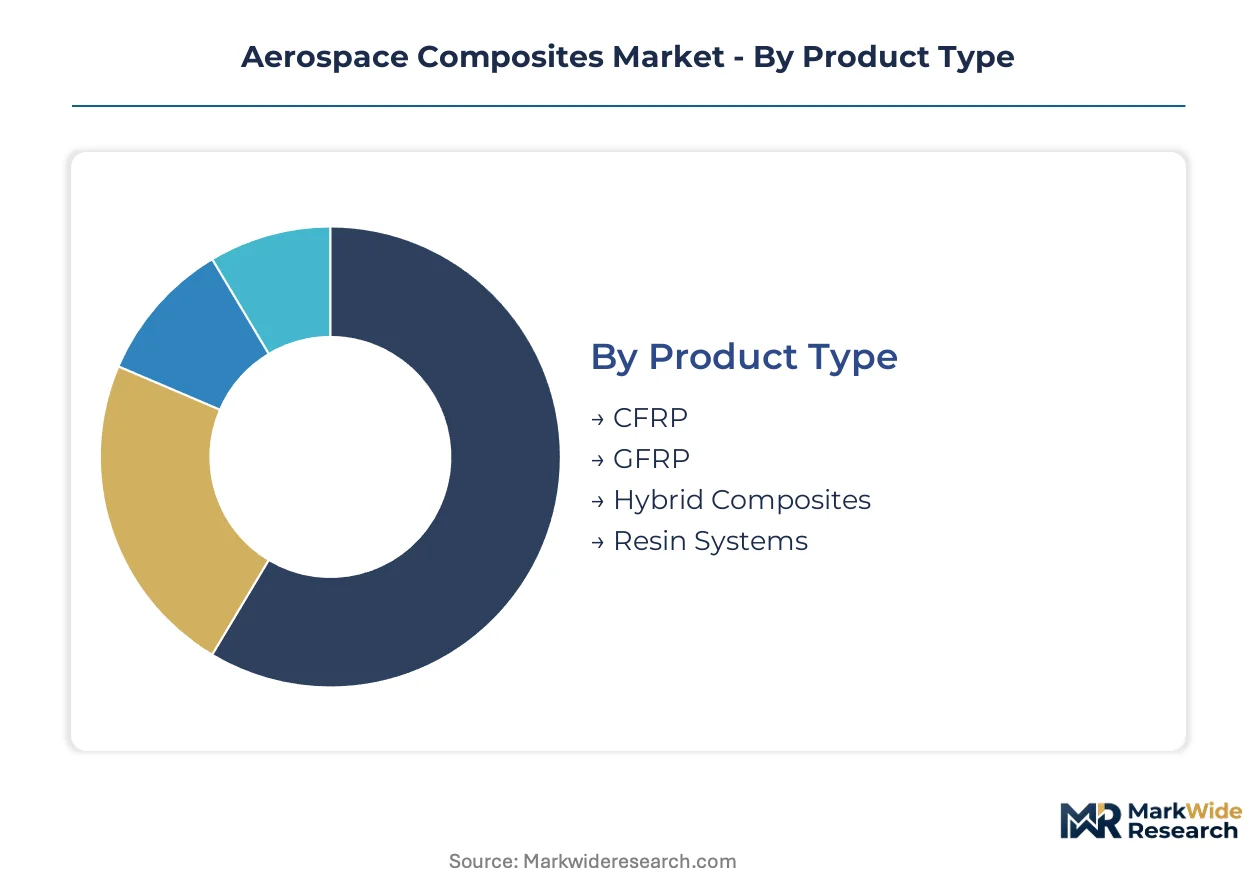
Aerospace composites segmentation reflects divergent qualification burdens across FAA Part 25 primary structures and interior subassemblies. Material selection and manufacturing process choices cascade through certification timelines, supplier capability tiers, and fleet-specific procurement strategies.
Product Type:
FAA damage tolerance mandates and EASA flammability protocols split composite qualification pathways by matrix chemistry and reinforcement architecture.
- CFRP:Carbon fiber reinforced polymers dominate wing skins and control surfaces where specific strength-to-weight ratios exceed 200 MPa per gram per cubic centimeter. Boeing 737 MAX and Airbus A320neo programs concentrate procurement volumes for primary load-bearing structures under sustained fatigue cycles.
- GFRP:Glass fiber systems serve interior panels and non-structural applications where dielectric properties and cost sensitivity outweigh stiffness requirements. Regional jet manufacturers and MRO retrofit programs favor GFRP for sidewall linings and overhead stowage in narrowbody cabin refreshes.
- Hybrid Composites:Carbon-glass combinations balance performance and cost in secondary structures.
- Resin Systems:Epoxy thermosets anchor current qualifications; thermoplastic alternatives gain traction for recyclability compliance.
Established volume favors CFRP; emerging adoption favors thermoplastic resin systems.
Application:
Airframe primary structures command extended material allowables development cycles compared to interior subassemblies.
- Airframes:Fuselage sections and wing boxes require damage tolerance certification under FAA Part 25 and EASA CS-25. Automated fiber placement equipment amortizes across multi-thousand-unit narrowbody backlogs at Spirit AeroSystems and GKN Aerospace facilities.
- Interiors:Cabin components face accelerated flammability testing under FAA AC 25.853. Seat shells, galleys, and lavatory modules adopt thermoplastic composites for faster processing and reduced smoke toxicity metrics.
- Propulsion Systems:Engine nacelles and thrust reversers demand fire-resistant prepregs.
- Cargo Doors:Cutout reinforcements and pressure-bearing edges utilize toughened epoxy systems.
Airframe applications absorb the majority of capital equipment investment; interior applications offer the shortest qualification-to-production pathways.
End User:
Procurement concentration varies sharply between production line deliveries and aftermarket retrofit cycles.
- Commercial Aviation:Boeing and Airbus anchor composite demand through tier-1 aerostructures suppliers. Single-aisle production rate targets concentrate wing skin and empennage volumes in Wichita and Broughton manufacturing clusters.
- Military Aviation:Defense programs impose ITAR-controlled supply chains and domestic sourcing mandates. Lockheed Martin F-35 and Northrop Grumman platforms sustain qualified billets for stealth-compatible material architectures.
- Aerospace MRO:Repair stations execute scarf repairs and bonded patches under FAA-approved procedures.
- UAV Manufacturers:Uncrewed platforms bypass Part 25 certification burden for rapid iteration cycles.
Commercial aviation commands the deepest supplier qualification investments; UAV manufacturers permit the fastest material substitution cycles.
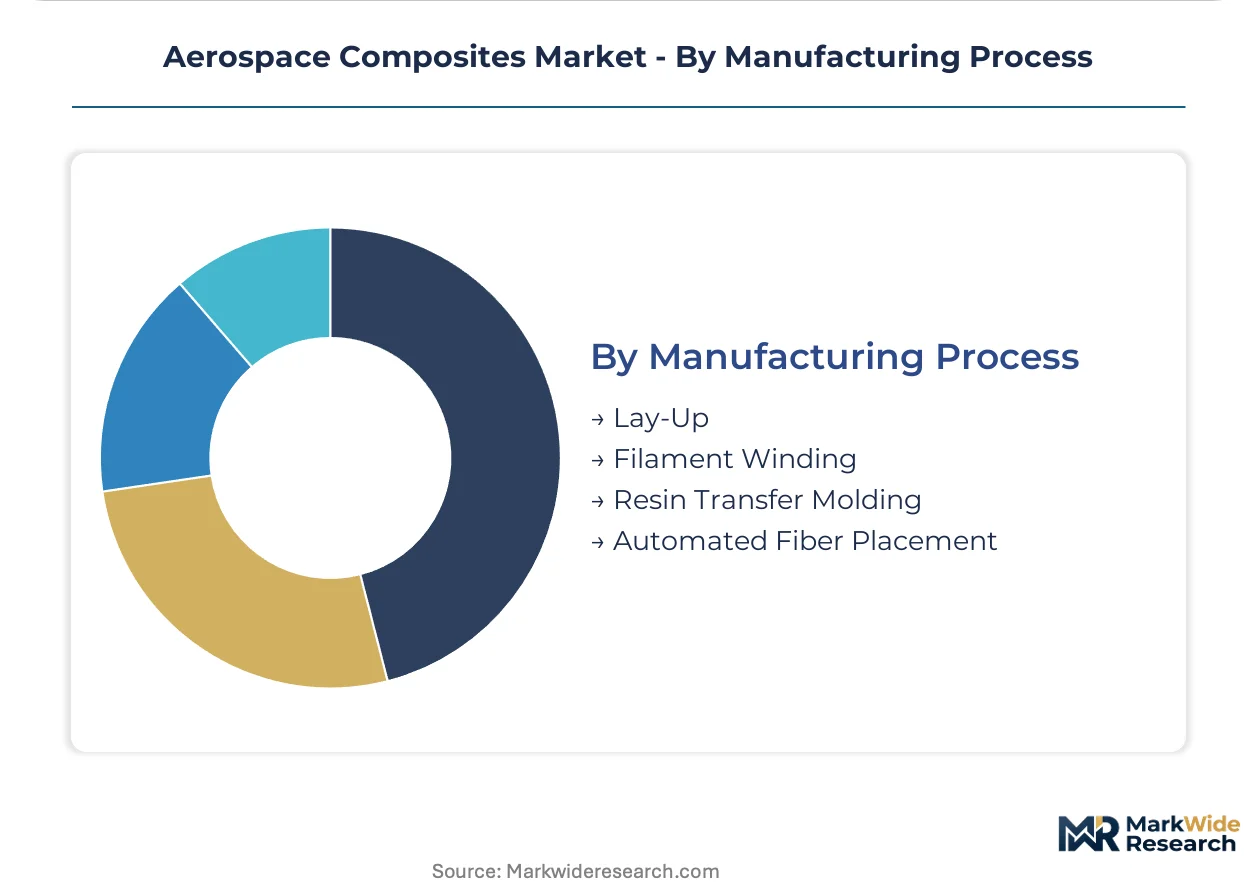
Manufacturing Process:
Capital intensity and technician certification requirements stratify supplier capability tiers across process categories.
- Automated Fiber Placement:Multi-axis robotic systems compress lay-up cycle times for complex geometries. Boeing 787 and Airbus A350 wing programs established AFP as the baseline for high-rate primary structures; equipment costs amortize across decade-long production contracts.
- Lay-Up:Hand lay-up persists in low-volume defense and business jet applications where tooling flexibility outweighs labor content. Skilled laminator scarcity constrains expansion at tier-2 suppliers lacking AFP capital access.
- Filament Winding:Pressure vessel and duct applications utilize continuous fiber deposition.
- Resin Transfer Molding:Closed-mold infusion reduces volatile organic compound exposure for large structural components.
AFP equipment separates qualified tier-1 suppliers; hand lay-up retains niche viability where program volumes resist capital deployment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies. The United States concentrates procurement for narrowbody programs under FAA Part 25 mandates, while European OEMs pursue thermoplastic pathways under EU Green Deal circularity rules. Asian markets split between defense indigenization and commercial supply chain integration.
United States
Boeing and Spirit AeroSystems anchor procurement for 737 MAX wing skins and fuselage sections. FAA damage tolerance standards compress material qualification timelines for primary structures. Wichita, Kansas hosts automated fiber placement clusters serving decade-long production backlogs.
France
Airbus A350 and A320neo programs concentrate thermoset prepreg demand at Toulouse and Nantes facilities. EASA continuing airworthiness regulations pressure accelerated adoption of out-of-autoclave cure cycles. The Nouvelle-Aquitaine region hosts prepreg qualification labs under EU Green Deal emissions benchmarks.
Japan
Toray, Teijin, and Mitsubishi Chemical anchor PAN-based carbon fiber precursor supply chains. METI industrial policy supports defense aerospace indigenization for F-X fighter programs. Nagoya industrial corridors concentrate AFP equipment manufacturing and technician training infrastructure.
Germany
Airbus Hamburg fuselage assembly drives thermoplastic welding trials for rib-to-skin joining. The F-Gas Regulation constrains solvent-based prepreg processing, favoring aqueous alternatives. Bavaria hosts automated consolidation R&D clusters serving Gulfstream and Dassault business jet programs.
India
HAL Tejas and AMCA programs create import-substitution demand for domestic prepreg qualification. DRDO specifications govern defense airframe material allowables development. Bangalore aerospace clusters concentrate hand-lay-up operations transitioning toward AFP capability.
Aerospace Composites Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier in aerospace composites supply. Japanese chemical conglomerates and US aerostructures fabricators occupy distinct vertical positions based on precursor control versus assembly integration. The competitive landscape sorts into three archetypes: carbon fiber precursor producers, prepreg formulators, and tier-1 aerostructures assemblers. Dominant competitive moves include capacity expansion in thermoplastic resin systems and strategic partnerships for out-of-autoclave process qualification.
Within the precursor-producer tier, Toray Industries and Mitsubishi Chemical Group exemplify integrated chemical conglomerates with backward control over PAN-based fiber supply. Hexcel Corporation occupies a position among US-based prepreg specialists serving FAA-qualified primary structure programs. Spirit AeroSystems anchors the aerostructures-assembly vector, representing tier-1 fabricators that assume design authority for composite detail parts.
| Leading Market Players |
|---|
| Mitsubishi Chemical Group Corporation |
| Gurit Holding AG |
| Toray Industries, Inc. |
| Spirit AeroSystems |
| Teijin Limited |
| Hexcel Corporation |
| SGL Carbon SE |
| Materion Corporation |
| Solvay SA |
| Others |
Supply Flow & Price Mechanics
Thermoplastic resin substitution for thermoset epoxy is redrawing procurement geography and compressing margin structures across supplier tiers. Japanese PAN-based precursor producers face pricing pressure as European OEMs requalify out-of-autoclave cure cycles under EU Green Deal circularity mandates.
Pricing Analysis
Long-term offtake contracts dominate primary structure procurement, with Boeing and Airbus locking in decade-spanning prepreg volumes at Spirit AeroSystems and GKN Aerospace. Price differentiation rests on FAA Part 25 certification tier and automated fiber placement capability access. Cost compression in hand-lay-up segments is intensifying because tier-2 suppliers lack capital for AFP equipment amortization. Defense programs show least price sensitivity due to ITAR-controlled supply chain mandates.
Supply Chain Analysis
Acrylonitrile feedstock transit through Strait of Malacca shipping lanes underwrites cost volatility for PAN-based carbon fiber precursors. Manufacturing concentrates in Japan, the United States, and France, with Toray Industries and Hexcel Corporation anchoring prepreg formulation. Raw material dependencies span acrylonitrile monomer, epoxy resin systems, and thermoplastic PEKK pellets. Single-source vulnerability concentrates in Japanese precursor supply. Distribution runs through tier-1 aerostructures assemblers holding design authority for composite detail parts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Aerospace composites markets reward service-attach models where aftermarket repair stations and MRO technical support expand faster than virgin material sales. Recurring revenue from certified repair procedures and technician training programs outpaces hardware growth rates.
For Market Incumbents: Fortify qualification moats by deepening backward integration into thermoplastic resin formulation and expanding AFP technician certification infrastructure at Wichita and Broughton clusters. Thermoset epoxy recyclability limits under EU Green Deal benchmarks threaten incumbent margin structures; out-of-autoclave process investment is the priority defensive lever.
For New Entrants and Emerging Players: Anchor in urban air mobility airframe segments where eVTOL manufacturers seek sub-Part-25 certification pathways for tilt-rotor hubs and battery enclosures. India defense indigenization offers the most penetrable geography, with HAL Tejas and AMCA programs creating import-substitution demand. A go-to-market angle through DRDO-qualified prepreg partnerships bypasses entrenched Boeing-Airbus supply tiers.
For Investors and Strategic Acquirers: Capital is best deployed toward mid-cap prepreg formulators with thermoplastic qualification pipelines and established FAA-EASA dual-certification track records. Long-term viability centers on consolidation plays across the analysis window as equipment amortization requirements bifurcate supplier capability bands. The signal to watch as inflection indicator is Airbus A350 follow-on program thermoplastic adoption rates.
| Strategic Initiative | Industry Significance |
|---|---|
| Thermoplastic Resin Qualification | PEKK and PEEK matrix approvals enable out-of-autoclave processing for Airbus wing programs. |
| AFP Equipment Deployment | Multi-axis robotic systems at Spirit AeroSystems compress Boeing 737 MAX manufacturing cycle times. |
| Technician Certification Expansion | FAA-approved AFP programming training closes capability gaps at tier-2 aerostructures suppliers. |
| Out-of-Autoclave Process Validation | EASA emissions benchmarks drive cure cycle requalification at Toulouse and Hamburg facilities. |
| Defense Supply Chain Indigenization | DRDO specifications for HAL Tejas create domestic prepreg demand in Bangalore aerospace clusters. |
Methodological Framework
Initial hypotheses were tested against primary input from aerostructures procurement directors, AFP equipment operators, composite materials engineers, and FAA certification specialists and refined through secondary validation. Bottom-up triangulation incorporated SEC filings from Hexcel Corporation and Toray Industries, EASA continuing airworthiness directives, and customs data on carbon fiber precursor trade flows. Top-down modeling cross-referenced FAA Part 25 type certification databases with production rate disclosures from Boeing and Airbus.
Variance decomposition across the projection horizon isolates volume drivers by aircraft program, resin system chemistry, and manufacturing process adoption curve. Segmentation dimensions span product type, application tier, end-user category, and regional regulatory cluster. CAGRs derive from production backlog amortization schedules and equipment installation rates. Forecast inputs include narrowbody delivery targets and thermoplastic welding trial outcomes at Airbus Hamburg.
Underlying assumptions cover sustained FAA-EASA regulatory convergence, with deviation risk concentrated in Japanese precursor supply disruptions and eVTOL certification pathway delays. Practitioners should keep alternative scenarios live as EU Green Deal circularity benchmarks and CAAC type certification timelines evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aerospace and Aircraft Materials
Aerogel Market
Aerospace and Aircraft Materials
Aerospace Foam Market
Aerospace and Aircraft Materials
Global Anti-Icing Coating Market
Aerospace and Aircraft Materials
Beryllium Aluminum Alloy Market
Aerospace and Aircraft Materials
Aircraft Soft Goods Market
Aerospace and Aircraft Materials
Titanium Aerospace Forgings Market
Aerospace and Aircraft Materials
Magnesium Beryllium Alloy Market
Aerospace and Aircraft Materials
Advanced Materials for Flying Cars Market
Aerospace and Aircraft Materials
Honeycomb Panel for Aircraft Market
Aerospace and Aircraft Materials
Aerospace and Defense Metal Stamping Market
Aerospace and Aircraft Materials
Global Aerospace Adhesives and Sealants Market
Aerospace and Aircraft Materials
Aerospace Radome Market
Aerospace and Aircraft Materials
Global Flame Retardant for Aerospace Plastics Market
Aerospace and Aircraft Materials
Radiation Shielding Market
Aerospace and Aircraft Materials
Russia Space Electronics Market
Aerospace and Aircraft Materials
Aerospace Plastics Market