
 Aerospace Ceramic Matrix Composites Market | 2026-2036
Aerospace Ceramic Matrix Composites Market Size, Share, and Industry Trends Forecast 2026-2036
Aerospace Ceramic Matrix Composites Market Outlook
Modular engine component bundling is restructuring how airframers and propulsion OEMs specify ceramic matrix composite procurement. GE Aerospace dominates the high-pressure turbine segment through captive manufacturing scale. Rolls-Royce plc anchors its UltraFan program with sustained R&D intensity in oxide-oxide CMC architectures. Safran differentiates via specialized leap engine shroud production for narrowbody platforms.
Aerospace ceramic matrix composites are fiber-reinforced ceramic systems, typically silicon carbide fibers embedded in silicon carbide or oxide matrices, engineered to withstand temperatures exceeding 1200°C while maintaining structural integrity under oxidative conditions; they serve primarily as lightweight replacements for nickel superalloys in hot-section engine components and thermal protection systems. Engine Components command the deepest margin pools due to qualification barriers and long-term supply agreements with propulsion OEMs. Structural Components within the Airframes application compete on weight reduction metrics against polymer matrix alternatives. Military Aviation end users leverage classified performance specifications that sustain premium pricing tiers.
FAA certification standards under Part 33 govern CMC durability in commercial propulsion systems, while EASA CS-E frames equivalent European airworthiness requirements for engine hot-section materials. The EPA's greenhouse gas emissions rules for aircraft indirectly shape CMC demand by pressuring fuel efficiency improvements that lighter hot-section components enable. Stakeholders must monitor evolving MEE dual carbon goals in China and their potential to redirect supply chain qualification resources toward domestic certification pathways.
Market Dynamics
Modular engine component bundling is restructuring procurement patterns among commercial aviation OEMs, forcing suppliers to qualify for multi-part contracts rather than single-component orders. This consolidation concentrates purchasing power with propulsion integrators while raising barriers for specialty CMC producers.
Growth Catalysts
- EPA greenhouse gas emissions rules:Aircraft CO2 limits pressure fuel efficiency improvements that lighter hot-section components enable. Propulsion OEMs specify CMC turbine shrouds to reduce engine weight.
- Silicon carbide fiber production scale-up:Domestic manufacturing investments in the United States lower input costs for SiC-SiC composite systems. Qualification volumes for narrowbody engine programs accelerate.
- Military thermal protection systems:Classified hypersonic vehicle programs sustain premium pricing tiers for oxide-oxide architectures. Defense procurement channels bypass commercial certification timelines.
Market Restraints
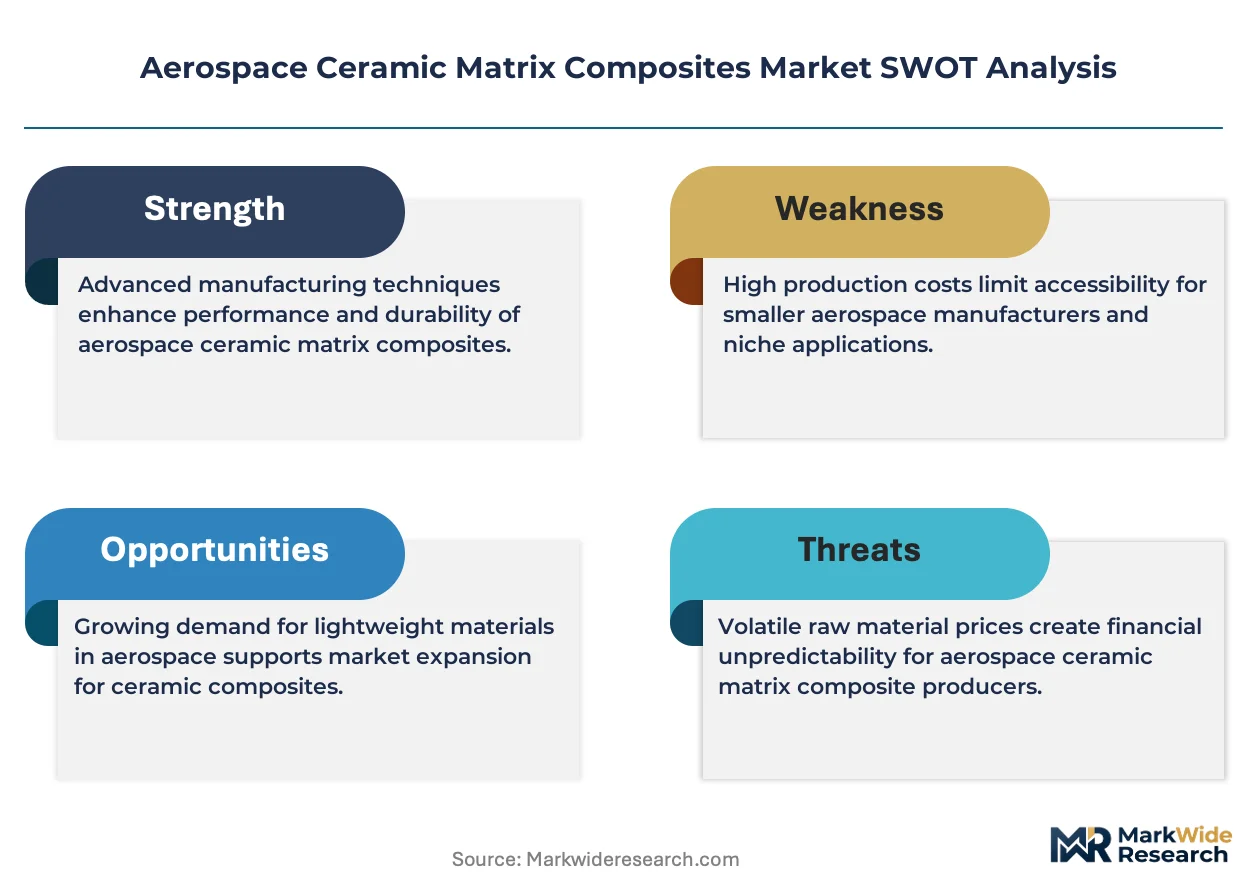
- Silicon carbide fiber supply concentration:Japanese producers dominate high-purity SiC fiber output, creating single-source vulnerability for Western CMC manufacturers. Geopolitical friction threatens qualification continuity.
- FAA Part 33 certification duration:Airworthiness validation for new CMC formulations requires 8-12 year test cycles. Development costs amortize across limited production volumes.
- Nickel superalloy incumbent performance:Established turbine blade coatings and cooling architectures delay CMC substitution in intermediate temperature zones. Legacy supply chains resist material switching.
Strategic Opportunities
- Urban air mobility thermal management:Electric vertical takeoff aircraft battery enclosures and motor housings require lightweight fire containment. Oxide CMC architectures penetrate this nascent segment.
- Japan METI carbon neutrality roadmap:Domestic engine development incentives redirect supply chain qualification resources toward indigenous certification pathways. Local CMC production partnerships gain policy support.
- Additive manufacturing convergence:Ceramic matrix deposition techniques merge with fiber placement automation. Hybrid processes reduce machining scrap rates in complex turbine vane geometries.
Industry Challenges
- Non-destructive evaluation technician scarcity:Ultrasonic and thermographic inspection of CMC components requires specialized training pipelines. OEMs compete for limited qualified personnel.
- Legacy MRO infrastructure incompatibility:Existing engine overhaul facilities lack ceramic repair stations and brazing equipment. Fleet transition demands parallel supply chain construction.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aerospace Ceramic Matrix Composites Market |
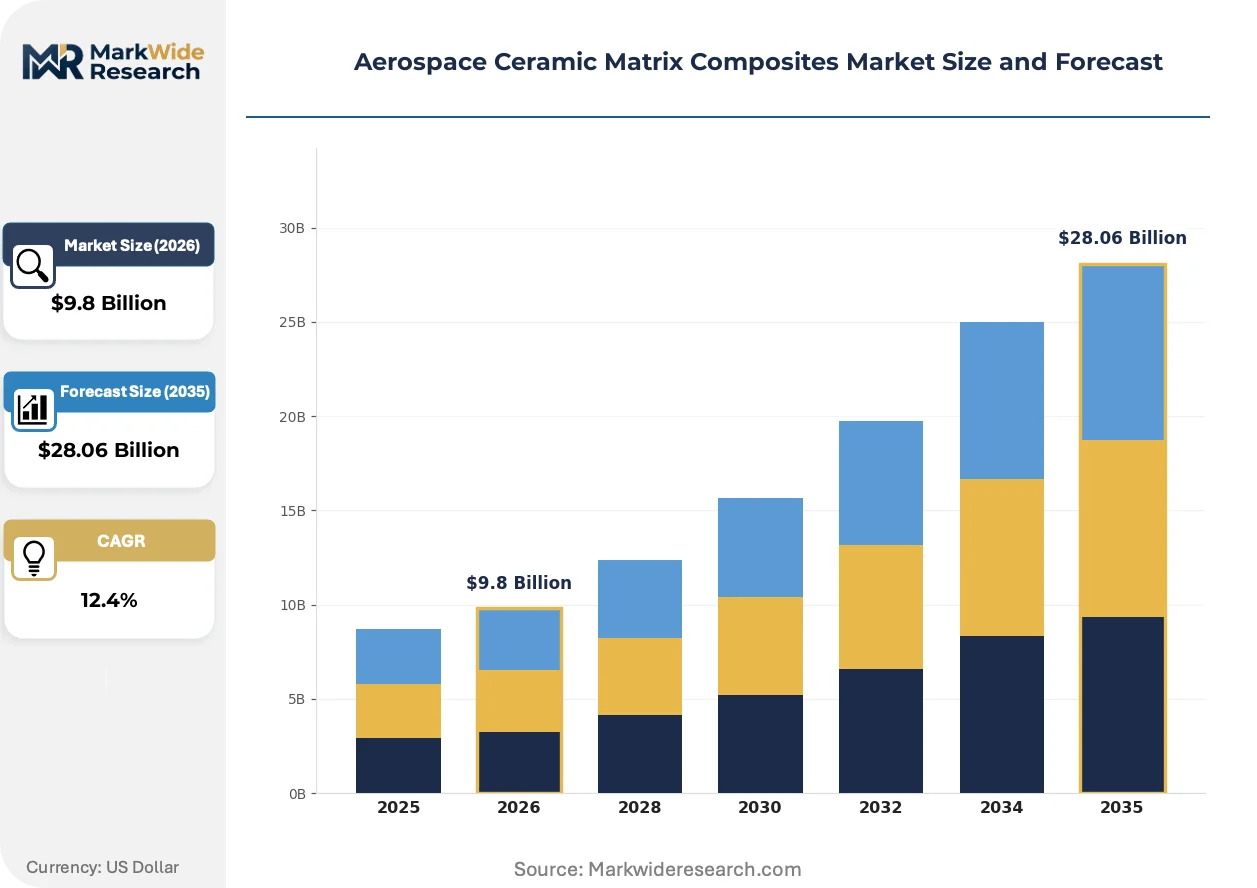
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $28.06 Billion |
| CAGR (2026 – 2036) | 12.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reinforced Ceramics, Prepreg Composites, Multifunctional Ceramics, Engine Components Application: Airframes, Engine Parts, Thermal Protection Systems, Structural Components End User: Commercial Aviation, Military Aviation, Space Exploration, UAVs Manufacturing Stage: Raw Material Processing, Forming, Curing, Machining |
| Companies Covered | GE Aerospace, Rolls-Royce plc, CoorsTek Inc., Safran, Mitsubishi Chemical Group Corporation, Axiom Materials, Ultramet, SGL Carbon, Spirit AeroSystems, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aerospace Ceramic Matrix Composites Market Strategic Shifts
Active matrix development is compressing qualification timelines while regulatory pressure on emissions intensifies material substitution. Three converging developments are restructuring competitive positioning in aerospace CMC supply.
Environmental barrier coatings are absorbing thermal cycling loads that previously degraded SiC-SiC substrates in combustion environments. Narrowbody engine OEMs now specify EBC-protected shrouds as standard for next-generation turbofans. This protective layer is absorbing margin pressure from raw fiber suppliers by extending component service intervals and reducing warranty exposure.
EASA CS-E amendments tighten airworthiness requirements for engine hot-section materials exposed to oxidative degradation above 1200°C. European propulsion manufacturers accelerate oxide-oxide CMC development to preempt compliance gaps. French certification authorities coordinate with Safran to establish precedent for leap engine shroud architectures under revised thermal endurance protocols.
Long-term supply agreements now bundle multi-component engine contracts rather than discrete material purchases. Tier-one propulsion integrators consolidate specification authority while specialty CMC producers accept volume commitments in exchange for qualification investment. This contractual evolution is most visible in United States narrowbody programs where GE Aerospace anchors procurement through captive manufacturing scale.
Aerospace Ceramic Matrix Composites Market Segmentation
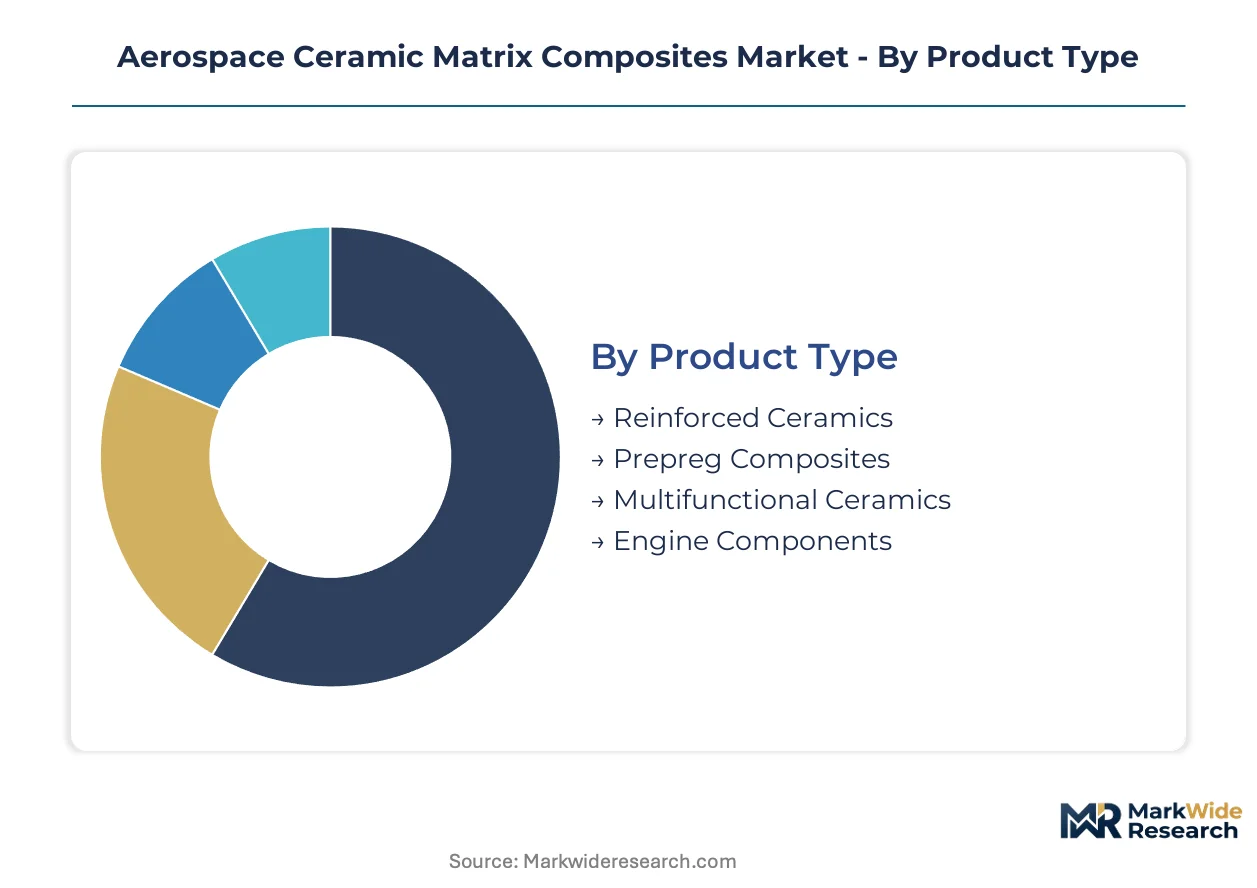
Ceramic matrix composite procurement patterns diverge sharply across product architectures, application temperatures, and end-user certification requirements. Each segmentation axis carries distinct margin profiles, qualification barriers, and supply chain configurations that shape supplier strategy.
Product Type:
Buyer differentiation hinges on thermal performance thresholds and fiber-matrix integration complexity rather than commodity pricing.
- Engine Components:SiC-SiC and oxide-oxide architectures withstand combustion environments exceeding 1200°C. Commercial propulsion OEMs in the United States and France specify these for high-pressure turbine shrouds, with qualification timelines spanning 8-12 years under FAA Part 33 protocols.
- Reinforced Ceramics:Continuous fiber reinforcement in ceramic matrices delivers damage tolerance for thermal protection systems. Military hypersonic vehicle programs sustain premium pricing tiers through classified performance specifications that bypass commercial certification.
- Prepreg Composites:Pre-impregnated fiber tapes enable automated layup for complex aerostructures.
- Multifunctional Ceramics:Integrated thermal-structural-electromagnetic properties serve specialized satellite components.
Volume sits with Engine Components; growth tilts toward Multifunctional Ceramics.
Application:
Temperature exposure and aerodynamic loading separate applications into hot-section versus structural substitution opportunities.
- Engine Parts:Turbine vanes, combustor liners, and shrouds replace nickel superalloys in the hottest zones. EASA CS-E amendments tightening oxidative degradation requirements above 1200°C accelerate oxide-oxide CMC development for European propulsion manufacturers.
- Thermal Protection Systems:Reusable insulation panels and leading-edge shields manage extreme heat flux during atmospheric entry. Space Exploration end users in the United States drive specification evolution for oxide-oxide architectures in reusable launch vehicles.
- Airframes:Control surfaces and access panels compete with polymer matrix alternatives on weight reduction metrics.
- Structural Components:Load-bearing brackets and struts exploit CMC stiffness-to-weight ratios in military platforms.
Margins concentrate in Engine Parts; adoption expands most quickly in Thermal Protection Systems.
End User:
Certification pathway and procurement authority distinguish defense-classified programs from commercial airworthiness frameworks.
- Commercial Aviation:Narrowbody and widebody propulsion OEMs dominate procurement through multi-component bundling contracts. EPA greenhouse gas emissions rules pressure fuel efficiency improvements that lighter hot-section components enable.
- Military Aviation:Fighter engine and hypersonic programs operate under classified specifications with accelerated development timelines. Defense procurement channels bypass FAA and EASA certification requirements.
- Space Exploration:Reusable launch vehicle operators specify thermal protection for booster recovery systems.
- UAVs:High-altitude long-endurance platforms require lightweight hot-section materials for turbine propulsion.
Procurement scale favors Commercial Aviation; contract velocity runs highest in Military Aviation.
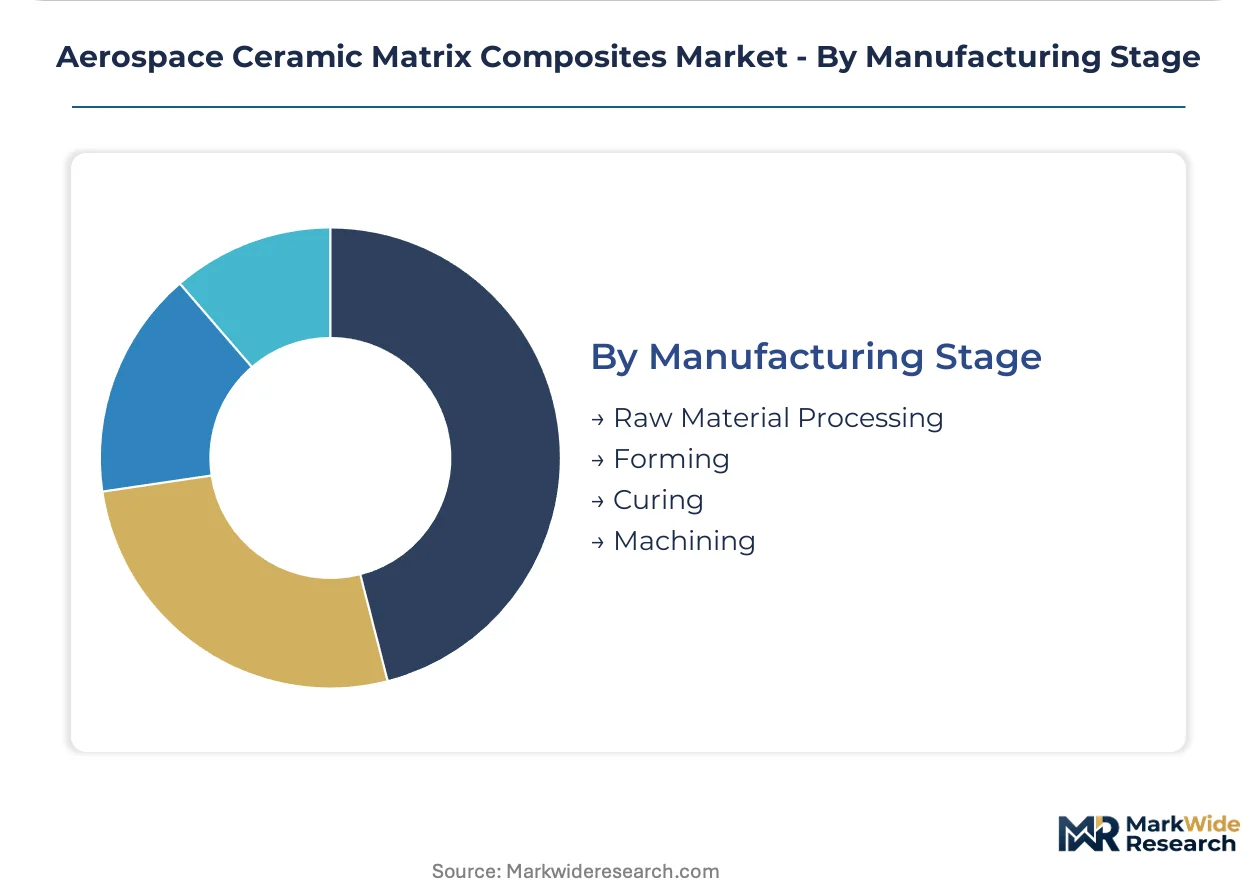
Manufacturing Stage:
Capital intensity and technical specialization concentrate competitive advantage at specific value chain positions.
- Raw Material Processing:High-purity silicon carbide fiber production anchors cost structures for SiC-SiC systems. Japanese producers dominate this segment, creating single-source vulnerability for Western CMC manufacturers.
- Forming:Chemical vapor infiltration and melt infiltration processes densify fiber preforms into ceramic matrices. Additive manufacturing convergence with fiber placement automation is compressing lead times for complex turbine vane geometries.
- Curing:High-temperature pyrolysis and sintering cycles transform precursors into ceramic phases.
- Machining:Diamond grinding and ultrasonic machining finish components to tight tolerances.
Value capture peaks at Raw Material Processing; process innovation concentrates in Forming.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production of silicon carbide fibers concentrates in Japan while fabrication of finished CMC components clusters in the United States and France. Engine OEMs in these markets drive specification standards that shape global procurement patterns. Military and space applications sustain additional demand pockets in the United Kingdom and Germany.
United States
GE Aerospace anchors domestic demand through captive manufacturing scale for high-pressure turbine components. FAA Part 33 certification protocols govern airworthiness validation timelines for new CMC formulations. Cincinnati and Evendale, Ohio host concentrated propulsion engineering clusters where qualification testing for narrowbody engine programs accelerates.
France
Safran drives specification evolution through specialized LEAP engine shroud production for Airbus narrowbody platforms. EASA CS-E amendments tightening oxidative degradation requirements above 1200°C accelerate oxide-oxide CMC development. The Toulouse-Paris corridor concentrates propulsion manufacturing where French certification authorities coordinate precedent-setting thermal endurance protocols.
Japan
Mitsubishi Chemical Group Corporation and Nippon Carbon dominate high-purity silicon carbide fiber output, creating single-source vulnerability for Western manufacturers. METI carbon neutrality roadmaps redirect supply chain qualification resources toward indigenous certification pathways. Nagoya and Tokyo-Yokohama clusters anchor domestic engine development incentives that support local CMC production partnerships.
United Kingdom
Rolls-Royce plc sustains R&D intensity in oxide-oxide CMC architectures through its UltraFan program and military propulsion contracts. Defense procurement channels bypass commercial FAA and EASA certification timelines for classified hypersonic applications. Derby and Bristol host concentrated aerospace engineering centers where thermal protection system specifications evolve for next-generation combat aircraft.
Germany
SGL Carbon anchors European carbon and ceramic fiber production serving both commercial and defense CMC supply chains. REACH chemical regulations and EU Green Deal emissions frameworks pressure material substitution toward lighter hot-section components. Bavaria and North Rhine-Westphalia concentrate automotive-aerospace crossover manufacturing where chemical vapor infiltration expertise transfers between sectors.
Aerospace Ceramic Matrix Composites Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across multiple value chain positions. The vendor base stratifies between captive engine OEM manufacturing arms and independent material suppliers serving tier-one propulsion integrators. Three archetypes dominate: vertically integrated aerospace primes controlling specification authority, specialty ceramic fiber producers commanding raw material scarcity premiums, and mid-scale fabricators qualifying for multi-component bundling contracts. Consolidation pressure intensifies through long-term supply agreements that bundle turbine shrouds, combustor liners, and vane assemblies into single procurement awards.
Within the captive manufacturing tier, GE Aerospace and Rolls-Royce plc exemplify specification authority concentration through in-house CMC production for proprietary engine platforms. Among independent material specialists, CoorsTek Inc. and SGL Carbon occupy positions as ceramic systems fabricators serving multiple propulsion OEMs under qualification-dependent contracts. Safran represents the European integrated model combining airframe partnerships with specialized LEAP engine component production.
| Leading Market Players |
|---|
| GE Aerospace |
| Rolls-Royce plc |
| CoorsTek Inc. |
| Safran |
| Mitsubishi Chemical Group Corporation |
| Axiom Materials |
| Ultramet |
| SGL Carbon |
| Spirit AeroSystems, Inc. |
| Others |
Value Chain & Pricing Dynamics
Specialized non-destructive evaluation technicians concentrated in Cincinnati, Ohio and Derby, United Kingdom widen pricing-tier spreads between premium-qualified and standard-grade ceramic matrix composite suppliers. Labor-cost differentials between these certification-heavy regions and emerging fabrication centers compress margins on commoditized prepreg products while sustaining premiums for FAA-validated engine components.
Pricing Analysis
Margin tightening in standard-grade reinforced ceramics reflects Japanese silicon carbide fiber supply concentration and volatile pyrolysis energy costs. Three-tier pricing structure across premium, standard, and economy levels separates FAA Part 33-certified engine shrouds from commercial thermal protection panels and uncertified prototype materials. Cost-down pressure on economy-tier prepreg accelerates as Chinese oxide-oxide alternatives penetrate satellite component applications. Commercial aviation OEMs exhibit highest price sensitivity due to multi-component bundling contract structures, while military hypersonic programs accept premium pricing for classified performance specifications.
Supply Chain Analysis
Japan METI domestic-content mandates and U.S. Buy American provisions for defense procurement reshape sourcing toward indigenous fiber production partnerships. High-purity silicon carbide fiber concentrates in Japan, finished CMC fabrication clusters in the United States and France, and carbon precursor processing anchors in Germany. Raw material dependencies rest on high-purity silicon carbide fibers, environmental barrier coating precursors, and specialized pyrolysis furnace equipment. Single-source vulnerability from Japanese SiC fiber dominance threatens qualification continuity amid geopolitical friction. Distribution runs through long-term supply agreements bundling turbine shrouds, combustor liners, and vane assemblies directly to tier-one propulsion integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The aerospace ceramic matrix composites market is a vertical-integration race where upstream fiber production and downstream qualification authority determine margin capture. Players pursue in-house silicon carbide fiber production to escape Japanese supply concentration and secure specification control.
For Market Incumbents: Deepen captive manufacturing scale in high-pressure turbine components to defend against emerging oxide-oxide specialists. Lock in 10-15 year qualification pipelines with FAA and EASA before regulatory amendments tighten thermal endurance protocols. Acquire specialized non-destructive evaluation firms to secure scarce technician pools in Cincinnati and Evendale clusters. For New Entrants and Emerging Players: Tier-two propulsion suppliers represent the most penetrable channel partner type for qualifying alternative SiC fiber sources. Target urban air mobility thermal management applications where oxide CMC battery enclosures bypass traditional engine certification timelines. Pursue joint development agreements with electric vertical takeoff aircraft manufacturers seeking lightweight fire containment solutions. For Investors and Strategic Acquirers: The window for entry favors mid-scale fabricators with existing EASA CS-E qualification momentum. Long-term viability hinges on securing positions before FAA Part 33 revisions extend validation cycles. Watch for Japan METI carbon neutrality roadmap implementation as the signal indicating indigenous certification pathway redirection and domestic partnership opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into SiC Fiber Production | GE Aerospace's captive manufacturing scale insulates against Japanese supply concentration and secures cost control. |
| Environmental Barrier Coating Development | Safran's EBC-protected LEAP shrouds extend service intervals and reduce warranty exposure under EASA thermal protocols. |
| Urban Air Mobility Thermal Management Entry | Oxide-oxide CMC architectures penetrate electric vertical takeoff aircraft battery enclosures without engine certification barriers. |
| Long-term Multi-Component Supply Agreements | Rolls-Royce consolidates turbine shroud, combustor liner, and vane procurement into single awards raising barriers for specialty producers. |
| Additive Manufacturing Convergence | Hybrid ceramic matrix deposition with fiber placement automation reduces machining scrap in complex turbine vane geometries. |
Study Parameters
Independent corroboration across propulsion OEM procurement executives, ceramic fiber production engineers, FAA certification specialists, and thermal protection system program managers underwrites the qualitative findings. Primary interviews with tier-one engine integrators and specialty CMC fabricators combined with secondary validation from FAA Part 33 airworthiness directives, EASA CS-E amendment filings, SEC 10-K aerospace segment disclosures, and Japan METI carbon neutrality policy documents. Bottom-up segment sizing triangulates against top-down propulsion OEM procurement forecasts.
Rate-of-change decomposition separates volume growth from price-mix effects across the projection horizon. Segmentation dimensions modeled include product architecture, application temperature exposure, end-user certification pathway, and manufacturing stage value capture position. CAGRs derive from installed base expansion of narrowbody engine programs, fleet retirement-replacement dynamics, and military hypersonic vehicle development intensity. Industry-specific forecast inputs incorporate silicon carbide fiber production capacity announcements and EASA thermal endurance protocol revision timelines.
Caveats apply where FAA certification duration extensions, Japanese export restriction impositions, or breakthrough nickel superalloy coating advances could materially shift the outlook. Forecasts reflect assumptions regarding continued EPA greenhouse gas emissions rule stringency and sustained defense procurement for classified thermal protection systems. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aerospace and Aircraft Materials
Aluminum Titanate Market
Aerospace and Aircraft Materials
Global AFP/ATL Machines Market
Aerospace and Aircraft Materials
Fiberglass for Aerospace Market
Aerospace and Aircraft Materials
Aircraft Coatings Market
Aerospace and Aircraft Materials
Aerospace and Defense Metal Stamping Market
Aerospace and Aircraft Materials
Aeroengine Composites Market
Aerospace and Aircraft Materials
Global Aerospace Adhesives Market
Aerospace and Aircraft Materials
Aerospace Composites Market
Aerospace and Aircraft Materials
Aerospace Fasteners Market
Aerospace and Aircraft Materials
Aerographite Market
Aerospace and Aircraft Materials
Aerographene Market
Aerospace and Aircraft Materials
Aerospace Carbon Fiber Market
Aerospace and Aircraft Materials
Magnesium Beryllium Alloy Market
Aerospace and Aircraft Materials
Ablative Coatings Market
Aerospace and Aircraft Materials
Aircraft AFP and ATL Composites Market
Aerospace and Aircraft Materials
Aircraft Insulation Materials Market