
 Magnesium Beryllium Alloy Market | 2026-2036
Magnesium Beryllium Alloy Market Size, Share, and Industry Trends Forecast 2026-2036
Magnesium Beryllium Alloy Market Intelligence
REACH is decoupling legacy supply chains from European defense and aerospace markets. Materion Corporation anchors North American supply through captive refining and controlled distribution of beryllium master alloys. Boeing Company dominates airframe qualification pathways, leveraging decades of in-house metallurgy data. Alcoa Corporation sustains primary magnesium integration from smelter to mill product, reducing feedstock cost volatility.
Magnesium beryllium alloys combine magnesium's low density with beryllium's elastic modulus advantage, typically formulated at beryllium contents below three percent to balance stiffness with ductility. Vacuum induction melting followed by inert atmosphere casting prevents oxide contamination critical for aerospace fatigue performance. Cast alloys occupy the mature defense electronics housing segment where legacy specifications resist substitution. Wrought alloys represent the fastest-growing category as airframers pursue sheet and extrusion solutions for satellite structures. Powder alloys attract research institution funding for additive manufacturing qualification, though margin pools remain thin without production scale.
EPA beryllium standards and OSHA permissible exposure limits shape worker protection costs across US fabrication facilities. ECHA's beryllium substance evaluation under REACH restricts import pathways for non-EU smelters. China's SAMR enforces GB standards on beryllium content labeling and waste handling for domestic processors. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded inventory or redundant certification investments.
Market Dynamics
REACH substance evaluation is decoupling legacy supply chains from European defense and aerospace markets, forcing qualification pathway reinvention around Stuttgart and Munich engineering clusters.
Growth Catalysts
- Aerospace OEM procurement:Airframe manufacturers are expanding wrought alloy specifications for satellite structures and lightweight assemblies.
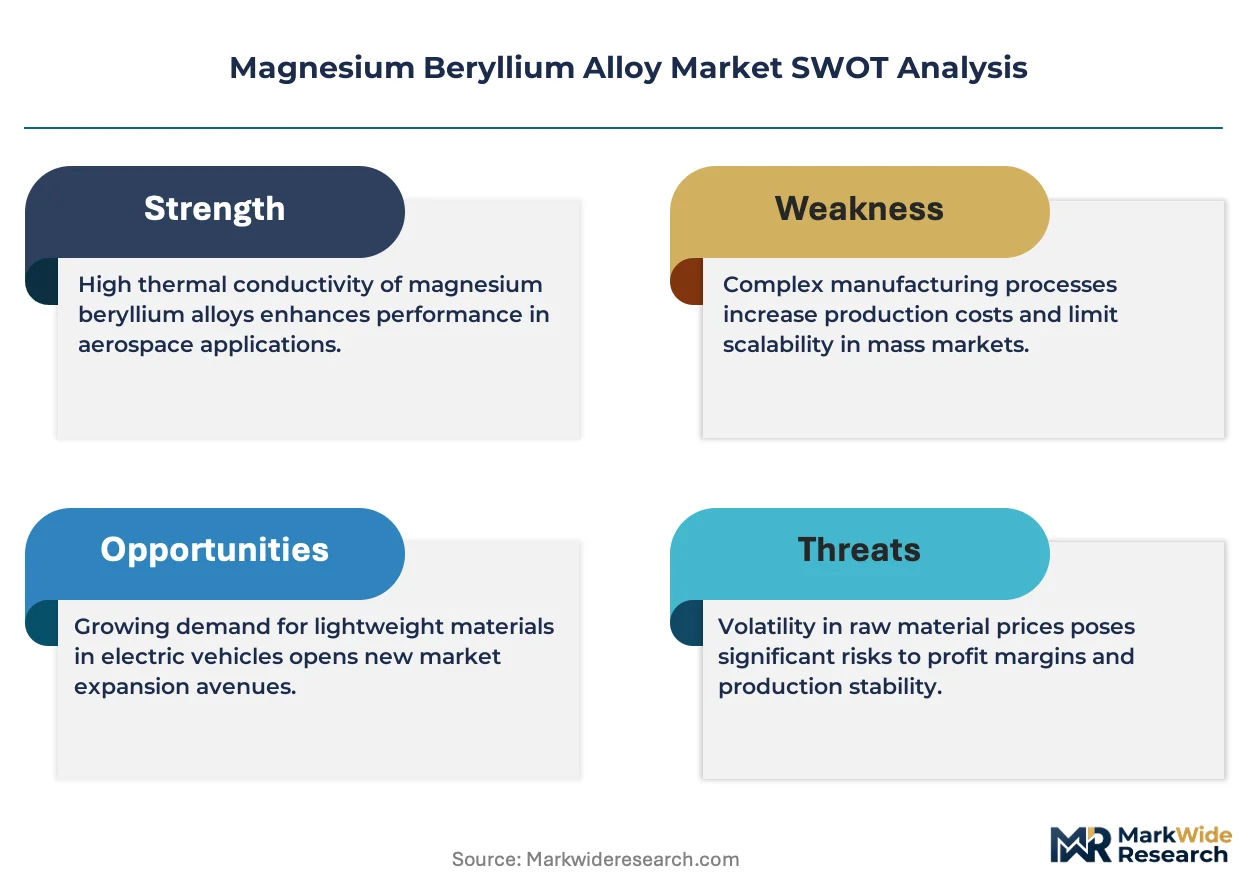
- REACH compliance differentiation:Materion Corporation's captive refining infrastructure creates regulatory moats against non-EU smelters facing ECHA import restrictions.
- Additive manufacturing research:Powder alloy qualification programs at US national laboratories are accelerating deposition process development for complex geometries.
Market Restraints
- Beryllium feedstock concentration:Spor Mountain, Utah deposits supply the majority of US primary beryllium, creating single-point-of-failure exposure for North American alloy producers.
- OSHA permissible exposure limits:Worker protection costs at fabrication facilities impose structural cost premiums versus competing lightweight alloys.
- Aluminum-lithium substitution:Airbus and Boeing qualification of Al-Li alloys for wing skins compresses addressable market for magnesium beryllium in secondary structures.
Strategic Opportunities
- China domestic certification:SAMR enforcement of GB standards on beryllium content labeling creates first-mover advantage for compliant Western suppliers establishing joint ventures.
- Dual-use technology convergence:Satellite miniaturization trends are merging commercial space demand with legacy defense electronics housing specifications.
- Scrap circularity infrastructure:Vacuum induction remelting capabilities for aerospace-grade chip and turnings recovery remain underdeveloped across European precision engineering corridors.
Industry Challenges
- Metallurgical talent scarcity:Vacuum induction melting expertise for reactive metal handling is concentrating among retiring cohorts at legacy defense contractors.
- Airframe qualification timelines:Boeing and Airbus fatigue test protocols for new alloy compositions extend certification cycles beyond typical capital planning horizons.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Magnesium Beryllium Alloy Market |
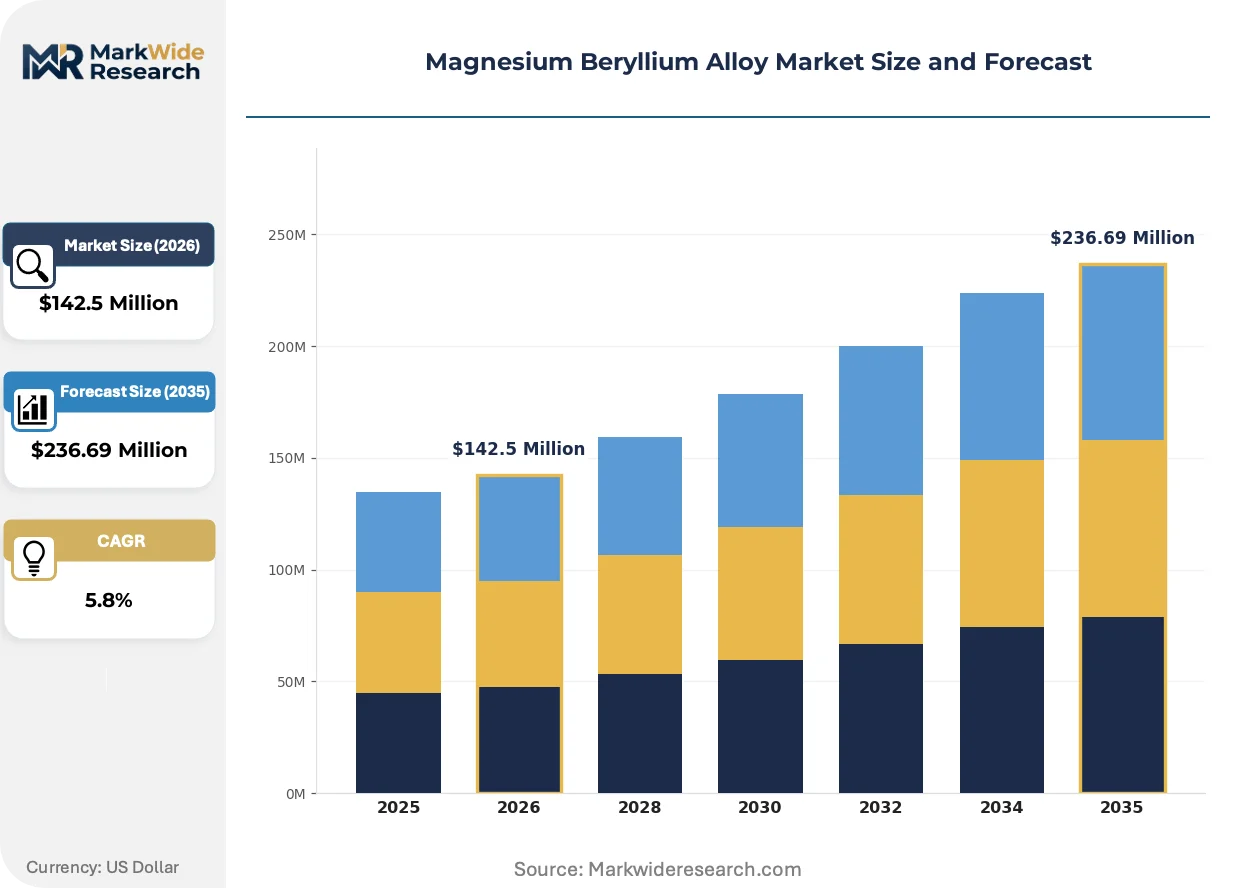
| Market Size in 2026 | $142.5 Million |
| Market Size in 2035 | $236.69 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cast Alloys, Wrought Alloys, Powder Alloys, Composite Alloys Application: Aerospace, Automotive, Defense, Medical Devices End User: Manufacturers, OEMs, Tier-1 Suppliers, Research Institutions Form: Sheets, Bars, Extrusions, Machined Parts |
| Companies Covered | Materion Corporation, Alcoa Corporation, Boeing Company, Lockheed Martin Corporation, Special Metals Corporation, North American Tungsten Corporation, Xiamen Tungsten Co, Zhongwei Special Alloy Co, Rare Element Resources Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Magnesium Beryllium Alloy Market Strategic Shifts & Innovations
Process automation and regulatory fragmentation are simultaneously compressing production economics and expanding compliance complexity across magnesium beryllium value chains.
Vacuum arc remelting is modularizing quality assurance for high-performance wrought alloys. Satellite manufacturers in California and Colorado are adopting VAR-processed billets for reduced oxide inclusion risk. This technology is modularizing supplier qualification pathways by decoupling primary smelting from final alloy specification.
ECHA's beryllium substance evaluation under REACH is restricting import pathways for Turkish and Kazakh smelters without captive refining. European defense primes are responding by consolidating procurement around Materion's Elmore, Ohio facility. German precision engineering clusters around Stuttgart face extended lead times as alternative qualification data is regenerated.
Specification-driven vendor consolidation is compressing approved supplier lists at tier-one airframers. Long-term alloy purchase agreements with minimum volume commitments are displacing spot market transactions. This pattern is most visible in Boeing's supply base, where dual-source requirements are being waived for qualified single-source wrought alloy providers.
Magnesium Beryllium Alloy Market Segmentation
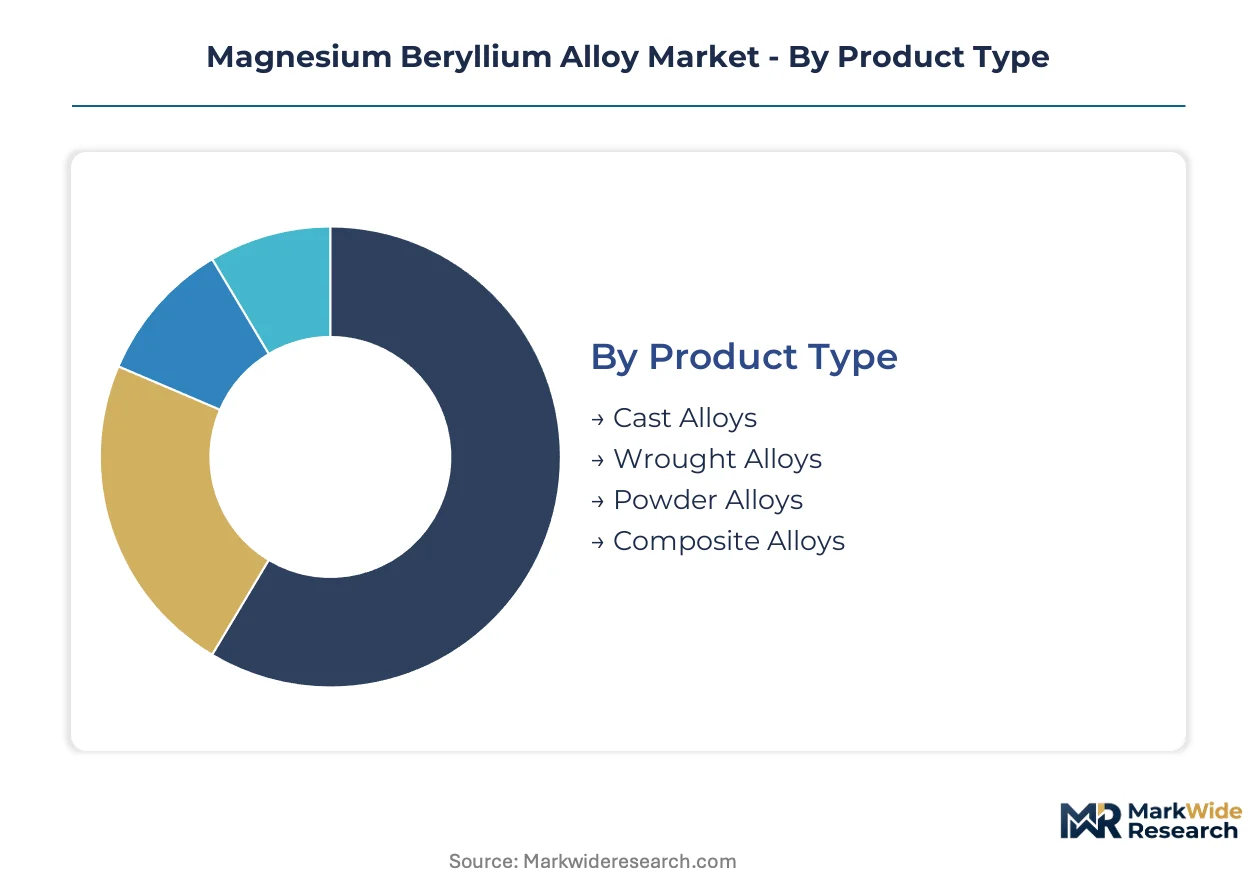
Segmentation in magnesium beryllium alloys tracks how processing method, application risk tolerance, and supply chain position allocate margin pools across radically different qualification barriers. Buyers sort by metallurgical pedigree and regulatory exposure rather than commodity pricing.
Product Type:
Procurement teams select product type based on fatigue performance requirements and airframe qualification status rather than unit cost.
- Wrought Alloys:Vacuum arc remelted billets yield sheet and extrusion products with oxide inclusion levels below aerospace fatigue thresholds. Boeing and satellite manufacturers in California concentrate specifications here as airframers pursue lightweight primary structures.
- Cast Alloys:Inert atmosphere casting of legacy compositions dominates defense electronics housings where decades-old specifications resist substitution. Demand concentrates in Utah and Ohio defense corridors where Materion maintains captive refining for controlled beryllium distribution.
- Powder Alloys:Gas atomized preforms attract additive manufacturing research at US national laboratories.
- Composite Alloys:Discontinuous beryllium reinforcement in magnesium matrices remains experimental.
Volume sits with Cast Alloys; growth tilts toward Wrought Alloys.
Application:
Application selection hinges on beryllium exposure justification versus aluminum-lithium substitution feasibility.
- Aerospace:Satellite structures and airframe secondary assemblies exploit the stiffness-to-density ratio for launch mass constraints. Stuttgart and Munich precision engineering clusters face extended lead times as ECHA REACH compliance forces supply chain reinvention around Materion's captive refining.
- Defense: Electronics housings and missile guidance structures rely on cast alloy legacy specifications with minimal substitution risk. China's SAMR enforcement of GB standards on beryllium content labeling is tightening certification protocols for Western joint ventures.
- Automotive:Motorsport and hypercar applications absorb limited volumes where cost thresholds permit.
- Medical Devices:X-ray window applications exploit beryllium's transparency to low-energy radiation.
Defense commands the installed base; Aerospace captures the steepest expansion trajectory.
End User:
End user category determines qualification data ownership and long-term agreement structure.
- OEMs:Boeing and Airbus retain in-house metallurgy data spanning decades of fatigue testing, enabling proprietary alloy specifications that lock out non-qualified suppliers.
- Tier-1 Suppliers:Precision forgers and extruders in Germany's Stuttgart corridor face stranded inventory risks as ECHA substance evaluation restricts Turkish and Kazakh smelter pathways.
- Research Institutions:Powder alloy qualification programs at national laboratories accelerate deposition process development without production scale economics.
- Manufacturers:Fabrication facilities absorb OSHA compliance costs for worker protection at permissible exposure limits.
Procurement authority concentrates with OEMs; research funding flows toward national laboratories.
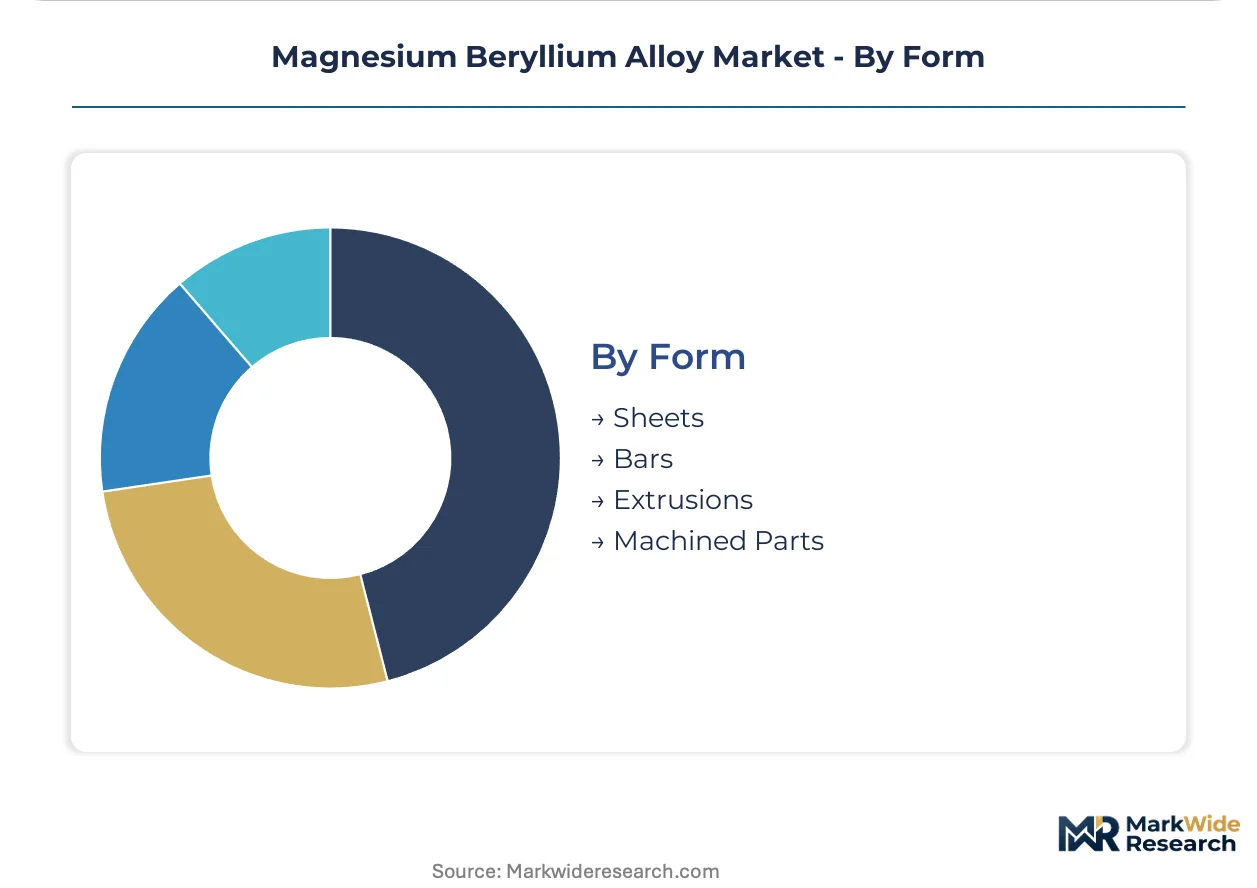
Form:
Form selection follows downstream processing method and scrap recovery economics.
- Extrusions:Complex cross-sections for satellite structural members require vacuum induction melting expertise concentrated among retiring cohorts at legacy defense contractors.
- Sheets:Rolled plate products for airframe skins compete directly with Al-Li alloy substitution pressure from Airbus qualification programs.
- Bars:Billet stock for precision machining of defense electronics housings maintains steady demand.
- Machined Parts:Finished components with certified chip and turnings recovery remain underdeveloped across European precision engineering corridors.
Sheet volume dominates airframe contracts; extrusion complexity commands premium positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Procurement of magnesium beryllium alloys concentrates in aerospace and defense corridors where fatigue performance requirements justify beryllium exposure costs. Demand clusters around Stuttgart and Munich in Germany, Spor Mountain in Utah, and emerging precision engineering zones in China.
United States
Aerospace OEMs in California and Colorado drive wrought alloy specifications for satellite structures. OSHA permissible exposure limits shape worker protection costs at fabrication facilities nationwide. The Spor Mountain deposit in Utah anchors North American primary beryllium supply, creating single-point concentration for alloy producers.
Germany
Precision engineering clusters around Stuttgart and Munich face extended lead times as ECHA REACH substance evaluation restricts Turkish and Kazakh smelter import pathways. The country's national materials regulator enforces stringent certification protocols under EU frameworks. German defense primes are consolidating procurement around captive refining infrastructure to bypass stranded inventory risks.
China
SAMR enforcement of GB standards on beryllium content labeling tightens certification protocols for domestic processors and Western joint ventures. The country's dual carbon goals pressure energy-intensive vacuum induction melting operations. Yangtze River Delta precision manufacturers are absorbing compliance costs to maintain aerospace export qualification.
Japan
METI-funded research institutions accelerate powder alloy qualification for additive manufacturing deposition processes. The country's national industrial standards body maintains rigorous fatigue test protocols that extend certification cycles. Osaka-based precision forgers specialize in defense electronics housing specifications with minimal substitution risk.
United Kingdom
Airbus wing skin qualification programs in Bristol and Broughton compress addressable market for magnesium beryllium in secondary structures. The country's health and safety executive enforces worker exposure limits aligned with EU OSHA benchmarks. Scottish research corridors attract powder alloy development funding without production scale economics.
Magnesium Beryllium Alloy Market Key Industry Players
North American producers anchor the integrated smelting tier; German and Chinese specialists hold positions in precision forging and secondary processing. The vendor base stratifies between captive refining operators with regulatory moats and fabrication-dependent processors facing stranded inventory exposure. Three archetypes dominate: vertically integrated primary producers, specification-locked aerospace suppliers, and research-funded powder alloy developers. Competitive moves center on qualification pathway reinvention and long-term purchase agreement consolidation at tier-one airframers.
Within the captive refining tier, Materion Corporation exemplifies regulatory moat construction through controlled distribution infrastructure. Alcoa Corporation occupies a position spanning primary magnesium integration from smelter to mill product. Boeing Company anchors the specification-locked aerospace supplier archetype, leveraging decades of in-house metallurgy data to retain proprietary alloy qualification authority.
| Leading Market Players |
|---|
| Materion Corporation |
| Alcoa Corporation |
| Boeing Company |
| Lockheed Martin Corporation |
| Special Metals Corporation |
| North American Tungsten Corporation |
| Xiamen Tungsten Co |
| Zhongwei Special Alloy Co |
| Rare Element Resources Ltd |
| Others |
Cost & Logistics Intelligence
Vacuum arc remelting adoption is simultaneously compressing oxide inclusion costs for aerospace-grade wrought alloys and concentrating supplier qualification authority around Materion's Elmore facility. This technology shift tightens the link between metallurgical pedigree and pricing power across German precision engineering clusters facing ECHA REACH compliance reinvention.
Pricing Analysis
Volume sits with cast alloys for defense electronics housings; margin concentrates in wrought alloy specifications for satellite structures. Three-tier pricing structure across aerospace-qualified, industrial-grade, and research-lot tiers separates Boeing-approved suppliers from secondary processors. Pricing pressure stems from aluminum-lithium substitution in wing skin applications at Airbus. Defense primes show least price sensitivity due to legacy specification lock-in; commercial space entrants face acute cost compression from launch mass economics.
Supply Chain Analysis
Domestic content mandates under China's GB standards are forcing Western joint ventures toward local vacuum induction melting partnerships. Primary beryllium concentrates in the United States at Spor Mountain; wrought alloy processing clusters in Germany and China. The supply chain draws from captive refining infrastructure, aerospace-qualified forgers, and national laboratory powder alloy programs. Single-source vulnerability runs through Utah's primary beryllium deposit. Distribution runs through long-term purchase agreements with minimum volume commitments at tier-one airframers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where ECHA REACH substance evaluation constructs regulatory moats favoring incumbents with captive refining infrastructure.
For Market Incumbents: Lock in Boeing and Airbus qualification pathways through proprietary fatigue test data accumulation before retiring metallurgical talent exits. Deepen backward integration into Spor Mountain feedstock arrangements to neutralize single-source vulnerability. Counter aluminum-lithium substitution by expanding satellite structure specifications where stiffness-to-density ratios resist substitution.
For New Entrants and Emerging Players: Enter via scrap circularity infrastructure for aerospace-grade chip and turnings recovery across European precision engineering corridors. Target powder alloy qualification programs at US national laboratories where additive manufacturing research lacks production scale economics. Pursue joint venture structures with Chinese domestic processors navigating SAMR GB standard enforcement.
For Investors and Strategic Acquirers: Exit pathways concentrate in captive refining operators with regulatory moats against ECHA import restrictions. Long-term viability hinges on aerospace OEM consolidation of approved supplier lists around qualified single-source providers. Watch for inflection signals in satellite miniaturization trends merging commercial space demand with legacy defense specifications.
| Strategic Initiative | Industry Significance |
|---|---|
| Captive Refining Expansion | ECHA REACH compliance creates regulatory moats for Materion's Elmore facility against Turkish and Kazakh smelters. |
| Long-term Supply Agreement | Boeing's dual-source waiver pattern consolidates procurement around qualified single-source wrought alloy providers. |
| Joint Venture Formation | SAMR GB standard enforcement drives Western suppliers toward Chinese domestic certification partnerships. |
| Scrap Circularity Infrastructure | Vacuum induction remelting capabilities for aerospace-grade chip recovery remain underdeveloped across Stuttgart clusters. |
| Additive Manufacturing Qualification | Powder alloy programs at US national laboratories accelerate deposition process development without production scale economics. |
Research Approach
Document review covered trade customs data, SEC filings from primary producers, and ECHA substance evaluation records, complemented by interviews with vacuum induction melting specialists, aerospace procurement managers at tier-one airframers, defense electronics housing engineers, and SAMR compliance officers. Secondary sources included aerospace fatigue test databases, REACH registration dossiers, and GB standard certification registries. Bottom-up alloy volume estimates triangulated against top-down aerospace and defense spending allocations.
Cross-referencing historical qualification timelines against expert panel input shaped the analytical framework across the projection horizon. Segmentation dimensions encompassed product type, application risk tolerance, end user category, and regional regulatory cluster. CAGRs derived from slope analysis of aerospace OEM procurement patterns and defense electronics housing replacement cycles. Industry-specific inputs included Boeing airframe qualification protocol durations and ECHA substance evaluation phase transitions.
Forecast precision tightens around the base case; tail outcomes carry wider variance under sudden OSHA permissible exposure limit revisions or Spor Mountain supply disruptions. Forecasts reflect assumptions around REACH compliance timeline adherence and aluminum-lithium substitution rates in secondary structures. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aerospace and Aircraft Materials
Aerospace Coatings Market
Aerospace and Aircraft Materials
Aerographene Market
Aerospace and Aircraft Materials
Electromagnetic and Radio Frequency Interference Coating Market
Aerospace and Aircraft Materials
Commercial Aerospace 3D Printing Market
Aerospace and Aircraft Materials
Composites in United States Defense Market
Aerospace and Aircraft Materials
Global Aerospace Adhesives and Sealants Market
Aerospace and Aircraft Materials
Radiation Shielding Market
Aerospace and Aircraft Materials
Coated Fabrics for Defense Market
Aerospace and Aircraft Materials
Aircraft Coatings Market
Aerospace and Aircraft Materials
Middle-East and Africa Aerospace Composites Market
Aerospace and Aircraft Materials
Aluminum Beryllium Market
Aerospace and Aircraft Materials
Honeycomb Panel for Aircraft Market
Aerospace and Aircraft Materials
Titanium Aerospace Forgings Market
Aerospace and Aircraft Materials
Aviation Coatings Market
Aerospace and Aircraft Materials
Aerospace and Defense Composites Market
Aerospace and Aircraft Materials
Global Aerospace Metal Closed-Die Forging Market