
 Aerospace Threaded Fasteners Market | 2026-2036
Aerospace Threaded Fasteners Market Size, Share, and Industry Trends Forecast 2026-2036
Aerospace Threaded Fasteners Market Insights
Project finance and long-term supply agreements with embedded escalation clauses is reshaping capital deployment across the aerospace threaded fasteners landscape. Howmet Aerospace leverages captive titanium and aluminum forging capacity to control feedstock costs for specialized bolts and nuts. LISI Aerospace anchors its position through dedicated aerospace fastener divisions serving Airbus and Safran assembly lines. Precision Castparts Corp. sustains manufacturing scale via integrated investment casting and fastener operations for engine hardware.
Aerospace threaded fasteners are mechanical joining devices featuring precisely machined helical threads, typically manufactured from titanium alloys or A-286 stainless steel to withstand cyclic loading at temperatures exceeding 315°C while maintaining clamp load integrity. These components transfer structural loads, seal pressurized compartments, and permit non-destructive disassembly during maintenance intervals across airframe, propulsion, and landing gear assemblies. Titanium alloy fasteners command premium positioning in engine and landing gear applications where strength-to-weight ratios dictate fuel efficiency gains, while stainless steel variants dominate cabin interiors and avionics housing where corrosion resistance supersedes weight optimization. OEM procurement channels represent the most concentrated margin pool, though aftermarket providers are capturing expanded scope as fleet utilization rates elevate scheduled maintenance events.
FAA airworthiness standards, EASA Part 21 design certification requirements, and NADCAP special process accreditation collectively govern material traceability, heat treatment protocols, and dimensional tolerances for flight-critical fasteners. These frameworks elevate entry barriers by mandating lot-specific chemical analysis and mechanical testing documentation that smaller suppliers cannot economically maintain. Stakeholders must monitor evolving sustainability disclosure obligations under CSRD and SEC climate rules, as scope 3 emissions tracking extends upstream to raw material extraction and forging energy intensity.
Market Dynamics
Fleet renewal cycles and OEM consolidation are compressing supplier margins while elevating performance specifications for fatigue-critical fastening systems across next-generation airframe architectures.
Growth Catalysts
- Commercial aviation fleet replacement:Boeing and Airbus production rate increases are expanding threaded fastener procurement volumes for single-aisle and wide-body programs.
- FAA airworthiness directive tightening:Enhanced fatigue testing mandates for primary structural joints are accelerating adoption of A-286 stainless steel and titanium alloy variants with improved cyclic load tolerance.
- Defense procurement acceleration:Pentagon modernization programs for next-generation combat aircraft and unmanned systems are channeling specialized fastener demand toward domestic forging capacity.
Market Restraints
- Titanium sponge supply concentration:Russian and Chinese dominance in titanium feedstock extraction exposes Western fastener manufacturers to geopolitical supply disruption and price volatility.
- NADCAP accreditation burden:Special process certification requirements for heat treatment and non-destructive testing impose fixed compliance costs that disadvantage smaller forging operations.
- Composite fastener substitution:Carbon fiber-reinforced polymer joining techniques in non-structural applications are displacing metallic threaded fasteners in cabin interior and secondary airframe segments.
Strategic Opportunities
- Urban air mobility integration:eVTOL airframe manufacturers represent unserved demand for lightweight, corrosion-resistant fastening systems certified to novel ASTM standards.
- CSRD scope 3 disclosure:European sustainability reporting mandates are creating first-mover advantage for suppliers with verified low-carbon titanium extraction and renewable-powered forging operations.
- Additive manufacturing convergence:Hybrid production combining powder-bed fusion with precision machining enables complex head geometries and internal thread profiles previously impossible through conventional forging.
Industry Challenges
- Heat treatment technician scarcity:Specialized metallurgical expertise for aerospace alloy processing is retiring faster than vocational programs can replenish qualified personnel.
- EASA Part 21 design approval timelines:Certification delays for novel fastener geometries extend product development cycles and compress return-on-investment windows for R&D-intensive programs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aerospace Threaded Fasteners Market |
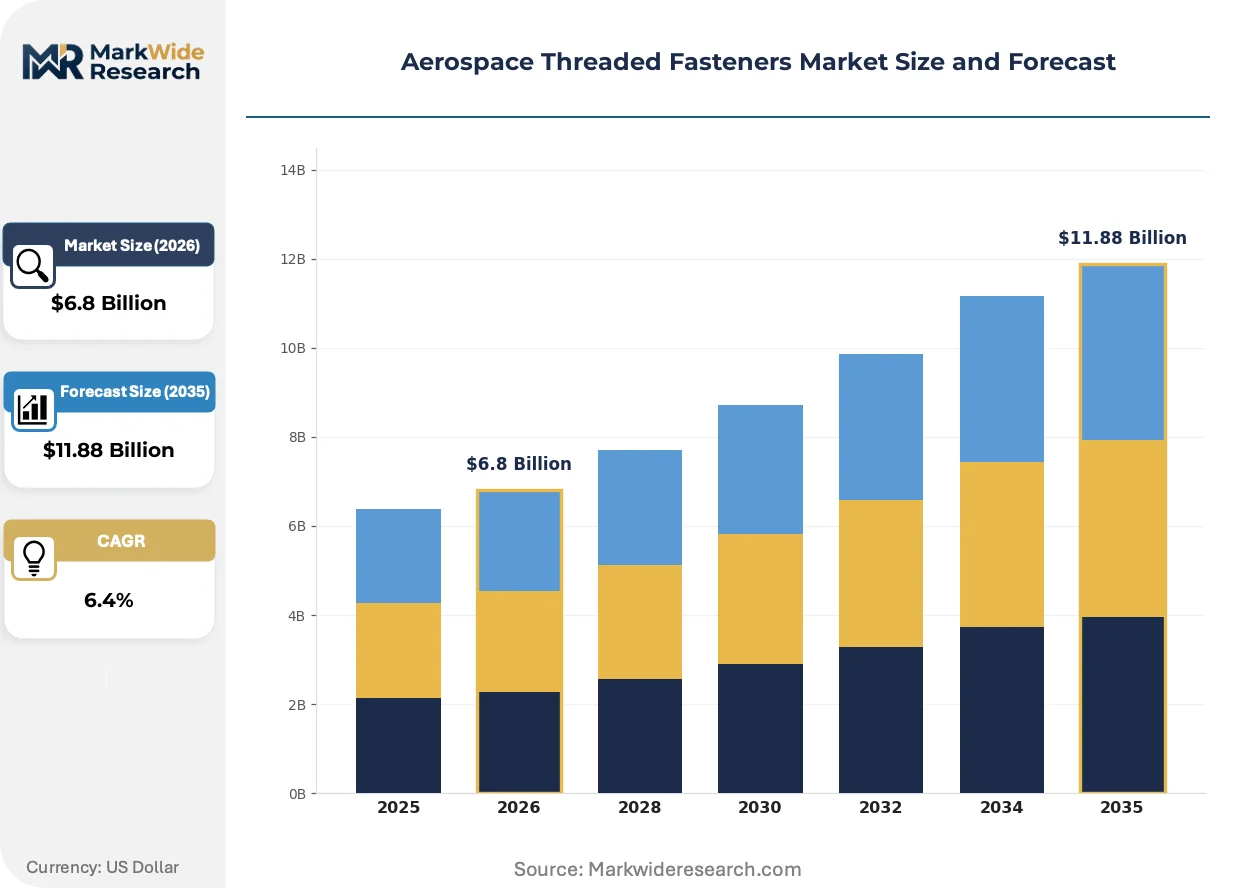
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.88 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bolts, Screws, Nuts, Washers, Rivets Material: Aluminum Alloys, Titanium Alloys, Stainless Steel, Inconel, Carbon Steel Application: Airframe Assemblies, Engine Components, Landing Gear, Cabin Interiors, Avionics Housing End User: OEMs, Maintenance Centers, Aerospace Tier-1 Suppliers, Aftermarket Providers |
| Companies Covered | Howmet Aerospace, Precision Castparts Corp., LISI Aerospace, TriMas Corporation, National Aerospace Fasteners Corporation, Stanley Black & Decker, Wurth Group, B&B Specialties Inc., M.S. Aerospace, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aerospace Threaded Fasteners Market Trends and Innovations
Digital thread integration and advanced material processing are redefining how threaded fasteners are designed, manufactured, and traced through complex aerospace supply chains.
Titanium-aluminide intermetallic coatings are hybridizing surface engineering approaches for engine-exposed fasteners, combining oxidation resistance with reduced galling tendency during installation. Turbine OEMs are specifying these treatments for high-pressure compressor stages where thermal cycling exceeds 650°C. The technology is hybridizing procurement specifications across GE Aerospace and Rolls-Royce supply chains, forcing legacy plating suppliers to retool or exit the segment.
EU CSRD sustainability disclosure rules are mandating granular carbon accounting from fastener raw material extraction through final machining. Suppliers must now document scope 3 emissions for titanium sponge, A-286 bar stock, and forging energy consumption. European tier-1 distributors are responding by consolidating supplier panels to those with ISO 14064-verified environmental management systems.
Airline technical procurement teams are compressing supplier qualification cycles through digital twin validation of fastener performance under simulated flight loads. This behavior is displacing traditional physical test campaigns for non-critical applications. The shift is most visible among low-cost carriers operating narrow-body fleets with high utilization rates, where maintenance interval predictability outweighs upfront hardware cost.
Aerospace Threaded Fasteners Market Segmentation
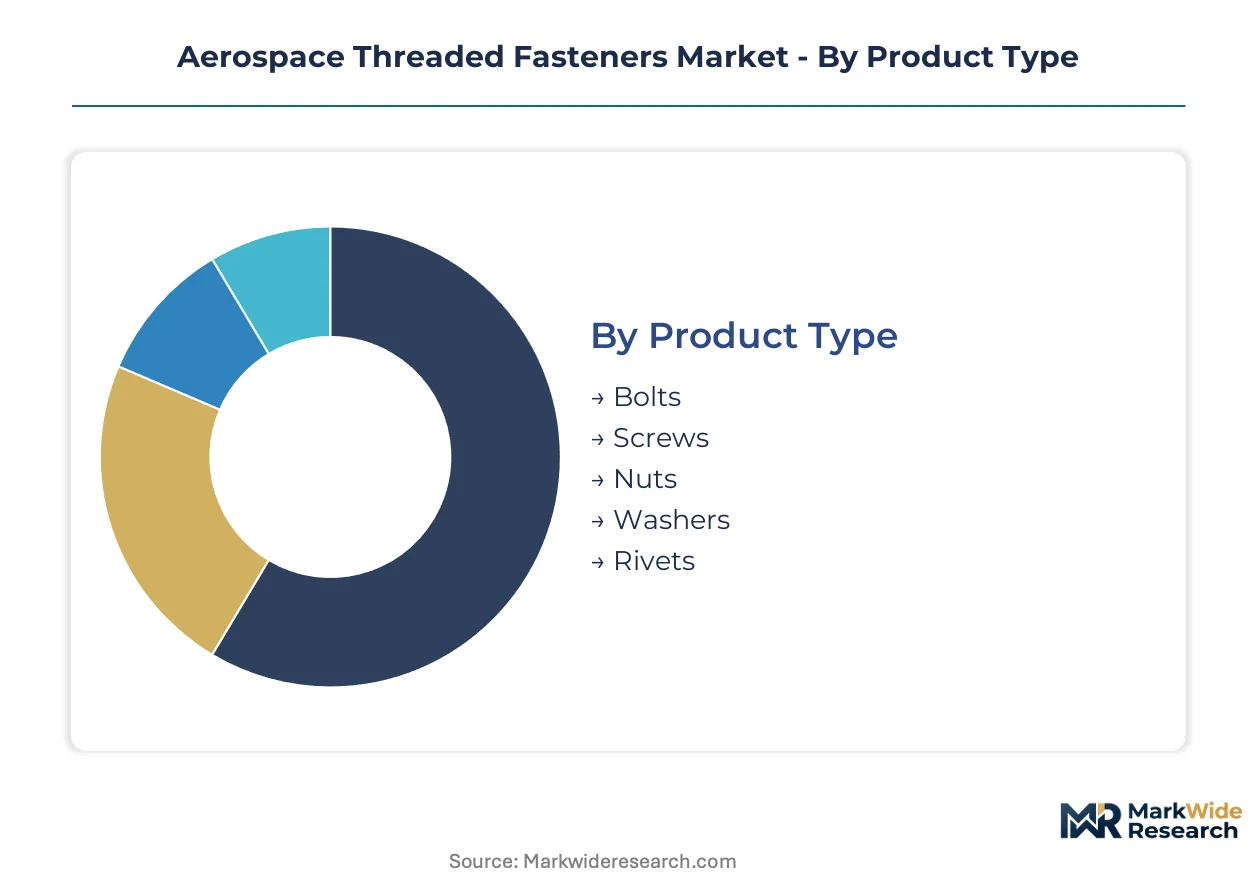
Threaded fastener segmentation reveals how material specifications, application criticality, and procurement channel economics fragment supplier strategies across aerospace value chains. Understanding these divides exposes where margin pools concentrate and where certification barriers protect incumbent positions.
Product Type:
Mature structural fasteners dominate procurement volumes while emerging specialty configurations capture premium positioning in next-generation airframe architectures.
- Bolts:High-tensile hex-head and 12-point configurations engineered from Ti-6Al-4V or A-286 stainless steel transfer primary structural loads across wing-box and fuselage joints. Boeing 737 MAX and Airbus A320neo production rate increases are channeling demand toward fatigue-resistant shank designs with rolled threads.
- Screws:Precision-machined thread forms with captive washer assemblies seal pressurized compartments and secure removable panels. eVTOL manufacturers are specifying corrosion-resistant thread-locking variants for exposed airframe segments subject to atmospheric moisture cycling.
- Nuts:Self-locking torque prevailing designs maintain clamp load integrity under vibration environments.
- Washers:Conical and flat configurations distribute bearing stress and prevent galvanic corrosion at material interfaces.
- Rivets:Solid and blind variants persist in permanent structural joints where threaded disassembly is not required.
Bolts retain volume leadership; screws hold the steepest expansion curve.
Material:
Cost tier stratification separates commodity carbon steel from engineered superalloys, with titanium commanding the widest price spreads and tightest supply constraints.
- Titanium Alloys:Ti-6Al-4V and Ti-5Al-5V-5Mo-3Cr formulations deliver strength-to-weight ratios critical for engine nacelles and landing gear assemblies. Russian and Chinese sponge supply concentration exposes Western forgers to geopolitical price volatility and export control risks.
- Stainless Steel:A-286 precipitation-hardening and 316L austenitic grades dominate cabin interiors and avionics housings where corrosion resistance supersedes weight optimization. FAA fatigue testing mandates are accelerating adoption of A-286 variants with improved cyclic load tolerance in primary structural joints.
- Aluminum Alloys:2024-T4 and 7075-T6 extrusions serve secondary structures and non-critical access panels.
- Inconel:Nickel-chromium superalloys withstand sustained exposure above 650°C in turbine exhaust environments.
- Carbon Steel:Zinc-plated commodity grades persist in ground support equipment and non-flight hardware.
Stainless steel commands the broadest application footprint; titanium alloys are climbing the fastest on engine lightweighting priorities.
Application:
Customer type fragmentation splits procurement between OEM engineering specifications and aftermarket maintenance interval predictability.
- Airframe Assemblies:Fuselage and wing primary structure fasteners must survive millions of pressurization cycles while maintaining preload under combined tension-shear loading. Airbus A350 and Boeing 787 composite-intensive designs are driving hybrid metallic-composite fastening system development.
- Engine Components:Turbine case and compressor stage hardware faces thermal cycling from ambient to 650°C with oxidation and creep constraints. GE Aerospace and Rolls-Royce are specifying titanium-aluminide surface treatments for high-pressure compressor fasteners exposed to extreme thermal gradients.
- Landing Gear:Oleo strut and trunnion attachments require ultra-high strength forgings with shot-peened surfaces for fatigue life extension.
- Cabin Interiors:Seat track and monument fasteners prioritize quick-release functionality and aesthetic finish over structural margins.
- Avionics Housing:EMI-shielded thread forms secure electronic enclosures against vibration and electromagnetic interference.
Airframe assemblies absorb the largest procurement volumes; engine components are gaining share fastest on propulsion system upgrade cycles.
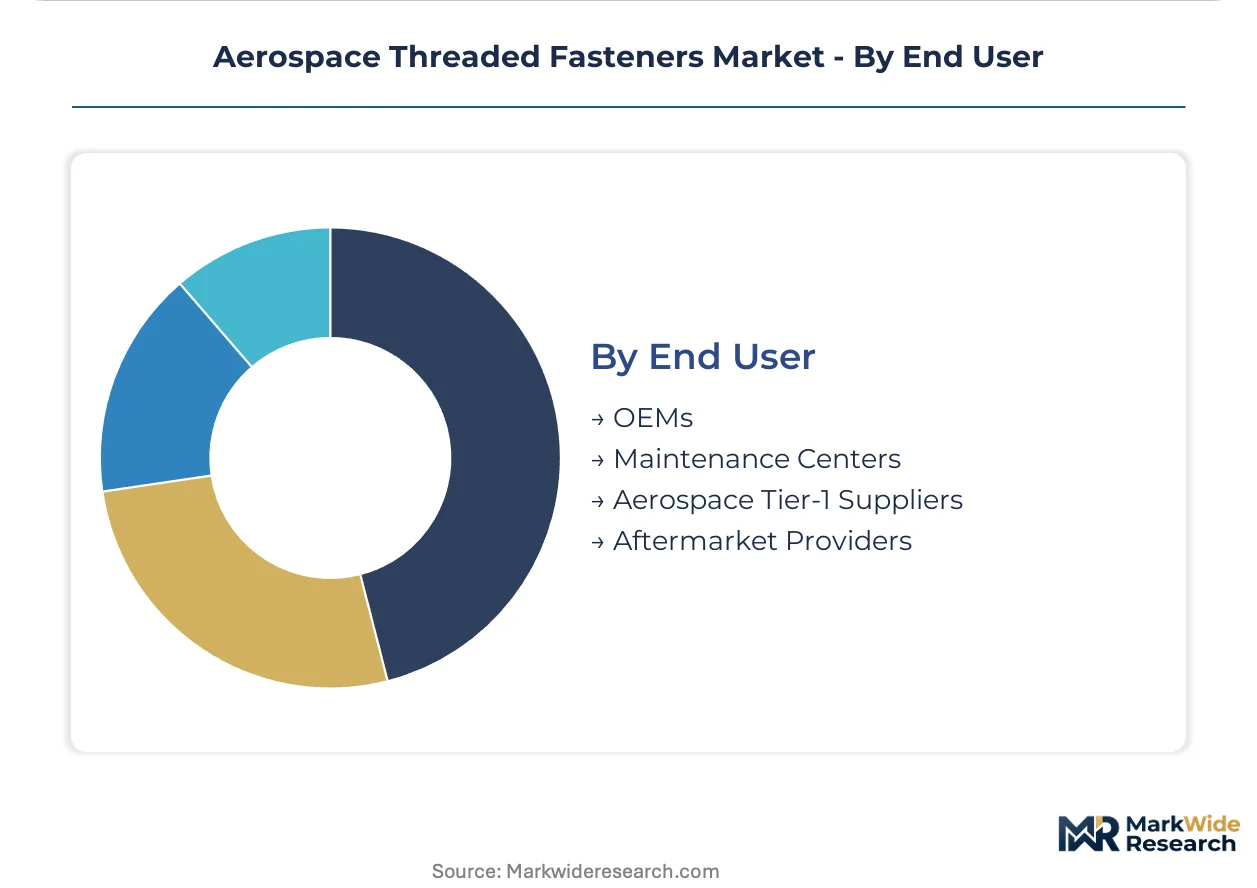
End User:
Supply concentration varies sharply across the channel, with OEMs consolidating supplier panels while aftermarket fragmentation sustains smaller forging operations.
- OEMs:Boeing, Airbus, and Lockheed Martin procurement teams enforce NADCAP special process accreditation and lot-specific material traceability that eliminates marginal suppliers. Long-term supply agreements with embedded escalation clauses lock in pricing for titanium and superalloy variants.
- Aerospace Tier-1 Suppliers:Spirit AeroSystems and GKN Aerospace intermediate fastener demand from airframe subassembly programs.
- Maintenance Centers:Delta TechOps and Lufthansa Technik operations drive scheduled replacement demand for corrosion-prone hardware in coastal operating environments.
- Aftermarket Providers:Distributors stock certified hardware for unscheduled AOG events and aging fleet support.
OEMs retain volume leadership; aftermarket providers are expanding most quickly as global fleet utilization rates elevate maintenance event frequency.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FAA airworthiness directives and Pentagon procurement acceleration anchor United States demand, while EASA certification standards and CSRD disclosure mandates reshape European supplier economics. Defense modernization programs across multiple jurisdictions are channeling specialized fastener requirements toward domestic forging capacity.
United States
Boeing's supply chain consolidation and Lockheed Martin's next-generation combat aircraft programs expand titanium and A-286 fastener procurement volumes. FAA fatigue testing mandates for primary structural joints tighten material traceability requirements that eliminate marginal suppliers. Wichita's aviation manufacturing cluster and Seattle's aerospace corridor concentrate tier-1 forging operations serving OEM assembly lines.
France
Airbus final assembly expansion in Toulouse and Safran's propulsion system upgrades drive demand for engine-exposed fastening hardware. EASA Part 21 design certification timelines extend product development cycles for novel fastener geometries. The Occitanie region's aerospace subcontractor network specializes in heat treatment and surface finishing for flight-critical components.
Germany
MTU Aero Engines' maintenance contracts and Liebherr-Aerospace's landing gear production sustain procurement of high-strength alloy fasteners. EU CSRD scope 3 disclosure rules mandate carbon accounting from titanium extraction through final machining. Bavaria's precision engineering cluster integrates NADCAP-accredited special process operations for aerospace tier-1 suppliers.
United Kingdom
Rolls-Royce's turbine upgrade programs and BAE Systems' combat air procurement channel demand toward fatigue-resistant superalloy fasteners. UK Export Finance guarantees for defense aerospace contracts stabilize long-term supply agreement pricing. The Midlands aerospace cluster maintains captive forging capacity for engine hardware and structural assemblies.
Japan
Mitsubishi Heavy Industries' regional jet programs and IHI's engine component manufacturing expand domestic fastener consumption. METI's aerospace industry revitalization subsidies support heat treatment facility modernization and technician training programs. The Nagoya aerospace cluster coordinates precision machining operations across tier-2 and tier-3 supplier networks.
Aerospace Threaded Fasteners Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a consolidated tier-1 supplier base and fragmented aftermarket distribution layer. OEM procurement teams enforce NADCAP accreditation and lot-specific traceability that eliminates smaller forging operations. Three archetypes dominate: vertically integrated metals processors with captive titanium supply, aerospace-dedicated fastener divisions with airframe OEM relationships, and precision casting specialists with hybrid fastener-engine component operations. Competitive moves concentrate on long-term supply agreements with embedded escalation clauses and additive manufacturing capability acquisition.
Among North American integrated suppliers, Howmet Aerospace and Precision Castparts Corp. exemplify the metals-processor archetype with upstream control over titanium and superalloy feedstock. LISI Aerospace occupies a position within the European aerospace-dedicated tier, representing the specialist division model serving Airbus and Safran assembly requirements. These three anchors illustrate how supplier economics fragment between feedstock-integrated and relationship-dependent competitive vectors.
| Leading Market Players |
|---|
| Howmet Aerospace |
| Precision Castparts Corp. |
| LISI Aerospace |
| TriMas Corporation |
| National Aerospace Fasteners Corporation |
| Stanley Black & Decker |
| Wurth Group |
| B&B Specialties Inc. |
| M.S. Aerospace |
| Others |
Pricing and Supply Chain Analysis
Russian and Chinese dominance in titanium sponge extraction creates a dual vulnerability that compresses margin spreads between certified aerospace-grade and commercial-grade fasteners while forcing Western manufacturers toward Japanese and Kazakh feedstock alternatives. This concentration dynamic simultaneously elevates NADCAP-accredited suppliers into premium pricing tiers and exposes non-integrated forgers to raw material cost volatility that erodes contract profitability.
Pricing Analysis
Certification level creates the primary spread between titanium alloy fasteners, with NADCAP special process accreditation and FAA/EASA lot-specific traceability commanding substantial premiums over commercial-grade alternatives. Pricing stratifies across flight-critical engine hardware, primary structural airframe joints, and non-critical cabin interiors based on fatigue testing documentation and material pedigree depth. Cost compression in standard-grade stainless steel variants is intensifying as Chinese forging capacity expands into A-286 bar stock processing. Aftermarket distributors exhibit highest price sensitivity due to inventory carrying costs, while OEM procurement teams prioritize total cost of ownership over unit pricing.
Supply Chain Analysis
Extended payment terms from Boeing and Airbus tier-1 procurement teams are forcing mid-size forgers into supply-chain finance facilities backed by aerospace-focused lenders. Raw material sourcing draws from Russian and Chinese titanium sponge, Japanese vacuum arc remelting capacity, and domestic A-286 stainless steel melt shops in the United States and Germany. Single-source vulnerability in high-purity titanium feedstock exposes Western fastener manufacturers to export control disruption and price spikes. Distribution runs through authorized aerospace distributors with NADCAP-accredited warehousing and lot-traceable inventory management systems serving OEM assembly lines and maintenance centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Additive manufacturing qualification for flight-critical fasteners represents a technological inflection that will reshape competitive economics across the next decade, compressing development timelines for complex geometries while elevating capital requirements.
For Market Incumbents: Insulate titanium feedstock positions through long-term offtake agreements with Japanese and Kazakh sponge producers, reducing exposure to Russian supply disruption. Expand NADCAP-accredited heat treatment capacity in Wichita and Toulouse manufacturing clusters to capture OEM consolidation-driven volume concentration. Certification investment in eVTOL-specific ASTM standards creates defensive positioning against emerging additive manufacturing specialists threatening traditional forging economics. For New Entrants and Emerging Players: Southeast Asian maintenance center networks present underpenetrated demand for corrosion-resistant stainless steel fasteners serving coastal airline operations with accelerated replacement cycles. Urban air mobility airframe manufacturers represent white-space demand for lightweight titanium-aluminide coated hardware certified to novel thermal cycling standards. A go-to-market angle combining digital twin validation capabilities with rapid prototype-to-certification timelines addresses compressed supplier qualification cycles among low-cost carriers. For Investors and Strategic Acquirers: NADCAP-accredited specialty heat treatment shops with captive aerospace customer relationships represent compelling acquisition targets given technician scarcity and expanding OEM traceability requirements. Long-term viability centers on suppliers with demonstrated scope 3 emissions documentation under EU CSRD rules and renewable-powered forging operations. The signal to watch is EASA Part 21 design approval timeline compression for additive manufacturing processes, which would accelerate capital deployment into hybrid production capabilities.| Strategic Initiative | Industry Significance |
|---|---|
| Long-term Titanium Supply Agreement | Locking Kazakh and Japanese sponge volumes insulates Howmet Aerospace from geopolitical price volatility. |
| NADCAP Heat Treatment Expansion | Adding accredited capacity in Wichita captures Boeing supply chain consolidation-driven volume concentration. |
| Additive Manufacturing Qualification | Hybrid powder-bed fusion capabilities enable GE Aerospace-specified complex head geometries for compressor hardware. |
| CSRD Scope 3 Documentation | ISO 14064-verified carbon accounting secures European tier-1 distributor panel consolidation advantages. |
| eVTOL Fastener Certification | ASTM-standard corrosion-resistant designs capture urban air mobility airframe manufacturer procurement. |
Research Methodology
Operator-level perspectives from fastener procurement managers at Boeing and Airbus, NADCAP accreditation auditors, heat treatment facility operators, and airline technical purchasing committees anchored the qualitative base. Secondary validation drew from FAA airworthiness directive filings, EASA Part 21 design certification databases, NADCAP special process audit records, and SEC 10-K disclosures from publicly traded aerospace suppliers. Bottom-up segment sizing triangulated against top-down OEM production rate forecasts and fleet renewal program announcements.
Scenario-bracketing around titanium supply disruption severity and additive manufacturing adoption pace structured the analytical framework across the projection horizon. Segmentation dimensions modeled include material alloy grade, application criticality tier, procurement channel type, and geographic regulatory cluster. CAGRs were derived from production rate trajectories for single-aisle and wide-body programs, maintenance interval frequency projections, and defense modernization program procurement schedules. Forecast inputs incorporated heat treatment capacity utilization rates and technician training program graduation volumes.
The forecast holds incumbent behavior within observed patterns; aggressive backward integration into titanium sponge extraction by major forgers would shift supply economics and pricing power distribution. Macroeconomic deviation in commercial aviation traffic recovery, regulatory tightening on scope 3 emissions disclosure, or breakthrough qualification of fully additive-manufactured flight-critical fasteners would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aerospace and Aircraft Materials
Global Anti-Icing Coating Market
Aerospace and Aircraft Materials
Composites in United States Defense Market
Aerospace and Aircraft Materials
Out-of-Autoclave Composite Skin Panels for Regional and Business Jets Market
Aerospace and Aircraft Materials
Middle-East and Africa Aerospace Composites Market
Aerospace and Aircraft Materials
Aerospace Composite Ducting Market
Aerospace and Aircraft Materials
Global Aerospace Adhesives Market
Aerospace and Aircraft Materials
Aerospace Fiber Optics Market
Aerospace and Aircraft Materials
Aircraft Carbon Brake Disc Market
Aerospace and Aircraft Materials
Aerospace Radome Market
Aerospace and Aircraft Materials
Aviation Coatings Market
Aerospace and Aircraft Materials
Global Aerospace Titanium Machining Market
Aerospace and Aircraft Materials
Fiberglass for Aerospace Market
Aerospace and Aircraft Materials
Aerospace 3D Printing Consumables Market
Aerospace and Aircraft Materials
Aerospace Raw Materials Market
Aerospace and Aircraft Materials
Aircraft Aluminium Plate Market
Aerospace and Aircraft Materials
Global AFP/ATL Machines Market