
 Aerospace Carbon Fiber Market | 2026-2036
Aerospace Carbon Fiber Market Size, Share, and Industry Trends Forecast 2026-2036
Aerospace Carbon Fiber Market Analysis
Japanese precursor supply is broadening as Toray Industries extends its PAN-based carbon fiber footprint across multiple continents. Hexcel Corporation leverages its Salt Lake City autoclave network to sustain qualification pipelines for next-generation narrowbody programs. SGL Carbon SE anchors European supply security through its Moses Lake facility, while Mitsubishi Chemical Corporation competes on pitch-based ultra-high modulus grades for satellite bus structures.
Aerospace carbon fiber denotes polyacrylonitrile-derived or pitch-based carbon filaments with tensile moduli exceeding 230 GPa, engineered through controlled oxidation and carbonization cycles to achieve specific strength-to-weight ratios for primary load-bearing applications. Prepreg formats dominate procurement value due to their controlled resin content and out-time predictability during layup operations, while carbon tapes capture expanding share in automated fiber placement workflows for wing skins and fuselage barrels. Commercial aviation end-use commands the largest volume allocation, though space exploration applications exhibit the steepest qualification momentum as reusable launch vehicle programs multiply.
FAA airworthiness directives and EASA CS-25 composite damage tolerance standards jointly shape material selection criteria, with both regulators mandating extended fatigue databases for bonded repairs. The EU Green Deal's aviation decarbonization targets are forcing OEMs to document lifecycle emissions from precursor production through end-of-life recycling. Stakeholders must monitor emerging thermoplastic resin infusion alternatives that promise to bypass autoclave bottlenecks without sacrificing FAA-compliant mechanical properties.
Market Dynamics
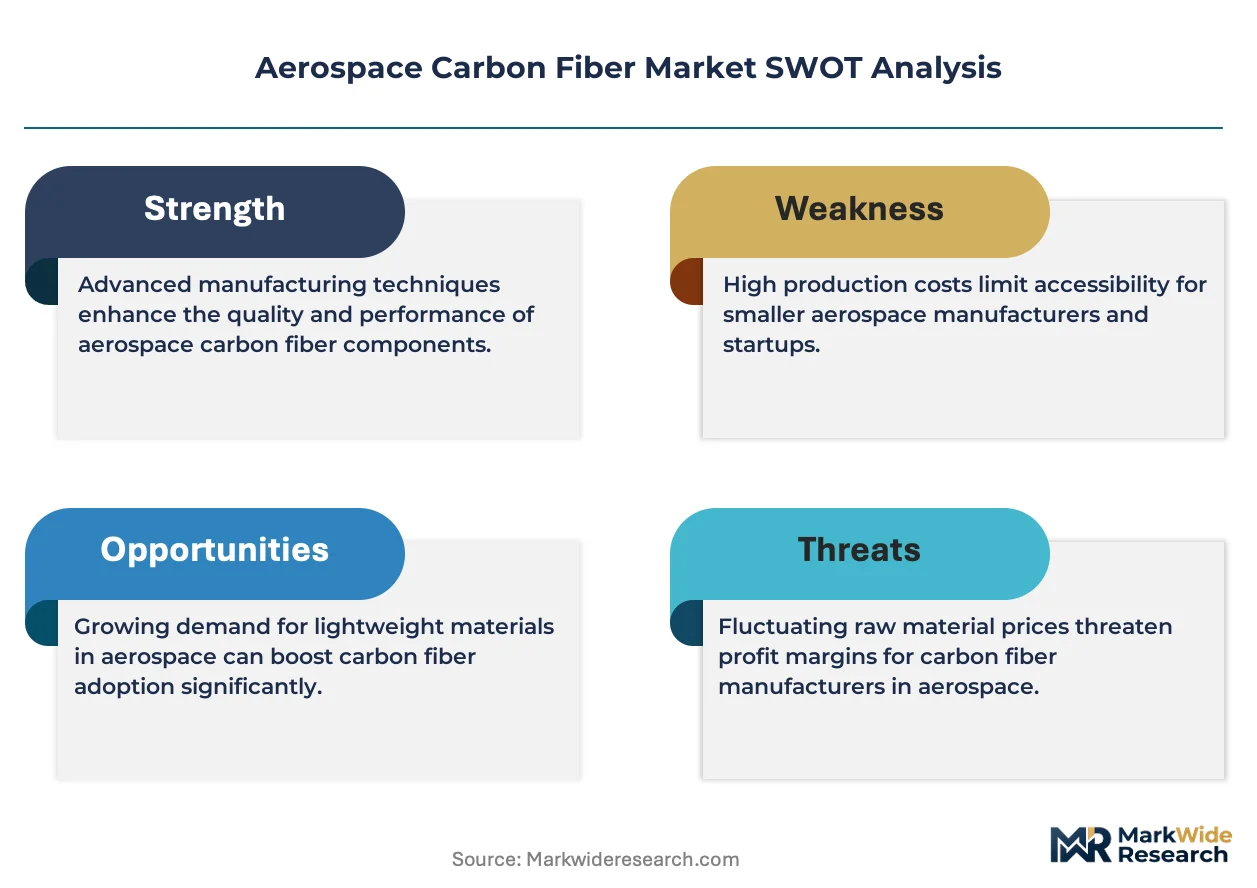
Composite-intensive airframe designs are forcing suppliers to restructure qualification pipelines around FAA damage tolerance mandates and Boeing's next-generation narrowbody procurement schedules. This regulatory-technical nexus compresses development cycles while elevating material traceability requirements across the entire precursor-to-component chain.
Growth Catalysts
- FAA Certification Pathways:Tightened material traceability standards for composite-intensive designs are accelerating investment in automated fiber placement systems for primary load-bearing structures.
- EU Green Deal Aviation Targets:Lifecycle emissions documentation requirements from precursor production through end-of-life recycling are expanding demand for recycled carbon fiber qualification programs.
- Reusable Launch Vehicles:Satellite bus manufacturers are qualifying pitch-based ultra-high modulus grades for thermal stability in rapid-turnaround orbital insertion missions.
Market Restraints
- Acrylonitrile Feedstock Volatility:PAN precursor production remains exposed to petrochemical input cost swings that compress margin predictability for carbon fiber manufacturers.
- Japanese Precursor Concentration:Toray Industries and Mitsubishi Chemical Corporation anchor global PAN supply, creating geographic single-point vulnerability for Western airframers.
- EASA CS-25 Damage Tolerance:Extended fatigue database requirements for bonded repairs lengthen qualification timelines and freeze material substitutions mid-program.
Strategic Opportunities
- Thermoplastic Resin Infusion:Out-of-autoclave processing alternatives are converging with FAA mechanical property requirements to unlock throughput bottlenecks in wing skin production.
- Satellite Constellation Deployments:Low Earth orbit megaconstellations are creating qualification demand for ultra-high modulus pitch-based filaments in deployable antenna structures.
- US Supplier Base Expansion:Hexcel's Salt Lake City autoclave network and SGL Carbon's Moses Lake facility are capturing reshoring procurement from Boeing's supplier qualification pipeline.
Industry Challenges
- Autoclave Throughput Constraints:Prepreg out-time predictability requirements clash with layup operation scheduling, forcing capital-intensive capacity expansion at qualification facilities.
- Bonded Repair Certification:FAA airworthiness directives mandate extended fatigue testing protocols that extend new material adoption cycles beyond program launch windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aerospace Carbon Fiber Market |
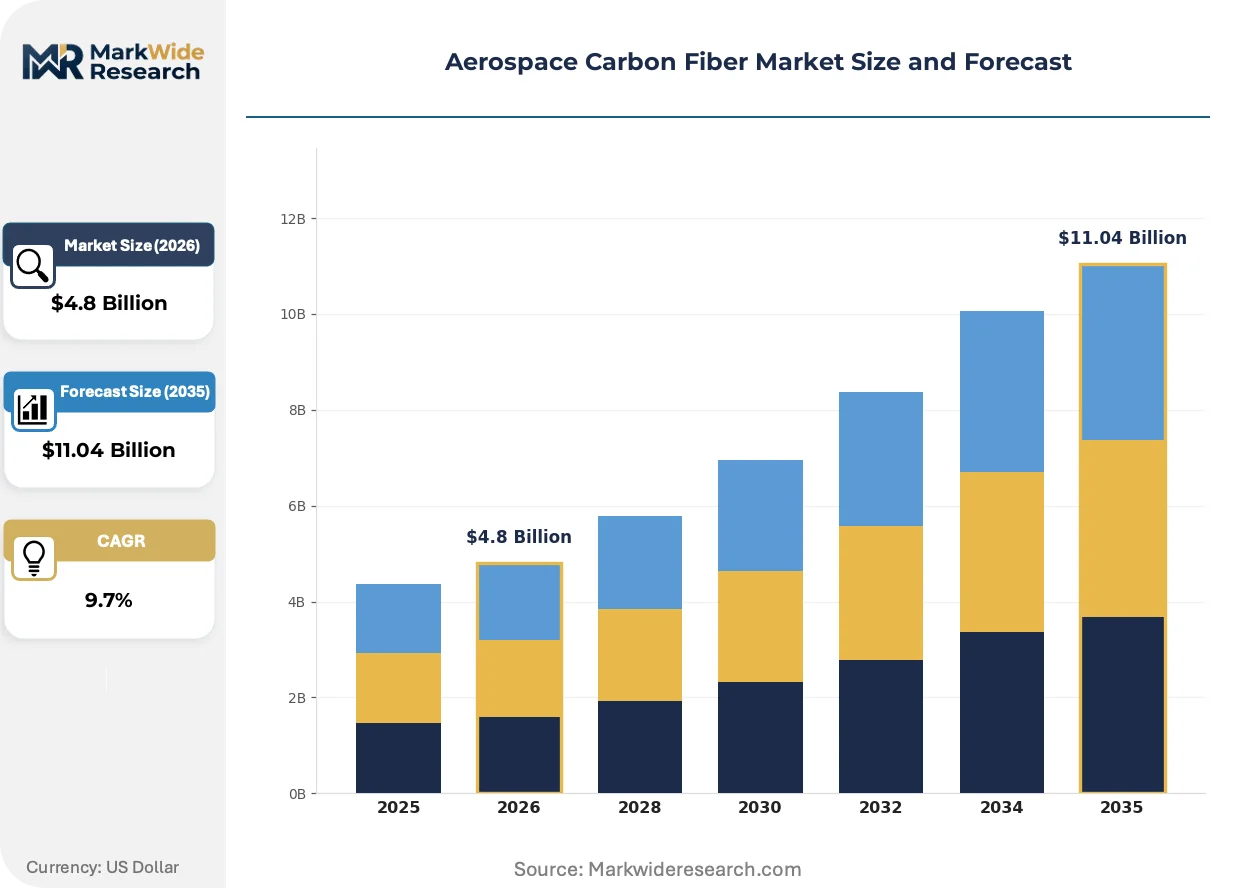
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $11.04 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Prepregs, Carbon Fabrics, Carbon Tapes, Carbon Reinforced Plastics Application: Structural Components, Interiors, Engine Parts, Wings End User: Commercial Aviation, Military Aviation, Space Exploration, UAVs Manufacturing Process: Autoclave, Resin Infusion, Filament Winding, Compression Molding |
| Companies Covered | Toray Industries, Hexcel Corporation, Solvay S.A., Teijin Limited, SGL Carbon SE, Mitsubishi Chemical Corporation, DuPont de Nemours, BGF Industries, Bally Ribbon Mills, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aerospace Carbon Fiber Market Emerging Trajectories
Automated fiber placement systems are displacing hand layup workflows across wing skin and fuselage barrel production, compressing labor content while elevating precision requirements for tape laying equipment. This manufacturing transition is reshaping supplier qualification criteria and capital deployment patterns.
Out-of-autoclave thermoplastic resin infusion is converging with automated fiber placement workflows to bypass traditional autoclave bottlenecks without sacrificing FAA-compliant mechanical properties. Tier-1 aerostructures suppliers are piloting these hybrid processing routes for next-generation narrowbody wing components. The technology is compressing capital intensity per unit of throughput while maintaining damage tolerance certification standards.
EASA CS-25 composite damage tolerance standards are tightening bonded repair qualification requirements across European-registered commercial aviation fleets. Extended fatigue database mandates are forcing OEMs to document crack growth rates under combined thermal-mechanical loading scenarios. European airframers are responding by consolidating material specifications around pre-qualified prepreg systems with established repair protocols.
Airline procurement departments are unbundling after-sales composite repair services from original airframe purchase agreements, creating independent qualification pathways for third-party MRO providers. This disintermediation is fragmenting material specification authority away from OEM engineering teams toward airline technical operations divisions. The shift is most visible in North American carrier fleets seeking operational flexibility across mixed-supplier maintenance networks.
Aerospace Carbon Fiber Market Segmentation
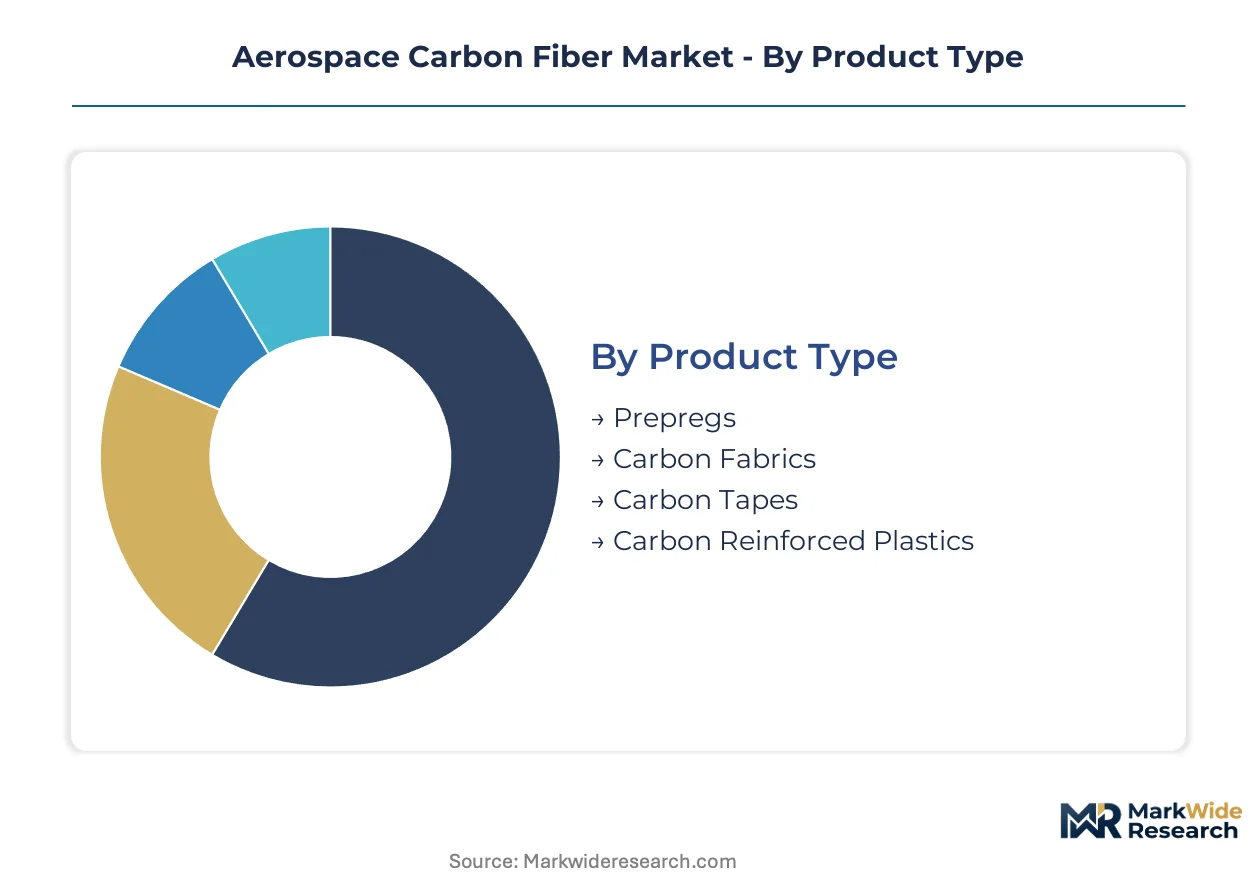
Segmentation in aerospace carbon fiber procurement determines qualification pathways, capital deployment, and margin structures across the value chain. Material format selection dictates processing equipment requirements, while end-use classification governs regulatory scrutiny intensity and damage tolerance certification protocols.
Product Type:
Supply concentration in prepreg manufacturing anchors procurement strategies for tier-1 aerostructures suppliers, with resin formulation control residing among a handful of qualified compounders.
- Prepregs:These resin-impregnated fiber sheets deliver controlled fiber volume fractions and predictable out-time windows during automated layup operations. Boeing's supplier qualification pipeline concentrates demand in the United States, where Salt Lake City autoclave networks sustain narrowbody production schedules under FAA material traceability mandates.
- Carbon Tapes:Unidirectional fiber arrangements optimize automated fiber placement workflows for wing skins and fuselage barrels. European airframers under EASA CS-25 damage tolerance standards are expanding tape-based procurement to compress labor content while maintaining bonded repair certification databases.
- Carbon Fabrics:Woven architectures serve complex curvature geometries in nacelles and control surfaces where drapeability outweighs stiffness optimization.
- Carbon Reinforced Plastics:Molding compounds address high-volume secondary structures with shorter qualification cycles than primary load-bearing prepregs.
Today's leader: Prepregs. Tomorrow's challenger: Carbon Tapes.
Application:
Cost tier differentiation separates primary structures commanding premium qualification investments from interior applications competing on cycle time and finish quality.
- Structural Components:Fuselage frames, floor beams, and pressure bulkheads absorb the most intensive FAA fatigue testing protocols. Japanese precursor suppliers anchor material specifications here, with Toray Industries and Mitsubishi Chemical Corporation controlling PAN-based fiber qualification pathways for Western airframers.
- Wings:Wing skins and spars drive automated fiber placement capital deployment across Moses Lake and Salt Lake City production clusters. EU Green Deal aviation decarbonization targets are forcing lifecycle emissions documentation from precursor production through end-of-life recycling for these high-mass components.
- Engine Parts:Fan blades and nacelle structures require oxidation-resistant resin systems for thermal exposure management.
- Interiors:Cabin monuments and galley structures prioritize fire-smoke-toxicity certification over mechanical property optimization.
Volume concentrates in Structural Components. Margin expansion potential sits with Wings.
End User:
Customer type fragmentation is accelerating as airline technical operations divisions unbundle composite repair services from original airframe purchase agreements.
- Commercial Aviation:Narrowbody and widebody fleets command the largest procurement volumes, with Boeing and Airbus supplier qualification pipelines dictating material specification consolidation. FAA airworthiness directives and EASA CS-25 standards jointly govern bonded repair protocols across North American and European carrier fleets.
- Space Exploration:Reusable launch vehicle programs are climbing the fastest, with satellite bus manufacturers qualifying pitch-based ultra-high modulus grades for thermal stability in rapid-turnaround orbital insertion missions.
- Military Aviation:Fighter and transport programs operate under classified damage tolerance requirements with longer procurement cycles than commercial equivalents.
- UAVs:Uncrewed platforms tolerate higher design risk tolerance and accelerated material substitution timelines absent passenger certification burdens.
Procurement gravity centers on Commercial Aviation. Technology leadership is shifting toward Space Exploration.
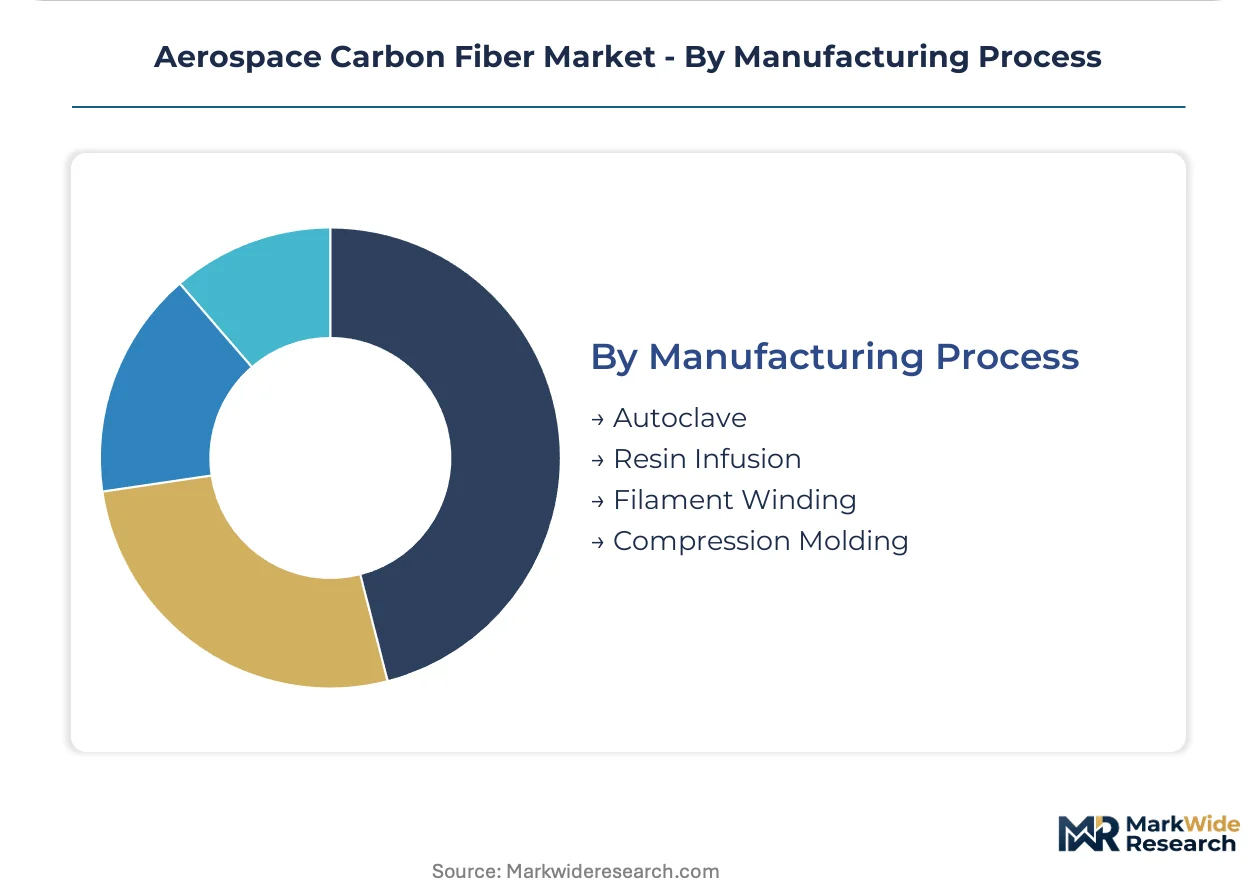
Manufacturing Process:
Maturity gradients separate autoclave-dependent qualification pipelines from emerging out-of-autoclave alternatives converging with FAA mechanical property requirements.
- Autoclave:Pressurized thermal processing remains the certification baseline for primary structures, with throughput constraints forcing capital-intensive facility expansion at Hexcel's Salt Lake City network and SGL Carbon's Moses Lake operations.
- Resin Infusion:Vacuum-assisted resin transfer molding is gaining share fastest in secondary structures and non-pressurized applications where damage tolerance certification requirements permit shorter fatigue databases.
- Filament Winding:Cylindrical pressure vessels and drive shafts exploit continuous fiber alignment for hoop stress optimization.
- Compression Molding:Short-cycle formats serve high-volume brackets and clips with minimal fiber architectural complexity.
Qualification authority rests with Autoclave. Throughput scalability favors Resin Infusion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Carbon fiber producers are arbitraging regulatory compliance costs by relocating precursor manufacturing to jurisdictions with streamlined environmental permitting. FAA certification requirements in the United States and EU Green Deal traceability mandates in Europe create divergent cost structures that reshape facility placement decisions.
United States
Boeing's next-generation narrowbody procurement pipeline drives qualification demand for PAN-based prepregs. FAA material traceability mandates for composite-intensive designs force suppliers to document precursor-to-component chain integrity. The Salt Lake City autoclave cluster sustains tier-1 aerostructures production under these certification protocols.
Japan
Toray Industries and Mitsubishi Chemical Corporation anchor global PAN precursor supply from domestic carbonization facilities. METI industrial policy supports pitch-based ultra-high modulus fiber development for satellite applications. Nagoya-area production complexes concentrate precursor spinning and surface treatment capacity for export markets.
Germany
Airbus supplier qualification pipelines concentrate demand in Bavaria and Hamburg aerostructures corridors. EASA CS-25 damage tolerance standards mandate extended fatigue databases for bonded repairs that lengthen material substitution cycles. SGL Carbon SE operates European precursor security through Moses Lake while maintaining German engineering headquarters.
China
State-directed capacity expansion targets import substitution in T800-grade carbon fiber for military aviation. MIIT standards harmonization with FAA damage tolerance protocols accelerates qualification for commercial export markets. Shandong and Jiangsu provinces concentrate new carbonization lines under dual carbon policy industrial prioritization.
France
Safran and Airbus engineering centers in Toulouse and Paris-Saclay dictate prepreg specification authority for European narrowbody programs. ANSM materials oversight converges with EASA airworthiness directives on composite repair certification. The Aquitaine region hosts thermoplastic resin infusion pilot lines targeting out-of-autoclave throughput gains.
Aerospace Carbon Fiber Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue thermoplastic processing and recycled fiber qualification to bypass incumbent autoclave networks. The supplier base concentrates around three archetypes: integrated precursor-to-prepreg conglomerates, specialized carbonization specialists, and resin compounders controlling formulation IP. Consolidation pressure intensifies as Boeing and Airbus reduce qualified supplier lists. Capacity expansion and backward integration into acrylonitrile feedstock represent the dominant competitive vectors.
Among Japanese integrated producers, Toray Industries and Mitsubishi Chemical Corporation exemplify the precursor-to-component conglomerate archetype. Hexcel Corporation anchors North American supply security through its Utah-based autoclave network. Solvay S.A. and Teijin Limited occupy positions within the European and Asian resin formulation tiers respectively. SGL Carbon SE represents the carbonization specialist model with transatlantic facility placement.
| Leading Market Players |
|---|
| Toray Industries |
| Hexcel Corporation |
| Solvay S.A. |
| Teijin Limited |
| SGL Carbon SE |
| Mitsubishi Chemical Corporation |
| DuPont de Nemours |
| BGF Industries |
| Bally Ribbon Mills |
| Others |
Supply Flow & Price Mechanics
Backward integration into acrylonitrile feedstock anchors both supply security and pricing power for Japanese conglomerates, while Western airframers absorb premium qualification costs under FAA material traceability mandates. This structural asymmetry compresses margin predictability for non-integrated compounders serving Boeing and Airbus procurement pipelines.
Pricing Analysis
Distributor margin capture concentrates in prepreg qualification tiers, where resin formulation IP separates premium-certified grades from standard industrial offerings. Price differentiation hinges on FAA/EASA certification database depth and automated fiber placement compatibility. Pricing pressure intensifies in secondary structures as airlines unbundle MRO services from original purchase agreements. Commercial aviation procurement teams exhibit highest price sensitivity, while satellite bus manufacturers tolerate premium pitch-based grades for thermal stability.
Supply Chain Analysis
Transpacific freight cost volatility compounds acrylonitrile feedstock exposure for Western compounders sourcing PAN precursor from Japan. Supply concentration clusters in Japan, the United States, and Germany, with raw material dependencies spanning petrochemical derivatives, specialty epoxy resins, and precision carbonization equipment. Single-source vulnerability persists in ultra-high modulus pitch-based fiber for space applications. Distribution runs through qualified tier-1 aerostructures suppliers with autoclave network access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where EU Green Deal lifecycle documentation costs diverge sharply from FAA-centric traceability investments, reshaping facility placement decisions for precursor and prepreg capacity.
For Market Incumbents: Extend qualification pipeline investments toward thermoplastic resin infusion alternatives that bypass autoclave bottlenecks without sacrificing FAA mechanical property compliance. Consolidate material specification authority as airlines fragment procurement across third-party MRO networks. Anchor backward integration into acrylonitrile supply to defend margin position against petrochemical input volatility.
For New Entrants and Emerging Players: Digital-channel qualification platforms offer lower-friction entry into UAV and satellite constellation segments where damage tolerance certification requirements permit accelerated substitution timelines. Target uncrewed platforms and low Earth orbit deployable structures as the most penetrable white-space categories. Pursue direct engagement with airline technical operations divisions disintermediating OEM engineering specifications.
For Investors and Strategic Acquirers: Roll-up economics work for regional carbonization specialists because EASA CS-25 and FAA damage tolerance mandates create sticky qualification relationships that resist price-based displacement. Five-to-ten year viability hinges on capturing reshoring procurement from Boeing's supplier pipeline. Watch thermoplastic out-of-autoclave certification milestones as the inflection signal for incumbent valuation compression.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Hexcel's Salt Lake City autoclave additions sustain narrowbody production schedules under FAA mandates. |
| Backward Integration | Toray's precursor spinning capacity in Nagoya secures PAN supply against petrochemical volatility. |
| Long-term Supply Agreement | SGL Carbon's Moses Lake facility locks in Boeing qualification pipeline through dedicated capacity. |
| Green Manufacturing Transition | EU Green Deal lifecycle documentation forces precursor-to-recycling emissions tracking for wing components. |
| Joint Venture | Thermoplastic resin infusion pilots in Aquitaine converge automated fiber placement with out-of-autoclave throughput. |
Methodological Framework
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combining interviews with tier-1 aerostructures procurement directors, FAA certification engineers, resin formulation R&D leads, and airline technical operations managers. Secondary validation draws from FAA airworthiness directive filings, EASA CS-25 amendment records, customs trade data on carbon fiber precursor flows, and SEC disclosures from listed composite manufacturers. Bottom-up segment sizing triangulates against top-down aerospace production forecasts.
Rate-of-change decomposition separates volume growth from value expansion across the analysis window, modeling product type, application tier, end-user category, and manufacturing process as core segmentation dimensions. CAGRs derive from aerospace OEM delivery schedules, satellite constellation deployment trajectories, and military program procurement cycles. Forecast inputs incorporate autoclave capacity utilization rates and qualification timeline compression from thermoplastic processing advances.
Acrylonitrile price volatility, regulatory amendment timing on bonded repair protocols, and reusable launch vehicle program acceleration are the dominant revision risks that could shift trajectory assumptions. Stakeholders should weight these inputs against their own operating context and supplier qualification exposure.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aerospace and Aircraft Materials
Aerospace Raw Materials Market
Aerospace and Aircraft Materials
Aircraft AFP and ATL Composites Market
Aerospace and Aircraft Materials
Global Aerospace Insulation Market
Aerospace and Aircraft Materials
Additive Manufactured Pressure Vessel Proof and Burst Test Rigs Market
Aerospace and Aircraft Materials
Fiberglass for Aerospace Market
Aerospace and Aircraft Materials
Aerospace Cold Forgings Market
Aerospace and Aircraft Materials
Aerospace Additive Manufacturing Market
Aerospace and Aircraft Materials
Aerospace 3D Printing Consumables Market
Aerospace and Aircraft Materials
Aerospace Fluoropolymers Market
Aerospace and Aircraft Materials
Aerospace Plastics Market
Aerospace and Aircraft Materials
Aerospace Superalloys Market
Aerospace and Aircraft Materials
Aerospace and Defense Materials Market
Aerospace and Aircraft Materials
Aircraft Soft Goods Market
Aerospace and Aircraft Materials
Global AFP/ATL Machines Market
Aerospace and Aircraft Materials
Aerospace Radome Market
Aerospace and Aircraft Materials
Aviation Carbon Fiber Market