
 Radiation Shielding Market | 2026-2036
Radiation Shielding Market Size, Share, and Industry Trends Forecast 2026-2036
Radiation Shielding Market Analytics
Buyer concentration among healthcare procurement groups is hardening as hospital networks consolidate radiology department purchasing across multi-site systems. ETS-Lindgren leverages its electromagnetic and ionizing radiation test chamber expertise to anchor contracts with major medical center networks. Nuclear Shields B.V. competes through specialized Dutch manufacturing of lead-free shielding barriers for European healthcare facilities. Burlington Medical sustains its position in the North American market through dedicated production of lightweight aprons and mobile shields for outpatient imaging centers.
Radiation shielding encompasses engineered materials and structural barriers designed to attenuate ionizing radiation through absorption, scattering, or reflection mechanisms, with lead-based systems typically achieving attenuation factors of 0.5 mm Pb equivalence for diagnostic applications and concrete barriers exceeding 2 m thickness for nuclear containment. The primary purpose is to protect personnel, patients, and environments from stochastic and deterministic health effects of gamma rays, X-rays, and neutron flux in medical, industrial, and energy settings. Lead remains the dominant material type due to its high atomic number and proven regulatory acceptance, though polyethylene segments gain traction for neutron moderation in research and nuclear waste management applications where hydrogen density matters more than photon attenuation. Medical imaging as an application area commands the largest installed base of shielding products, while radiation therapy represents the fastest-expanding margin pool as proton and heavy-ion facilities require precisely engineered barriers with multi-material layering.
The NRC enforces 10 CFR Part 20 dose limits that mandate facility-specific shielding designs and periodic compliance audits for medical and industrial licensees. EPA regulations under 40 CFR Part 190 constrain environmental releases from nuclear fuel cycle operations, directly influencing waste management shielding specifications. ISO 9001 and IEC 61223 quality frameworks shape product certification requirements for equipment sold into regulated healthcare and nuclear markets. Stakeholders must monitor evolving lead-restriction mandates in the European Union and corresponding material substitution timelines that will reshape supplier qualification criteria and testing protocols.
Market Dynamics
Hospital network consolidation is compressing procurement timelines and forcing shielding suppliers to reconfigure service models around multi-site contracting frameworks rather than single-facility sales cycles.
Growth Catalysts
- 10 CFR Part 20 dose-limit enforcement:The NRC's stricter audit protocols compel US medical facilities to upgrade barrier systems ahead of license renewal cycles.
- Proton therapy facility construction:Heavy-ion treatment centers require precisely engineered multi-material shielding barriers that command premium specification tiers.
- Germany:Nuclear decommissioning programs and medical infrastructure renewal sustain procurement velocity for lead and polyethylene-based solutions.
Market Restraints
- Lead price volatility:Primary lead smelter concentration in China creates input cost instability for traditional shielding manufacturers.
- REACH lead-restriction timelines:European material substitution mandates force premature R&D redeployment before alternative compounds achieve regulatory equivalence.
- Concrete barrier thickness requirements:Nuclear containment specifications exceeding two meters constrain retrofit feasibility in existing facility footprints.
Strategic Opportunities
- Outpatient imaging center expansion:Mobile shielding and lightweight apron demand concentrates in North American freestanding diagnostic chains.
- Neutron moderation applications:Polyethylene segments gain specification share in research reactor decommissioning and waste management where hydrogen density dominates photon attenuation.
- CE marking harmonization:Streamlined EU medical device regulation reduces certification friction for multi-country hospital network contracts.
Industry Challenges
- Radiation health physics specialist scarcity:Qualified shielding design engineers remain concentrated in legacy nuclear markets, constraining project velocity.
- Multi-material layering certification:Proton facility barriers require sequential testing protocols that extend compliance timelines.
- Legacy lead apron disposal:Hazardous waste handling regulations complicate replacement cycles for hospital protective equipment fleets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Radiation Shielding Market |
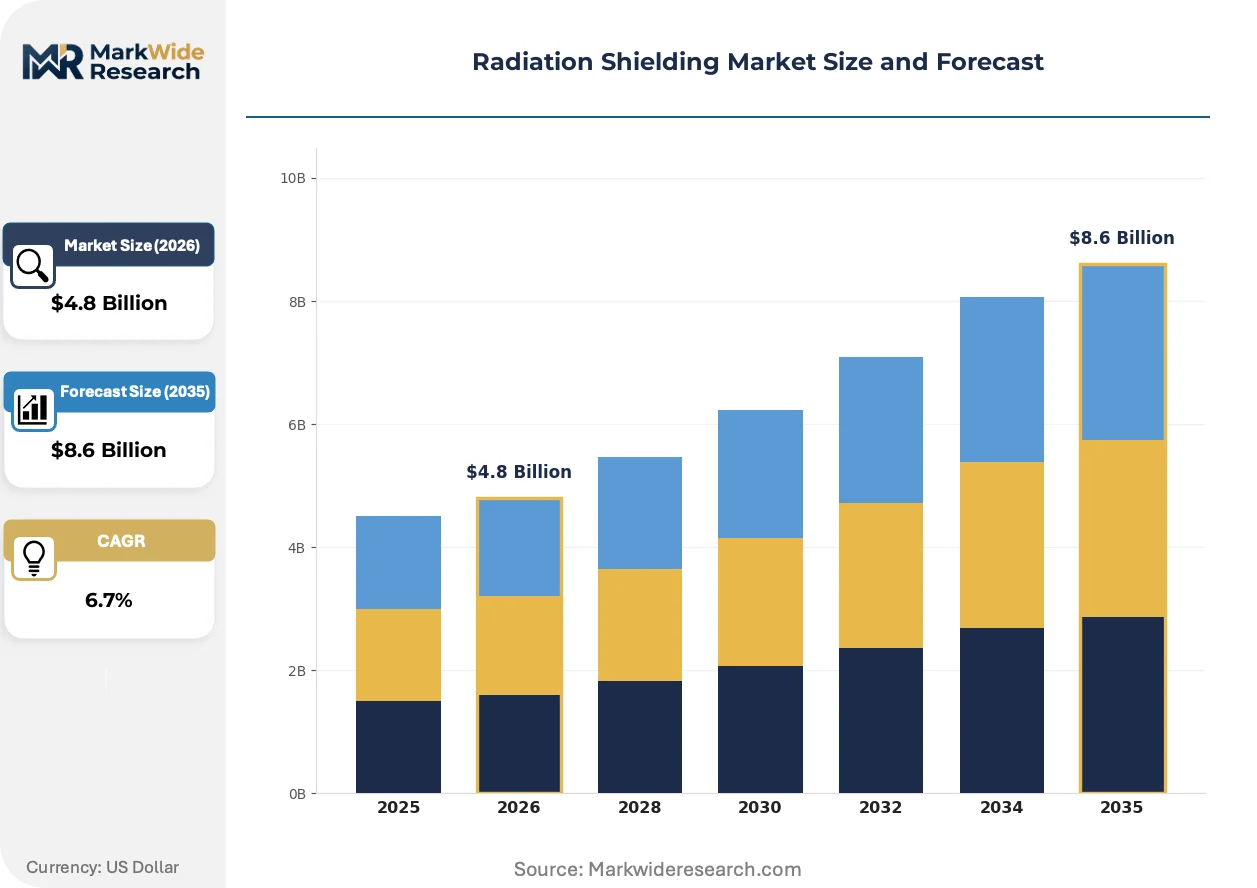
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Lead, Barium, Polyethylene, Concrete Product Form: Sheets, Plates, Coatings, Barriers End User: Healthcare Facilities, Nuclear Power Plants, Research Institutions, Industrial Applications Application Area: Medical Imaging, Radiation Therapy, Nuclear Waste Management, Industrial Radiography |
| Companies Covered | Infab LLC, Nuclear Shields B.V., ETS-Lindgren, Burlington Medical, MarShield, Ray-Bar Engineering Corp, NELCO, Gaven Industries, Radiation Protection Products, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Radiation Shielding Market Evolving Landscape
Material science advances and regulatory chemistry restrictions are fragmenting the traditional lead-dominant specification landscape into a multi-compound competitive arena where hydrogen-rich moderators and composite barriers gain technical legitimacy.
Polyethylene-based neutron shielding is decentralizing the historical lead monopoly in research and waste management applications. National laboratories and decommissioning contractors specify hydrogen-dense moderators for neutron flux environments where photon attenuation remains secondary. This material pivot compresses lead demand concentration in non-medical segments.
RoHS lead-restriction mandates are forcing European manufacturers to accelerate tungsten and bismuth composite qualification timelines. The ECHA substance restriction roadmap eliminates grandfathered lead exemptions for non-medical industrial shielding by 2027. German and Dutch suppliers front-load alternative material certification to defend healthcare market access.
Hospital procurement groups now unbundle shielding specification from equipment vendor packages to secure multi-site volume leverage. Radiology department consolidations across US and German hospital networks displace single-facility purchasing autonomy. This concentration is most visible in American metropolitan health systems where three-facility minimum orders have become standard contracting thresholds.
Radiation Shielding Market Segmentation
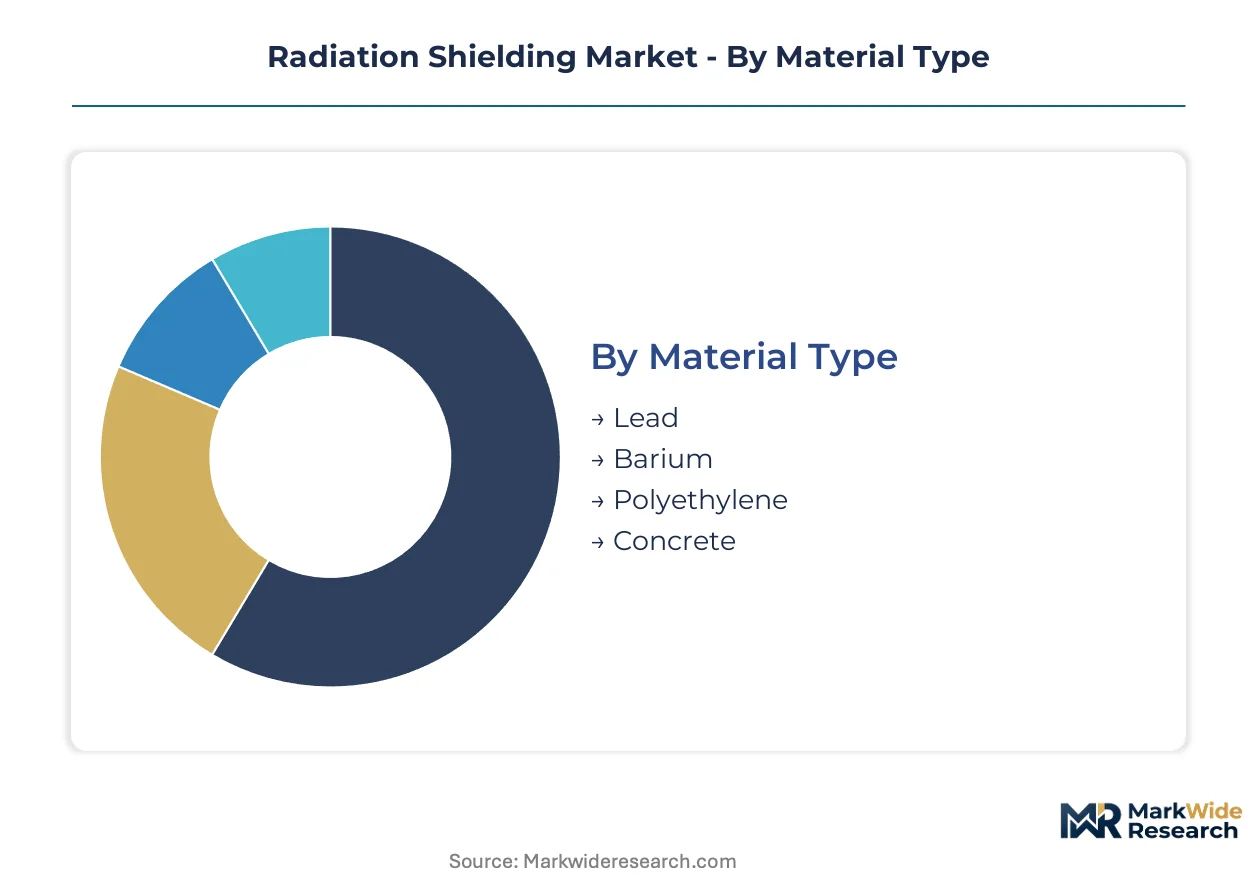
Material selection in radiation shielding hinges on attenuation requirements, regulatory chemistry restrictions, and facility retrofit constraints. Procurement groups increasingly unbundle material specification from equipment vendor packages to secure multi-site volume leverage.
Material Type:
Buyer specification decisions center on atomic number, hydrogen density, and REACH compliance timelines rather than unit cost alone.
- Lead:High atomic number delivers proven photon attenuation for diagnostic suites. German and US hospital networks specify lead barriers for CT and general radiography installations where regulatory grandfathering persists.
- Polyethylene:Hydrogen-rich structure moderates neutron flux in research reactor decommissioning and waste management applications. Demand concentrates at national laboratories where photon attenuation remains secondary to neutron thermalization.
- Barium:Composite formulations substitute for lead in apron and mobile shielding where weight reduction matters. European manufacturers accelerate barium qualification ahead of ECHA restriction deadlines.
- Concrete:Density exceeds 2 m thickness for nuclear containment specifications. Retrofit feasibility constraints limit concrete barrier deployment to greenfield proton therapy and heavy-ion facilities.
Volume sits with lead; growth tilts toward polyethylene.
Product Form:
Form factor selection reflects installation logistics, replacement cycle frequency, and facility mobility requirements.
- Sheets:Rolled lead or polyethylene sheet stock enables custom fabrication for irregular barrier geometries. US outpatient imaging chains specify sheet material for rapid deployment across multi-site rollouts.
- Barriers:Pre-engineered wall and ceiling systems command premium specification tiers in proton therapy construction. German decommissioning contractors deploy modular barriers for temporary containment during reactor dismantling.
- Plates:Cast lead plates serve permanent installations in nuclear medicine hot labs and radiopharmaceutical production. Plate thickness correlates directly to isotope activity levels.
- Coatings:Spray-applied or rolled shielding coatings address retrofit applications where structural modification is prohibited. Coatings gain traction in heritage building conversions for medical use.
Barrier systems capture the steepest expansion trajectory; sheets retain the largest installed base.
End User:
End-user procurement autonomy varies sharply by sector consolidation patterns and regulatory audit intensity.
- Healthcare Facilities:Hospital network consolidation compresses purchasing timelines across radiology department rollouts. Three-facility minimum orders have become standard contracting thresholds in US metropolitan health systems.
- Nuclear Power Plants:Decommissioning programs in Germany sustain procurement velocity for lead and polyethylene solutions. Plant operators specify shielding for spent fuel pool coverage and reactor vessel segmentation.
- Research Institutions:National laboratories drive neutron moderation demand where hydrogen density dominates material selection. Research shielding procurement cycles align with federal budget authorization timelines.
- Industrial Applications:Non-destructive testing and pipeline inspection generate cyclical demand for portable shielding. Industrial buyers prioritize lead price stability over material innovation.
Healthcare commands the largest revenue pool; nuclear decommissioning shows the fastest specification growth.
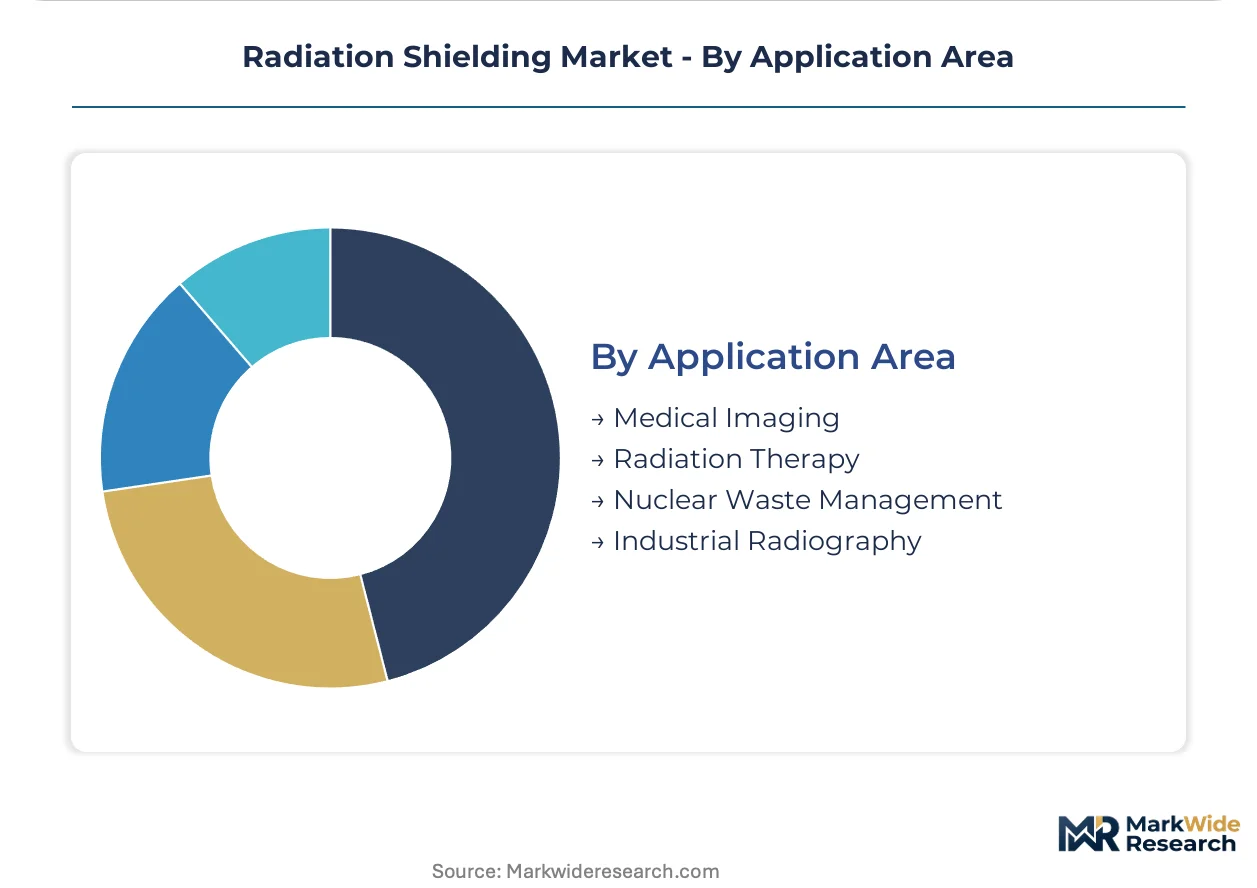
Application Area:
Application-specific shielding requirements diverge on dose rate, occupancy factor, and regulatory jurisdiction.
- Medical Imaging:CT suites and interventional radiography rooms specify 0.5 mm Pb equivalence for diagnostic barriers. Imaging center expansion concentrates demand for mobile shields and lightweight apron fleets.
- Radiation Therapy:Proton and heavy-ion facilities require multi-material layering with precisely engineered attenuation profiles. Therapy shielding commands the highest specification premiums in the product portfolio.
- Nuclear Waste Management:Cask shielding and interim storage barriers prioritize long-term material stability under thermal and radiation load. Waste management specifications reference EPA 40 CFR Part 190 constraints.
- Industrial Radiography:Gamma radiography enclosures and pipeline crawler shielding emphasize portability and rapid deployment. Industrial radiography procurement tracks oil and gas infrastructure inspection cycles.
Medical imaging anchors current volume; radiation therapy delivers the fastest margin expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Lead smelter concentration in China creates input cost instability that ripples through fabrication centers in Germany, the United States, and the Netherlands. Hospital network consolidation and nuclear decommissioning programs concentrate procurement velocity in specific metropolitan clusters.
United States
Metropolitan health systems in Chicago, Houston, and Atlanta drive multi-site radiology department rollouts with three-facility minimum contracting thresholds. The NRC enforces 10 CFR Part 20 dose-limit standards that compel barrier upgrades ahead of license renewal cycles. Boston and New York medical centers anchor proton therapy construction requiring precisely engineered multi-material shielding barriers.
Germany
Nuclear decommissioning programs at Biblis and Philippsburg sustain procurement velocity for lead and polyethylene-based containment solutions. ECHA substance restriction timelines under REACH force accelerated tungsten and bismuth composite qualification before 2027 deadlines. The Ruhr industrial corridor concentrates fabrication capacity for reactor vessel segmentation shielding.
Netherlands
Dutch manufacturing clusters specialize in lead-free shielding barriers for European healthcare facilities facing RoHS chemistry mandates. The Port of Rotterdam serves as a distribution hub for polyethylene neutron moderation materials bound for research institutions. Eindhoven-based suppliers front-load alternative material certification to defend hospital network contracts.
China
Primary lead smelter concentration in Henan and Yunnan provinces creates input cost volatility transmitted to downstream fabricators. The NMPA regulates medical device shielding certification while MIIT oversees industrial radiography equipment standards. Shanghai and Beijing medical centers expand CT suite installations requiring 0.5 mm Pb equivalence barriers.
Japan
Heavy-ion therapy facilities in Chiba and Hyogo prefectures command premium specification tiers for multi-material layering barriers. METI coordinates national laboratory procurement for research reactor decommissioning shielding. The Kansai region concentrates neutron moderation demand where hydrogen density dominates material selection criteria.
Radiation Shielding Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue lead-free chemistry certifications ahead of European restriction deadlines. The vendor base stratifies across electromagnetic test chamber specialists, dedicated medical shielding fabricators, and nuclear containment contractors. Three archetypes dominate: multi-technology conglomerates with electromagnetic expertise, specialized European manufacturers of non-lead barriers, and North American producers of lightweight mobile shielding. Competitive moves concentrate on multi-site hospital network contracting and accelerated alternative material qualification timelines.
Within the electromagnetic and ionizing radiation test chamber tier, ETS-Lindgren anchors contracts with major medical center networks through combined expertise. Among European specialists, Nuclear Shields B.V. occupies a position exemplifying Dutch manufacturing concentration in lead-free barrier solutions. At the lightweight mobile shielding vector, Burlington Medical represents North American production dedicated to outpatient imaging center requirements.
| Leading Market Players |
|---|
| Infab LLC |
| Nuclear Shields B.V. |
| ETS-Lindgren |
| Burlington Medical |
| MarShield |
| Ray-Bar Engineering Corp |
| NELCO |
| Gaven Industries |
| Radiation Protection Products |
| Others |
Value Network & Pricing Analysis
Radiation health physics specialists concentrated in legacy nuclear markets drive labor-cost differentials that widen pricing-tier spreads between premium proton therapy barriers and standard diagnostic shielding.
Pricing Analysis
Volume concentrates in lead-sheet stock for CT suites while margins concentrate in multi-material proton therapy barriers. Three-tier pricing structure across premium, standard, and economy levels separates certified proton facility systems from hospital network diagnostic contracts and industrial radiography commodity purchases. Price differentiation rests on NRC audit-grade certification and multi-site volume scale. Cost compression in standard lead barriers is intensifying because primary smelter concentration in China transmits volatility downstream. Outpatient imaging chains exhibit highest price sensitivity; proton therapy developers accept premium specifications.
Supply Chain Analysis
Dual-sourcing requirements from hospital network procurement groups mandate multi-supplier qualification for lead sheet and polyethylene neutron moderators. Geographic supply concentrates in China for primary lead, Germany for fabricated barriers, and the Netherlands for lead-free alternatives. Raw material dependencies center on lead ingots, high-density polyethylene resin, and tungsten-bismuth composite feedstock. Single-source vulnerability in Chinese primary smelting creates structural risk. Distribution runs through medical equipment distributors and direct contracting with hospital GPOs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a vertical-integration race. Players pursue backward integration into lead recycling and captive polymer compounding to secure input cost control against Chinese smelter volatility.
For Market Incumbents: Anchor multi-site hospital network contracts through integrated design-build-service offerings that emerging lead-free specialists cannot replicate. Invest in tungsten-bismuth composite certification ahead of ECHA deadlines. Deepen vertical integration into spent lead apron recycling to control hazardous waste handling costs and tighten replacement cycle capture.
For New Entrants and Emerging Players: Hydrogen-rich neutron moderation compounds offer a technology-first wedge into national laboratory and decommissioning contractor procurement where lead incumbents lack technical depth. Target German nuclear decommissioning programs and Japanese heavy-ion research facilities as underpenetrated segments. Lead with polyethylene-based temporary containment systems that bypass legacy lead fabrication capacity constraints.
For Investors and Strategic Acquirers: The window for entry favors lead-free chemistry specialists with REACH pre-certification and established European hospital network relationships. Five-to-ten year viability hinges on material substitution velocity outpacing regulatory grandfathering. Watch ECHA enforcement intensity against lead exemptions as the inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Lead-Free Material Certification | ECHA REACH pre-qualification secures European hospital network access before 2027 restriction deadlines. |
| Multi-Site Hospital Contracting | Three-facility minimum thresholds concentrate purchasing power with integrated design-build vendors. |
| Proton Therapy Barrier Engineering | Multi-material layering expertise commands premium specification tiers in Boston and New York medical centers. |
| Spent Apron Recycling Integration | Hazardous waste handling control tightens replacement cycle capture in US outpatient imaging chains. |
| Neutron Moderation Compound Development | Hydrogen-dense polyethylene formulations penetrate national laboratory procurement in Germany and Japan. |
Research Methodology
Trade data from the US International Trade Commission, Eurostat customs records, and Japanese METI industrial statistics formed the secondary backbone. Primary interviews with radiation health physicists, hospital GPO contract managers, nuclear decommissioning procurement officers, and lead fabricator operations directors combined with bottom-up and top-down triangulation. Secondary validation drew from NRC license renewal databases, ECHA substance restriction roadmaps, and ISO 9001 certification registries.
Bottom-up modeling anchored volume estimates in facility-specific shielding specifications by material type and installation geometry. Top-down cross-checks referenced national healthcare infrastructure spending patterns and nuclear decommissioning program budgets. Segmentation dimensions included material chemistry, product form factor, end-user sector procurement autonomy, and application-specific attenuation requirements. CAGRs derived from regression against historical procurement velocity and regulatory compliance cycle timing.
Several conditions sit outside the modeled scope, including military and defense shielding applications, spacecraft radiation protection, and speculative fusion reactor construction timelines. Forecasts reflect assumptions about ECHA enforcement intensity, NRC audit protocol continuity, and Chinese lead smelter output stability. Deviation in REACH grandfathering timelines or proton therapy construction financing availability would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aerospace and Aircraft Materials
Aircraft Soft Goods Market
Aerospace and Aircraft Materials
Europe Aerospace Composites Market
Aerospace and Aircraft Materials
Global Military Aerospace Coatings Market
Aerospace and Aircraft Materials
Titanium Aerospace Forgings Market
Aerospace and Aircraft Materials
Aircraft Aluminium Plate Market
Aerospace and Aircraft Materials
Aerospace Superalloys Market
Aerospace and Aircraft Materials
Aerospace Coatings Market
Aerospace and Aircraft Materials
Aluminum Titanate Market
Aerospace and Aircraft Materials
Aerospace Composites Market
Aerospace and Aircraft Materials
Stealth Coating Market
Aerospace and Aircraft Materials
Beryllium Aluminum Alloy Market
Aerospace and Aircraft Materials
Aerogel Blanket Market
Aerospace and Aircraft Materials
Aerographite Market
Aerospace and Aircraft Materials
Aerospace Materials Market
Aerospace and Aircraft Materials
Global AFP/ATL Machines Market
Aerospace and Aircraft Materials
Commercial Aerospace 3D Printing Market