
 Global Anti-Icing Coating Market | 2026-2036
Global Anti-Icing Coating Market Size, Share, and Industry Trends Forecast 2026-2036
Global Anti-Icing Coating Market Foresight
China is narrowing its reliance on imported anti-icing coating precursors through domestic fluoropolymer synthesis expansions in Jiangsu province. BASF SE leverages integrated silicone resin supply chains to sustain European aerospace qualification programs. PPG Industries anchors North American aftermarket demand through MRO channel density. Hempel A/S specializes in marine-grade formulations that compete on salt-spray durability across Nordic shipping lanes.
Anti-icing coatings constitute functional surface treatments engineered to prevent ice nucleation and adhesion through low surface energy chemistry, typically incorporating fluorinated or silicone-modified polymers with contact angles exceeding 150 degrees for superhydrophobic variants. These formulations serve critical de-icing and anti-icing roles across transportation and energy infrastructure exposed to sub-zero operating conditions. Fluoropolymer-based chemistries command premium positioning due to extreme durability requirements in aerospace nacelle applications, while silicone-based alternatives occupy broader marine and construction equipment markets where cost-performance thresholds differ. Hydrophobic technology dominates current volume deployment, though electrothermal integration represents the fastest-growing architecture as wind turbine OEMs seek active-passive hybrid ice management.
FAA airworthiness standards, EASA CS-25 icing certification requirements, and China's GB/T aviation material specifications collectively shape product qualification pathways and market access barriers. REACH restrictions on long-chain perfluorinated substances are forcing reformulation investments across European supply chains, redirecting R&D toward shorter-chain fluorinated and non-fluorinated alternatives. Stakeholders must monitor regulatory divergence between jurisdictions on acceptable chemistries, as compliance fragmentation threatens to segment supply chains by geography rather than performance tier.
Market Dynamics
Electrothermal-hybrid architectures are fragmenting procurement patterns across wind energy and aerospace verticals, forcing coating suppliers to requalify products for integrated active-passive systems rather than standalone surface treatments.
Growth Catalysts
- REACH reformulation mandates:European restrictions on long-chain perfluorinated substances are redirecting R&D investment toward shorter-chain fluorinated alternatives, accelerating qualification of next-generation chemistries.
- Wind turbine OEM procurement:Offshore installations in the North Sea and Baltic are specifying superhydrophobic coatings as mandatory components of ice management systems under German BSH certification requirements.
- FAA airworthiness directives:Updated ice protection system standards for regional aircraft fleets are compelling MRO providers to upgrade legacy surfaces with qualified anti-icing formulations.
Market Restraints
- Fluoropolymer precursor concentration:Synthesis capabilities for high-performance resins cluster in China and Germany, exposing supply chains to export control volatility and logistics bottlenecks.
- Qualification timeline compression:EASA CS-25 icing certification requires 24-36 months of flight testing, locking capital in pre-revenue product development cycles.
- Electrothermal substitution:Active heating systems for wind turbine blades are capturing share in markets with reliable grid access, narrowing the addressable market for passive coatings in Northern Europe.
Strategic Opportunities
- India aerospace MRO expansion:Greenfield maintenance facilities in Bengaluru and Hyderabad lack qualified coating applicators, creating first-mover advantage for technical service partnerships.
- GB/T aviation material specifications:China's domestic certification pathway for imported formulations is streamlining, reducing market entry friction for qualified suppliers.
- Marine superstructure convergence:Salt-spray durability requirements for Arctic shipping routes are merging anti-icing and anti-corrosion specifications into unified coating procurement.
Industry Challenges
- Fluoropolymer synthesis talent scarcity:Specialized polymer chemists with aerospace qualification experience command premium compensation, constraining formulation team scaling.
- Dual-certification complexity:Products must simultaneously satisfy FAA airworthiness directives and EASA CS-25 requirements, doubling documentation and testing overhead.
- Legacy fleet retrofit integration:Older aircraft surfaces require substrate preparation protocols incompatible with next-generation coating adhesion chemistries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Anti-Icing Coating Market |
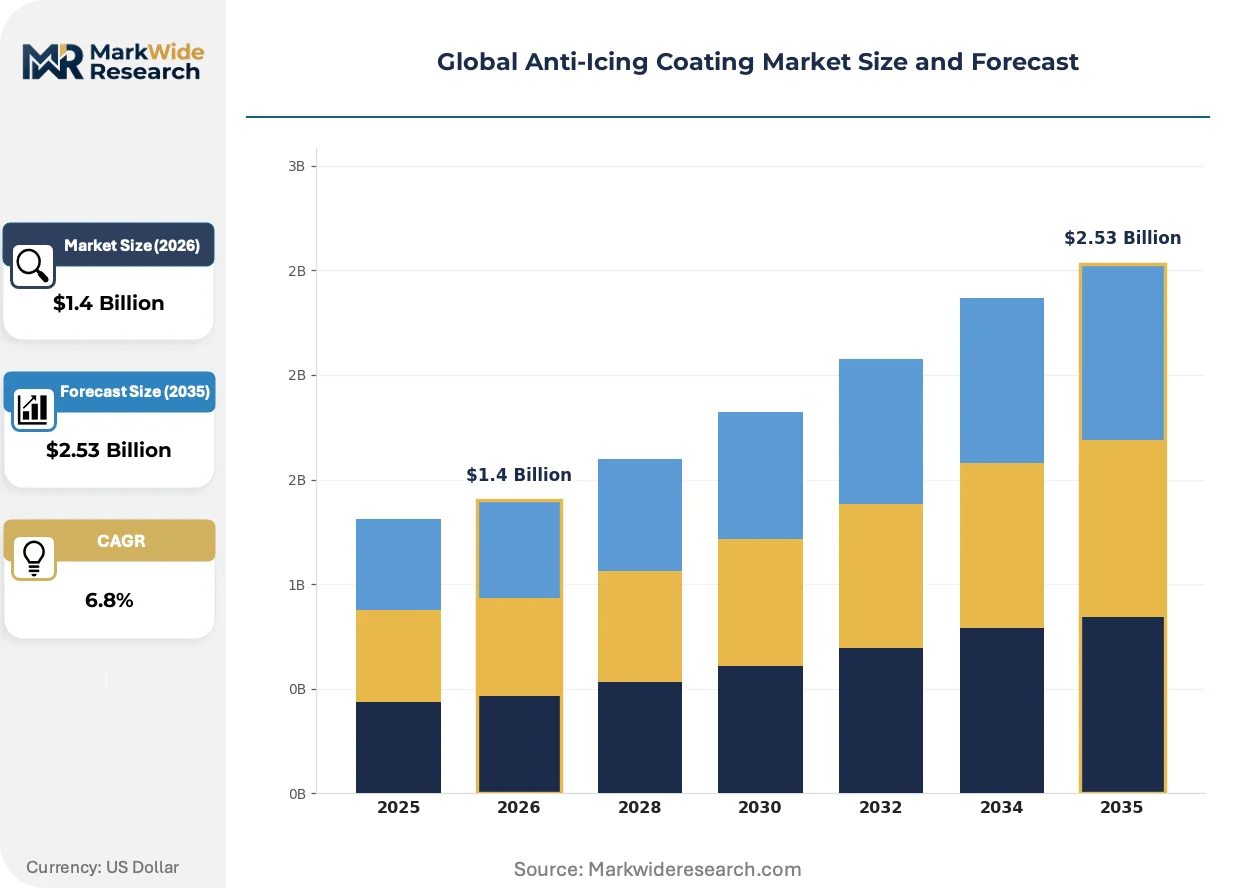
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.53 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Silicone-Based, Fluoropolymer-Based, Acrylic-Based, Polyurethane-Based, Epoxy-Based Application: Aerospace, Marine Vessels, Wind Turbines, Electrical Transmission Lines, Construction Equipment Technology: Hydrophobic, Hydrophilic, Superhydrophobic, Electrothermal, Photocatalytic End User: Aircraft Manufacturers, Energy Producers, Shipping Companies, Infrastructure Operators, OEMs |
| Companies Covered | BASF SE, Jotun A/S, The Sherwin-Williams Company, Kansai Paint Co., Ltd., Hempel A/S, PPG Industries, Inc., Axalta Coating Systems Ltd., DuPont, Akzo Nobel N.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Anti-Icing Coating Market Shifts & Advancements
Formulation chemistry is pivoting from passive hydrophobicity toward multifunctional surfaces that combine icephobicity with sensing, heating, or structural health monitoring capabilities.
Graphene-doped silicone matrices are rendering obsolete conventional fluoropolymer monolayers in wind turbine leading-edge applications. Vestas and Siemens Gamesa are qualifying these conductive coatings at pilot scale in Denmark and Spain. The technology enables embedded resistive heating without separate wiring harnesses, collapsing installation labor costs and maintenance intervals for offshore assets.
EU F-Gas Regulation phase-down schedules are restricting hydrofluorocarbon propellants in coating application processes. Formulators are reformulating spray systems around compressed CO2 and hydrocarbon carriers, increasing equipment capital requirements but preserving market access. Aerospace OEMs in France and Italy face the steepest compliance deadlines, accelerating supplier audits for alternative application technologies.
Buyer consolidation among European wind farm operators is compressing vendor qualification cycles and unbundling coating supply from blade manufacturing contracts. Independent service providers in Hamburg and Rotterdam are capturing aftermarket application volume previously held by OEM-integrated channels. This disintermediation is most pronounced in the North Sea, where turbine density supports dedicated regional coating service fleets.
Global Anti-Icing Coating Market Segmentation
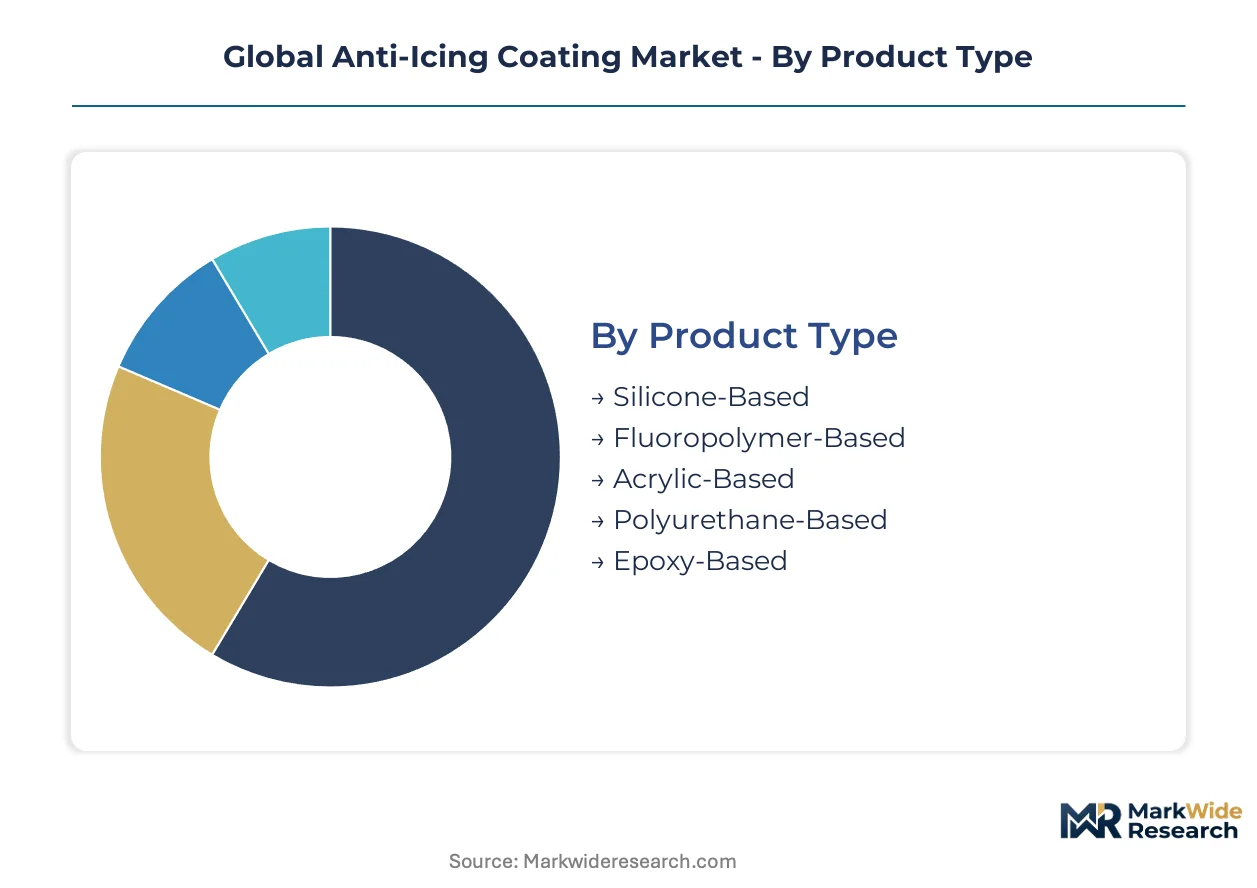
Anti-icing coatings serve divergent performance requirements across aerospace, marine, and energy infrastructure. Segmentation reveals how formulation chemistry, application environment, and integration architecture determine procurement decisions and supplier positioning.
Product Type:
Use-case spectrum spans from extreme durability aerospace nacelles to cost-sensitive construction machinery, with chemistry selection dictated by surface energy requirements and environmental exposure severity.
- Fluoropolymer-Based:Perfluorinated resin systems deliver contact angles exceeding 150 degrees and thermal stability above 250°C. Aerospace OEMs in France and Italy specify these for engine nacelle leading edges under EASA CS-25 icing certification. REACH restrictions on long-chain perfluorinated substances are forcing reformulation toward shorter-chain alternatives.
- Silicone-Based:Polysiloxane backbone formulations offer UV stability and salt-spray resistance at moderate cost points. Marine operators across Nordic shipping lanes favor these for superstructure ice protection where fluoropolymer premiums are unjustified. BASF SE maintains integrated supply chain dominance for European qualification programs.
- Acrylic-Based:Waterborne systems with moderate hydrophobicity serve construction equipment and temporary protective applications.
- Polyurethane-Based:Tough, abrasion-resistant films integrate well with structural coatings for wind turbine blade roots.
- Epoxy-Based:Rigid, chemically resistant substrates anchor multi-layer systems in electrical transmission infrastructure.
The dominant share belongs to fluoropolymer-based formulations, while silicone-based alternatives are closing the gap fastest through marine and wind energy volume expansion.
Application:
Cost tier separation distinguishes specification-grade aerospace procurement from aftermarket marine and infrastructure maintenance cycles.
- Aerospace:Flight-critical surfaces demand FAA airworthiness directive compliance and 24-36 month qualification timelines. PPG Industries anchors North American aftermarket demand through MRO channel density. Electrothermal-hybrid architectures are fragmenting procurement patterns toward integrated active-passive systems.
- Wind Turbines:Offshore installations in the North Sea and Baltic specify superhydrophobic coatings as mandatory under German BSH certification. Vestas and Siemens Gamesa are qualifying graphene-doped silicone matrices at pilot scale in Denmark and Spain.
- Marine Vessels:Salt-spray durability requirements for Arctic shipping routes merge anti-icing and anti-corrosion specifications.
- Electrical Transmission Lines:Grid operators in cold climate zones apply passive coatings to reduce ice loading and conductor galloping.
- Construction Equipment:Seasonal cold-weather operations drive aftermarket spray applications with lower durability requirements.
Aerospace commands premium pricing tiers, though wind turbine applications are expanding most quickly through offshore installation mandates.
Technology:
Volume concentration favors mature hydrophobic chemistries, while margin migration follows electrothermal integration and multifunctional surface architectures.
- Superhydrophobic:Micro- and nano-structured surfaces achieve contact angles above 150 degrees through combined chemical and topographical effects. German wind turbine operators face mandatory performance standards for offshore installations. EU F-Gas Regulation phase-down is restricting application propellants and accelerating equipment upgrades.
- Electrothermal:Embedded resistive heating layers enable active ice management without separate wiring harnesses. Graphene-doped silicone matrices collapse installation labor costs for offshore wind assets. This architecture is displacing passive-only systems in markets with reliable grid access.
- Hydrophobic:Conventional low-surface-energy treatments dominate current deployment volume across transportation and infrastructure.
- Hydrophilic:Icephobic surfaces that disrupt hydrogen bonding at the ice-substrate interface remain developmental for most commercial applications.
- Photocatalytic:Titanium dioxide-based systems offer self-cleaning alongside modest anti-icing performance in architectural and limited industrial settings.
Hydrophobic technology retains installed base dominance, yet electrothermal systems are gaining share fastest through wind energy OEM procurement.
End User:
Customer type determines contract structure, with OEM-integrated channels giving way to independent service providers in maturing aftermarket segments.
- Energy Producers:Wind farm operators in the North Sea are consolidating vendor bases and compressing qualification cycles. Buyer consolidation is unbundling coating supply from blade manufacturing contracts. Independent service providers in Hamburg and Rotterdam capture aftermarket volume previously held by OEM-integrated channels.
- Aircraft Manufacturers:Commercial and regional jet programs specify qualified coatings at design phase, locking suppliers into multi-year production agreements. China is narrowing reliance on imported precursors through domestic fluoropolymer synthesis expansions in Jiangsu province.
- Shipping Companies:Nordic and Arctic route operators specify marine-grade formulations competing on salt-spray durability.
- Infrastructure Operators:Grid and construction asset managers prioritize total cost of ownership over initial material expense.
- OEMs:Equipment manufacturers across verticals integrate coating specifications into supplier quality requirements.
Aircraft manufacturers anchor qualification-intensive premium segments, while energy producers are driving volume scaling fastest through offshore wind deployment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FAA airworthiness directives anchor the United States as the regulatory benchmark for ice protection system certification, while EASA CS-25 requirements and China's GB/T aviation material specifications create parallel qualification pathways across manufacturing clusters in Germany, China, and France.
United States
Regional aircraft fleet upgrades drive coating procurement through FAA-mandated ice protection system overhauls. MRO providers in Wichita and Dallas-Fort Worth anchor North American aftermarket application capacity. PPG Industries leverages channel density across these maintenance hubs to capture recurring specification-grade demand.
Germany
Offshore wind installations in the North Sea and Baltic specify superhydrophobic coatings under BSH certification mandates. Hamburg and Rotterdam service clusters capture aftermarket volume from disintermediated blade manufacturing contracts. REACH restrictions on long-chain perfluorinated substances force reformulation investments across domestic supply chains.
China
Domestic fluoropolymer synthesis expansions in Jiangsu province narrow reliance on imported precursors. GB/T aviation material specifications streamline qualification pathways for imported formulations. Beijing-Tianjin-Hebei and Yangtze River Delta clusters concentrate aerospace OEM procurement and wind turbine manufacturing integration.
France
Engine nacelle leading-edge applications demand EASA CS-25 icing certification with 24-36 month flight testing timelines. Toulouse and Bordeaux aerospace clusters lock suppliers into multi-year production agreements for commercial jet programs. EU F-Gas Regulation phase-down accelerates supplier audits for alternative spray application technologies.
Denmark
Vestas and Siemens Gamesa qualify graphene-doped silicone matrices at pilot scale for embedded resistive heating integration. Copenhagen and Aarhus R&D clusters collapse installation labor costs for offshore wind assets through conductive coating architectures. Danish technical partnerships extend qualification protocols across Nordic shipping route specifications.
Global Anti-Icing Coating Market Competitive Landscape
Integrated chemical conglomerates and specialized coating formulators split the market across qualification-intensive aerospace tiers and volume-driven marine and energy segments. European suppliers leverage REACH-compliant reformulation capabilities to sustain premium positioning, while Asian manufacturers exploit domestic precursor access for cost-advantaged expansion. Consolidation pressure concentrates around M&A activity targeting aerospace qualification assets and strategic partnerships for electrothermal-hybrid system integration.
Among Germany-based chemical conglomerates, BASF SE anchors integrated silicone resin supply chains for European aerospace programs. Danish specialist Hempel A/S occupies marine-grade formulation positioning across Nordic salt-spray durability requirements. US industrial coatings leader PPG Industries exemplifies MRO channel density strategies for North American aftermarket capture. These three archetypes represent distinct competitive vectors: upstream chemical integration, vertical specialization, and distribution infrastructure control.
| Leading Market Players |
|---|
| BASF SE |
| Jotun A/S |
| The Sherwin-Williams Company |
| Kansai Paint Co., Ltd. |
| Hempel A/S |
| PPG Industries, Inc. |
| Axalta Coating Systems Ltd. |
| DuPont |
| Akzo Nobel N.V. |
| Others |
Supply & Pricing Matrix
Jiangsu province's fluoropolymer synthesis expansions are compressing precursor costs for domestic Chinese formulators while elevating pricing power for qualified European suppliers serving aerospace certification tiers. This geographic bifurcation in supply capability translates directly into tiered pricing structures across the value chain.
Pricing Analysis
Geographic price spreads of 40-60% separate REACH-compliant European formulations from cost-optimized Asian alternatives. Three-tier pricing structure across aerospace-qualified premium, industrial-standard, and economy-grade construction tiers dominates procurement frameworks. Price differentiation hinges on EASA CS-25 certification status and fluoropolymer chain length compliance. Margins are tightening in the industrial mid-tier due to electrothermal hybrid substitution in Northern European wind markets. Construction equipment buyers exhibit highest price sensitivity, while aerospace OEMs prioritize qualification certainty over unit cost.
Supply Chain Analysis
Tariff exposure between China and Germany dominates supply chain risk calculations for fluoropolymer resin flows. Synthesis capabilities cluster in China, Germany, and the United States, with Jiangsu province and the Ruhr Valley anchoring high-performance resin production. Raw material dependencies center on perfluorinated monomers, silicone precursors, and graphene feedstocks. Single-source vulnerability persists for aerospace-grade fluoropolymer qualification batches. Distribution runs through OEM-integrated channels for aerospace, independent service fleets for wind energy aftermarket, and marine coating distributors for Nordic shipping.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among European wind farm operators and Chinese aerospace OEMs, compressing vendor margins and accelerating qualification cycle demands. This consolidation fragments supplier pricing leverage across the value chain.
For Market Incumbents: Entrench certification assets by accelerating REACH-compliant shorter-chain fluoropolymer qualification timelines before regulatory deadlines harden. Deepen backward integration into silicone resin production to defend margin position against electrothermal substitution in offshore wind. Lock multi-year production agreements with Toulouse and Hamburg aerospace clusters to preempt competitor entry.
For New Entrants and Emerging Players: Build out technical service partnerships in Bengaluru and Hyderabad MRO corridors where qualified coating applicators remain scarce. Target India's aerospace aftermarket as the most penetrable geography given greenfield facility expansion and absence of entrenched service infrastructure. Pursue joint qualification pathways with Vestas and Siemens Gamesa for graphene-doped silicone pilot programs.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-arbitrage play because jurisdictional divergence on fluorinated chemistry acceptance will segment supply chains by compliance tier rather than performance. Acquisition targets should prioritize European formulators with active REACH reformulation pipelines and existing EASA CS-25 qualification assets. Monitor EU F-Gas Regulation enforcement intensity as the signal for application technology upgrade inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fluoropolymer Synthesis | Jiangsu province expansions demonstrate how captive precursor supply secures margin control against import volatility. |
| REACH-Compliant Reformulation Investment | Shorter-chain fluoropolymer qualification preserves European market access as ECHA restrictions harden on long-chain substances. |
| Electrothermal-Hybrid System Partnership | Graphene-doped silicone integration with Vestas collapses installation labor costs for offshore wind assets. |
| MRO Channel Density Expansion | PPG Industries' Wichita and Dallas-Fort Worth presence captures recurring FAA-mandated fleet upgrade demand. |
| GB/T Aviation Material Certification | Streamlined Chinese qualification pathways reduce market entry friction for imported formulations in Beijing-Tianjin-Hebei clusters. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with coating formulators, wind turbine OEM procurement leads, aerospace MRO facility managers, marine fleet superintendents, and chemical regulatory affairs specialists. Secondary validation drew from EASA CS-25 certification databases, FAA airworthiness directive filings, BSH offshore wind standards, EU F-Gas Regulation implementation reports, and customs trade data on fluoropolymer precursor flows. Bottom-up volume estimates by application segment were triangulated against top-down chemical industry production capacity assessments.
Calibration against historical certification timelines and regulatory implementation patterns anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include formulation chemistry tier, application vertical, technology architecture, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted demand projections incorporating electrothermal substitution rates and REACH reformulation investment cycles. Industry-specific inputs included wind turbine installation forecasts for the North Sea and Baltic, regional aircraft fleet age profiles, and marine route traffic density for Arctic shipping lanes.
Practitioners should monitor EASA-FAA regulatory divergence on acceptable fluorinated chemistries, Chinese domestic precursor capacity utilization rates, and electrothermal system cost curves for early signals of forecast revision. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aerospace and Aircraft Materials
Magnesium Beryllium Alloy Market
Aerospace and Aircraft Materials
Aerospace Fiber Optics Market
Aerospace and Aircraft Materials
Aerospace Lightweight Materials Market
Aerospace and Aircraft Materials
Global High Strength Aluminum Alloys Market
Aerospace and Aircraft Materials
Aerospace Titanium Market
Aerospace and Aircraft Materials
Global AFP/ATL Machines Market
Aerospace and Aircraft Materials
Global Aerospace Adhesives Market
Aerospace and Aircraft Materials
Global Aerospace Adhesives and Sealants Market
Aerospace and Aircraft Materials
Aerogel Blanket Market
Aerospace and Aircraft Materials
Global Flame Retardant for Aerospace Plastics Market
Aerospace and Aircraft Materials
Honeycomb Panel for Aircraft Market
Aerospace and Aircraft Materials
India Aerospace Coating Market
Aerospace and Aircraft Materials
3D Printing for Aerospace Market
Aerospace and Aircraft Materials
Beryllium Aluminum Alloy Market
Aerospace and Aircraft Materials
Middle-East and Africa Aerospace Composites Market
Aerospace and Aircraft Materials
Aircraft Soft Goods Market