
 Aerospace Coatings Market | 2026-2036
Aerospace Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Aerospace Coatings Market Analysis
Aerospace coatings chemist shortages across North America and Western Europe is reorganizing how manufacturers secure formulation talent. PPG Industries leverages its integrated resin-to-coating pipeline to reduce dependency on external specialty chemical suppliers. Akzo Nobel NV anchors its competitive stance through deep expertise in chromate-free pretreatment systems for military airframes.
Aerospace coatings are engineered film-forming systems—typically 25–75 microns dry-film thickness—comprising binders, pigments, solvents, and functional additives that protect aluminum, titanium, and composite substrates from ultraviolet degradation, fluid exposure, and thermal cycling in flight operations. Polyurethane topcoats dominate exterior applications due to their gloss retention and flexibility under aerodynamic stress, while epoxy primers command the anti-corrosion segment through superior adhesion to anodized surfaces. Water-based technology is gaining fastest traction as OEMs face tightening emissions protocols during application and curing phases.
The EPA regulates volatile organic compound limits under aerospace-specific National Emission Standards for Hazardous Air Pollutants, while REACH restricts chromium trioxide in corrosion-inhibiting primers across Europe. OEMs and tier suppliers must monitor evolving substance restrictions and qualification timelines to avoid airworthiness certification delays.
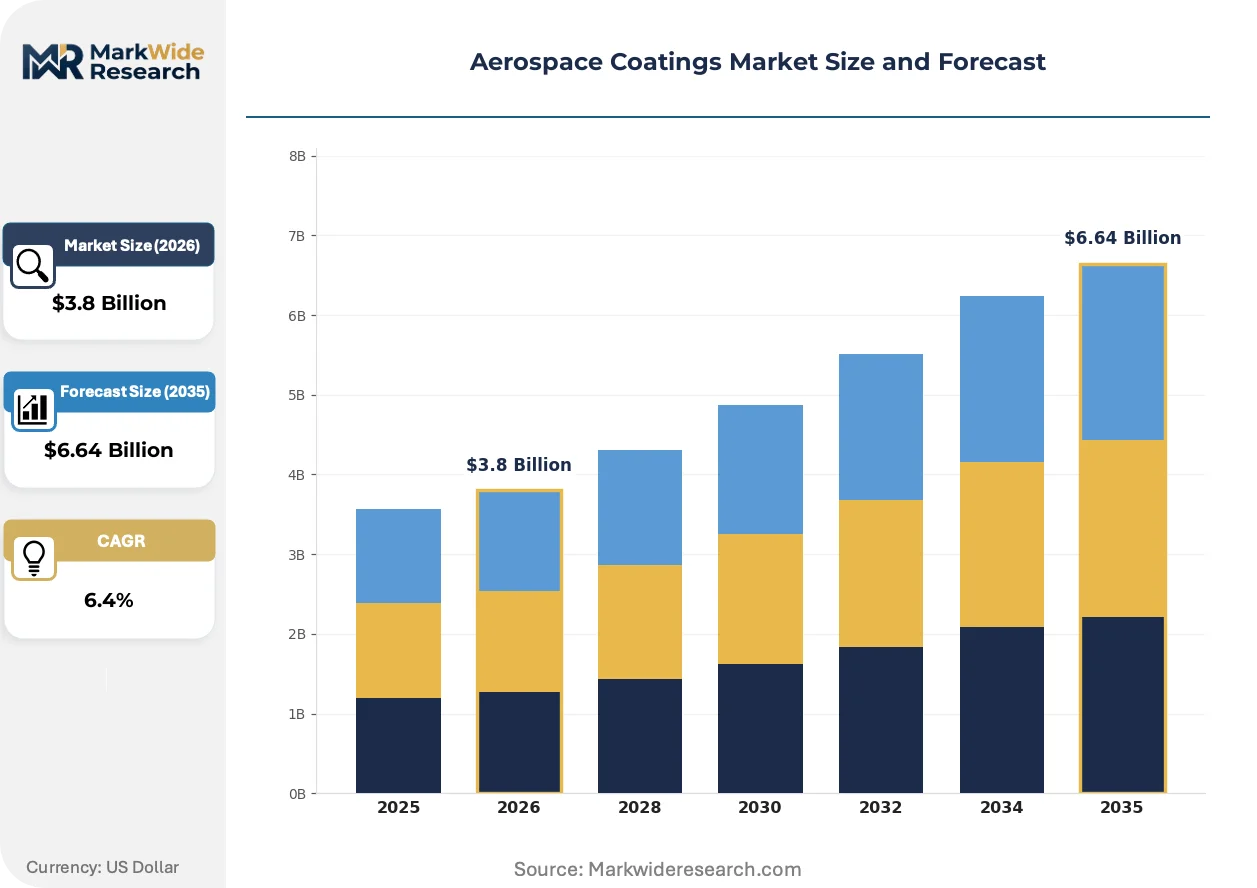
Market Dynamics
The aerospace coatings sector is undergoing a forced technology transition as chromate-free pretreatment systems and water-based chemistries replace legacy solvent-heavy formulations under tightening EPA and REACH emission ceilings.
Growth Catalysts
- Fleet renewal cycles:Commercial airlines in the United States are accelerating MRO spending on exterior refinishing as aging narrow-body aircraft exceed 15-year service intervals.
- REACH Annex XVII restrictions:The European Union's chromium trioxide prohibitions are mandating conversion coating substitutions across military and civil airframe maintenance networks.
- Epoxy primer technology:Advanced epoxy systems with improved adhesion to anodized aluminum are extending corrosion protection intervals on coastal-operating aircraft.
Market Restraints
- Specialty resin supply concentration:Isocyanate and polyol feedstock production clusters in Germany and China create vulnerability to logistics disruptions.
- Application equipment capex:Water-based coating systems require humidity-controlled spray booths and forced-air curing infrastructure that triples facility investment versus conventional solvent lines.
- Qualification timeline friction:FAA and EASA airworthiness certification cycles for new coating chemistries extend 18-36 months, freezing formulation innovation in place.
Strategic Opportunities
- Urban air mobility platforms:Electric vertical take-off aircraft manufacturers in the United States require lightweight, UV-stable topcoats for composite-intensive airframes.
- Defense offset programs:India's domestic fighter production under PLI scheme incentives is creating captive demand for chromate-free military-grade pretreatment systems.
- High-solids UV curing:Convergence of ultraviolet-initiated polymerization with reduced-VOC formulations is enabling line-speed increases at OEM assembly plants.
Industry Challenges
- Formulation chemist scarcity:Retiring expertise in polyurethane and epoxy resin synthesis across North America is outpacing university pipeline output.
- Legacy system integration:Water-based primers exhibit adhesion failures when applied over existing solvent-based substrate layers, complicating MRO workflow redesign.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aerospace Coatings Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyurethane, Epoxy, Ceramics, Acrylic Technology: Solvent-Based, Water-Based, High Solids, UV-Curable End User: Civil Aviation, Defense, Space, Aftermarket Application: Interior, Exterior, Engine Components, Anti-Corrosion |
| Companies Covered | The Sherwin-Williams Company, Hentzen Coatings, Akzo Nobel NV, Brycoat Inc, Argosy International, PPG Industries, Henkel AG & Co. KGaA, IHI Ionbond AG, BASF SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aerospace Coatings Market Emerging Trajectories
Formulation chemistry is pivoting toward ambient-cure water-based systems as regulatory pressure compounds with airline sustainability commitments. This shift is compressing the viable technology set and rewiring supplier-customer technical service relationships.
Chromate-free pretreatment chemistry is supplanting hexavalent chromium conversion coatings in corrosion-critical applications. Military depots in the United States and Western Europe are adopting zirconium-based and trivalent chromium alternatives under accelerated qualification schedules. This transition is collapsing the supplier base as only integrated resin-to-coating manufacturers possess the technical resources to certify replacement systems.
REACH authorization requirements for chromium trioxide are forcing inventory drawdowns across European MRO facilities. The restriction is compressing qualified supplier lists and triggering dual-source qualification campaigns among tier-one maintenance providers. Germany and France are experiencing the most acute formulation substitution pressure due to dense concentrations of legacy military overhaul infrastructure.
Airline procurement teams are consolidating coating supply agreements into multi-year performance contracts with embedded technical service provisions. Direct sourcing from formulation houses is displacing distributor intermediaries for high-volume MRO accounts. This consolidation is most pronounced among United States-based carriers operating dedicated paint facilities in the Gulf Coast region.
Aerospace Coatings Market Segmentation
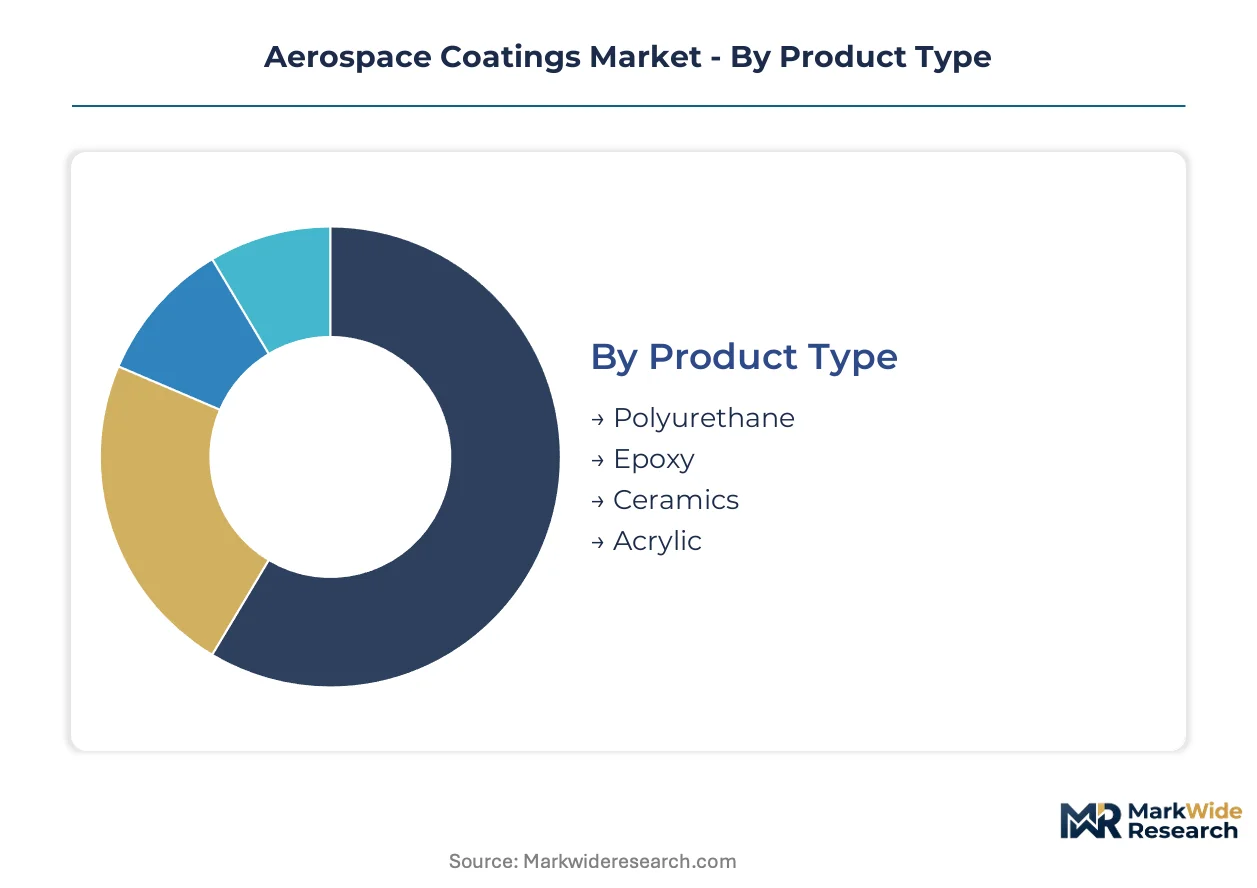
Aerospace coatings segmentation reflects divergent qualification pathways and performance specifications across military and commercial airworthiness regimes. Regulatory pressure on volatile organic compounds and hexavalent chromium is compressing viable technology sets within each category.
Product Type:
REACH Annex XVII restrictions on chromium trioxide and EPA aerospace NESHAP emission ceilings are fragmenting competitive positioning across resin chemistries.
- Polyurethane:Aliphatic polyurethane topcoats deliver gloss retention above 80% after accelerated weathering exposure. Demand concentrates on exterior fuselage refinishing for United States-based narrow-body fleets undergoing 15-year service interval overhauls.
- Epoxy:Bisphenol-A and novolac epoxy primers bond to anodized aluminum through polar functional groups. Coastal-operating aircraft in Florida and California drive specification for extended corrosion protection intervals.
- Ceramics:Yttria-stabilized zirconia thermal barrier coatings protect turbine blades in high-thrust engines.
- Acrylic:Thermoplastic acrylic lacquers serve interior cabin applications requiring rapid touch-up capability.
Polyurethane handles the majority of throughput; Epoxy is gaining share fastest on pretreatment system conversions.
Technology:
Application infrastructure investment separates cost tiers, with humidity-controlled spray booths and forced-air curing systems tripling capital outlay versus conventional lines.
- Solvent-Based:Legacy alkyd and nitrocellulose formulations dominate existing MRO equipment footprints. Germany and France face accelerated phase-out timelines under EU Green Deal implementation.
- Water-Based:Acrylic-urethane dispersions cure through ambient moisture evaporation with volatile organic compound content below regulatory thresholds. Gulf Coast MRO facilities in Texas and Alabama are retrofitting spray booths to handle humidity-sensitive application windows.
- High Solids:Reduced-solvent epoxy and polyurethane systems bridge performance gaps during facility transition periods.
- UV-Curable:Photoinitiator-activated acrylate oligomers enable line-speed increases at Boeing and Airbus final assembly lines.
Water-Based commands the steepest expansion trajectory; Solvent-Based retains residual volume in legacy military depot infrastructure.
End User:
Procurement consolidation patterns diverge between long-term OEM supply agreements and spot MRO purchasing.
- Civil Aviation:United States carriers operating dedicated paint facilities in Georgia and Washington state are consolidating multi-year performance contracts with embedded technical service provisions.
- Defense:Chromate-free pretreatment qualification campaigns are accelerating at military depots under Department of Defense sustainability mandates.
- Space:Low-earth orbit satellite manufacturers specify atomic oxygen-resistant silicate coatings.
- Aftermarket:Independent MRO providers in Arizona and Kansas face adhesion failure risks when applying water-based primers over existing solvent-based substrate layers.
Civil Aviation generates the dominant revenue base; Defense is climbing the fastest on chromate substitution deadlines.
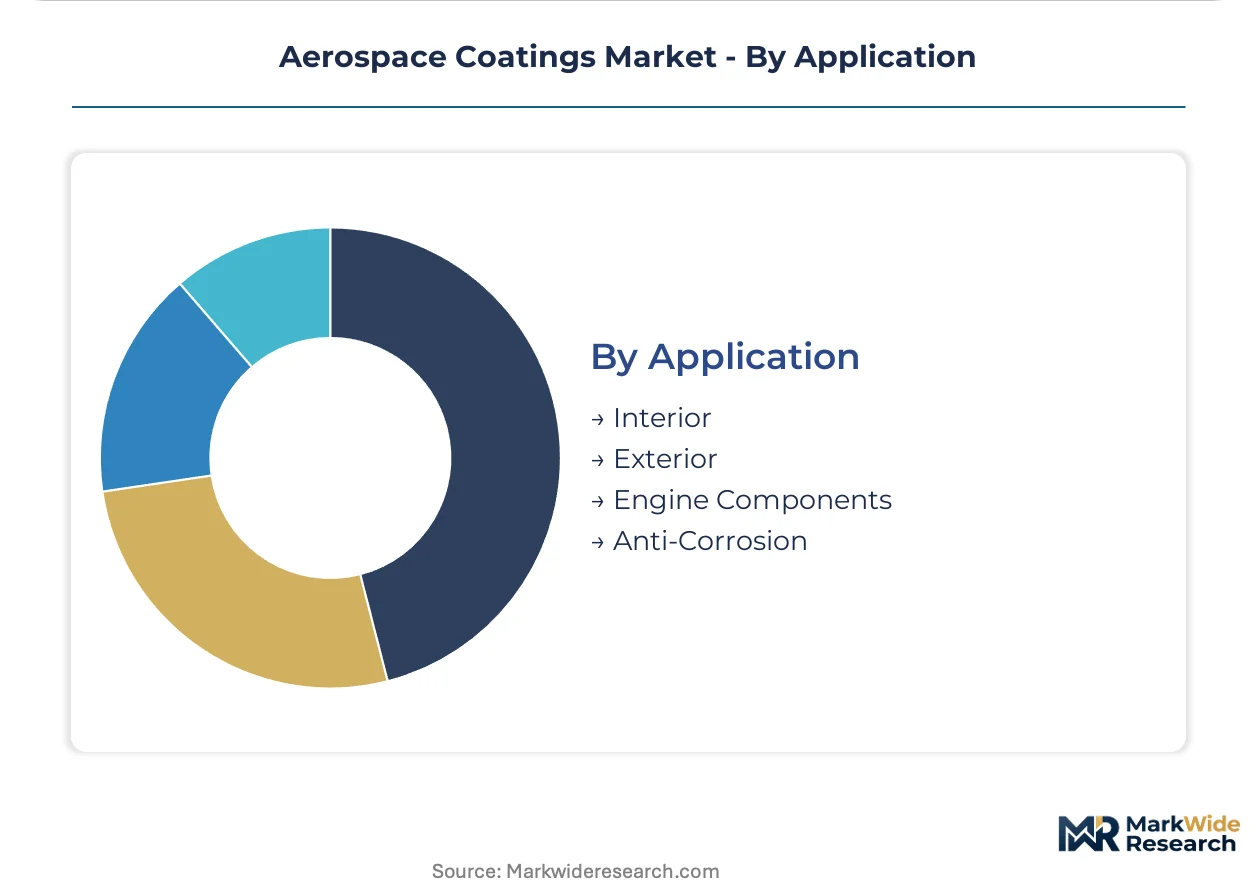
Application:
Substrate material shifts—aluminum to carbon fiber reinforced polymer—are rewiring adhesion chemistry requirements.
- Interior:Cabin sidewall and overhead bin coatings must meet FAA flammability standards with low smoke toxicity. United States-based retrofit specialists are sourcing directly from formulation houses to bypass distributor margins.
- Exterior:Aerodynamic smoothness specifications demand 25-75 micron dry-film thickness with orange peel below visual tolerance.
- Engine Components:Thermal cycling resistance from -54°C to 200°C separates qualified suppliers.
- Anti-Corrosion:Trivalent chromium and zirconium-based conversion coatings are supplanting hexavalent chromium at European MRO facilities under REACH authorization pressure.
Exterior coatings absorb the largest application volume; Anti-Corrosion is expanding most quickly on regulatory substitution mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States consumes aerospace coatings through OEM assembly line contracts and dense MRO networks, while European demand channels through regulatory-driven chromate substitution programs and Germany concentrates specialty resin production.
United States
Boeing's final assembly lines in Washington state and South Carolina anchor OEM coating demand through multi-year supply agreements. The EPA's aerospace NESHAP emission standards enforce volatile organic compound limits at application facilities. Gulf Coast MRO clusters in Texas and Alabama are retrofitting humidity-controlled spray booths to handle water-based chemistry transitions.
Germany
Isocyanate and polyol feedstock production concentrates in the industrial corridor between Cologne and Frankfurt, supplying binders across European coating formulation. ECHA's REACH Annex XVII restrictions on chromium trioxide are forcing inventory drawdowns at military overhaul depots. Bavaria's aerospace supplier ecosystem around Munich faces acute pressure to qualify chromate-free pretreatment alternatives.
France
Airbus final assembly at Toulouse drives specification authority for exterior coating systems across European supplier networks. The EU Green Deal implementation timeline accelerates solvent-based phase-out at legacy military maintenance infrastructure. The Paris-Saclay research cluster houses formulation development for trivalent chromium conversion coating substitutes.
China
Domestic narrow-body aircraft production under COMAC programs is building captive demand for qualified coating suppliers. The Ministry of Ecology and Environment enforces volatile organic compound emission controls at manufacturing facilities. Yangtze River Delta industrial zones around Shanghai concentrate application equipment manufacturing and technical service capacity.
India
Domestic fighter production under the PLI scheme incentives is creating demand for military-grade chromate-free pretreatment systems. The Bureau of Indian Standards monitors coating qualification for defense airworthiness certification. Karnataka's aerospace manufacturing corridor near Bangalore hosts emerging MRO facilities requiring coating application infrastructure.
Aerospace Coatings Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier in the aerospace coatings sector. Three to five multinational chemical conglomerates control resin synthesis and formulation qualification pipelines, while regional specialists occupy narrow application niches. The competitive terrain separates into integrated resin-to-coating manufacturers, military specification specialists, and application equipment-integrated service providers. Consolidation pressure and qualification timeline compression represent the dominant competitive vectors reshaping supplier positioning.
Within the integrated formulation tier, PPG Industries and Akzo Nobel NV occupy positions defined by captive resin production and chromate-free pretreatment expertise respectively. BASF SE anchors the specialty chemical supply dimension through upstream polymer intermediates. These three exemplify the vertical integration archetype that regulatory complexity favors.
| Leading Market Players |
|---|
| The Sherwin-Williams Company |
| Hentzen Coatings |
| Akzo Nobel NV |
| Brycoat Inc |
| Argosy International |
| PPG Industries |
| Henkel AG & Co. KGaA |
| IHI Ionbond AG |
| BASF SE |
| Others |
Supply Flow & Price Mechanics
Long-term performance contracts with embedded technical service provisions lock in supply access for United States carriers while anchoring price visibility across multi-year fleet renewal cycles. These agreements concentrate procurement power among Gulf Coast MRO operators and Boeing assembly facilities, compressing spot-market liquidity for specialty formulations.
Pricing Analysis
Contract-based long-term offtake dominates aerospace coatings procurement, with pricing stratifying across military-specification, OEM-qualified, and aftermarket-economy tiers based on airworthiness certification grade and volume scale. Cost compression in water-based technology tiers is intensifying because humidity-controlled application infrastructure triples facility investment versus legacy solvent lines. Commercial airlines operating dedicated paint facilities exhibit lowest price sensitivity due to embedded technical service dependencies, while independent MRO providers in Arizona and Kansas face acute margin pressure from adhesion failure risks during formulation transitions.
Supply Chain Analysis
Strategic stockpiling of isocyanate and polyol feedstocks prevails among integrated manufacturers, while just-in-time resin delivery exposes smaller formulators to logistics disruptions. Supply concentrates in Germany, China, and the United States, with specialty resin synthesis anchored in the Cologne-Frankfurt industrial corridor and Yangtze River Delta zones. The supply chain draws from concentrated aromatic isocyanate, aliphatic polyol, and chromate-free pretreatment chemical inputs, with single-source vulnerability around qualified trivalent chromium conversion coating suppliers. Distribution runs through direct formulation house relationships for high-volume accounts, displacing distributor intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among United States carriers consolidating multi-year coating supply agreements, fragmenting pricing leverage for smaller independent MRO operators.
For Market Incumbents: Fortify chromate-free pretreatment qualification pipelines at military depots before REACH authorization deadlines collapse supplier lists. Deepen captive resin production of aliphatic polyurethane intermediates to offset feedstock concentration risk in Germany and China. Lock in exclusive technical service provisions with Gulf Coast MRO clusters to preempt direct-sourcing displacement of distributor networks. For New Entrants and Emerging Players: FAA airworthiness certification fast-tracks for water-based epoxy primers present the most penetrable entry vector, given 18-36 month qualification timelines that freeze incumbent innovation. Target aftermarket independent MRO facilities in Arizona and Kansas with adhesion-failure remediation protocols as differentiated service bundling. Pursue qualification partnerships with urban air mobility manufacturers requiring UV-stable composite topcoats. For Investors and Strategic Acquirers: Capital is best deployed toward integrated resin-to-coating manufacturers possessing in-house pretreatment chemistry expertise and military specification authority. The five-to-ten year viability window favors backward integration into specialty isocyanate production or captive conversion coating technology. Watch for EASA acceleration of chromate substitution deadlines as inflection signal for qualification-capacity scarcity premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Chromate-Free Pretreatment Qualification | REACH Annex XVII restrictions on chromium trioxide compress viable supplier lists to integrated manufacturers with military depot relationships. |
| Humidity-Controlled Spray Booth Retrofit | Gulf Coast MRO facilities in Texas and Alabama triple capital outlay to handle water-based chemistry application windows. |
| Direct Sourcing Consolidation | United States carriers bypass distributor intermediaries through multi-year performance contracts with embedded technical service provisions. |
| Urban Air Mobility Coating Partnership | Electric vertical take-off aircraft manufacturers require lightweight UV-stable topcoats for composite-intensive airframes. |
| Specialty Resin Backward Integration | Captive isocyanate and polyol production reduces dependency on Cologne-Frankfurt and Yangtze River Delta feedstock clusters. |
Methodological Framework
Initial hypotheses were tested against primary input from aerospace coatings formulators, MRO procurement directors, OEM supply chain managers, and military depot qualification officers and refined through secondary validation. Primary fieldwork encompassed technical interviews across polyurethane synthesis chemists, EPA compliance consultants, and ECHA regulatory affairs specialists. Secondary sources included FAA airworthiness certification databases, ECHA REACH authorization timelines, SEC 10-K filings from integrated chemical conglomerates, and customs trade data on isocyanate feedstock flows. Bottom-up volume estimates from individual MRO facility throughput were triangulated against top-down OEM assembly line coating consumption projections.
Variance decomposition across resin chemistry, application technology, and end-user qualification pathways structured the analytical framework throughout the projection horizon. Segmentation dimensions encompassed product type, technology platform, end-user procurement pattern, and regional regulatory cluster. CAGRs were derived from fitted growth curves calibrated to fleet renewal cycle timing and chromate substitution mandate deadlines. Industry-specific forecast inputs included Boeing and Airbus delivery schedules, REACH Annex XVII implementation phasing, and military depot sustainability mandate compliance trajectories.
Decision-makers should treat outputs as directional under assumptions of stable EPA aerospace NESHAP enforcement and no catastrophic feedstock logistics disruption; material deviation would warrant model refresh. Revision becomes warranted when EASA accelerates chromium trioxide prohibition timelines or when water-based primer adhesion failure rates exceed qualification thresholds at major MRO facilities.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aerospace and Aircraft Materials
Aerospace Composites Market
Aerospace and Aircraft Materials
Aerospace Lightweight Materials Market
Aerospace and Aircraft Materials
Aerographite Market
Aerospace and Aircraft Materials
Europe Aerospace Composites Market
Aerospace and Aircraft Materials
Supersonic Wind Tunnel Market
Aerospace and Aircraft Materials
Aluminum Beryllium Market
Aerospace and Aircraft Materials
Aerospace Carbon Fiber Market
Aerospace and Aircraft Materials
Commercial Aerospace Carbon Brakes Market
Aerospace and Aircraft Materials
Global Aerospace Adhesives and Sealants Market
Aerospace and Aircraft Materials
Honeycomb Panel for Aircraft Market
Aerospace and Aircraft Materials
Global Aerospace and Defense Elastomers Market
Aerospace and Aircraft Materials
Aerographene Market
Aerospace and Aircraft Materials
Stealth Coating Market
Aerospace and Aircraft Materials
Russia Space Electronics Market
Aerospace and Aircraft Materials
Aerospace Titanium Market
Aerospace and Aircraft Materials
Fiberglass for Aerospace Market