
 Aircraft AFP and ATL Composites Market | 2026-2036
Aircraft AFP and ATL Composites Market Size, Share, and Industry Trends Forecast 2026-2036
Aircraft AFP and ATL Composites Market Analysis
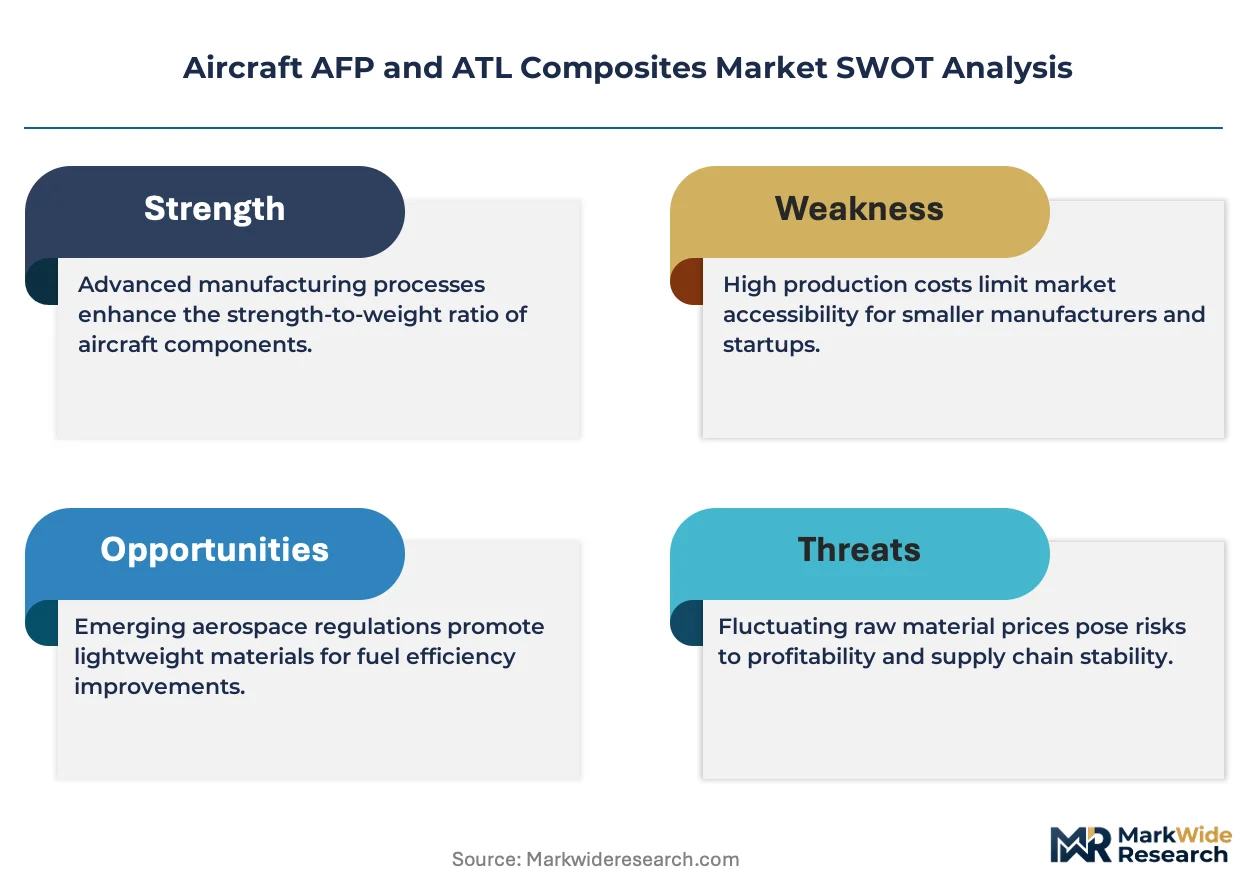
A capital-intensity divergence between automated fiber placement system builders and raw material suppliers is redrawing competitive boundaries in aerospace composites manufacturing. Hexcel Corporation leverages its carbon fiber prepreg dominance to anchor long-term supply agreements with tier-one aerostructures firms. Electroimpact Inc. specializes in large-scale AFP/ATL machine architectures that dominate wing and fuselage automation programs for Boeing and Airbus. Solvay sustains its position through integrated thermoset and thermoplastic material portfolios that compete across multiple qualification pathways.
Automated fiber placement and automated tape laying composites are advanced polymer matrix structures manufactured by precisely depositing resin-impregnated tape or tow onto contoured tooling at controlled temperatures and pressures, achieving fiber volume fractions typically exceeding 60% and void contents below 1%. These processes produce primary aerostructures—wing skins, fuselage barrels, and empennage components—with strength-to-weight ratios that aluminum alloys cannot match, directly enabling the fuel efficiency targets that drive modern aircraft design programs. Carbon fiber materials occupy the dominant value position due to their established qualification base across commercial and military platforms, while hybrid fiber formulations represent the fastest-growing material category as OEMs seek to optimize cost-performance tradeoffs in secondary structures. Manufacturing process selection follows a bifurcated pattern: autoclave curing retains margin concentration in critical primary structures, whereas out-of-autoclave methods including vacuum infusion are displacing legacy approaches in interior components and non-structural applications where throughput economics favor simplified tooling.
FAA airworthiness standards for composite damage tolerance and repair, EASA certification requirements for bonded joints in primary structure, and ISO quality management frameworks for aerospace suppliers collectively shape market access and product qualification timelines. These regulatory layers demand extensive testing databases and sustained engineering investment, creating barriers that favor incumbent suppliers with established certification histories over new entrants. Stakeholders must monitor evolving EPA and ICAO emissions mandates that tighten the operational efficiency requirements driving composite penetration rates in next-generation aircraft programs.
Market Dynamics
High-rate production mandates from Boeing and Airbus for narrowbody platforms are forcing tier-one suppliers to retool legacy autoclave capacity toward automated fiber placement systems that can deposit thermoplastic tapes at speeds exceeding one meter per second.
Growth Catalysts
- FAA Damage Tolerance Standards:Certification pathways for composite primary structures under FAA AC 20-107B accelerate material qualification timelines and lock in supplier relationships for multi-decade aircraft programs.
- Carbon Fiber Tow Placement:Next-generation AFP heads with in-situ consolidation capabilities enable out-of-autoclave processing of wing skins, reducing cycle times by half compared to traditional oven curing.
- United States Manufacturing Concentration:Boeing's supplier base in Washington and South Carolina states is expanding machine parks to support 737 MAX and 777X rate increases, concentrating demand for large-format ATL systems.
Market Restraints
- Acrylonitrile Price Volatility:Carbon fiber precursor costs swing with propylene feedstock markets, compressing prepreg margins for suppliers locked into long-term aerospace contracts.
- Machine Builder Oligopoly:AFP/ATL system supply concentrates among three specialized equipment manufacturers, creating bottlenecks for OEMs seeking to expand capacity on compressed timelines.
- Thermoplastic Qualification Gaps:PEEK and PPS matrix systems lack the extensive damage-tolerance databases of thermoset epoxies, delaying their adoption in primary wing and fuselage structures.
Strategic Opportunities
- Urban Air Mobility Airframes:eVTOL manufacturers require high-rate, low-cost composite production methods that bypass traditional autoclave infrastructure, favoring AFP with electron-beam curing.
- EU Green Deal Aviation Targets:Binding emissions reduction mandates under the EU's Sustainable Aviation Fuels regulation accelerate lightweighting investments, creating thermoplastic composite demand for regional aircraft.
- In-Situ Consolidation Robotics:Convergence of AFP heads with automated guided vehicle platforms enables factory-floor reconfiguration for mixed-model production without fixed gantry investments.
Industry Challenges
- Multi-Axis Programmer Shortage:AFP/ATL machine operation requires specialized NC programming skills for complex surface geometries, with training pipelines failing to match OEM hiring rates.
- Digital Thread Integration:Ply-by-ply inspection data from automated placement systems must feed back into MES and PLM platforms, creating interoperability friction with legacy ERP installations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aircraft AFP and ATL Composites Market |
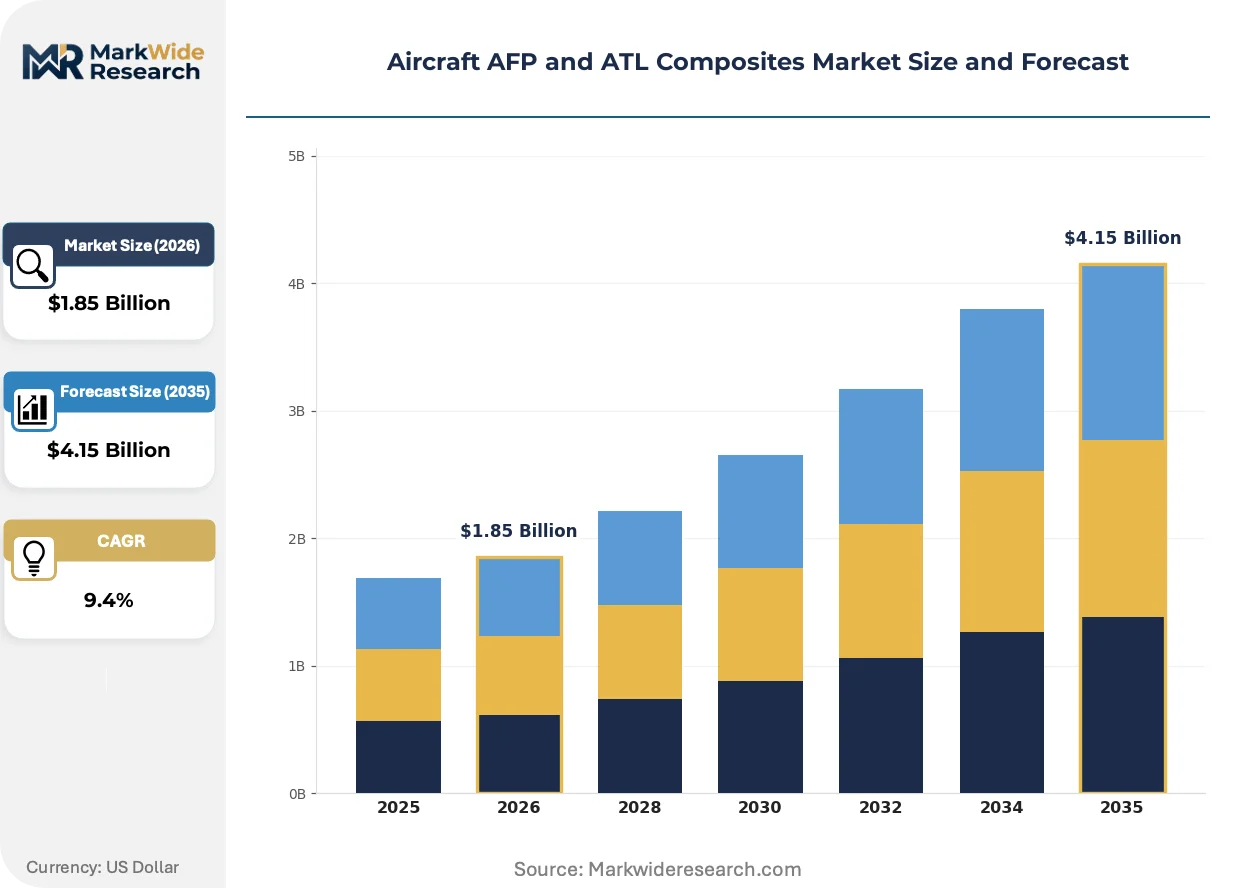
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $4.15 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Carbon Fiber, Glass Fiber, Aramid Fiber, Hybrid Fiber Manufacturing Process: Autoclave, Vacuum Infusion, Resin Transfer Molding, Hand Lay-up Application: Aerospace Structures, Interior Components, Wing Components, Engine Components End User: Commercial Aviation, Military Aviation, Space Exploration, UAV Manufacturers |
| Companies Covered | Hexcel Corporation, Solvay, Airbus Group SE, AVEL Robotics SAS, Electroimpact Inc., The Boeing Company, Collins Aerospace, Mitsubishi Heavy Industries, Spirit AeroSystems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aircraft AFP and ATL Composites Market Emerging Trajectories
Process automation and regulatory stringency are converging to compress the traditional decade-long material qualification cycle, while thermoplastic matrices gain traction in applications previously reserved for thermoset epoxies.
Continuous compression molding is supplanting autoclave curing for thermoplastic wing ribs and control surfaces, with Gulfstream and Dassault Aviation adopting the technology for business jet programs to eliminate oven bottlenecks and reduce energy intensity by two-thirds compared to legacy thermal processing.
EPA emissions standards for commercial aircraft under the Greenhouse Gas Endangerment Finding are tightening fuel efficiency benchmarks, compelling airframers to specify lower-weight composite solutions in secondary structures previously built from aluminum, with the regulatory pressure most acute on narrowbody programs targeting 2030 entry-into-service dates.
Long-term throughput agreements are displacing spot purchasing for carbon fiber prepreg, with tier-one aerostructures firms locking in decade-plus supply contracts indexed to aircraft delivery schedules rather than resin commodity prices, a pattern most visible in the United States where Boeing's supplier base seeks margin stability amid raw material volatility.
Aircraft AFP and ATL Composites Market Segmentation
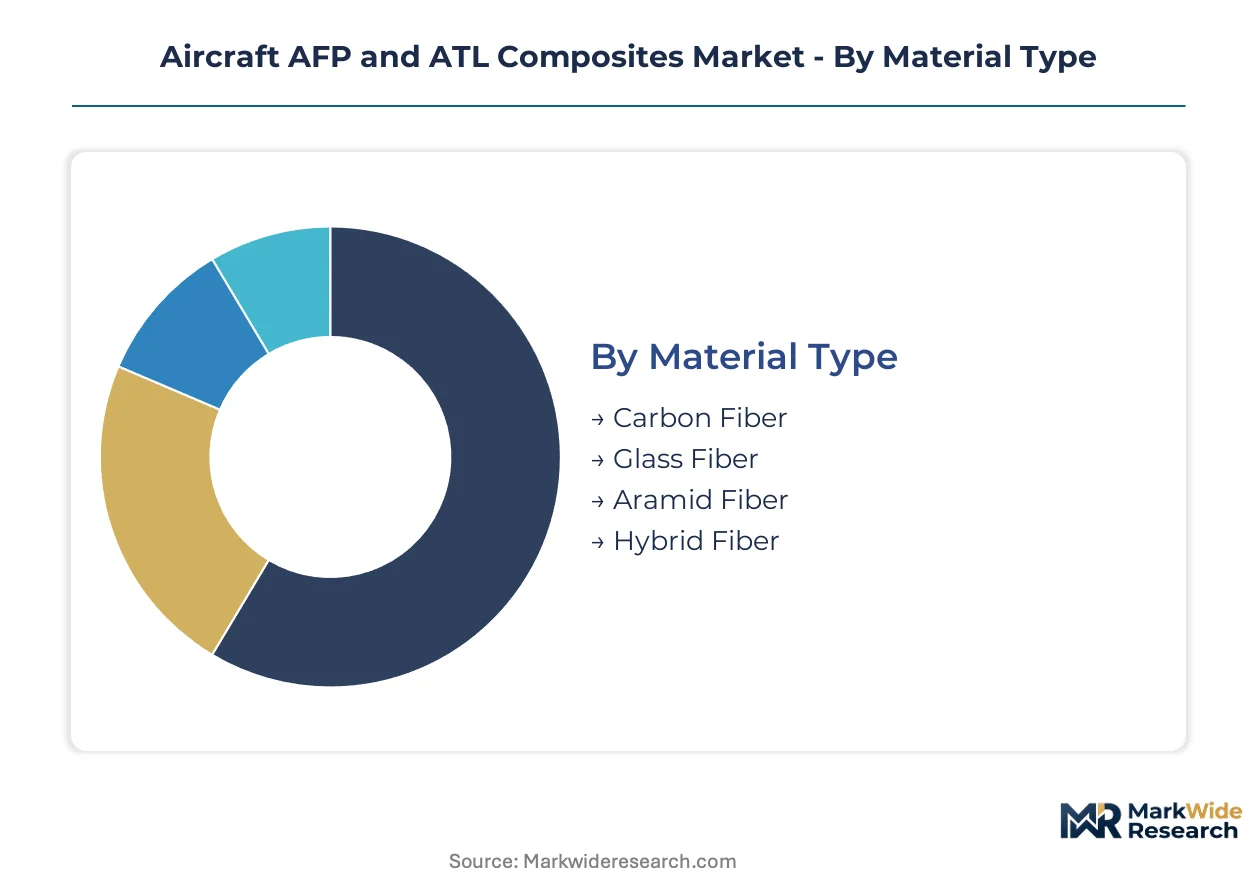
Segmentation in the Aircraft AFP and ATL Composites Market reveals how material selection, process economics, and regulatory requirements concentrate value across distinct supply tiers. Understanding these divisions exposes where qualification barriers protect incumbent positions and where process innovation opens substitution pathways.
Material Type:
Margin pools concentrate in carbon fiber formulations where decades of FAA damage-tolerance databases lock in aerospace-grade specifications and multi-year qualification timelines.
- Carbon Fiber:High-modulus and intermediate-modulus tow configurations dominate wing skins and fuselage barrels where strength-to-weight ratios exceed aluminum by 40%. Boeing 787 and Airbus A350 programs anchor demand in the United States and France, with long-term prepreg contracts indexed to aircraft delivery schedules insulating suppliers from acrylonitrile feedstock swings.
- Hybrid Fiber:Blended carbon-glass and carbon-aramid layups optimize cost-performance tradeoffs in secondary structures and control surfaces. Regional aircraft OEMs in Brazil and Canada specify hybrid formulations for empennage components to reduce material costs without sacrificing fatigue performance.
- Glass Fiber:E-glass and S-glass variants serve interior panels and non-structural applications where electromagnetic transparency and damage visibility matter more than absolute stiffness.
- Aramid Fiber:Kevlar and Twaron reinforcements absorb impact energy in engine nacelles and leading-edge protection systems where ballistic tolerance complements composite stiffness.
Carbon fiber holds installed capacity across primary aerostructures. Hybrid fiber is rotating up the share rankings as secondary structure specifications relax modulus requirements.
Manufacturing Process:
Process selection divides along throughput requirements and capital intensity, with autoclave curing retaining margin concentration in safety-critical structures while out-of-autoclave methods expand in rate-sensitive applications.
- Autoclave:Pressurized thermal processing achieves void contents below 1% and fiber volume fractions exceeding 60% in wing spars and fuselage frames. Boeing's Everett and North Charleston facilities maintain the largest installed autoclave base for 777X and 787 programs, where FAA AC 20-107B damage-tolerance standards mandate proven cure cycles.
- Vacuum Infusion:Resin flow under vacuum pressure eliminates oven infrastructure for interior monuments and cargo liners. Gulfstream and Dassault Aviation specify vacuum-infused thermoplastics for business jet cabin components to compress lead times and reduce energy intensity.
- Resin Transfer Molding:Closed-mold injection suits complex geometries with double-curvature such as engine cowls and thrust reverser cascades where fiber preform precision controls resin distribution.
- Hand Lay-up:Manual ply placement persists in repair stations and low-rate military programs where part complexity or volume does not justify automated fiber placement capital investment.
Autoclave systems retain the highest value-add per square meter. Vacuum infusion is climbing the fastest as OEMs eliminate thermal processing bottlenecks in non-structural applications.
Application:
Application segmentation tracks how structural criticality determines material grade, process qualification depth, and supplier certification longevity.
- Wing Components:Skins, spars, and ribs demand unidirectional and quasi-isotropic layups with automated fiber placement achieving deposition speeds above one meter per second. Airbus Hamburg and Boeing Renton factories concentrate ATL capacity for narrowbody wing boxes where high-rate production mandates eclipse legacy hand lay-up economics.
- Aerospace Structures:Fuselage barrels and empennage assemblies integrate cocured stringers and frames to reduce fastener count. Bombardier and Embraer specify out-of-autoclave thermoplastic fuselage sections for regional jets to avoid the capital intensity of large-diameter autoclaves.
- Interior Components:Sidewall panels, overhead bins, and galleys prioritize fire-smoke-toxicity compliance over structural modulus, favoring phenolic and thermoplastic matrices with simplified processing.
- Engine Components:Fan cowls, thrust reversers, and acoustic liners combine acoustic attenuation with foreign object damage resistance, specifying toughened epoxy systems qualified to EASA engine certification standards.
Wing components command the longest qualification cycles. Aerospace structures are gaining share as thermoplastic welding displaces mechanical fastening in barrel assemblies.
End User:
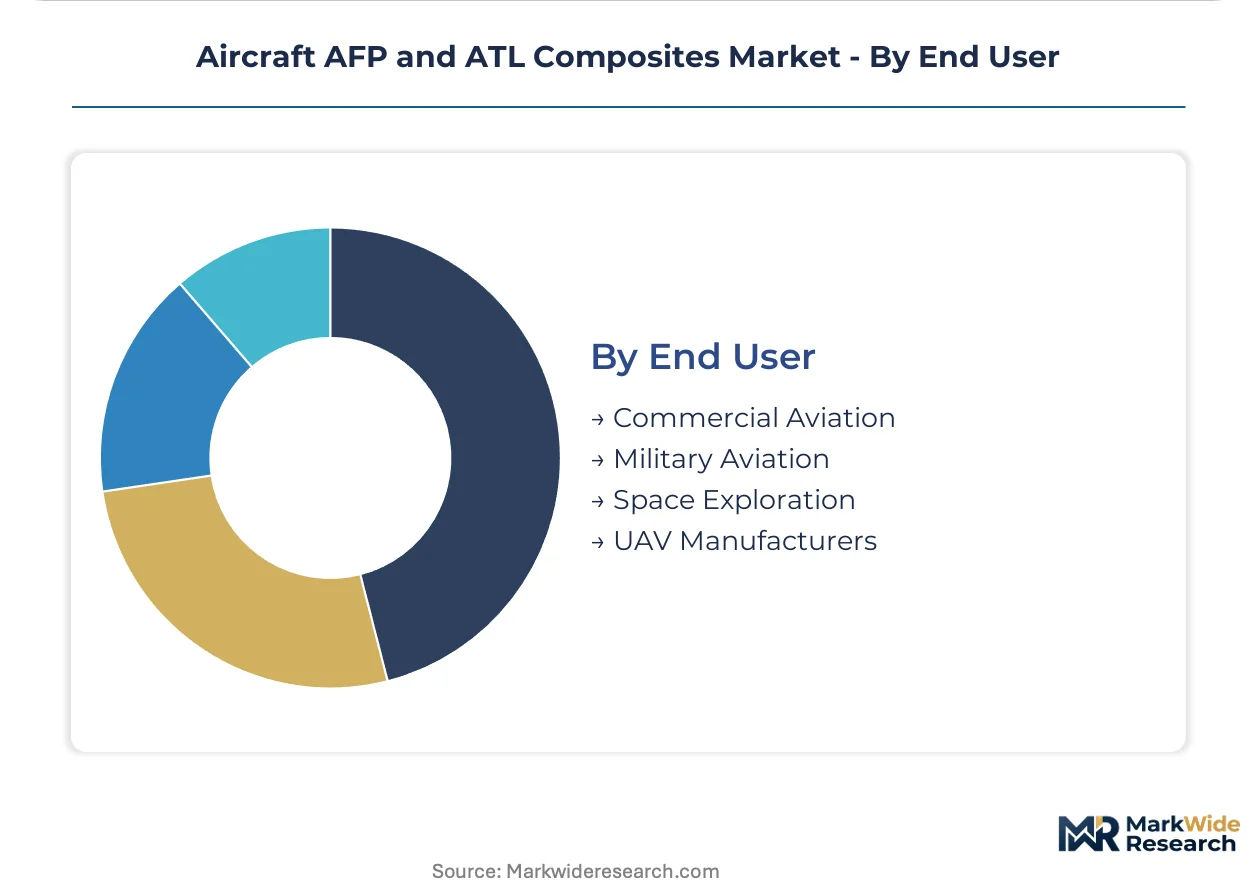
End user segmentation exposes divergent procurement patterns between commercial rate production and military low-rate initial production with extended service life requirements.
- Commercial Aviation:Boeing and Airbus drive AFP/ATL machine park expansion with narrowbody rate targets exceeding sixty aircraft monthly. Supply agreements span fifteen to twenty years with raw material costs passed through via escalation clauses.
- Military Aviation:F-35 and B-21 programs specify BMI and cyanate ester matrices for high-temperature performance, with low-rate initial production tolerating longer cycle times than commercial equivalents.
- UAV Manufacturers:Military and commercial drone producers specify tape-wound fuselage sections with reduced damage-tolerance margins compared to manned aircraft, accepting higher void contents for cost and speed.
- Space Exploration:Launch vehicle fairings and satellite structures demand ultra-high-modulus carbon fiber with coefficient of thermal expansion matching payload requirements, processed in cleanroom environments with lot traceability to individual fiber spools.
Commercial aviation concentrates machine utilization. UAV manufacturers are expanding most quickly as defense and logistics applications multiply platform demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in the United States exhibit the lowest price elasticity, absorbing premium automation systems for high-rate narrowbody production, while emerging aerospace clusters in Asia-Pacific remain acutely sensitive to capital expenditure thresholds for thermoplastic qualification.
United States
Boeing's 737 MAX and 777X rate targets drive AFP machine park expansion across Washington and South Carolina manufacturing corridors. FAA AC 20-107B certification pathways for composite primary structures lock in decade-long supplier relationships. The Pacific Northwest cluster around Everett concentrates the largest installed base of large-format ATL systems for wing skin automation.
France
Airbus Hamburg and Toulouse factories anchor European demand for automated tape laying capacity on A320neo and A350 programs. EASA certification requirements for bonded joints in primary structure extend qualification timelines beyond thermoset alternatives. The Occitanie region hosts specialized thermoplastic composite research facilities advancing out-of-autoclave processing for next-generation narrowbody wings.
Japan
Mitsubishi Heavy Industries and tier-two suppliers serve Boeing and Airbus subcontracting networks with precision AFP components for regional jet programs. METI industrial policy supports carbon fiber precursor development to reduce acrylonitrile import dependency. The Nagoya aerospace cluster integrates automated fiber placement with existing machining expertise from automotive supply chains.
Germany
MTU Aero Engines and Premium Aerotec drive demand for complex geometry AFP heads in thrust reverser and engine cowl applications. REACH compliance for resin systems shapes material selection in European supply contracts. The Bavarian aerospace corridor around Munich concentrates thermoplastic welding R&D for future fuselage barrel assembly.
United Kingdom
Spirit AeroSystems and GKN Aerospace facilities in Northern Ireland and Bristol maintain legacy ATL capacity for wing box and empennage components. UK Export Finance guarantees support capital equipment purchases for automation upgrades. The Midlands aerospace cluster faces margin pressure from acrylonitrile price volatility transmitted through long-term prepreg contracts.
Aircraft AFP and ATL Composites Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with raw material suppliers and machine builders occupying distinct margin pools that resist easy consolidation. The upper tier combines carbon fiber prepreg dominance with multi-decade FAA qualification histories, while mid-tier specialists compete on deposition speed and machine architecture customization. Two strategic archetypes predominate: integrated material suppliers leveraging backward control over fiber and resin supply, and pure-play automation houses capturing value through proprietary head designs and software ecosystems. Competitive moves center on capacity expansion tied to Boeing and Airbus rate announcements, plus strategic partnerships bridging material qualification gaps for thermoplastic matrices.
Within the integrated materials tier, Hexcel Corporation and Solvay anchor long-term supply agreements through established aerospace-grade prepreg portfolios. Electroimpact Inc. occupies a distinctive position among specialized equipment manufacturers, with machine architectures dominating wing and fuselage automation programs. These three entities exemplify how qualification depth and capital intensity create defensive positions against new entrants lacking comparable certification databases or installed machine bases.
| Leading Market Players |
|---|
| Hexcel Corporation |
| Solvay |
| Airbus Group SE |
| AVEL Robotics SAS |
| Electroimpact Inc. |
| The Boeing Company |
| Collins Aerospace |
| Mitsubishi Heavy Industries |
| Spirit AeroSystems |
| Others |
Supply Flow & Price Mechanics
Large-format ATL system utilization rates above eighty percent in Boeing's Washington and South Carolina corridors create fixed-cost leverage that elevates price floors for composite aerostructures. This scale concentration locks tier-one suppliers into decade-long prepreg contracts indexed to aircraft delivery schedules rather than spot resin markets, insulating Hexcel and Solvay from acrylonitrile volatility while compressing margins for undifferentiated machine operators lacking backward fiber integration.
Pricing Analysis
After-market service contracts and spare AFP head rebuilds generate lifetime value multiples exceeding original equipment sales for specialized automation houses. Three-tier pricing structure across FAA-certified primary structures, EASA-qualified secondary components, and non-certified interior applications separates Boeing-tier suppliers from regional jet subcontractors. Cost compression in standard-grade thermoset prepreg is intensifying because Gulfstream and Dassault Aviation are qualifying out-of-autoclave alternatives for business jet programs. UAV manufacturers exhibit the highest price sensitivity, accepting higher void contents and reduced damage-tolerance margins to bypass multi-year qualification costs.
Supply Chain Analysis
Strategic stockpiling of acrylonitrile precursor dominates inventory strategy among Japanese carbon fiber producers seeking insulation from propylene feedstock swings. Manufacturing concentration in the United States, Japan, and France draws from specialized AFP machine builders in Washington state, precision tow processing in Nagoya, and Airbus-aligned ATL capacity in Toulouse. Single-source vulnerability concentrates in large-format gantry systems where Electroimpact's proprietary head designs anchor Boeing's narrowbody automation programs. Distribution runs through tier-one aerostructures firms—Spirit AeroSystems, Collins Aerospace, Mitsubishi Heavy Industries—before reaching final assembly lines in Everett, Hamburg, and Toulouse.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Aircraft AFP and ATL composites represent a high-growth disruption as FAA AC 20-107B certification pathways compress material qualification timelines from decade-long cycles toward five-year windows, forcing supplier consolidation around incumbent qualification databases.
For Market Incumbents: Compound defensive positions by deepening backward integration into carbon fiber precursor production to neutralize acrylonitrile volatility, and accelerate thermoplastic welding R&D to outpace out-of-autoclave challengers threatening autoclave-margin strongholds in primary structures. For New Entrants and Emerging Players: Differentiate on electron-beam curing speed for urban air mobility airframes where eVTOL manufacturers bypass traditional FAA damage-tolerance databases. Target UAV manufacturers in defense and logistics segments with tape-wound fuselage sections that accept reduced qualification depth. Pursue equipment-leasing models rather than capital sales to lower entry barriers for emerging aerospace clusters. For Investors and Strategic Acquirers: Specialized thermoplastic composite research facilities with active PEEK and PPS matrix programs offer the strongest acquisition profile, as Boeing and Airbus rate announcements for next-generation narrowbodies will trigger step-change demand for qualified out-of-autoclave capacity. Monitor EPA emissions standard tightening as the inflection signal—binding fuel efficiency benchmarks accelerate lightweighting investments and thermoplastic penetration timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Thermoplastic Qualification Investment | PEEK matrix databases unlock out-of-autoclave wing skin contracts from Airbus Hamburg. |
| Backward Integration into Precursor | Captive acrylonitrile supply insulates prepreg margins from propylene commodity swings. |
| Electron-Beam Curing Partnership | eVTOL manufacturers specify high-rate AFP bypassing traditional autoclave infrastructure. |
| In-Situ Consolidation Robotics | AGV-mounted AFP heads enable mixed-model production without fixed gantry capital. |
| Long-Term Throughput Agreement | Fifteen-year prepreg contracts indexed to 737 MAX delivery schedules lock Boeing supply. |
Methodological Framework
A spread of perspectives from AFP machine programmers, tier-one aerostructures procurement leads, FAA certification engineers, and carbon fiber plant managers converged on the working assumptions driving this analysis. Primary fieldwork combined with secondary validation from FAA AC 20-107B guidance documents, EASA certification bulletins for bonded joints, SEC 10-K disclosures from composite suppliers, and customs data tracking carbon fiber tow imports. Bottom-up machine park capacity estimates and top-down aircraft delivery schedule triangulation anchored volume projections.
Segmentation dimensions modeled span material type, manufacturing process, application criticality, and end-user procurement pattern across the projection horizon. CAGRs derive from installed automation capacity expansion tied to Boeing and Airbus rate announcements, cross-referenced with thermoplastic qualification timeline assumptions and EPA emissions benchmark stringency trajectories. Forecast inputs include acrylonitrile price elasticity coefficients and narrowbody program entry-into-service schedules.
Decision-makers should treat outputs as directional under assumptions of sustained FAA certification pathway stability and continued Boeing-Airbus duopoly rate coordination; material deviation would warrant model refresh. Revision becomes warranted when thermoplastic damage-tolerance database completion crosses thresholds enabling primary wing structure substitution or when urban air mobility certification frameworks diverge from Part 25 standards.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aerospace and Aircraft Materials
Aerospace and Defense Composites Market
Aerospace and Aircraft Materials
Europe Advanced Aerospace Coatings Market
Aerospace and Aircraft Materials
Aerospace Plastics Market
Aerospace and Aircraft Materials
Aerospace Composite Ducting Market
Aerospace and Aircraft Materials
Aviation Coatings Market
Aerospace and Aircraft Materials
Global Flame Retardant for Aerospace Plastics Market
Aerospace and Aircraft Materials
Composites in United States Defense Market
Aerospace and Aircraft Materials
Global Military Aerospace Coatings Market
Aerospace and Aircraft Materials
Aerospace Threaded Fasteners Market
Aerospace and Aircraft Materials
Coated Fabrics for Defense Market
Aerospace and Aircraft Materials
Aerospace Radome Market
Aerospace and Aircraft Materials
Aircraft Soft Goods Market
Aerospace and Aircraft Materials
Aircraft Insulation Materials Market
Aerospace and Aircraft Materials
Aerospace and Defense Metal Stamping Market
Aerospace and Aircraft Materials
Middle-East and Africa Aerospace Composites Market
Aerospace and Aircraft Materials
Aerospace Fluoropolymers Market